
 Middle East and Africa Vaccines Market | 2026-2036
Middle East and Africa Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Vaccines Market Foresight
Prequalified vaccine status is redrawing competitive access across the Middle East and Africa. Serum Institute of India Pvt Ltd leverages WHO prequalification to anchor supply contracts across multiple African national immunization programs. GSK plc sustains its position through pediatric combination vaccines that dominate procurement tenders in the region. Pfizer Inc. differentiates via mRNA technology leadership and direct government partnerships in Gulf Cooperation Council states.
Vaccines are biologic preparations containing attenuated or inactivated pathogens, subunit antigens, or nucleic acid sequences that stimulate adaptive immune response, manufactured through cell culture, egg-based propagation, or synthetic mRNA synthesis in lipid nanoparticle formulations, with stability defined by cold-chain maintenance at two to eight degrees Celsius for most formulations. Live attenuated and inactivated products occupy the largest volume share due to established cold-chain protocols and lower per-dose cost structures, while mRNA segments represent the fastest-expanding margin pool as Gulf states fund advanced manufacturing partnerships. Government health programs channel the majority of procurement spend through centralized tender mechanisms, with hospitals and clinics serving as the terminal delivery nodes.
South Africa's SAHPRA, Saudi Arabia's SFDA, and Nigeria's NAFDAC enforce varying registration and lot-release standards that fragment market entry timelines and elevate local testing requirements. WHO prequalification serves as the de facto passport for multi-country tender eligibility, yet national regulators increasingly mandate supplementary stability data and local bridging studies. Stakeholders must monitor divergent regulatory clock speeds and pre-position compliant dossiers ahead of national budget cycles.
Market Dynamics
WHO prequalification requirements are compressing competitive access timelines across the Middle East and Africa, forcing manufacturers to front-load stability dossiers and local bridging studies before national budget cycles open. This regulatory gatekeeping is redrawing procurement eligibility and concentrating supply relationships among prequalified holders.
Growth Catalysts
- GAVI and UNICEF pooled procurement frameworks:These multilateral mechanisms aggregate demand across multiple African national immunization programs, creating volume commitments that justify cold-chain infrastructure investments by suppliers.
- Cell culture manufacturing platforms:Serum producers are migrating from egg-based propagation to mammalian cell culture systems, shortening strain changeover timelines and improving pandemic response elasticity for regional health ministries.
- Saudi Vision 2030 biotechnology localization mandates:Gulf Cooperation Council states are directing sovereign wealth toward domestic fill-finish capacity and technology transfer agreements, creating captive supply zones for advanced vaccine formats.
Market Restraints
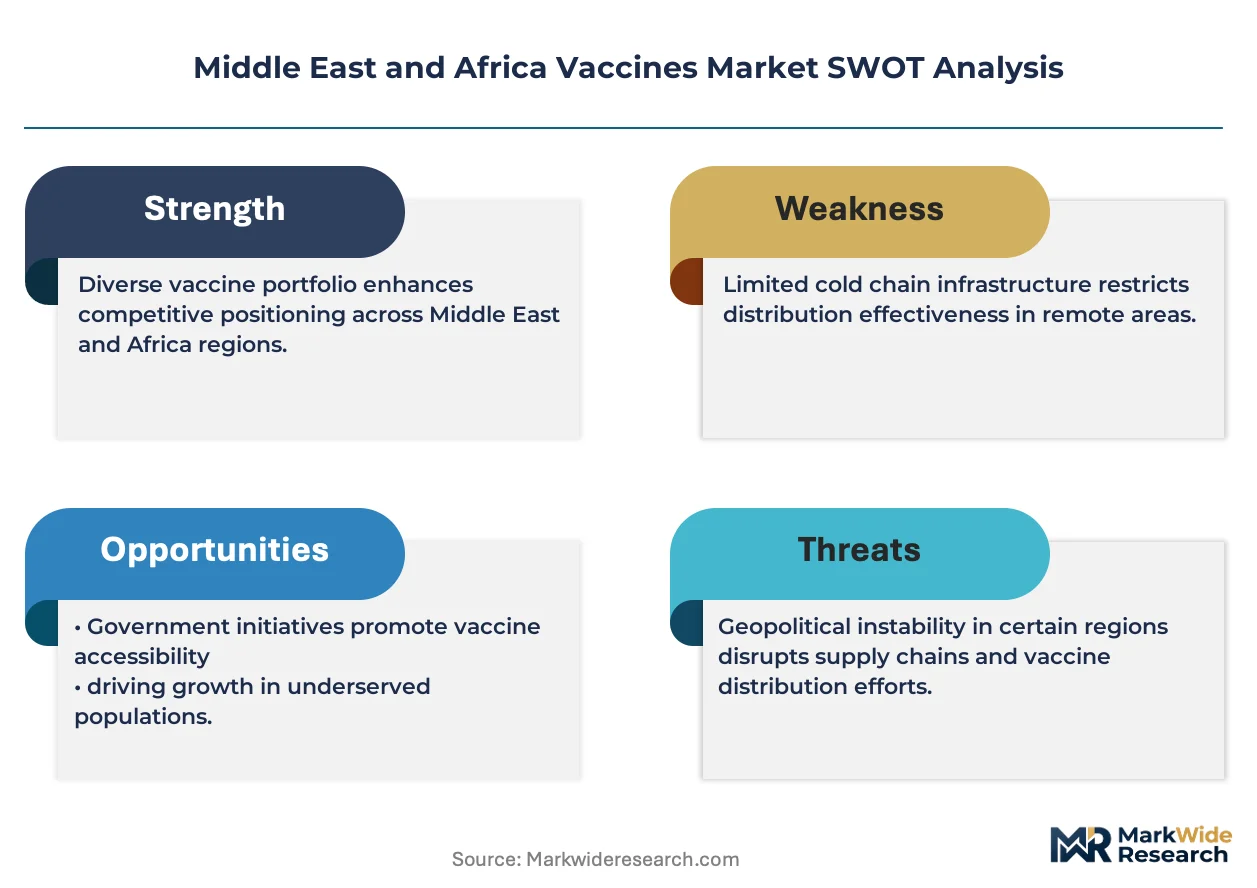
- Active pharmaceutical ingredient import dependence:Regional formulation facilities rely on concentrated Asian bulk antigen supply, exposing procurement timelines to customs delays and currency volatility at port of entry.
- Ultra-cold chain infrastructure gaps:mRNA lipid nanoparticle formulations requiring minus seventy degrees Celsius storage face last-mile distribution failures in rural Nigeria and Ethiopia where solar-powered refrigeration remains sparse.
- Divergent national lot-release protocols:South Africa's SAHPRA, Nigeria's NAFDAC, and Saudi Arabia's SFDA enforce non-harmonized stability testing requirements that fragment registration timelines and duplicate analytical costs.
Strategic Opportunities
- Ethiopia and Democratic Republic of Congo underpenetrated corridors:These high-burden disease markets lack consistent cold-chain reach, creating first-mover advantage for thermostable formulation technologies that tolerate ambient temperature excursions.
- Direct government partnership contracting:Gulf states are bypassing multilateral procurement to negotiate bilateral advanced purchase commitments for mRNA manufacturing technology transfer and local production licensing.
- Digital vaccine verification integration:National health ministries are embedding blockchain-anchored immunization certificates into digital identity systems, opening adjacent software and authentication service revenue streams.
Industry Challenges
- Qualified pharmacovigilance officer scarcity:National regulators mandate dedicated safety surveillance personnel for marketing authorization holders, but trained professionals cluster in South Africa and Egypt leaving Gulf and East African operations understaffed.
- Legacy cold-chain asset stranding:Existing two-to-eight-degree Celsius distribution networks face premature obsolescence as mRNA and viral vector platforms requiring sub-zero storage capture premium procurement tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Vaccines Market |
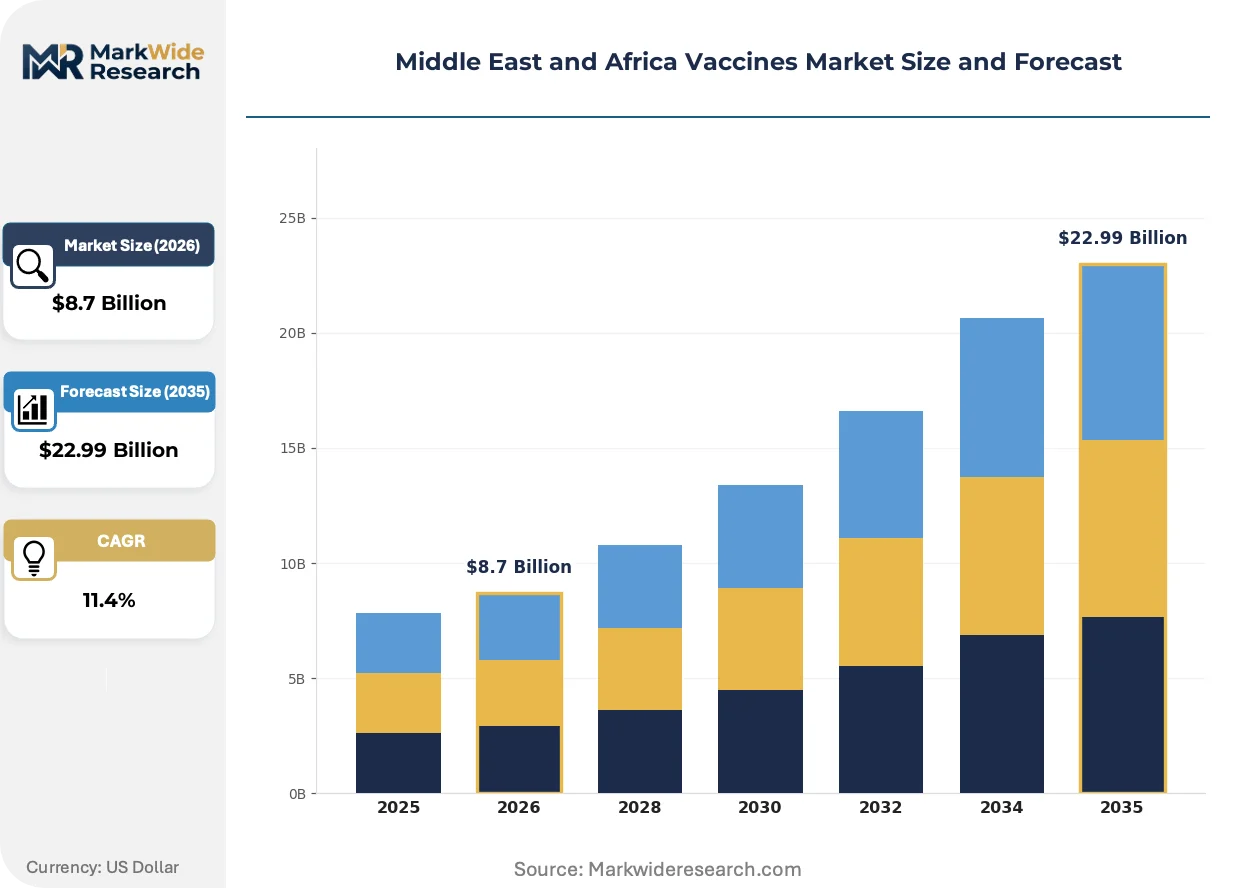
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, mRNA End User: Hospitals, Clinics, Pharmacies, Government Health Programs Age Group: Pediatric, Adult, Geriatric, Adolescent Administration Route: Intramuscular, Subcutaneous, Intravascular, Oral |
| Companies Covered | Sanofi SA, GSK plc, Pfizer Inc., Merck & Co. Inc., Serum Institute of India Pvt Ltd, Novartis AG, CSL Ltd, BioNTech SE, Sinovac Biotech Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Vaccines Market Shifts & Advancements
Thermostable formulation chemistry and nucleic acid delivery platforms are splitting manufacturing investment priorities across the Middle East and Africa. Procurement authorities face technology selection decisions that will lock in supply relationships for decade-long immunization program horizons.
mRNA synthetic biology platforms are bifurcating the competitive landscape between established live-attenuated manufacturers and new entrants. Gulf Cooperation Council health ministries are accelerating advanced purchase timelines for respiratory syncytial virus and influenza mRNA candidates. This technology compression is forcing legacy suppliers to defend position through combination pediatric portfolios rather than novel platform parity.
Saudi Arabia's SFDA and South Africa's SAHPRA are tightening post-marketing surveillance requirements for vaccines distributed through national immunization programs. Lot-level traceability mandates now extend from manufacturer release through clinic administration. Pediatric combination products face the steepest compliance cost escalation as multi-antigen complexity compounds batch testing burdens.
Hospital procurement committees are consolidating supplier relationships around integrated cold-chain service providers rather than discrete product vendors. Nigeria's federal teaching hospitals and Kenya's county referral facilities are bundling equipment lease, maintenance, and temperature monitoring into multi-year supply agreements. This vendor consolidation is most advanced in South Africa's private hospital networks where pharmacy directors negotiate enterprise-wide formulary commitments.
Middle East and Africa Vaccines Market Segmentation
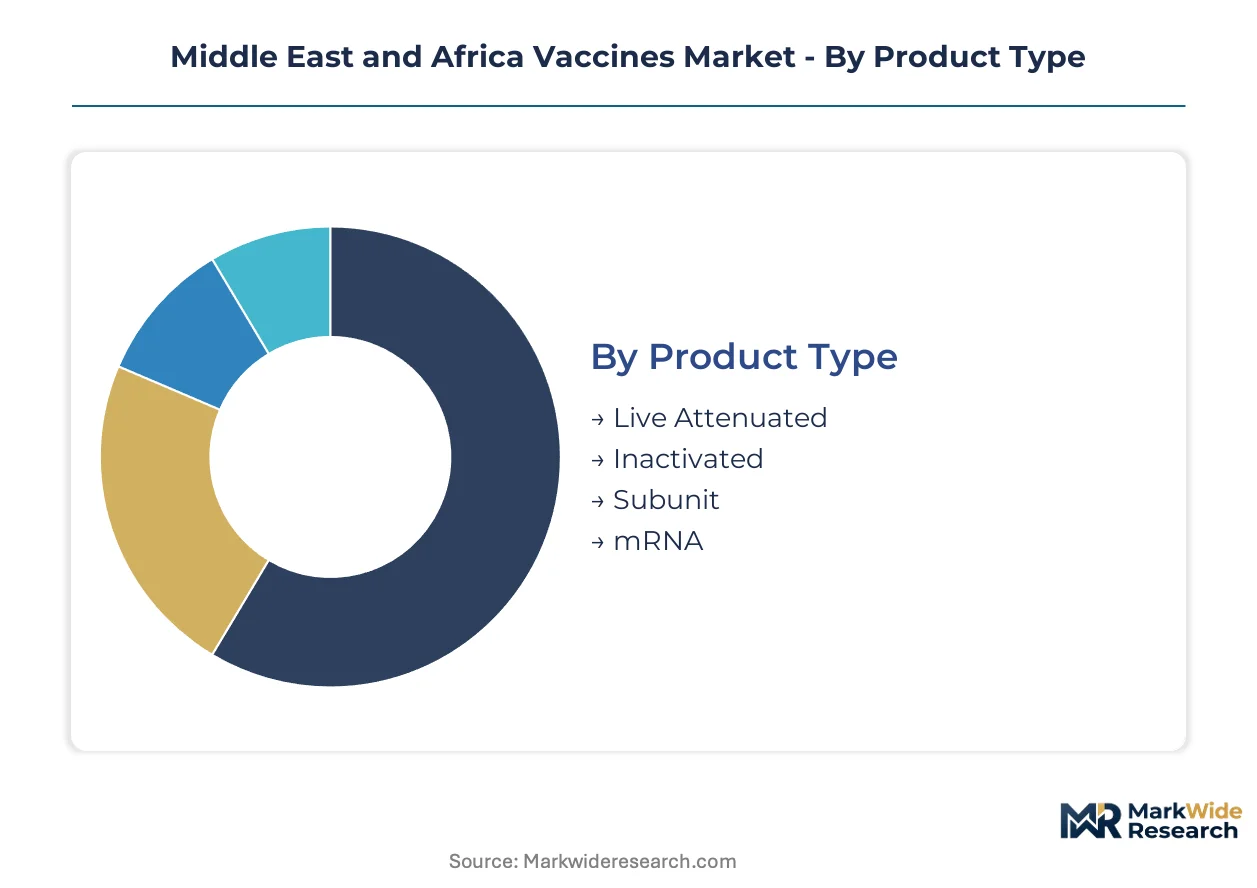
Vaccine procurement across the Middle East and Africa fragments across multiple technical and delivery dimensions. Each segmentation axis reveals distinct margin concentration points and infrastructure requirements that shape supplier competitive positioning.
Product Type:
Margin pools concentrate in mRNA lipid nanoparticle formulations as Gulf states fund advanced manufacturing partnerships, while live attenuated products dominate procurement volume through established cold-chain protocols.
- Live Attenuated:Weakened pathogen preparations retain replication capacity to stimulate cellular immunity. Demand concentrates in Nigeria's national immunization program for measles-rubella combination doses, constrained by minus-fifteen-degree Celsius storage requirements in rural corridors.
- mRNA:Synthetic nucleic acid sequences encapsulated in lipid nanoparticles direct host cell antigen production. Saudi Arabia's SFDA fast-tracks respiratory syncytial virus candidates through bilateral technology transfer agreements with Pfizer and Moderna, creating premium procurement tiers.
- Inactivated:Heat-killed whole pathogens suspended in alum adjuvant generate humoral antibody response. Egypt's VACSERA facility produces hepatitis A and B bulk antigens for regional formulation.
- Subunit:Purified protein antigens or polysaccharide conjugates eliminate reactogenicity risks of whole-cell preparations. South Africa's Biovac Institute manufactures pneumococcal conjugate under license from GSK.
Live attenuated holds installed capacity across African cold-chain networks. mRNA is rotating up the share rankings through Gulf sovereign wealth commitments.
End User:
Procurement authority centralization determines contract scale, with government health programs aggregating volume through GAVI and UNICEF frameworks while hospital networks negotiate integrated service bundles.
- Government Health Programs:National immunization programs operate through ministry of health tender mechanisms with WHO prequalification prerequisites. Ethiopia's EPI expansion targets ninety percent DTP3 coverage, channeling demand through UNICEF pooled procurement.
- Hospitals:Federal teaching hospitals and private networks manage cold-chain infrastructure for specialty vaccines including rabies immunoglobulin and travel medicine portfolios. Kenya's Aga Khan University Hospital anchors high-value procurement in East Africa.
- Clinics:Primary health centers serve as last-mile delivery nodes for routine immunization, particularly in Nigeria's ward-level health system. Temperature monitoring compliance varies by state cold-chain equipment maintenance budgets.
- Pharmacies:Retail channels capture influenza and travel vaccine demand in South Africa's private market and Gulf urban centers. Dubai's community pharmacies now stock COVID-19 bivalent boosters under MOHAP authorization.
Government health programs command volume concentration. Hospital networks are rotating up the share rankings through enterprise formulary consolidation.
Age Group:
Pediatric segments anchor procurement predictability through birth-cohort-based forecasting, while adult expansion reflects emerging market chronic disease burden and Gulf workforce vaccination mandates.
- Pediatric:Birth-to-five-year schedules encompass pentavalent, measles-rubella, and rotavirus doses with GAVI co-financing eligibility determining national program scope. Nigeria's twelve million annual birth cohort drives continental volume.
- Adult:Occupational health mandates and chronic disease prevention target working-age populations. Saudi Arabia's hajj pilgrimage health requirements sustain meningococcal quadrivalent demand exceeding twenty million doses annually.
- Adolescent:Human papillomavirus catch-up campaigns and tetanus-diphtheria boosters concentrate in South Africa's school-based delivery system. HPV introduction delays in Francophone West Africa create coverage gaps.
- Geriatric:Pneumococcal polysaccharide and herpes zoster vaccines address aging demographics in Gulf Cooperation Council states and South Africa's private insurance market. Reimbursement fragmentation limits access elsewhere.
Pediatric holds installed capacity through GAVI supply commitments. Adult is climbing fastest through occupational mandate expansion.
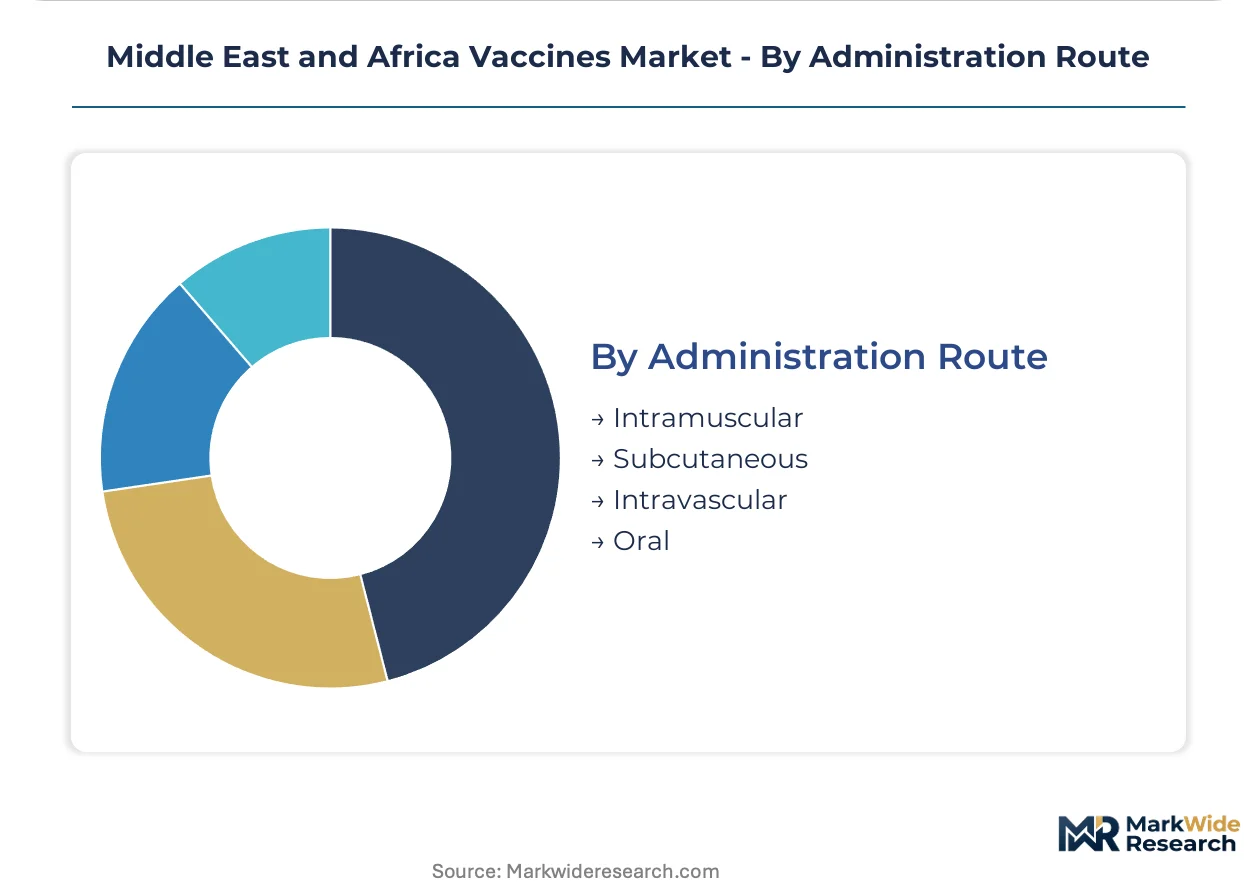
Administration Route:
Delivery modality selection shapes cold-chain packaging requirements and healthcare worker training intensity, with intramuscular formats dominating injectable portfolios and oral delivery offering last-mile distribution advantages.
- Intramuscular:Deltoid or vastus lateralis injection of alum-adjuvanted suspensions requires needle-syringe supply security and sharps waste management. WHO auto-disable syringe specifications govern UNICEF procurement tenders.
- Oral:Live attenuated Sabin poliovirus and rotavirus liquid formulations bypass cold-chain dependence through thermostabilization. Ethiopia's health extension workers administer oral cholera doses during outbreak response.
- Subcutaneous:Yellow fever and measles vaccines deposit in adipose tissue with twenty-five-millimeter needle specifications. Nigeria's yellow fever preventive mass campaigns target seventy million people.
- Intravascular:Rabies immunoglobulin and specialized antisera require intravenous infusion capacity concentrated in tertiary referral hospitals. South Africa's Netcare private network maintains dedicated immunoglobulin cold rooms.
Intramuscular holds installed capacity across routine immunization platforms. Oral is gaining share fastest through thermostable formulation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vaccine supply into the Middle East and Africa tilts toward import dependence, with regional formulation capacity concentrated in Egypt, South Africa, and Saudi Arabia while bulk antigens arrive from Asian manufacturing hubs. National regulators enforce divergent stability testing protocols that fragment registration timelines and elevate local bridging study costs.
South Africa
The Biovac Institute in Cape Town anchors regional formulation capacity under technology transfer agreements with multinational licensors. SAHPRA mandates supplementary lot-release testing beyond WHO prequalification standards, extending marketing authorization timelines for imported products. Johannesburg's private hospital networks consolidate procurement around integrated cold-chain service providers rather than discrete vaccine vendors.
Saudi Arabia
Saudi Vision 2030 biotechnology localization directives channel sovereign wealth toward domestic fill-finish capacity and mRNA technology transfer partnerships. The SFDA fast-tracks respiratory syncytial virus candidates through bilateral advanced purchase commitments with synthetic biology platforms. Riyadh's King Abdullah International Medical Research Center anchors clinical trial infrastructure for novel vaccine candidates targeting Gulf populations.
Nigeria
NAFDAC's national lot-release requirements duplicate WHO prequalification dossiers, creating registration bottlenecks for suppliers lacking local regulatory affairs capacity. The federal government's twelve million annual birth cohort drives continental volume for measles-rubella and pentavalent doses through GAVI co-financing. Lagos state cold-chain equipment maintenance budgets determine last-mile temperature monitoring compliance across ward-level primary health centers.
Egypt
VACSERA's Cairo facility produces hepatitis A and B bulk antigens for regional formulation, reducing import dependence for government immunization programs. The national pharmaceutical regulator mandates local bridging studies for all novel vaccine introductions, extending timelines for mRNA platform registrations. The 6th of October City industrial zone concentrates fill-finish operations serving North African procurement authorities.
United Arab Emirates
Dubai's MOHAP-authorized community pharmacies now stock COVID-19 bivalent boosters, expanding retail channel access beyond hospital-based administration. The federal health ministry embeds blockchain-anchored immunization certificates into digital identity systems, creating adjacent authentication service procurement. Abu Dhabi's G42 Healthcare anchors advanced manufacturing partnerships for nucleic acid delivery platforms targeting Gulf Cooperation Council markets.
Middle East and Africa Vaccines Market Competitive Landscape
Listed leaders compete with private specialists across prequalification status and cold-chain service integration. The supplier base concentrates around WHO-prequalified holders capable of meeting UNICEF pooled procurement specifications, with tiering between established live-attenuated manufacturers and synthetic biology entrants. Three archetypes dominate: multinationals defending position through pediatric combination portfolios, Indian private specialists leveraging cost-advantaged bulk supply, and mRNA platform licensors capturing Gulf premium tenders. Competitive moves center on technology transfer agreements for regional fill-finish capacity and direct government partnership contracting bypassing multilateral frameworks.
Within the multinational tier, GSK plc and Pfizer Inc. exemplify divergent platform strategies, with the former anchoring procurement through established pediatric combinations and the latter capturing premium positioning via nucleic acid delivery partnerships with Gulf health ministries. Serum Institute of India Pvt Ltd occupies a distinct cost-leadership archetype, supplying volume doses across African national immunization programs through prequalified bulk antigen arrangements. These three entities collectively represent the spectrum of competitive positioning: portfolio breadth, technology premium, and manufacturing scale.
| Leading Market Players |
|---|
| Sanofi SA |
| GSK plc |
| Pfizer Inc. |
| Merck & Co. Inc. |
| Serum Institute of India Pvt Ltd |
| Novartis AG |
| CSL Ltd |
| BioNTech SE |
| Sinovac Biotech Ltd |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with Gulf health ministries lock in supply access and price visibility for mRNA lipid nanoparticle formulations across the analysis window. These contracts tether procurement timelines to technology transfer milestones while insulating suppliers from spot-market volatility in bulk antigen inputs.
Pricing Analysis
Government health programs anchor three-tier pricing structure across premium, standard, and economy levels based on WHO prequalification status and cold-chain service bundling. Price differentiation stems from certification tier and volume scale, with UNICEF pooled procurement commanding lowest unit economics. Cost compression in standard-tier live-attenuated products is intensifying as Indian bulk suppliers expand capacity. Private hospital networks in South Africa exhibit least price sensitivity due to integrated formulary commitments.
Supply Chain Analysis
Strait of Hormuz transit underwrites bulk antigen import security for regional formulation facilities in Egypt and Saudi Arabia. Supply concentration centers on India, China, and South Korea for active pharmaceutical ingredients and lipid nanoparticle excipients. Single-source vulnerability in minus-seventy-degree Celsius cold-chain equipment creates last-mile risk for mRNA distribution into Nigeria and Ethiopia. Distribution runs through government central medical stores with temperature-monitored last-mile handoffs to ward-level clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA platform disruption is accelerating competitive reordering across Middle East and Africa procurement corridors. Saudi Arabia's SFDA fast-track pathways and GAVI co-financing expansion create dual-track market access.
For Market Incumbents: Shield pediatric combination portfolios through exclusive WHO prequalification maintenance and local bridging study pre-positioning ahead of Nigerian NAFDAC budget cycles. Deepen backward integration into fill-finish capacity in Egypt's 6th of October City industrial zone to offset Asian API import dependence. Counter mRNA entrants by bundling established cold-chain service contracts with ministry tender submissions. For New Entrants and Emerging Players: Anchor in Ethiopia and Democratic Republic of Congo underpenetrated corridors where thermostable oral formulations bypass ultra-cold infrastructure gaps. Target government health program procurement through GAVI co-financing eligibility rather than Gulf premium tenders dominated by technology transfer partnerships. Pursue digital vaccine verification integration as adjacent revenue stream alongside product supply. For Investors and Strategic Acquirers: Regional fill-finish specialists with technology transfer licenses and SFDA compliance track records represent priority acquisition archetypes. Long-term viability hinges on sovereign wealth commitment durability to biotechnology localization mandates. Monitor Saudi Vision 2030 funding disbursement velocity as inflection indicator for mRNA manufacturing partnership sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Serum Institute leverages status to anchor UNICEF supply contracts across African national immunization programs. |
| mRNA Technology Transfer Agreement | Pfizer and Moderna secure bilateral commitments with Saudi SFDA for respiratory syncytial virus candidates. |
| Regional Fill-Finish Capacity Expansion | Biovac Institute anchors South African formulation under GSK pneumococcal conjugate licensing. |
| Thermostable Formulation Development | Oral rotavirus and poliovirus formats bypass cold-chain gaps in rural Nigeria and Ethiopia. |
| Digital Verification Integration | UAE MOHAP embeds blockchain-anchored certificates into federal digital identity systems. |
Research Methodology
Operator-level perspectives from regulatory affairs leads at SAHPRA and NAFDAC, ministry procurement officers, cold-chain logistics managers, and hospital pharmacy directors anchored the qualitative base. These primary insights combined with secondary validation from WHO prequalification listings, GAVI disbursement records, UNICEF supply forecasts, and national immunization program budget documents. Bottom-up demand modeling across patient cohorts and top-down macroeconomic triangulation ensured cross-verified outputs.
Sensitivity analysis framed volume and value projections across the modeling period by technology platform, end-user procurement authority, age-group immunization schedule, and regional regulatory cluster. CAGRs derived from segment-level growth trajectory blending with macro healthcare expenditure elasticity. Forecast inputs incorporated GAVI co-financing transition timelines and Gulf sovereign wealth biotechnology allocation patterns.
Decision-makers should treat outputs as directional under sustained GAVI funding and Gulf localization commitment assumptions; material deviation would warrant model refresh. Forecasts reflect documented base-case parameters with explicit scenario branches for ultra-cold infrastructure deployment pace and regulatory harmonization progress. Practitioners should keep alternative scenarios live as NAFDAC lot-release protocol evolution and Ethiopian EPI coverage targets shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Toxoid Vaccines Market
Pharmaceuticals
Omeprazole Market