
 Global Chronic Lymphocytic Leukemia Therapeutics Market | 2026-2036
Global Chronic Lymphocytic Leukemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chronic Lymphocytic Leukemia Therapeutics Market Foresight
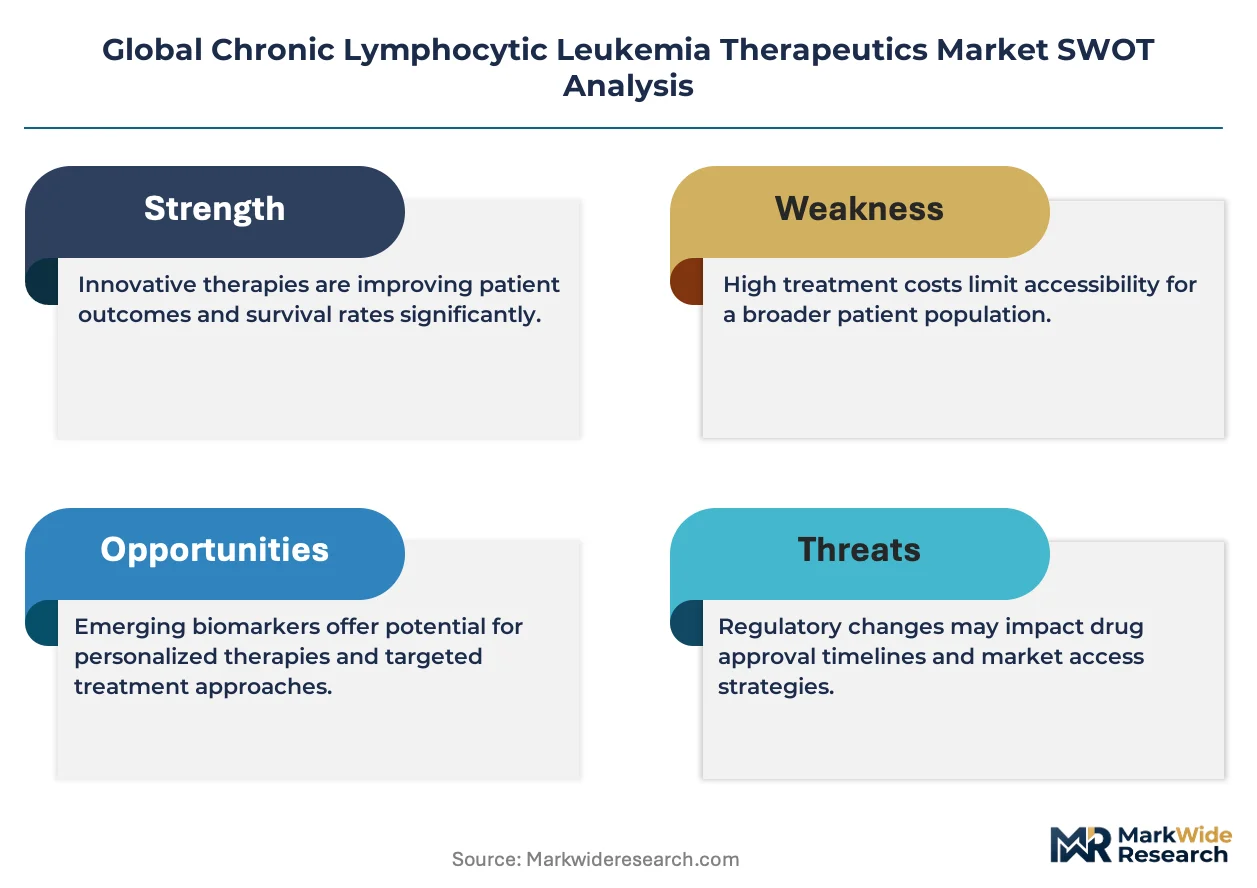
EMA's updated oncology benefit-risk guidelines is shifting the evidentiary threshold for CLL therapy approvals across European markets. AbbVie Inc. leverages its venetoclax franchise to anchor chronic lymphocytic leukemia positioning in BCL-2 inhibition. Johnson & Johnson competes through ibrutinib-based portfolio depth across relapsed and first-line settings. BeiGene specializes in differentiated BTK inhibitor chemistry to extend its footprint in resistant patient populations.
Chronic lymphocytic leukemia therapeutics comprise targeted small molecules, monoclonal antibodies, and immunomodulatory agents designed to interrupt malignant B-cell survival signaling through BTK, BCL-2, or PI3K pathway inhibition, with primary purpose of extending progression-free survival while preserving quality of life in an incurable hematologic malignancy. Tyrosine kinase inhibitors dominate current prescribing patterns due to established oral convenience and durable remission data. BCL-2 inhibitors represent the fastest-growing product class as fixed-duration regimens reshape treatment economics. Hematology clinics capture concentrated margin pools through infusion administration fees and companion diagnostic bundling.
FDA, EMA, and Japan's PMDA each enforce distinct post-marketing surveillance requirements that shape label expansion strategies and commercial launch sequencing for CLL developers. REACH compliance in Europe and state-level oncology biosimilar substitution laws in the United States create fragmented pricing and access conditions across major markets. Stakeholders must monitor evolving overall survival endpoints in regulatory guidance and payer technology assessments to anticipate which mechanism classes will retain premium positioning.
Market Dynamics
The transition from chemotherapy-based protocols to targeted oral therapies is compressing treatment cycles and redistributing margin capture from infusion centers to retail pharmacy networks. This mechanism shift is forcing wholesale restructuring of hematology clinic economics and patient monitoring infrastructure across major prescribing markets.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's oncology review frameworks compress Phase II-to-launch timelines for BTK and BCL-2 inhibitors. Developers exploit this regulatory velocity to secure first-mover positioning in relapsed settings.
- Fixed-Duration Regimen Economics:Time-limited therapy protocols reduce lifetime treatment costs and expand payer willingness to reimburse premium mechanism classes. Hematology clinics capture efficiency gains through reduced chair time.
- Companion Diagnostic Bundling:Integrated biomarker testing with TP53 and IGHV profiling streamlines patient selection for targeted agents. Laboratory networks deepen clinical trial recruitment through centralized genomic screening.
Market Restraints
- API Manufacturing Concentration:Active pharmaceutical ingredient production for kinase inhibitors clusters in Chinese and Indian contract manufacturing organizations. Geopolitical friction threatens supply continuity for oral oncology portfolios.
- Resistance Mutation Surveillance:BTK C481S and PLCG2 mutations erode durable response rates and necessitate sequential therapy switching. Real-world evidence collection lags behind clinical progression patterns.
- REACH Compliance Burden:European chemical registration requirements for novel synthetic intermediates extend pre-commercial manufacturing timelines. EMA environmental risk assessments add six to twelve months to facility qualification.
Strategic Opportunities
- Brazilian Public Oncology Expansion:ANVISA regulatory harmonization with FDA standards accelerates market entry for approved CLL agents. SUS reimbursement list inclusion opens access to 200 million covered lives.
- Real-World Evidence Generation:Flatiron Health and similar oncology data platforms enable post-approval label expansion through retrospective outcome analysis. Payers accept RWE for formulary positioning in competitive mechanisms.
- Subcutaneous Administration Formats:Monoclonal antibody reformulation from infusion to injection shifts administration site from hospital to home health settings. Patient preference data supports premium pricing for convenience differentiation.
Industry Challenges
- Hematology Specialist Workforce Constraints:Fellowship training programs produce insufficient board-certified oncologists to manage expanding CLL prevalence. Rural and community practice settings face particular recruitment shortfalls.
- Cross-Border Reference Pricing Arbitrage:Parallel trade between German and Greek pharmaceutical markets undermines country-specific net pricing strategies. Manufacturers deploy anti-diversion packaging and contractual pharmacy audit clauses.
- Legacy EHR Integration Complexity:Electronic health record systems require substantial customization to support integrated genomic result reporting and clinical decision support. Implementation timelines delay precision medicine program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chronic Lymphocytic Leukemia Therapeutics Market |
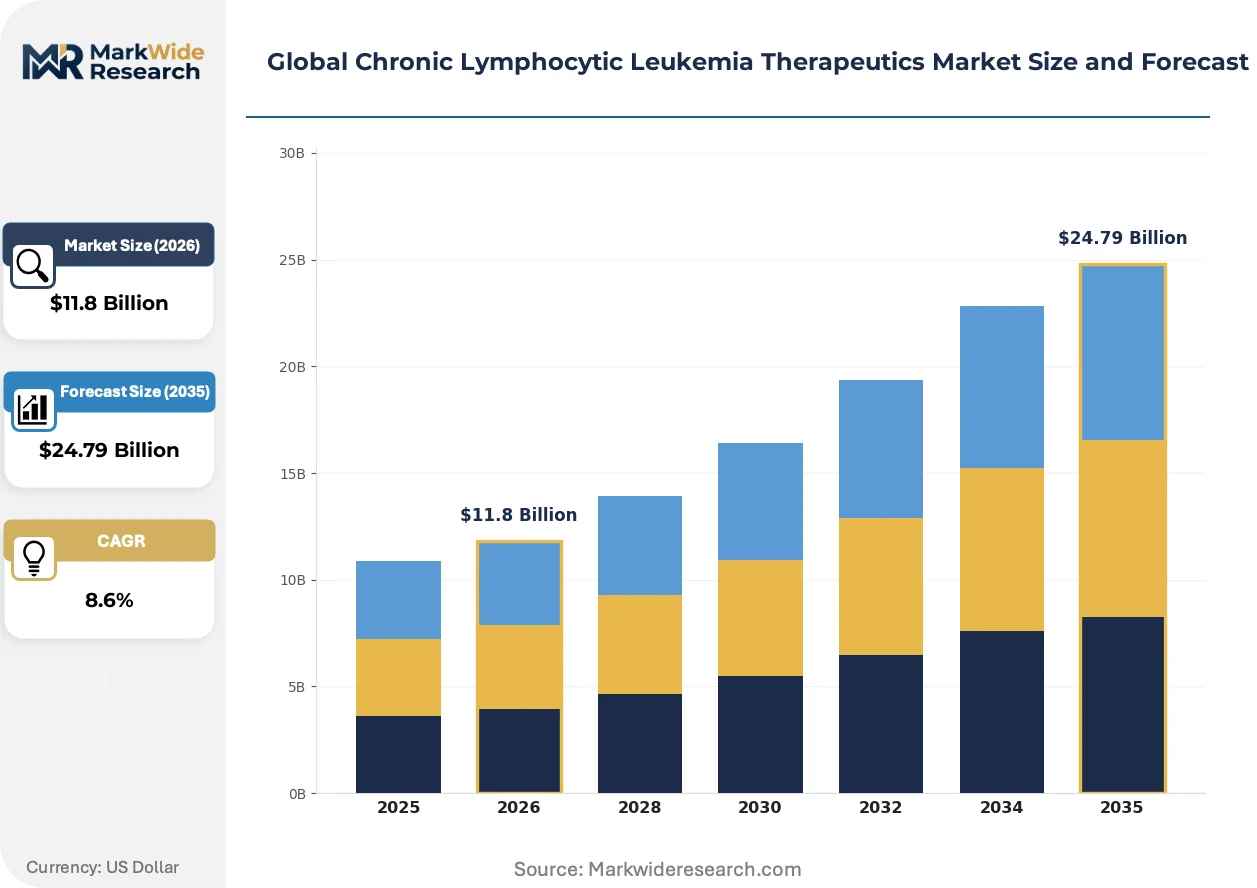
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Tyrosine Kinase Inhibitors, BCL-2 Inhibitors, Chemotherapy Agents, Immunomodulators Therapy Area: First-line Treatment, Relapsed/Refractory, Maintenance Therapy, Combination Therapy, Supportive Care End User: Hematology Clinics, Oncology Centers, Specialized Laboratories, Ambulatory Care, Research Institutes Delivery Mode: Oral, Intravenous, Subcutaneous, Injectable, Infusion |
| Companies Covered | Novartis AG, Johnson & Johnson, AbbVie Inc., BeiGene, Pfizer Inc., F. Hoffmann-La Roche Ltd, Gilead Sciences Inc., Bristol Myers Squibb Company, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chronic Lymphocytic Leukemia Therapeutics Market Shifts & Advancements
Next-generation sequencing integration is collapsing the diagnostic-to-treatment interval from months to weeks. This compression is redrawing competitive advantage around data infrastructure rather than molecule chemistry alone.
Non-covalent BTK inhibitors are expanding into ibrutinib-resistant patient populations through reversible binding mechanisms that circumvent C481S mutation escape. Academic medical centers in the United States and Germany are prioritizing these agents for clinical trial enrollment. The technology is expanding into earlier treatment lines as head-to-head data against covalent predecessors mature.
EMA's updated oncology benefit-risk guidelines now mandate overall survival data for full approval of CLL therapies previously authorized on progression-free survival endpoints. This evidentiary elevation is extending confirmatory trial timelines and increasing development capital requirements. European developers are responding by prioritizing US-first launch sequences to generate survival data before EMA submission.
Specialty pharmacy distribution is consolidating patient access management under three national US dispensers. This channel concentration enables direct manufacturer engagement for adherence monitoring and copay assistance programs. The model is most visible in Medicare Part D enrollment where oral oncology parity legislation eliminated prior cost-sharing differentials against infused therapies.
Global Chronic Lymphocytic Leukemia Therapeutics Market Segmentation
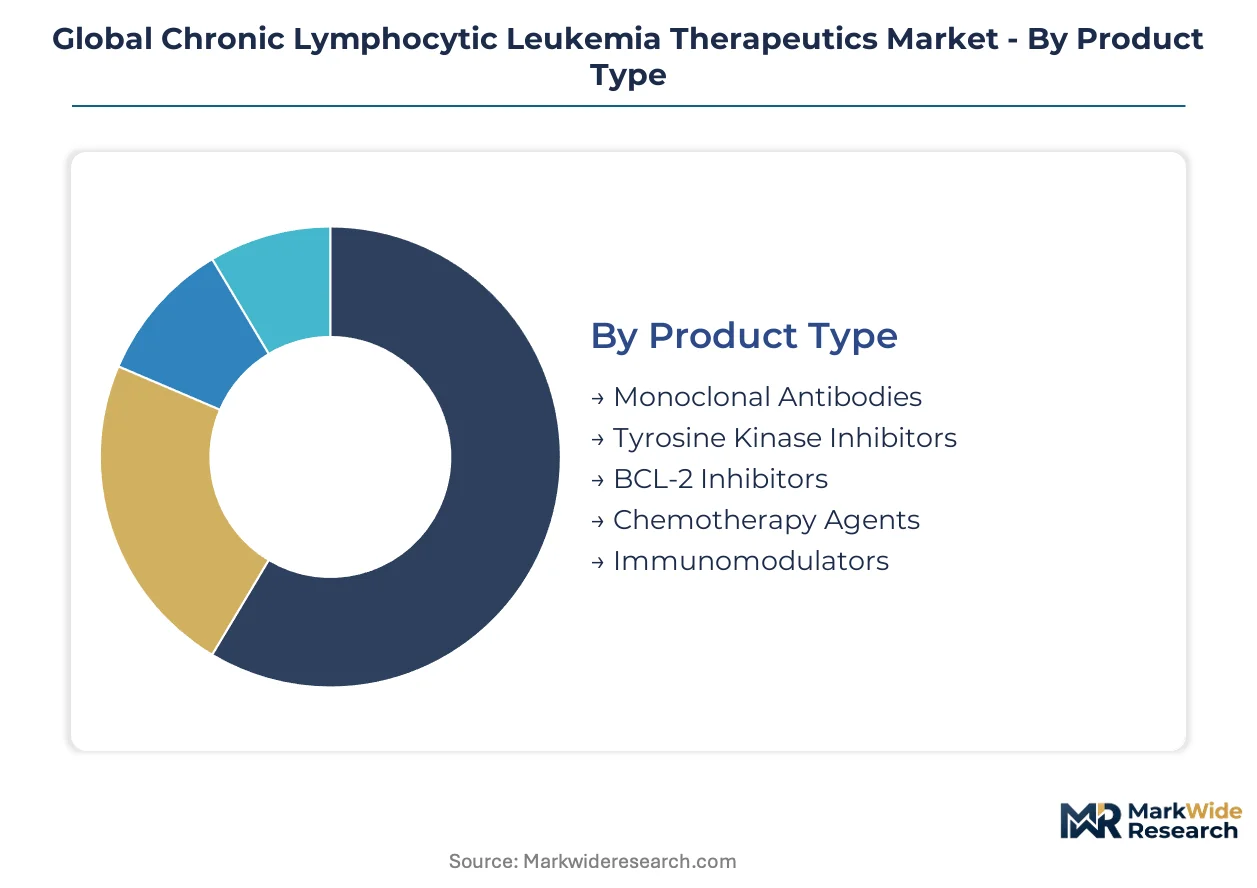
CLL therapeutics segmentation reflects the mechanism shift from cytotoxic chemotherapy to precision-targeted oral agents. Treatment selection now hinges on biomarker profiling, resistance mutation status, and fixed-duration regimen economics rather than age-adjusted protocols alone.
Product Type:
Replacement cycles favor oral kinase inhibitors over legacy chemotherapy as first-line protocols, compressing infusion center utilization and redirecting margin capture toward retail pharmacy networks.
- Tyrosine Kinase Inhibitors:Covalent BTK inhibitors such as ibrutinib and acalabrutinib dominate current prescribing through once-daily oral dosing and durable progression-free survival data. Hematology clinics in the United States and Germany concentrate demand for these agents as backbone therapy in IGHV-unmutated populations, though C481S resistance mutations are forcing earlier sequencing decisions.
- BCL-2 Inhibitors:Venetoclax-based regimens enable time-limited therapy protocols that reduce lifetime treatment costs while preserving quality-of-life endpoints. Fixed-duration economics are expanding payer willingness to reimburse these agents in the United States and Japan, where reimbursement frameworks favor novel mechanism classes with defined treatment horizons.
- Monoclonal Antibodies:CD20-directed agents such as obinutuzumab retain positioning in combination protocols despite infusion administration burdens.
- Chemotherapy Agents:Fludarabine-cyclophosphamide-rituximab protocols now concentrate in resource-constrained settings and TP53-mutated populations lacking targeted alternatives.
- Immunomodulators:Lenalidomide and related agents occupy niche maintenance settings with modest market presence relative to kinase and BCL-2 pathways.
Tyrosine kinase inhibitors sit at the top of the volume ranking, with BCL-2 inhibitors climbing the fastest as fixed-duration protocols reshape treatment economics.
Therapy Area:
Cost tier differentiation separates curative-intent first-line protocols from salvage regimens, with maintenance therapy occupying a contested middle ground as evidence for continuous versus fixed-duration strategies evolves.
- First-line Treatment:Initial therapy selection now prioritizes BTK or BCL-2 inhibition based on IGHV mutation status and TP53 functionality. Academic medical centers in Germany and the United States drive adoption of chemo-free protocols, with companion diagnostic bundling streamlining patient selection.
- Relapsed/Refractory:Sequential therapy switching dominates this segment as resistance mutations erode response to prior mechanism classes. Non-covalent BTK inhibitors and next-generation BCL-2 combinations are expanding into ibrutinib-failed populations through reversible binding chemistry.
- Combination Therapy:Venetoclax-obinutuzumab and similar doublet protocols concentrate in fixed-duration strategies with defined treatment horizons.
- Maintenance Therapy:Continuous BTK inhibition versus time-limited BCL-2 protocols generate payer scrutiny over lifetime cost accumulation.
- Supportive Care:Growth factor support and infection prophylaxis retain essential positioning despite declining chemotherapy utilization.
First-line treatment commands the largest addressable population, though relapsed/refractory settings are expanding most quickly as resistance mechanisms proliferate.
End User:
Customer type fragmentation separates high-academic centers with genomic profiling capabilities from community practices dependent on centralized laboratory networks.
- Hematology Clinics:Specialized CLL-focused practices concentrate in urban clusters across the United States, Germany, and Japan. These sites capture margin pools through infusion administration fees, companion diagnostic bundling, and clinical trial recruitment.
- Oncology Centers:Generalist oncology practices manage the majority of incident CLL cases in community settings, relying on centralized genomic screening and telemedicine specialist consultation for complex sequencing decisions.
- Specialized Laboratories:Centralized NGS providers such as Foundation Medicine and Tempus anchor biomarker-driven treatment selection through TP53 and IGHV profiling.
- Ambulatory Care:Retail pharmacy networks and home health settings are expanding as oral therapy protocols displace infusion-dependent regimens.
- Research Institutes:Academic medical centers in the United States and Germany prioritize enrollment in head-to-head trials comparing non-covalent BTK inhibitors against covalent predecessors.
Hematology clinics retain the highest patient volume concentration, with ambulatory care gaining share fastest as oral administration formats proliferate.
Delivery Mode:
Supply concentration in API manufacturing shapes delivery mode economics, with oral formulations dependent on Chinese and Indian contract manufacturing organizations for kinase inhibitor active pharmaceutical ingredients.
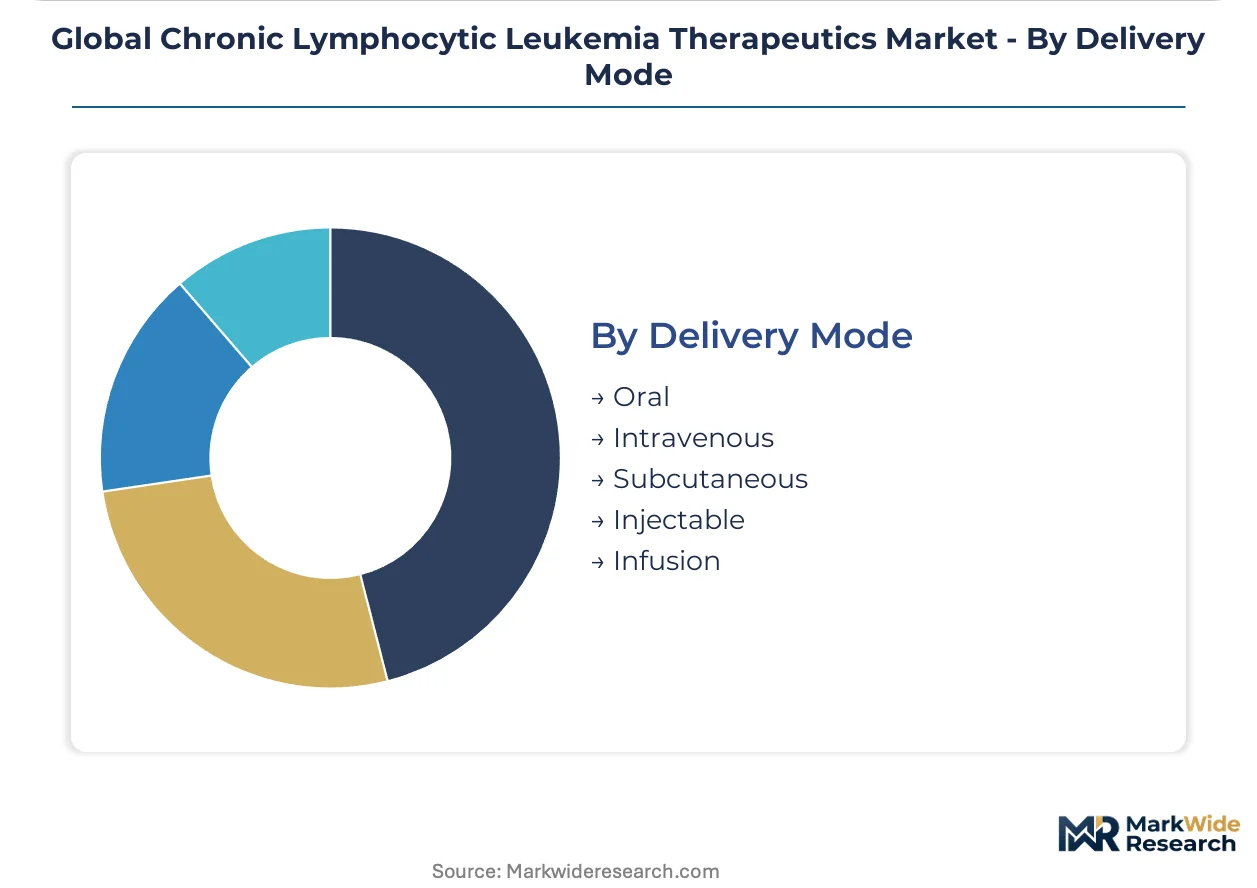
- Oral:Once-daily tablet and capsule formulations dominate BTK and BCL-2 inhibitor portfolios, enabling home administration and reducing treatment disruption. Patient preference data from the United States supports premium positioning for convenience differentiation.
- Intravenous:CD20-directed monoclonal antibodies and chemotherapy agents retain IV dependence, concentrating utilization in hospital-based infusion centers with specialized nursing capabilities.
- Subcutaneous:Reformulation of monoclonal antibodies from infusion to injection is shifting administration from hospital to home health settings, with patient preference studies supporting route differentiation.
- Injectable:Supportive care agents and short-acting formulations occupy niche positioning within broader CLL protocols.
- Infusion:Extended-duration monoclonal antibody administration retains limited utilization as subcutaneous alternatives mature.
Oral delivery sits at the top of the volume ranking, with subcutaneous administration climbing the fastest as monoclonal antibody reformulation programs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hematology specialist density anchors geographic demand concentration. Fellowship-trained oncologists cluster in urban academic medical centers where genomic profiling infrastructure and clinical trial access concentrate patient volumes.
United States
Medicare Part D oral oncology parity legislation eliminated cost-sharing differentials against infused therapies. FDA accelerated approval pathways compress Phase II-to-launch timelines for BTK and BCL-2 inhibitors. Academic medical centers in Boston and Houston prioritize enrollment in head-to-head trials comparing non-covalent BTK inhibitors against covalent predecessors.
Germany
Cross-border reference pricing arbitrage between German and Greek pharmaceutical markets undermines country-specific net pricing strategies. EMA's updated oncology benefit-risk guidelines mandate overall survival data for full approval of CLL therapies previously authorized on progression-free survival endpoints. Heidelberg and Munich hematology clinics capture margin pools through infusion administration fees and companion diagnostic bundling.
Japan
PMDA post-marketing surveillance requirements shape label expansion strategies and commercial launch sequencing for CLL developers. Reimbursement frameworks favor novel mechanism agents with defined treatment horizons. Tokyo and Osaka oncology centers drive adoption of chemo-free protocols, with centralized genomic screening streamlining patient selection.
Brazil
ANVISA regulatory harmonization with FDA standards accelerates market entry for approved CLL agents. SUS reimbursement list inclusion opens access to 200 million covered lives. São Paulo hematology specialists manage the majority of incident CLL cases, relying on telemedicine consultation for complex sequencing decisions.
United Kingdom
NICE technology appraisals scrutinize overall survival endpoints in competitive mechanism classes. NHS England's Cancer Drugs Fund provides conditional reimbursement pending confirmatory trial data. London and Manchester academic centers anchor biomarker-driven treatment selection through TP53 and IGHV profiling.
Global Chronic Lymphocytic Leukemia Therapeutics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across mechanism classes and patient populations. The vendor base stratifies into three tiers: global pharmaceutical conglomerates with oncology divisions, mid-cap biotech specialists in hematologic malignancies, and emerging innovators in resistance mutation targeting. Consolidation pressure intensifies as fixed-duration regimen economics compress lifetime revenue per patient. Dominant competitive moves include portfolio diversification through mechanism class expansion and strategic partnerships for companion diagnostic co-development.
Within the global pharmaceutical conglomerate tier, Novartis AG and Johnson & Johnson occupy positions anchored by established kinase inhibitor franchises. AbbVie Inc. exemplifies the focused hematology specialist archetype through its venetoclax-based BCL-2 inhibition portfolio. BeiGene represents the emerging innovator model, specializing in differentiated BTK inhibitor chemistry for resistant patient populations. These three companies collectively illustrate the competitive spectrum from diversified oncology platforms to targeted mechanism depth.
| Leading Market Players |
|---|
| Novartis AG |
| Johnson & Johnson |
| AbbVie Inc. |
| BeiGene |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Gilead Sciences Inc. |
| Bristol Myers Squibb Company |
| AstraZeneca plc |
| Others |
Supply & Pricing Matrix
Fixed-duration oral therapy protocols are redrawing cost structures across the CLL therapeutics value chain while compressing manufacturing batch economics for kinase inhibitor active pharmaceutical ingredients. This mechanism shift simultaneously elevates payer willingness to reimburse premium mechanism classes and concentrates API production risk in Asian contract manufacturing networks.
Pricing Analysis
Bundled companion diagnostic testing and unbundled drug-only reimbursement create divergent net pricing outcomes across United States and European markets. Three-tier pricing structure across premium novel mechanisms, standard-of-care BTK inhibitors, and economy chemotherapy alternatives reflects biomarker stratification and resistance mutation status. Pricing pressure stems from cross-border reference pricing arbitrage between German and Greek pharmaceutical markets. Community oncology practices exhibit highest price sensitivity due to thin formulary margins, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Specialized chemical synthesis workforce availability in Chinese and Indian contract manufacturing organizations anchors global production capacity for BTK and BCL-2 inhibitor APIs. Supply chains draw from concentrated intermediate suppliers in Zhejiang province and Hyderabad corridor, with purification-grade solvents and chiral building blocks as critical inputs. Single-source vulnerability for C481S mutation-resistant compound precursors poses continuity risk. Distribution runs through three national United States specialty pharmacy dispensers with direct manufacturer engagement for adherence monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed-duration regimen economics present a margin-expansion pathway as reduced lifetime treatment costs improve payer access while preserving per-cycle pricing power for novel mechanism classes.
For Market Incumbents: Deploy backward integration into API manufacturing to secure supply continuity for kinase inhibitor portfolios against geopolitical friction. Fortify formulary positioning through real-world evidence generation platforms that demonstrate overall survival differentiation. Counter non-covalent BTK inhibitor entrants by accelerating head-to-head trial readouts in ibrutinib-resistant populations. For New Entrants and Emerging Players: Enter via Brazilian public oncology expansion where ANVISA regulatory harmonization with FDA standards compresses market entry timelines. Concentrate initial launches on relapsed/refractory settings with documented resistance mutations, leveraging reversible binding chemistry as clinical differentiation. Pursue subcutaneous administration reformulation partnerships to shift site-of-care economics toward home health settings. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap biotech specialists with differentiated BTK inhibitor chemistry and incomplete commercial infrastructure. Long-term viability hinges on pipeline depth beyond covalent inhibition mechanisms and geographic diversification outside United States-Germany-Japan concentration. Monitor EMA benefit-risk guideline enforcement as signal for European pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Integrated TP53 and IGHV profiling streamlines patient selection for venetoclax-based protocols. |
| Non-Covalent BTK Inhibitor Advancement | Reversible binding mechanisms circumvent C481S resistance mutations in ibrutinib-failed populations. |
| Subcutaneous Formulation Reformulation | CD20-directed monoclonal antibody injection shifts administration from infusion centers to home health. |
| Real-World Evidence Platform Investment | Flatiron Health partnerships enable post-approval label expansion through retrospective outcome analysis. |
| Brazilian Regulatory Harmonization | ANVISA alignment with FDA standards accelerates SUS reimbursement list inclusion for 200 million covered lives. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market size estimates.
Comparable-period anchoring linked projection assumptions to historical therapy adoption curves across the analysis window, with segmentation modeling across treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs derived from epidemiological prevalence projections, mechanism-class switching rates, and reimbursement access evolution. Forecast inputs incorporated resistance mutation surveillance patterns and fixed-duration protocol penetration assumptions.
Inputs from clinical trial registries and payer policy databases were available through the study window; gaps in real-world progression-free survival data introduce uncertainty bands around long-term market share projections. Practitioners should monitor EMA overall survival data requirements and BTK C481S mutation prevalence trends for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Immunology Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Histamine Toxicity Market