
 Acrocallosal Syndrome Therapeutics Market | 2026-2036
Acrocallosal Syndrome Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Acrocallosal Syndrome Therapeutics Market Outlook
The gap between premium gene therapy development and commodity symptom management is rebalancing as payers demand clearer clinical evidence for high-cost interventions. Sanofi anchors its position through deep rare disease infrastructure and established regulatory pathways. Biogen differentiates by concentrating R&D spend on neurological genetic disorders with unmet need. Pfizer Inc. leverages global manufacturing scale to supply supportive care medications across dispersed patient populations.
Acrocallosal Syndrome therapeutics encompass pharmacological, surgical, and genetic interventions designed to manage congenital brain malformations, polydactyly, and associated developmental delays through modulation of SHH pathway dysfunction and corpus callosum anomalies. Gene therapy represents the fastest-expanding segment as CRISPR and targeted biologics advance through preclinical validation, while supportive care maintains the largest patient volume base due to immediate accessibility. Medications targeting symptom management occupy the most mature margin pool, though RNA interference platforms are attracting accelerated investment from research institutions seeking disease-modifying approaches.
FDA orphan drug exclusivity provisions and EMA's PRIME designation framework shape developer prioritization by compressing review timelines and reducing regulatory fees for qualifying therapies. The EU AI Act and HIPAA compliance requirements in the United States further constrain how patient genetic data flows into clinical trial recruitment and real-world evidence generation. Stakeholders must monitor how payer evidence frameworks evolve for ultra-rare conditions with single-digit patient counts per country.
Market Dynamics
The divergence between high-risk gene therapy platforms and established supportive care is forcing developers to prove clinical utility before premium pricing. Payers in the United States, Germany, and Japan are tightening evidence thresholds for ultra-rare neurological conditions with minimal patient pools.
Growth Catalysts
- Orphan drug incentives:FDA orphan drug exclusivity provisions compress review timelines and reduce regulatory fees for qualifying Acrocallosal Syndrome therapies. Developers prioritize these pathways for accelerated market entry.
- Pediatric clinic expansion:Dedicated rare disease centers in Boston, Heidelberg, and Osaka are building specialized multidisciplinary teams for corpus callosum anomaly management. These facilities aggregate patient volume for clinical trial recruitment.
- CRISPR platform maturation:Preclinical validation of targeted SHH pathway modulation is attracting institutional investment from research universities with established gene therapy manufacturing capabilities.
Market Restraints
- Single-source genetic material supply:AAV vector production concentrates among three contract manufacturers in the United States and Europe, creating capacity bottlenecks for gene therapy candidates.
- HIPAA compliance friction:United States patient genetic data restrictions constrain real-world evidence generation and natural history study recruitment for ultra-rare cohorts.
- Substitution by supportive care:Immediate accessibility of symptom management medications limits uptake of investigational disease-modifying approaches in resource-constrained settings.
Strategic Opportunities
- EMA PRIME designation leverage:European priority medicine frameworks offer accelerated assessment pathways that reduce time-to-market for eligible neurological genetic disorder therapies.
- RNA interference convergence:Combination of antisense oligonucleotide platforms with established pediatric neurology infrastructure opens disease-modifying approaches for developmental delay management.
- Direct-to-clinic distribution:Bypassing traditional wholesale channels through hospital-integrated specialty pharmacies reduces cold-chain complexity for biologic supportive care medications.
Industry Challenges
- Neurodevelopmental trial design complexity:Endpoint validation for corpus callosum anomaly interventions lacks standardized outcome measures accepted by FDA and EMA reviewers.
- Genetic counseling workforce scarcity:SHH pathway disorder expertise concentrates in academic medical centers, limiting patient identification and prenatal diagnostic referral networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrocallosal Syndrome Therapeutics Market |
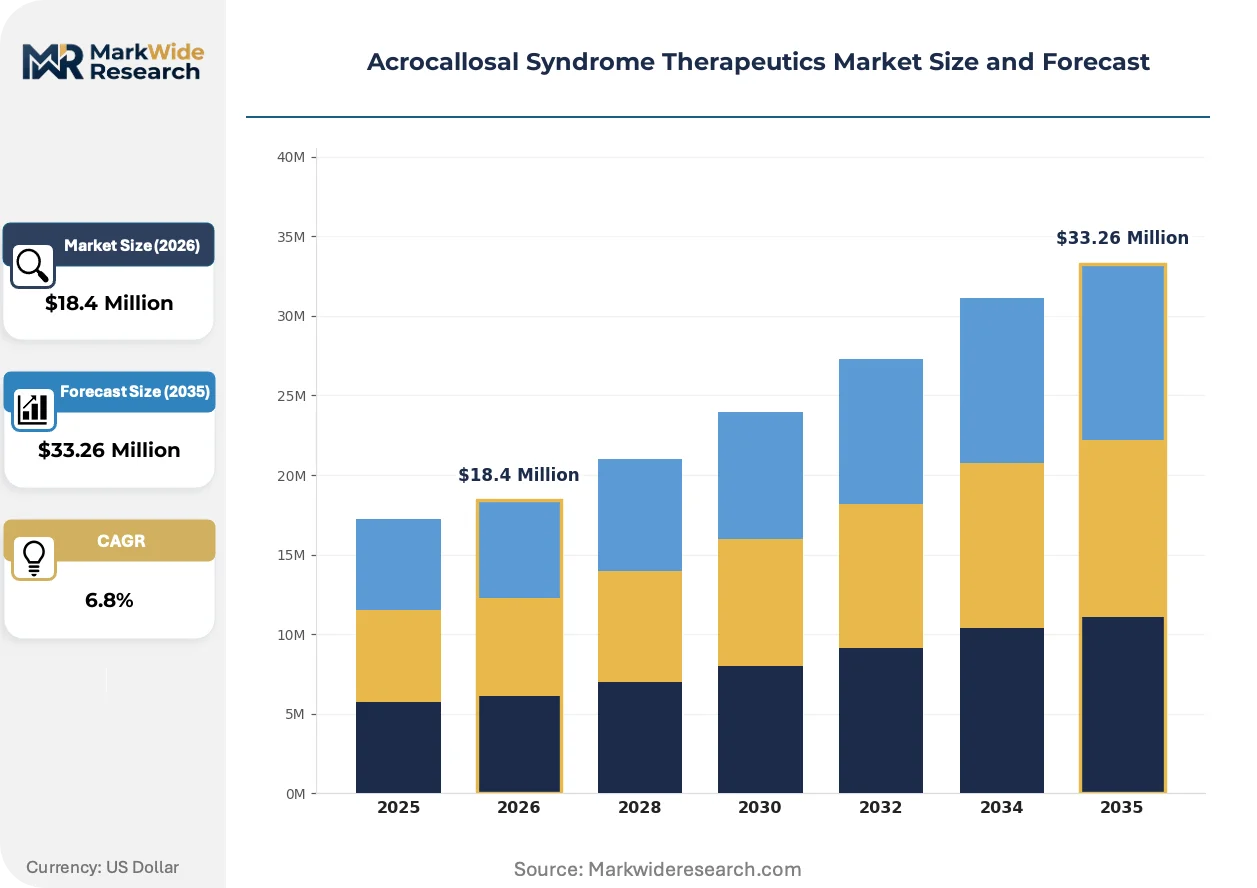
| Market Size in 2026 | $18.4 Million |
| Market Size in 2035 | $33.26 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Interventions, Gene Therapy, Supportive Care End User: Pediatric Clinics, Hospitals, Research Institutions, Home Care Technology: CRISPR, RNA Interference, Targeted Therapy, Biologics Application: Symptom Management, Genetic Counseling, Rehabilitation Services, Patient Support |
| Companies Covered | Sanofi, Biogen, Novartis AG, Takeda Pharmaceutical, Sarepta Therapeutics, Pfizer Inc., Vertex Pharmaceuticals, Eli Lilly and Company, Roche Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrocallosal Syndrome Therapeutics Market Strategic Shifts
Gene editing platforms are compressing development timelines for previously undruggable genetic targets while regulatory frameworks adapt to single-patient evidence generation. The tension between innovation velocity and payer sustainability is reshaping how developers sequence clinical programs.
CRISPR-Cas9 base editing is electrifying preclinical research into SHH pathway correction for corpus callosum anomalies. Academic medical centers in the United States and Japan are establishing dedicated rare disease gene therapy units. This technology is compressing the traditional decade-long development cycle for neurological genetic disorders into five-year validation timelines.
The EU AI Act imposes strict governance requirements on algorithmic tools used for polydactyly screening and genetic risk stratification in prenatal settings. Developers must document training data provenance and establish human oversight protocols for automated diagnostic outputs. European pediatric neurology networks are responding by segregating AI-assisted tools from clinical decision workflows until compliance certification completes.
Consolidated buying by United States children's hospital systems is displacing fragmented physician practice purchasing for supportive care medications. Procurement teams at Cincinnati Children's, Boston Children's, and Children's Hospital of Philadelphia are negotiating multi-year sole-source agreements for developmental delay symptom management. This concentration is most visible in the Northeast and Midwest regions where hospital network density enables volume-based contracting.
Acrocallosal Syndrome Therapeutics Market Segmentation
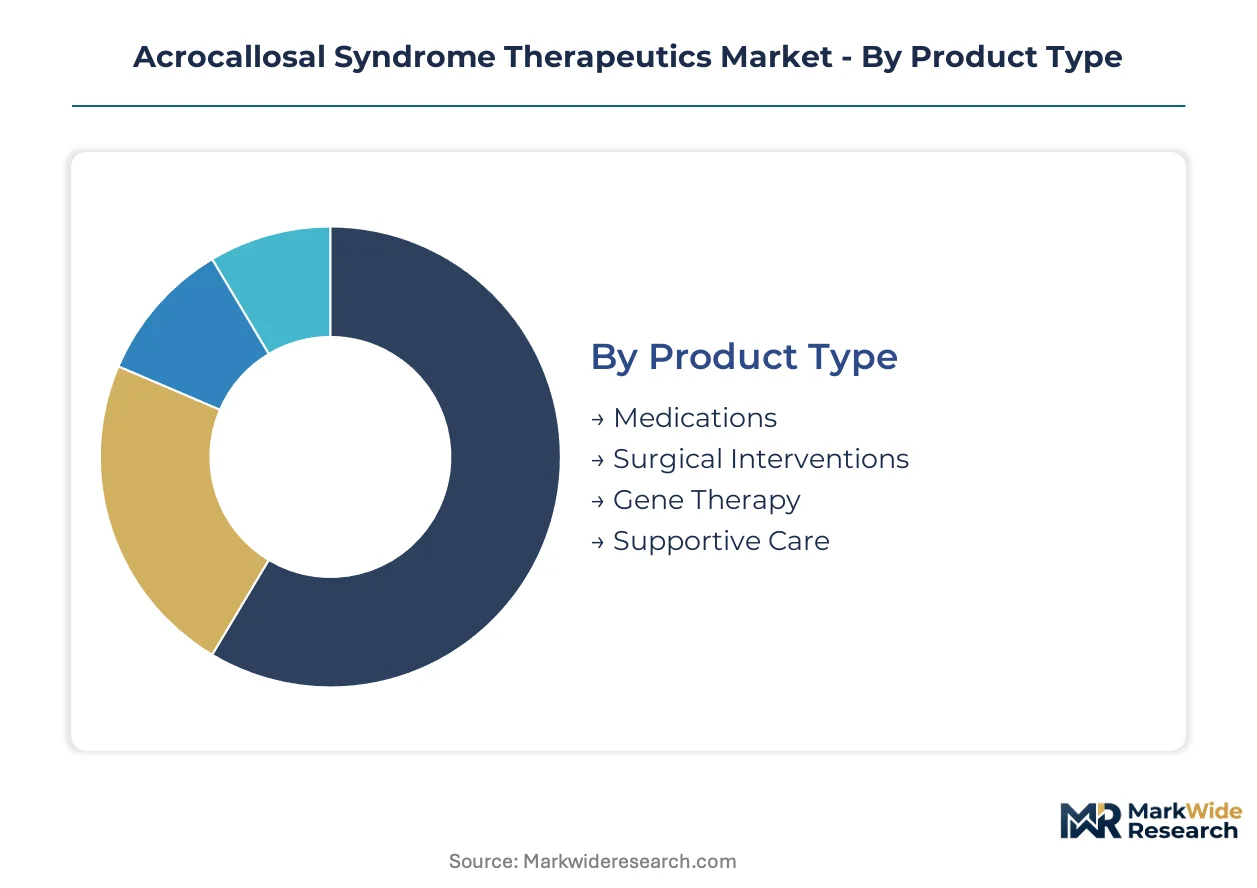
Acrocallosal Syndrome therapeutics span intervention modalities with vastly different development timelines and reimbursement profiles. Segmentation reveals where capital is concentrating versus where patient volume actually resides.
Product Type:
Upgrade cycles favor disease-modifying platforms over legacy supportive care, though accessibility constraints sustain demand for established options.
- Gene Therapy:CRISPR-based SHH pathway modulation targets corpus callosum anomalies at the genetic source. Academic medical centers in the United States and Japan are prioritizing these programs for their curative potential despite manufacturing complexity.
- Supportive Care:Developmental delay medications and seizure management protocols constitute the immediate-access tier for newly diagnosed patients. Demand concentrates in pediatric neurology departments at Boston Children's, Cincinnati Children's, and Heidelberg University Hospital where multidisciplinary teams manage symptom burden.
- Medications:Small-molecule and biologic formulations address polydactyly complications and hydrocephalus progression.
- Surgical Interventions:Craniofacial reconstruction and digit correction procedures require specialized pediatric surgical units.
Supportive Care sits at the top of the volume ranking, with Gene Therapy climbing the fastest.
End User:
Patient flow is consolidating into centers with dedicated rare disease infrastructure, displacing fragmented community-based management.
- Pediatric Clinics:Dedicated rare disease centers in Boston, Heidelberg, and Osaka aggregate patient volume for clinical trial recruitment and longitudinal care coordination.
- Hospitals:Tertiary academic medical centers house the surgical and intensive care capabilities required for complex congenital anomaly management.
- Research Institutions:University-affiliated gene therapy units conduct preclinical validation and early-phase trials for CRISPR platforms.
- Home Care:Family-administered developmental therapies and monitoring tools extend institutional protocols into residential settings.
Pediatric Clinics command the highest patient throughput per facility, with Research Institutions expanding capacity most aggressively.
Technology:
Platform maturation curves separate near-term deployable tools from multi-year development horizons.
- CRISPR:Base editing technologies compress validation timelines for SHH pathway correction, attracting institutional investment from research universities with established manufacturing capabilities.
- RNA Interference:Antisense oligonucleotide platforms offer intermediate-term disease-modifying potential for developmental delay management. European pediatric neurology networks are building infrastructure to deliver these therapies.
- Targeted Therapy:Small-molecule SHH pathway modulators address specific phenotypic expressions.
- Biologics:Recombinant protein and monoclonal antibody approaches manage inflammatory complications.
CRISPR captures the steepest investment trajectory, while RNA Interference bridges toward commercial viability.
Application:
Service bundling is shifting from episodic intervention toward continuous care coordination.
- Symptom Management:Pharmacological and rehabilitative protocols address seizures, motor deficits, and cognitive delays. Procurement teams at major children's hospital systems are consolidating purchasing for these medications.
- Genetic Counseling:Prenatal diagnostic referral networks identify at-risk pregnancies for SHH pathway disorders. Workforce scarcity limits expansion beyond academic medical centers.
- Rehabilitation Services:Physical, occupational, and speech therapy protocols adapt to developmental trajectories.
- Patient Support:Caregiver education and psychosocial services reduce hospitalization frequency.
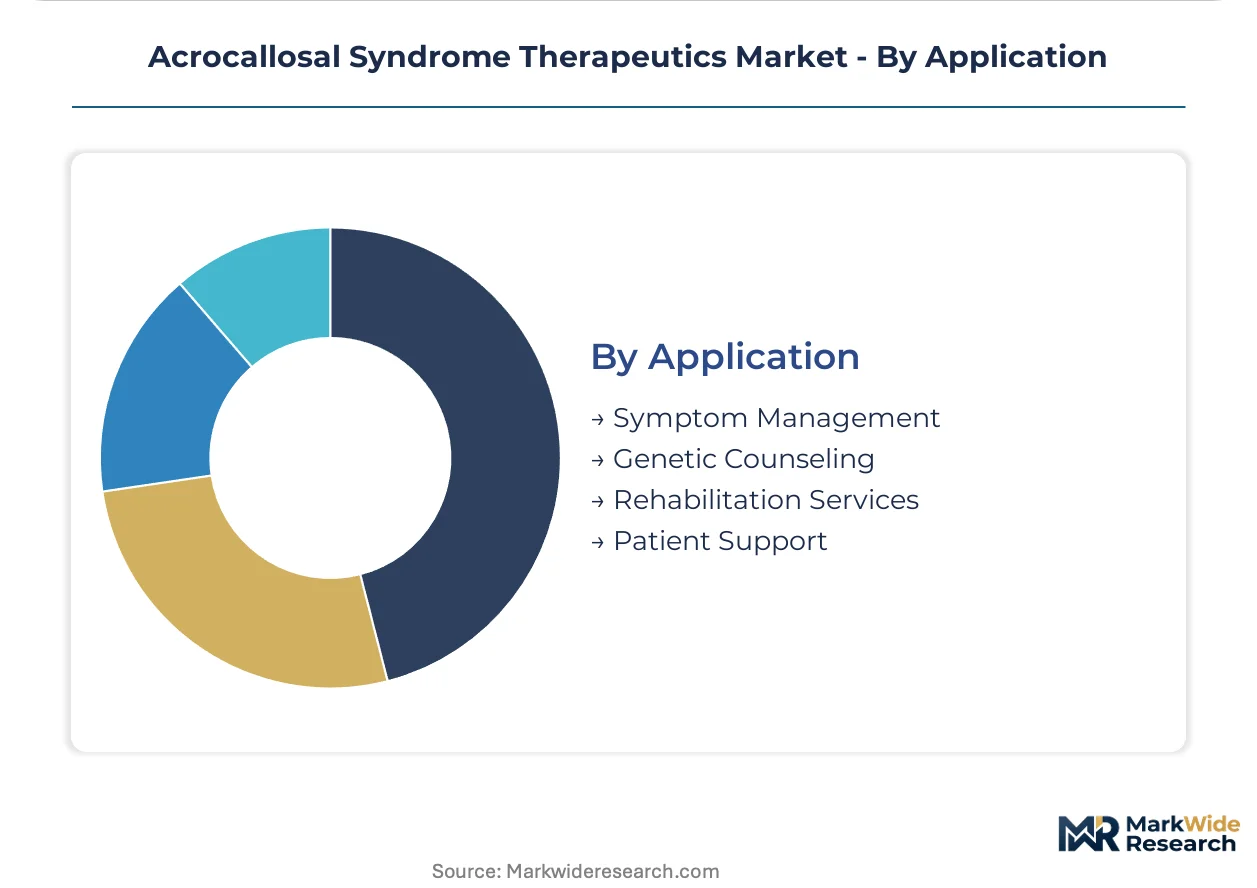
Symptom Management generates the highest service volume, with Genetic Counseling facing the most severe capacity constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pediatric neurology infrastructure outpaces German rare disease center density, though Heidelberg's corpus callosum research clusters rival Boston's patient recruitment volume. Japanese gene therapy manufacturing capabilities are compressing development timelines for SHH pathway interventions.
United States
FDA orphan drug exclusivity provisions attract developers to Acrocallosal Syndrome programs through compressed review timelines and fee reductions. HIPAA compliance requirements constrain how patient genetic data flows into clinical trial recruitment and natural history studies. Cincinnati Children's, Boston Children's, and Children's Hospital of Philadelphia negotiate multi-year sole-source agreements for developmental delay symptom management.
Germany
EMA PRIME designation frameworks accelerate assessment pathways for neurological genetic disorder therapies targeting corpus callosum anomalies. The EU AI Act imposes strict governance requirements on algorithmic tools used for polydactyly screening and genetic risk stratification. Heidelberg University Hospital anchors European multidisciplinary teams for rare disease management and longitudinal care coordination.
Japan
PMDA priority review vouchers and sakigake designation programs incentivize domestic development of gene therapies for ultra-rare congenital brain malformations. METI funding streams support academic medical centers establishing dedicated rare disease gene therapy units. Osaka's pediatric neurology networks aggregate patient volume for clinical trial recruitment and preclinical validation of CRISPR platforms.
United Kingdom
NHS England specialized commissioning frameworks concentrate Acrocallosal Syndrome care within designated rare disease centers. MHRA innovative licensing pathways enable early access to gene therapy candidates for developmental delay management. London's Great Ormond Street Hospital and Manchester's pediatric neurology units coordinate national referral networks for SHH pathway disorder expertise.
Switzerland
Swissmedic expedited access pathways reduce time-to-market for therapies addressing unmet needs in corpus callosum anomaly management. Federal research funding prioritizes RNA interference platforms through ETH Zurich and University of Basel gene therapy manufacturing partnerships. Basel's pharmaceutical cluster houses contract development organizations specializing in AAV vector production for neurological genetic disorders.
Acrocallosal Syndrome Therapeutics Market Competitive Environment
Top-tier vendors anchor rare disease infrastructure investments, while mid-cap gene therapy specialists concentrate R&D spend on neurological genetic disorders with minimal patient pools. The vendor base stratifies across three tiers: established pharmaceutical conglomerates with global regulatory pathways, biotechnology firms with platform-specific manufacturing capabilities, and emerging developers with preclinical CRISPR assets. Two strategic archetypes dominate: infrastructure-heavy incumbents leveraging orphan drug incentives for accelerated market entry, and platform-native specialists seeking disease-modifying validation. Competitive moves center on academic medical center partnerships for patient recruitment and AAV manufacturing capacity expansion through contract manufacturer alliances.
Within the infrastructure-heavy tier, Sanofi and Biogen occupy positions exemplifying divergent strategic postures toward ultra-rare neurological conditions. Sanofi represents the archetype of deep rare disease commercial infrastructure with established FDA and EMA regulatory pathways. Biogen exemplifies concentrated R&D allocation toward genetic neurological disorders with unmet medical need. Pfizer Inc. anchors the manufacturing-scale archetype, supplying supportive care medications across dispersed pediatric patient populations through global production networks.
| Leading Market Players |
|---|
| Sanofi |
| Biogen |
| Novartis AG |
| Takeda Pharmaceutical |
| Sarepta Therapeutics |
| Pfizer Inc. |
| Vertex Pharmaceuticals |
| Eli Lilly and Company |
| Roche Holding AG |
| Others |
Value Chain & Pricing Dynamics
EMA orphan drug fee waivers and FDA priority review voucher programs gate qualified supply access for developers while establishing premium-tier pricing floors for disease-modifying therapies. These regulatory incentives concentrate manufacturing investment among established AAV vector producers, compressing cost structures for gene therapy candidates while sustaining margin premiums for supportive care medications.
Pricing Analysis
Capacity additions in Switzerland and Japan are reshaping price floors for AAV vector manufacturing as Basel's contract development organizations expand GMP-compliant production suites. Three-tier pricing structure across premium gene therapy, standard biologic supportive care, and economy generic symptom management segments stratifies the market. Cost compression in the supportive care tier intensifies because consolidated children's hospital procurement teams negotiate multi-year sole-source agreements. Pediatric clinics demonstrate highest price sensitivity due to constrained reimbursement budgets, while research institutions show lowest sensitivity when accessing preclinical CRISPR platforms.
Supply Chain Analysis
AAV vector supply rests on contract manufacturers concentrated in the United States, Switzerland, and Germany, with gene therapy-grade plasmid DNA, HEK293 cell lines, and specialized chromatography resins constituting critical input dependencies. Single-source vulnerability characterizes the upstream tier where three producers control majority GMP capacity for neurological genetic disorder applications. Distribution runs through hospital-integrated specialty pharmacies for temperature-controlled biologics, bypassing traditional wholesale channels to reduce cold-chain complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA PRIME designation accelerates European market entry at lower regulatory cost than FDA orphan drug pathways, creating differential returns for developers sequencing geographic launches.
For Market Incumbents: Deploy regulatory exclusivity provisions as defensive moats against emerging CRISPR platform specialists. Secure AAV manufacturing capacity through captive supply agreements with Basel and Boston contract manufacturers. Counter substitution risk from supportive care medications by accelerating disease-modifying pipeline candidates through EMA accelerated assessment pathways. For New Entrants and Emerging Players: Capture white-space in RNA interference platforms for developmental delay management where European pediatric neurology networks lack established supplier relationships. Target Japan's sakigake designation pathway for fastest regulatory validation. Leverage direct-to-clinic distribution partnerships with Osaka and Heidelberg academic medical centers to bypass incumbent wholesale relationships. For Investors and Strategic Acquirers: Roll-up economics work for preclinical CRISPR asset aggregators because FDA and EMA review timelines compress when multiple SHH pathway candidates enter simultaneous validation. Five-to-ten year viability hinges on successful translation of base editing from academic medical center partnerships to commercial manufacturing. Watch PMDA gene therapy approval velocity as inflection indicator for Japanese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EMA PRIME Designation Pursuit | Accelerated assessment compresses time-to-market for Heidelberg and Boston clinic networks. |
| AAV Manufacturing Scale-Up | Basel contract development organizations expand GMP capacity for neurological genetic disorder candidates. |
| Pediatric Clinic Partnership | Cincinnati Children's and Osaka networks aggregate patient volume for clinical trial recruitment. |
| RNA Interference Platform Development | Antisense oligonucleotide approaches bridge toward commercial disease-modifying viability. |
| Direct-to-Clinic Distribution | Hospital-integrated specialty pharmacies reduce cold-chain complexity for biologic supportive care. |
Study Parameters
Direct dialogue with gene therapy development executives, regulatory affairs leads at EMA and FDA, pediatric neurology department heads, and hospital procurement managers anchored the qualitative foundation. Secondary validation drew from ClinicalTrials.gov entries, EMA PRIME designation databases, FDA orphan drug approval records, and Japanese PMDA sakigake designations. Bottom-up patient volume estimates across Boston, Heidelberg, and Osaka treatment centers triangulated against top-down market size calculations derived from supportive care medication procurement data.
Segment-level outputs across gene therapy, supportive care, medications, and surgical interventions were modeled over the projection horizon, with technology platforms disaggregated by CRISPR, RNA interference, targeted therapy, and biologics categories. CAGRs were derived from regression analysis against historical orphan drug approval timelines and pediatric rare disease center expansion rates. Forecast inputs incorporated EMA fee waiver program uptake, HIPAA compliance friction indices, and AAV manufacturing capacity utilization assumptions.
Regulatory pathway delays, AAV vector supply disruptions, and payer evidence threshold tightening are the dominant revision risks for Acrocallosal Syndrome therapeutic forecasts. Model outputs assume sustained orphan drug incentive structures and stable pediatric neurology infrastructure investment trajectories across the United States, Germany, and Japan. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Global Hereditary Angioedema Therapeutics Market