
 Sporothrix Schenckii Infection Treatment Market | 2026-2036
Sporothrix Schenckii Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Sporothrix Schenckii Infection Treatment Market Analytics
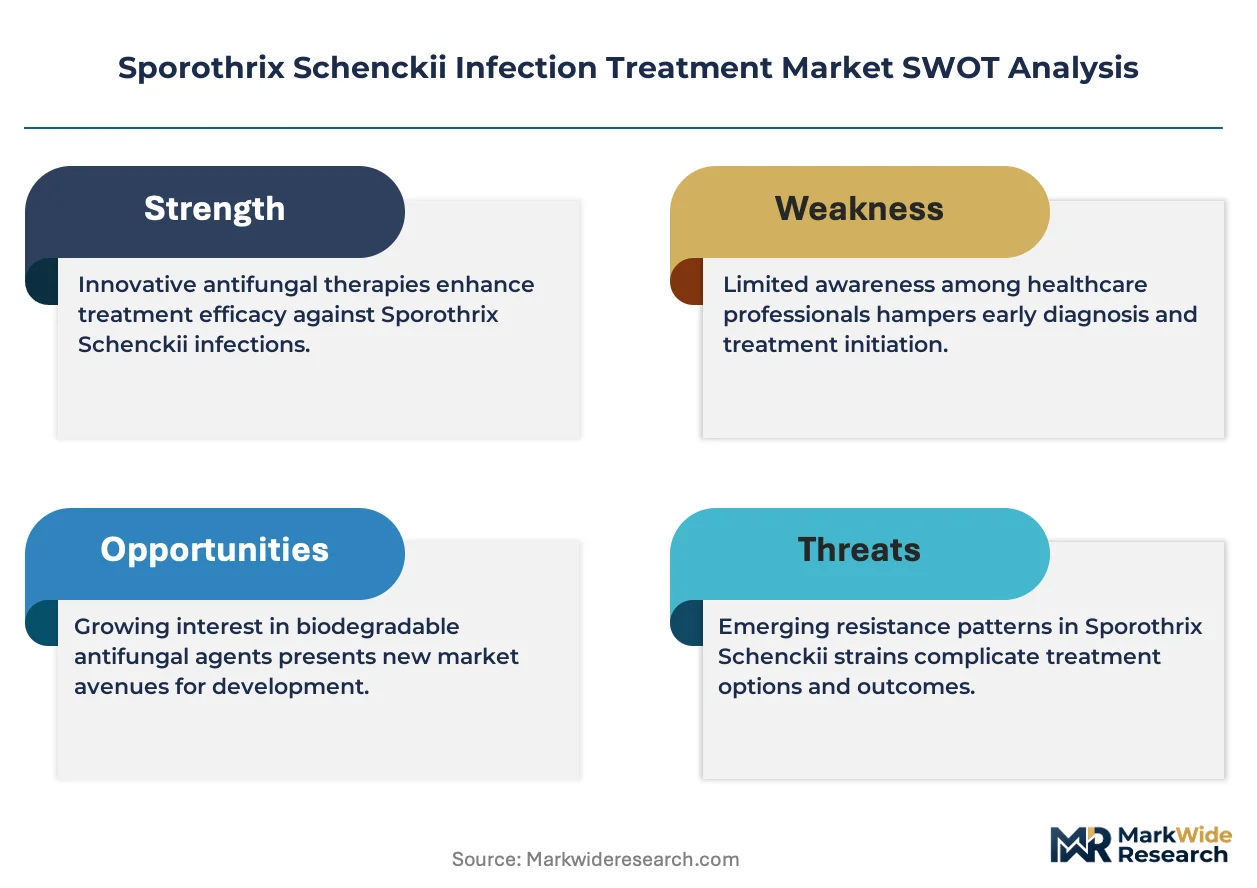
Fixed-dose combination packaging is shifting buyer preference toward bundled azole-polyene regimens that simplify adherence protocols. Pfizer Inc leverages its manufacturing scale to dominate oral itraconazole supply chains across Latin America. Merck Sharp & Dohme Corp. anchors its position through R&D intensity in novel antifungal formulations. Sandoz competes aggressively on cost-engineered generic azoles that penetrate clinic-tier procurement channels.
Sporothrix schenckii infection treatment encompasses pharmaceutical interventions targeting the dimorphic fungal pathogen Sporothrix schenckii, with azole compounds such as itraconazole functioning as first-line therapy through ergosterol biosynthesis inhibition in fungal cell membranes. The primary purpose centers on resolving subcutaneous, pulmonary, and disseminated manifestations in immunocompetent and immunocompromised hosts. Azoles occupy the largest revenue share due to established efficacy profiles and generic availability, while intravenous delivery modes capture premium margins in severe disseminated cases requiring hospital-based administration. Homecare settings represent the fastest-growing end-user channel as oral therapy protocols enable outpatient management of uncomplicated lymphocutaneous infections.
FDA antifungal guidance documents shape clinical trial endpoints and labeling requirements for new sporotrichosis therapies seeking US market access, while WHO fungal priority pathogen lists elevate national screening commitments in endemic regions. Brazil's national health surveillance agency, ANVISA, enforces import and quality standards that filter which azole formulations reach public hospital formularies. Stakeholders must monitor evolving resistance surveillance data and regulatory harmonization between national reference laboratories to anticipate shifts in first-line therapy designations.
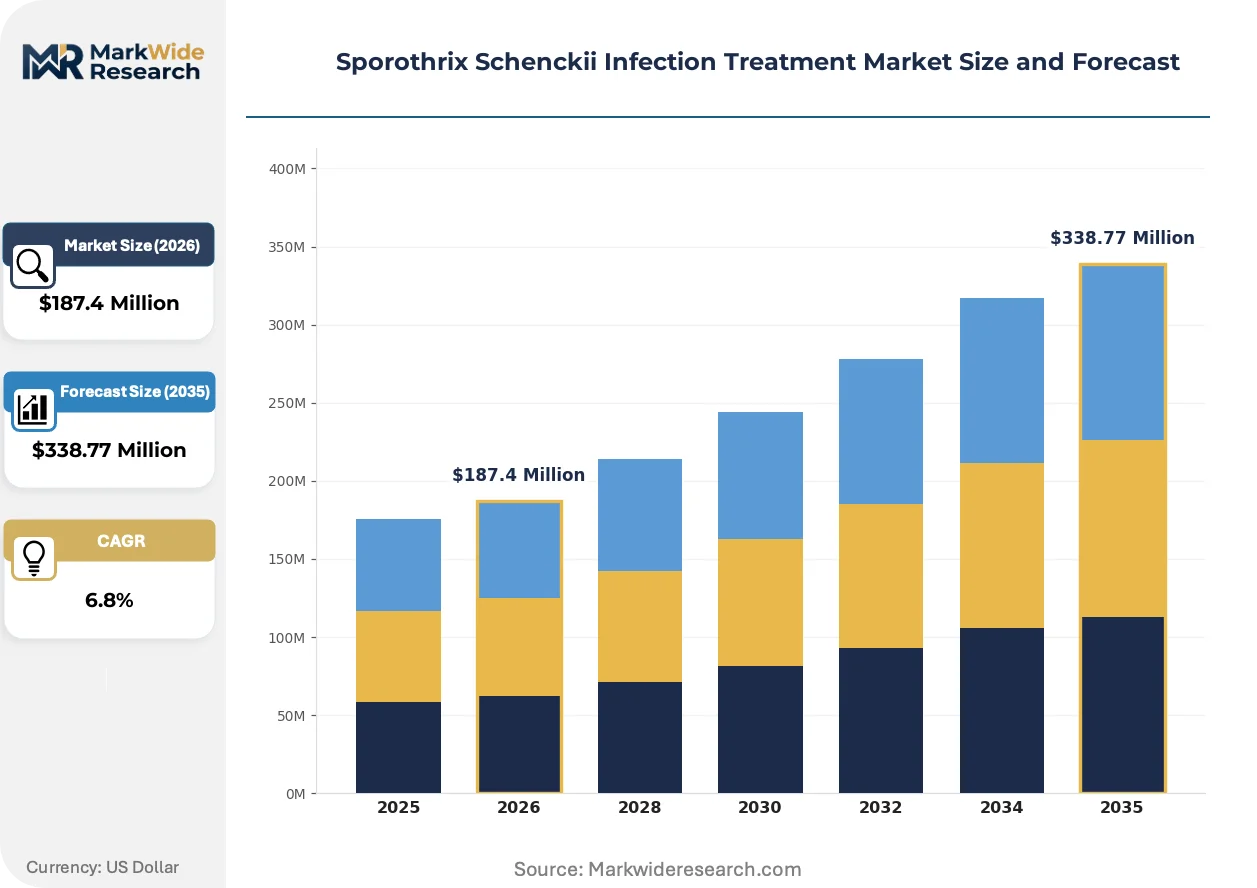
Market Dynamics
WHO fungal priority pathogen lists are reshaping national screening commitments and first-line therapy protocols across endemic regions, forcing health systems to reallocate diagnostic and procurement budgets toward sporotrichosis management.
Growth Catalysts
- ANVISA quality enforcement:Brazil's national health surveillance agency mandates stringent import standards for azole formulations, elevating product quality thresholds and consolidating demand around validated suppliers.
- Homecare therapy protocols:Oral itraconazole regimens enable outpatient management of lymphocutaneous infections, expanding addressable patient populations beyond hospital settings.
- WHO fungal pathogen prioritization:The framework elevates sporotrichosis on national infectious disease agendas, triggering dedicated budget lines for endemic region health ministries.
Market Restraints
- Azole supply concentration:Active pharmaceutical ingredient production clusters in select Asian manufacturing hubs, exposing formulators to single-source dependency risks.
- Polyene input cost volatility:Amphotericin B fermentation feedstock prices fluctuate with agricultural commodity cycles, compressing margin stability for intravenous therapy providers.
- Diagnostic access limitations:Mycological culture confirmation requires specialized laboratory infrastructure absent in rural clinic networks, delaying treatment initiation.
Strategic Opportunities
- Fixed-dose combination packaging:Bundled azole-polyene regimens simplify adherence protocols and create differentiation in clinic-tier procurement channels.
- Point-of-care molecular diagnostics:PCR-based Sporothrix identification at peripheral health posts collapses diagnostic timelines and accelerates appropriate therapy selection.
- Sub-regional Brazil expansion:Underpenetrated Amazon basin municipalities present volume potential as surveillance networks extend into remote riverine communities.
Industry Challenges
- Antifungal stewardship compliance:Hospital pharmacy committees impose restrictive azole utilization criteria, requiring extensive clinical documentation for therapy authorization.
- Cold chain integrity for intravenous formulations:Amphotericin B liposomal suspensions demand uninterrupted temperature control through last-mile distribution, complicating rural reach.
- Reference laboratory harmonization:Discordant susceptibility testing methodologies across national networks generate conflicting resistance surveillance data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sporothrix Schenckii Infection Treatment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoles, Polyenes, Echinocandins, Others Delivery Mode: Oral, Intravenous, Topical, Inhalation End User: Hospitals, Clinics, Homecare, Laboratories Therapy Area: Fungal Infections, Immunocompromised Patients, Infectious Diseases, Others |
| Companies Covered | Elanco, Sentosa Geigy, Mylan Pharmaceuticals Inc, Accord-UK Ltd, Avimedical B.V, Success Pharmaceuticals, Merck Sharp & Dohme Corp., Pfizer Inc, Sandoz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sporothrix Schenckii Infection Treatment Market Evolving Landscape
Oral therapy enablement and diagnostic decentralization are compressing hospital dependency while regulatory prioritization reshapes procurement hierarchies in endemic regions.
Liposomal amphotericin B formulations are decentralizing severe disseminated sporotrichosis management from tertiary referral centers toward district hospitals with basic infusion capabilities. Regional health directors in Brazil's endemic states are adopting these protocols to reduce patient transport burdens. This shift is compressing the premium pricing power historically concentrated in academic medical center procurement channels.
Brazil's ANVISA has tightened bioequivalence demonstration requirements for generic itraconazole submissions, extending regulatory review timelines for new market entrants. Domestic manufacturers must now submit expanded pharmacokinetic bridging studies to validate therapeutic equivalence claims. Generic azole suppliers are responding by consolidating pre-submission consulting resources and extending development runway assumptions.
Hospital formulary committees are unbundling antifungal procurement from bundled infectious disease contracts, creating direct negotiation windows with azole manufacturers. This fragmentation of purchasing authority is displacing centralized pharmacy benefit manager intermediaries in Brazil's public hospital networks. The pattern is most visible in São Paulo state's municipal health system, where individual facilities now execute direct purchase agreements for sporotrichosis therapies.
Sporothrix Schenckii Infection Treatment Market Segmentation
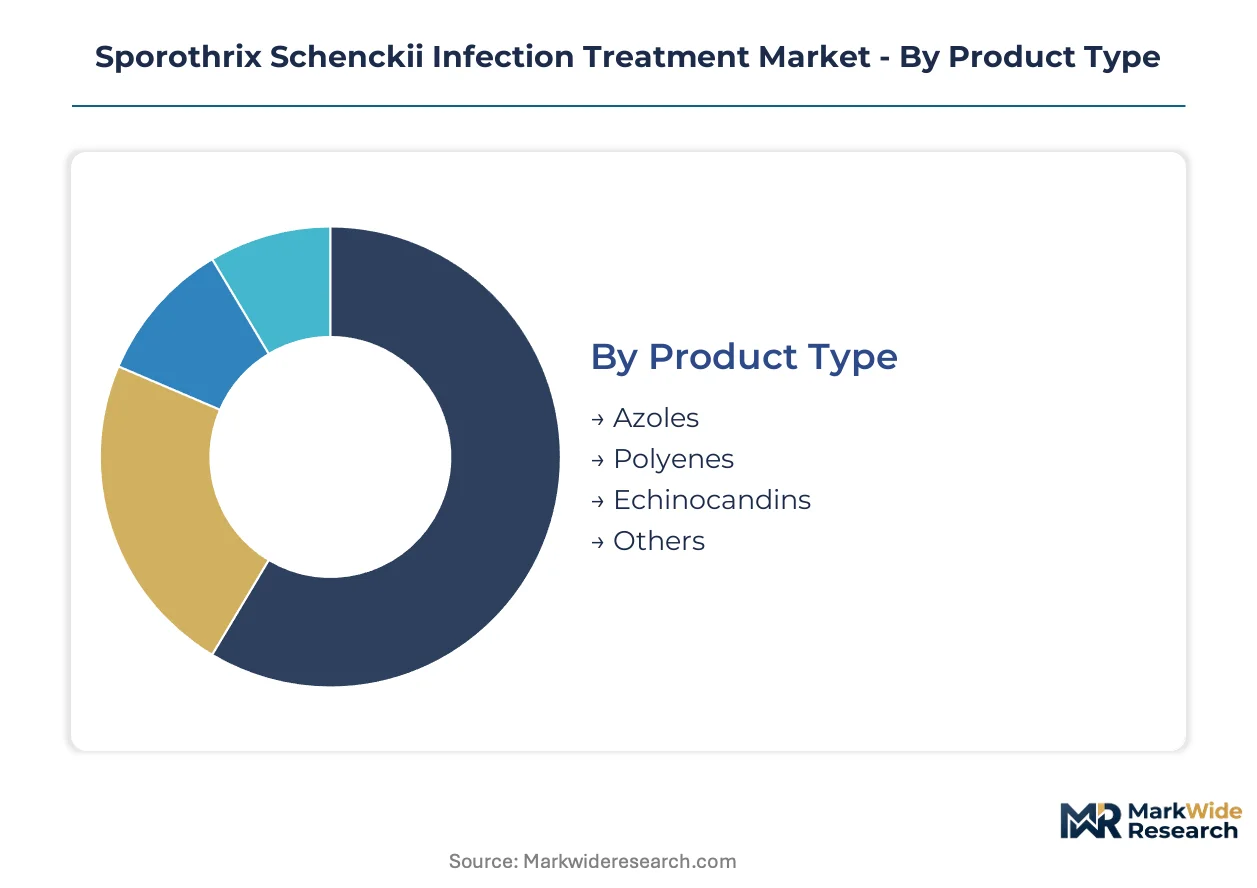
Therapy selection for Sporothrix schenckii infection hinges on matching pathogen presentation to pharmacokinetic profile. Segmentation reveals where formulation innovation intersects with care setting constraints and regulatory pathway requirements.
Product Type:
Azole formulations carry the heaviest bioequivalence demonstration burden under ANVISA's tightened generic approval framework. Polyene submissions face fermentation-derived API sourcing documentation requirements. Echinocandins and other antifungal classes navigate abbreviated pathways where reference drug availability determines trial design.
- Azoles:Itraconazole dominates first-line therapy through ergosterol biosynthesis inhibition in fungal cell membranes. Oral bioavailability enables outpatient lymphocutaneous management, with demand concentrating in Brazil's municipal hospital networks where formulary committees now execute direct procurement agreements.
- Polyenes:Amphotericin B formulations target severe disseminated cases requiring hospital-based intravenous administration. Liposomal suspensions command premium positioning in tertiary centers, though district hospital adoption is compressing historical academic medical center pricing power.
- Echinocandins:Caspofungin and micafungin alternatives serve salvage therapy protocols where azole intolerance or resistance emerges.
- Others:Terbinafine and potassium iodide reserve options persist in resource-limited settings with constrained azole access.
Leading the category by volume: Azoles. Growing fastest: Liposomal polyene formulations.
Delivery Mode:
Route selection determines cold chain infrastructure investment and reimbursement coding complexity. Oral and topical pathways minimize logistics burden; intravenous demands temperature-controlled distribution networks.
- Oral:Capsule and solution formulations of itraconazole anchor lymphocutaneous sporotrichosis management. Homecare enablement expands addressable populations beyond hospital catchment zones, particularly in Brazil's Amazon basin municipalities.
- Intravenous:Liposomal amphotericin B and conventional formulations serve pulmonary and disseminated presentations. Infusion capability requirements historically restricted access to tertiary centers; district hospital protocol adoption is redistributing volume.
- Topical:Limited utility for superficial cutaneous manifestations without lymphatic spread.
- Inhalation:Investigational delivery for pulmonary sporotrichosis remains preclinical.
Oral delivery captures the largest patient volume. Intravenous administration maintains the steepest expansion trajectory as district hospital capabilities mature.
End User:
Procurement authority fragmentation reshapes supplier engagement models. Hospital committees unbundle antifungal purchasing from infectious disease bundles; homecare channels demand patient adherence packaging innovation.
- Hospitals:Tertiary centers manage severe disseminated cases with intravenous polyene protocols. São Paulo state's municipal health system exemplifies direct manufacturer negotiation replacing centralized pharmacy benefit manager intermediation.
- Clinics:Peripheral health posts in endemic regions drive oral azole volume. Point-of-care molecular diagnostic integration accelerates appropriate therapy selection.
- Homecare:Oral itraconazole regimens enable outpatient lymphocutaneous infection management, representing the steepest channel expansion as surveillance networks extend into remote communities.
- Laboratories:Reference facilities perform culture confirmation and susceptibility testing, with discordant methodologies across national networks generating conflicting resistance surveillance data.
Hospitals retain the dominant procurement volume. Homecare channels are climbing the fastest as oral therapy protocols decentralize care.
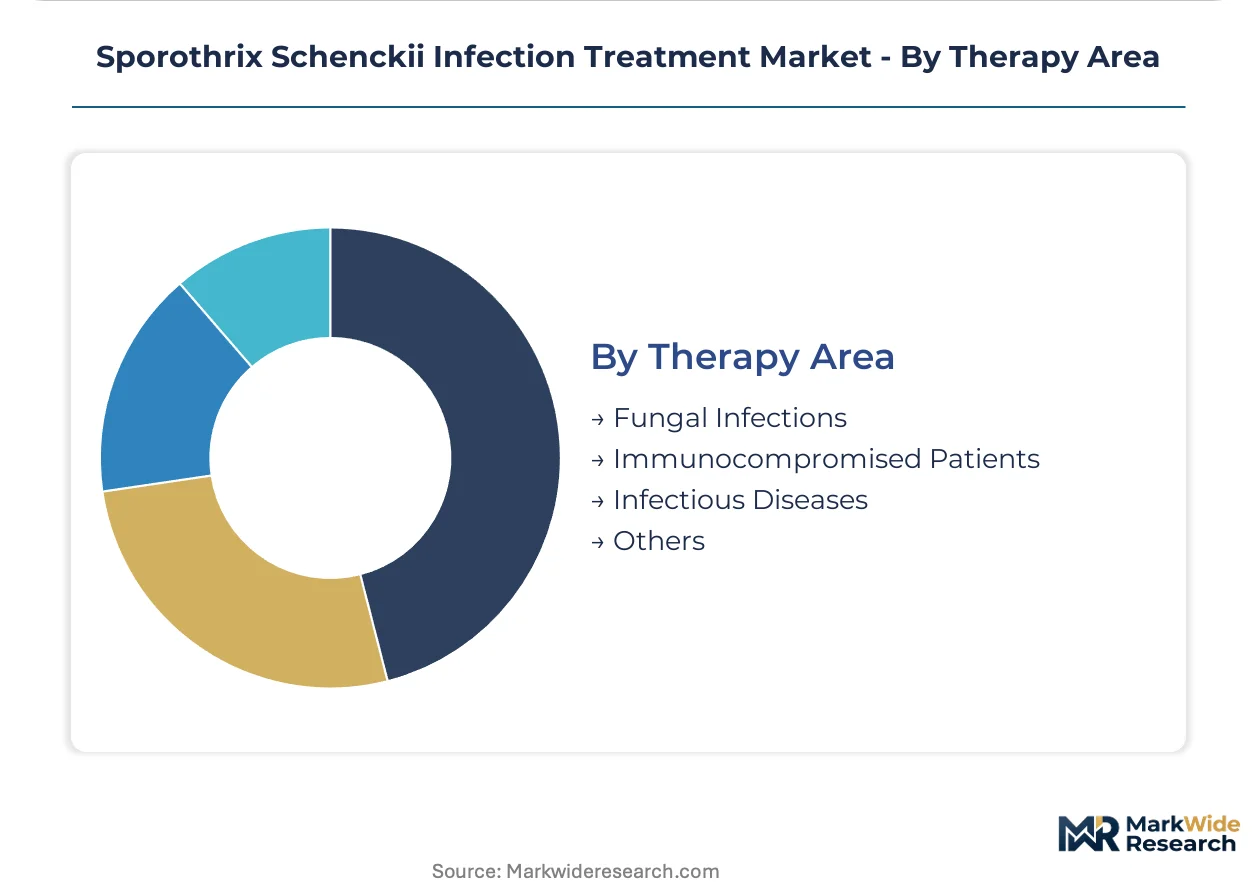
Therapy Area:
Patient immunocompetence status determines prophylaxis intensity and duration, with HIV co-infection and transplant immunosuppression expanding the addressable severe case population.
- Fungal Infections:Primary sporotrichosis presentations span subcutaneous nodular-lymphangitic, fixed cutaneous, and extracutaneous forms. Brazil's public health burden concentration drives national surveillance investment.
- Immunocompromised Patients:HIV-associated and iatrogenic immunosuppression cases require extended or combination therapy. Disseminated osteoarticular and meningeal involvement demands prolonged intravenous polyene courses.
- Infectious Diseases:Differential diagnosis complexity with leishmaniasis, nocardiosis, and atypical mycobacterial infection necessitates mycological confirmation.
- Others:Veterinary sporotrichosis zoonotic transmission management in endemic regions.
Fungal infections command the largest therapy volume. Immunocompromised patient protocols are gaining share fastest as HIV prevalence and transplant volumes rise in endemic regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Zona Franca de Manaus tax-incentive zone concentrates pharmaceutical manufacturing for Amazon basin distribution, anchoring regional supply chain architecture for sporotrichosis therapies.
Brazil
Sporotrichosis surveillance networks in São Paulo and Rio de Janeiro drive diagnostic infrastructure investment. ANVISA enforces stringent bioequivalence standards for generic itraconazole, extending regulatory review timelines. Municipal health systems in São Paulo state now execute direct procurement agreements with azole manufacturers, displacing centralized pharmacy benefit managers.
United States
FDA antifungal guidance documents shape clinical trial endpoints for novel sporotrichosis therapies seeking market access. Hospital formulary committees impose restrictive azole utilization criteria requiring extensive documentation. Academic medical centers in the Northeast corridor maintain premium pricing power for liposomal amphotericin B formulations.
Mexico
Subcutaneous mycosis endemic zones in Oaxaca and Chiapas generate demand for oral itraconazole protocols. The country's national pharmaceutical regulator filters import quality for public hospital formularies. Distribution networks from Mexico City radiate toward southern states with limited cold chain infrastructure.
Argentina
Lymphocutaneous sporotrichosis cases in northern provinces drive clinic-tier procurement of generic azoles. The national health ministry maintains sporotrichosis on its neglected tropical disease surveillance list. Buenos Aires-based reference laboratories perform culture confirmation for peripheral health posts.
Colombia
Cutaneous fungal infection burden in coffee-growing regions concentrates demand for topical and oral formulations. The national food and drug surveillance institute enforces import documentation for polyene formulations. Bogotá hospital networks coordinate with regional laboratories on susceptibility testing harmonization.
Sporothrix Schenckii Infection Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and distribution tiers. The vendor base clusters around three strategic archetypes: multinational pharmaceutical conglomerates with manufacturing scale, generic specialists competing on cost-engineered production, and regional distributors with endemic market access. Dominant competitive moves include direct procurement negotiations with municipal health systems and fixed-dose combination packaging to differentiate clinic-tier offerings.
Among multinational pharmaceutical conglomerates, Pfizer Inc and Merck Sharp & Dohme Corp. exemplify scale-driven positions in oral azole and novel formulation development respectively. Sandoz occupies a cost-leadership archetype within generic azole supply, while Mylan Pharmaceuticals Inc represents the mid-tier generic specialist segment. These three anchors collectively illustrate the competitive spectrum from premium branded positioning to volume-driven generic penetration.
| Leading Market Players |
|---|
| Elanco |
| Sentosa Geigy |
| Mylan Pharmaceuticals Inc |
| Accord-UK Ltd |
| Avimedical B.V |
| Success Pharmaceuticals |
| Merck Sharp & Dohme Corp. |
| Pfizer Inc |
| Sandoz |
| Others |
Value Network & Pricing Analysis
Captive itraconazole API production anchors pricing power for manufacturers with backward integration into fermentation capacity, insulating them from polyene feedstock volatility while forcing spot purchasers into premium positioning. This integration choice separates validated ANVISA suppliers from formulators exposed to Asian API import delays.
Pricing Analysis
Short lead-time premiums dominate hospital procurement negotiations, with same-week liposomal amphotericin B delivery commanding 15-30% markups over standard scheduling. Three-tier pricing structure across premium, standard, and economy levels reflects brand bioequivalence certification, volume commitment scale, and cold chain service bundling. Cost compression in generic azole tiers is intensifying because municipal health systems now execute direct manufacturer negotiations. Clinic-tier buyers in Brazil's Amazon basin exhibit highest price sensitivity, while tertiary academic medical centers maintain lowest sensitivity due to restricted formulary protocols.
Supply Chain Analysis
Dual-sourcing requirements for liposomal polyene formulations mandate multi-supplier qualification among Brazil's municipal hospital networks, forcing distributors to maintain redundant cold chain partnerships. Active pharmaceutical ingredient production draws from India, China, and select European fermentation hubs. Amphotericin B fermentation feedstocks, liposomal formulation excipients, and sterile vial packaging constitute critical input dependencies. Single-source vulnerability concentrates in liposomal suspension manufacturing capacity. Distribution runs through São Paulo-based regional depots with last-mile cold chain extension to Amazon basin municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity for amphotericin B API props pricing across intravenous therapy tiers, constraining supply elasticity and sustaining margin pools for integrated manufacturers.
For Market Incumbents: To counter municipal procurement unbundling, anchor hospital formulary position through direct negotiation contracts with São Paulo state health systems and deepen backward integration into itraconazole API fermentation to secure ANVISA validation timelines. For New Entrants and Emerging Players: Enter via point-of-care molecular diagnostic partnerships with Brazil's peripheral health posts, targeting underpenetrated Amazon basin municipalities where surveillance network extension creates first-mover access to oral azole prescribing channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking endemic market access. Long-term viability hinges on regulatory validation durability and diagnostic integration capabilities. Watch ANVISA bioequivalence enforcement intensity as inflection indicator for generic azole margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | Bundled azole-polyene packaging simplifies adherence protocols for Brazil's clinic-tier procurement channels. |
| Point-of-Care Diagnostic Integration | PCR-based Sporothrix identification at peripheral health posts accelerates appropriate therapy selection timelines. |
| ANVISA Bioequivalence Investment | Expanded pharmacokinetic bridging studies secure generic itraconazole approval pathways under tightened standards. |
| Direct Municipal Procurement Negotiation | Manufacturer agreements with São Paulo state health systems displace centralized pharmacy benefit manager intermediation. |
| Liposomal Formulation District Expansion | District hospital infusion capability adoption redistributes severe disseminated case volume from tertiary centers. |
Research Methodology
Multi-period observation of ANVISA approval timelines, municipal procurement contract structures, and resistance surveillance network expansion anchored the trend analysis, supplemented by interviews with formulary directors at Brazilian tertiary hospitals, regulatory affairs leads at generic azole manufacturers, infectious disease specialists at São Paulo state health ministries, and cold chain logistics operators serving Amazon basin municipalities. Secondary validation drew from FDA antifungal guidance documents, WHO fungal priority pathogen lists, ANVISA bioequivalence demonstration requirements, and hospital procurement database filings. Bottom-up patient volume estimates and top-down pharmaceutical sales data were triangulated to reconcile segmentation outputs.
Input-output matrices modeled therapy volume and value across product type, delivery mode, end user, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from segmented growth rate differentials applied to base-year estimates. Forecast inputs incorporated ANVISA enforcement intensity scenarios, district hospital infusion capability adoption curves, and point-of-care diagnostic penetration rates in endemic municipalities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANVISA regulatory harmonization delays or liposomal formulation cold chain infrastructure failures. Deviation in itraconazole API import authorization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Acromegaly Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Amino Acid Metabolism Disorders Treatment Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Congenital Neutropenia Treatment Market