
 Amyotrophic Lateral Sclerosis (ALS) Market | 2026-2036
Amyotrophic Lateral Sclerosis (ALS) Market Size, Share, and Industry Trends Forecast 2026-2036
Amyotrophic Lateral Sclerosis (ALS) Market Intelligence
Small-molecule platforms are repositioning long-standing assumptions about ALS drug economics, as oral formulations challenge the historical dominance of parenteral biologics. Ionis Pharmaceuticals leverages antisense oligonucleotide expertise to anchor its presence in genetic ALS subpopulations. Amylyx Pharmaceuticals differentiates through dual-mechanism oral therapies that sustain physician interest amid evolving treatment paradigms. Mitsubishi Tanabe Pharma competes via established regulatory relationships and manufacturing scale across multiple geographies.
Amyotrophic lateral sclerosis denotes a progressive neurodegenerative disorder characterized by upper and lower motor neuron degeneration, with diagnostic criteria requiring evidence of both corticospinal tract dysfunction and anterior horn cell involvement through electromyography or neuroimaging. The condition demands sustained multidisciplinary intervention spanning pharmacotherapy, respiratory support, and nutritional management to extend functional independence. Pharmaceuticals and biologics command the dominant margin pools, reflecting the premium pricing attached to disease-modifying mechanisms versus symptomatic agents. The injectable delivery mode leads in revenue concentration due to biologic administration requirements, though oral pathways in clinical development are expanding prescriber choice and patient adherence potential.
The FDA's accelerated approval pathway and the EMA's conditional marketing authorization framework both shape ALS product development timelines and reimbursement negotiations across their respective jurisdictions. The FDA's orphan drug incentives, including tax credits and market exclusivity provisions, directly influence portfolio prioritization decisions among developers targeting this indication. Stakeholders must monitor evolving biomarker validation efforts and payer willingness to accept surrogate endpoints, as these factors will determine which mechanisms progress from accelerated to full approval status.
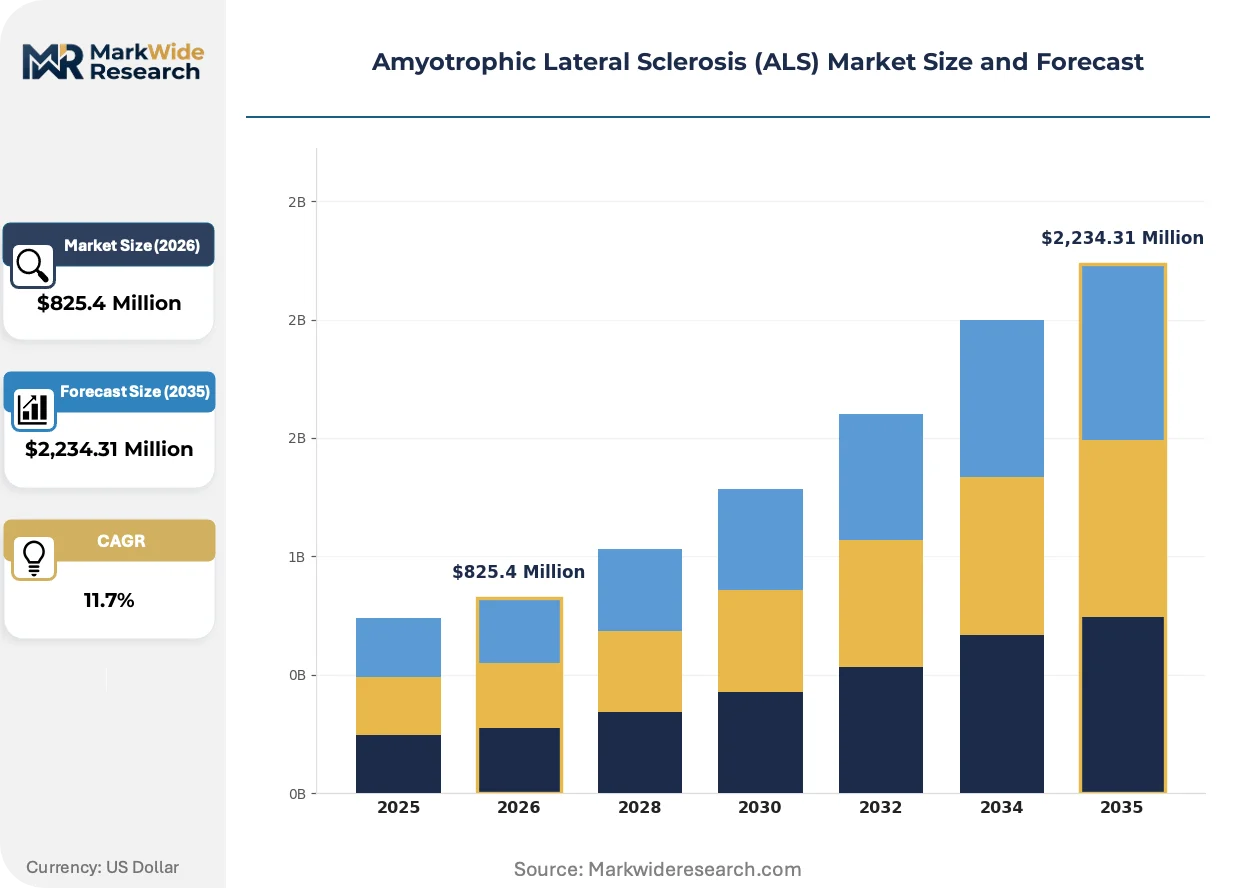
Market Dynamics
The FDA's accelerated approval framework is compressing development timelines for disease-modifying ALS therapies, while biomarker validation efforts are reshaping how surrogate endpoints gain payer acceptance across jurisdictions.
Growth Catalysts
- Orphan drug incentives:The FDA's tax credit provisions and seven-year market exclusivity accelerate portfolio prioritization decisions among developers targeting rare neurodegenerative indications.
- Specialist network expansion:Dedicated ALS care pathways in neurology clinics across the United States and Germany are concentrating referral volumes and treatment initiation rates.
- Antisense oligonucleotide platforms:Genetic subpopulation targeting through precision mechanisms is expanding addressable patient segments previously excluded from broad-spectrum trials.
Market Restraints
- Biologic manufacturing concentration:Parenteral formulation production clusters in contract manufacturing organizations across Switzerland and Ireland, creating single-source vulnerabilities for global supply.
- Reimbursement friction:Payer skepticism toward surrogate endpoints under EMA conditional marketing authorization limits commercial uptake in European markets pending confirmatory trial readouts.
- Diagnostic latency:Electromyography confirmation requirements and corticospinal tract dysfunction documentation extend time-to-treatment initiation by 12-18 months in most healthcare systems.
Strategic Opportunities
- Oral formulation development:Small-molecule platforms challenging injectable biologic dominance are capturing prescriber preference for patient adherence and home administration feasibility.
- Respiratory support integration:Non-invasive ventilation and nutritional management device bundling with pharmaceutical protocols creates service-based revenue expansion in multidisciplinary care models.
- Japan's regulatory pathway:PMDA's Sakigake designation system offers priority review and early reimbursement listing for novel ALS mechanisms demonstrating preliminary efficacy signals.
Industry Challenges
- Trial recruitment scarcity:Rare disease prevalence limits eligible cohort sizes, forcing sponsors to operate 15-20 active sites simultaneously across North America and Western Europe to achieve statistical power.
- Biomarker standardization delays:Lack of consensus on neurofilament light chain and other fluid biomarker thresholds complicates patient stratification and regulatory submission packages.
- Cross-functional talent gaps:Integration of neurology, respiratory therapy, and palliative care expertise within single care teams strains workforce availability in secondary and tertiary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amyotrophic Lateral Sclerosis (ALS) Market |
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $2,234.31 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biologics, Nutritional Supplements, Medical Devices Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Home Care, Research Institutions Application: Symptom Management, Disease Modification, Clinical Trials, Palliative Care |
| Companies Covered | Ionis Pharmaceuticals, Amylyx Pharmaceuticals, Mitsubishi Tanabe Pharma, BrainStorm Cell Therapeutics, Cytokinetics, Sanofi, Otsuka Pharmaceutical, AB Science, Biogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amyotrophic Lateral Sclerosis (ALS) Market Strategic Shifts & Innovations
Multimodal mechanism combinations and real-world evidence generation are displacing monotherapy development paradigms, while digital biomarker platforms are compressing clinical observation windows.
Antisense oligonucleotide technology is consolidating genetic ALS subpopulation targeting as its core function. Academic medical centers and specialist referral networks in the United States and Germany are adopting platform-based screening protocols at accelerated pace. This mechanism is consolidating developer pipelines around precision indications rather than broad sporadic ALS populations, compressing competitive differentiation timelines.
REACH authorization requirements for novel chemical entities are tightening environmental fate documentation obligations for small-molecule ALS drug candidates. European manufacturers now face extended pre-submission consultation timelines with ECHA regarding persistent, bioaccumulative, and toxic substance classifications. Oral formulation developers targeting EU market access are responding by reformulating active pharmaceutical ingredients to meet biodegradability thresholds ahead of MDR implementation deadlines.
Specialist referral networks are consolidating treatment initiation decisions away from general neurology practices toward dedicated ALS center accreditation models. United States payers are channeling prior authorization requirements through certified multidisciplinary clinics, displacing community-based prescribing. This concentration is most visible in Medicare Advantage plan designs across the Northeast and Midwest, where network adequacy rules now mandate minimum annual patient volumes for continued formulary inclusion.
Amyotrophic Lateral Sclerosis (ALS) Market Segmentation
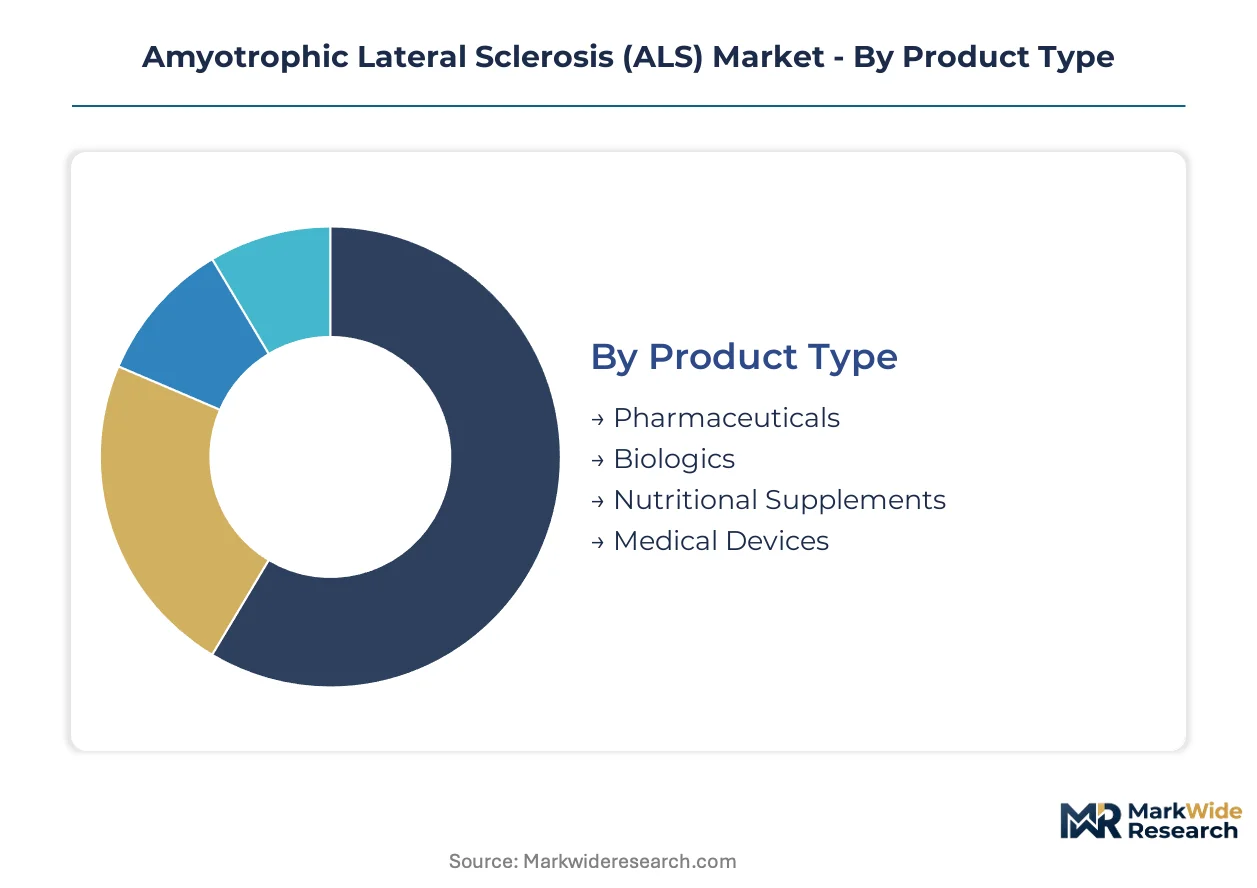
ALS market segmentation reflects divergent regulatory pathways and reimbursement mechanisms across therapeutic modalities. Product type and delivery mode distinctions determine which segments access accelerated approval frameworks versus standard review timelines.
Product Type:
Certification burdens concentrate in pharmaceuticals and biologics, where FDA orphan drug designation and EMA conditional marketing authorization create tiered approval timelines. Nutritional supplements and medical devices navigate distinct regulatory channels with lower evidentiary thresholds.
- Pharmaceuticals:Small-molecule compounds targeting glutamate modulation or mitochondrial function comprise the traditional therapeutic backbone. Demand concentrates in the United States, where Medicare Part D coverage for riluzole and edaravone establishes reimbursement benchmarks that European payers reference.
- Biologics:Antisense oligonucleotides and monoclonal antibodies require parenteral administration and cold-chain logistics. Germany's statutory health insurance system has pioneered outcome-based reimbursement contracts for genetic ALS subpopulations, creating a reference market for risk-sharing agreements.
- Nutritional Supplements:Enteral feeding formulations and metabolic support products face lighter FDA oversight as medical foods. Japan's PMDA has streamlined approval for amyotrophic lateral sclerosis-specific nutritional interventions under the Sakigake pathway.
- Medical Devices:Non-invasive ventilation systems and communication aids fall under FDA 510(k) or EU MDR Class IIa/IIb pathways. Swissmedic maintains stringent post-market surveillance requirements for respiratory support devices distributed across Alpine healthcare networks.
Pharmaceuticals sits at the top of the volume ranking, with biologics climbing the fastest.
Delivery Mode:
Cost tier differentiation separates hospital-administered intravenous infusions from home-based oral regimens, with reimbursement rates scaling to supervision intensity.
- Oral:Tablet and capsule formulations eliminate infusion center dependency and enable patient self-administration. United States specialty pharmacies capture dispensing margins for oral ALS therapies, with prior authorization automation reducing administrative friction.
- Injectable:Subcutaneous and intramuscular delivery accommodates biologics with poor oral bioavailability. Ireland's contract manufacturing cluster supplies pre-filled syringes for European distribution, leveraging FDA mutual recognition agreements.
- Transdermal:Patch-based delivery remains experimental for ALS, with academic medical centers in the Netherlands conducting pilot studies for dopaminergic symptom control.
- Intravenous:Hospital-based infusion requires nursing supervision and creates site-of-care cost differentials. French ANSM has mandated real-world evidence collection for all intravenous ALS therapies receiving temporary reimbursement authorization.
Oral formulations command the broadest prescriber base, while intravenous delivery retains the highest per-dose reimbursement rates.
End User:
Application maturity varies across care settings, with multidisciplinary ALS centers displacing general neurology practices for treatment initiation decisions.
- Hospitals:Tertiary academic centers coordinate respiratory support, nutritional intervention, and clinical trial enrollment. The Cleveland Clinic and Mayo Clinic anchor referral networks that concentrate patient volumes for disease-modifying therapy access.
- Clinics:Dedicated ALS centers in Germany's university hospital system achieve diagnostic latency reductions through standardized electromyography protocols. Payer network adequacy rules in US Medicare Advantage plans increasingly mandate minimum annual patient volumes for formulary inclusion.
- Home Care:Palliative nursing and respiratory therapy services extend functional independence outside institutional settings. Japan's long-term care insurance system reimburses home ventilation support with fewer utilization restrictions than US Medicare.
- Research Institutions:Academic medical centers manage natural history studies and expanded access programs. The Sean M. Healey & AMG Center for ALS at Massachusetts General Hospital maintains one of the largest prospective cohort registries globally.
Hospitals retain the highest patient acuity mix, with home care expanding most quickly as non-invasive ventilation technology improves.
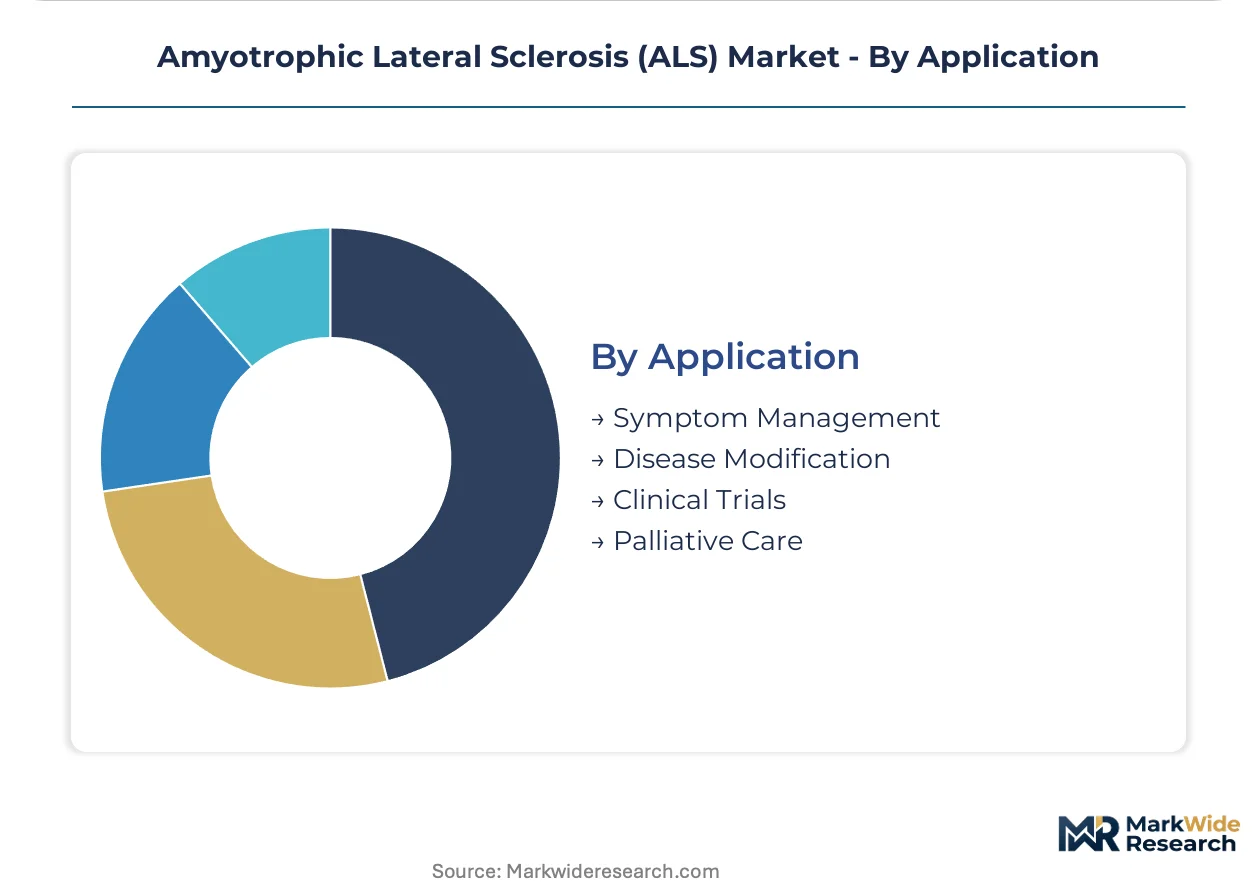
Application:
Margin concentration follows mechanism of action, with disease-modifying therapies commanding premium pricing over symptomatic agents.
- Symptom Management:Spasticity control, sialorrhea management, and pseudobulbar affect treatment address quality-of-life endpoints. FDA-approved therapies for ALS-associated symptoms face less stringent evidentiary requirements than disease-modifying candidates.
- Disease Modification:Neuroprotective and antisense mechanisms target survival and functional decline. The FDA's accelerated approval pathway has compressed development timelines for therapies demonstrating effects on surrogate biomarkers like neurofilament light chain.
- Clinical Trials:Natural history studies and interventional protocols generate revenue through site fees and per-patient payments. Western European regulatory harmonization enables single-protocol studies across multiple EMA member states.
- Palliative Care:End-of-life symptom control and advance care planning integration falls outside pharmaceutical revenue concentration. Hospice reimbursement in the United States operates under Medicare Part A with fixed per-diem rates.
Disease modification captures the steepest pricing premiums, with clinical trials gaining share fastest as biomarker-stratified recruitment protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Massachusetts biotechnology corridor anchors ALS therapeutic development, concentrating antisense oligonucleotide research and specialist clinical trial infrastructure. FDA accelerated approval pathways and orphan drug incentives have established the United States as the primary commercialization venue. Germany, Japan, and Switzerland maintain complementary positions through differentiated regulatory frameworks and manufacturing specialization.
United States
Specialist referral networks in the Northeast and Midwest concentrate treatment initiation decisions through Medicare Advantage prior authorization requirements. FDA orphan drug tax credits and seven-year market exclusivity provisions accelerate portfolio prioritization among developers. The Sean M. Healey & AMG Center at Massachusetts General Hospital anchors one of the largest prospective ALS cohort registries globally.
Germany
Statutory health insurance outcome-based reimbursement contracts for genetic ALS subpopulations create reference markets for risk-sharing agreements. EMA conditional marketing authorization frameworks shape payer negotiations pending confirmatory trial readouts. University hospital systems in Bavaria and North Rhine-Westphalia achieve diagnostic latency reductions through standardized electromyography protocols.
Japan
PMDA's Sakigake designation system offers priority review and early reimbursement listing for novel mechanisms demonstrating preliminary efficacy signals. Long-term care insurance reimburses home ventilation support with fewer utilization restrictions than comparable US programs. The Kanto region around Tokyo concentrates regulatory consulting expertise for neurology-focused submissions.
Switzerland
Contract manufacturing organizations across Basel and Zurich supply pre-filled syringes for European distribution under FDA mutual recognition agreements. Swissmedic maintains stringent post-market surveillance requirements for respiratory support devices across Alpine healthcare networks. The country's statutory health insurance system provides predictable reimbursement for orphan neurology indications.
Amyotrophic Lateral Sclerosis (ALS) Market Key Industry Players
Strategic partnerships dominate the current landscape as developers seek to combine antisense platforms with small-molecule mechanisms. The market exhibits tiered concentration, with large-cap biopharmaceuticals controlling manufacturing scale and mid-cap specialists anchoring precision genetic targeting. Three archetypes prevail: antisense oligonucleotide platform holders, dual-mechanism oral therapy developers, and established neurology portfolio incumbents. Portfolio diversification and geographic expansion through regulatory relationship leverage represent the dominant competitive vectors.
Within the precision genetic tier, Ionis Pharmaceuticals exemplifies antisense platform specialization, while Amylyx Pharmaceuticals occupies a position emphasizing oral formulation development. Mitsubishi Tanabe Pharma represents the established regulatory incumbent archetype, leveraging manufacturing scale across multiple jurisdictions.
| Leading Market Players |
|---|
| Ionis Pharmaceuticals |
| Amylyx Pharmaceuticals |
| Mitsubishi Tanabe Pharma |
| BrainStorm Cell Therapeutics |
| Cytokinetics |
| Sanofi |
| Otsuka Pharmaceutical |
| AB Science |
| Biogen |
| Others |
Cost & Logistics Intelligence
Orphan-drug premium tiers diverge sharply from symptomatic-agent commodity pricing, with FDA accelerated approval pathways and seven-year exclusivity provisions anchoring the former while generic glutamate modulators compete on volume in the latter. This bifurcation concentrates manufacturing investment in cold-chain biologics facilities across Switzerland and Ireland, while oral small-molecule production disperses to lower-cost contract sites.
Pricing Analysis
Input-cost pass-through from single-source antisense oligonucleotide manufacturing concentrates pricing power with Ionis Pharmaceuticals and platform holders commanding genetic ALS subpopulations. Three-tier pricing structure across premium biologics, standard small-molecules, and economy symptomatic agents reflects certification intensity and administration mode. Cost compression in the oral standard tier intensifies as Amylyx Pharmaceuticals and Mitsubishi Tanabe Pharma expand manufacturing scale. Hospital procurement committees exhibit highest price sensitivity for intravenous infusion regimens requiring nursing supervision, while Medicare Part D plans absorb premium biologic costs through orphan drug carve-outs.
Supply Chain Analysis
Reverse-logistics flows for refrigerated biologics create specialized return pathways for expired antisense oligonucleotides and temperature-deviated shipments, with Switzerland and Ireland anchoring European cold-chain recovery operations. Active pharmaceutical ingredient sourcing draws from Indian and Chinese chemical manufacturers for small-molecule precursors, while parenteral formulation fill-finish rests on Swiss and Irish contract manufacturing clusters. Single-source vulnerability concentrates in pre-filled syringe production for genetic subpopulation therapies. Distribution runs through United States specialty pharmacies capturing dispensing margins, with hospital-based infusion centers retaining intravenous biologic administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
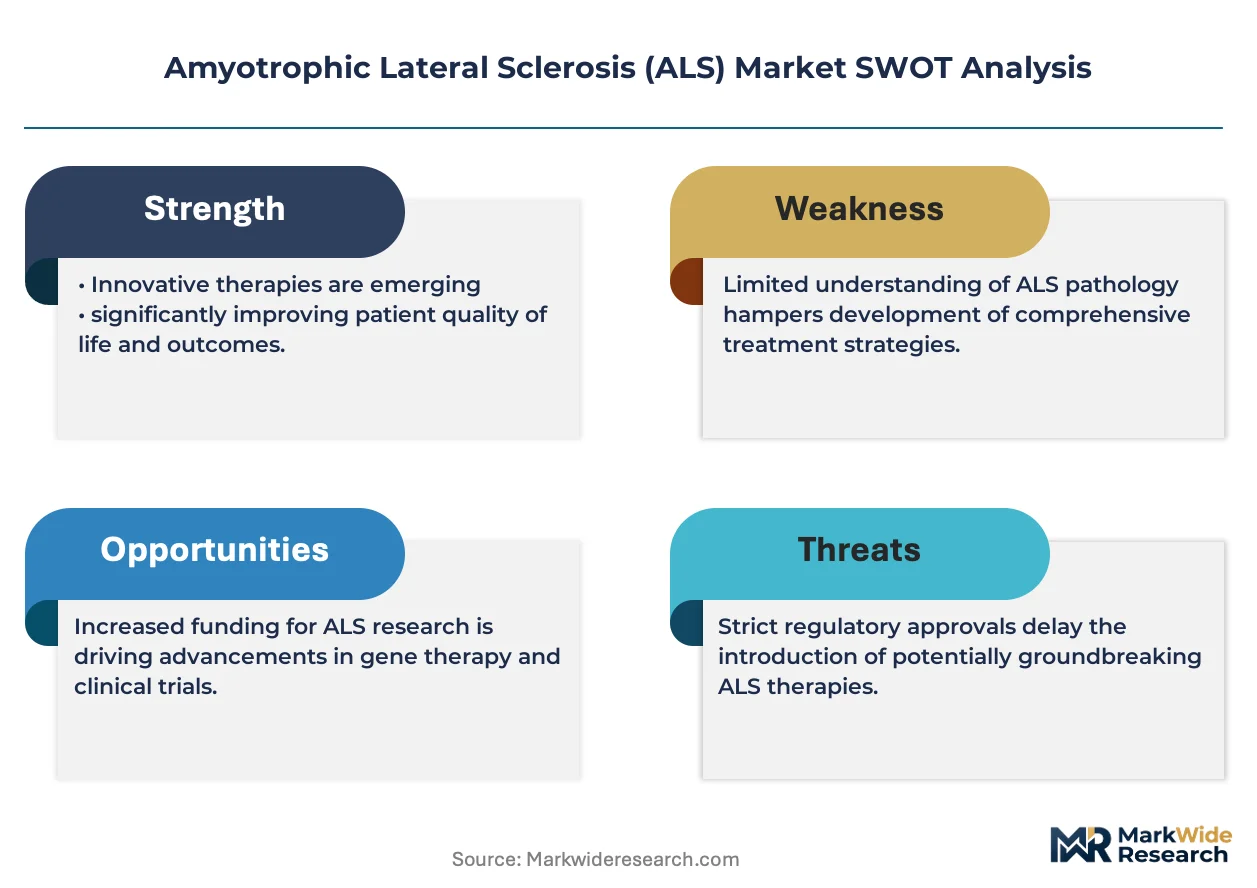
The ALS market compounds steadily as orphan drug incentives and specialist network expansion concentrate treatment initiation in accredited multidisciplinary centers. FDA accelerated approval frameworks and biomarker validation efforts sustain pipeline investment across mechanism classes.
For Market Incumbents: Cement antisense platform dominance through backward integration into oligonucleotide manufacturing capacity in Basel and Zurich, securing supply continuity against Irish contract manufacturing bottlenecks. Expand specialist referral network accreditation requirements in United States Medicare Advantage plans to channel prior authorization through certified ALS centers, displacing community neurology prescribing and defending margin position against oral small-molecule entrants.
For New Entrants and Emerging Players: Telemedicine-enabled diagnostic pathways offer lowest-friction entry into diagnostic latency reduction, targeting the 12-18 month electromyography confirmation gap with remote neurophysiology screening protocols. Japan's PMDA Sakigake designation provides the most penetrable regulatory route for novel mechanisms demonstrating preliminary neurofilament light chain signals, enabling priority review and early reimbursement listing ahead of confirmatory trials.
For Investors and Strategic Acquirers: Consolidation pressure builds where antisense platform holders lack small-molecule oral capabilities and dual-mechanism developers seek manufacturing scale. The five-to-ten year viability window favors precision genetic targeting over broad sporadic ALS approaches, with biomarker-stratified trial enrollment as the critical inflection signal. Target acquisition archetypes include antisense specialists with validated surrogate endpoints and oral formulation developers with FDA breakthrough therapy designation.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Validation Program | Neurofilament light chain standardization accelerates FDA accelerated approval conversions for antisense platforms. |
| Specialist Network Accreditation | Cleveland Clinic and Mayo Clinic referral concentration channels Medicare prior authorization through certified centers. |
| Oral Formulation Development | Small-molecule tablets displace intravenous biologics in prescriber preference for home administration feasibility. |
| Japan Regulatory Pathway | PMDA Sakigake designation compresses review timelines for genetic ALS subpopulation mechanisms. |
| Outcome-Based Contracting | Germany's statutory health insurance risk-sharing agreements establish reference pricing for genetic subpopulations. |
Research Approach
Coverage spans the United States, Germany, Japan, and Switzerland, with primary inputs from each market's regulatory and reimbursement stakeholders. Drug development executives at antisense and small-molecule developers, regulatory affairs leads navigating FDA and EMA accelerated pathways, formulary directors at United States Medicare Advantage plans, and payer access specialists in Germany's statutory health insurance system provided structured interviews. Secondary validation drew from FDA orphan drug designation filings, EMA conditional marketing authorization submissions, ClinicalTrials.gov recruitment protocols, and hospital procurement databases. Bottom-up patient population sizing triangulated against top-down pharmaceutical revenue estimates.
Granularity-level modeling deployed treatment line stratification across first-line disease modification, second-line combination therapy, and symptomatic palliation, crossed with administration route segmentation and regional regulatory cluster differentiation. Patient population forecasts by genetic versus sporadic ALS subtype, biomarker stratification eligibility, and care setting concentration informed volume assumptions. CAGRs derived from epidemiological incidence projections, treatment penetration curves, and pricing evolution by mechanism class across the analysis window.
Biomarker validation delays, payer skepticism toward surrogate endpoints, and diagnostic latency extensions are the dominant revision risks to patient population and revenue assumptions. Practitioners should monitor neurofilament light chain threshold consensus, EMA conditional marketing authorization confirmatory trial readouts, and electromyography protocol standardization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Lung Cancer Therapeutics Market