
 Growth Hormone Deficiency Market | 2026-2036
Growth Hormone Deficiency Market Size, Share, and Industry Trends Forecast 2026-2036
Growth Hormone Deficiency Market Analysis
Monthly versus weekly dosing bundles is recalibrating how payers and physicians evaluate total cost of care in pediatric growth hormone therapy. Novo Nordisk A/S leverages its long-acting somapacitan platform to differentiate from daily-injection legacy products. Pfizer Inc. anchors its position through manufacturing scale and established hospital formulary relationships across North American and European markets. Eli Lilly and Company competes by extending its endocrinology portfolio into connected injection devices that track adherence metrics.
Growth hormone deficiency denotes a clinical endocrine disorder characterized by insufficient secretion of growth hormone from the anterior pituitary, quantified by provocative stimulation testing and insulin-like growth factor-1 serum levels below age-adjusted norms; recombinant DNA-derived somatropin remains the standard replacement therapy, administered via subcutaneous injection to restore linear growth velocity in children and metabolic homeostasis in adults. Recombinant growth hormones occupy the dominant revenue position due to decades of safety data and broad label indications, while biosimilars are gaining structural traction as patent cliffs open pathways for cost-competitive entrants in European and select Asian markets. Pediatric patients represent the core demand pool where diagnosis protocols and height velocity screening drive treatment initiation, though adult patients constitute a faster-growing segment as awareness of metabolic sequelae expands among primary care physicians.
The FDA oversees approval pathways for novel growth hormone products through its Center for Drug Evaluation and Research, while the EMA's Committee for Medicinal Products for Human Use evaluates pediatric investigation plans and orphan designations across European member states. Both regulators shape market access through requirements for long-term safety registries and post-marketing surveillance of immunogenicity signals in biologic therapies. Stakeholders must monitor how real-world evidence requirements and biosimilar interchangeability standards will reshape competitive dynamics and pricing power across branded and follow-on portfolios.
Market Dynamics
Long-acting recombinant formulations are compressing treatment protocols from daily to weekly or monthly intervals, forcing payers to recalibrate cost-per-outcome metrics and pediatric endocrinology clinics to redesign patient monitoring workflows around extended dosing windows.
Growth Catalysts
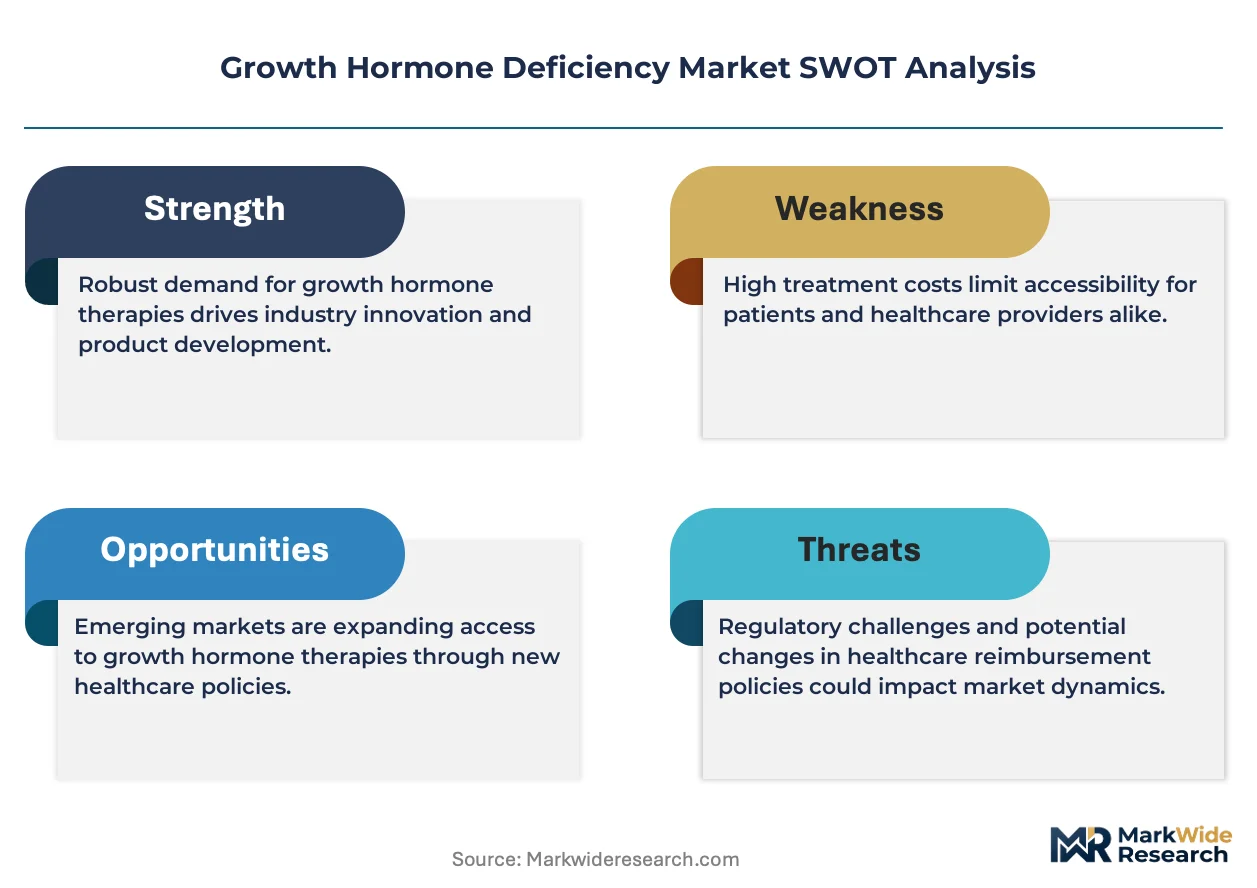
- FDA Orphan Drug Exclusivity:Extended market protection periods incentivize biopharmaceutical investment in novel delivery mechanisms for rare endocrine disorders, accelerating pipeline diversification beyond legacy daily-injection platforms.
- Pediatric Height Velocity Screening:Systematic growth monitoring protocols in school-based health programs and primary care networks are expanding diagnostic capture rates for idiopathic growth hormone deficiency in pre-adolescent populations.
- Subcutaneous Autoinjector Miniaturization:Advances in precision micro-needle arrays and spring-actuated delivery systems are reducing caregiver administration burden and expanding home-based therapy feasibility.
Market Restraints
- Recombinant Protein Cold Chain Dependency:Temperature-controlled distribution requirements from manufacturing through patient administration impose logistics costs and limit pharmacy dispensing flexibility in rural and emerging markets.
- Provocative Stimulation Testing Complexity:Multi-hour diagnostic protocols requiring specialized endocrine nursing and pharmacy support create bottlenecks in tertiary referral centers, delaying treatment initiation.
- Insulin-like Growth Factor-1 Assay Variability:Inter-laboratory standardization gaps in IGF-1 immunoassay methodologies generate diagnostic uncertainty and drive repeat testing cycles that fragment care coordination.
Strategic Opportunities
- Adult Metabolic Syndrome Indications:Expanding label claims for somatropin replacement in adult growth hormone deficiency with cardiovascular risk profiles opens addressable populations beyond pediatric stature correction.
- EMA Pediatric Investigation Plan Incentives:Structured regulatory pathways rewarding juvenile toxicity studies and long-term follow-up protocols create competitive differentiation for sponsors committed to pediatric-specific evidence generation.
- Connected Device Data Monetization:Injection platforms capturing real-world adherence and biometric data offer pathways to outcomes-based contracting with integrated delivery networks and specialty pharmacy benefit managers.
Industry Challenges
- Pediatric Endocrinology Workforce Constraints:Fellowship program graduation rates lag patient referral growth, extending appointment wait times and fragmenting continuity of care for chronic therapy management.
- Biosimilar Immunogenicity Surveillance:Post-marketing pharmacovigilance requirements for anti-drug antibody monitoring impose registry maintenance burdens on healthcare systems and manufacturers without established neutralizing assay harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Growth Hormone Deficiency Market |
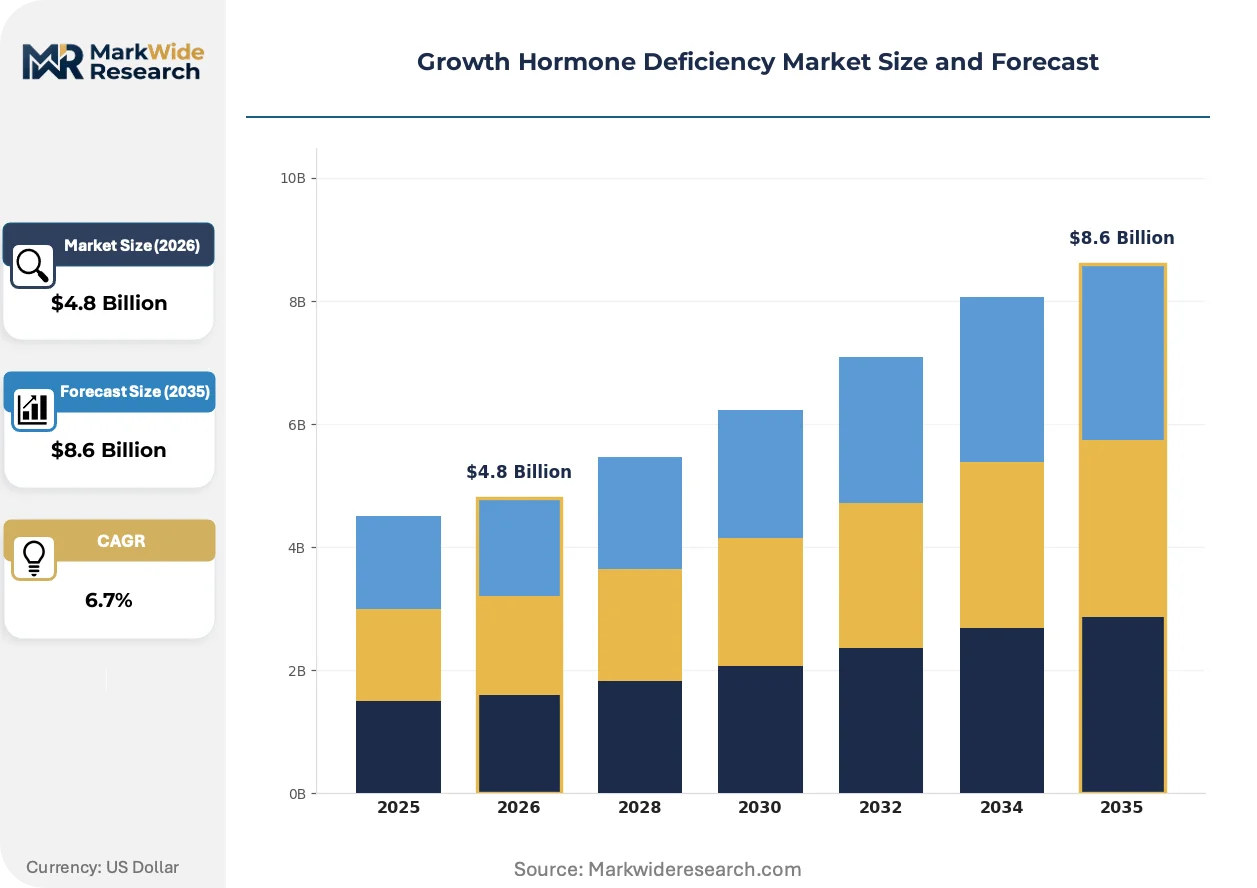
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Growth Hormones, Somatropin, Injection Devices, Biosimilars End User: Pediatric Patients, Adult Patients, Hospitals, Clinics Administration Route: Subcutaneous, Intramuscular, Infusion, Oral Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Pfizer Inc., Novo Nordisk A/S, F. Hoffmann-La Roche Ltd., Genentech Inc., Eli Lilly and Company, Ascendis Pharma, Merck & Co., Inc., Ipsen Pharma, Lumos Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Growth Hormone Deficiency Market Emerging Trajectories
Biologic half-life extension technologies are restructuring competitive advantage around dosing convenience rather than molecular efficacy alone, while regulatory frameworks for real-world evidence submission are compressing traditional randomized controlled trial dependencies.
Albumin-binding fusion technology is absorbing the functional role of polyethylene glycolylation in sustained-release growth hormone engineering. Pediatric endocrinology practices in the United States and Germany are adopting these long-acting platforms at replacement rates exceeding prior formulation transitions. The technology is absorbing market share from daily-injection legacy products by collapsing caregiver burden and improving adherence metrics in real-world registry data.
The EMA's Committee for Orphan Medicinal Products has tightened pediatric investigation plan requirements for growth hormone analogs, mandating juvenile animal toxicology and longitudinal neurocognitive outcome tracking. This regulatory tightening extends development timelines but creates durable exclusivity windows for compliant sponsors. European member states with centralized health technology assessment processes are prioritizing long-acting formulations with demonstrated quality-of-life endpoint improvements.
Specialty pharmacy networks are consolidating patient onboarding and prior authorization management into single-source distribution models that disintermediate traditional hospital outpatient pharmacies. This channel concentration is most pronounced in United States markets where pharmacy benefit managers have carved out endocrine therapy categories for exclusive formulary placement. Payer concentration is forcing manufacturers to accept outcome-based rebate structures tied to height velocity milestones and treatment persistence metrics.
Growth Hormone Deficiency Market Segmentation
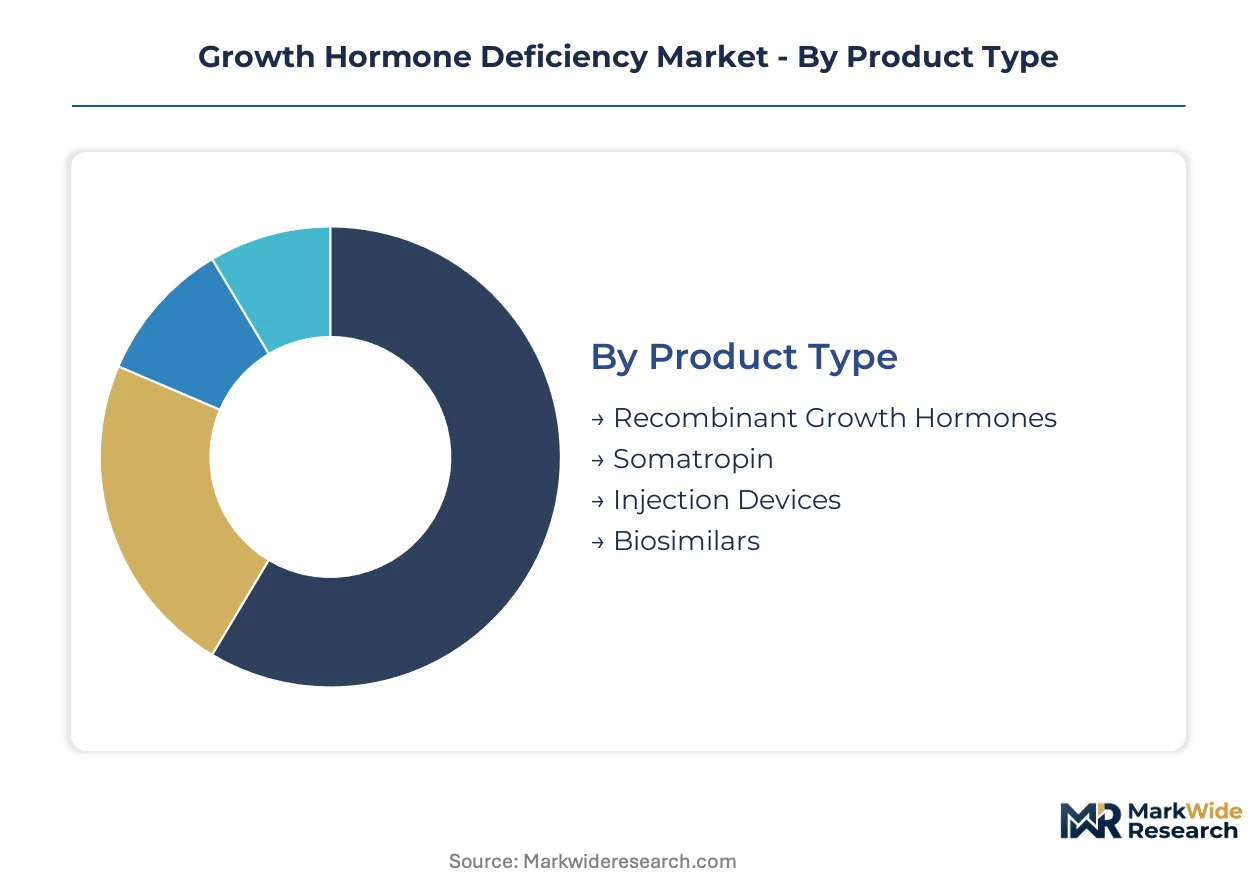
Segmentation in the growth hormone deficiency market reveals how dosing technology, patient lifecycle positioning, and channel economics split commercial opportunity. Each axis carries distinct margin profiles and regulatory exposure that shape portfolio allocation decisions.
Product Type:
Biologic half-life extension and manufacturing process sophistication define competitive tiers across therapeutic formats.
- Recombinant Growth Hormones:Full-length somatropin produced via E. coli or mammalian cell culture systems remains the clinical standard with decades of longitudinal safety data. Demand concentrates in the United States and Germany where prior authorization pathways favor established molecules with comprehensive registry documentation.
- Somatropin:The identical 191-amino acid sequence to endogenous growth hormone, delivered through daily or extended-release formulations. European markets with centralized health technology assessment processes are prioritizing long-acting variants with demonstrated quality-of-life endpoint improvements.
- Injection Devices:Autoinjector platforms incorporating spring-actuated delivery and dose-tracking electronics reduce caregiver burden in home settings.
- Biosimilars:Follow-on biologics referencing approved somatropin products with abbreviated clinical development pathways.
Mature deployment sits with Recombinant Growth Hormones. Newer deployment is concentrated in Biosimilars.
End User:
Patient age and care setting determine treatment protocol complexity and reimbursement pathway structure.
- Pediatric Patients:Pre-adolescent populations with idiopathic or organic growth hormone deficiency requiring stature correction through puberty. United States school-based health screening programs and height velocity monitoring drive diagnostic capture and treatment initiation volumes.
- Adult Patients:Individuals with persistent deficiency from childhood onset or acquired pituitary disease, treated for metabolic homeostasis and cardiovascular risk modification. This cohort is expanding most quickly as primary care awareness of adult sequelae broadens referral patterns.
- Hospitals:Tertiary centers managing complex diagnostic workups and initial therapy titration.
- Clinics:Ambulatory endocrinology practices handling chronic maintenance and dose adjustments.
Volume concentration remains with Pediatric Patients. Margin expansion is shifting toward Adult Patients.
Administration Route:
Pharmacokinetic profile and patient convenience trade-offs segment delivery methodology preference.
- Subcutaneous:Standard delivery into adipose tissue via pen devices or traditional syringes, supporting both daily and extended-release formulations.
- Intramuscular:Deep tissue injection reserved for specific depot formulations with modified release characteristics.
- Infusion:Continuous or intermittent pump-based delivery for specialized metabolic indications.
- Oral:Experimental and developmental approaches seeking to bypass injection burden through gastrointestinal absorption enhancement.
Established clinical practice centers on Subcutaneous delivery. Pipeline investment is redirecting toward Oral absorption technologies.
Distribution Channel:
Supply chain control and patient data capture differentiate channel economics and manufacturer access.
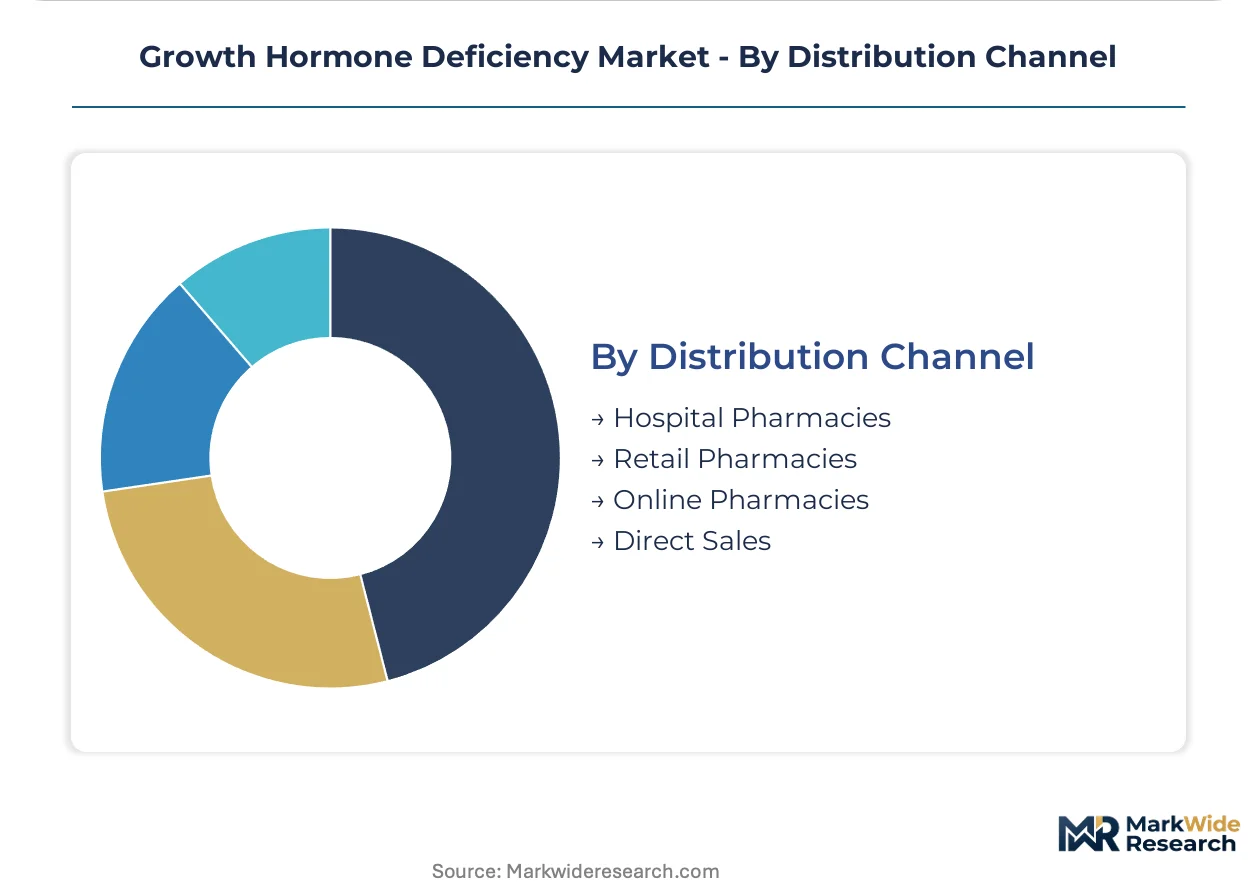
- Hospital Pharmacies:Integrated dispensing within tertiary centers managing complex prior authorization and benefit verification.
- Retail Pharmacies:Community-based dispensing with limited cold chain infrastructure for biologic storage.
- Online Pharmacies:Direct-to-patient shipping with temperature-controlled logistics and telehealth coordination.
- Direct Sales:Manufacturer-controlled distribution bypassing wholesale intermediaries for specialty therapy management.
Channel consolidation is elevating Direct Sales. Geographic reach extension is driving Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for recombinant growth hormones clusters in the United States and Western Europe, while diagnostic uptake and treatment initiation rates vary sharply across national healthcare systems and reimbursement frameworks.
United States
Specialty pharmacy networks and mature prior authorization pathways concentrate demand for long-acting somatropin formulations. The FDA's orphan drug exclusivity framework accelerates novel delivery mechanism development through extended market protection periods. Boston and San Francisco anchor biotech clusters where half-life extension technologies advance from laboratory to commercial scale.
Germany
Centralized health technology assessment processes prioritize long-acting formulations with demonstrated quality-of-life endpoint improvements in pediatric populations. The EMA's Committee for Medicinal Products for Human Use shapes pediatric investigation plan requirements that extend development timelines for compliant sponsors. Munich and Heidelberg host endocrinology research centers driving real-world evidence generation for metabolic syndrome indications.
Japan
Aging demographics and expanding primary care awareness of adult growth hormone deficiency sequelae broaden referral patterns beyond traditional pediatric stature correction. The PMDA evaluates somatropin biosimilars through abbreviated pathways that accelerate cost-competitive market entry. Tokyo and Osaka metropolitan areas concentrate tertiary endocrinology centers managing complex diagnostic workups.
United Kingdom
National Health Service formularies negotiate outcome-based rebate structures tied to height velocity milestones and treatment persistence metrics. The MHRA aligns post-Brexit regulatory pathways with EMA standards while maintaining independent pharmacovigilance oversight. London and Cambridge clusters integrate connected injection device development with digital health infrastructure.
France
School-based health screening programs and systematic growth monitoring protocols expand diagnostic capture rates for idiopathic growth hormone deficiency. ANSM oversight of biologic cold chain distribution imposes logistics standards that limit pharmacy dispensing flexibility in rural departments. Paris and Lyon anchor pediatric endocrinology networks redesigning patient monitoring workflows around extended dosing windows.
Growth Hormone Deficiency Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the growth hormone deficiency market, creating a tiered structure where scale advantages in manufacturing and distribution clash with agility in novel delivery platform development. The competitive field segments into three strategic archetypes: established pharmaceutical conglomerates with endocrinology portfolio breadth, biotechnology specialists concentrating on half-life extension technologies, and emerging platform companies pursuing oral or gene therapy alternatives. Consolidation pressures intensify as M&A activity targets connected device capabilities and biosimilar manufacturing assets, while strategic partnerships between formulation innovators and specialty pharmacy distributors reshape channel access economics.
Among established pharmaceutical conglomerates, Pfizer Inc., Novo Nordisk A/S, and Eli Lilly and Company occupy positions that exemplify divergent strategic postures within the same therapeutic domain. Pfizer represents scale-driven manufacturing and hospital formulary anchoring across North American and European markets. Novo Nordisk exemplifies platform specialization through long-acting somapacitan technology that differentiates from legacy daily-injection products. Eli Lilly sits within the connected device tier, extending endocrinology portfolios into adherence-tracking injection platforms that generate real-world evidence for payer negotiations.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novo Nordisk A/S |
| F. Hoffmann-La Roche Ltd. |
| Genentech Inc. |
| Eli Lilly and Company |
| Ascendis Pharma |
| Merck & Co., Inc. |
| Ipsen Pharma |
| Lumos Pharma |
| Others |
Supply Flow & Price Mechanics
Recombinant protein cold chain logistics costs cascade through distribution tiers into three-tier pricing structure across premium, standard, and economy levels. Temperature-controlled storage requirements from manufacturing through patient administration concentrate pricing power with manufacturers possessing validated distribution networks, while biosimilar entrants compress margins in markets with centralized health technology assessment processes.
Pricing Analysis
Cost-down pressure on long-acting formulations accelerates because payer concentration forces outcome-based rebate structures tied to height velocity milestones. Pricing stratifies across premium, standard, and economy tiers based on dosing frequency convenience and connected device bundling. Pediatric endocrinology clinics exhibit highest price sensitivity due to prior authorization burden, while adult metabolic syndrome segments tolerate premium positioning for cardiovascular risk modification claims.
Supply Chain Analysis
EMA pediatric investigation plan certification gates access to European reimbursement pathways, filtering supplier tiers by juvenile toxicology documentation maturity. Manufacturing concentrates in the United States, Germany, and Switzerland, drawing from mammalian cell culture systems and precision micro-needle component suppliers. Single-source vulnerability sits with albumin-binding fusion technology licensors. Distribution runs through specialty pharmacy networks with exclusive formulary placement in United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA orphan drug exclusivity and EMA pediatric investigation plan requirements erect barrier-to-entry moats favoring sponsors with longitudinal safety registry infrastructure.
For Market Incumbents: Cement formulary anchoring through manufacturing scale commitments in North American and European production hubs. Prioritize connected device data monetization capabilities to defend against biosimilar interchangeability pressure. Lock in exclusive specialty pharmacy distribution partnerships before channel consolidation completes. For New Entrants and Emerging Players: Oral absorption enhancement platforms offer the most penetrable wedge against injection-dominant incumbents. Target adult metabolic syndrome indications where primary care referral patterns remain underdeveloped. Pursue licensing partnerships with established endocrinology portfolios to bypass cold chain infrastructure requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor half-life extension technology specialists with EMA-compliant pediatric investigation plans in Germany and France. Long-term viability hinges on real-world evidence generation capabilities across the analysis window. Watch for FDA biosimilar interchangeability determinations as portfolio repricing inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | Compresses dosing frequency from daily to weekly, collapsing caregiver burden in pediatric populations. |
| Connected Injection Device Launch | Captures adherence metrics for outcomes-based contracting with pharmacy benefit managers. |
| Pediatric Investigation Plan Submission | Secures EMA regulatory exclusivity windows through juvenile toxicology compliance. |
| Specialty Pharmacy Partnership | Consolidates patient onboarding and prior authorization management into single-source models. |
| Adult Metabolic Syndrome Label Expansion | Broadens addressable population beyond pediatric stature correction into cardiovascular risk modification. |
Methodological Framework
Document review covered FDA orphan drug filings, EMA pediatric investigation plans, ClinicalTrials.gov registries, and formulary databases, complemented by interviews with pediatric endocrinologists, regulatory affairs leads at biopharmaceutical sponsors, specialty pharmacy benefit managers, and hospital procurement directors. Secondary validation drew from SEC 10-K disclosures, CMS Medicare Part D claims, and European health technology assessment reports. Bottom-up patient flow modeling and top-down revenue triangulation anchored segmentation outputs.
Cross-referencing historical adoption curves against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, patient age cohort, administration route, and regional regulatory cluster. CAGRs derived from slope analysis of dosing technology transitions and payer concentration indices. Forecast inputs incorporated real-world adherence registry data and biosimilar penetration assumptions.
Several conditions sit outside the modeled scope, including gene therapy platform commercialization timelines and oral formulation bioequivalence determinations. Forecasts reflect assumptions about long-acting formulation reimbursement persistence and pediatric endocrinology workforce expansion rates. A model refresh is warranted upon material change in FDA biosimilar interchangeability guidance or EMA pediatric investigation plan requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Global Lichen Nitidus Treatment Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Gingivostomatitis Market