
 Malignant Glioma Therapeutics Market | 2026-2036
Malignant Glioma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Malignant Glioma Therapeutics Market Analytics
Tumor-treating fields technology paired with checkpoint inhibitors is reshaping first-line glioblastoma protocols. F. Hoffmann-La Roche Ltd anchors its position through sustained investment in blood-brain barrier penetration platforms. Merck & Co., Inc. leverages its immuno-oncology infrastructure to compete in combination therapy development. Novocure differentiates through dedicated delivery hardware that extends into maintenance settings.
Malignant glioma therapeutics comprise systemic and localized treatments directed at diffusely infiltrating glial tumors, including alkylating agents such as temozolomide and monoclonal antibodies engineered for receptor blockade. The primary purpose centers on extending progression-free survival while preserving neurological function in patients with WHO grade III-IV astrocytic tumors. Chemotherapy retains the largest patient volume footprint, yet immunotherapy represents the fastest-expanding segment as CAR-T and vaccine platforms advance through clinical validation. Convection-enhanced delivery commands premium positioning due to its capacity to bypass the blood-brain barrier, while oral formulations dominate outpatient maintenance protocols across hospital and homecare settings.
The FDA's accelerated approval framework and Breakthrough Therapy designation compress development timelines for glioblastoma candidates, while EMA's PRIME scheme shapes European access pathways. ISO 14155 governs clinical investigation standards that manufacturers must satisfy for transatlantic trial consistency. Stakeholders must weigh early-stage platform bets against the risk of biomarker-defined patient stratification narrowing addressable populations.
Market Dynamics
The FDA's accelerated approval pathway compresses development timelines for glioblastoma candidates, while tumor-treating fields technology paired with checkpoint inhibitors forces protocol restructuring across academic medical centers. Blood-brain barrier penetration platforms now determine competitive positioning in first-line therapy.
Growth Catalysts
- Breakthrough Therapy designation:The FDA's expedited review mechanism compresses Phase II-to-approval timelines for glioblastoma candidates. Academic medical centers in the United States expand enrollment in NCI-funded trial networks.
- Convection-enhanced delivery:This localized administration technology bypasses the blood-brain barrier, enabling therapeutic concentrations previously unattainable through systemic routes. Neuro-oncology departments at tertiary centers are retrofitting surgical suites.
- CAR-T platform maturation:Cellular therapy infrastructure developed for hematologic malignancies now redirects toward solid tumor applications. Glioma-specific antigen targeting programs advance through investigator-initiated trials.
Market Restraints
- Alkylating agent supply concentration:Temozolomide active pharmaceutical ingredient production concentrates among a limited set of contract manufacturers in India and China, exposing formulation sponsors to single-source risk.
- Blood-brain barrier technical limitation:Systemic biologics achieve subtherapeutic central nervous system penetration without engineered transport mechanisms, constraining antibody-drug conjugate applicability.
- EMA PRIME scheme friction:European eligibility requirements for priority medicines status create documentation burdens that delay multi-regional trial activation timelines.
Strategic Opportunities
- Maintenance setting expansion:Tumor-treating fields delivery hardware extends into post-radiation maintenance protocols, creating recurring revenue streams beyond acute intervention windows.
- Japan's Sakigake designation:Japan's PMDA priority review system offers condensed approval timelines for glioma therapeutics demonstrating early efficacy signals, incentivizing Japanese site inclusion in global protocols.
- Biomarker-driven stratification:MGMT promoter methylation testing enables patient selection for alkylating agent sensitivity, supporting companion diagnostic co-development strategies.
Industry Challenges
- Neuro-oncology trialist scarcity:Principal investigator availability constrains site activation for glioblastoma studies, with qualified investigators concentrated at NCI-designated cancer centers.
- ISO 14155 compliance timeline:Transatlantic clinical investigation standard harmonization demands quality system investments that extend study start-up durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malignant Glioma Therapeutics Market |
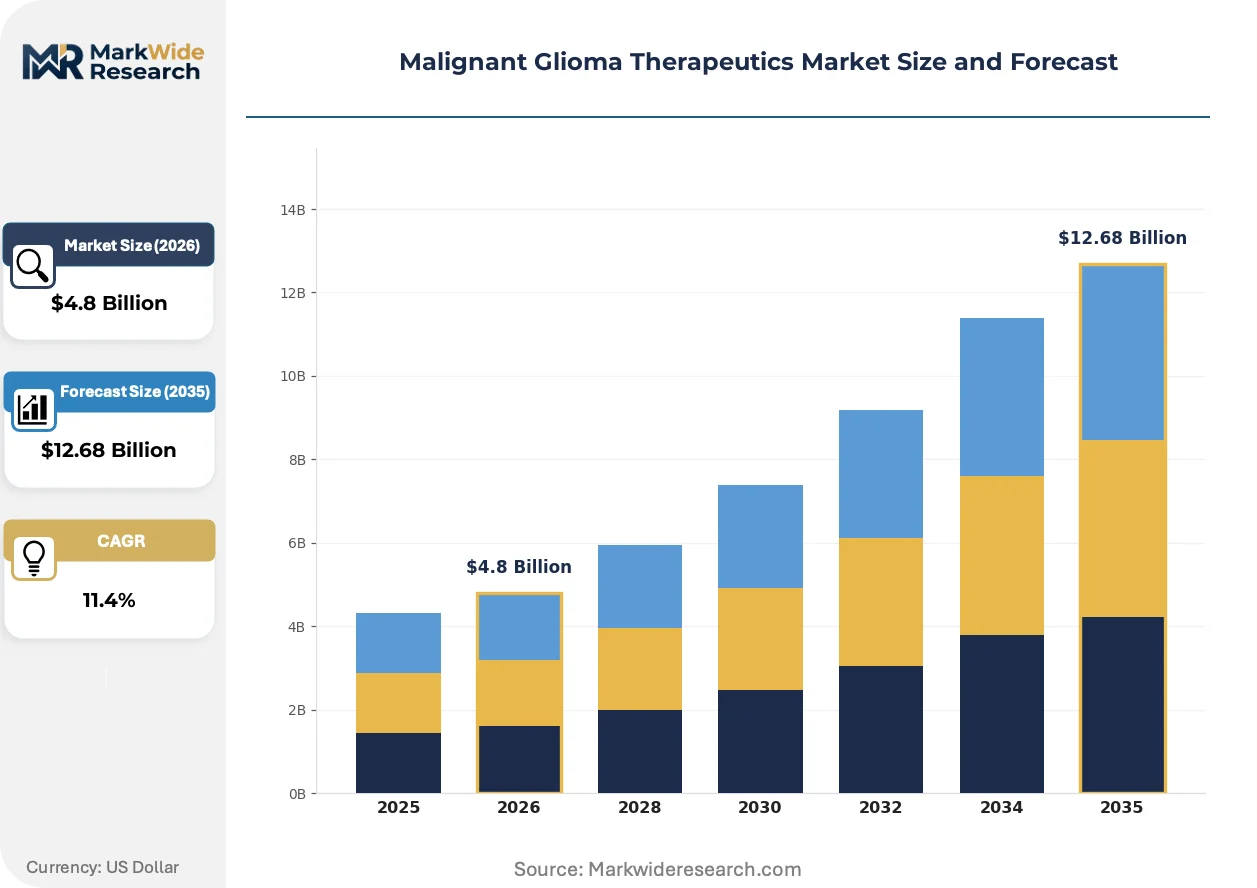
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiotherapy Delivery Mode: Oral, Intravenous, Intratumoral, Convection-Enhanced End User: Hospitals, Specialty Clinics, Research Institutions, Homecare Treatment Stage: Adjuvant, Neoadjuvant, Maintenance, Palliative |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Pfizer Inc., Amgen Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd, Arbor Pharmaceuticals LLC, AbbVie Inc., Novocure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malignant Glioma Therapeutics Market Evolving Landscape
Digital biomarker integration and adaptive trial designs are compressing evidence-generation cycles for glioma therapeutics. Blood-brain barrier engineering and localized delivery modalities dominate platform investment.
Artificial intelligence-powered radiomic analysis is digitizing tumor boundary detection and treatment response assessment. Neuroradiology departments at academic medical centers deploy machine learning algorithms to standardize RECIST criteria application across multicenter trials. This capability is digitizing endpoint adjudication processes that previously required centralized expert review.
REACH authorization requirements for novel chemical entities are reshaping European manufacturing strategies for alkylating agents. Sponsors must demonstrate environmental fate assessments and exposure controls during commercial production scale-up. High-potency oncology API manufacturers are relocating final synthesis steps to facilities with dedicated containment infrastructure.
Hospital procurement committees now require health technology assessment submissions prior to formulary inclusion for novel glioma therapies. United States academic medical centers increasingly delegate evaluation to integrated pharmacy and therapeutics subcommittees with specialized oncology expertise. This structural shift concentrates purchasing authority within institutions maintaining NCI Comprehensive Cancer Center designation.
Malignant Glioma Therapeutics Market Segmentation
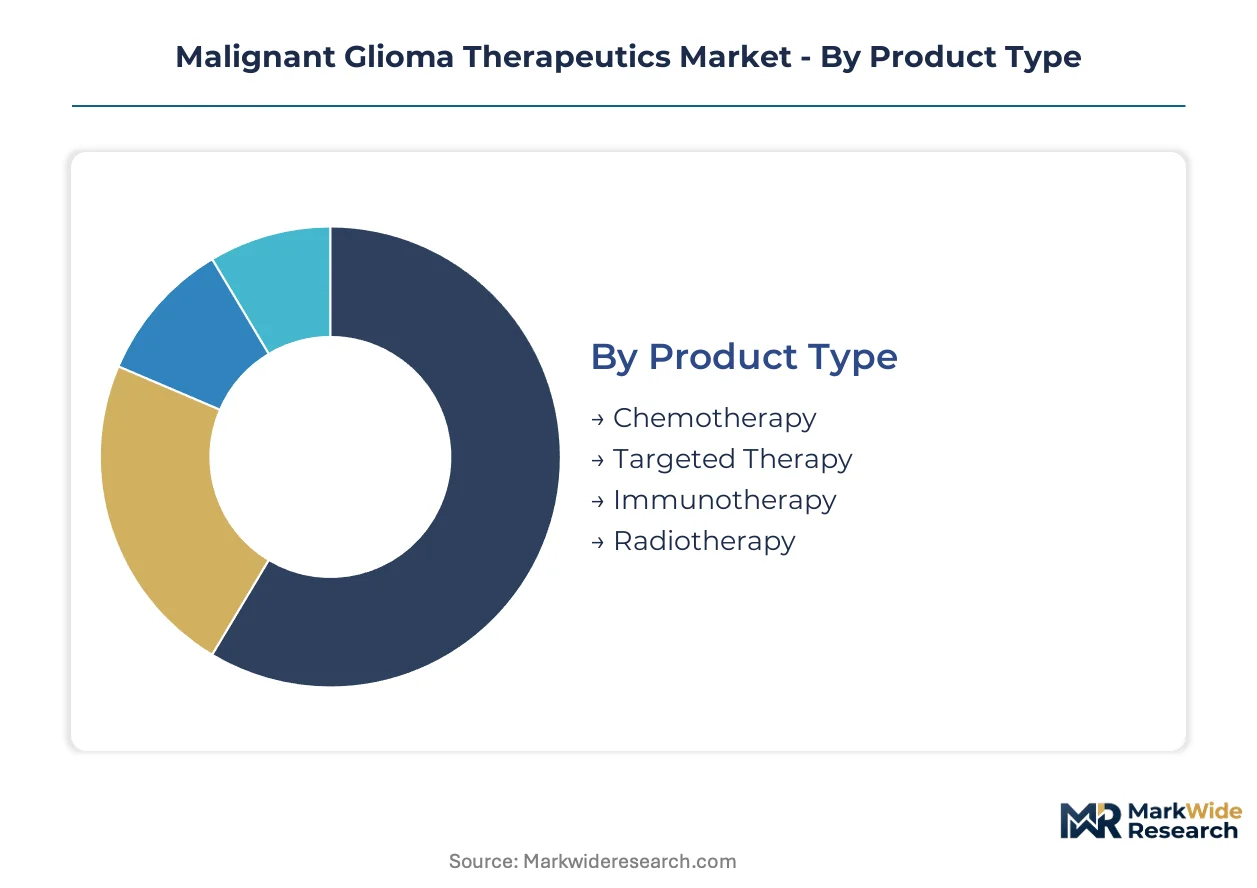
Malignant glioma therapeutics fragment across four distinct dimensions that shape procurement patterns and clinical adoption. Product type determines reimbursement tiering, while delivery mode dictates site-of-care requirements and capital investment intensity.
Product Type:
Cost tier stratification separates mature alkylating agents from premium-priced biologics and cellular platforms.
- Chemotherapy:Temozolomide and nitrosourea derivatives constitute the foundational systemic approach, with established compendia listings driving formulary inclusion. United States academic medical centers anchor demand volume through NCI-designated trial networks, though generic substitution pressures compress margins for oral formulations.
- Immunotherapy:Checkpoint inhibitors, therapeutic vaccines, and CAR-T platforms represent the steepest expansion trajectory, requiring specialized manufacturing partnerships and cold-chain logistics. Japan's PMDA Sakigake designation accelerates approval timelines for glioma-specific candidates, redirecting regional clinical investment.
- Targeted Therapy:Receptor tyrosine kinase inhibitors and angiogenesis modulators address molecularly defined patient subsets.
- Radiotherapy:External beam and brachytherapy protocols integrate with systemic regimens in multidisciplinary protocols.
Chemotherapy holds installed capacity. Immunotherapy is rotating up the share rankings.
Delivery Mode:
Application requirements differentiate outpatient self-administration from inpatient surgical intervention.
- Convection-Enhanced:Catheter-based intraparenchymal infusion bypasses the blood-brain barrier, enabling therapeutic concentrations of large-molecule biologics previously excluded from CNS indications. Tertiary neurosurgical centers in the United States are retrofitting operating suites with MRI-compatible delivery systems, with FDA breakthrough therapy designations compressing capital justification timelines.
- Oral:Temozolomide capsules dominate maintenance protocols, enabling home-based administration and reducing infusion center burden. Medicare reimbursement structures in the United States favor oral oncology parity provisions, though prior authorization requirements create administrative friction.
- Intravenous:Bevacizumab and other monoclonal antibodies require infusion center capacity.
- Intratumoral:Direct injection approaches concentrate at specialized neuro-oncology centers.
Oral formulations hold installed capacity. Convection-enhanced delivery is rotating up the share rankings.
End User:
Customer type determines purchasing authority, with integrated delivery networks diverging from independent specialty practices.
- Hospitals:NCI Comprehensive Cancer Centers concentrate glioblastoma case volume and trial enrollment, with pharmacy and therapeutics committees exercising centralized formulary control. These institutions command preferential pricing through committed volume agreements and investigator-initiated trial participation.
- Homecare:Oral maintenance therapy and portable tumor-treating fields hardware shift treatment administration beyond institutional walls. United States Medicare home health benefit expansions for oncology supportive care accelerate this migration.
- Specialty Clinics:Community neuro-oncology practices manage stable patients between hospital visits.
- Research Institutions:Academic medical centers with dedicated brain tumor programs anchor early-phase clinical trial infrastructure.
Hospitals hold installed capacity. Homecare is rotating up the share rankings.
Treatment Stage:
Maturity of indication shapes competitive intensity, with established adjuvant protocols facing disruption from neoadjuvant and maintenance expansion.
- Maintenance:Tumor-treating fields devices and oral alkylating agents extend intervention windows post-chemoradiation, creating recurring revenue streams and patient monitoring touchpoints. Novocure's Optune hardware anchors this segment with dedicated delivery systems that integrate into outpatient workflows.
- Neoadjuvant:Pre-surgical systemic and localized approaches aim to reduce residual disease burden and improve resection margins. Investigator-initiated trials at MD Anderson Cancer Center and Memorial Sloan Kettering Cancer Center are validating imaging biomarkers for response assessment.
- Adjuvant:Post-surgical chemoradiation remains the standard-of-care backbone.
- Palliative:Symptom-directed interventions address end-stage disease burden.
Adjuvant protocols hold installed capacity. Maintenance is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based pharmaceutical exports supply glioma therapeutic compounds to European hospital networks and Japanese academic medical centers. Cross-border clinical trial data sharing accelerates regulatory convergence between FDA, EMA, and PMDA review pathways. Manufacturing partnerships concentrate active pharmaceutical ingredient production in India and China for formulation finishing in North American and European facilities.
United States
Medicare reimbursement parity for oral oncology drugs sustains demand for temozolomide maintenance protocols. FDA Breakthrough Therapy designations compress Phase II-to-approval timelines for glioblastoma candidates. NCI-designated Comprehensive Cancer Centers in Houston and New York anchor multi-site trial networks for convection-enhanced delivery validation.
Germany
University hospital neurosurgery departments drive adoption of MRI-compatible infusion systems for blood-brain barrier bypass. EMA PRIME scheme eligibility requirements shape documentation strategies for glioma therapeutic sponsors. The Heidelberg and Berlin metropolitan clusters concentrate neuroradiology expertise for adaptive trial endpoint adjudication.
Japan
PMDA Sakigake priority review designation attracts global protocol inclusion for glioma-specific immunotherapy candidates. METI funding for regenerative medicine infrastructure redirects CAR-T platform investment toward solid tumor applications. Tokyo and Osaka academic medical centers expand investigator-initiated trial capacity for tumor-treating field combinations.
United Kingdom
NHS England specialized commissioning frameworks concentrate high-cost glioma therapy access at designated neuro-oncology centers. MHRA reliance recognition agreements with FDA and EMA streamline parallel marketing authorization submissions. The Greater Manchester and London cancer center networks validate digital biomarker integration for treatment response monitoring.
India
Contract manufacturing organizations in Hyderabad and Ahmedabad supply temozolomide active pharmaceutical ingredient to global formulation sponsors. CDSCO accelerated approval pathways for oncology therapies align with FDA precedent for glioblastoma indications. Bangalore and Delhi-NCR research institutions anchor investigator-initiated trials for localized delivery platform adaptation.
Malignant Glioma Therapeutics Market Competitive Landscape
On the supply side, the industry is consolidating around integrated oncology portfolios with blood-brain barrier penetration capabilities. Large-cap pharmaceutical sponsors dominate first-line glioblastoma protocols through sustained R&D investment and regulatory relationship depth. Mid-tier specialists occupy positions in localized delivery hardware and maintenance-setting devices. Competitive moves center on combination therapy co-development agreements and biomarker-driven patient stratification capabilities.
Among Switzerland-based diversified pharmaceutical groups, F. Hoffmann-La Roche Ltd exemplifies platform investment in blood-brain barrier engineering. United States-based Merck & Co., Inc. occupies a position within the immuno-oncology archetype through checkpoint inhibitor infrastructure. Novocure represents the device-specialist tier with dedicated delivery hardware extending into maintenance settings. These anchors illustrate how competitive positioning fragments across therapeutic modality rather than consolidating around single mechanism dominance.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Amgen Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd |
| Arbor Pharmaceuticals LLC |
| AbbVie Inc. |
| Novocure |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient production for temozolomide concentrates among contract manufacturers in Hyderabad and Ahmedabad, anchoring margin capture downstream with formulation sponsors in North America and Europe who command premium positioning through FDA Breakthrough Therapy designations and Medicare reimbursement parity.
Pricing Analysis
First-generation alkylating agents, second-generation checkpoint inhibitor combinations, and third-generation CAR-T cellular platforms stratify across three distinct pricing tiers. Oral temozolomide maintenance protocols follow per-unit transactional models with generic substitution compressing margins, while convection-enhanced delivery systems and tumor-treating fields hardware deploy capital-equipment subscription structures. Price differentiation rests on FDA approval tier and blood-brain barrier penetration capability. Cost compression in oral chemotherapy intensifies as Indian API suppliers expand capacity. Community neuro-oncology practices exhibit highest price sensitivity; NCI-designated Comprehensive Cancer Centers demonstrate lowest sensitivity due to committed volume agreements.
Supply Chain Analysis
Dr. Reddy's Laboratories, Sun Pharmaceutical Industries, and Cipla anchor global temozolomide API capacity from facilities in India, with formulation finishing concentrated in United States and European Union sites. Supply chains draw from nitrosourea precursor chemicals, sterile packaging components, and cold-chain logistics infrastructure. Single-source vulnerability in Indian API manufacturing exposes sponsors to regulatory inspection delays and export restriction risk. Distribution runs through hospital procurement committees at NCI-designated centers, specialty pharmacy networks for oral maintenance, and direct-to-site delivery for clinical trial materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The malignant glioma therapeutics market rewards organizations that control blood-brain barrier engineering expertise and FDA regulatory relationship depth, capabilities concentrated among large-cap pharmaceutical sponsors with sustained oncology infrastructure investment.
For Market Incumbents: Harden blood-brain barrier penetration platforms through sustained R&D investment in receptor-mediated transport mechanisms and focused ultrasound delivery systems. Consolidate investigator relationships at NCI-designated cancer centers to secure principal investigator availability for combination therapy trials. Defensive positioning against CAR-T platform entrants requires biomarker-driven patient stratification capabilities and companion diagnostic co-development agreements with centralized laboratories. For New Entrants and Emerging Players: Build out localized delivery hardware specialization targeting maintenance-setting expansion, where tumor-treating fields devices create recurring revenue streams beyond acute intervention windows. Japan's PMDA Sakigake designation offers the most penetrable regulatory pathway for glioma-specific immunotherapy candidates. Go-to-market execution should prioritize investigator-initiated trial partnerships at Tokyo and Osaka academic medical centers to generate clinical evidence ahead of formal regulatory submission. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract manufacturing organizations in India that supply temozolomide API to global formulation sponsors. Long-term viability across the analysis window favors platforms with demonstrated blood-brain barrier penetration and maintenance-setting hardware integration. Acquisition targets should demonstrate FDA Breakthrough Therapy designation momentum or PMDA Sakigake eligibility. The signal to watch is biomarker-driven patient stratification narrowing addressable populations, which would compress valuation multiples for undifferentiated alkylating agent portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | NCI-funded trial networks at MD Anderson and Memorial Sloan Kettering compress Phase II-to-approval timelines for combination protocols. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation and EMA PRIME scheme eligibility reshape documentation strategies for transatlantic submissions. |
| Manufacturing Scale-Up | API production expansion in Hyderabad and Ahmedabad requires REACH authorization compliance for European market access. |
| Pipeline Diversification | CAR-T platform maturation redirects cellular therapy infrastructure from hematologic malignancies toward solid tumor applications. |
| Reimbursement Strategy | Medicare oral oncology parity provisions sustain demand for temozolomide maintenance protocols in United States homecare settings. |
Research Methodology
The analysis maps chemotherapy, immunotherapy, targeted therapy, and radiotherapy segments, each validated through neuro-oncology department heads, formulary directors at NCI-designated cancer centers, and regulatory affairs leads with FDA Breakthrough Therapy experience. Primary interviews with hospital procurement managers and payer access specialists combined with secondary validation from ClinicalTrials.gov, FDA filings, EMA submissions, and CMS Medicare reimbursement data. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing across the projection horizon.
Assumption sets held fixed regulatory approval timelines for FDA Breakthrough Therapy and EMA PRIME designations while varying biomarker-driven patient stratification penetration and CAR-T platform clinical success rates. Segmentation dimensions modeled include product type, delivery mode, end user, and treatment stage, with regional regulatory clusters capturing FDA, EMA, PMDA, and CDSCO pathway differences. CAGRs derived from patient incidence projections, treatment rate assumptions, and pricing trajectory analysis across oral, intravenous, and convection-enhanced administration routes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by CAR-T platform specialists or blood-brain barrier engineering entrants would shift outcomes beyond modeled ranges. Quarterly review of FDA Breakthrough Therapy designation grants, PMDA Sakigake approvals, and NCI trial network enrollment metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Diverticulitis Disease Market