
 Tularemia Therapeutics Market | 2026-2036
Tularemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Tularemia Therapeutics Market Analytics
Hospital procurement of tularemia countermeasures is tilting toward dual-use biodefense platforms that serve both civilian health systems and national security stockpiles. Merck & Co., Inc. anchors its position through decades of infectious disease manufacturing scale. Pfizer Inc. leverages broad antibiotic portfolios that intersect with public health emergency protocols. EMERGENT specializes in government contract fulfillment for medical countermeasure reserves.
Tularemia therapeutics encompass antimicrobial agents, vaccine candidates, and immunotherapies targeting Francisella tularensis, a Tier 1 select agent requiring Biosafety Level 3 handling protocols and specialized cold-chain distribution. These products serve dual purposes: treating natural zoonotic infections and fulfilling biodefense preparedness mandates under federal acquisition programs. The antibiotics segment dominates current revenue as frontline treatment for ulceroglandular and pneumonic presentations, while vaccines command premium positioning within government stockpiling channels where procurement terms span multi-year delivery schedules. Monoclonal antibodies represent the fastest-expanding category as developers pursue post-exposure prophylaxis indications with longer shelf stability than traditional biologics.
FDA's Animal Rule governs efficacy requirements for tularemia vaccines where human challenge studies remain unethical, while BARDA coordinates development funding through Project BioShield procurement mechanisms. The USDA regulates select agent possession and transfer, creating compliance barriers that shape facility location and partnership strategies for developers. Stakeholders must monitor congressional appropriations cycles for the Strategic National Stockpile, as funding volatility directly alters multi-year procurement commitments and program sustainability.
Market Dynamics
Federal biodefense procurement cycles dominate tularemia therapeutic development, with BARDA's Project BioShield creating multi-year demand commitments that outpace natural infection treatment volumes by orders of magnitude.
Growth Catalysts
- Animal Rule Pathway:FDA's alternative efficacy framework permits licensure without human challenge studies, compressing vaccine development timelines for Tier 1 select agents.
- Strategic National Stockpile Mandates:Congressional appropriations for medical countermeasure reserves generate predictable procurement pipelines independent of commercial pharmaceutical demand cycles.
- Monoclonal Antibody Platforms:Recombinant protein engineering is displacing traditional vaccine formats in post-exposure prophylaxis development due to superior shelf stability and dosing flexibility.
Market Restraints
- Biosafety Level 3 Infrastructure:Francisella tularensis handling requirements restrict manufacturing to specialized containment facilities, concentrating production in a handful of federally contracted sites.
- USDA Select Agent Regulations:Possession and transfer permits create compliance barriers that delay partnership negotiations and facility expansion timelines.
- Limited Clinical Endpoint Diversity:Ulceroglandular presentation predominates in natural infections while biodefense programs prioritize pneumonic models, fragmenting trial design standardization.
Strategic Opportunities
- Dual-Use Platform Technologies:Vaccine adjuvant systems developed for tularemia are converging with platforms for other Category A pathogens, enabling portfolio diversification across BARDA contract vehicles.
- State-Level Public Health Laboratories:Decentralized diagnostic networks in the United States present untapped distribution channels for rapid field-deployable therapeutic kits.
- Extended Shelf-Life Formulations:Thermostable vaccine presentations address cold-chain vulnerabilities in strategic stockpile storage, aligning with SNS inventory rotation requirements.
Industry Challenges
- BSL-3 Workforce Scarcity:Containment facility operations require specialized technician certification that exceeds standard pharmaceutical manufacturing training pipelines.
- Animal Model Translation Uncertainty:Efficacy data generated under the Animal Rule faces skepticism from procurement officers evaluating real-world human response predictability.
- Multi-Agency Coordination Friction:FDA, USDA, and BARDA oversight overlaps create conflicting submission timelines and inspection protocols for single product candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tularemia Therapeutics Market |
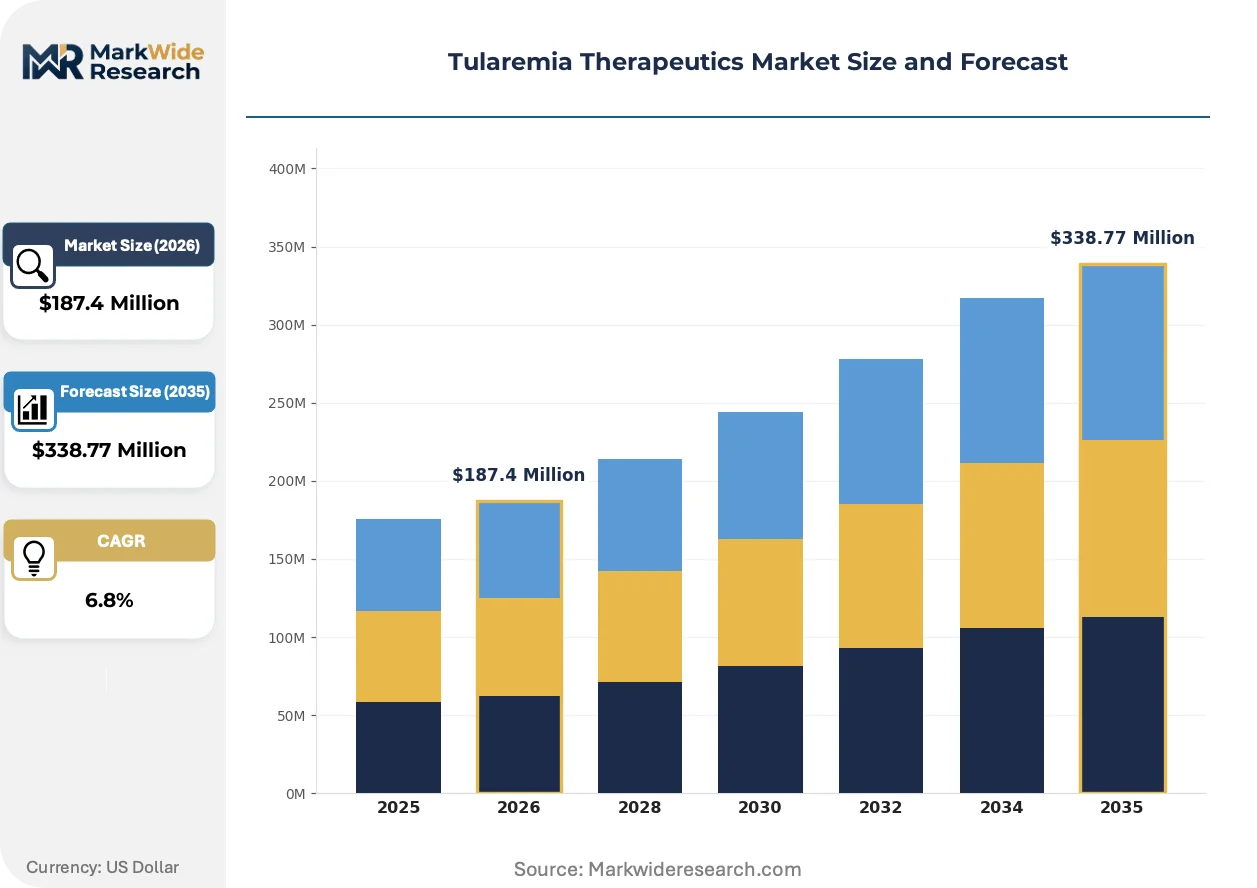
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Monoclonal Antibodies, Supportive Care Therapy Area: Infectious Diseases, Emergency Medicine, Public Health, Critical Care End User: Hospitals, Research Institutes, Pharmacies, Government Agencies Distribution Channel: Direct Sales, Online Pharmacies, Wholesale Distributors, Retail Pharmacies |
| Companies Covered | Appili Therapeutics, Merck & Co., Inc, Debiopharm, EpiVax, Inc., Cerus Corporation, EMERGENT, Sanofi, Pfizer Inc., GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tularemia Therapeutics Market Evolving Landscape
Live attenuated vaccine platforms are yielding to molecularly defined subunit approaches as developers seek regulatory pathways with clearer correlates of protection and reduced reactogenicity profiles.
mRNA-encoded antigen delivery is hybridizing traditional tularemia vaccine development by enabling rapid sequence optimization against Francisella subspecies variants. BARDA-funded developers are adopting this modality for prototype pathogen preparedness. The technology is compressing preclinical-to-IND timelines from years to months while raising manufacturing scalability questions for surge capacity scenarios.
EMA's updated guidelines on medicinal products for emergency stockpiling are harmonizing stability data requirements across European Union member states. This regulatory convergence reduces redundant testing burdens for developers seeking dual US-EU market access. Vaccine manufacturers are responding by designing unified formulation strategies that satisfy both FDA Animal Rule and EMA exceptional circumstances pathways.
Hospital formulary committees are consolidating antibiotic procurement through group purchasing organizations that bundle tularemia countermeasures with broader infectious disease portfolios. This channel concentration is displacing direct manufacturer-to-provider relationships that historically governed biodefense product distribution. The shift is most pronounced in tertiary care centers designated as regional Ebola and special pathogens treatment facilities under the US Hospital Preparedness Program.
Tularemia Therapeutics Market Segmentation
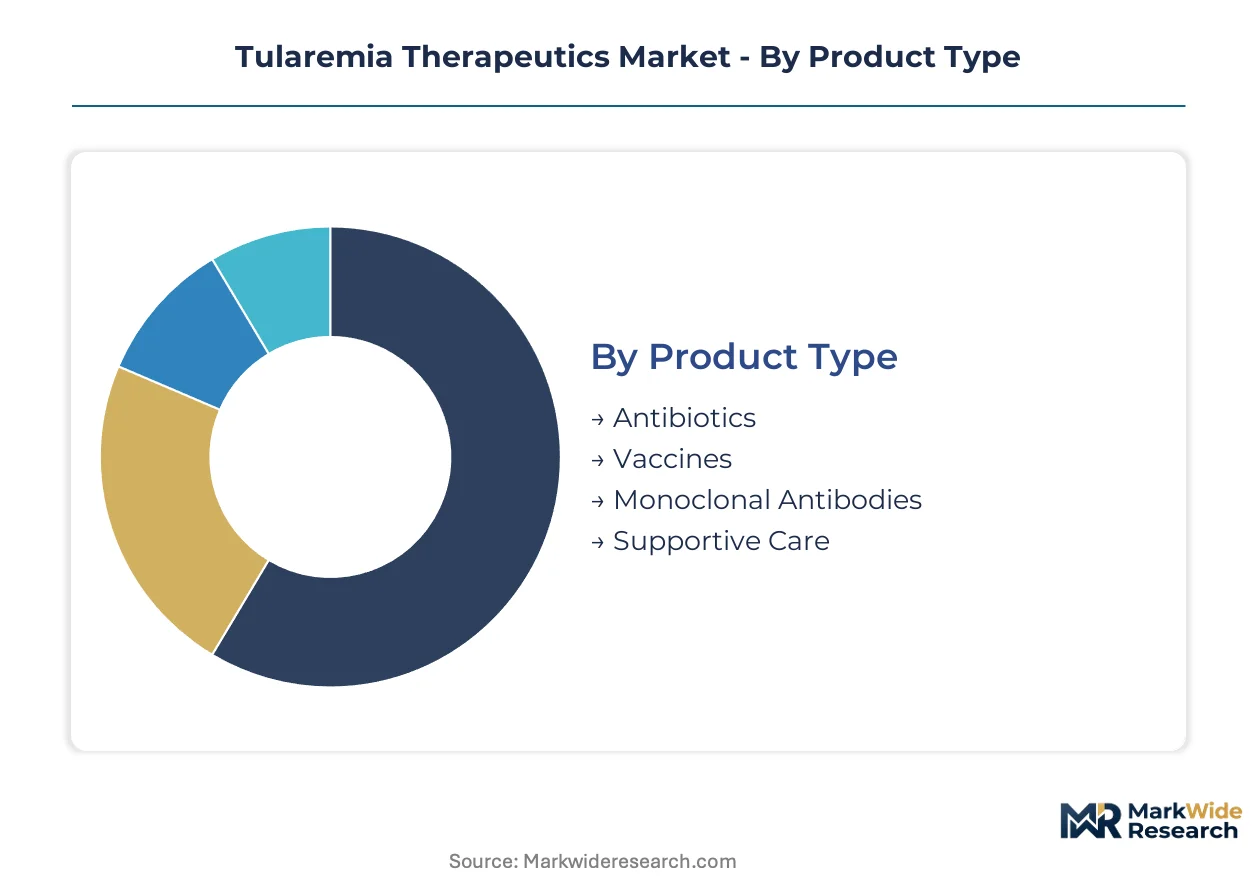
Segmentation of tularemia therapeutics reveals how procurement patterns bifurcate between biodefense stockpiling and clinical treatment pathways. Understanding these divisions exposes where margin concentration and volume scale diverge across product categories and customer types.
Product Type:
Mature antibiotic formulations coexist with emerging biologic platforms as developers navigate divergent regulatory pathways and shelf-life requirements.
- Antibiotics:Streptomycin and gentamicin formulations constitute frontline therapy for ulceroglandular and pneumonic tularemia presentations. Hospital procurement through group purchasing organizations dominates commercial demand, while the Strategic National Stockpile maintains multi-year reserves of parenteral formulations for mass casualty scenarios.
- Vaccines:Live attenuated and subunit candidates target post-exposure prophylaxis under FDA's Animal Rule pathway. BARDA-funded developers prioritize thermostable presentations that withstand strategic stockpile storage conditions without continuous cold-chain infrastructure.
- Monoclonal Antibodies:Recombinant protein engineering enables extended shelf stability beyond traditional vaccine formats. Federal contracts increasingly specify these platforms for surge capacity requirements.
- Supportive Care:Intravenous fluids, respiratory support equipment, and intensive care consumables complete treatment protocols for severe pneumonic cases. State-level public health laboratories stock these alongside diagnostic reagents.
Antibiotics retain volume leadership; monoclonal antibodies hold the steepest expansion curve.
Therapy Area:
Application contexts range from routine infectious disease management to specialized biodefense preparedness mandates with distinct procurement mechanisms.
- Infectious Diseases:Standard clinical protocols govern antibiotic administration for naturally acquired zoonotic infections, with infectious disease specialists directing treatment in tertiary care centers.
- Emergency Medicine:Emergency departments maintain tularemia countermeasures within Category A pathogen response protocols, requiring rapid diagnostic and therapeutic activation for suspected bioterrorism events.
- Public Health:Federal and state health departments coordinate mass prophylaxis distribution through the Cities Readiness Initiative, pre-positioning medical countermeasures in designated metropolitan areas.
- Critical Care:Intensive care units manage respiratory failure and septic complications of pneumonic tularemia, with specialized ventilation strategies and hemodynamic support protocols.
Emergency medicine commands procurement priority; public health channels are gaining share fastest through BARDA contract expansion.
End User:
Customer concentration tilts heavily toward institutional purchasers with specialized handling capabilities and regulatory clearances for select agents.
- Hospitals:Regional Ebola and special pathogens treatment centers anchor demand for complete tularemia treatment protocols, including antibiotics, vaccines, and critical care infrastructure.
- Research Institutes:Biosafety Level 3 facilities at universities and federal laboratories conduct efficacy studies under the Animal Rule, requiring controlled access to Francisella tularensis strains and investigational products.
- Pharmacies:Retail and specialty pharmacy channels serve outpatient antibiotic dispensing for naturally acquired infections, though volumes remain constrained by disease rarity.
- Government Agencies:ASPR, CDC, and DOD manage strategic stockpile procurement through multi-year indefinite delivery contracts with surge optionality clauses.
Government agencies dominate absolute procurement value; hospitals represent the most fragmented expansion opportunity.
Distribution Channel:
Channel structure reflects the dual-use nature of tularemia products, with specialized pathways for biodefense stockpiling parallel to conventional pharmaceutical distribution.
- Direct Sales:Manufacturers fulfill government contracts through dedicated account teams managing BARDA and SNS procurement cycles, bypassing traditional wholesale intermediaries.
- Online Pharmacies:Limited relevance given controlled substance scheduling of frontline antibiotics and cold-chain requirements for biological products.
- Wholesale Distributors:McKesson, AmerisourceBergen, and Cardinal Health handle hospital antibiotic procurement through group purchasing organization contracts.
- Retail Pharmacies:CVS, Walgreens, and independent pharmacies dispense oral doxycycline and ciprofloxacin for outpatient ulceroglandular cases, though awareness among frontline pharmacists remains variable.
Direct sales capture the biodefense premium; wholesale distributors consolidate routine hospital procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BARDA's Project BioShield procurement cycles anchor demand concentration in the United States, while EMA's exceptional circumstances pathway accelerates European market entry for developers seeking dual regulatory approval. National stockpile mandates in select jurisdictions are compressing procurement timelines for biodefense countermeasures.
United States
Federal preparedness mandates through ASPR and CDC drive multi-year procurement commitments for the Strategic National Stockpile. FDA's Animal Rule pathway permits licensure without human challenge studies, compressing vaccine development timelines for Tier 1 select agents. Maryland's I-270 biotech corridor hosts EMERGENT and other federally contracted manufacturers operating BSL-3 containment facilities.
Germany
Paul-Ehrlich-Institut oversight harmonizes with EMA guidelines on emergency stockpiling stability requirements, reducing redundant testing for developers. The country's pharmaceutical manufacturing base supplies antibiotic formulations across European Union member states. Frankfurt-Rhine-Main logistics clusters support cold-chain distribution networks for biological countermeasures.
Switzerland
Swissmedic's alignment with international biodefense preparedness frameworks positions the jurisdiction as a regulatory bridge for US-EU product registration. Federal Office of Public Health coordinates canton-level stockpile pre-positioning for Category A pathogens. Basel's pharmaceutical research triangle concentrates vaccine adjuvant development capabilities.
United Kingdom
UK Health Security Agency procurement through the National Medical Stockpile generates demand independent of NHS clinical treatment volumes. MHRA's post-Brexit regulatory autonomy enables accelerated assessment pathways for prototype pathogen vaccines. Oxford-London biotech corridor hosts developers pursuing recombinant protein platforms for post-exposure prophylaxis.
Canada
Public Health Agency of Canada coordinates federal-provincial stockpile agreements that mirror US Strategic National Stockpile rotation schedules. Health Canada leverages FDA Animal Rule data packages under abbreviated review pathways for select biodefense products. Quebec's vaccine manufacturing infrastructure supports thermostable formulation development for northern climate storage.
Tularemia Therapeutics Market Competitive Landscape
On the supply side, the industry is bifurcated between federally contracted biodefense specialists and diversified pharmaceutical manufacturers serving dual-use markets. Large-cap antibiotic producers anchor hospital procurement channels through group purchasing organization relationships. Emerging biologics developers concentrate on BARDA-funded vaccine and monoclonal antibody platforms. Competitive positioning hinges on BSL-3 manufacturing access and multi-agency regulatory navigation capabilities.
Within the federally contracted tier, EMERGENT exemplifies government fulfillment specialization through indefinite delivery contract vehicles. Merck & Co., Inc. and Pfizer Inc. represent diversified pharmaceutical archetypes leveraging infectious disease manufacturing scale and broad antibiotic portfolios respectively. These structures occupy positions that intersect with public health emergency protocols and national security stockpiling requirements.
| Leading Market Players |
|---|
| Appili Therapeutics |
| Merck & Co., Inc |
| Debiopharm |
| EpiVax, Inc. |
| Cerus Corporation |
| EMERGENT |
| Sanofi |
| Pfizer Inc. |
| GlaxoSmithKline |
| Others |
Value Network & Pricing Analysis
US-based BSL-3 manufacturing concentration in Maryland's I-270 corridor and federal contractor sites concentrates upstream supply, directing margin pools toward government procurement channels and specialized containment facility operators while squeezing commercial hospital buyers.
Pricing Analysis
Volume-discount tiering structures separate Strategic National Stockpile multi-year indefinite delivery contracts from hospital group purchasing organization bundles and retail pharmacy outpatient dispensing. Pricing stratifies across premium, standard, and economy tiers based on FDA Animal Rule certification status and BSL-3 manufacturing pedigree versus generic antibiotic formulations. Cost compression in standard-tier antibiotics intensifies as GPOs consolidate procurement leverage, while premium-tier biodefense vaccines command price insensitivity from BARDA and ASPR. Government agencies exhibit least price sensitivity due to congressional appropriation mandates; retail pharmacies face greatest pressure from formulary substitution and awareness gaps.
Supply Chain Analysis
Single-source vulnerability in Francisella tularensis strain repositories and live attenuated vaccine seed stocks dominates supply chain risk assessment for developers. Manufacturing concentrates in the United States, Switzerland, and the United Kingdom, with raw material dependencies on specialized cell culture media, recombinant protein expression systems, and BSL-3 containment equipment. USDA Select Agent permit requirements create regulatory friction that delays cross-border transfer of biological materials. Distribution runs through direct government contract fulfillment for biodefense products, while wholesale distributors handle hospital antibiotic procurement through McKesson, AmerisourceBergen, and Cardinal Health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA-encoded antigen platforms and recombinant monoclonal antibodies threaten substitution of traditional live attenuated vaccine formats, forcing incumbents to defend manufacturing infrastructure investments against shelf-stable biologic alternatives.
For Market Incumbents: Entrench BSL-3 manufacturing capacity through backward integration into containment facility operations and captive supply of Francisella tularensis reference strains. Secure multi-year BARDA contract extensions with surge optionality clauses before substitution platforms gain Animal Rule approval. Vertical integration into thermostable formulation technology defends against mRNA platform encroachment. For New Entrants and Emerging Players: Pursue state-level public health laboratory distribution channels for rapid field-deployable diagnostic-therapeutic kits, a white-space segment underserved by federal contractors. Target European Union exceptional circumstances pathway approvals to capture dual-market access before US-EU regulatory divergence widens. Partner with GPOs for hospital antibiotic bundling to bypass direct government procurement barriers. For Investors and Strategic Acquirers: Capital is best deployed toward federally contracted biodefense specialists with established BSL-3 infrastructure and multi-agency regulatory navigation capabilities rather than diversified pharmaceutical manufacturers. Long-term viability over the projection horizon rests on congressional appropriation continuity for Project BioShield and SNS rotation schedules. The signal to watch is BARDA funding allocation shifts toward prototype pathogen preparedness versus established Tier 1 select agent programs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Animal Rule Submission | Accelerates licensure pathway for Tier 1 select agents without human challenge studies. |
| BARDA Contract Vehicle Diversification | Spans Project BioShield, CARB-X, and DOD Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense. |
| BSL-3 Manufacturing Scale-Up | Addresses workforce scarcity through specialized technician certification pipelines at federally contracted sites. |
| Dual-Use Platform Technology Licensing | Enables portfolio expansion across Category A pathogens through shared adjuvant systems. |
| Extended Shelf-Life Formulation Development | Aligns with SNS inventory rotation requirements and cold-chain vulnerability mitigation. |
Research Methodology
Cross-validation between regulatory filing analysis and procurement database review anchors the qualitative findings in this study. Primary interviews with biodefense program officers at ASPR, BARDA contract managers, BSL-3 facility operations directors, hospital formulary committee members, and infectious disease specialists combined with secondary validation against FDA Animal Rule guidance documents, BARDA Broad Agency Announcements, Strategic National Stockpile inventory disclosures, and USDA Select Agent registry data. Bottom-up segment sizing triangulates with top-down federal appropriation tracking across the analysis window.
Calibration against historical BARDA contract award values and SNS procurement cycles shapes the analytical framework. Segmentation dimensions modeled include product type, therapy area, end user archetype, and regional regulatory cluster. CAGRs derive from compound growth trajectory analysis of federal biodefense spending patterns and hospital procurement volume trends. Forecast inputs incorporate congressional appropriation volatility for medical countermeasure reserves and Animal Rule approval timeline distributions.
Sensitivities concentrate around congressional funding continuity for the Strategic National Stockpile, FDA Animal Rule correlates of protection validation, and BSL-3 manufacturing capacity expansion timelines. Forecasts reflect assumptions regarding multi-year procurement commitment stability and regulatory pathway harmonization between FDA and EMA. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Gastritis Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market