
 Biochips Market | 2026-2036
Biochips Market Size, Share, and Industry Trends Forecast 2026-2036
Biochips Market Intelligence
The transition towards higher-density, multi-analyte microarrays is reorganizing the market structure for genomic and proteomic analysis. Thermo Fisher Scientific Inc. leverages its broad portfolio to serve diverse research and clinical segments. Illumina, Inc. specializes in sequencing and array-based solutions, anchoring its position in genomics. Agilent Technologies, Inc. competes with a strong focus on custom arrays and integrated workflow solutions for diagnostics and life sciences.
A biochip is a miniaturized device with thousands of molecular probes on a solid surface for massive parallel analysis of biological samples. Its primary purpose is high-throughput screening for gene expression, biomarker discovery, and diagnostics. DNA Microarrays constitute a foundational segment, but growth is accelerating in Protein Chips for drug discovery. Pharmaceutical firms and academic institutions remain the largest end-user segments, driving requirements for higher specificity and throughput.
Regulatory frameworks from the FDA in the United States and the EMA in Europe under the MDR establish stringent validation requirements for biochips used in clinical diagnostics. In China, the NMPA oversees market approval, creating distinct regional compliance pathways. Future competitive advantage depends on a vendor's ability to integrate sophisticated data analysis software with their biochip hardware platforms.
Market Dynamics
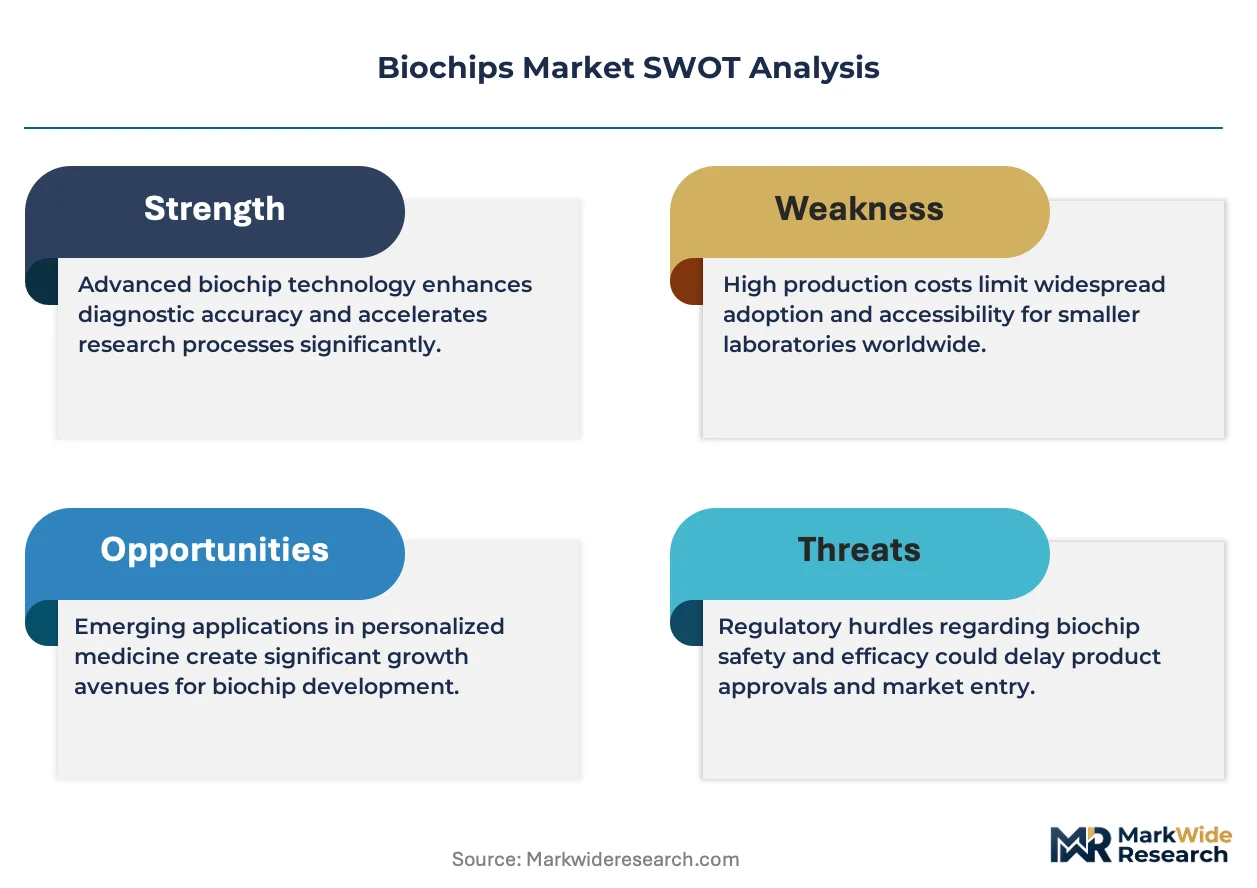
The central force shaping the biochips market is the escalating requirement from pharmaceutical and biotechnology firms for higher throughput and specificity in drug discovery and diagnostics. This demand accelerates innovation in microarray and microfluidic technologies for parallel analysis.
Growth Catalysts
- Electrochemical Sensing Advances:Improvements in electrochemical detection methods are increasing the sensitivity and lowering the cost of biochip analysis, expanding their use beyond specialized research labs into broader clinical applications.
- Pharmaceutical Research Demand:Drug discovery and development pipelines in pharmaceutical companies rely heavily on high-throughput screening. Biochips, particularly protein chips, meet this need by enabling rapid analysis of compound interactions and biomarker validation.
- Academic Research Infrastructure:The extensive network of government-funded academic and research institutions, particularly in the United States, provides a stable, large-scale end-user base that drives foundational technology development and adoption.
Market Restraints
- High Capital Investment:The fabrication of biochips requires sophisticated cleanroom facilities and lithography equipment, representing a significant upfront capital expenditure that acts as a barrier to entry for smaller firms.
- Data Management Bottlenecks:High-density microarrays generate vast quantities of complex data, creating challenges for data storage, processing, and bioinformatic analysis, which can limit the practical throughput for some end-users.
- Stringent Regulatory Hurdles:Biochips intended for clinical diagnostics face rigorous and lengthy validation processes from bodies like the FDA and under Europe's MDR, delaying commercialization and increasing development costs.
Strategic Opportunities
- Point-of-Care Diagnostics:Developing miniaturized, portable biochip systems for point-of-care testing presents a major growth opportunity, enabling rapid diagnostics in clinics, physicians' offices, and resource-limited settings.
- AI and Machine Learning Integration:Combining biochip platforms with AI-driven data analysis software can unlock new capabilities in predictive modeling for disease risk, treatment response, and accelerated biomarker discovery from complex datasets.
- Personalized Medicine Applications:The growing focus on personalized medicine creates demand for custom biochips capable of analyzing an individual's unique genetic or proteomic profile to guide tailored therapeutic strategies.
Industry Challenges
- Lack of Standardization:The absence of universal standards for biochip formats, data output, and quality control metrics hinders the comparability of results across different platforms and laboratories, impeding widespread clinical adoption.
- Bioinformatics Skill Gap:A shortage of professionals with hybrid expertise in molecular biology, microfluidics, and computational data analysis creates a bottleneck in interpreting biochip-generated data and developing new applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biochips Market |
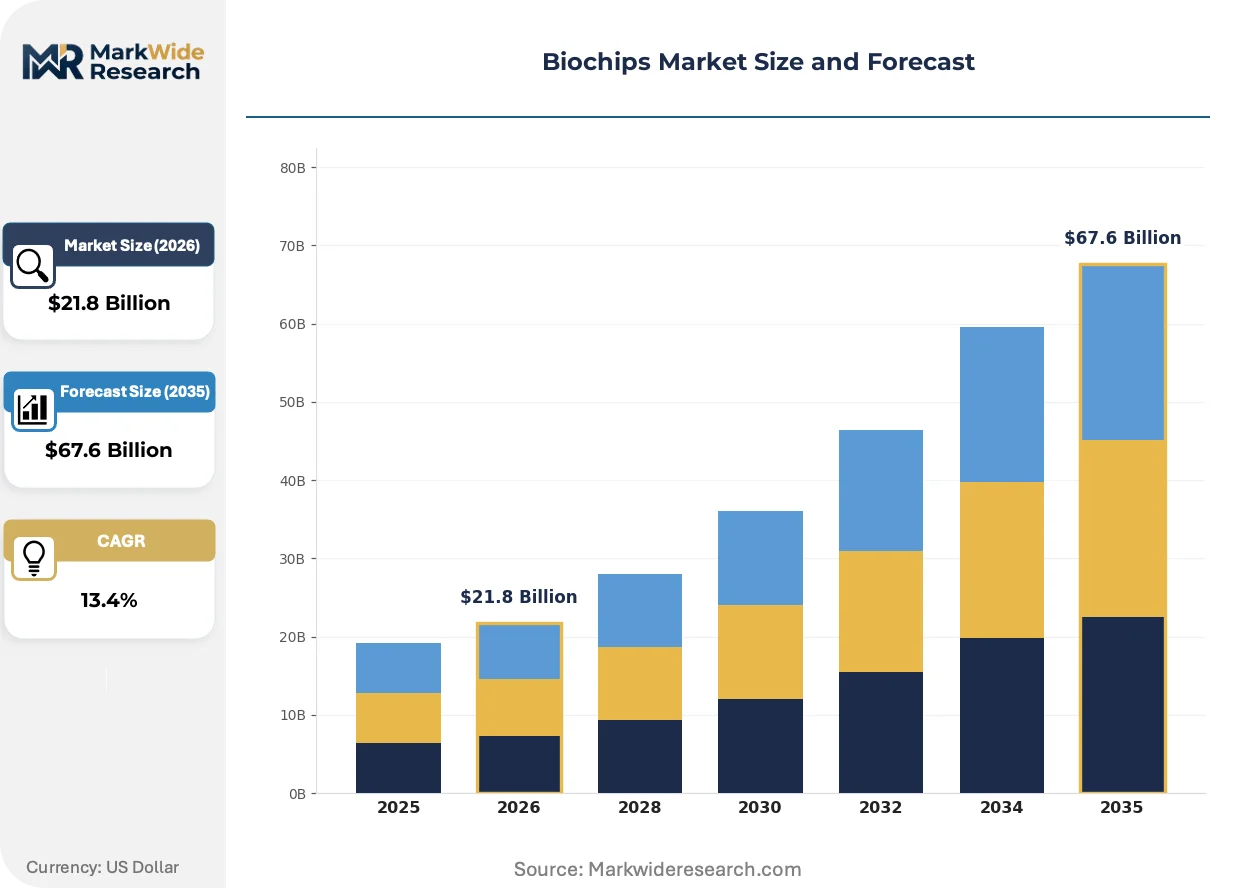
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $67.6 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Microarray, Protein Chips, Tissue Chips, Glycan Biochips, Lipid Chips Technology: Optical Detection, Electrochemical Sensing, Mass Spectrometry, Fluorescence, Label-free Detection Application: Genomics Research, Drug Discovery, Biomarker Identification, Diagnostics, Environmental Monitoring End User: Pharmaceutical Firms, Academic Institutions, Biotechnology Laboratories, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Illumina, Inc., Agilent Technologies, Inc., F. Hoffmann-La Roche Ltd, QIAGEN, Bio-Rad Laboratories, Inc., Abbott Laboratories, PerkinElmer, Inc., GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biochips Market Strategic Shifts & Innovations
The convergence of microfluidics, genomics, and data science is defining the next generation of biochip platforms. This evolution moves the technology from purely research tools toward integrated systems for clinical decision-making and personalized health monitoring.
Lab-on-a-Chip (LOC) technology integrates multiple laboratory processes like sample preparation and analysis onto a single miniaturized device. This technology is seeing rapid adoption in clinical diagnostics and environmental monitoring sectors due to its portability and minimal sample requirements. The core consequence is that LOC technology is miniaturizing complex analytical workflows, enabling rapid, on-site analysis that was previously confined to centralized laboratories.
Europe's Medical Device Regulation (MDR) establishes more stringent requirements for clinical evidence and post-market surveillance for all medical devices, including diagnostic biochips. This regulatory shift forces manufacturers to generate more extensive performance and safety data prior to obtaining a CE marking. As a result, companies targeting the European in-vitro diagnostics market are increasing investment in quality management systems and conducting more rigorous clinical validation studies.
End-user purchasing behavior is shifting from acquiring standalone biochip readers to investing in fully integrated workflow solutions. These systems bundle the hardware platform with proprietary software, reagents, and consumables, offering a streamlined process from sample to result. This trend is most visible within large pharmaceutical firms and contract research organizations, which prioritize throughput, data integrity, and reduced technical variability across experiments.
Biochips Market Segmentation
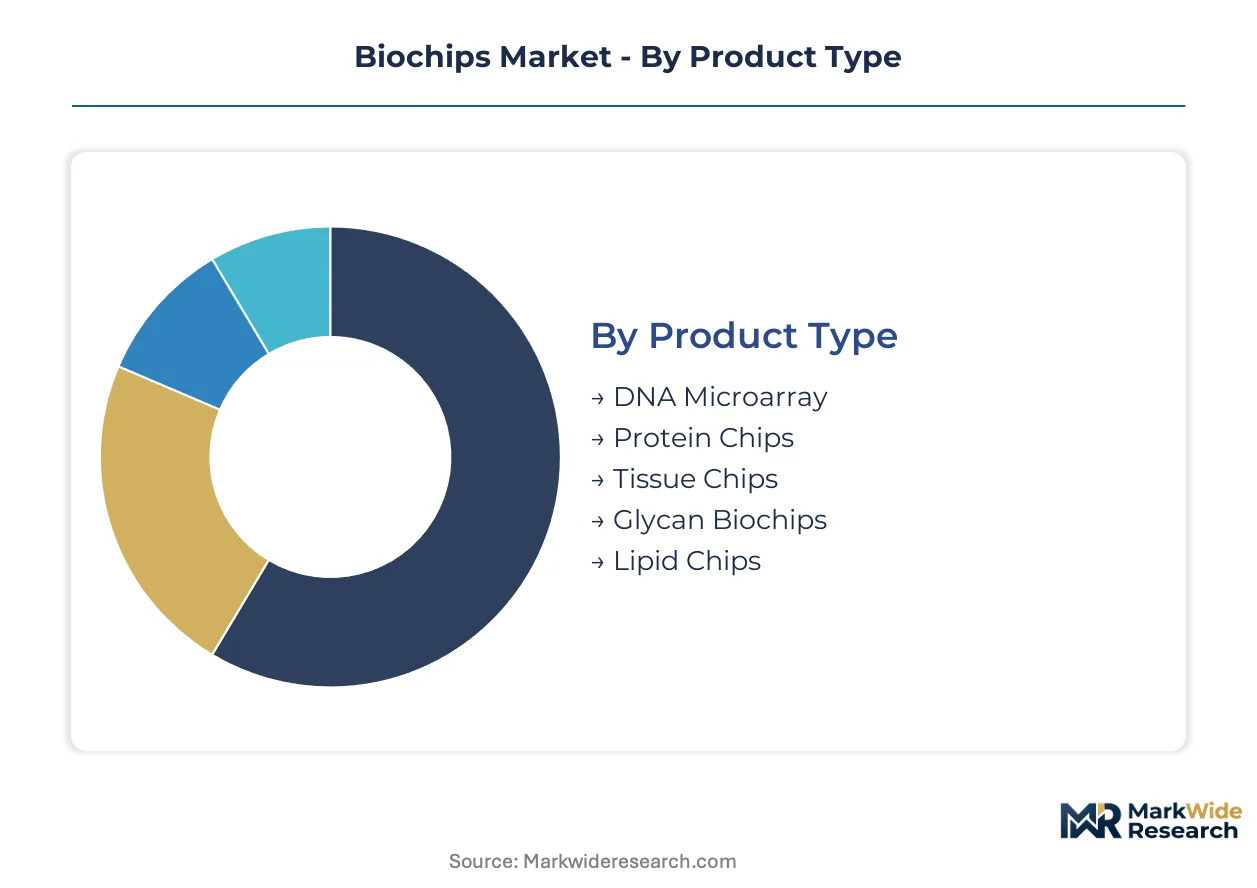
The Biochips Market segmentation reveals distinct areas of innovation and demand, driven by specialized research needs and clinical applications. Understanding these segments helps to identify where technological advancements and strategic investments are most impactful across the industry.
Product Type:
Product Type segmentation illustrates how different biochip formats cater to regional research priorities and clinical adoption patterns.
- DNA Microarray:DNA Microarrays feature thousands of immobilized DNA probes on a solid substrate for parallel analysis of gene expression and genetic variations. Demand remains strong in academic institutions and biotechnology laboratories, driven by genomic research requiring high-throughput screening.
- Protein Chips:Protein Chips utilize arrays of proteins or antibodies to analyze protein-protein interactions, enzyme activity, and biomarker discovery. Pharmaceutical firms increasingly adopt these chips for drug discovery, where rapid validation of therapeutic targets is critical.
- Tissue Chips:Tissue Chips mimic human organ physiology for drug efficacy and toxicity testing, reducing reliance on animal models.
- Glycan Biochips:Glycan Biochips enable high-throughput analysis of carbohydrate structures, supporting research in immunology and cancer biology.
- Lipid Chips:Lipid Chips facilitate the study of lipid-protein interactions and membrane biology, crucial for understanding cellular processes.
DNA Microarray holds the largest share; momentum sits with Protein Chips.
Technology:
Technology segmentation highlights the varying cost structures and performance capabilities inherent in different detection methodologies for biochip analysis.
- Electrochemical Sensing:Electrochemical Sensing detects molecular interactions via electrical signal changes, offering high sensitivity and miniaturization potential. These advancements expand biochip use into broader clinical applications, driven by lower per-test costs and rapid results.
- Optical Detection:Optical Detection methods, like fluorescence and chemiluminescence, rely on light-based signals to quantify biomolecule binding events on biochip surfaces. This foundational technology maintains widespread use in research, valued for established protocols and robust data output.
- Mass Spectrometry:Mass Spectrometry integrates with biochips for label-free, highly specific identification and quantification of biomolecules, particularly proteins.
- Fluorescence:Fluorescence detection remains prevalent due to its high sensitivity and compatibility with various biochip formats.
- Label-free Detection:Label-free detection technologies monitor molecular interactions in real-time without requiring fluorescent or radioactive tags.
Optical Detection technologies command significant installed base, while Electrochemical Sensing exhibits the steepest expansion trajectory.
Application:
Application segmentation delineates where biochip utilization generates the highest volumes of data and clinical insights across diverse scientific fields.
- Drug Discovery:Drug Discovery applications leverage biochips for high-throughput screening of compound libraries, target validation, and toxicity testing in pharmaceutical development. This segment demands miniaturized platforms for rapid, parallel analysis to accelerate lead compound identification.
- Diagnostics:Diagnostics applications utilize biochips for rapid and accurate detection of diseases, pathogens, and genetic predispositions in clinical settings. Regulatory frameworks from the FDA and Europe's MDR establish stringent validation requirements for these critical tools.
- Genomics Research:Genomics Research employs biochips for gene expression profiling, SNP analysis, and DNA sequencing, advancing understanding of genetic mechanisms.
- Biomarker Identification:Biomarker Identification uses biochips to discover and validate disease-specific markers, crucial for early diagnosis and personalized treatment.
- Environmental Monitoring:Environmental Monitoring applications deploy biochips for detecting pollutants and toxins in water and air samples, ensuring public safety.
Drug Discovery applications drive substantial revenue, with Diagnostics gaining share fastest due to clinical integration.
End User:
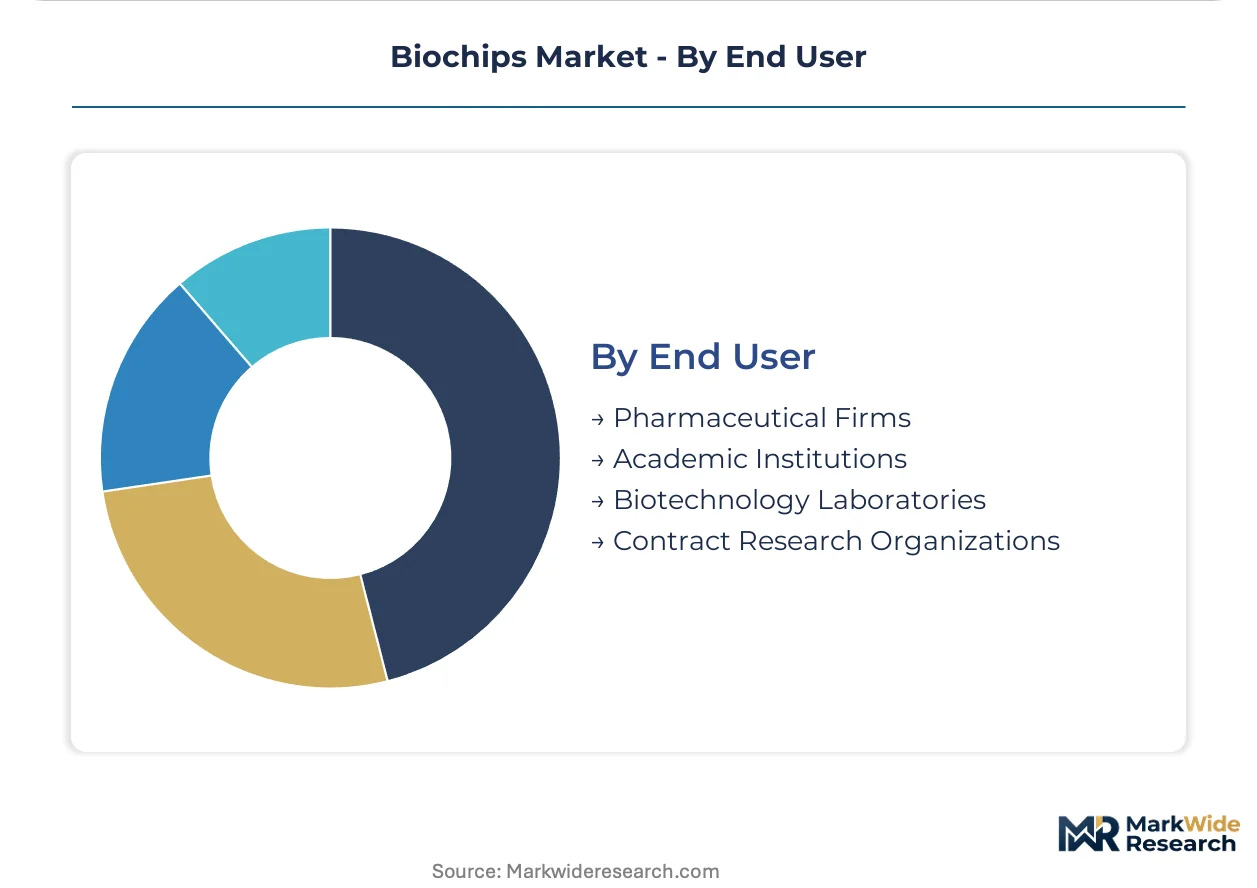
End User segmentation categorizes the primary institutional and commercial entities driving demand for biochip technologies based on their operational models.
- Pharmaceutical Firms:Pharmaceutical Firms represent a major end-user segment, employing biochips for high-throughput screening, drug candidate optimization, and early-stage clinical trials. Their demand for higher specificity and throughput accelerates innovation in biochip design.
- Academic Institutions:Academic Institutions, particularly in the United States, constitute a stable, large-scale end-user base for biochips, driving foundational technology development. Government funding supports extensive research projects in genomics and proteomics, fueling biochip adoption.
- Biotechnology Laboratories:Biotechnology Laboratories leverage biochips for various R&D activities, including genetic engineering, cell culture analysis, and novel assay development.
- Contract Research Organizations:Contract Research Organizations (CROs) utilize biochips to offer specialized research services to pharmaceutical and biotech clients, optimizing outsourced drug development.
Pharmaceutical Firms represent the largest consumer base, while Biotechnology Laboratories are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Biochips Market exhibits varied regional dynamics, with some nations serving as net exporters of advanced biochip technologies while others primarily drive demand through domestic research and diagnostic needs. This balance influences local manufacturing capabilities, regulatory harmonization efforts, and the strategic positioning of global vendors. Trade flows of specialized biochip components and integrated systems reflect national investments in biotechnology infrastructure.
United States
United States demand for biochips stems from its robust pharmaceutical research and academic institutions. The Food and Drug Administration (FDA) sets rigorous standards for diagnostic biochips, ensuring clinical reliability. The Boston-Cambridge biotechnology cluster remains a hub for biochip innovation, attracting significant venture capital for new platform development.
Germany
German pharmaceutical firms and research centers drive demand for high-throughput protein chips in drug discovery. European Medical Device Regulation (MDR) mandates stringent clinical validation for biochips sold within the European Union. Munich's vibrant biotech ecosystem fosters collaborations between academic research and industry for advanced biochip applications.
China
China's biochips market expands rapidly, fueled by increasing investment in genomic research and clinical diagnostics. The National Medical Products Administration (NMPA) oversees market approval processes, influencing product design and localization strategies. Shanghai's burgeoning life science parks attract both domestic and international biochip manufacturers establishing local R&D and production facilities.
Japan
Japanese academic institutions and biotech companies seek advanced biochip solutions for biomarker identification and personalized medicine research. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates the development and commercialization of diagnostic biochips. Tokyo's research universities and industrial parks contribute to cutting-edge microfluidic and label-free detection biochip advancements.
Biochips Market Key Industry Players
Listed leaders compete with private specialists across the biochip technology and application spectrum, creating a dynamic market environment. The market structure is characterized by a blend of highly diversified conglomerates offering broad portfolios and niche technology innovators focusing on specific detection methods. Strategic archetypes include integrated workflow solution providers, specialized platform developers for genomics, and consumables-focused suppliers. Companies frequently engage in portfolio diversification and strategic partnerships to expand their market reach and integrate new analytical capabilities.
Integrated workflow solution providers like Thermo Fisher Scientific Inc. exemplify the strategy of offering comprehensive platforms that span instruments, specialized reagents, and advanced data analysis software. Illumina, Inc. occupies a position as a specialized platform developer, anchoring its offerings around sequencing and array-based genomic solutions for high-throughput analysis. Agilent Technologies, Inc. represents another key player, known for its custom arrays and integrated workflow solutions particularly in diagnostics and life sciences, catering to diverse research and clinical segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| Agilent Technologies, Inc. |
| F. Hoffmann-La Roche Ltd |
| QIAGEN |
| Bio-Rad Laboratories, Inc. |
| Abbott Laboratories |
| PerkinElmer, Inc. |
| GE Healthcare |
| Others |
Cost & Logistics Intelligence
Europe's Medical Device Regulation (MDR) gates both supply qualification and price differentiation for biochips, particularly in clinical diagnostics. This regulatory framework necessitates significant investment in validation, influencing the cost structures across the value chain.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing models for biochips. Price differentiation stems from certification levels, such as FDA approval for clinical use, and the degree of customization required for specialized research applications. Pricing softness reflects intense competition among established vendors for large institutional contracts. Academic institutions, often operating under grant funding, exhibit the highest price sensitivity, driving demand for cost-effective, high-throughput solutions.
Supply Chain Analysis
Single-source vulnerability for advanced microfluidic components underpins a key supply chain risk for biochip manufacturers. Geographic supply concentration centers on the United States and Germany for high-end research biochips, while China increasingly supplies lower-cost, high-volume diagnostic arrays. Raw material dependencies include specialized polymers, silicon wafers, and high-purity reagents. Distribution runs through a blend of direct sales channels to large pharmaceutical firms and a network of specialized distributors serving academic and biotechnology laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Biochips Market is undergoing a platform-economics inflection, driven by the increasing interoperability between biochip hardware and advanced data analysis ecosystems.
For Market Incumbents: Compound existing advantages in integrated workflow solutions by acquiring specialized software analytics firms. This move addresses the bioinformatics skill gap and enhances the value proposition against emerging, vertically integrated competitors. Focus on securing long-term supply agreements for critical raw materials to mitigate single-source vulnerabilities in the supply chain.
For New Entrants and Emerging Players: Differentiate on rapid point-of-care diagnostics for specific disease indications. Target underpenetrated clinical segments in emerging economies with portable, user-friendly biochip systems. A go-to-market angle emphasizing cost-effectiveness combined with regulatory compliance, particularly in regions with less stringent approval pathways, can create market traction.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting in an upward direction across the advanced biochip manufacturing sub-segment. Seek out mid-cap specialists with strong intellectual property in electrochemical sensing or label-free detection technologies. The signal to watch is the increasing investment by pharmaceutical firms in dedicated in-house biochip R&D facilities, indicating future demand for highly specialized platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI with Biochip Platforms | This enhances data interpretation and accelerates biomarker discovery, creating significant analytical value for end-users. |
| Secure Advanced Microfluidic Component Supply | Ensuring access to specialized materials mitigates production risks and maintains manufacturing capacity. |
| Pursue FDA/EMA Clinical Validation | Achieving regulatory approval unlocks access to lucrative clinical diagnostics markets in key regions. |
| Develop Portable Point-of-Care Systems | Miniaturized devices expand market reach into decentralized healthcare settings and resource-limited areas. |
| Form Strategic Partnerships with CROs | Collaborations with contract research organizations streamline outsourced drug development workflows for pharmaceutical clients. |
Research Approach
Operator-level perspectives from R&D directors, lab managers, procurement specialists, and regulatory affairs leads anchored the qualitative base of this analysis. Primary interviews were triangulated with extensive secondary validation from scientific publications, patent databases, and annual reports. This approach ensured a balanced bottom-up and top-down understanding of market dynamics.
Sensitivity analysis framed the quantitative projections across the analysis window, modeling various market scenarios. Segmentation dimensions included product type, technology, application, end-user, and regional demand patterns. Compound annual growth rates were derived by factoring in historical data, technological advancements, and projected end-user adoption trends, with forecast inputs including R&D spending and clinical trial volumes.
Material uncertainties — including unforeseen regulatory changes or disruptive technological breakthroughs — sit outside the modeled envelope. Forecasts reflect a comprehensive set of assumptions regarding market drivers and restraints. Practitioners should keep alternative scenarios live as biotechnology investment and healthcare policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Strand Displacement Amplicon (SDA) Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
Global Cell Dissociation Market