
 Antibody Isotyping Kit Market | 2026-2036
Antibody Isotyping Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Isotyping Kit Market Outlook
The EU In Vitro Diagnostic Regulation is consolidating compliance requirements across European diagnostic supply chains, forcing kit manufacturers to revalidate labeling and performance claims. Thermo Fisher Scientific leverages its CLIA-certified manufacturing network to sustain dual-market access under both IVDR and FDA pathways. Bio-Rad anchors its position through proprietary multiplexing chemistries that reduce assay time for high-throughput laboratories. BD competes on integrated workflow solutions that bundle isotyping reagents with its cytometry hardware platforms.
Antibody isotyping kits are reagent systems designed to classify immunoglobulin subclasses—IgG, IgM, IgA, and IgE—through antigen-binding detection, typically employing enzyme-linked immunosorbent assay or lateral flow formats with species-specific secondary antibodies. Their primary purpose is to characterize humoral immune responses in vaccine development, hybridoma screening, and therapeutic antibody quality control. Flow cytometry-based isotyping commands premium positioning due to single-cell resolution requirements in immuno-oncology pipelines, while ELISA formats dominate routine diagnostic volume through lower per-test costs and minimal equipment requirements. Research laboratories represent the most price-sensitive end-user tier, whereas pharmaceutical companies generate concentrated margin pools through bulk custom assay development contracts.
FDA 21 CFR Part 820 quality system regulations, EU IVDR Class C designation requirements, and ISO 13485 medical device quality standards collectively govern kit commercialization, with IVDR's expanded clinical evidence mandates particularly elevating barriers for smaller reagent suppliers. Health Canada and Japan's PMDA maintain aligned but distinct approval pathways that fragment go-to-market timing for multinational kit portfolios. Stakeholders must monitor evolving biosimilar immunogenicity guidance from regulators and assess whether backward integration into recombinant antibody production strengthens supply security or dilutes core reagent focus.
Market Dynamics
Biologics pipelines are reshaping kit demand as pharmaceutical developers require subclass-specific characterization for therapeutic antibody candidates. The FDA's evolving biosimilar immunogenicity guidance is compressing validation timelines while elevating performance thresholds for commercial reagent suppliers.
Growth Catalysts
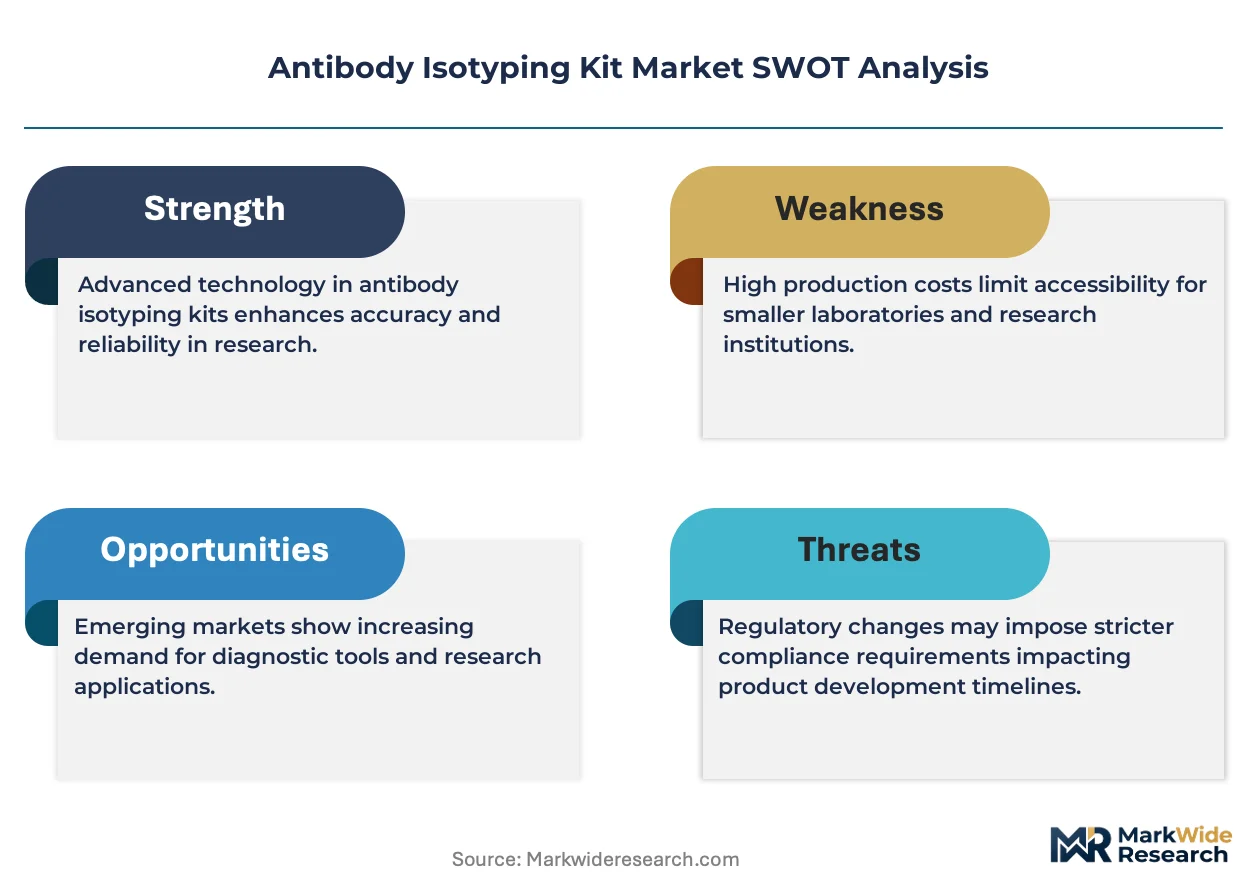
- IVDR Class C designation:The EU In Vitro Diagnostic Regulation mandates elevated clinical evidence for antibody detection reagents, creating replacement demand as laboratories retire non-compliant inventory.
- Hybridoma screening intensity:Academic immunology laboratories in the United States are expanding monoclonal antibody production for infectious disease research, driving consumable throughput.
- Flow cytometry convergence:Single-cell resolution requirements in immuno-oncology pipelines are pulling premium isotyping formats into clinical development workflows.
Market Restraints
- Species-specific antibody supply concentration:Secondary antibody production concentrates among specialized serum fractionators, exposing kit manufacturers to raw material availability risk.
- IVDR technical documentation burden:Smaller reagent suppliers face structural exclusion as the EU regulation mandates performance study investments exceeding their capital base.
- ELISA format commoditization:Established enzyme-linked immunosorbent assay protocols face price compression from lateral flow alternatives in routine diagnostic settings.
Strategic Opportunities
- Health Canada alignment pathway:The regulator's structured recognition of FDA and EU approvals creates accelerated entry for validated kit portfolios into the Canadian market.
- Multiplexing chemistry convergence:Laboratories seek reduced assay time through simultaneous IgG/IgM/IgA detection, rewarding proprietary detection chemistry development.
- Contract research organization channel:Outsourced biologics characterization services represent underpenetrated demand for bulk reagent supply agreements with guaranteed volume commitments.
Industry Challenges
- ISO 13485 quality system implementation:Medical device certification timelines extend 12-18 months for reagent manufacturers transitioning from research-use-only production.
- Analytical validation personnel scarcity:Kit developers compete for immunoassay scientists capable of executing parallel FDA and IVDR performance studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Isotyping Kit Market |
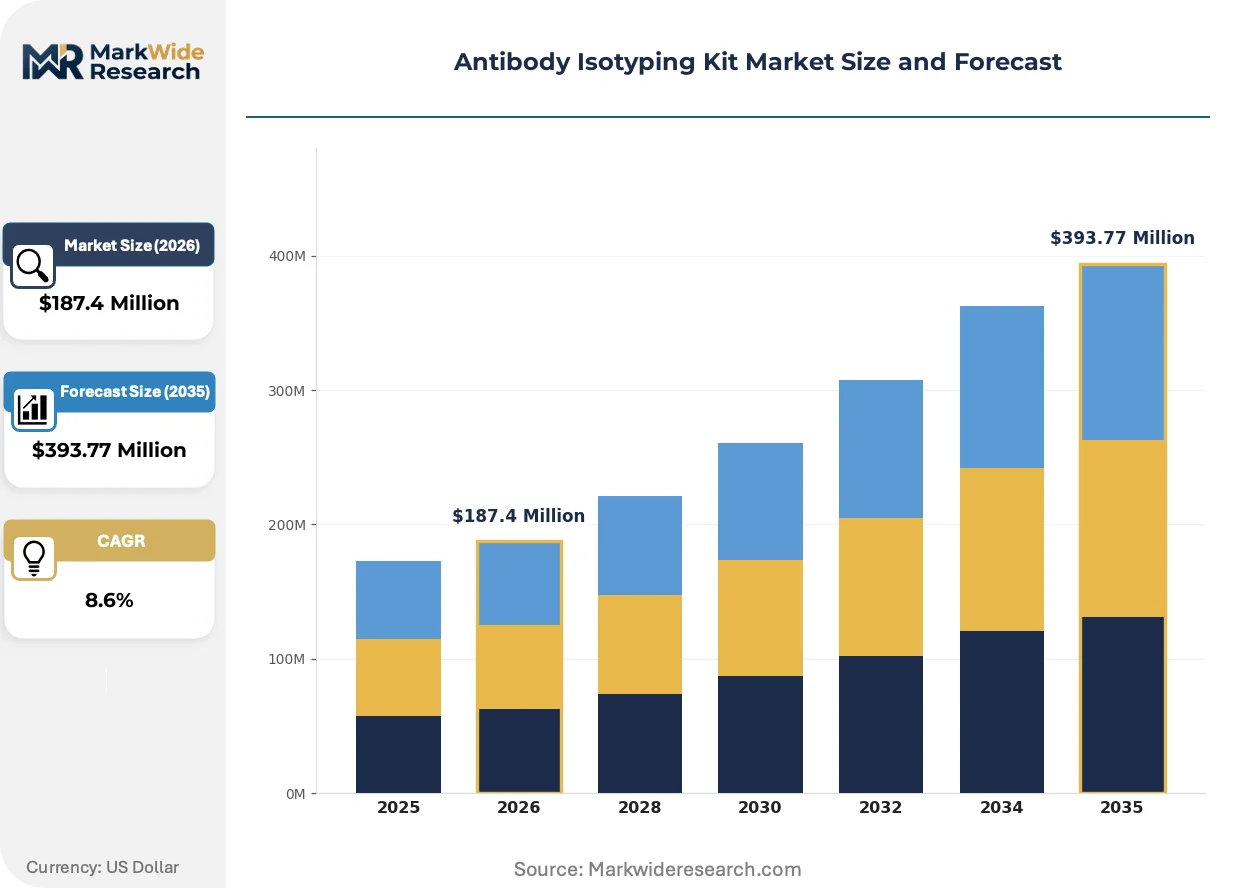
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IgG, IgM, IgA, IgE Application: Immunology, Cancer Diagnosis, Infectious Diseases, Autoimmune Disorders End User: Research Laboratories, Diagnostic Centers, Pharmaceutical Companies, Academic Institutions Technology: Flow Cytometry, ELISA, Western Blotting, Immunofluorescence |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad, BD, Abbott, Roche, Danaher, BioMérieux, Ortho Clinical Diagnostics, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Isotyping Kit Market Strategic Shifts
Detection platform evolution is compressing assay timelines while regulatory harmonization efforts are fragmenting compliance strategies across major commercial jurisdictions.
Multiplexed lateral flow formats are expanding into point-of-care vaccine response monitoring. Public health laboratories in low-resource settings are adopting these strips for field-deployable serosurveillance. The technology is expanding into previously instrument-dependent applications by eliminating cold-chain requirements for reagent stability.
Japan's PMDA has aligned biologics immunogenicity testing guidance with FDA precedent, reducing redundant validation for multinational kit portfolios. This convergence accelerates submission preparation but requires simultaneous documentation in English and Japanese. Pharmaceutical quality control laboratories in Osaka and Tokyo are consolidating supplier qualifications around vendors with dual-pathway experience.
Research laboratories are unbundling after-sales technical support from reagent procurement, driving kit manufacturers to publish open-access protocol optimization resources. This behavior shift compresses margin capture from service contracts while elevating self-service documentation quality as a competitive discriminator. The pattern is most visible in NIH-funded academic centers where indirect cost recovery constraints limit discretionary spending.
Antibody Isotyping Kit Market Segmentation
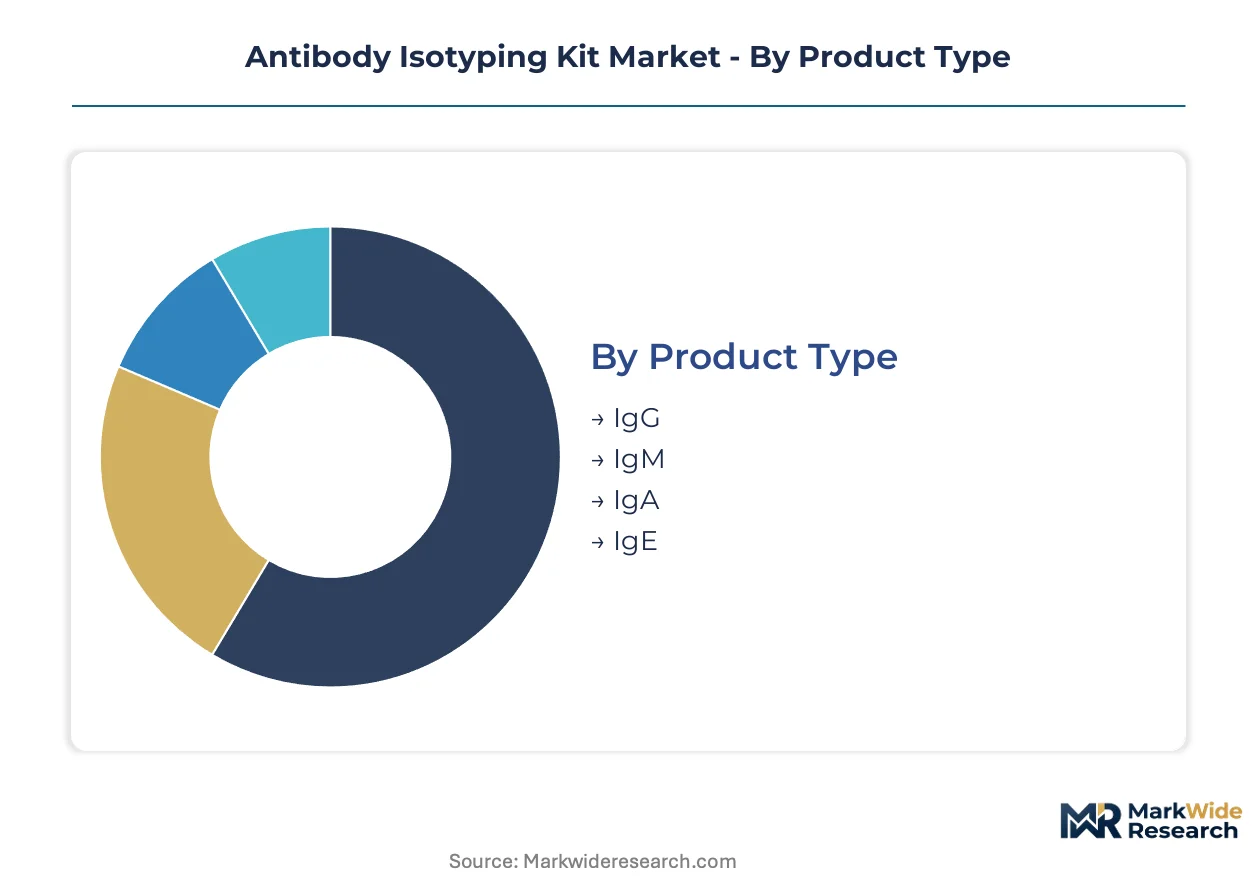
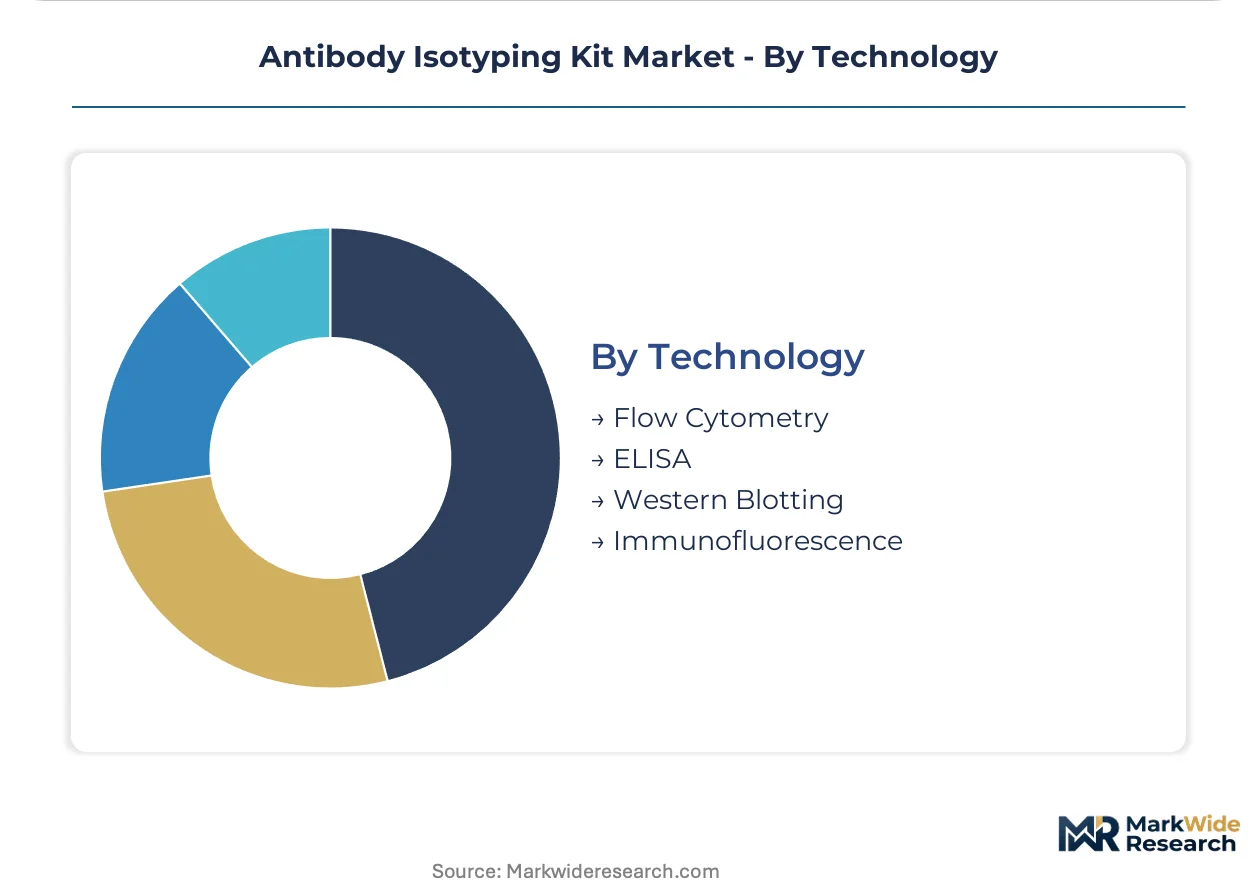
Antibody isotyping kit segmentation reveals distinct procurement patterns across detection platforms and end-use environments. Supply chain configuration varies sharply between high-volume diagnostic formats and precision research tools, shaping manufacturer portfolio priorities.
Product Type:
Secondary antibody supply concentration dictates kit availability across immunoglobulin classes, with serum fractionation bottlenecks affecting subclass-specific reagent lead times.
- IgG:Dominant subclass for therapeutic monoclonal antibody characterization, with subclass-specific secondary antibodies sourced primarily from US and European serum processors. Pharmaceutical quality control laboratories in Massachusetts and California drive concentrated demand for high-specificity IgG1/IgG2a discrimination reagents.
- IgM:Primary detection target for acute infection serology and early vaccine response assessment. Diagnostic centers in Texas and Florida generate routine volume for infectious disease panels, though cold-chain stability requirements limit field-deployable format adoption.
- IgA:Mucosal immunity research applications concentrate in NIH-funded academic centers studying respiratory and gastrointestinal pathogen responses.
- IgE:Allergy and hypersensitivity testing niche with premium pricing tied to specialized secondary antibody conjugation protocols.
IgG absorbs the bulk of installed capacity; IgM is expanding most quickly through infectious disease diagnostic automation.
Application:
Cost tier differentiation separates validated clinical assays from research-grade reagents, with regulatory burden scaling proportionally to patient-facing use cases.
- Immunology:Foundational research applications spanning hybridoma screening, B-cell repertoire analysis, and autoimmune biomarker discovery. Academic medical centers in Maryland and Pennsylvania sustain steady consumable demand through NIH R01-funded investigator programs.
- Cancer Diagnosis:Immuno-oncology biomarker profiling for checkpoint inhibitor monitoring and CAR-T cell product characterization. Flow cytometry-based isotyping commands premium positioning in clinical trial laboratories seeking single-cell resolution.
- Infectious Diseases:Serosurveillance and vaccine efficacy measurement, with lateral flow format adoption accelerating in public health field deployments.
- Autoimmune Disorders:Anti-nuclear antibody subclass profiling for lupus and rheumatoid arthritis differential diagnosis.
Immunology captures the highest reagent volume throughput; cancer diagnosis exhibits the steepest expansion trajectory as immuno-oncology pipelines mature.
End User:
Customer type determines pricing tolerance and technical support expectations, with pharmaceutical procurement teams negotiating multi-year supply agreements against research laboratory spot purchasing.
- Research Laboratories:Price-sensitive academic and government facilities prioritizing per-test economy over regulatory documentation. Bulk purchasing consortia in the Research Triangle and San Francisco Bay Area concentrate negotiation leverage.
- Pharmaceutical Companies:Therapeutic antibody developers requiring validated reagents with full regulatory traceability for IND-enabling studies and GMP quality control. Custom assay development contracts generate concentrated margin pools through guaranteed volume commitments.
- Diagnostic Centers:High-throughput clinical laboratories seeking workflow integration with existing immunoassay platforms.
- Academic Institutions:Teaching hospitals and undergraduate research programs with constrained indirect cost recovery limiting discretionary reagent spending.
Pharmaceutical companies command the deepest supplier relationships; diagnostic centers are gaining procurement sophistication through laboratory network consolidation.
Technology:
Platform maturity shapes competitive dynamics, with established ELISA protocols facing displacement pressure from multiplexed alternatives in time-sensitive applications.
- ELISA:Enzyme-linked immunosorbent assay formats dominate routine diagnostic volume through minimal equipment requirements and established protocol familiarity. Clinical laboratories in Ohio and Illinois maintain substantial installed bases of automated plate processors.
- Flow Cytometry:Single-cell resolution capability drives adoption in immuno-oncology and stem cell research applications requiring phenotypic subset discrimination. Instrument manufacturer bundling strategies influence reagent procurement decisions.
- Western Blotting:Semi-quantitative subclass confirmation for research antibody validation and publication-grade specificity documentation.
- Immunofluorescence:Tissue-based localization studies in pathology research, with manual microscopy protocols limiting throughput scalability.
ELISA retains the broadest installed instrument base; flow cytometry is climbing the fastest through clinical trial laboratory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibody isotyping kit production concentrates among specialized serum fractionators in the United States and Europe, while demand expansion accelerates across Asia-Pacific biologics manufacturing hubs. Consumption patterns diverge sharply between mature diagnostic markets and emerging therapeutic development centers.
United States
Pharmaceutical quality control laboratories in Massachusetts and California drive concentrated demand for high-specificity IgG subclass discrimination reagents. FDA 21 CFR Part 820 quality system regulations govern kit commercialization, with evolving biosimilar immunogenicity guidance compressing validation timelines. The Research Triangle and San Francisco Bay Area anchor academic procurement through NIH-funded immunology research programs.
Germany
Diagnostic centers in Bavaria and North Rhine-Westphalia maintain substantial installed bases of automated ELISA plate processors for routine immunoglobulin testing. EU IVDR Class C designation mandates elevated clinical evidence for antibody detection reagents, forcing laboratories to retire non-compliant inventory. The Munich biotech cluster sustains premium demand for flow cytometry-based isotyping in immuno-oncology applications.
Japan
PMDA-aligned biologics immunogenicity testing guidance with FDA precedent reduces redundant validation for multinational kit portfolios. Pharmaceutical quality control laboratories in Osaka and Tokyo consolidate supplier qualifications around vendors with dual-pathway regulatory experience. The Kansai region exhibits particular concentration in therapeutic antibody manufacturing quality control.
China
Domestic biologics developers expand monoclonal antibody production capacity, driving consumable throughput for hybridoma screening applications. NMPA medical device regulations create structured but distinct approval pathways that fragment go-to-market timing for imported reagent portfolios. The Yangtze River Delta biopharma corridor generates concentrated demand for validated research-grade isotyping kits.
India
Contract research organizations in Hyderabad and Bengaluru represent underpenetrated demand for bulk reagent supply agreements with guaranteed volume commitments. CDSCO medical device regulations maintain alignment with international standards while requiring localized performance documentation. The Genome Valley cluster anchors outsourced biologics characterization services procurement.
Antibody Isotyping Kit Market Competitive Environment
The competitive structure tilts toward diversified life science conglomerates with CLIA-certified manufacturing networks and integrated workflow capabilities. Kit manufacturers compete across three primary vectors: regulatory pathway breadth, multiplexing chemistry proprietary position, and cytometry hardware bundling leverage. Two dominant competitive moves define current positioning: strategic partnerships with instrument manufacturers for workflow integration, and geographic expansion through dual FDA-IVDR validated manufacturing footprints.
Among diversified life science conglomerates, Thermo Fisher Scientific, Bio-Rad, and BD occupy positions reflecting distinct strategic archetypes. Thermo Fisher Scientific exemplifies the regulatory breadth archetype through sustained dual-market access capabilities. Bio-Rad represents the detection chemistry specialization vector with proprietary multiplexing capabilities. BD anchors the integrated workflow archetype through reagent-hardware bundling strategies. These three entities collectively illustrate how scale, chemistry expertise, and platform integration define competitive positioning in antibody isotyping reagent supply.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad |
| BD |
| Abbott |
| Roche |
| Danaher |
| BioMérieux |
| Ortho Clinical Diagnostics |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between IVDR-validated clinical reagents and research-use-only consumables manifests in both pricing power and supplier qualification requirements. Pharmaceutical quality control laboratories in Massachusetts and California pay substantial premiums for GMP-traceable IgG subclass discrimination reagents, while academic consortia in the Research Triangle negotiate spot pricing on ELISA formats with minimal documentation.
Pricing Analysis
Cost-down pressure on research-grade ELISA formats accelerates because lateral flow alternatives commoditize routine diagnostic applications. Three-tier pricing structure across premium, standard, and economy levels separates flow cytometry bundles with cytometry hardware integration from standalone plate-based assays and unvalidated research reagents. IVDR Class C designation requirements elevate clinical-grade pricing by mandating performance study investments that smaller suppliers cannot absorb. Research laboratories exhibit the highest price sensitivity through bulk purchasing consortia, whereas pharmaceutical procurement teams prioritize regulatory traceability over per-test economy.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical quality control laboratories mandate qualified secondary antibody suppliers in both the United States and Germany. Serum fractionation capacity concentrates among specialized processors in the United States, Germany, and the Netherlands, with subclass-specific secondary antibody conjugation tethered to seasonal serum availability. Single-source vulnerability in polyclonal antibody production exposes kit manufacturers to raw material lead time volatility. Distribution runs through CLIA-certified manufacturing networks for clinical-grade reagents and direct-to-laboratory channels for research-use-only products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where IVDR Class C designation creates a structural barrier-to-entry moat for manufacturers with validated European manufacturing footprints.
For Market Incumbents: Hedge against lateral flow commoditization by deepening proprietary multiplexing chemistry positions that compress assay timelines for high-throughput laboratories. Secure backward integration into recombinant antibody production to reduce dependency on concentrated serum fractionators. Prioritize dual FDA-IVDR manufacturing certification to maintain access across fragmented regulatory pathways. For New Entrants and Emerging Players: Digital distribution channels through contract research organization procurement platforms offer lower customer acquisition costs than direct pharmaceutical sales forces. White-space opportunity concentrates in outsourced biologics characterization services in India and China, where CDSCO and NMPA pathways remain underpenetrated by validated Western suppliers. Target research-grade consumable supply agreements with guaranteed volume commitments from academic consortia. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier reagent specialists possessing IVDR technical documentation capabilities given the regulatory exclusion of smaller competitors. Long-term viability favors manufacturers with CLIA-certified production networks spanning multiple regulatory jurisdictions. Watch for IVDR enforcement acceleration as the signal indicating consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Class C Certification Investment | Elevated clinical evidence mandates exclude smaller reagent suppliers from European diagnostic supply chains. |
| Multiplexing Chemistry Development | Proprietary simultaneous IgG/IgM/IgA detection reduces assay time for immuno-oncology pipeline laboratories. |
| Cytometry Hardware Bundling | Instrument manufacturer partnerships lock in reagent procurement decisions through workflow integration. |
| Contract Research Organization Channel | Bulk supply agreements with guaranteed volume commitments penetrate outsourced biologics characterization services. |
| Dual-Pathway Regulatory Manufacturing | CLIA-certified networks sustaining FDA and IVDR access reduce go-to-market timing fragmentation. |
Study Parameters
Document review covered FDA 21 CFR Part 820 quality system regulations, EU IVDR technical documentation requirements, and ISO 13485 certification standards, complemented by interviews with kit manufacturing quality directors, pharmaceutical regulatory affairs leads, diagnostic laboratory procurement managers, and academic immunology principal investigators. Secondary validation drew from FDA guidance documents, EMA implementing acts, NIH funding databases, and clinical trial registry entries. Bottom-up segmentation modeling triangulated against top-down market sizing from reagent manufacturer revenue disclosures.
Output modeling produced volume and value estimates across detection platform, immunoglobulin subclass, end-user archetype, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from regression analysis against biologics pipeline expansion rates and IVDR compliance transition timelines. Forecast inputs incorporated hybridoma screening intensity indices and flow cytometry instrument placement data from clinical trial laboratory networks.
The model holds under stable IVDR enforcement and continued NIH immunology funding; deviation in biosimilar immunogenicity guidance stringency or secondary antibody supply disruption would shift trajectory. A model refresh is warranted upon material change in FDA-EMA regulatory harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Cell Cycle Analysis Market