
 Global Serological Transplant Diagnostics Market | 2026-2036
Global Serological Transplant Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Serological Transplant Diagnostics Market Intelligence
Stricter hospital protocols on managing biohazardous waste is hardening demand for assays with smaller reagent volumes and streamlined disposal pathways. This shift favors vendors with efficient kit designs. Thermo Fisher Scientific specializes in pre-transplant antibody screening solutions that align with this efficiency trend. Bio-Rad Laboratories leverages its extensive portfolio in immunoassays to serve diverse laboratory needs. Immucor sustains its market position through deep relationships with blood banks and large transplant centers, providing integrated testing platforms.
Serological transplant diagnostics encompass techniques that utilize antibody-antigen reactions to determine immunological compatibility between donors and recipients. These methods primarily detect the presence of pre-formed anti-HLA antibodies, which can cause hyperacute rejection. The primary purpose is to minimize the risk of organ rejection and improve post-transplant patient outcomes. Enzyme-Linked Immunosorbent Assay (ELISA) products form the backbone of routine screening, while flow cytometry applications provide higher sensitivity for complex antibody identification. Organ compatibility testing and antibody screening are the principal applications driving test volumes in transplant centers.
Regulatory oversight from bodies like the US Food and Drug Administration (FDA) and adherence to CE marking under Europe's Medical Device Regulation (MDR) are critical for market access. These frameworks, along with standards from Japan's PMDA, impose strict validation requirements on assay performance and manufacturing quality. This ensures the reliability of tests used in life-critical decisions. The strategic decision for laboratories now centers on balancing the cost-effectiveness of established serological methods against the precision of emerging molecular diagnostics.
Market Dynamics
The central dynamic in serological transplant diagnostics is the strategic tension between established, cost-effective methods and the superior precision of emerging molecular technologies. Laboratories must balance the routine utility of serological screening against the diagnostic power of newer platforms.
Growth Catalysts
- High-Sensitivity Assays:The development of high-sensitivity chemiluminescence immunoassays is improving detection accuracy for anti-HLA antibodies, leading transplant centers to increase testing volumes for better organ compatibility matching.
- Increasing Transplant Procedures:A rising number of organ transplant procedures, particularly in the United States and parts of Europe, directly expands the required volume of pre-transplant compatibility testing.
- Favorable Reimbursement Frameworks:Established reimbursement policies for organ compatibility testing in countries like the United States and Germany provide financial stability for laboratories, encouraging investment in advanced diagnostic platforms.
Market Restraints
- Competition from Molecular Diagnostics:The precision of molecular techniques like Next-Generation Sequencing (NGS) for HLA typing presents a significant substitution threat, challenging the market position of traditional serological methods.
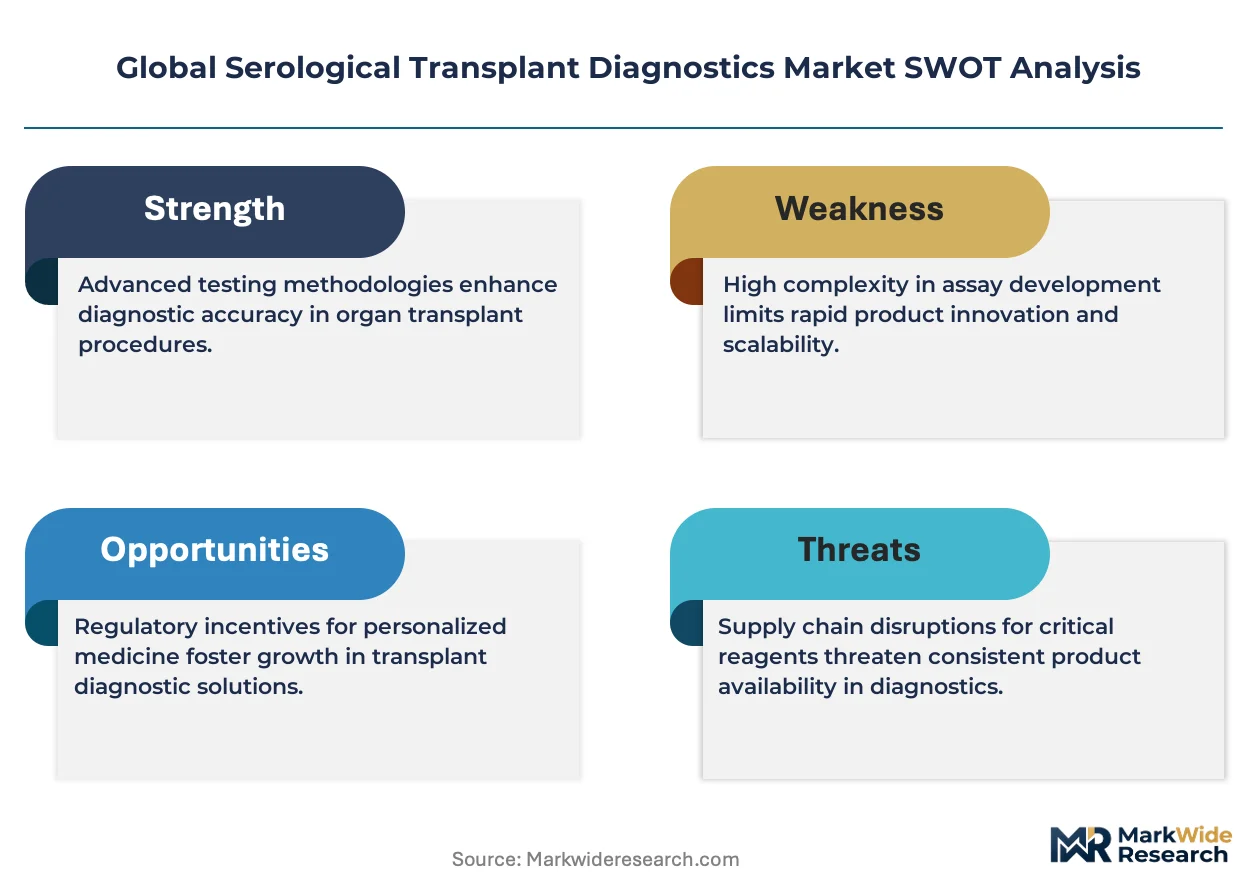
- Stringent Validation Requirements:Gaining market access requires adherence to strict validation protocols from regulatory bodies like the US FDA and compliance with Europe's MDR, increasing development time and costs.
- High Cost of Advanced Platforms:The capital expenditure for advanced platforms, such as those used for flow cytometry and chemiluminescence, can be prohibitive for smaller laboratories or those in regions with limited healthcare budgets.
Strategic Opportunities
- Expansion in Emerging Markets:Growing healthcare infrastructure in markets like Brazil and India creates opportunities for introducing standardized serological screening programs where they are currently limited or nonexistent.
- Integration with Laboratory Information Systems:Developing assays that seamlessly integrate with hospital LIS and electronic health records offers a significant opportunity to improve workflow efficiency and data management for transplant centers.
- Post-Transplant Monitoring:There is a growing opportunity to position serological assays for routine post-transplant monitoring of de novo donor-specific antibodies to predict and manage chronic rejection.
Industry Challenges
- Shortage of Specialized Technicians:A scarcity of laboratory personnel skilled in interpreting complex antibody profiles from flow cytometry and single antigen bead assays creates an operational bottleneck for many transplant centers.
- Lack of Inter-Laboratory Standardization:Variability in testing protocols and result interpretation across different laboratories complicates patient data comparison and can impact clinical decision-making, posing a challenge to creating universal standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Serological Transplant Diagnostics Market |
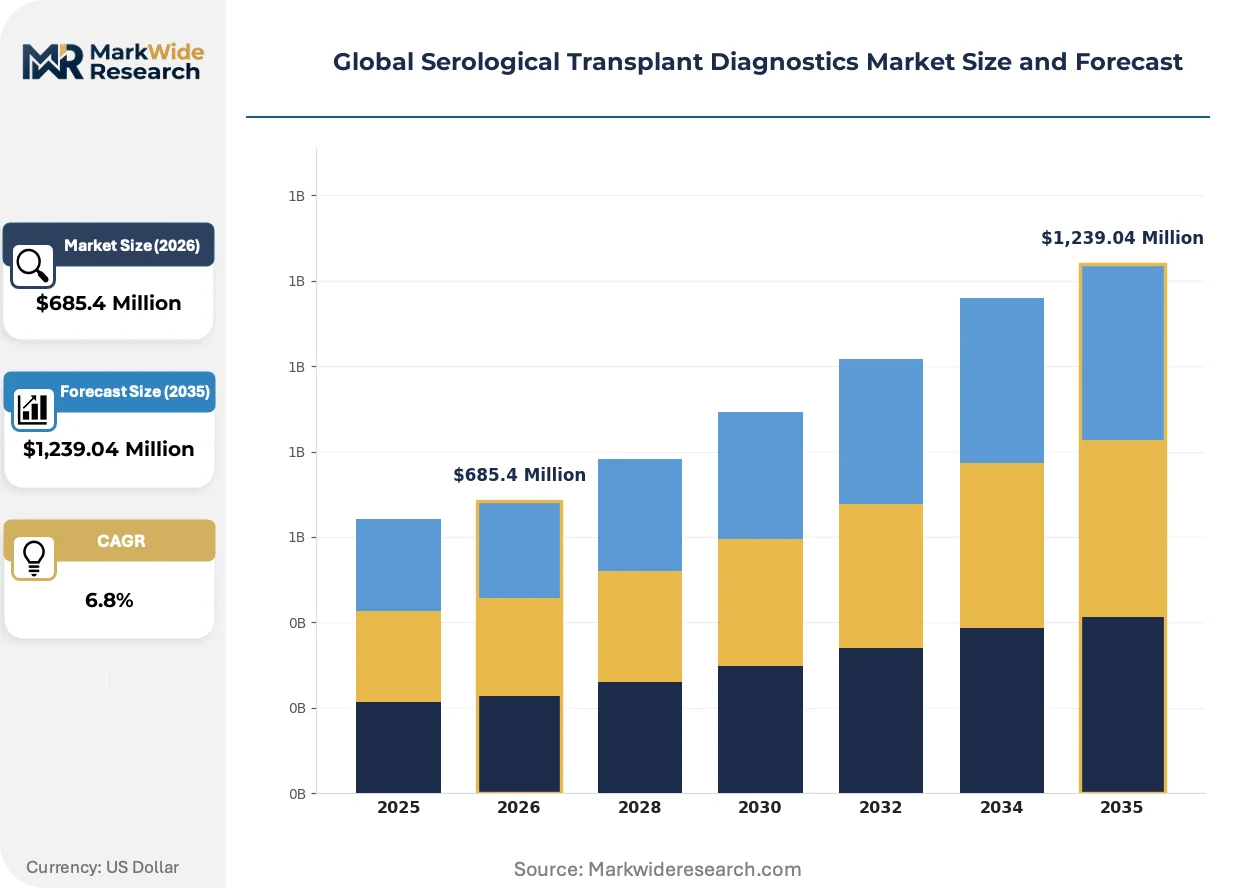
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme-Linked Immunosorbent Assay, Flow Cytometry, Immunofluorescence Assay, Western Blot, Chemiluminescence Immunoassay Application: Organ Compatibility Testing, Antibody Screening, Crossmatching, Infection Monitoring, Rejection Detection End User: Clinical Laboratories, Diagnostic Centers, Research Institutes, Transplant Centers, Blood Banks Deployment: Hospital-Based, Standalone Diagnostic Labs, Point-of-Care Facilities, Reference Laboratories |
| Companies Covered | Bio-Rad Laboratories, Immucor, Siemens Healthineers, Ortho Clinical Diagnostics, Thermo Fisher Scientific, Agena Bioscience, BAG Healthcare, BD, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Serological Transplant Diagnostics Market Strategic Shifts & Innovations
The evolution of serological diagnostics is driven by a dual focus on improving assay sensitivity and streamlining laboratory workflows. This push affects everything from kit design and regulatory compliance to how transplant centers manage patient data for critical matching decisions.
Chemiluminescence immunoassay (CLIA) technology provides a high-throughput, automated method for detecting anti-HLA antibodies with enhanced sensitivity over traditional ELISA. Large transplant centers and reference laboratories are adopting CLIA platforms to manage high testing volumes. The technology's ability to deliver faster, more precise results is rewriting the standards for pre-transplant risk assessment.
Europe’s Medical Device Regulation (MDR) imposes more rigorous clinical evidence and post-market surveillance requirements for in-vitro diagnostic devices. This regulation increases the burden of proof for manufacturers to demonstrate assay safety and performance throughout the product lifecycle. Serological test kits are most affected, forcing vendors to invest heavily in updated technical documentation and quality management systems to maintain CE marking.
Transplant centers are increasingly prioritizing assays with smaller reagent volumes and simplified disposal pathways to comply with stricter hospital protocols on biohazardous waste. This demand for workflow efficiency is displacing older, more manual testing kits in favor of integrated, automated platforms. This shift is most visible in high-volume laboratories in the United States and Western Europe, where operational efficiency and cost-containment are paramount.
Global Serological Transplant Diagnostics Market Segmentation
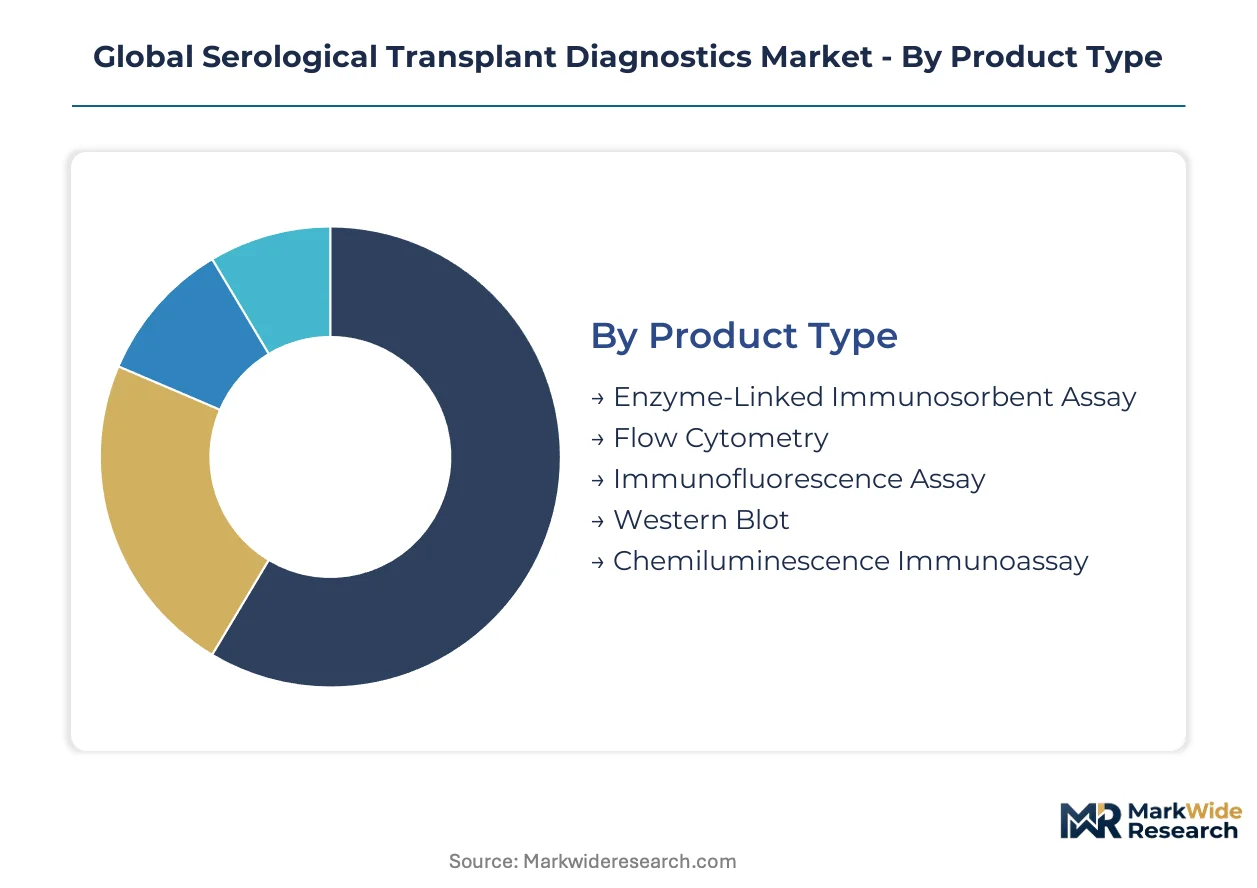
Understanding the Global Serological Transplant Diagnostics Market requires a granular view of its constituent parts, reflecting diverse technological approaches and end-user requirements. Segmentation reveals how different product types and applications cater to distinct clinical needs in organ transplantation. This detailed breakdown highlights areas of innovation and established practice across the diagnostic landscape.
Product Type:
The market for serological transplant diagnostics sees continuous evolution in instrument and reagent replacement cycles.
- Chemiluminescence Immunoassay:CLIA technology employs chemiluminescent reactions to detect anti-HLA antibodies with high sensitivity and a broad dynamic range. Demand concentrates in large transplant centers in the United States, driven by the need for high-throughput, automated screening with enhanced precision.
- Flow Cytometry:This method uses fluorescently labeled antibodies and laser detection to identify and quantify specific cell populations or antibody-coated beads. Transplant centers in Germany are increasingly adopting flow cytometry for complex antibody identification, offering superior resolution for patient risk assessment.
- Enzyme-Linked Immunosorbent Assay:ELISA remains a foundational technique for routine antibody screening, widely used in clinical laboratories due to its cost-effectiveness.
- Immunofluorescence Assay:IFA detects antibodies by labeling them with fluorescent dyes, providing visual identification of antibody-antigen reactions in many diagnostic centers.
- Western Blot:This technique separates proteins by size and identifies specific antibodies, often employed for confirmatory testing in research institutes.
Volume placements concentrate in Enzyme-Linked Immunosorbent Assay; the faster expansion belongs to Chemiluminescence Immunoassay.
Application:
The specific clinical use cases for serological diagnostics define varying technical requirements and adoption patterns across laboratories.
- Organ Compatibility Testing:This application assesses immunological compatibility between organ donors and recipients to minimize rejection risk. Demand in European transplant centers is high, driven by increasing transplant volumes and the critical need for precise HLA matching.
- Antibody Screening:This involves detecting pre-formed anti-HLA antibodies in recipient serum, a crucial step before transplantation. Clinical laboratories across Japan prioritize comprehensive antibody screening to identify potential rejection risks early.
- Crossmatching:Crossmatching directly tests recipient serum against donor lymphocytes to predict immediate rejection, a critical pre-transplant procedure.
- Infection Monitoring:Serological tests monitor for post-transplant infections, identifying pathogens that compromise graft survival and patient health.
- Rejection Detection:These assays help identify early signs of organ rejection by detecting specific antibodies or inflammatory markers after transplantation.
Organ Compatibility Testing generates significant test volumes; Antibody Screening is demonstrating considerable growth.
End User:
Different end-user segments exhibit distinct procurement patterns and technical requirements for serological transplant diagnostics.
- Transplant Centers:These specialized medical facilities perform organ transplant procedures and require advanced, high-sensitivity diagnostic platforms. Demand in the United States for integrated testing solutions is substantial, driven by high procedure volumes and stringent compatibility requirements.
- Clinical Laboratories:These laboratories conduct routine and specialized tests, serving a broad range of healthcare providers. Cost-effectiveness and high-throughput capabilities drive procurement in clinical laboratories across India, supporting widespread initial screening efforts.
- Diagnostic Centers:Independent diagnostic centers offer specialized testing services, often complementing hospital-based laboratories with advanced serological assays.
- Research Institutes:These entities utilize serological diagnostics for studies on immunology, transplant rejection mechanisms, and novel biomarker discovery.
- Blood Banks:Blood banks use serological methods for HLA typing and antibody screening of blood products and potential donors.
Transplant Centers represent a high-value customer base; Clinical Laboratories are expanding their serological testing capabilities.
Deployment:
The operational setup of diagnostic facilities influences technology adoption and the scale of serological testing.
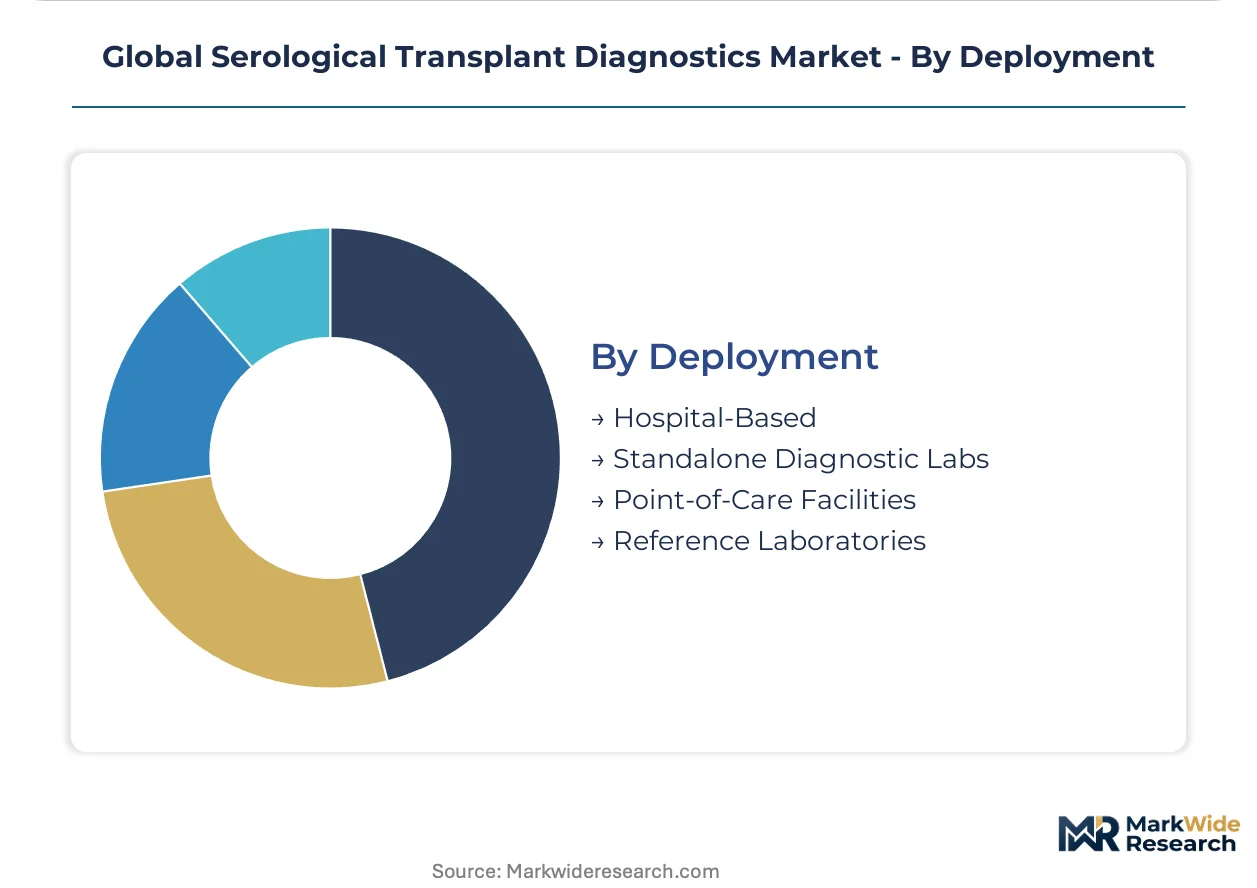
- Hospital-Based:These facilities integrate diagnostic services directly within hospitals, providing rapid turnaround for critical pre-transplant decisions. Hospitals in the United Kingdom prioritize integrated systems for seamless patient data management and immediate clinical action.
- Reference Laboratories:These specialized laboratories handle complex or high-volume testing, often serving multiple hospitals and clinics. Reference laboratories in Canada focus on advanced molecular and serological assays, providing expert interpretation for challenging cases.
- Standalone Diagnostic Labs:Independent laboratories offer a range of diagnostic tests, catering to outpatient needs and specialized serological screening.
- Point-of-Care Facilities:POC settings provide rapid testing closer to the patient, though serological transplant diagnostics are less common here due to complexity.
Hospital-Based deployment remains foundational; Reference Laboratories are advancing specialized testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global serological transplant diagnostics market exhibits a clear divide between established demand centers and emerging regions where testing capabilities are expanding. Advanced healthcare infrastructures in developed nations drive significant test volumes, while developing economies focus on building foundational screening programs.
United States
High transplant procedure volumes and established reimbursement frameworks drive substantial demand for serological transplant diagnostics in the United States. The US Food and Drug Administration (FDA) imposes strict validation requirements for assay performance, ensuring test reliability. Major transplant centers in New York and California are increasing their adoption of high-sensitivity chemiluminescence immunoassays for pre-transplant risk assessment.
Germany
European transplant centers, particularly in Germany, show high demand for organ compatibility testing due to increasing transplant volumes. Compliance with Europe's Medical Device Regulation (MDR) is critical for market access, impacting manufacturers' product development. Laboratories in cities like Berlin and Munich are increasingly adopting flow cytometry for complex antibody identification, enhancing patient risk assessment.
Japan
Clinical laboratories across Japan prioritize comprehensive antibody screening to identify potential rejection risks early in transplant recipients. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures stringent quality and performance standards for diagnostic assays. Tokyo's major medical institutions focus on integrating advanced serological methods to improve post-transplant patient outcomes.
India
Clinical laboratories across India are expanding their serological testing capabilities, driven by the need for cost-effective, high-throughput screening solutions. The Central Drugs Standard Control Organization (CDSCO) regulates diagnostic device approvals, promoting standardized testing. Cities like Mumbai and Bangalore are witnessing increased investment in diagnostic infrastructure to support growing healthcare needs.
Global Serological Transplant Diagnostics Market Key Industry Players
The competitive structure tilts toward established diagnostic providers with broad portfolios and specialized companies focusing on specific transplant testing needs. These players aim to offer integrated solutions that address both high-volume screening and complex antibody identification. Companies often engage in strategic partnerships to expand their market reach and invest in advanced platform development to improve assay sensitivity.
Specialists in pre-transplant antibody screening, like Thermo Fisher Scientific, exemplify a focus on efficiency trends with smaller reagent volumes. Bio-Rad Laboratories sits within the segment of companies leveraging extensive immunoassay portfolios to serve diverse laboratory needs. Immucor anchors its market position through deep relationships with blood banks and large transplant centers, providing integrated testing platforms for critical compatibility decisions.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Immucor |
| Siemens Healthineers |
| Ortho Clinical Diagnostics |
| Thermo Fisher Scientific |
| Agena Bioscience |
| BAG Healthcare |
| BD |
| Beckman Coulter |
| Others |
Cost & Logistics Intelligence
Reagent chemical purity, a critical upstream input, significantly influences the final assay performance and cascades through pricing tiers for diagnostic kits. This cost component directly affects the profitability of manufacturers and the procurement strategies of transplant centers.
Pricing Analysis
Assay throughput and detection accuracy serve as the primary value-based pricing anchors for serological transplant diagnostics. The dominant pricing structure is a hybrid model combining per-unit transactional sales for reagents with tiered subscription or lease agreements for automated platforms. Price differentiation stems from assay sensitivity, such as high-performance CLIA kits, and the level of post-sales technical support offered by vendors. Pricing pressure arises from the increasing competition from molecular diagnostic alternatives, pushing serological test costs downwards. Clinical laboratories in emerging markets exhibit the highest price sensitivity, while specialized transplant centers prioritize performance over cost.
Supply Chain Analysis
The reverse logistics of biohazardous waste disposal for spent reagents and kits imposes significant costs and regulatory compliance burdens on transplant centers. Geographic supply concentration for key raw materials like specialized antibodies and detection chemicals primarily resides in Germany, the United States, and Japan. The industry's supply chain draws from a limited number of highly specialized chemical manufacturers. Single-source vulnerability for niche reagents represents a structural risk, potentially disrupting global supply. Downstream, distribution runs through a network of specialized medical device distributors and direct sales channels to large hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global serological transplant diagnostics market is fundamentally a vertical-integration race, with manufacturers pursuing upstream control over critical reagent production to secure supply and enhance proprietary technology.
For Market Incumbents:Deepen R&D investment into next-generation serological assays that offer enhanced sensitivity and multiplexing capabilities. Consolidate market share through strategic acquisitions of smaller, innovative diagnostic firms specializing in novel antibody detection platforms. This counters the precision threat posed by emerging molecular diagnostics. Reinforce relationships with large transplant centers by offering integrated workflow solutions that include LIS integration and comprehensive training programs.
For New Entrants and Emerging Players:Specialized diagnostic distributors represent the most effective channel for market penetration, leveraging their existing relationships with clinical laboratories. Target underpenetrated clinical laboratories in emerging markets like India and Brazil, which prioritize cost-effective screening solutions. Focus on developing user-friendly, semi-automated systems that simplify complex antibody identification. A compelling go-to-market angle involves offering robust, standardized ELISA kits at competitive price points, bundled with localized technical support.
For Investors and Strategic Acquirers:Regulatory approval for a novel, high-sensitivity serological assay is the leading indicator that signals a significant shift in competitive advantage. The long-term viability of this market hinges on the continued need for cost-effective, high-throughput screening methods, even as molecular diagnostics advance. Acquisition targets should be mid-sized firms with proprietary chemiluminescence or flow cytometry technologies and strong intellectual property portfolios. Investors should monitor shifts in reimbursement policies for serological vs. molecular tests for early signals of market disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop next-generation CLIA platforms | Enhances detection accuracy and throughput for anti-HLA antibodies, meeting demand from large transplant centers. |
| Invest in assay workflow automation | Streamlines laboratory operations and reduces manual errors, addressing labor shortage challenges in diagnostics. |
| Expand into post-transplant monitoring | Creates new revenue streams by addressing the growing need for de novo donor-specific antibody detection. |
| Secure critical reagent supply agreements | Mitigates supply chain risks and ensures consistent production of high-quality diagnostic kits. |
| Integrate with hospital LIS systems | Improves data management and clinical decision-making within transplant centers, boosting product utility. |
Research Approach
Independent corroboration across industry white papers, scientific publications, and regulatory agency reports underwrites the qualitative findings of this study. Primary interviews with transplant center directors, clinical laboratory managers, and diagnostic product specialists provided critical insights into market dynamics. Secondary data from medical device databases, healthcare expenditure reports, and company financial statements further validated market trends. This approach leveraged both bottom-up and top-down triangulation to ensure comprehensive data coverage.
The analytical framework anchored the forecast window to historical performance and current market conditions over the projection horizon. Segmentation dimensions modeled included product type, application, end-user, and deployment, alongside an industry-specific dimension of HLA antibody specificity. Compound Annual Growth Rates (CAGRs) were derived using a weighted average approach, integrating market size projections with anticipated technology adoption rates. Key industry-specific forecast inputs included organ transplant procedure volumes and regulatory approval timelines for new diagnostic platforms.
Several conditions sit outside the modeled scope, including unforeseen global pandemics or drastic shifts in healthcare funding structures. Forecasts reflect assumptions documented through extensive primary and secondary research, but are subject to change. Practitioners should monitor regulatory changes in medical device approval and the pace of molecular diagnostic innovation for early signals of market reorientation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Exosomes Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
BOD Incubator Market
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Lipid Transfer Proteins Market