
 Ubiquitin Proteasome Market | 2026-2036
Ubiquitin Proteasome Market Size, Share, and Industry Trends Forecast 2026-2036
Ubiquitin Proteasome Market Analysis
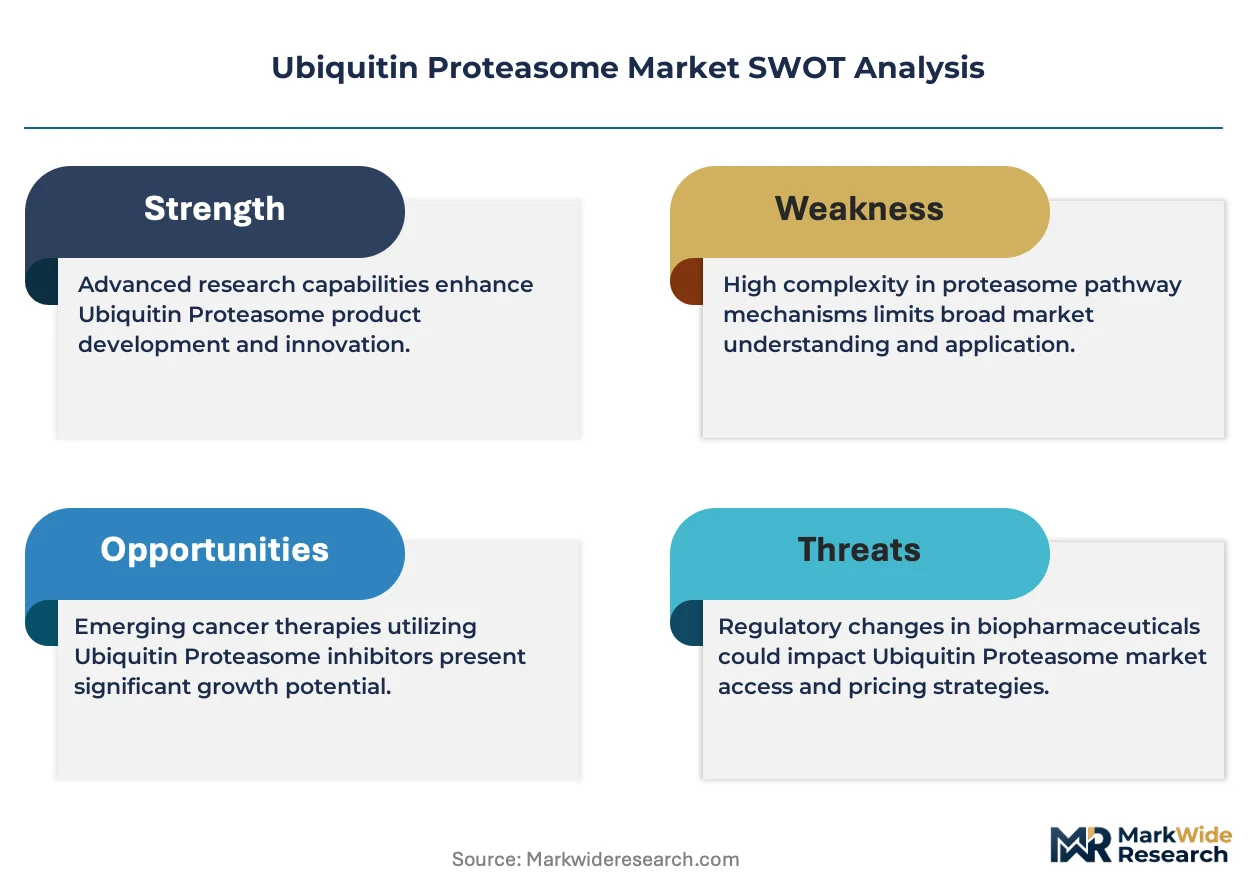
ISO 15189 certification for clinical laboratory quality management is rotating competitive advantage toward vendors with validated assay platforms. Promega Corporation leverages its integrated reagent-instrument ecosystem to sustain recurring revenue in proteasome research workflows. Johnson & Johnson anchors therapeutic development through its Janssen unit's proteasome inhibitor portfolio. Merck KGaA differentiates via mass spectrometry-grade substrate libraries that control access to high-precision quantification.
The ubiquitin proteasome system comprises a conserved enzymatic cascade—E1 activating enzymes, E2 conjugating enzymes, and E3 ligases—that tags substrate proteins with polyubiquitin chains for 26S proteasomal degradation, operating at physiological temperature and ATP-dependent kinetics. This machinery serves as the primary intracellular protein quality control mechanism, with pharmacological modulation enabling targeted elimination of disease-driving proteins previously considered undruggable. Inhibitors command the largest value pool given their direct therapeutic application in multiple myeloma and expanding solid tumor indications, while mass spectrometry technology captures the fastest growth trajectory as proteomics-driven drug discovery shifts from candidate identification to mechanism validation. Assays segment margins concentrate in multiplexed high-throughput formats serving contract research organizations managing sponsor pipelines.
FDA's Breakthrough Therapy designation framework and EMA's PRIME scheme jointly compress development timelines for proteolysis-targeting chimeras, forcing sponsors to front-load manufacturing scale-up and biomarker validation. The EPA's Good Laboratory Practice enforcement and OECD Test Guideline harmonization shape preclinical study acceptability across jurisdictions, directly influencing CRO procurement criteria. Stakeholders must monitor emerging FDA guidance on targeted protein degradation chemistry manufacturing controls, as regulatory clarity will determine which platform technologies achieve commercial validation first.
Market Dynamics
FDA's Breakthrough Therapy designation and EMA's PRIME scheme are compressing development timelines for proteolysis-targeting chimeras, forcing sponsors to front-load manufacturing scale-up and biomarker validation before Phase II data matures.
Growth Catalysts
- Accelerated approval pathways:FDA Breakthrough Therapy and EMA PRIME designations truncate clinical development timelines for targeted protein degradation therapies, pulling forward revenue recognition for sponsors.
- Oncology pipeline expansion:Multiple myeloma and solid tumor indications are driving proteasome inhibitor program scaling across pharmaceutical R&D budgets.
- Mass spectrometry infrastructure:Proteomics-driven drug discovery is shifting from candidate identification to mechanism validation, amplifying demand for high-precision quantification platforms.
Market Restraints
- ATP-dependent kinetics complexity:The ubiquitin proteasome system's physiological temperature and energy requirements create formulation stability challenges for in vitro assay standardization.
- Reagent supply concentration:Validated substrate libraries for mass spectrometry-grade quantification remain controlled by limited specialized vendors, creating procurement bottlenecks.
- GLP study harmonization friction:EPA Good Laboratory Practice enforcement and OECD Test Guideline variations across jurisdictions force redundant preclinical study execution.
Strategic Opportunities
- ISO 15189-certified assay platforms:Clinical laboratory quality management certification is rotating competitive advantage toward vendors with validated integrated reagent-instrument ecosystems.
- Contract research organization channel expansion:Multiplexed high-throughput assay formats are capturing margin concentration from sponsor pipeline management outsourcing.
- Chemistry manufacturing controls guidance:Emerging FDA clarity on targeted protein degradation CMC requirements will determine which platform technologies achieve first-mover commercial validation.
Industry Challenges
- E3 ligase biology expertise scarcity:The enzymatic cascade complexity of E1 activating enzymes, E2 conjugating enzymes, and E3 ligases requires specialized protein biochemistry talent pools that outstrip current training pipeline output.
- Biomarker validation capex intensity:Front-loaded investment in patient stratification assays ahead of Phase II readouts strains venture-funded biotech balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ubiquitin Proteasome Market |
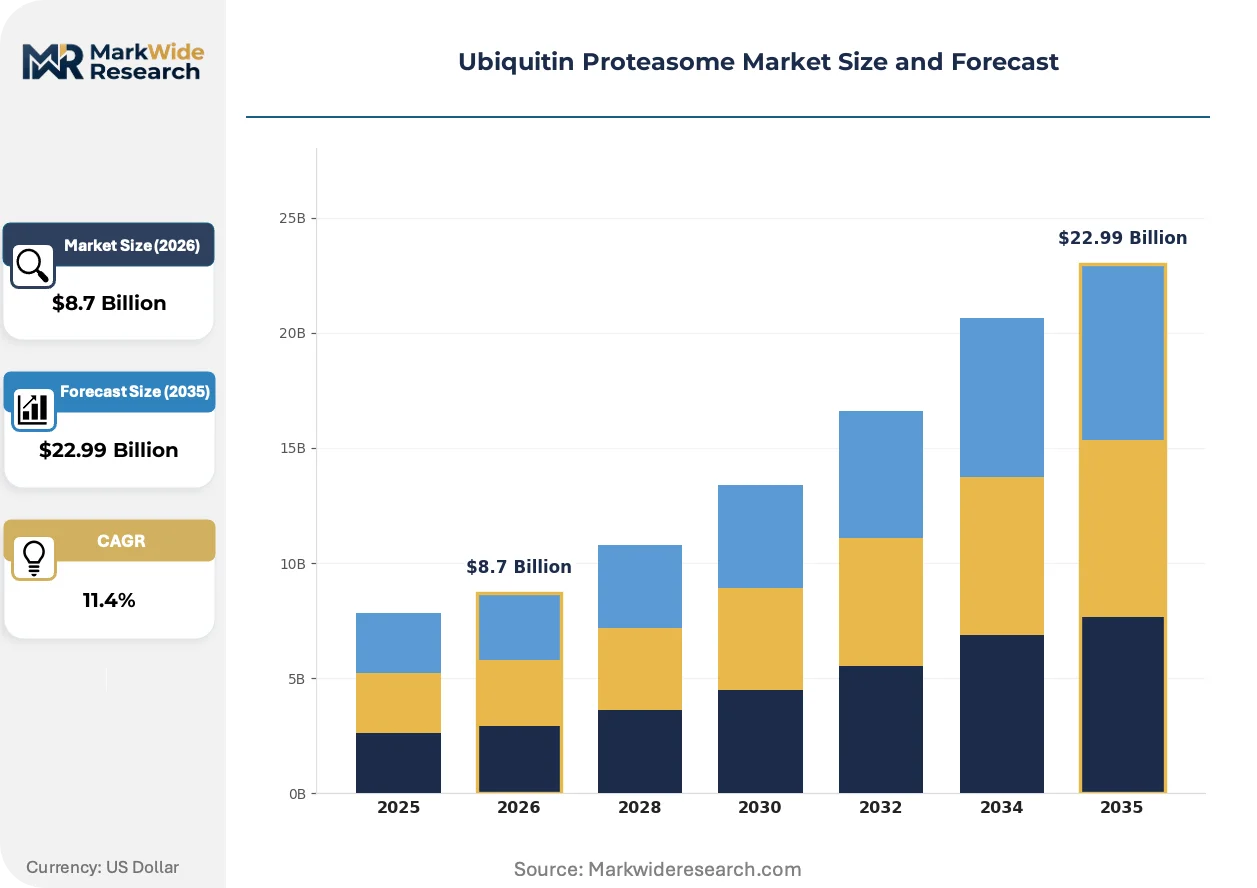
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhibitors, Substrates, Probes, Assays Technology: Mass Spectrometry, Western Blotting, ELISA, Flow Cytometry End User: Pharmaceutical Companies, Research Institutions, Academic Labs, Contract Research Organizations Application: Cancer Research, Neurodegenerative Disorders, Cardiovascular Diseases, Infectious Diseases |
| Companies Covered | Promega Corporation, Johnson & Johnson, Merck KGaA, Amgen, AstraZeneca, Takeda Pharmaceuticals, Tocris Bioscience, Arvinas, BioVision Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ubiquitin Proteasome Market Emerging Trajectories
Targeted protein degradation is fundamentally altering druggability assumptions, expanding the addressable target space beyond conventional binding pockets toward previously inaccessible disease-driving proteins.
Proteolysis-targeting chimeras are displacing traditional small-molecule inhibition strategies in oncology discovery programs. Large pharmaceutical sponsors are redirecting internal chemistry resources toward bifunctional degrader design. This modality shift is compressing the timeline from target validation to clinical candidate nomination.
EMA's PRIME scheme and FDA's Breakthrough Therapy designation are creating synchronized regulatory competition between European and American development tracks. Sponsors are now filing parallel qualification packages to capture priority review benefits in both jurisdictions. The proteasome inhibitor segment is responding by establishing transatlantic manufacturing redundancy earlier in development cycles.
Biotech venture funding concentration in the United States is reshaping CRO procurement geography. Sponsors are consolidating contract research relationships with providers maintaining specialized proteasome assay infrastructure in Boston and San Diego clusters. This geographic demand rotation is marginalizing European CROs lacking validated 26S proteasomal degradation kinetic platforms.
Ubiquitin Proteasome Market Segmentation
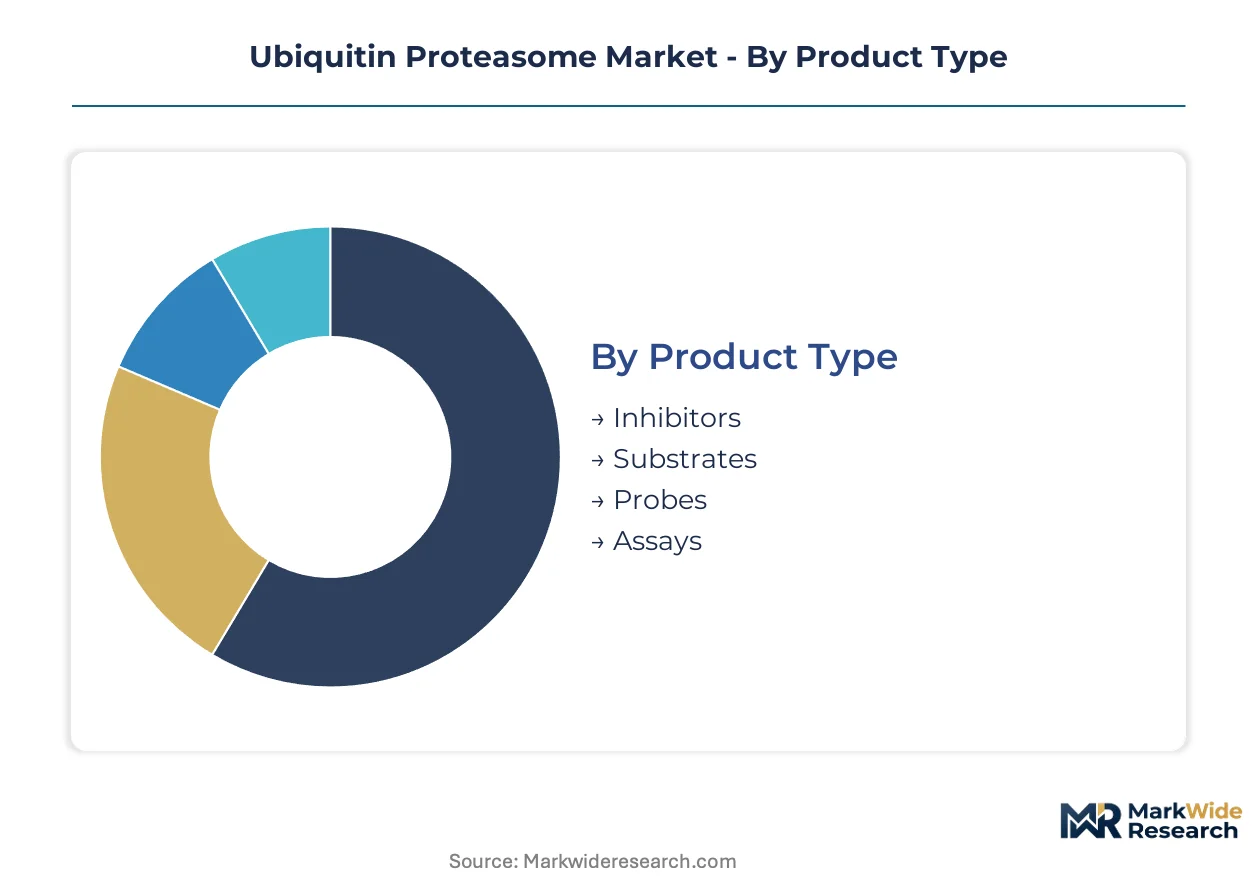
Ubiquitin proteasome market segmentation reveals distinct procurement patterns between domestic R&D operations and export-oriented therapeutic manufacturing. Technology choices and end-user concentration vary sharply across geographic clusters.
Product Type:
Domestic consumption concentrates in assay formats and research-grade inhibitors, while export demand flows toward GMP-certified substrates and clinical-grade probes.
- Inhibitors:Small-molecule compounds modulating 26S proteasome activity through reversible or irreversible binding mechanisms. Multiple myeloma therapeutic protocols in the United States and Japan absorb the majority of clinical-grade volumes. FDA Breakthrough Therapy designations for next-generation candidates are compressing sponsor procurement cycles.
- Assays:Multiplexed high-throughput formats enabling kinetic profiling of E1-E2-E3 enzymatic cascades. Contract research organizations in Boston and San Diego clusters specify ISO 15189-certified platforms for sponsor pipeline management. Margin concentration follows validation documentation rigor.
- Substrates:Mass spectrometry-grade peptide libraries for ubiquitin chain topology analysis.
- Probes:Fluorescent and affinity-tagged reagents for live-cell degradation imaging.
Inhibitors hold the largest share; momentum sits with assays.
Technology:
Cost tier stratification separates capital-intensive mass spectrometry installations from consumable-heavy immunoassay workflows.
- Mass Spectrometry:High-resolution platforms quantifying ubiquitin chain linkages and post-translational modifications with sub-femtomole sensitivity. Proteomics-driven drug discovery shifting from candidate identification to mechanism validation is amplifying demand in German and Swiss pharmaceutical clusters. Equipment procurement concentrates among top-20 global sponsors.
- ELISA:Plate-based immunoassay formats for ubiquitinated protein detection in crude lysates. Academic labs across India and South Korea prioritize cost-per-sample efficiency over absolute quantification precision. Reagent recurring revenue sustains vendor margin stability.
- Western Blotting:Electrophoretic separation with antibody detection for ubiquitin chain visualization.
- Flow Cytometry:Single-cell resolution of proteasome activity reporters in heterogeneous populations.
Mass spectrometry commands premium pricing; ELISA volumes are climbing fastest.
End User:
Customer type determines specification stringency, with pharmaceutical sponsors demanding GMP documentation that academic procurement bypasses.
- Pharmaceutical Companies:Integrated R&D and manufacturing operations requiring scalable reagent supply with chemistry manufacturing controls documentation. Janssen and Merck KGaA anchor therapeutic development through internal proteasome inhibitor portfolios and substrate library control. Vendor qualification audits extend 12-18 months.
- Contract Research Organizations:Specialized infrastructure providers managing sponsor pipeline execution with validated assay platforms. CROs in the United States concentrate proteasome assay expertise in Boston and San Diego, marginalizing European competitors lacking 26S kinetic platform validation. Multiplexed formats capture margin from high-throughput screening contracts.
- Research Institutions:Government-funded centers pursuing basic ubiquitin biology without therapeutic development timelines.
- Academic Labs:Principal investigator-led groups prioritizing publication-grade data on constrained budgets.
Pharmaceutical companies dominate value capture; contract research organizations are expanding most quickly.
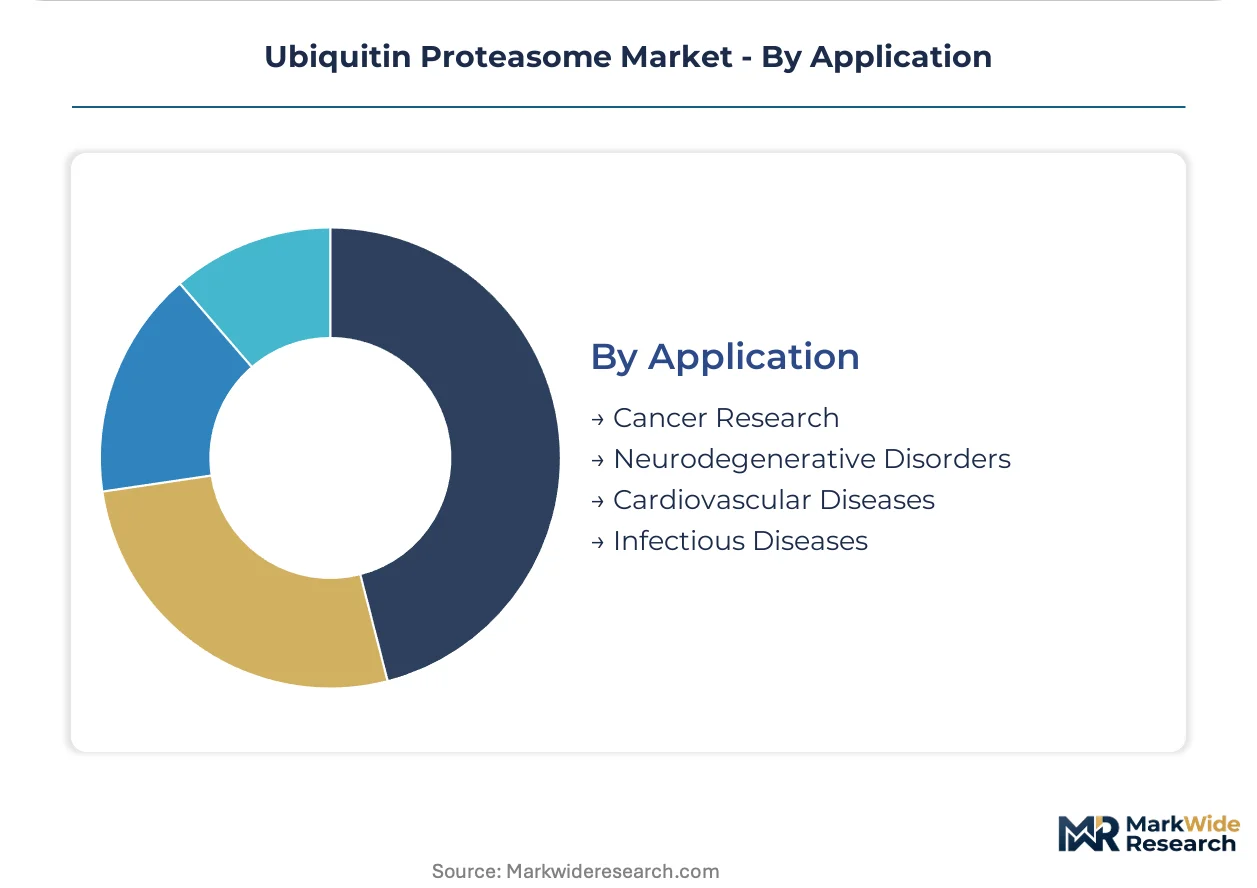
Application:
Maturity gradients separate established oncology protocols from emerging neurodegenerative programs still in target validation phases.
- Cancer Research:Proteasome inhibitor therapeutic development and resistance mechanism studies in multiple myeloma and solid tumor indications. FDA accelerated approval pathways and EMA PRIME schemes compress development timelines, forcing front-loaded biomarker validation investment. Clinical trial density concentrates in the United States.
- Neurodegenerative Disorders:Targeted protein degradation approaches for tau, alpha-synuclein, and huntingtin aggregate clearance. Biotech venture funding in Cambridge, Massachusetts and Basel, Switzerland supports platform technology bets on previously undruggable CNS targets. E3 ligase brain penetration remains unresolved.
- Cardiovascular Diseases:Proteasome modulation in ischemia-reperfusion injury and hypertrophic signaling.
- Infectious Diseases:Pathogen ubiquitin ligase exploitation and host-pathogen degradation interface targeting.
Cancer research anchors current revenue; neurodegenerative disorders show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Diego-Boston biotech corridor anchors North American proteasome research infrastructure, while Basel and Cambridge pharmaceutical clusters drive European therapeutic development. Cross-border venture capital flows concentrate assay platform demand in these three metropolitan zones.
United States
FDA Breakthrough Therapy designations for proteolysis-targeting chimeras compress development timelines for multiple myeloma candidates. The agency's emerging guidance on targeted protein degradation chemistry manufacturing controls shapes sponsor pre-IND preparation. San Diego and Boston CRO clusters absorb the majority of multiplexed high-throughput screening contracts, marginalizing providers lacking ISO 15189-certified 26S kinetic platforms.
Germany
EMA PRIME scheme qualifications for targeted protein degradation therapies pull forward European clinical trial initiation. The country's national pharmaceutical regulator enforces OECD Test Guideline harmonization for preclinical proteasome inhibitor studies. Frankfurt and Munich pharmaceutical manufacturing zones establish transatlantic supply redundancy for clinical-grade substrates.
Switzerland
Swissmedic accelerated assessment pathways for oncology biologics attract proteasome inhibitor program headquarters. Basel's pharmaceutical cluster concentrates mass spectrometry-grade substrate library production for mechanism validation workflows. The city's venture capital access supports biotech platform technology bets on neurodegenerative E3 ligase targets.
Japan
PMDA Sakigake designation system creates competitive pressure for proteasome inhibitor sponsors seeking Asian market entry. METI funding for precision medicine infrastructure expands academic proteomics capacity in Tokyo and Osaka. The Kanto region's CRO sector develops specialized 26S degradation assay capabilities for domestic pharmaceutical outsourcing.
United Kingdom
Medicines and Healthcare products Regulatory Agency innovation passports for novel modalities streamline proteasome-targeting therapy development. The MHRA's post-Brexit regulatory autonomy enables differentiated approval timelines from EMA tracks. Cambridge and London biotech clusters concentrate targeted protein degradation venture funding, though manufacturing scale-up increasingly flows to continental European partners.
Ubiquitin Proteasome Market Vendor Landscape
Listed leaders compete with private specialists across therapeutic modality and research reagent domains, creating a tiered structure where scale advantages in clinical development meet niche dominance in assay instrumentation. The market segments into three strategic archetypes: integrated pharmaceutical conglomerates with proteasome inhibitor portfolios, specialized reagent-instrument ecosystem vendors, and targeted protein degradation platform biotechs. Consolidation pressure concentrates among assay platform providers, while therapeutic developers pursue strategic partnerships to access E3 ligase biology expertise.
Among diversified healthcare conglomerates, Johnson & Johnson and Merck KGaA occupy positions spanning therapeutic development through reagent supply. Promega Corporation exemplifies the integrated reagent-instrument archetype, anchoring recurring revenue streams in proteasome research workflows. These three entities represent distinct competitive vectors: pharmaceutical integration, laboratory infrastructure control, and platform technology specialization.
| Leading Market Players |
|---|
| Promega Corporation |
| Johnson & Johnson |
| Merck KGaA |
| Amgen |
| AstraZeneca |
| Takeda Pharmaceuticals |
| Tocris Bioscience |
| Arvinas |
| BioVision Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for ISO 15189-certified assay platforms concentrate pricing power with vendors maintaining validated reagent-instrument ecosystems in the United States and Germany, while buyers in academic segments absorb premium markups for GMP-grade substrates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers capturing pharmaceutical sponsors demanding chemistry manufacturing controls documentation and economy tiers serving Indian and South Korean academic labs prioritizing cost-per-sample efficiency. Price differentiation rests on certification grade and volume scale, with FDA Breakthrough Therapy designation holders front-loading large substrate orders. Cost compression in standard-tier ELISA reagents is intensifying because Chinese suppliers are expanding peptide library production. Academic labs exhibit highest price sensitivity; Janssen-tier pharmaceutical sponsors demonstrate lowest.
Supply Chain Analysis
The United States and Germany anchor clinical-grade proteasome inhibitor production, while Switzerland concentrates mass spectrometry-grade substrate library manufacturing for mechanism validation workflows. Raw material dependencies include recombinant E1 activating enzymes, ubiquitin-activating chemistry precursors, and fluorogenic peptide substrates. Single-source vulnerability in E3 ligase biology expertise creates procurement bottlenecks for targeted protein degradation programs. Distribution runs through specialized CRO channels in Boston and San Diego clusters, with direct-to-sponsor contracting for GMP-certified volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ubiquitin proteasome market is cycling through a therapeutic modality expansion driven by proteolysis-targeting chimera pipeline maturation, with sponsor investment patterns following FDA and EMA accelerated approval designations.
For Market Incumbents: Shield proteasome inhibitor margins by deepening ISO 15189 certification moats against emerging Chinese assay platform competitors, and secure captive supply of E3 ligase biology talent through dedicated training partnerships with Basel and Cambridge academic clusters. Threat substitution from CRISPR-based protein modulation approaches demands accelerated bifunctional degrader R&D investment. For New Entrants and Emerging Players: White-space in neurodegenerative E3 ligase brain penetration assays offers entry points where incumbents under-serve, particularly for tau and alpha-synuclein clearance validation. Target Japanese CRO infrastructure gaps in 26S kinetic platforms, leveraging METI precision medicine funding for domestic partnership anchoring. Go-to-market angle should emphasize ISO certification documentation speed against European competitor audit cycles. For Investors and Strategic Acquirers: Long-term, this sits as a platform technology consolidation play because targeted protein degradation modality validation will concentrate winner-take-most economics among assay-reagent integrated vendors. Acquisition archetype: mid-cap specialists with validated substrate libraries and transatlantic manufacturing redundancy. Signal to watch: FDA chemistry manufacturing controls guidance finalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses proteasome inhibitor development timelines for multiple myeloma candidates. |
| Manufacturing Scale-Up | EMA PRIME scheme qualifications pull forward European clinical trial initiation requiring transatlantic substrate supply redundancy. |
| Platform Integration | Mass spectrometry-grade substrate library control enables mechanism validation workflows for proteolysis-targeting chimeras. |
| Strategic Partnership | Specialized CRO relationships in San Diego and Boston clusters concentrate proteasome assay expertise for sponsor outsourcing. |
| Geographic Expansion | Japanese CRO sector development of 26S degradation capabilities captures PMDA Sakigake designation program opportunities. |
Methodological Framework
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration across primary interview cycles, validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up reagent demand modeling triangulated with top-down pharmaceutical R&D budget allocations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, technology platform, end-user category, and therapeutic application area. CAGRs were derived from sponsor pipeline density analysis and biomarker validation capex intensity patterns, incorporating proteomics infrastructure deployment rates and venture funding geographic concentration.
Forecasts assume regulatory continuity in FDA Breakthrough Therapy and EMA PRIME scheme frameworks; material policy shifts would require re-modeling. Specific risks include E3 ligase biology expertise scarcity and ATP-dependent assay standardization bottlenecks. Recalibration cycles align with material shifts in targeted protein degradation chemistry manufacturing controls guidance and accelerated approval pathway utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Reverse Transcriptase Enzymes Market