
 Asia-Pacific Biomedical Sensors Market | 2026-2036
Asia-Pacific Biomedical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biomedical Sensors Market Outlook
Japan's METI carbon-neutrality roadmap for medical devices is expanding procurement criteria for low-power biomedical sensors. GE Healthcare leverages its imaging heritage to anchor high-end diagnostic sensor lines across East Asian hospital networks. NXP Semiconductors specializes in secure connectivity architectures for wearable patient monitors. STMicroelectronics NV competes on MEMS fabrication scale, supplying pressure and motion sensing dies to regional device OEMs.
Biomedical sensors are electrochemical, optical, or thermal transducers that convert physiological signals into quantifiable electrical outputs, typically operating at milliampere current draws with biocompatible encapsulation for blood-contact or tissue-adjacent deployment. Their primary purpose is enabling real-time physiological monitoring, diagnostic biomarker detection, and closed-loop therapeutic feedback in clinical and ambulatory settings. Biosensors capture the fastest expansion trajectory, fueled by glucose and lactate assay demand in point-of-care configurations across India's tier-two cities. Wearable technology dominates volume production, though implantable sensors command the deepest margin pools due to sterilization-grade reliability requirements and extended regulatory validation cycles. Optical sensors sustain steady hospital adoption for pulse oximetry and photoplethysmography applications.
Japan's PMDA enforces stringent biocompatibility and electromagnetic compatibility standards that filter out low-reliability sensor suppliers, while China's NMPA accelerates review timelines for domestically manufactured innovative devices under its priority review pathway. India's CDSCO alignment with ICH-GMP protocols is reshaping import substitution strategies for foreign sensor manufacturers seeking hospital procurement contracts. Stakeholders must weigh Japan's premium certification value against China's volume scaling efficiency when allocating regional production capacity and regulatory submission resources.
Market Dynamics
India's PLI scheme for medical electronics is redirecting manufacturing investment toward domestic sensor fabs, compressing procurement timelines for hospital networks and tier-two diagnostic chains across the subcontinent.
Growth Catalysts
- Japan's METI carbon-neutrality roadmap:METI's procurement criteria for low-power biomedical sensors is expanding addressable demand for energy-efficient transducers in precision device clusters.
- Chronic disease management programs:Hospital-based diabetes and cardiovascular protocols are accelerating electrochemical sensor deployment for real-time glucose and lactate monitoring.
- MEMS fabrication scale:Regional foundry capacity for pressure and motion sensing dies is reducing unit costs for wearable patient monitor OEMs.
Market Restraints
- Biocompatibility certification costs:Japan's PMDA sterilization-grade reliability requirements impose extended validation cycles that filter low-reliability suppliers from implantable sensor pools.
- Semiconductor input volatility:MEMS wafer and biocompatible encapsulation material costs fluctuate with foundry utilization rates across East Asian supply nodes.
- Optical sensor substitution:Photoplethysmography modules in pulse oximetry face displacement risk from multi-parameter fusion chips integrating optical and thermal transduction.
Strategic Opportunities
- China's priority review pathway:NMPA accelerated timelines for domestically manufactured innovative devices create first-mover advantages for local sensor design houses.
- Point-of-care expansion:India's tier-two cities present underpenetrated demand for biosensor-based glucose and lactate assay configurations outside metropolitan hospital networks.
- Secure connectivity convergence:Near-field communication architectures for wearable patient monitors are converging with biometric authentication protocols in premium device segments.
Industry Challenges
- CDSCO-ICH-GMP alignment:India's import substitution mandates require foreign manufacturers to reconfigure quality management systems for hospital procurement eligibility.
- Implantable sensor integration:Closed-loop therapeutic feedback systems demand specialized firmware engineering talent scarce across regional device OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biomedical Sensors Market |
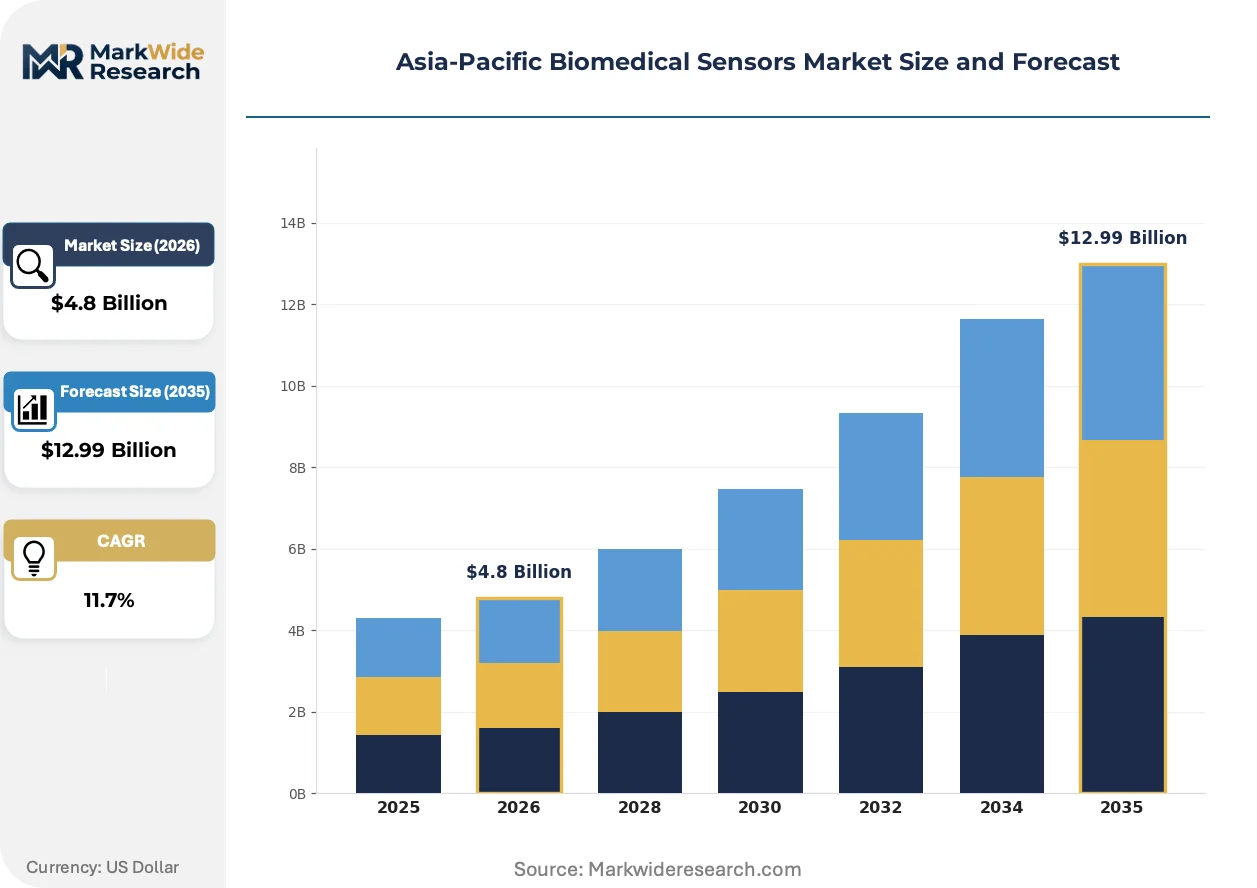
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sensors, Pressure Sensors, Temperature Sensors, Biosensors Application: Patient Monitoring, Diagnostics, Therapeutic Devices, Fitness Tracking Technology: Wearable Technology, Implantable Sensors, Point-of-Care Testing, Lab-on-a-Chip End User: Hospitals, Research Laboratories, Home Care, Fitness Centers |
| Companies Covered | GE Healthcare, NXP Semiconductors, Medtronic, Honeywell International Inc., STMicroelectronics NV, Smiths Medical, Analog Devices Inc., TE Connectivity, Texas Instruments Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
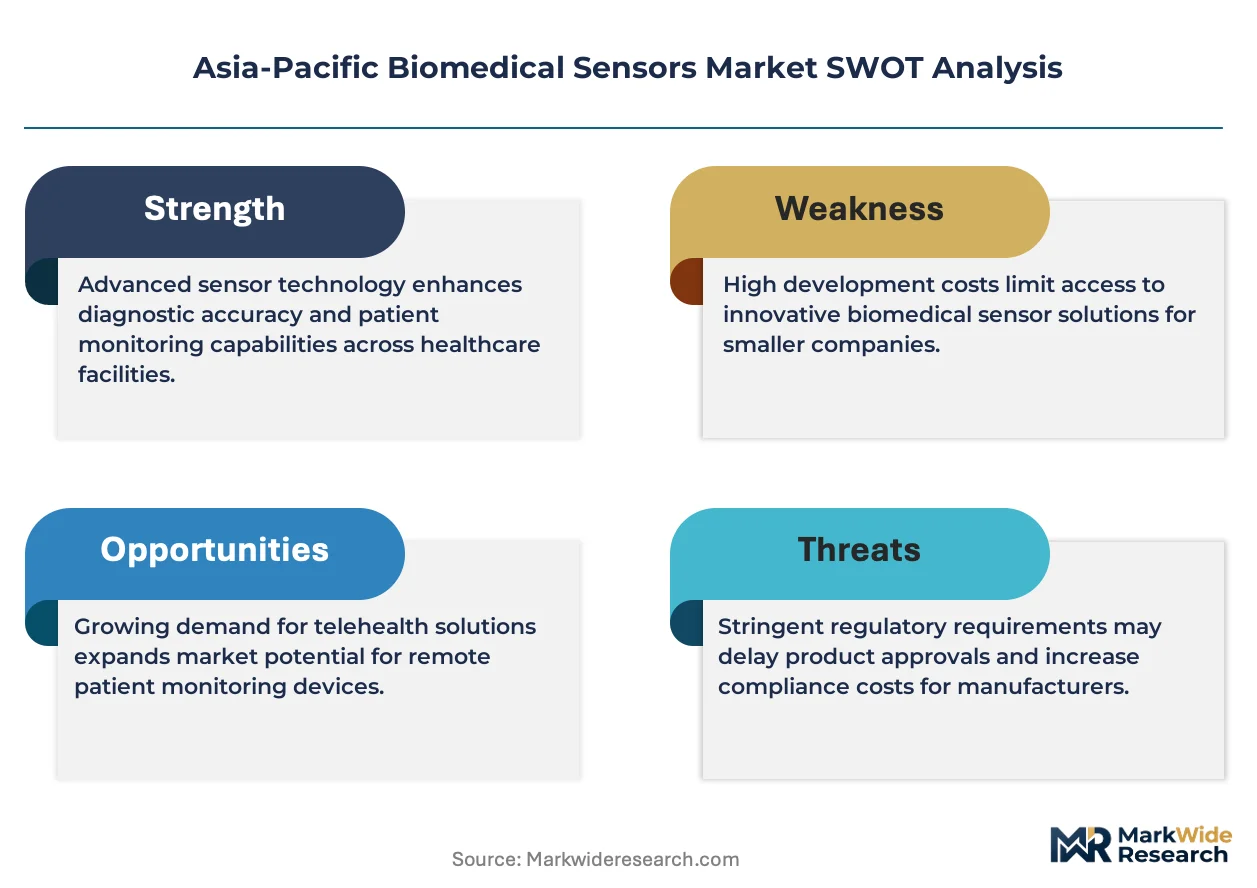
Asia-Pacific Biomedical Sensors Market Strategic Shifts
Sensor architectures across the Asia-Pacific are bifurcating between high-volume wearable production and premium implantable reliability tiers, with regulatory differentiation becoming the primary sorting mechanism for supplier positioning.
Optical sensing modalities for pulse oximetry and photoplethysmography are converging with machine-learning inference at the edge, enabling real-time arrhythmia detection without cloud dependency. Cardiology departments in Japan's precision device clusters are adopting these fused modules fastest, compressing the traditional multi-vendor diagnostic stack into single-patch configurations. This convergence is forcing standalone optical sensor suppliers to add algorithmic IP or cede margin to integrated platform vendors.
China's NMPA priority review pathway is compressing regulatory timelines for domestically manufactured innovative devices, accelerating product cycles for MEMS-based pressure sensors in ambulatory blood pressure monitors. Local design houses are responding by front-loading biocompatibility documentation and electromagnetic compatibility pre-submissions. The policy shift most affects mid-tier wearable OEMs previously dependent on imported sensing dies.
Hospital procurement in India's tier-two cities is fragmenting from centralized state tenders toward direct contracts with diagnostic chains seeking point-of-care biosensor integration. Device vendors are building dedicated distribution teams for these secondary markets, displacing traditional importer-distributor hierarchies. This channel restructuring is most visible in Maharashtra and Karnataka, where private laboratory networks now specify sensor performance thresholds in direct RFQs rather than accepting bundled instrument packages.
Asia-Pacific Biomedical Sensors Market Segmentation
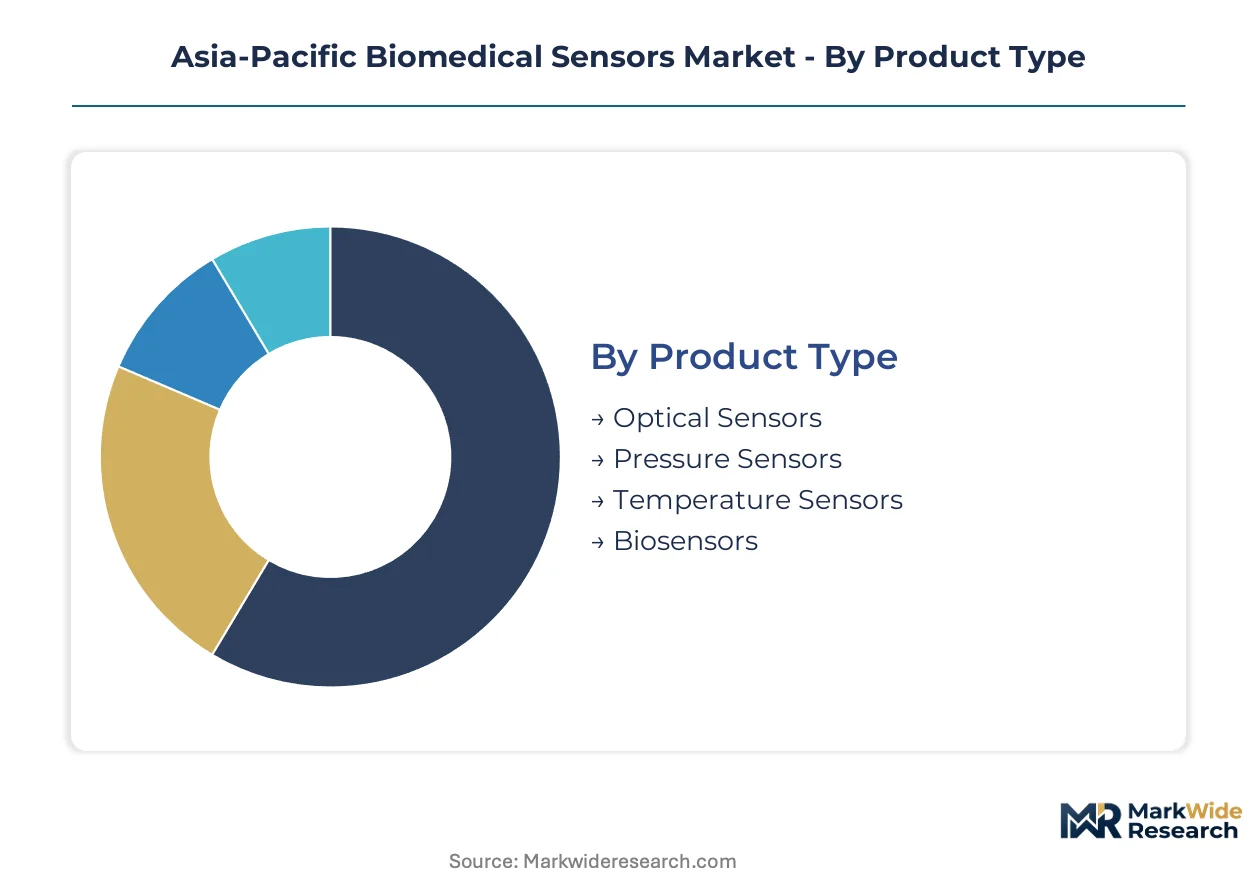
Segmentation in the Asia-Pacific biomedical sensors market reveals distinct capital requirements and margin profiles across product architectures. Each dimension—product type, application, technology, and end user—channels investment toward different validation timelines and certification tiers.
Product Type:
Capital intensity varies sharply across transducer categories, with sterilization-grade reliability requirements driving foundry investment toward implantable-compatible fabrication nodes.
- Optical Sensors:Photodiode arrays and LED-photodetector pairs convert tissue absorbance into pulse oximetry and photoplethysmography signals. Demand concentrates in Japan's precision device clusters where METI carbon-neutrality procurement criteria favor low-power configurations.
- Biosensors:Electrochemical transducers with enzyme-immobilized electrodes enable glucose and lactate quantification at milliampere current draws. India's tier-two diagnostic chains are accelerating procurement for point-of-care assay configurations outside metropolitan hospital networks.
- Pressure Sensors:MEMS-fabricated piezoresistive dies measure arterial and intracranial pressure with biocompatible encapsulation.
- Temperature Sensors:Thermistor and thermopile architectures track core body temperature through skin-contact or ingestible formats.
Most installed capacity flows through Optical Sensors. Expansion is steepest in Biosensors.
Application:
Application segmentation sorts customers by clinical risk tier and reimbursement pathway, with therapeutic indications commanding premium pricing over wellness-oriented deployments.
- Patient Monitoring:Continuous physiological tracking through wearable patches and bedside instruments requires real-time signal processing and secure connectivity architectures. China's NMPA priority review pathway is accelerating domestic OEM timelines for multi-parameter fusion devices.
- Diagnostics:Biomarker detection systems for infectious disease and metabolic panels demand specialized calibration protocols. Japan's PMDA enforces stringent electromagnetic compatibility standards that filter low-reliability suppliers from hospital procurement pools.
- Therapeutic Devices:Closed-loop drug delivery and neuromodulation systems integrate sensing with actuation.
- Fitness Tracking:Consumer-grade motion and heart rate monitoring operates outside medical device regulatory frameworks.
Patient Monitoring absorbs the largest share of regional sensor output. Diagnostics is climbing the fastest as tier-two hospital networks upgrade from centralized laboratory models.
Technology:
Technology segmentation distinguishes between external-body deployment and invasive implantation, with the latter requiring extended validation cycles and specialized firmware engineering talent.
- Wearable Technology:Skin-adjacent patches and wrist-worn instruments integrate optical, thermal, and motion sensing with near-field communication for data offload. NXP Semiconductors anchors secure connectivity architectures for these configurations across East Asian hospital networks.
- Implantable Sensors:Sterilization-grade devices with biocompatible encapsulation enable blood-contact deployment for glucose monitoring and cardiac rhythm management. Extended regulatory validation cycles and firmware scarcity across regional OEMs constrain supply expansion.
- Point-of-Care Testing:Portable biosensor cartridges deliver assay results at decentralized clinical sites.
- Lab-on-a-Chip:Microfluidic architectures consolidate sample preparation and detection onto single substrates.
Wearable Technology dominates volume production. Implantable Sensors command the deepest margin pools due to reliability requirements and certification barriers.
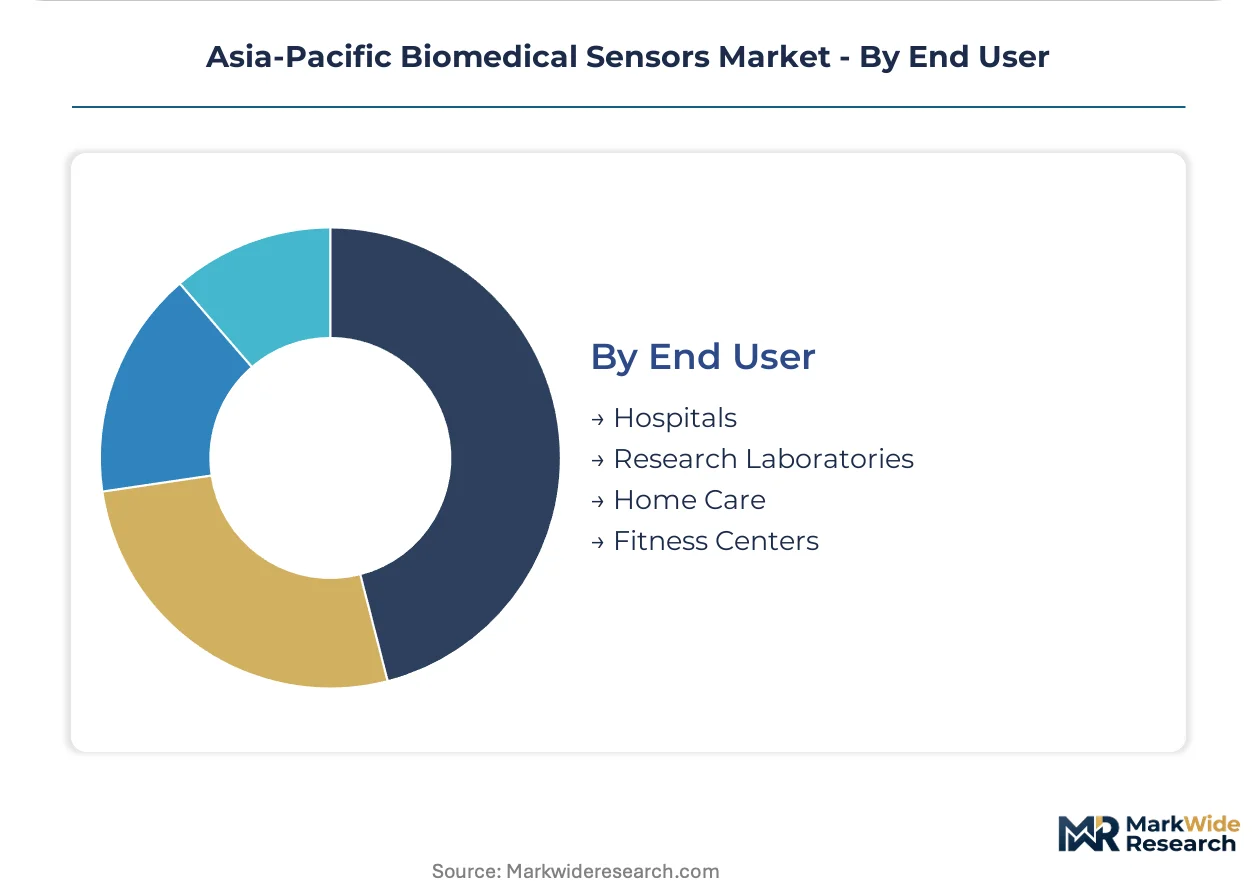
End User:
End user segmentation tracks procurement centralization, from state-level tenders in public hospital systems to direct contracts with private diagnostic chains.
- Hospitals:Acute care networks specify multi-parameter sensing stacks for intensive care and operating theater deployment. India's CDSCO alignment with ICH-GMP protocols is reshaping import substitution strategies for foreign manufacturers seeking procurement eligibility.
- Home Care:Post-discharge monitoring and chronic disease management programs accelerate demand for patient-operated biosensors. Maharashtra and Karnataka laboratory networks now specify performance thresholds in direct RFQs rather than accepting bundled instrument packages.
- Research Laboratories:Preclinical and clinical trial applications require calibrated reference-grade transducers.
- Fitness Centers:Commercial wellness facilities deploy consumer-grade wearables for member engagement programs.
Hospitals retain the largest procurement budget share. Home Care is expanding most quickly as discharge protocols shift toward ambulatory monitoring models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical sensor manufacturing first scaled in Japan's precision electronics corridors during the 1980s, establishing design protocols and cleanroom standards that later diffused to South Korean and Taiwanese foundries. This technical lineage now anchors regional production networks across East Asia.
Japan
Tokyo and Osaka precision device clusters drive demand for low-power optical transducers in cardiology and patient monitoring applications. METI's carbon-neutrality procurement criteria filter hospital purchasing toward energy-efficient sensor configurations. Kansai-based OEMs are consolidating multi-parameter sensing modules into single-patch diagnostic platforms for domestic hospital networks.
China
Domestic MEMS foundry capacity in Jiangsu and Zhejiang provinces supplies pressure and motion sensing dies to wearable monitor manufacturers. NMPA's priority review pathway accelerates regulatory timelines for locally designed innovative devices. Shenzhen design houses are front-loading biocompatibility documentation to capture first-mover advantages in ambulatory blood pressure monitoring segments.
India
Maharashtra and Karnataka laboratory networks are fragmenting procurement from state tenders toward direct RFQs with biosensor specifications for point-of-care glucose and lactate assays. CDSCO alignment with ICH-GMP protocols is reshaping import substitution strategies for foreign manufacturers seeking hospital eligibility. Tamil Nadu's medical electronics corridor is attracting PLI scheme investment toward domestic sensor fabrication.
South Korea
Seoul Capital Area semiconductor fabs supply secure connectivity architectures for wearable patient monitors with integrated biometric authentication. MFDS enforces electromagnetic compatibility standards that align with Japan's PMDA reliability thresholds. Busan-Ulsan industrial zones are expanding MEMS packaging capacity for regional OEMs serving East Asian hospital networks.
Australia
TGA-regulated research laboratories in New South Wales and Victoria drive demand for calibrated reference-grade transducers in clinical trial applications. Melbourne's medtech precinct is specializing in implantable sensor firmware engineering for closed-loop therapeutic feedback systems. Sydney-based distributors are bridging procurement gaps between Asian sensor foundries and domestic hospital procurement offices.
Asia-Pacific Biomedical Sensors Market Competitive Environment
Capital-heavy producers compete with asset-light designers across distinct fabrication strategies in the Asia-Pacific biomedical sensors market. Foundry-dependent sensor houses source MEMS dies from Taiwan and South Korean wafer facilities, while integrated manufacturers retain captive cleanroom capacity for implantable-grade reliability tiers. The competitive landscape sorts into three archetypes: imaging heritage conglomerates anchoring high-end diagnostic lines, semiconductor specialists supplying connectivity and transduction components, and diversified industrials leveraging materials science portfolios. Dominant competitive moves include strategic partnerships between sensor designers and regional hospital networks, plus capacity expansion into India's PLI-subsidized medical electronics zones.
Among imaging heritage conglomerates, GE Healthcare occupies a position exemplifying integrated diagnostic platform strategies. Within semiconductor connectivity specialists, NXP Semiconductors and STMicroelectronics NV represent secure architecture and MEMS fabrication scale archetypes respectively. These three anchors illustrate how technical lineage—in medical imaging, secure NFC design, and MEMS foundry operations—shapes competitive positioning across East Asian procurement channels.
| Leading Market Players |
|---|
| GE Healthcare |
| NXP Semiconductors |
| Medtronic |
| Honeywell International Inc. |
| STMicroelectronics NV |
| Smiths Medical |
| Analog Devices Inc. |
| TE Connectivity |
| Texas Instruments Incorporated |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between implantable sterilization tiers and wearable commodity production channels pricing power toward Japanese PMDA-validated suppliers while compressing margins for unqualified foundries serving price-sensitive Indian diagnostic chains. This bifurcation concentrates procurement budgets in Tokyo-Osaka precision clusters and fragments downstream sourcing across tier-two city laboratory networks seeking point-of-care biosensor configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels sorts Asia-Pacific biomedical sensor procurement by validation depth and biocompatibility certification. Premium tiers anchor in Japan's METI carbon-neutrality criteria and PMDA sterilization-grade requirements, while economy tiers serve Indian tier-two diagnostic chains through CDSCO-aligned import substitution mandates. Price differentiation hinges on electromagnetic compatibility pre-certification and MEMS fabrication node geometry, with cost compression in wearable optical modules intensifying as Chinese NMPA priority review accelerates domestic OEM timelines. Hospital procurement committees in East Asian precision device clusters exhibit lowest price sensitivity; Maharashtra private laboratory networks demonstrate highest elasticity.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, while MEMS wafer fabrication feeds from Taiwan and South Korean foundry complexes. Biocompatible encapsulation polymers draw from German and US medical-grade resin suppliers, with sensor packaging capacity concentrating in Shenzhen and Busan-Ulsan industrial zones. Single-source vulnerability in 200mm MEMS wafer supply creates exposure to foundry utilization rate fluctuations across East Asian nodes. Distribution runs through hospital procurement offices in Japan, state tender authorities in India, and direct RFQ channels with Maharashtra diagnostic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific biomedical sensors market functions as a regulatory compounder, with China's NMPA priority review pathway accelerating product cycles and reshaping competitive entry economics across the region.
For Market Incumbents: Acquire firmware engineering talent pools in Australia and South Korea to address implantable sensor integration scarcity constraining closed-loop therapeutic feedback development. Consolidate biocompatibility documentation capabilities ahead of India's CDSCO-ICH-GMP alignment deadlines to defend hospital procurement eligibility against emerging domestic competitors. Capacity addition in Tamil Nadu's PLI-subsidized medical electronics corridor secures volume positioning for point-of-care biosensor expansion. For New Entrants and Emerging Players: NMPA priority review pathway in China opens a window for domestic design houses to capture first-mover advantages in ambulatory blood pressure monitoring segments through front-loaded electromagnetic compatibility pre-submissions. India's tier-two city diagnostic chains present underpenetrated white space for glucose and lactate assay configurations outside metropolitan hospital networks. Direct RFQ engagement with Maharashtra and Karnataka laboratory networks bypasses traditional importer-distributor hierarchies. For Investors and Strategic Acquirers: Asymmetric upside sits with implantable sensor firmware specialists bridging closed-loop therapeutic feedback engineering gaps across regional OEMs. Long-term viability favors acquisition targets with captive cleanroom capacity for sterilization-grade reliability tiers rather than foundry-dependent commodity producers. Watch NMPA review timeline compression and CDSCO import substitution enforcement as inflection indicators for regional production capacity allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | GE Healthcare anchors high-end diagnostic sensor lines through East Asian network procurement contracts. |
| CE Marking Pathway | European regulatory alignment accelerates Japan PMDA biocompatibility certification reciprocity for implantable tiers. |
| Software Companion Development | Machine-learning edge inference modules compress multi-vendor diagnostic stacks into single-patch configurations. |
| Reimbursement Strategy | Chronic disease management program eligibility determines hospital procurement volume for glucose monitoring biosensors. |
| Regulatory Approval Pathway | CDSCO-ICH-GMP alignment reshapes foreign manufacturer quality management system configurations for Indian hospital eligibility. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down MEMS foundry capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at CDSCO and NMPA interface with secondary validation from FDA 510(k) filings, PMDA approval databases, hospital procurement contract registries, and SEMI fab capacity reports. Triangulation across these sources anchors volume estimates in actual tender awards and foundry utilization disclosures.
Input-output matrices map sensor die production through encapsulation, calibration, and final device integration across wearable and implantable technology tiers. Segmentation dimensions span product type, application risk tier, deployment technology, and end-user procurement centralization. CAGRs derive from regression against chronic disease prevalence trajectories, regulatory review timeline changes, and foundry capacity expansion announcements. Forecast inputs incorporate METI carbon-neutrality procurement criteria adoption curves and PLI scheme manufacturing investment flows.
Revisions become necessary when NMPA priority review pathway scope expands, CDSCO enforcement intensity shifts, or MEMS wafer supply disruptions materialize across Taiwan and South Korean nodes. Forecasts reflect documented assumptions regarding regulatory timeline stability and foundry utilization continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Middle East and Africa Exosome Research Products Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Northern Blotting Market