
 Digital Biology Market | 2026-2036
Digital Biology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Biology Market Insights
Platform licensing revenue is narrowing as vendors bundle analytics with cloud infrastructure. Thermo Fisher Scientific leverages its instrument installed base to pull through recurring software subscriptions. Illumina sustains dominance in genomic data generation, though its push into secondary analysis tools reshapes margin capture. Lonza Group anchors its position through integration of biomanufacturing data with digital twin platforms for cell-line optimization.
Digital biology encompasses the computational modeling, simulation, and data-driven analysis of biological systems using genomic sequences, molecular interaction networks, and cellular behavior parameters to predict phenotypic outcomes. The field applies machine learning algorithms to multi-omics datasets with throughput exceeding 10,000 samples per day in commercial settings, primarily to compress timelines in therapeutic discovery and precision agriculture breeding programs. Genomic sequencing technology retains the largest revenue share as declining per-base costs expand addressable sample volumes, though machine learning applications exhibit the fastest expansion as pharmaceutical firms retrain proprietary models on accumulated experimental data. Cloud computing infrastructure underpins margin migration toward platform economics, with research institutions and academic labs representing price-sensitive demand segments that favor pay-per-use architectures over perpetual licenses.
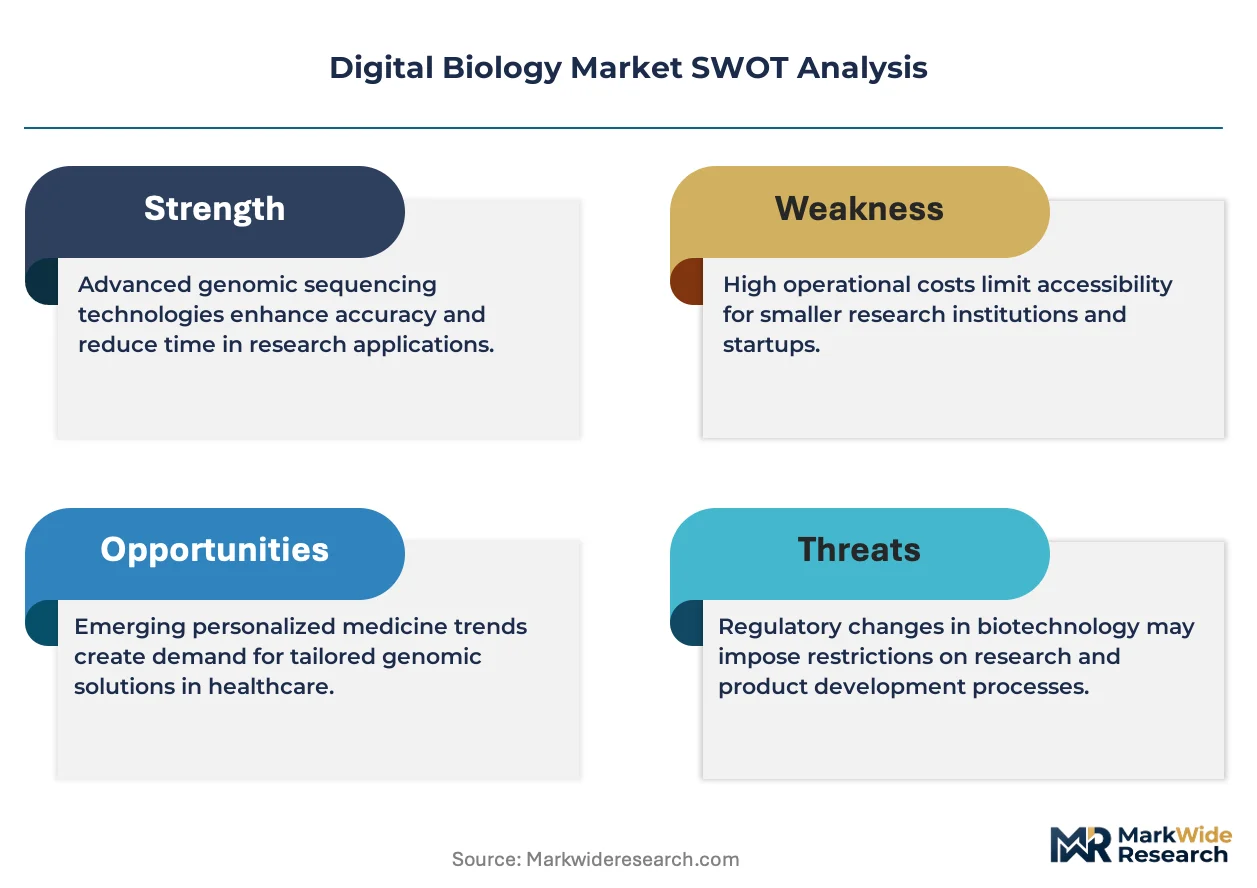
FDA software-as-a-medical-device guidance and HIPAA data governance requirements constrain architecture choices for platforms handling patient-derived genomic information, while EMA's evolving stance on computational evidence in regulatory submissions shapes European deployment timelines. ISO 13485 quality management expectations extend into digital biology tool validation, particularly where outputs inform clinical decision-making or manufacturing release criteria. Stakeholders must monitor divergence between FDA and EMA digital-evidence standards when architecting multi-territory platform deployments.
Market Dynamics
Machine learning inference at scale is compressing therapeutic discovery timelines from years to months, forcing pharmaceutical firms to restructure R&D workflows around computational-first validation rather than wet-lab iteration.
Growth Catalysts
- AI-enabled medical device software guidance:The FDA's validation framework for computational diagnostics accelerates regulatory clearance for genomic classifiers, expanding reimbursable use cases in oncology and rare disease screening.
- Multi-omics data integration:Pharmaceutical pipelines now combine transcriptomic, proteomic, and metabolomic layers into unified models, generating demand for platforms that harmonize heterogeneous data formats at terabyte scale.
- Cloud infrastructure maturation:Research institutions in the United States, Germany, and Japan are migrating from on-premise servers to elastic compute environments, enabling pay-per-analysis pricing that lowers barriers for mid-sized biotech entrants.
Market Restraints
- GPU supply concentration:Training large biological foundation models requires NVIDIA H100 clusters, with lead times extending 40-52 weeks and pricing volatility constraining platform expansion budgets.
- HIPAA-GDPR jurisdictional friction:Cross-border transfer of patient-derived genomic datasets requires dual compliance architectures, adding 15-25% overhead to platform engineering costs for multi-territory deployments.
- Wet-lab validation bottlenecks:Computational predictions still require experimental confirmation in cell-based assays, creating throughput constraints that limit full automation of discovery pipelines.
Strategic Opportunities
- Precision agriculture penetration:Crop breeding programs in Brazil and India remain underdigitized, presenting whitespace for genomic selection platforms that compress varietal development from 8-10 years to 3-4 years.
- Cell-line digital twin adoption:Biomanufacturers seek predictive models of CHO cell behavior to optimize titer yields, creating demand for platforms that integrate bioreactor sensor data with mechanistic simulations.
- EU AI Act compliance services:Risk classification requirements for high-stakes biological AI systems will generate recurring revenue streams for validation tooling and audit documentation workflows.
Industry Challenges
- Computational biology talent scarcity:The intersection of machine learning expertise and biological domain knowledge remains shallow, with PhD-level practitioners commanding premium compensation that strains mid-tier platform vendors.
- ISO 13485 quality system implementation:Digital biology tools used in clinical decision-making require medical device-grade documentation, extending development cycles by 18-24 months for firms lacking prior regulatory experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Biology Market |
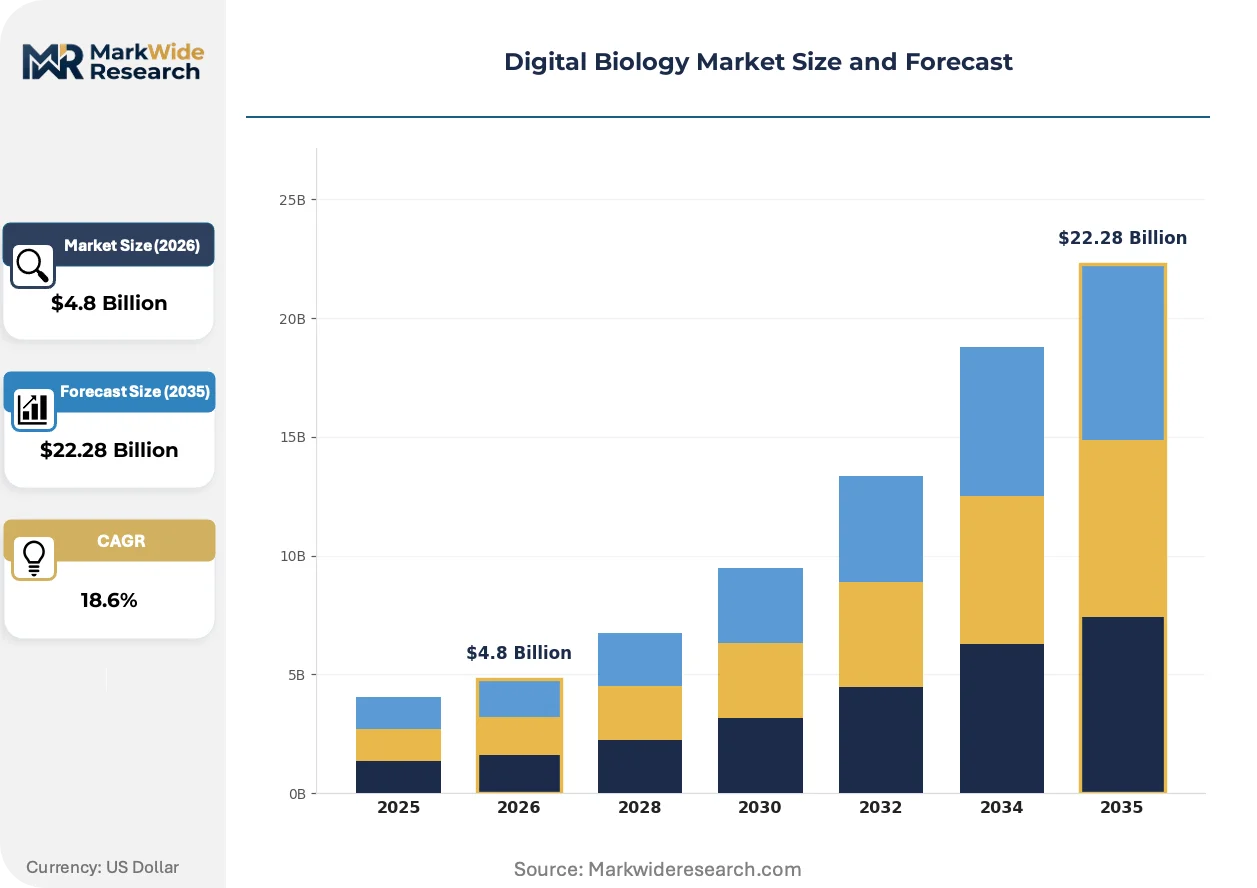
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platforms, Devices, Tools Technology: Genomic Sequencing, Data Analytics, Machine Learning, Cloud Computing End User: Research Institutions, Pharmaceutical Firms, Biotechnology Companies, Academic Labs Application: Drug Development, Disease Diagnosis, Genetic Research, Agriculture |
| Companies Covered | Agilent Technologies, Lonza Group, Thermo Fisher Scientific, LatchBio, WuXi AppTec, Illumina, SOPHiA GENETICS, Andson Biotech, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Biology Market Trends and Innovations
Foundation models trained on protein structures and chemical reaction graphs are displacing rule-based molecular design, compressing lead optimization from iterative screening to generative synthesis.
AlphaFold-derived structure prediction is digitizing target validation workflows for kinase and GPCR programs, with mid-cap pharmaceutical firms now licensing structural databases rather than maintaining internal crystallography units, collapsing the traditional structure-function bottleneck that delayed program initiation.
The EU AI Act's risk-tiered compliance framework is forcing re-architecture of diagnostic algorithms that process genomic data, with Class IIa and IIb medical device classifications triggering conformity assessment requirements that favor established vendors with notified body relationships over venture-stage entrants lacking quality management maturity.
Subscription-based access to curated training datasets is displacing perpetual license sales for bioinformatics platforms, with academic consortia and pharmaceutical procurement teams negotiating enterprise-wide agreements that bundle compute credits with pre-validated reference genomes, shifting vendor economics toward recurring revenue recognition.
Digital Biology Market Segmentation
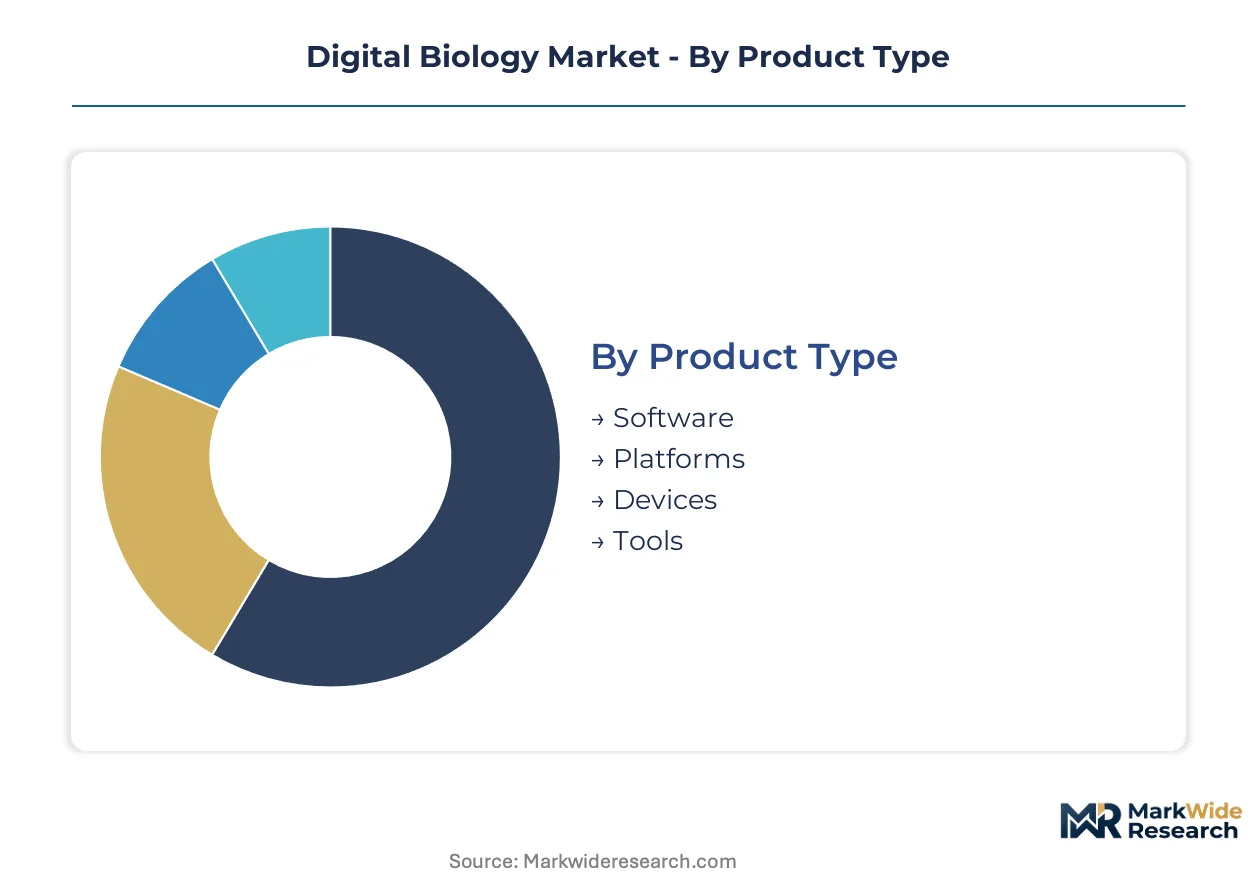
Segmentation in digital biology reveals how computational infrastructure, analytical methods, and end-user sophistication stratify purchasing behavior. Vendors must align pricing architectures and deployment models to distinct technical maturity levels across customer bases.
Product Type:
Mature perpetual-license software coexists with emerging platform-as-a-service offerings that bundle compute with analytics.
- Software:Standalone bioinformatics applications for sequence alignment, variant calling, and pathway analysis. Demand concentrates in academic labs across Germany and Japan seeking cost-predictable perpetual licenses with minimal IT overhead.
- Platforms:Integrated environments combining data ingestion, processing pipelines, and visualization layers. Pharmaceutical firms in the United States drive procurement, prioritizing elastic scaling for multi-territory clinical trials and FDA submission workflows.
- Devices:Purpose-built hardware for edge computing in sequencing facilities and biomanufacturing plants. Biotechnology companies favor on-premise deployment to maintain HIPAA-compliant data custody.
- Tools:Specialized utilities for niche analytical tasks such as CRISPR guide RNA design or protein structure refinement. Research institutions adopt these as modular supplements to broader platform investments.
Software retains volume leadership; platforms hold the steepest expansion curve.
Technology:
Cost tiers separate capital-intensive sequencing infrastructure from margin-light cloud consumption models.
- Genomic Sequencing:High-throughput instruments generating raw nucleotide data with per-base costs declining below $100 for whole human genomes. Academic consortia in the United Kingdom and Australia anchor demand, though instrument refresh cycles are elongating.
- Data Analytics:Statistical and visualization methods for interpreting multi-omics datasets. Biotechnology companies in South Korea deploy these for biomarker discovery in immuno-oncology programs.
- Machine Learning:Predictive models trained on accumulated experimental data to forecast molecular behavior. Pharmaceutical firms invest heavily here, retraining proprietary foundation models on decade-scale compound libraries.
- Cloud Computing:Elastic infrastructure for storage and processing of terabyte-scale biological datasets. Research institutions migrate fastest, drawn by pay-per-analysis pricing that converts fixed capital to variable operational expenditure.
Genomic sequencing dominates current spending; machine learning applications are gaining share fastest.
End User:
Customer type determines procurement sophistication, with enterprise buyers demanding integration and academic segments prioritizing accessibility.
- Research Institutions:Universities and national laboratories conducting fundamental biological inquiry. Budget constraints favor open-source tools supplemented by selective commercial platform licensing.
- Pharmaceutical Firms:Large-cap drug developers restructuring R&D around computational-first validation. These buyers negotiate enterprise agreements bundling software, compute credits, and professional services.
- Biotechnology Companies:Venture-stage and mid-cap therapeutics developers lacking internal infrastructure. Subscription-based access to curated datasets and pre-validated pipelines reduces capital requirements.
- Academic Labs:Individual investigator groups with limited IT support. Demand concentrates on browser-accessible tools with minimal configuration requirements.
Pharmaceutical firms command the largest contract values; biotechnology companies show the most elastic demand growth.
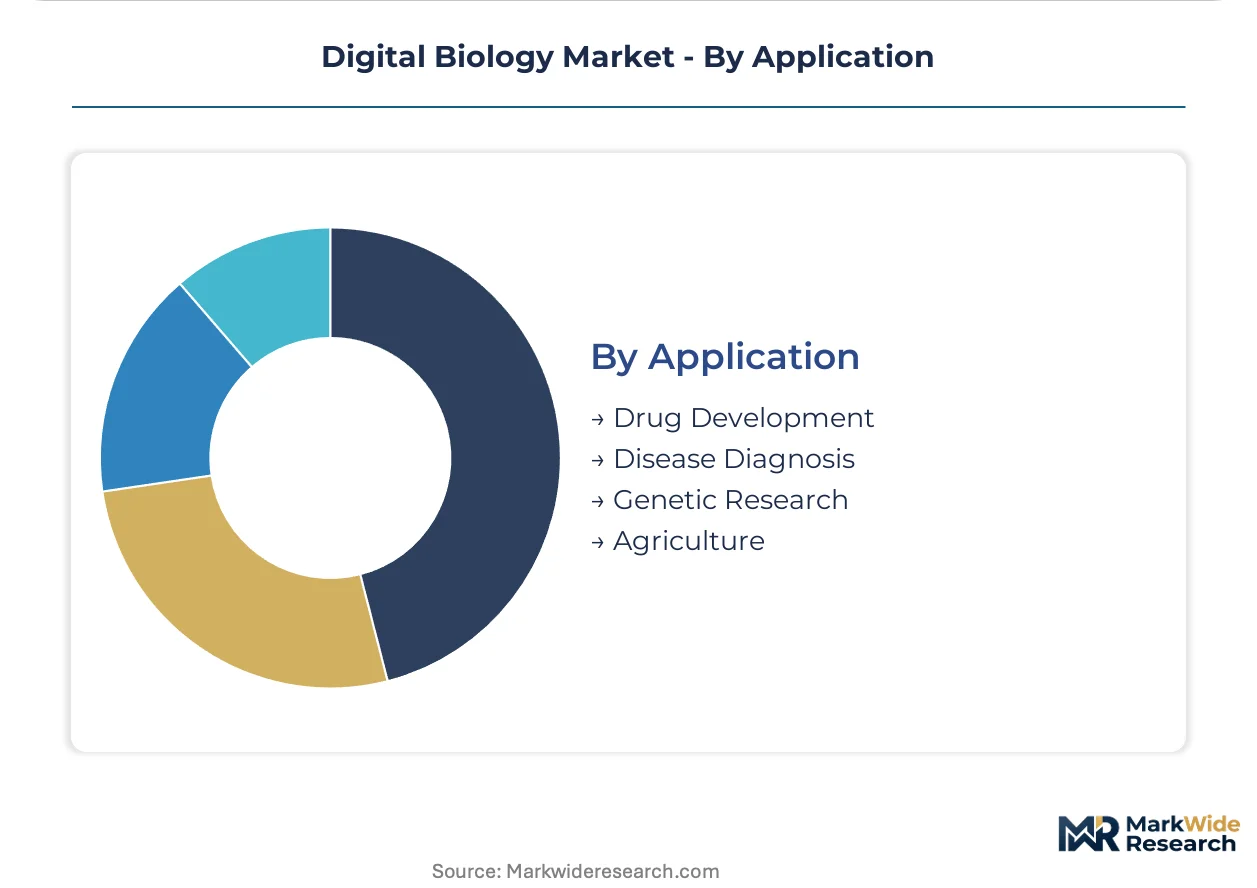
Application:
Application scope spans regulated therapeutic development to exploratory agricultural breeding with divergent compliance burdens.
- Drug Development:Computational target identification, lead optimization, and clinical trial simulation. FDA software-as-a-medical-device guidance shapes validation requirements for predictive algorithms supporting regulatory submissions.
- Disease Diagnosis:Genomic classifiers for oncology screening and rare disease identification. Reimbursement pathways under CMS and private payors determine commercial viability in the United States.
- Genetic Research:Population-scale studies and functional genomics investigations. Research institutions lead adoption, often sharing data through controlled-access repositories.
- Agriculture:Genomic selection for crop improvement and livestock breeding. Brazil and India present whitespace as breeding programs digitize varietal development timelines.
Drug development absorbs the majority of platform investment; agriculture offers the most underpenetrated expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research institutions in Germany and Japan exhibit the highest price elasticity, favoring perpetual licenses with predictable costs, while pharmaceutical buyers in the United States accept premium platform pricing for regulatory-grade validation and elastic scaling capabilities.
United States
Enterprise pharmaceutical procurement drives platform-as-a-service adoption, with FDA software-as-a-medical-device guidance accelerating reimbursable genomic classifier deployments in oncology. The Greater Boston and San Francisco Bay Area clusters concentrate venture-stage biotechnology firms migrating computational workloads to HIPAA-compliant cloud environments.
Germany
Academic consortia and Max Planck institutes anchor demand for cost-predictable bioinformatics tools, with EMA computational-evidence standards shaping European deployment timelines for multi-territory trials. The Munich and Heidelberg research corridors sustain dense instrumentation networks that pull through secondary analysis software subscriptions.
China
Domestic biotechnology scale-up and agricultural breeding digitization generate demand for genomic selection platforms, with NMPA evolving regulatory frameworks for AI-enabled diagnostic algorithms. The Yangtze River Delta biocluster around Shanghai concentrates contract research organizations integrating computational pipelines with manufacturing data.
United Kingdom
Population-scale genomic initiatives and NHS precision medicine programs expand addressable volumes for clinical decision-support tools, with MHRA alignment to FDA validation pathways streamlining dual-market submissions. The Cambridge-London corridor anchors structural biology and CRISPR tool development ecosystems.
Japan
Pharmaceutical R&D restructuring around computational-first validation compresses discovery timelines, with PMDA guidance on digital therapeutics shaping platform architecture choices. The Kanto region around Tokyo concentrates instrument-installed bases that vendors leverage for recurring software pull-through.
Digital Biology Market Competitive Landscape
Instrument-anchored conglomerates and cloud-native platform specialists split the market into distinct capability tiers. Consolidation pressure concentrates around vendors controlling sequencing hardware installed bases, while mid-tier entrants compete on modular analytics and pay-per-use pricing. Two strategic archetypes dominate: legacy instrumentation firms leveraging hardware pull-through for software subscriptions, and venture-stage platform vendors bundling compute with curated training datasets. Dominant competitive moves include backward integration into proprietary reference databases and geographic expansion through notified-body relationships for EU AI Act compliance.
Within the instrumentation-anchored tier, Thermo Fisher Scientific and Illumina exemplify hardware-to-software margin migration strategies, with the former leveraging its analytical instrument installed base and the latter sustaining dominance in genomic data generation infrastructure. Lonza Group occupies a distinct position integrating biomanufacturing process data with predictive modeling platforms for cell-line optimization. Among specialized service providers, WuXi AppTec represents the contract research organization archetype embedding computational biology capabilities into integrated discovery workflows.
| Leading Market Players |
|---|
| Agilent Technologies |
| Lonza Group |
| Thermo Fisher Scientific |
| LatchBio |
| WuXi AppTec |
| Illumina |
| SOPHiA GENETICS |
| Andson Biotech |
| F. Hoffmann-La Roche |
| Others |
Pricing and Supply Chain Analysis
The Port of Rotterdam-to-Hamburg freight corridor shapes cost dynamics for sequencing instrument imports into Europe, concentrating pricing power with vendors controlling hardware installed bases while downstream price differentiation separates HIPAA-compliant enterprise deployments from academic pay-per-use tiers.
Pricing Analysis
After-sales revenue from consumables and extended service contracts drives lifetime value capture for instrumentation vendors. Three-tier pricing structure across premium regulatory-grade, standard commercial, and economy academic tiers separates FDA-validated platform deployments from open-source tool adoption. Pricing pressure stems from GPU cluster scarcity extending platform expansion timelines. Research institutions exhibit highest price sensitivity, favoring perpetual licenses, while pharmaceutical firms accept premium SaaS pricing for elastic scaling and compliance documentation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for sequencing hardware and GPU accelerators. Manufacturing concentrates in the United States, China, and Taiwan for high-throughput instruments, while cloud infrastructure draws from hyperscaler facilities in Ireland, Singapore, and Virginia. Critical dependencies include NVIDIA H100 clusters, Illumina flow cells, and specialized reagent chemistries. Distribution runs through direct enterprise sales for pharmaceutical accounts and academic consortia purchasing cooperatives for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital biology market rewards scarce computational biology talent and regulatory quality-system maturity, with PhD-level practitioners commanding compensation premiums that strain mid-tier vendors and extend development cycles for firms lacking ISO 13485 experience.
For Market Incumbents: Entrench platform economics by bundling cloud compute credits with curated training datasets, converting perpetual license buyers to recurring revenue. Defend against venture-stage entrants by deepening notified body relationships for EU AI Act compliance and accelerating FDA software-as-a-medical-device validation pathways. For New Entrants and Emerging Players: Mid-market biotechnology companies in South Korea and Brazil represent the most penetrable entry point, lacking internal infrastructure for multi-omics integration but possessing funded therapeutic pipelines. Precision agriculture breeding programs in India offer whitespace for genomic selection platforms with localized crop reference databases. Go-to-market through channel partnerships with contract research organizations embedding computational modules into integrated discovery workflows. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical firms spinning out internal bioinformatics units lacking scale for independent platform economics. Long-term viability hinges on recurring revenue recognition and regulatory quality-system maturity rather than project-based service contracts. Watch for inflection signals in enterprise SaaS renewal rates and notified body audit completion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Notified body relationships accelerate market access for high-risk genomic classifiers under Class IIa and IIb medical device pathways. |
| Cloud Infrastructure Partnership | Hyperscaler alliances enable HIPAA-compliant elastic compute for pharmaceutical clinical trial workloads without capital-intensive GPU procurement. |
| Backward Integration into Reference Databases | Proprietary curated training datasets differentiate platform predictions and reduce dependency on public genomic repositories. |
| Precision Agriculture Platform Launch | Localized crop and livestock genomic selection tools capture whitespace in Brazil and India breeding digitization. |
| Cell-Line Digital Twin Development | CHO cell behavior prediction integrates bioreactor sensor data with mechanistic simulations for biomanufacturing yield optimization. |
Research Methodology
Operator-level perspectives from computational biology directors, regulatory affairs leads at genomic platform vendors, biopharma R&D procurement managers, and cloud infrastructure specialists anchored the qualitative base. Secondary validation drew from FDA software-as-a-medical-device guidance documents, EMA computational-evidence consultation papers, ClinicalTrials.gov genomic classifier submissions, and hyperscaler capex disclosures for life sciences verticals. Bottom-up segment sizing triangulated against top-down market envelope checks across technology, end-user, and application dimensions.
Scenario-bracketing framed the analytical approach, with base, upside, and downside cases tested against GPU supply constraints, regulatory timeline slippage, and biotechnology funding environment shifts. Modeled dimensions spanned product type, technology layer, end-user sophistication, application compliance burden, and regional regulatory cluster. CAGRs derived from segment-level growth rate synthesis anchored to observable adoption inflections in pharmaceutical computational-first restructuring and agricultural breeding digitization. Forecast inputs incorporated instrument refresh cycle elongation and machine learning application penetration curves.
Macroeconomic conditions sit as an overlay; deviation in biotechnology venture funding availability, cloud infrastructure pricing, or trade policy affecting GPU cluster procurement would shift the trajectory. Forecasts reflect documented assumptions about regulatory convergence between FDA and EMA digital-evidence standards and cloud migration pace among academic consortia. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
BOD Incubator Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Global Biomarker Technologies Market