
 Asia-Pacific Exosome Research Products Market | 2026-2036
Asia-Pacific Exosome Research Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Exosome Research Products Market Outlook
The capability gap between instrument-heavy platforms and reagent-only suppliers is bifurcating competitive dynamics across the region. Thermo Fisher Scientific leverages its integrated workflow portfolio to sustain premium positioning in characterization systems. Lonza Group anchors its presence through specialized bioprocessing services for exosome manufacturing scale-up. QIAGEN competes on nucleic acid extraction kits that dominate upstream isolation workflows in academic settings.
Asia-Pacific exosome research products encompass reagents, instruments, and services designed to isolate, characterize, and analyze extracellular vesicles ranging from 30 to 150 nanometers in diameter, primarily serving biomarker discovery and therapeutic development pipelines. These products employ ultracentrifugation, size-exclusion chromatography, and nanoparticle tracking analysis to purify and quantify exosomes for downstream genomic, proteomic, and functional studies. Reagents and kits currently occupy the largest revenue share due to recurring consumable demand across high-throughput screening programs, while instruments for advanced characterization command higher per-unit margins despite slower replacement cycles. Services tied to custom exosome engineering and GMP-compliant manufacturing represent the fastest-expanding category as pharmaceutical sponsors outsource vector production for clinical-stage programs.
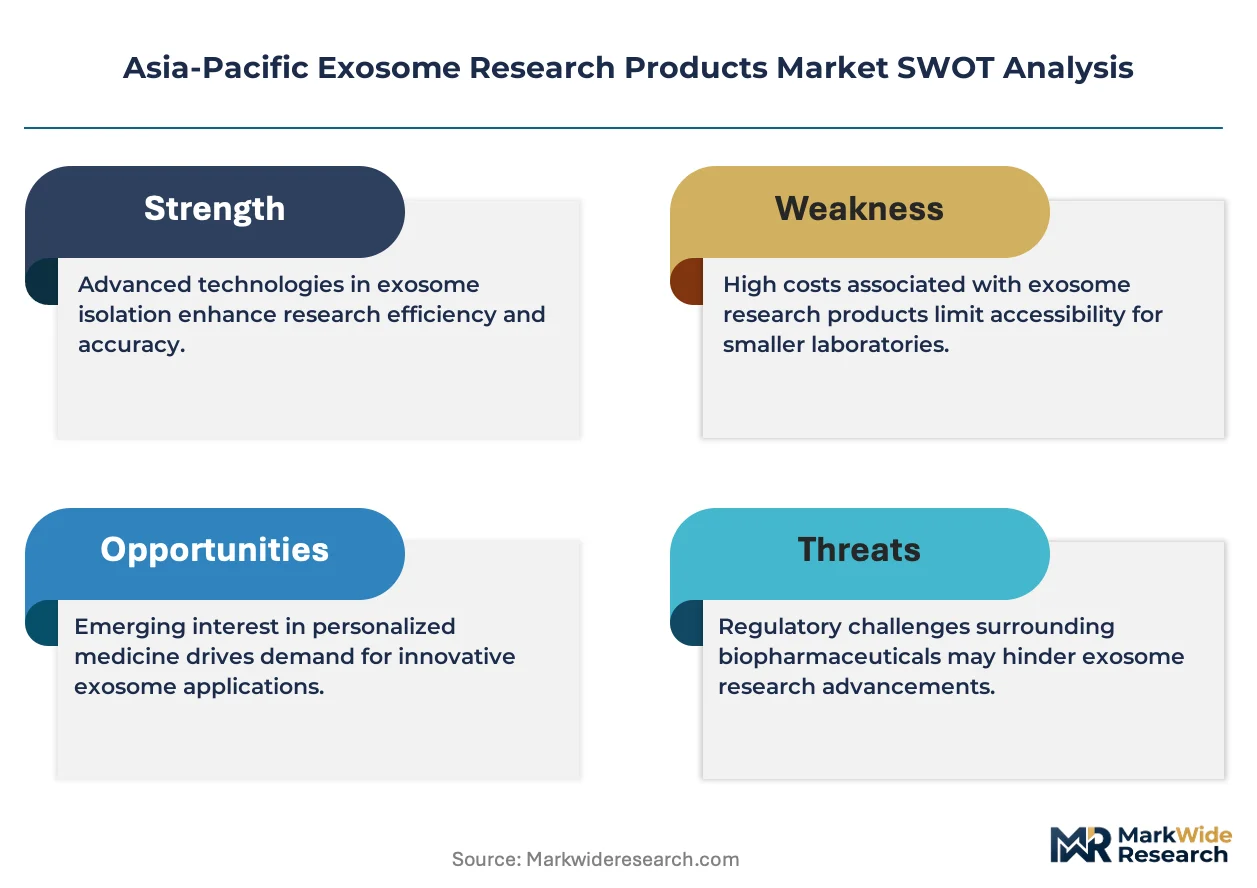
CDSCO in India, PMDA in Japan, and China's NMPA are each developing distinct regulatory pathways for exosome-derived therapeutics and diagnostics, creating fragmented compliance requirements that favor suppliers with multi-jurisdictional quality certifications. The EU AI Act and REACH-equivalent frameworks under discussion in several Asia-Pacific jurisdictions will further shape data integrity and material safety standards for automated analysis platforms. Stakeholders must monitor divergent classification decisions between cell therapy and biologic routes across national regulators to anticipate product registration timelines and capital allocation priorities.
Market Dynamics
The Asia-Pacific exosome research products market is experiencing a structural compression as CDSCO, PMDA, and NMPA each tighten quality benchmarks for extracellular vesicle therapeutics, forcing suppliers to pursue multi-jurisdictional certifications that fragment compliance costs and delay product registration timelines.
Growth Catalysts
- Biopharma outsourcing surge:Pharmaceutical sponsors across China and Japan are contracting specialized bioprocessing services for GMP-compliant exosome manufacturing, expanding the services segment faster than hardware or consumables.
- CDSCO diagnostic pathway development:India's national pharmaceutical regulator is establishing clearer classification frameworks for exosome-derived liquid biopsy products, reducing regulatory ambiguity that previously stalled clinical translation.
- Shanghai-Shenzhen cluster concentration:China's biotech hubs are aggregating talent, capital, and CDMO infrastructure for exosome engineering, creating self-reinforcing ecosystems that pull in upstream reagent demand.
Market Restraints
- Ultracentrifugation consumable cost volatility:High-purity sucrose gradients and specialized rotors for density-based isolation carry input costs that scale non-linearly with throughput, pricing out smaller academic labs.
- Japanese PMDA biologic-classification friction:Exosome therapeutics face extended review timelines when routed through cell therapy rather than biologic pathways, creating regulatory uncertainty that dampens sponsor investment.
- Antibody-based capture kit substitution:Emerging affinity magnetic bead platforms from adjacent cell separation markets threaten displacement of traditional precipitation reagents in standardized workflows.
Strategic Opportunities
- Southeast Asia underpenetration:Singapore and Australia's research infrastructure remains underserved by localized exosome service providers, creating first-mover advantages for CDMOs establishing regional GMP facilities.
- AI-integrated nanoparticle tracking convergence:Machine learning algorithms paired with NTA hardware are enabling real-time exosome subpopulation classification, opening premium pricing tiers for characterization instruments.
- China NMPA innovation fast-track:The regulator's breakthrough therapy designation for extracellular vesicle-based cancer diagnostics compresses approval timelines, incentivizing sponsors to prioritize the Chinese market for first-in-region launches.
Industry Challenges
- EV isolation standardization deficits:No unified International Society for Extracellular Vesicles protocol has achieved regulatory endorsement across CDSCO, PMDA, and NMPA jurisdictions, forcing suppliers to validate multiple workflow variants.
- GMP facility capex intensity:Closed-system bioreactors and aseptic filling lines for clinical-grade exosome production require capital commitments that strain mid-scale service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Exosome Research Products Market |
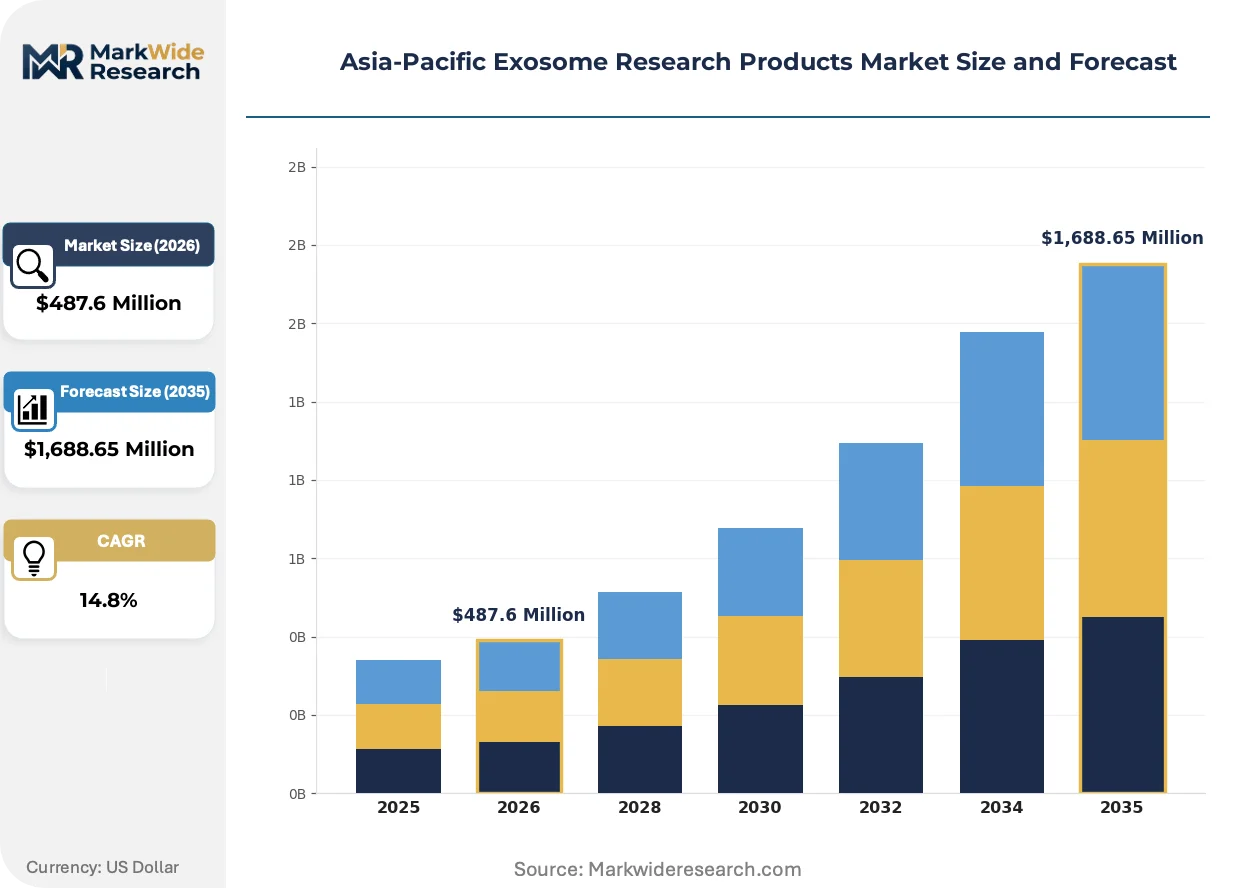
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,688.65 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Services Technology: Isolation, Characterization, Analysis, Delivery Application Area: Biomarker Discovery, Drug Delivery, Diagnostics, Therapeutics End User: Academic Institutions, Research Laboratories, Pharmaceutical Companies, Biotech Firms |
| Companies Covered | QIAGEN, Lonza Group, Thermo Fisher Scientific, FUJIFILM Holdings, Danaher Corporation, Bio-Techne, Miltenyi Biotec, HansaBioMed Life Sciences, System Biosciences, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Exosome Research Products Market Strategic Shifts
Workflow integration and automation are compressing manual handling steps in exosome isolation, while regulatory data integrity requirements and procurement centralization are reshaping how products reach end-users across academic and pharmaceutical segments.
Microfluidic chip-based isolation platforms are miniaturizing exosome purification from bench-scale ultracentrifugation to cartridge-format processing. Biotech startups in China's Yangtze River Delta are piloting these systems for point-of-care diagnostic development. The technology is miniaturizing footprint requirements and enabling distributed processing nodes that bypass centralized core facility bottlenecks.
PMDA's 2023 guidance on extracellular vesicle quality attributes is mandating expanded release testing for particle concentration, morphology, and surface marker profiles. Japanese CDMOs are retrofitting analytical laboratories to accommodate multi-parameter flow cytometry and single-particle interferometric imaging. The regulation is accelerating instrument sales for advanced characterization while compressing margins on basic reagent kits that lack accompanying validation data packages.
Consolidated procurement through national research infrastructure programs is displacing individual laboratory purchasing across Australian and South Korean academic institutions. University consortia are negotiating framework agreements with preferred suppliers for multi-year reagent supply, bundling characterization services and technical support. This concentration is most visible in Australia's National Collaborative Research Infrastructure Strategy, where centralized funding pools are redirecting spend toward integrated workflow providers.
Asia-Pacific Exosome Research Products Market Segmentation
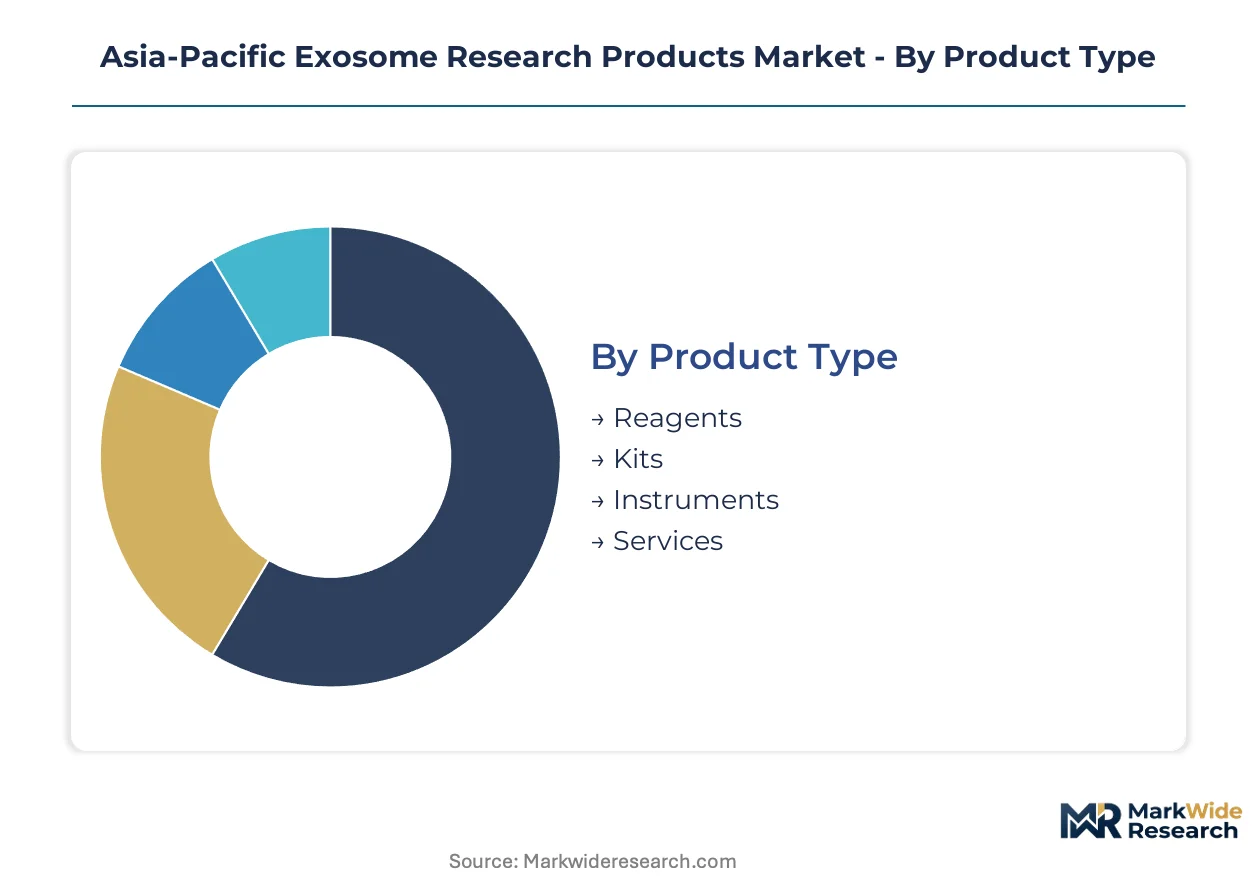
Segmentation in the Asia-Pacific exosome research products market reveals how regulatory fragmentation across CDSCO, PMDA, and NMPA jurisdictions shapes product development priorities and commercial positioning. Suppliers must align their portfolios with divergent quality benchmarks that favor certain technologies over others in specific national markets.
Product Type:
CDSCO's tightening quality benchmarks for extracellular vesicle therapeutics in India are elevating demand for validated reagent kits with accompanying documentation packages, while PMDA's release testing mandates in Japan are pulling instrument sales toward multi-parameter characterization systems.
- Reagents:Density-gradient media, precipitation polymers, and buffer formulations constitute the recurring consumable base for ultracentrifugation and chemical isolation workflows. Academic laboratories across China's Shanghai-Shenzhen corridor account for concentrated demand, though sucrose gradient cost volatility is pricing out smaller institutions.
- Kits:Pre-formulated extraction systems bundling reagents, protocols, and quality controls are displacing home-brewed workflows in regulated environments. Japanese pharmaceutical sponsors favor these for PMDA-compliant manufacturing, where standardized documentation accelerates regulatory submissions.
- Instruments:Nanoparticle tracking analyzers, flow cytometers, and interferometric imaging systems for particle quantification and morphology assessment.
- Services:Custom exosome engineering, GMP-compliant manufacturing, and analytical validation for clinical-stage programs.
Reagents handle the majority of throughput; services are the fastest mover on share.
Technology:
Cost tier differentiation separates gold-standard ultracentrifugation from emerging microfluidic alternatives, with premium characterization technologies commanding margins that sustain instrument vendor profitability despite elongated replacement cycles.
- Isolation:Ultracentrifugation remains the benchmark for high-purity exosome recovery, though size-exclusion chromatography and affinity capture are gaining traction in high-throughput screening environments. China's biotech clusters are piloting microfluidic chip-based systems that miniaturize processing footprints for point-of-care diagnostic development.
- Characterization:Multi-parameter flow cytometry and single-particle interferometric imaging are becoming mandatory under PMDA's expanded release testing requirements. Japanese CDMOs are retrofitting analytical laboratories to accommodate these platforms, compressing margins on basic reagent kits lacking validation data packages.
- Analysis:Proteomic, genomic, and functional assays for downstream exosome cargo interrogation.
- Delivery:Engineering platforms for exosome loading, surface modification, and targeted tissue distribution.
Isolation handles the majority of throughput; characterization is climbing the fastest on share.
Application Area:
Customer type stratification distinguishes exploratory academic research from regulated pharmaceutical development, with divergent tolerance for protocol standardization and documentation rigor.
- Biomarker Discovery:Liquid biopsy development for cancer and neurodegenerative disease detection drives upstream reagent consumption. India's CDSCO is establishing clearer classification frameworks for exosome-derived diagnostics, reducing regulatory ambiguity that previously stalled clinical translation.
- Drug Delivery:Exosome engineering for targeted therapeutic cargo transport is attracting pharmaceutical outsourcing contracts. Bioprocessing services for GMP-compliant manufacturing are expanding fastest in China and Japan as sponsors seek to de-risk internal production investments.
- Diagnostics:Clinical-grade exosome-based assays for disease detection and monitoring.
- Therapeutics:Cell-free exosome therapies routed through biologic or cell therapy regulatory pathways.
Biomarker discovery handles the majority of throughput; drug delivery is gaining share fastest.
End User:
Geographic concentration within the Asia-Pacific region creates self-reinforcing ecosystems where talent aggregation and capital availability pull in specialized supplier presence.
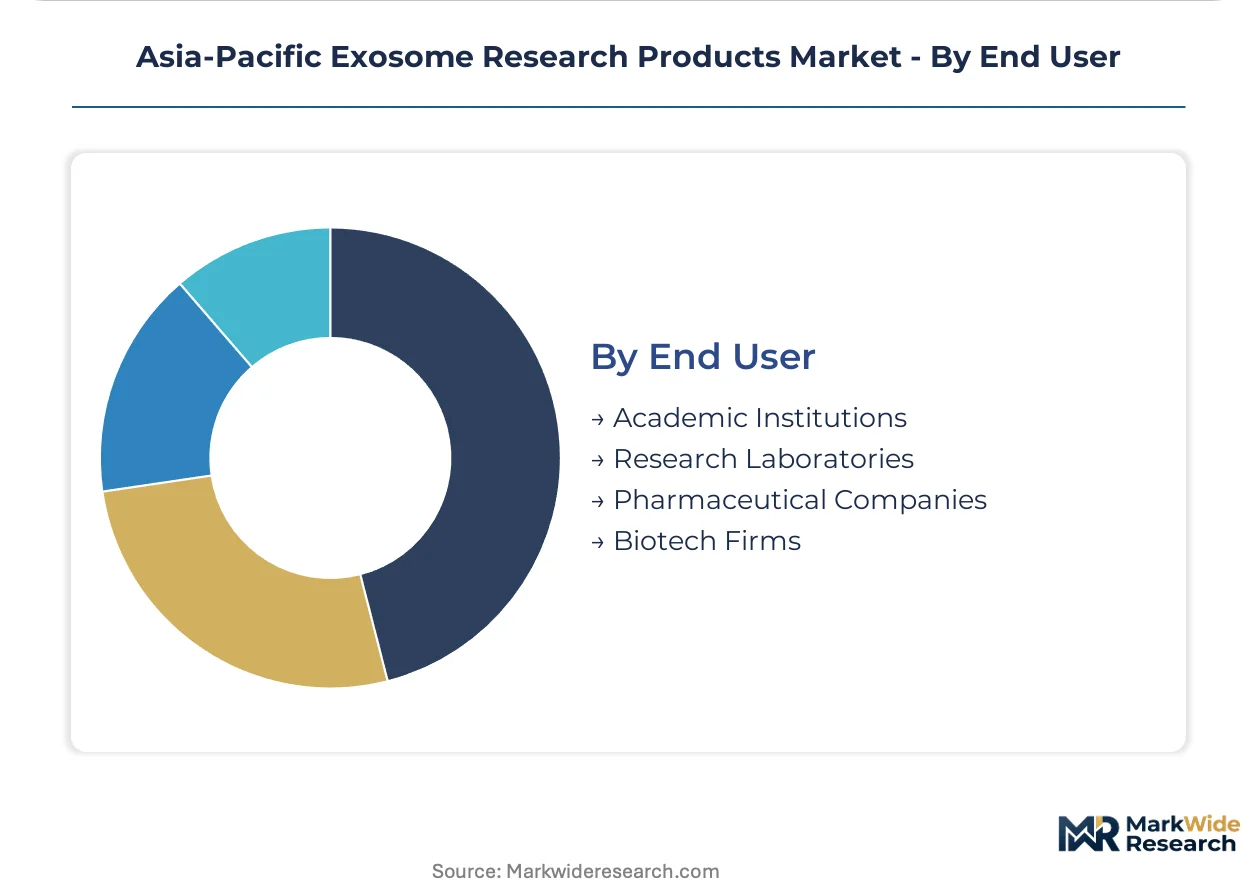
- Academic Institutions:Consolidated procurement through national research infrastructure programs is displacing individual laboratory purchasing across Australian and South Korean universities. Australia's National Collaborative Research Infrastructure Strategy bundles multi-year reagent supply agreements with integrated workflow providers.
- Pharmaceutical Companies:Sponsors across China and Japan are contracting specialized bioprocessing services for GMP-compliant exosome manufacturing, prioritizing suppliers with multi-jurisdictional quality certifications that satisfy fragmented CDSCO, PMDA, and NMPA requirements.
- Research Laboratories:Government and private institutes conducting exploratory exosome biology studies.
- Biotech Firms:Venture-backed startups developing proprietary exosome engineering platforms.
Academic institutions handle the majority of throughput; pharmaceutical companies are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia-Pacific exosome research products market. Academic laboratories in India and Southeast Asia prioritize low-cost precipitation reagents, while Japanese pharmaceutical sponsors absorb premium pricing for PMDA-compliant characterization systems.
China
Shanghai and Shenzhen biotech clusters aggregate venture capital and CDMO infrastructure for exosome engineering. NMPA's breakthrough therapy designation for extracellular vesicle-based cancer diagnostics compresses approval timelines. The Yangtze River Delta hosts pilot programs for microfluidic chip-based isolation platforms.
Japan
Pharmaceutical sponsors contract specialized bioprocessing services for GMP-compliant exosome manufacturing. PMDA's 2023 guidance mandates expanded release testing for particle concentration and morphology. Tokyo-Osaka corridor CDMOs retrofit analytical laboratories for multi-parameter flow cytometry.
India
Academic institutions drive demand for low-cost ultracentrifugation reagents despite sucrose gradient cost volatility. CDSCO is establishing clearer classification frameworks for exosome-derived liquid biopsy products. Bangalore and Hyderabad research clusters concentrate biomarker discovery programs.
South Korea
Consolidated procurement through national research infrastructure programs displaces individual laboratory purchasing. MFDS alignment with international extracellular vesicle quality standards shapes import requirements. Seoul metropolitan area universities negotiate framework agreements for multi-year reagent supply.
Australia
Specialized exosome service providers remain underpenetrated relative to research infrastructure investment. TGA consultation papers signal forthcoming alignment with PMDA and FDA extracellular vesicle guidance. Sydney and Melbourne institutions participate in National Collaborative Research Infrastructure Strategy funding pools.
Asia-Pacific Exosome Research Products Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific exosome research products market. Thermo Fisher Scientific and Danaher Corporation leverage workflow integration to capture premium positioning in characterization systems. Lonza Group and Miltenyi Biotec anchor the bioprocessing services archetype. Specialists including QIAGEN and Bio-Techne dominate nucleic acid extraction kits for upstream isolation. Competitive moves center on multi-jurisdictional quality certification pursuit and AI-integrated nanoparticle tracking convergence.
Within the integrated workflow tier, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven portfolio breadth. Lonza Group occupies a position representing specialized bioprocessing services for GMP-compliant manufacturing. Among reagent-focused specialists, QIAGEN anchors nucleic acid extraction dominance in academic settings. These archetypes reflect divergent responses to CDSCO, PMDA, and NMPA regulatory fragmentation.
| Leading Market Players |
|---|
| QIAGEN |
| Lonza Group |
| Thermo Fisher Scientific |
| FUJIFILM Holdings |
| Danaher Corporation |
| Bio-Techne |
| Miltenyi Biotec |
| HansaBioMed Life Sciences |
| System Biosciences |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation agreements with CDMOs in China's Yangtze River Delta lock in multi-year access to GMP-compliant bioreactors while capping per-batch processing costs for pharmaceutical sponsors navigating fragmented PMDA and NMPA quality benchmarks.
Pricing Analysis
Service contract extensions and technical support bundles drive lifetime value beyond initial instrument sales. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-validated characterization systems from basic academic reagents. Cost compression in precipitation-based isolation kits intensifies as Chinese manufacturers scale polymer chemistry production. Academic laboratories in India exhibit highest price sensitivity, while Japanese pharmaceutical sponsors absorb premium positioning for compliant manufacturing services.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for European-sourced density-gradient media and specialized analytical consumables. Manufacturing concentrates in China, Japan, and South Korea for microfluidic chips, chromatography resins, and flow cytometry components. Raw material dependencies rest on high-purity sucrose, affinity magnetic beads, and synthetic polymer formulations. Single-source vulnerability permeates ultracentrifugation rotor production. Distribution runs through authorized distributors serving academic consortia and direct sales teams targeting pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microfluidic miniaturization and AI-integrated nanoparticle tracking are compressing development timelines for point-of-care diagnostics, creating a high-growth disruption window as NMPA fast-tracks extracellular vesicle-based cancer assays.
For Market Incumbents: Shield installed base revenue by embedding predictive maintenance contracts with NTA hardware users facing PMDA's expanded release testing mandates. Deepen backward integration into affinity bead chemistry production to offset substitution pressure from adjacent cell separation markets. Prioritize multi-jurisdictional quality certification investments that satisfy divergent CDSCO, PMDA, and NMPA documentation requirements. For New Entrants and Emerging Players: Lead with AI-enhanced characterization software licensing to pharmaceutical sponsors retrofitting Tokyo-Osaka corridor CDMOs for compliance. Australia's underpenetrated service provider landscape offers lowest competitive density for GMP facility establishment. Target biomarker discovery outsourcing contracts from Bangalore and Hyderabad academic clusters seeking cost-competitive alternatives to ultracentrifugation workflows. For Investors and Strategic Acquirers: Specialized bioprocessing service providers with existing PMDA inspection history command scarcity premiums as pharmaceutical outsourcing accelerates. Long-term viability hinges on exposure to clinical-stage program pipelines rather than exploratory academic demand. Monitor NMPA breakthrough therapy designation announcements as volume inflection signals for Chinese market prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Quality Certification | PMDA, CDSCO, and NMPA alignment accelerates product registration timelines across Asia-Pacific pharmaceutical accounts. |
| AI-Integrated Nanoparticle Tracking Convergence | Machine learning algorithms paired with NTA hardware enable real-time exosome subpopulation classification for premium pricing. |
| GMP Manufacturing Scale-Up | Closed-system bioreactor investments capture pharmaceutical outsourcing contracts for clinical-grade exosome production. |
| Microfluidic Chip Platform Development | Cartridge-format processing miniaturizes footprints for point-of-care diagnostic applications in China's Yangtze River Delta. |
| Consolidated Procurement Framework Participation | Australia's National Collaborative Research Infrastructure Strategy bundles multi-year reagent supply with integrated workflow providers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with exosome manufacturing executives, regulatory affairs specialists at CDMOs, academic laboratory procurement managers, and pharmaceutical sponsor outsourcing leads; and secondary validation against NMPA drug master files, PMDA consultation documents, CDSCO classification guidelines, and MFDS import registration databases. Bottom-up demand modeling triangulated against top-down market sizing anchored instrument vendor revenue disclosures and service provider capacity announcements.
Across the analysis window, projections integrated product type segmentation by reagents, kits, instruments, and services; technology tiers spanning isolation, characterization, analysis, and delivery; application area splits between biomarker discovery and drug delivery; and end-user stratification across academic institutions and pharmaceutical companies. CAGRs derived from weighted average growth assumptions applied to segment-level addressable markets, calibrated against NMPA approval velocity and CDSCO pathway development progress.
The analysis sits within stated boundaries; outcomes outside sustained regulatory harmonization progress or abrupt shifts in pharmaceutical R&D capital allocation would require recalibration. Forecasts reflect assumptions regarding CDSCO diagnostic framework finalization, PMDA biologic-classification route clarity, and NMPA breakthrough designation utilization rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Latin America Digital Biology Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
Nano-Silicon Drug Delivery Platform Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
BOD Incubator Market
Biomedical Technology
Asia-Pacific Digital PCR Market