
 Bacteriophage Market | 2026-2036
Bacteriophage Market Size, Share, and Industry Trends Forecast 2026-2036
Bacteriophage Market Analysis
The bacteriophage market is restructuring around a sharp split between engineered phage platforms commanding premium pricing and natural phage commodities facing margin compression. Locus Biosciences leverages CRISPR-enhanced phage engineering to sustain technology leadership in precision antibacterial therapies. Eliava BioPreparations anchors legacy natural phage production from its Tbilisi heritage facility, while Pherecydes Pharma competes through proprietary manufacturing scale for hospital-grade phage cocktails.
Bacteriophages are viruses that infect and lyse specific bacterial hosts, typically comprising a protein capsid enclosing a DNA or RNA genome of 20 to 200 kilobases, with tail fiber structures determining host-range specificity. Their primary commercial purpose centers on targeted bacterial elimination without disrupting human microbiomes, distinguishing them from broad-spectrum antibiotics. Engineered phages command the fastest expansion trajectory due to programmable host range and enhanced lytic kinetics, while natural phage cocktails retain entrenched positions in food safety applications where regulatory pathways are established. Intravenous delivery dominates clinical revenue pools, though inhalation formulations are gaining traction in respiratory infection protocols.
The FDA's QIDP framework and EMA's adaptive pathways for antimicrobials shape product development incentives and accelerated review timelines for novel phage therapies. REACH compliance and ISO 13485 certification requirements govern manufacturing standards for European market access and medical device-quality production systems. Stakeholders must monitor regulatory divergence between adaptive licensing models and traditional pharmaceutical approval frameworks as investment priorities shift toward engineered platforms.
Market Dynamics
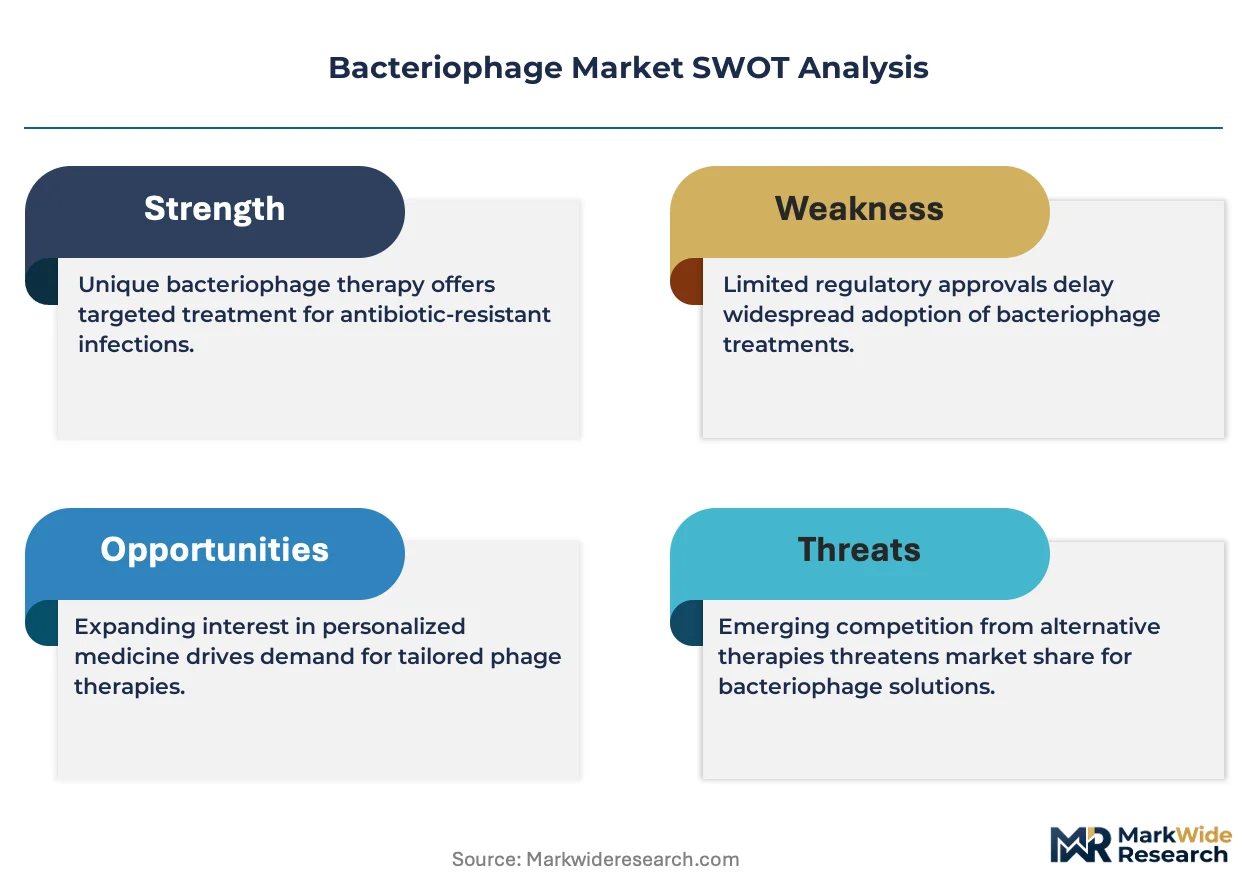
The bacteriophage market is bifurcating around engineered precision platforms versus legacy natural phage production, with CRISPR-enhanced engineering commanding development capital while natural phage cocktails face commoditization pressure in established food safety channels.
Growth Catalysts
- FDA Qualified Infectious Disease Product designation:The accelerated review framework compresses clinical trial timelines and reduces regulatory uncertainty for developers targeting antibiotic-resistant infections. Hospital formulary committees increasingly prioritize QIDP-backed therapies for formulary inclusion.
- Respiratory infection protocols:Inhalation delivery formulations are expanding addressable patient populations beyond intravenous administration, opening cystic fibrosis and ventilator-associated pneumonia treatment pathways previously inaccessible to phage therapy.
- United States specialized center proliferation:Dedicated phage therapy centers in major metropolitan hospital systems are building clinical infrastructure and reimbursement precedent that reduces adoption friction for referring physicians.
Market Restraints
- High-purity manufacturing inputs:Pharmaceutical-grade fermentation media and endotoxin removal systems impose fixed cost structures that scale poorly for personalized phage cocktails, compressing margins on small-batch production.
- Host-range specificity limitations:Natural phage narrow bacterial targeting requires empirical matching against patient isolates, creating diagnostic bottlenecks and treatment delays that broad-spectrum antibiotics circumvent.
- EMA adaptive pathway uncertainty:Conditional marketing authorization frameworks for antimicrobials lack precedent for phage products, creating investor hesitation around European market entry timelines and revenue recognition.
Strategic Opportunities
- Companion diagnostic convergence:Rapid bacterial identification platforms paired with pre-screened phage libraries enable same-day personalized therapy selection, collapsing the current multi-week matching process.
- United Kingdom NHS innovation procurement:The Accelerated Access Collaborative pathway creates dedicated reimbursement channels for novel antimicrobials, reducing commercialization risk for first movers in national health systems.
- Agricultural microbiome applications:Livestock gut health and crop protection segments remain underpenetrated by engineered phage platforms, offering volume scale absent the clinical regulatory burden of human therapeutics.
Industry Challenges
- Phage engineering talent scarcity:Synthetic biology expertise combining virology with CRISPR system design concentrates in academic centers, constraining platform expansion timelines for commercial developers.
- ISO 13485 certification timelines:Medical device-quality manufacturing system validation for engineered phage production requires 18-24 month implementation cycles, delaying product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacteriophage Market |
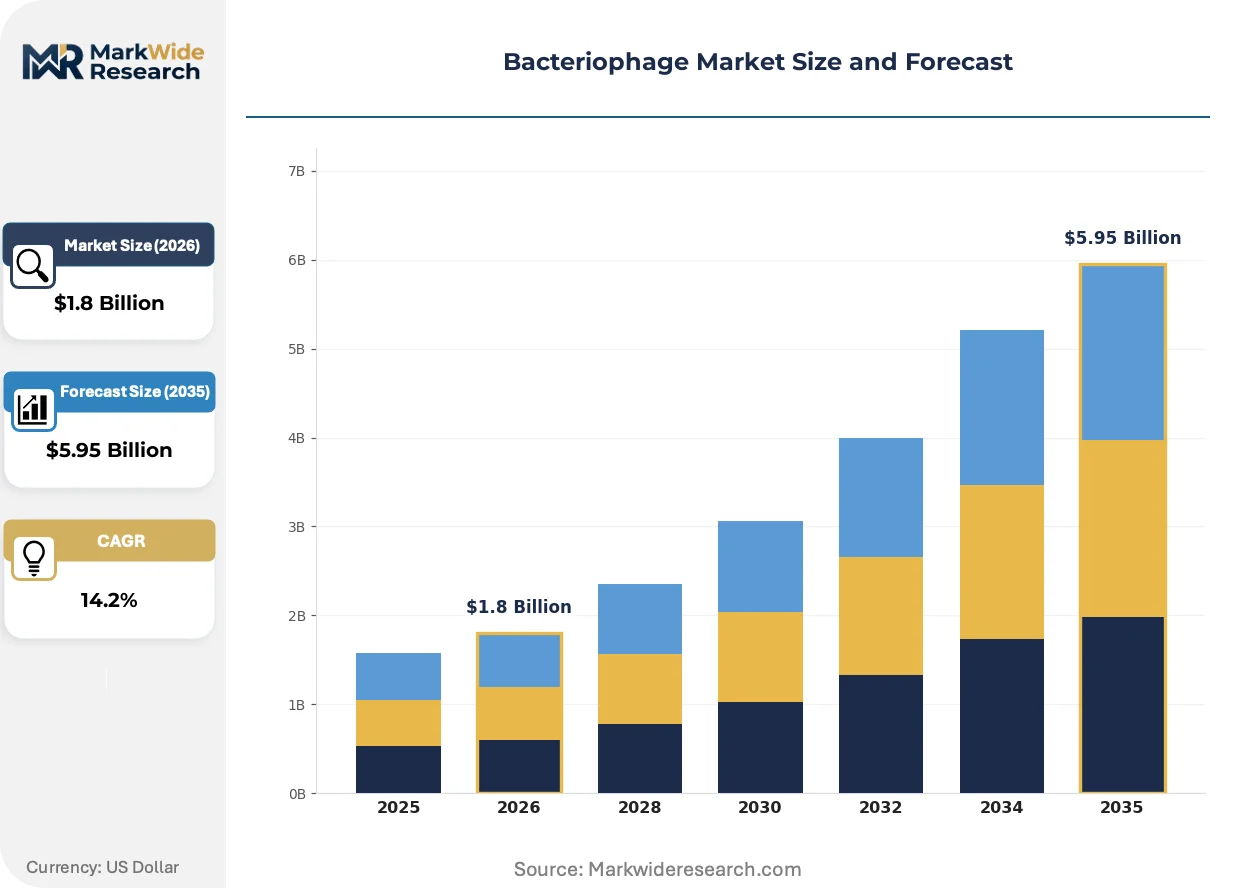
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
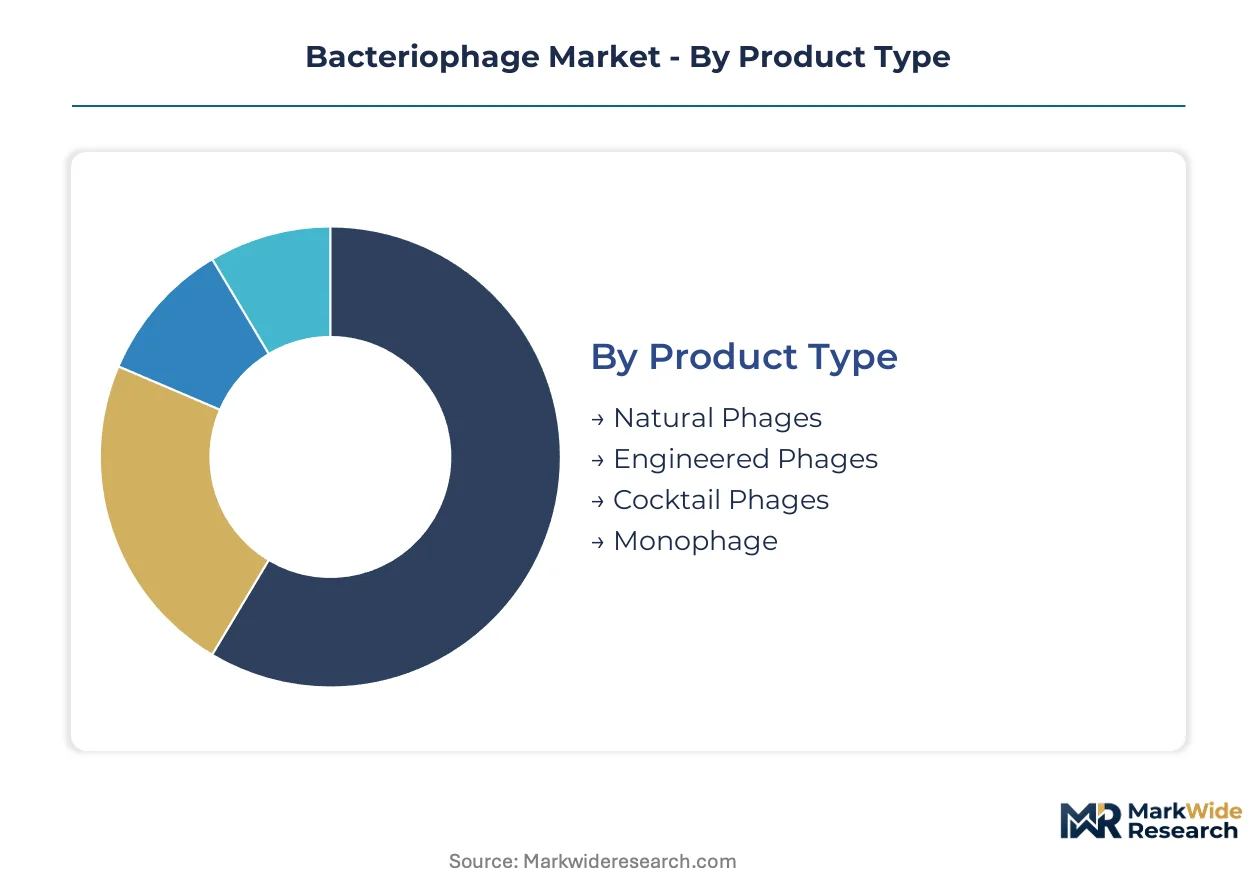
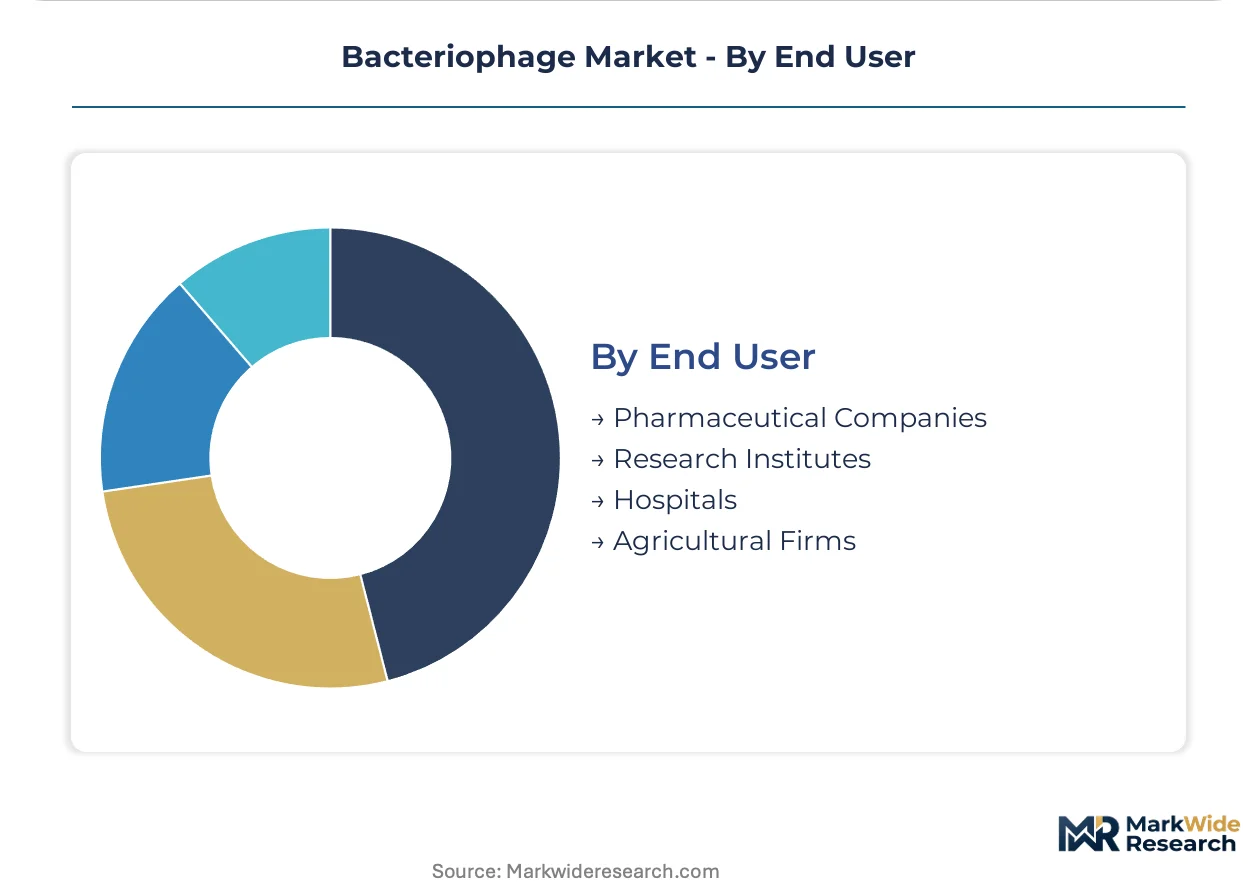
| Segmentation | Product Type: Natural Phages, Engineered Phages, Cocktail Phages, Monophage Application: Food Safety, Agriculture, Veterinary Medicine, Clinical Therapy Delivery Mode: Intravenous, Intra-abdominal, Inhalation, Oral End User: Pharmaceutical Companies, Research Institutes, Hospitals, Agricultural Firms |
| Companies Covered | Locus Biosciences, Phagelux, NPO Microgen, Eliava BioPreparations, Micreos, Proteon Pharmaceuticals, Armata Pharmaceuticals, Pherecydes Pharma, Intralytix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacteriophage Market Emerging Trajectories
CRISPR-Cas systems are rewiring competitive advantage in antibacterial therapeutics, enabling programmable host-range expansion and resistance-evasion mechanisms that natural phage cocktails cannot replicate.
CRISPR-enhanced phage engineering is integrating programmable DNA targeting modules into lytic bacteriophage genomes, enabling simultaneous bacterial killing and resistance gene disruption. Academic medical centers in the United States and Germany are adopting these platforms for compassionate-use protocols ahead of commercial availability. The technology is integrating precision genome editing with established phage biology, compressing development timelines for therapies against multidrug-resistant pathogens.
REACH compliance requirements for novel biological substances are tightening manufacturing disclosure standards for European market access, forcing developers to document full supply chain substance flows. The regulation is accelerating investment in closed-system bioreactor infrastructure to reduce environmental release risk documentation burdens. Engineered phage platforms with defined genetic modifications face stricter substance registration pathways than natural phage cocktails, creating divergent compliance cost structures across product categories.
Hospital procurement committees are consolidating antibacterial therapy purchasing around formulary pre-approval systems, displacing physician-directed compassionate use channels that historically enabled phage therapy access. The shift is compressing vendor qualification timelines and demanding standardized efficacy documentation that natural phage suppliers struggle to provide. This behavioral pivot is most pronounced in United States academic medical centers building dedicated antimicrobial stewardship programs.
Bacteriophage Market Segmentation
Phage therapy commercialization demands precise segment targeting. Product engineering intensity, regulatory pathway complexity, and reimbursement infrastructure vary dramatically across application settings and delivery modalities.
Product Type:
Standardization decreases and customization intensity increases as products move from natural isolates to precision-engineered platforms.
- Natural Phages:Wild-type bacteriophage isolates harvested from environmental sources carry undefined genomic heterogeneity. Eliava BioPreparations and legacy Eastern European suppliers anchor production in Tbilisi heritage facilities. Demand concentrates in food safety applications where regulatory pathways are established and clinical trial investments are unnecessary.
- Engineered Phages:CRISPR-Cas enhanced platforms integrate programmable DNA targeting modules for host-range expansion and resistance evasion. Locus Biosciences and academic medical centers in the United States and Germany drive development capital toward these precision antibacterial therapies. FDA QIDP designation accelerates review timelines for engineered candidates targeting multidrug-resistant pathogens.
- Cocktail Phages:Multi-strain formulations combine complementary host-range specificities to broaden bacterial coverage. Hospital procurement committees increasingly demand standardized efficacy documentation that empirical cocktail matching struggles to provide.
- Monophage:Single-strain products enable precise diagnostic matching against identified pathogens. Companion diagnostic convergence is collapsing multi-week matching processes into same-day therapy selection.
Most installed capacity flows through Natural Phages. Expansion is steepest in Engineered Phages.
Application:
Regulatory burden intensity and reimbursement infrastructure maturity determine commercialization feasibility across use cases.
- Clinical Therapy:Hospital-based intravenous administration targets antibiotic-resistant infections with FDA QIDP-backed development timelines. United States specialized phage therapy centers in major metropolitan hospital systems are building clinical infrastructure and reimbursement precedent.
- Food Safety:Surface decontamination and preservation applications carry established regulatory pathways without clinical trial requirements. Natural phage cocktails retain entrenched positions where margin compression pressures commodity producers.
- Agriculture:Livestock gut health and crop protection segments remain underpenetrated by engineered platforms. Volume scale is accessible absent the clinical regulatory burden of human therapeutics.
- Veterinary Medicine:Companion animal and production animal therapeutic applications bridge food safety and clinical regulatory frameworks. EMA adaptive pathway uncertainty creates investor hesitation around European market entry timelines.
Revenue concentration sits with Clinical Therapy. Agricultural microbiome applications are climbing the fastest.
Delivery Mode:
Route selection constrains addressable patient populations and manufacturing complexity simultaneously.
- Intravenous:Direct bloodstream administration dominates hospital revenue pools for systemic infections. ISO 13485 certification requirements for medical device-quality production impose 18-24 month implementation cycles on sterile injectable manufacturing.
- Inhalation:Aerosolized formulations are expanding cystic fibrosis and ventilator-associated pneumonia treatment pathways. Respiratory infection protocols previously inaccessible to phage therapy are opening through nebulized delivery development.
- Oral:Gastrointestinal targeting leverages acid-stable phage encapsulation for enteric infections. Formulation stability through gastric passage limits strain selection and dosing reliability.
- Intra-abdominal:Localized delivery targets peritonitis and surgical site infections with reduced systemic exposure. Surgical administration requires operating room integration and sterile field protocols.
Hospital formulary penetration runs deepest through Intravenous. Inhalation is gaining share fastest among emerging modalities.
End User:
Purchasing sophistication and technical capability requirements segment the customer base sharply.
- Hospitals:Academic medical centers with dedicated antimicrobial stewardship programs are consolidating antibacterial therapy purchasing around formulary pre-approval systems. United States metropolitan hospital systems building specialized phage therapy centers reduce adoption friction for referring physicians.
- Pharmaceutical Companies:Platform licensing and co-development partnerships transfer engineered phage capabilities through structured collaboration agreements. Synthetic biology expertise scarcity in CRISPR-enhanced virology concentrates deal-making around academic center spinouts.
- Research Institutes:Compassionate-use protocol sponsorship and preclinical validation studies drive demand for characterized phage libraries. REACH compliance documentation for novel biological substances tightens supply chain disclosure standards for European access.
- Agricultural Firms:Volume procurement of natural phage products for livestock and crop applications operates through established distribution channels. Price sensitivity and regulatory pathway simplicity favor commodity suppliers over precision platform developers.
Procurement volume concentrates through Hospitals. Partnership activity is expanding most quickly with Pharmaceutical Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic biology talent clusters in Boston and San Diego anchor North American phage engineering capacity, while Tbilisi's Soviet-era phage research infrastructure sustains Eastern European natural phage production.
United States
FDA QIDP designation accelerates clinical trial timelines for developers targeting antibiotic-resistant infections. Specialized phage therapy centers in metropolitan hospital systems are building reimbursement precedent and clinical infrastructure. Boston and San Diego biotech clusters concentrate CRISPR-enhanced phage engineering talent and venture capital flows.
Germany
EMA adaptive pathway uncertainty creates investor hesitation around phage therapy commercialization timelines. Academic medical centers in Berlin and Munich adopt engineered phage platforms for compassionate-use protocols. REACH compliance requirements tighten manufacturing disclosure standards for novel biological substances entering European markets.
Georgia
Eliava BioPreparations anchors legacy natural phage production from Tbilisi heritage facilities established during Soviet research programs. The country's national pharmaceutical regulator maintains simplified pathways for phage products with decades of clinical use documentation. Tbilisi's specialized phage institute supplies empirical cocktail formulations to international buyers.
France
Pherecydes Pharma competes through proprietary manufacturing scale for hospital-grade phage cocktails. ANSM oversees conditional marketing authorization frameworks for novel antimicrobials lacking precedent for phage-specific pathways. Lyon and Paris hospital networks consolidate antibacterial therapy purchasing around formulary pre-approval systems.
United Kingdom
NHS Accelerated Access Collaborative pathway creates dedicated reimbursement channels for novel antimicrobials. The country's national pharmaceutical regulator evaluates phage therapies through adaptive licensing models diverging from traditional pharmaceutical frameworks. London academic medical centers build antimicrobial stewardship programs displacing physician-directed compassionate use channels.
Bacteriophage Market Vendor Landscape
Top-tier vendors anchor engineered precision platforms, while commodity natural phage suppliers face margin compression in established food safety channels. The vendor base splits between CRISPR-enhanced developers commanding premium pricing and legacy Eastern European producers sustaining volume through heritage infrastructure. Three strategic archetypes dominate: synthetic biology platform companies, Soviet-era natural phage manufacturers, and hospital-focused cocktail suppliers. Competitive moves concentrate on companion diagnostic convergence and ISO 13485 certification acceleration.
Within the engineered platform tier, Locus Biosciences represents CRISPR-enhanced precision antibacterial development. Eliava BioPreparations exemplifies heritage natural phage production anchored in Tbilisi research infrastructure. Pherecydes Pharma occupies a position bridging manufacturing scale with hospital-grade cocktail standardization.
| Leading Market Players |
|---|
| Locus Biosciences |
| Phagelux |
| NPO Microgen |
| Eliava BioPreparations |
| Micreos |
| Proteon Pharmaceuticals |
| Armata Pharmaceuticals |
| Pherecydes Pharma |
| Intralytix |
| Others |
Supply Flow & Price Mechanics
Captive fermentation infrastructure in Georgia and proprietary bioreactor systems in France anchor supply positions for natural phage cocktails and hospital-grade formulations respectively, with backward integration into endotoxin removal technology conferring pricing power on developers of engineered precision platforms. This integration choice separates premium-tier CRISPR-enhanced products from commodity natural phage suppliers facing margin compression in established food safety channels.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes engineered phage platforms commanding project-based licensing with companion diagnostic integration from natural phage commodities transacted on per-unit spot terms. Price differentiation hinges on FDA QIDP certification tier and ISO 13485 manufacturing grade, with premium tiers capturing value from resistance-evasion guarantees. Cost compression in natural phage food safety segments is intensifying because empirical cocktail matching struggles to provide standardized efficacy documentation demanded by hospital procurement committees. Agricultural firms exhibit highest price sensitivity, while academic medical centers in the United States demonstrate lowest sensitivity due to dedicated antimicrobial stewardship budgets.
Supply Chain Analysis
ISO 13485 certification gating restricts pharmaceutical-grade phage manufacturing to facilities in the United States, France, and Germany, with REACH compliance documentation requirements tightening substance registration pathways for engineered platforms entering European markets. Raw material dependencies center on pharmaceutical-grade fermentation media, endotoxin removal resin systems, and CRISPR-Cas plasmid libraries. Single-source vulnerability concentrates in synthetic biology expertise combining virology with programmable genome editing, which draws from academic centers in Boston and San Diego. Distribution runs through hospital formulary pre-approval systems displacing physician-directed compassionate use channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bacteriophage therapeutics rests on the shift from empirical cocktail matching toward companion diagnostic-converged precision platforms, with CRISPR-enhanced engineering reducing per-patient production costs through programmable host-range standardization.
For Market Incumbents: Anticipate consolidation pressure from emerging synthetic biology platform companies by accelerating ISO 13485 certification timelines and securing captive supply of endotoxin removal systems. Defensive positioning requires deepening companion diagnostic partnerships to collapse treatment selection windows, while channel control through hospital formulary pre-approval systems protects against physician-directed compassionate use displacement.
For New Entrants and Emerging Players: Academic medical center spinouts offer the most penetrable entry channel, leveraging existing compassionate-use protocol relationships to bypass formulary committee gatekeeping. White-space targets include agricultural microbiome applications in livestock gut health and cystic fibrosis inhalation formulations where regulatory burden remains lighter than systemic intravenous indications. A go-to-market angle through NHS Accelerated Access Collaborative procurement pathways reduces reimbursement risk for first movers in national health systems.
For Investors and Strategic Acquirers: Roll-up economics work for synthetic biology platform companies because CRISPR-enhanced phage engineering talent concentrates in geographically clustered academic centers, enabling capability consolidation through targeted acquisitions. Long-term viability across the projection horizon favors developers with FDA QIDP-backed pipelines and defined genetic modification portfolios over legacy natural phage suppliers facing commoditization. The signal to watch is EMA adaptive pathway precedent establishment for phage-specific conditional marketing authorization frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Convergence | Same-day phage matching against patient isolates collapses multi-week empirical selection timelines. |
| ISO 13485 Certification Acceleration | Medical device-quality manufacturing validation opens hospital formulary channels in United States metropolitan systems. |
| CRISPR Host-Range Engineering | Programmable DNA targeting modules enable resistance-evasion mechanisms natural phage cocktails cannot replicate. |
| Agricultural Microbiome Expansion | Livestock gut health and crop protection segments offer volume scale absent clinical regulatory burden. |
| NHS Accelerated Access Collaborative Entry | Dedicated reimbursement channels for novel antimicrobials reduce commercialization risk in national health systems. |
Methodological Framework
Coverage spans the United States, Germany, Georgia, France, and the United Kingdom, with primary inputs from each market's regulatory and clinical stakeholder base. The analysis combines structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation from FDA QIDP filings, EMA adaptive pathway submissions, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up segment sizing and top-down market triangulation cross-validate volume and value estimates across engineered phage platforms, natural phage cocktails, and emerging delivery modalities.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window, with CAGRs derived from segment-level modeling of product type, application setting, delivery mode, and end-user purchasing sophistication. The analytical framework incorporates phage engineering pipeline stage, regulatory designation status, and reimbursement infrastructure maturity as industry-specific forecast inputs. Segmentation dimensions include treatment line, administration route, and regional regulatory cluster.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA adaptive pathway precedent establishment and CRISPR-Cas system patent landscape evolution. Forecasts reflect assumptions around FDA QIDP designation continuity and hospital formulary consolidation trajectories. A model refresh is warranted upon material change in European conditional marketing authorization frameworks for biological therapeutics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Ligation Market
Biomedical Technology
Neoantigen Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Orthobiological Products Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Handheld DNA Reader Market