
 Global Automated Cell Cultures Market | 2026-2036
Global Automated Cell Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Cell Cultures Market Foresight
Buyer concentration among contract development and manufacturing organizations is realigning procurement patterns toward integrated automation platforms. Thermo Fisher Scientific leverages its consumables-to-instrument ecosystem to sustain recurring revenue streams across large-scale biologics facilities. Danaher anchors its position through analytical instrument integration with cell culture hardware. Sartorius AG differentiates via single-use bioreactor technology leadership in perfusion applications.
Automated cell cultures encompass bioreactor systems, cell processing platforms, and imaging technologies that maintain controlled environmental parameters for mammalian, microbial, or stem cell propagation under minimal human intervention. These systems deploy sensors integration and robotic automation to maintain pH, dissolved oxygen, and temperature within specification ranges of 0.1 pH units and 0.5 percent dissolved oxygen for therapeutic protein consistency. Bioreactors command the largest installed base due to their centrality in commercial biologics manufacturing, while microfluidics represents the fastest-expanding technology segment as miniaturization reduces media costs and accelerates clone screening cycles. Drug discovery applications generate substantial instrument demand, though regenerative medicine is emerging as the highest-margin application as cell therapy developers seek closed-system compliance.
FDA process analytical technology frameworks and EMA cell-based medicinal product guidelines shape equipment validation requirements and data integrity standards for automated culture platforms. ISO 14644 cleanroom classifications and GMP Annex 1 sterility provisions further constrain system design, favoring closed architectures over open manipulations. China's NMPA biologics manufacturing standards and Japan's PMDA regenerative medicine safety frameworks add compliance layers for vendors serving Asia-Pacific customers. Stakeholders must monitor evolving AI-driven process control regulations and determine whether to build predictive analytics capabilities internally or partner with specialized software vendors.
Market Dynamics
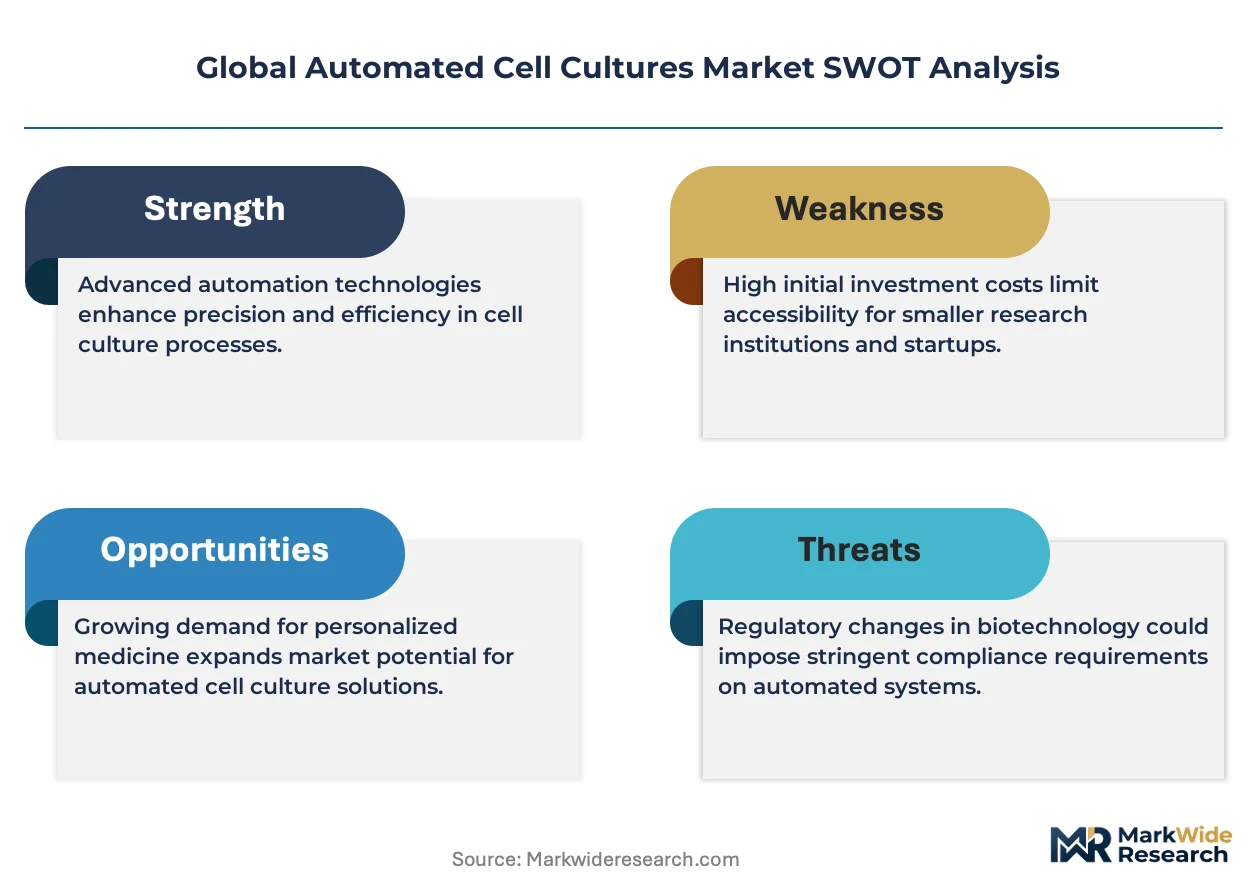
Biopharmaceutical contract manufacturers are consolidating procurement around integrated automation platforms that compress antibody production timelines from 18 months to 10 months. This demand concentration is restructuring vendor relationships toward ecosystem partnerships rather than discrete equipment purchases.
Growth Catalysts
- FDA Process Analytical Technology:The framework mandates real-time quality monitoring, forcing biologics facilities to retrofit legacy bioreactors with sensor-integrated control systems. Equipment vendors capture upgrade cycles across mammalian cell culture suites.
- Perfusion bioprocessing:Continuous manufacturing protocols reduce media consumption by 60 percent compared with fed-batch methods. Single-use bioreactor adoption accelerates as developers seek productivity gains for monoclonal antibody campaigns.
- China's NMPA biologics standards:Domestic manufacturers must demonstrate closed-system compliance for cell therapy manufacturing. Local CDMOs are importing automated processing platforms to satisfy inspection protocols for CAR-T production facilities.
Market Restraints
- Stainless steel bioreactor installed base:Depreciation cycles extending 15-20 years lock capital into legacy equipment. Facilities delay automation investments until existing assets reach end-of-life, slowing platform conversion rates.
- Specialized polymer supply concentration:Single-use bioreactor film production concentrates among three European suppliers. Geopolitical friction or raw material shortages propagate immediately into bioprocessing consumables lead times.
- Cross-contamination validation complexity:EMA cell-based medicinal product guidelines require documented proof of absence for adventitious agents between campaigns. Multi-product facilities face extended downtime for cleaning verification protocols.
Strategic Opportunities
- Japan's regenerative medicine framework:PMDA accelerated approval pathways for allogeneic cell therapies create demand for closed, automated expansion systems. Vendors can anchor Asia-Pacific growth through Tokyo-Osaka manufacturing clusters.
- Microfluidic clone screening convergence:Integration of high-content imaging with liquid handling robotics compresses cell line development from 6 months to 10 weeks. Early-stage biotechs represent an underserved automation customer segment.
- AI-driven process control:Machine learning algorithms predicting metabolite exhaustion or apoptosis onset enable autonomous media exchange decisions. Partnerships between hardware manufacturers and specialized software developers unlock predictive maintenance revenue streams.
Industry Challenges
- Bioprocess engineer scarcity:Universities produce insufficient graduates trained in both cell biology and automation engineering. Facilities compete for talent capable of programming SCADA systems while interpreting metabolic flux data.
- Legacy MES integration:Manufacturing execution systems from the 2010s lack API architectures compatible with modern IoT sensor networks. Custom middleware development extends deployment timelines by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Cell Cultures Market |
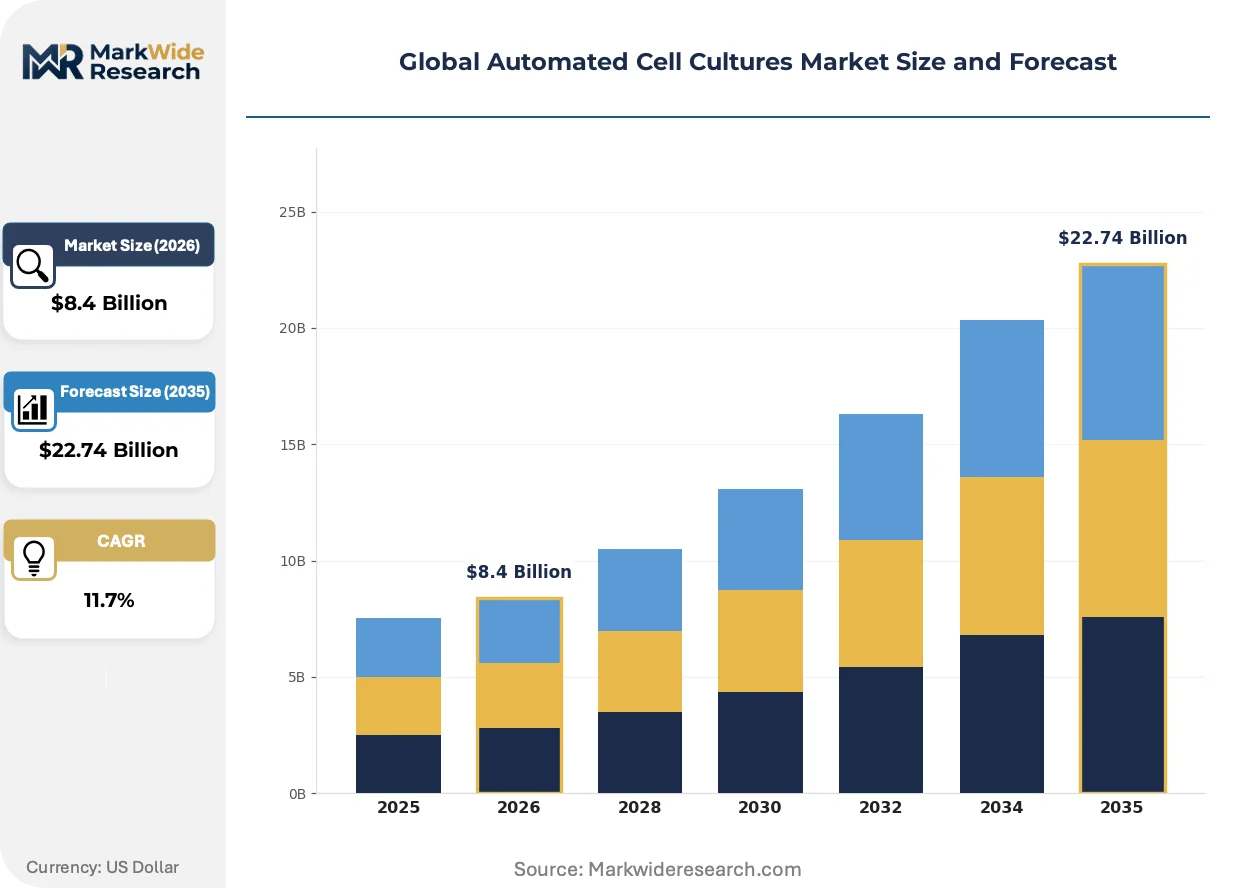
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioreactors, Cell Processing Systems, Imaging Systems, Cell Harvesters, Centrifuges Technology: Microfluidics, 3D Cell Culture, Robotic Automation, Sensors Integration, Artificial Intelligence Application: Drug Discovery, Toxicology Testing, Regenerative Medicine, Stem Cell Research, Vaccine Development End User: Biopharmaceutical Companies, Academic Institutions, Contract Research Organizations, Government Labs |
| Companies Covered | Sartorius AG, Thermo Fisher Scientific, Danaher, Lonza, Merck KGaA, Corning Incorporated, Eppendorf AG, GE Healthcare, Hamilton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Cell Cultures Market Shifts & Advancements
Automation architectures are migrating from hardware-centric control systems toward software-defined bioprocessing environments where algorithmic optimization replaces manual parameter tuning. This shift compresses process development timelines while elevating data integrity requirements.
Microfluidic perfusion bioreactors are electrifying small-scale cell culture workflows by enabling continuous media exchange at microliter volumes. Stem cell therapy developers are adopting these systems for expansion-phase optimization before scale-up to manufacturing bioreactors. The technology is electrifying clone selection economics by reducing screening campaign costs from hundreds of thousands to tens of thousands of dollars per candidate.
EMA's revised Annex 1 on sterile manufacturing mandates closed-system processing for all cell-based medicinal products entering European markets. The regulation disqualifies open manipulations previously tolerated in early-phase clinical manufacturing. Autologous cell therapy developers are responding by retrofitting cleanrooms with isolator-based automation platforms that eliminate human intervention during expansion.
CDMO consolidation is compressing vendor negotiation cycles as large contract manufacturers centralize equipment specifications across multi-site networks. Thermo Fisher and Danaher are displacing regional distributors through direct enterprise agreements with top-twenty biologics outsourcers. This concentration is most visible in Massachusetts and North Carolina, where three CDMOs control 40 percent of US mammalian cell culture capacity.
Global Automated Cell Cultures Market Segmentation
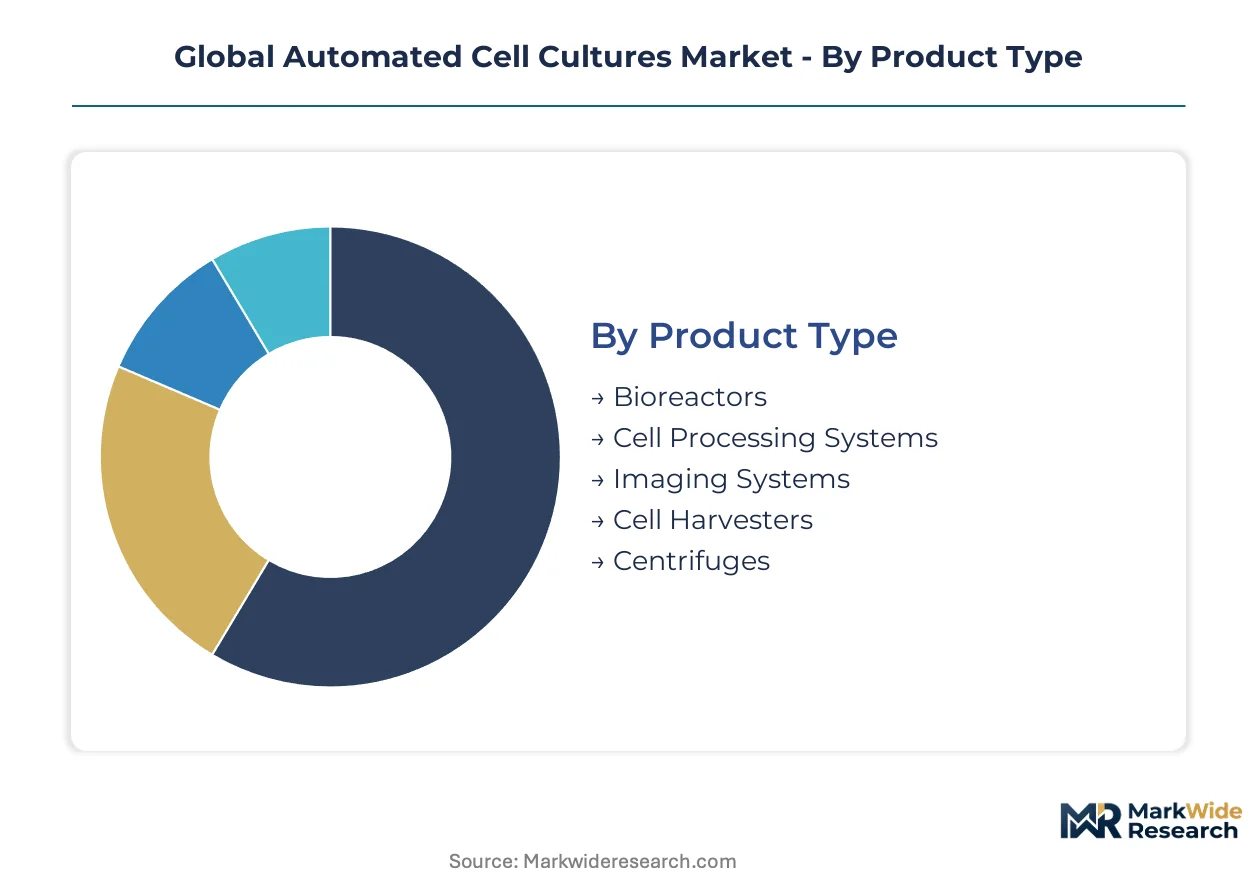
Automated cell culture procurement patterns diverge sharply by buyer sophistication and scale. Large biopharmaceutical manufacturers prioritize integrated platforms with validated GMP compliance, while academic researchers emphasize modularity and capital flexibility.
Product Type:
Capital intensity and facility lifecycle position separate the installed base from replacement demand.
- Bioreactors:Stainless steel and single-use vessel systems dominate commercial manufacturing footprints, with perfusion configurations commanding premium positioning. Demand concentrates among mammalian cell therapy developers in Massachusetts and North Carolina seeking continuous processing economics.
- Cell Processing Systems:Closed-system automation platforms integrate centrifugation, washing, and concentration steps for cell therapy manufacturing. China's NMPA-compliant CDMOs are importing these systems to satisfy CAR-T production inspection protocols.
- Imaging Systems:High-content screening microscopes with AI-enabled colony recognition.
- Cell Harvesters:Automated detachment and collection systems for adherent cultures.
- Centrifuges:Continuous flow separation units for downstream bioprocessing.
Volume sits with bioreactors; growth tilts toward cell processing systems.
Technology:
Process control sophistication determines automation tier and regulatory acceptance.
- Microfluidics:Miniaturized perfusion chambers enable microliter-scale media exchange with real-time metabolite monitoring. Stem cell therapy developers in Japan's Kansai cluster adopt these for expansion-phase optimization before manufacturing scale-up.
- Robotic Automation:Liquid handling and plate manipulation systems execute sterile transfers without human intervention. EMA Annex 1 revisions mandating closed processing accelerate isolator-integrated robotic deployments across European cell therapy facilities.
- 3D Cell Culture:Scaffold-based and organoid systems replicating tissue microenvironments.
- Sensors Integration:Multi-parameter probes tracking pH, dissolved oxygen, and biomass density.
- Artificial Intelligence:Predictive algorithms for media exchange timing and apoptosis detection.
Installed base concentrates in robotic automation; microfluidics exhibits the steepest expansion trajectory.
Application:
Margin structure and regulatory burden shape automation investment returns.
- Drug Discovery:High-throughput screening workflows demand rapid clone selection with minimal operator intervention. Microfluidic integration reduces campaign costs from hundreds of thousands to tens of thousands per candidate among early-stage biotechs.
- Regenerative Medicine:Cell therapy manufacturing requires closed, validated systems with full batch records. FDA process analytical technology frameworks and EMA cell-based medicinal product guidelines force retrofit investments across autologous and allogeneic production facilities.
- Toxicology Testing:Predictive safety assessment using human cell models.
- Stem Cell Research:Pluripotent and adult stem cell expansion for clinical translation.
- Vaccine Development:Viral vector production and attenuated strain cultivation.
Revenue concentrates in drug discovery; regenerative medicine captures the highest margin expansion.
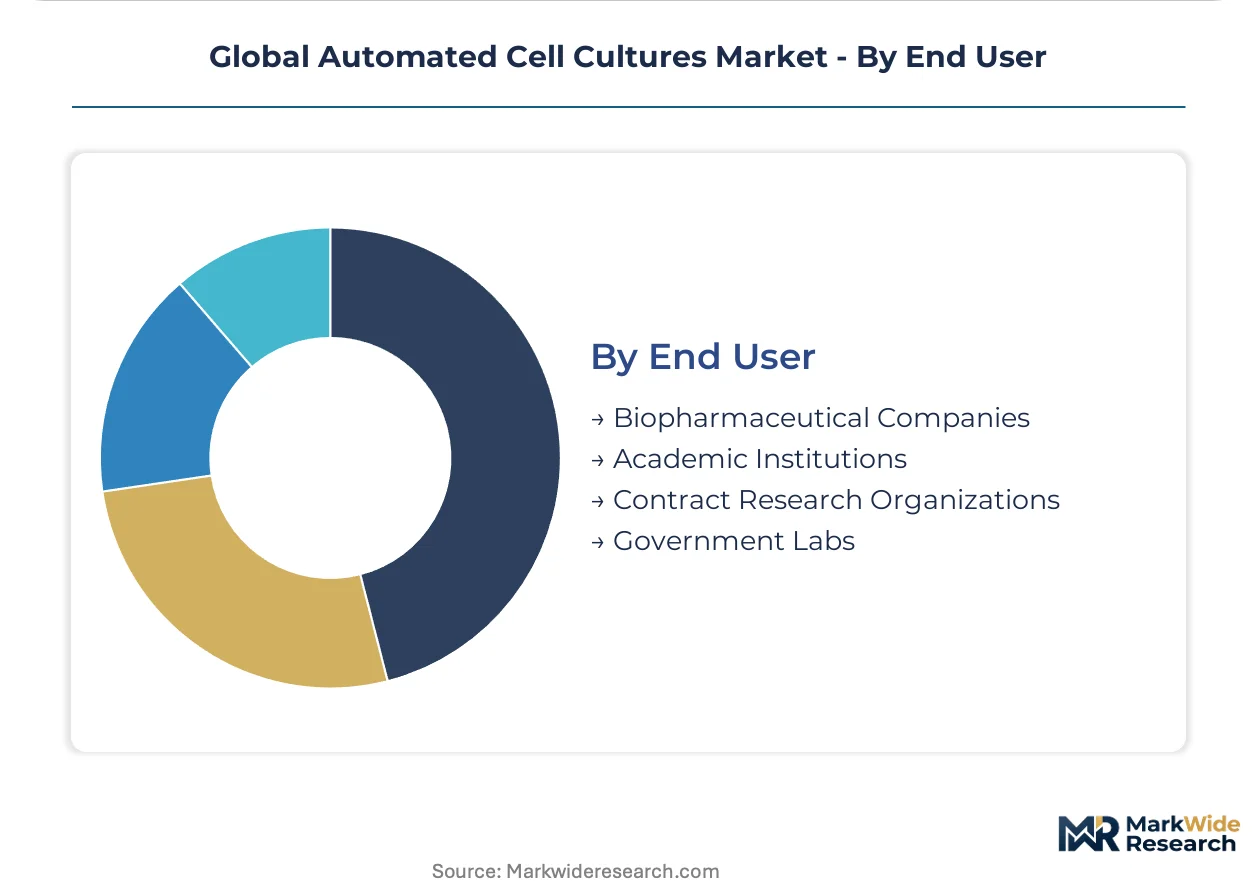
End User:
Procurement authority and validation requirements segment the customer base.
- Biopharmaceutical Companies:Internal manufacturing networks specify enterprise-wide automation platforms with centralized data architectures. Thermo Fisher and Danaher displace regional distributors through direct agreements with top-twenty biologics outsourcers controlling multi-site capacity.
- Contract Research Organizations:Project-based demand favors flexible instrumentation with rapid reconfiguration capabilities. Academic spinouts and venture-backed biotechs represent an underserved segment for entry-level automation.
- Academic Institutions:Research-scale systems with publication-grade data output.
- Government Labs:National biosecurity and reference standard production facilities.
Procurement volume sits with biopharmaceutical companies; CROs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical contract manufacturers cluster automated cell culture procurement around multi-product facilities near research universities in the United States, Germany, and China. FDA process analytical technology mandates, EMA cell-based therapy standards, and China's NMPA biologics guidelines collectively reshape equipment validation requirements across these demand centers.
United States
Massachusetts and North Carolina host three CDMOs controlling 40 percent of mammalian cell culture capacity. FDA process analytical technology frameworks mandate real-time quality monitoring, forcing biologics facilities to retrofit legacy bioreactors with sensor-integrated control systems. Boston-Cambridge and Research Triangle Park anchor antibody production automation investments.
Germany
Single-use bioreactor film production concentrates among three European suppliers, making Germany a critical node in consumables supply. EMA cell-based medicinal product guidelines require documented proof of absence for adventitious agents between campaigns. Frankfurt-Rhine-Main and Munich manufacturing clusters drive perfusion bioprocessing platform adoption.
China
Domestic manufacturers must demonstrate closed-system compliance for cell therapy manufacturing under NMPA biologics standards. Local CDMOs import automated processing platforms to satisfy inspection protocols for CAR-T production facilities. Shanghai and Suzhou biotech parks concentrate cell therapy facility investments.
Japan
PMDA accelerated approval pathways for allogeneic cell therapies create demand for closed, automated expansion systems. Tokyo-Osaka manufacturing clusters anchor Asia-Pacific growth for regenerative medicine equipment vendors. Kansai region stem cell therapy developers adopt microfluidic systems for expansion-phase optimization.
Switzerland
Swissmedic oversight of advanced therapy medicinal products elevates data integrity requirements for automated culture platforms. Basel and Zurich biopharmaceutical hubs specify enterprise-wide automation with centralized data architectures. Swiss facilities lead in isolator-based automation retrofits for autologous cell therapy manufacturing.
Global Automated Cell Cultures Market Competitive Landscape
United States producers anchor one tier; German and Swiss specialists hold differentiated positions in single-use and analytical integration. The vendor base structures around three tiers: diversified life science conglomerates with consumables-to-instrument ecosystems, analytical instrument specialists extending into cell culture hardware, and single-use technology pure-plays. Strategic moves concentrate on ecosystem partnerships replacing discrete equipment purchases, and predictive analytics capability building through software vendor alliances.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher exemplify platform consolidation strategies. Sartorius AG occupies a distinct position as a single-use technology specialist. These three anchors represent competing archetypes for procurement consolidation among contract development and manufacturing organizations.
| Leading Market Players |
|---|
| Sartorius AG |
| Thermo Fisher Scientific |
| Danaher |
| Lonza |
| Merck KGaA |
| Corning Incorporated |
| Eppendorf AG |
| GE Healthcare |
| Hamilton Company |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up CDMO networks in North Carolina and Massachusetts wield consolidated procurement volumes to extract preferential pricing from automated cell culture vendors, while their long-term service contracts insulate equipment suppliers from margin erosion in the consumables-heavy single-use segment.
Pricing Analysis
Volume concentrates in stainless steel bioreactor retrofits where depreciation cycles extend 15-20 years, while margin expansion sits with closed-system cell processing platforms for regenerative medicine applications. Pricing stratifies across GMP-validated premium tiers, mid-range configurable systems, and entry-level research units. Cost compression in the research-tier segment is intensifying because academic budget constraints and early-stage biotech funding volatility force vendors to absorb configuration customization. Contract development and manufacturing organizations exhibit the lowest price sensitivity due to pass-through mechanisms in client service agreements, while academic spinouts demonstrate acute sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Single-source vulnerability sits with specialized polymer film production concentrated among three European suppliers in Germany and France, where geopolitical friction propagates immediately into bioprocessing consumables lead times. Raw material dependencies encompass fluorinated ethylene propylene films, platinum-cured silicone tubing, and gamma-sterilizable polymer resins. Supply chain risk centers on regulatory restriction as EMA Annex 1 sterility provisions and FDA process analytical technology frameworks tighten validation documentation requirements for each consumables lot. Distribution runs through direct enterprise agreements with top-twenty biologics outsourcers, displacing regional distributor networks in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated cell culture market sits in a technology-transition phase where software-defined bioprocessing environments and AI-driven process control systems are displacing hardware-centric SCADA architectures that dominated the 2010s.
For Market Incumbents: Lock in ecosystem partnerships with specialized predictive analytics software developers to fortify recurring revenue streams against modular competitors. Prioritize backward integration into single-use consumables manufacturing to capture margin pools currently concentrated among three European polymer film suppliers. Defensive positioning requires anchoring enterprise-wide automation platforms across multi-site CDMO networks before regional distributors recover footing. For New Entrants and Emerging Players: The price-point gap between premium GMP-validated systems and economy-tier research equipment creates entry space for mid-range platforms targeting venture-backed biotechs in Boston-Cambridge and Research Triangle Park. White-space opportunities concentrate in microfluidic clone screening workflows where early-stage developers face campaign cost thresholds in the tens of thousands rather than hundreds of thousands. A software-heavy, hardware-light go-to-market angle bypasses capital-intensive bioreactor manufacturing while capturing process optimization value. For Investors and Strategic Acquirers: FDA process analytical technology retrofit mandates across legacy mammalian cell culture facilities is the leading indicator that equipment upgrade cycles will accelerate regardless of biotech funding environments. Long-term viability favors vendors with consumables-to-instrument ecosystems that generate recurring revenue through single-use bioreactor film and sensor cartridge replacement. Acquisition targets should display validated GMP compliance for closed-system cell therapy manufacturing and established direct relationships with top-twenty biologics outsourcers.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Process Control Partnership | Machine learning integration with bioreactor hardware unlocks predictive maintenance revenue from FDA-mandated retrofit cycles. |
| Single-Use Consumables Backward Integration | In-house polymer film production insulates margins from European supplier concentration and geopolitical supply shocks. |
| Closed-System Validation Certification | EMA Annex 1 compliance documentation accelerates procurement decisions among autologous cell therapy developers. |
| Microfluidic Platform Launch | Microliter-scale perfusion chambers capture stem cell therapy expansion-phase optimization demand in Japan's Kansai cluster. |
| Direct CDMO Enterprise Agreement | Multi-site automation standardization displaces regional distributors in Massachusetts and North Carolina manufacturing hubs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with bioprocess engineering directors, regulatory affairs leads at cell therapy developers, CDMO procurement executives, and academic core facility managers. Secondary sources encompassed FDA 483 inspection observations, EMA marketing authorization submissions, NMPA biologics manufacturing guidance documents, and import-export records for automated cell culture equipment. Bottom-up demand modeling triangulated against top-down industry association revenue aggregates.
Segment-level granularity modeled product type at the bioreactor configuration level, technology tier at the automation sophistication level, application at the therapeutic modality level, and end user at the procurement authority level across the projection horizon. CAGRs derived from regression analysis against biologics manufacturing capacity expansion, regulatory mandate implementation timelines, and cell therapy clinical pipeline progression. Forecast inputs incorporated CDMO consolidation patterns, university technology transfer office licensing activity, and sovereign-backed biotech investment flows in China and Japan.
Underlying measurement precision varies by segment; drug discovery applications and biopharmaceutical company end users carry tighter precision than academic institution procurement and toxicology testing applications due to disclosure requirements and procurement transparency. Forecasts reflect documented assumptions regarding regulatory implementation pacing, technology adoption curves, and competitive dynamics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Latin America Digital Biology Market
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Europe Exosome Research Products Market