
 Southern Blotting Market | 2026-2036
Southern Blotting Market Size, Share, and Industry Trends Forecast 2026-2036
Southern Blotting Market Outlook
Capillary transfer automation is tilting Southern blotting from manual membrane handling toward integrated electrophoretic workflows. Thermo Fisher Scientific leverages its reagent-instrument bundling to anchor high-throughput genomics labs. Bio-Rad Laboratories sustains gel electrophoresis dominance through proprietary tank and semi-dry transfer systems. QIAGEN differentiates with silica-membrane spin column integration that competes with traditional capillary methods.
Southern blotting denotes a nucleic acid detection technique wherein DNA fragments separated by agarose gel electrophoresis are transferred to a nitrocellulose or nylon membrane, immobilized via UV cross-linking or baking, and hybridized with labeled sequence-specific probes for target identification. The method serves forensic DNA fingerprinting, genetic disorder diagnosis, and restriction fragment length polymorphism analysis in research and clinical laboratories. Reagents and kits capture recurring revenue from probe synthesis and hybridization buffers, while instruments face replacement cycles driven by imaging sensitivity gains. Diagnostics applications expand as companion biomarker validation demands fragment-size confirmation absent in qPCR alone.
The FDA oversees analyte-specific reagent classifications that shape kit commercialization pathways for clinical laboratories, while the EMA's IVDR implementation in Europe elevates conformity assessment burdens for probe-based diagnostic kits. ISO 15189 accreditation requirements for medical laboratories further filter vendor selection toward traceable reagent suppliers. Stakeholders must weigh capital deployment between legacy membrane workflows and emerging automated platforms as reimbursement frameworks tighten around molecular diagnostic specificity thresholds.
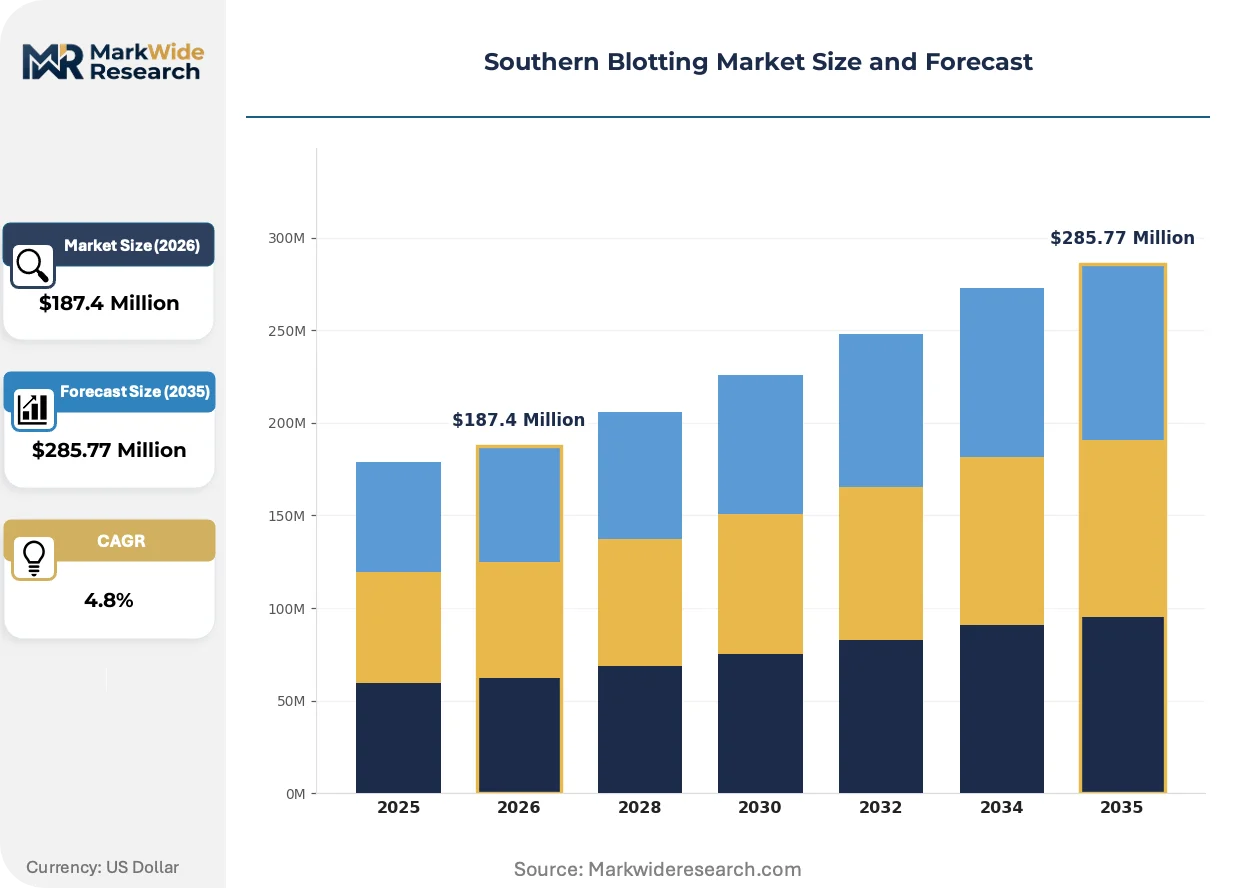
Market Dynamics
Capillary transfer automation is compressing manual membrane handling workflows while IVDR recalibration in Europe and FDA analyte-specific reagent classifications force kit manufacturers to revalidate probe specificity claims, creating simultaneous cost and compliance pressures.
Growth Catalysts
- NIH and Max Planck funding streams:Sustained capital allocation to core facility upgrades in the United States and Germany sustains reagent-intensive procurement cycles for genomic research infrastructure.
- Companion biomarker validation protocols:Fragment-size confirmation demands from diagnostic laboratories expand Southern blotting applications beyond qPCR capabilities alone.
- Forensic DNA fingerprinting mandates:Judicial evidence standards in criminal investigations require restriction fragment length polymorphism analysis that Southern blotting uniquely provides.
Market Restraints
- Nylon and nitrocellulose membrane supply concentration:Specialty membrane production clusters in select manufacturing regions create input vulnerability for transfer workflows.
- IVDR conformity assessment burdens:The European Union's recalibration of in vitro diagnostic regulations elevates validation costs and timeline uncertainty for probe-based diagnostic kits.
- qPCR and next-generation sequencing substitution:Alternative nucleic acid detection platforms capture volume from fragment analysis applications through faster turnaround times.
Strategic Opportunities
- Academic core facility automation:United States research universities present underpenetrated demand for integrated electrophoretic transfer systems that reduce manual handling labor.
- Silica-membrane spin column convergence:Hybrid workflows combining traditional capillary methods with column-based purification open protocol flexibility for sample preparation vendors.
- ISO 15189 accreditation tailwinds:Medical laboratory certification requirements filter vendor selection toward traceable reagent suppliers with documented quality systems.
Industry Challenges
- UV cross-linking equipment obsolescence cycles:Imaging sensitivity gains force replacement timelines for membrane immobilization hardware in budget-constrained facilities.
- Probe synthesis technical expertise gaps:Sequence-specific hybridization buffer formulation requires specialized molecular biology training that core facility staffing struggles to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southern Blotting Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Software Application: Research, Diagnostics, Forensics, Quality Control End User: Academic Institutions, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Technology: Hybridization, Probe Labeling, Gel Electrophoresis, Imaging |
| Companies Covered | PerkinElmer Inc., Cleaver Scientific Ltd., Thermo Fisher Scientific, Aplegan, Pall Life Science Laboratories, Agilent Technologies, Applied Biosystems, QIAGEN, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southern Blotting Market Strategic Shifts
Automation is collapsing manual transfer steps while regulatory recalibration and procurement consolidation reshape how reagent suppliers compete for laboratory budgets.
Automated capillary transfer systems are collapsing the membrane handling bottleneck that has constrained Southern blotting throughput for decades. High-throughput genomics laboratories in the United States are adopting integrated electrophoretic workflows that eliminate manual gel manipulation. This compression is enabling core facilities to process sample batches that previously required overnight technician attendance.
EMA's IVDR implementation is elevating conformity assessment burdens for probe-based diagnostic kits across European medical laboratories. Kit manufacturers must now revalidate specificity claims through notified body review, extending commercialization timelines by twelve to eighteen months. German and French diagnostic laboratories are responding by consolidating procurement toward established suppliers with documented quality management systems.
Reagent bundling is reshaping how academic institutions evaluate Southern blotting suppliers. Core facility directors are unbundling instrument purchases from consumable contracts, favoring vendors with transparent per-reaction pricing over locked-in equipment-reagent packages. This behavioral shift is most visible in NIH-funded research centers where grant accountability requirements demand detailed cost attribution.
Southern Blotting Market Segmentation
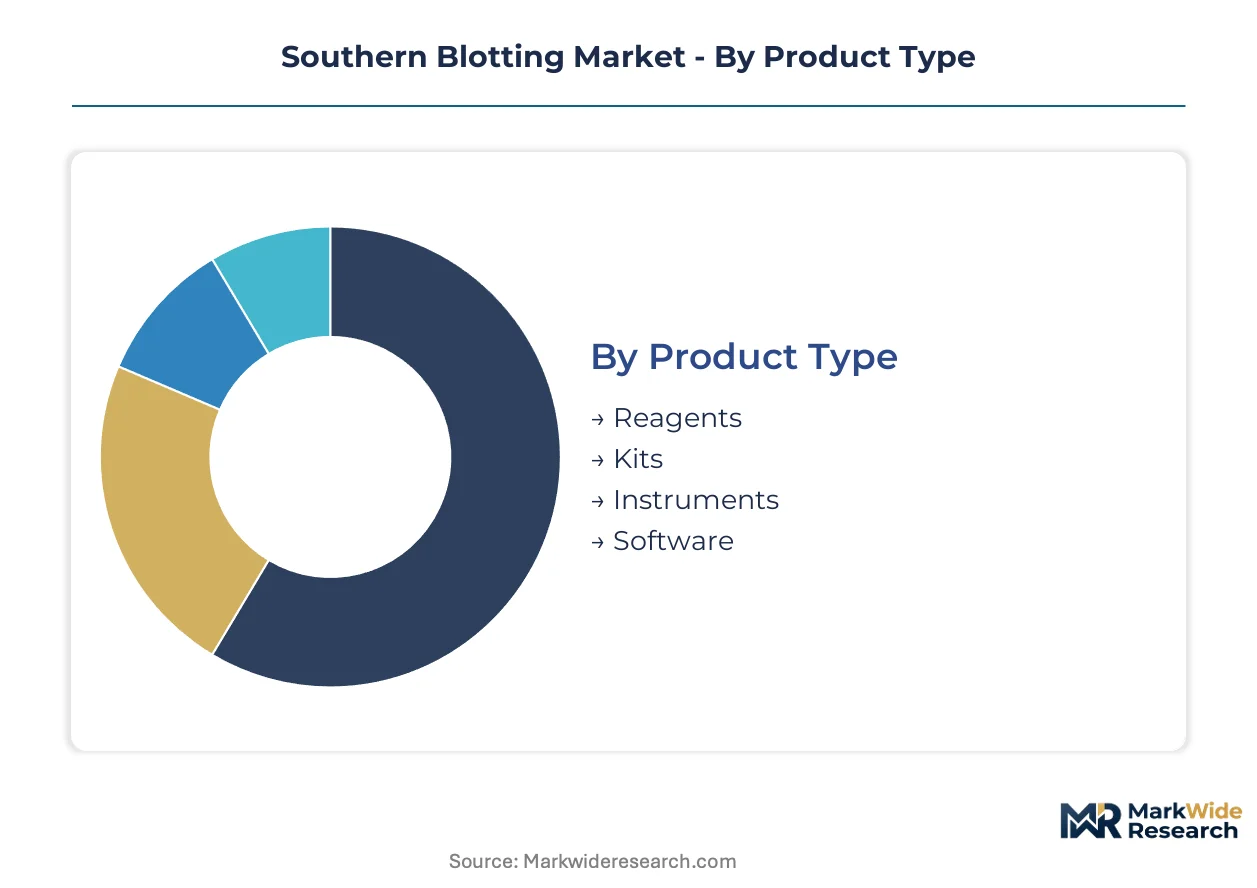
Southern blotting procurement patterns diverge sharply between high-frequency consumable replenishment and capital-intensive instrument replacement. Understanding segment turnover rhythms clarifies where suppliers capture recurring revenue versus episodic sales.
Product Type:
Reagents and kits compress procurement cycles to weeks while instruments stretch replacement timelines across multiple years.
- Reagents:Hybridization buffers, labeled probes, and membrane chemistries constitute the highest-velocity procurement category. Academic core facilities in Germany and the United States maintain standing orders for restriction enzymes and radioactive or chemiluminescent detection reagents.
- Kits:Pre-formulated probe labeling and hybridization systems reduce protocol variability for clinical laboratories. IVDR recalibration in Europe is forcing kit manufacturers to revalidate specificity claims, extending development timelines for probe-based diagnostic products.
- Instruments:Automated capillary transfer systems and UV cross-linking equipment face replacement cycles driven by imaging sensitivity gains. NIH-funded research centers defer capital expenditure during grant renewal gaps.
- Software:Band analysis and fragment sizing algorithms integrate with gel documentation systems. Medical laboratories pursuing ISO 15189 accreditation prioritize traceable software validation.
Reagents dominate installed base. Kits are where expansion concentrates.
Application:
Diagnostic and forensic applications impose stricter regulatory validation than research workflows, compressing addressable market breadth while expanding per-test value.
- Research:Genomic mapping and transgene detection in model organisms sustain volume demand at academic institutions. Max Planck Institute facilities prioritize restriction fragment length polymorphism analysis for genetic linkage studies.
- Diagnostics:Companion biomarker validation and genetic disorder screening require fragment-size confirmation absent in qPCR alone. FDA analyte-specific reagent classifications shape kit commercialization pathways for clinical laboratories.
- Forensics:Judicial evidence standards mandate Southern blotting for DNA fingerprinting in criminal investigations. German and French forensic laboratories maintain certified protocols for restriction fragment length polymorphism analysis.
- Quality Control:Biopharmaceutical manufacturing employs Southern blotting for cell line authentication and vector copy number determination. Contract manufacturers integrate fragment analysis into release testing workflows.
Research anchors current volume. Diagnostics is climbing the fastest.
End User:
Academic procurement concentrates in United States and German research clusters while pharmaceutical demand fragments across outsourced testing networks.
- Academic Institutions:NIH and Max Planck funding streams sustain reagent-intensive procurement for core facility upgrades. United States research universities present underpenetrated demand for integrated electrophoretic transfer systems.
- Pharmaceutical Companies:In-house genomic screening capabilities compete with outsourced testing arrangements. Companion biomarker validation teams require fragment-size confirmation for regulatory submissions.
- Biotechnology Firms:Cell line development and gene therapy vector characterization drive probe synthesis demand. Start-ups favor kit-based workflows over capital-intensive instrument acquisition.
- Contract Research Organizations:Multi-client service models amortize equipment costs across project portfolios. ISO 15189 accreditation requirements filter vendor selection toward traceable reagent suppliers.
Academic Institutions dominate installed base. Contract Research Organizations are gaining share fastest.
Technology:
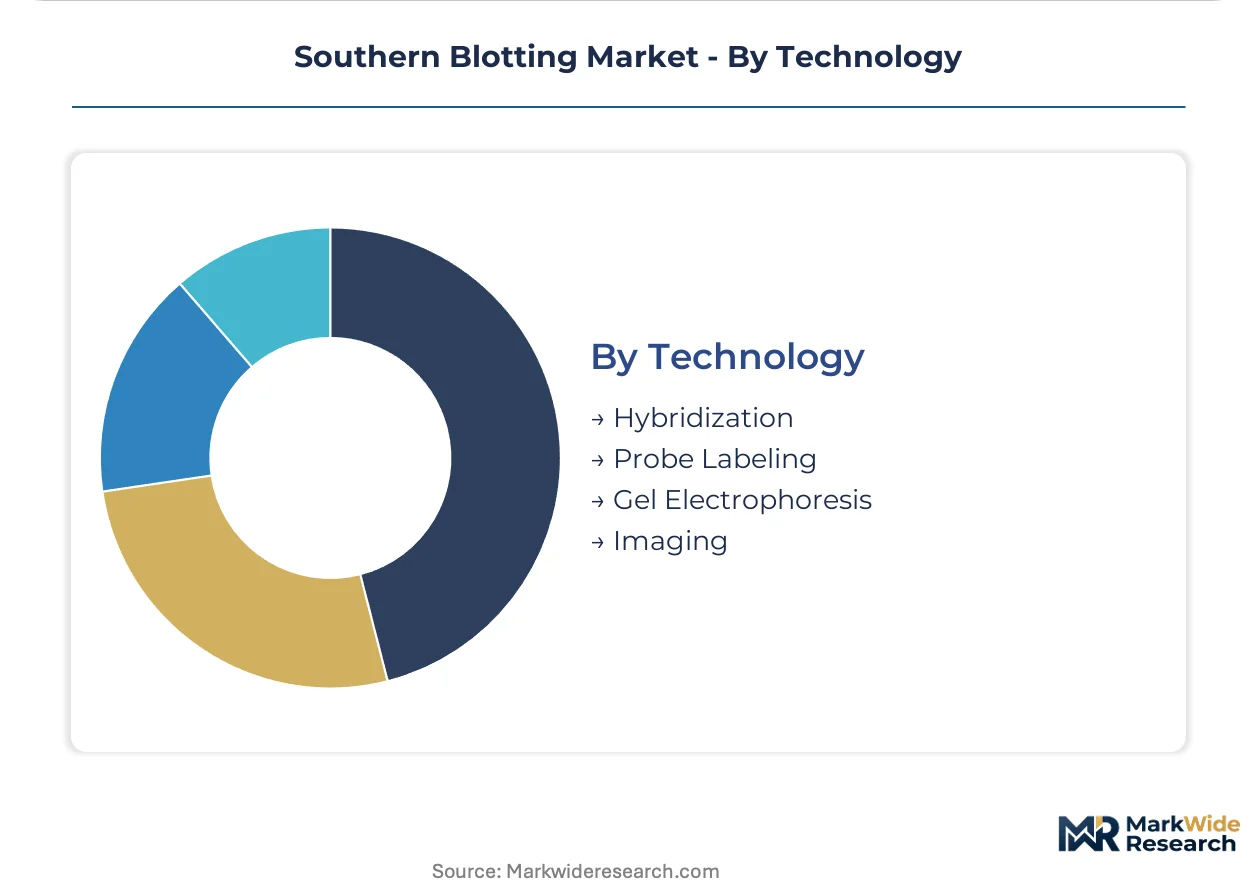
Automation is collapsing manual handling steps in gel electrophoresis and imaging while probe labeling retains specialized technical expertise requirements.
- Hybridization:Sequence-specific probe binding to membrane-immobilized DNA remains the definitive detection step. Buffer formulation optimization demands molecular biology training that core facilities struggle to retain.
- Probe Labeling:Radioactive, chemiluminescent, and fluorescent tag attachment requires isotope handling licenses or advanced imaging infrastructure. Kit manufacturers consolidate toward chemiluminescent detection for clinical market access.
- Gel Electrophoresis:Agarose separation and capillary transfer automation eliminates manual membrane handling bottlenecks. Thermo Fisher Scientific and Bio-Rad Laboratories compete for high-throughput genomics laboratory placements.
- Imaging:Chemiluminescent and fluorescent detection systems face obsolescence cycles from sensitivity improvements. Budget-constrained facilities defer replacement of UV cross-linking and documentation hardware.
Gel Electrophoresis dominates installed base. Imaging is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German reagent manufacturers export probe synthesis kits to French and British diagnostic laboratories under recalibrated EU regulatory frameworks. This trade corridor channels specialized hybridization buffers toward forensic and clinical validation centers.
United States
NIH funding streams sustain core facility upgrades at research universities in Massachusetts and California. FDA analyte-specific reagent classifications shape kit commercialization pathways for clinical laboratories. Boston and San Diego clusters anchor high-throughput genomics infrastructure procurement.
Germany
Max Planck Institute networks drive reagent-intensive workflows for restriction fragment length polymorphism analysis. EMA IVDR implementation elevates conformity assessment burdens for probe-based diagnostic kits. Munich and Heidelberg research campuses concentrate automated capillary transfer system deployments.
United Kingdom
Forensic Science Service laboratories maintain certified DNA fingerprinting protocols for judicial evidence standards. MHRA oversight aligns with IVDR recalibration timelines for in vitro diagnostic kit validation. London and Birmingham forensic clusters sustain membrane-based fragment analysis workflows.
France
ANSM regulatory frameworks filter vendor selection toward traceable reagent suppliers for medical laboratories. Companion biomarker validation teams require fragment-size confirmation beyond qPCR capabilities. Paris and Lyon diagnostic hubs consolidate procurement toward established quality management systems.
Japan
PMDA pharmaceutical regulations govern probe-based diagnostic kit approvals for genetic disorder screening. Academic medical centers in Tokyo and Osaka sustain genomic research infrastructure through METI-supported technology programs. Yokohama biotech corridors anchor cell line authentication service demand.
Southern Blotting Market Competitive Environment
Channel-controlling players compete with product-specialist players across reagent bundling and instrument placement strategies. The vendor base clusters around three archetypes: diversified life science conglomerates with reagent-instrument integration capabilities, electrophoresis-focused specialists with proprietary transfer systems, and sample preparation vendors with membrane-purification hybrid workflows. Consolidation pressures concentrate among kit manufacturers facing IVDR revalidation timelines. Competitive moves center on automation platform launches and silica-membrane protocol convergence.
Within the diversified conglomerate tier, Thermo Fisher Scientific and QIAGEN occupy positions anchoring reagent bundling strategies. Bio-Rad Laboratories exemplifies the electrophoresis-specialist archetype with tank and semi-dry transfer system offerings. These three companies represent distinct competitive vectors: reagent-instrument integration, electrophoretic workflow dominance, and sample preparation hybridization.
| Leading Market Players |
|---|
| PerkinElmer Inc. |
| Cleaver Scientific Ltd. |
| Thermo Fisher Scientific |
| Aplegan |
| Pall Life Science Laboratories |
| Agilent Technologies |
| Applied Biosystems |
| QIAGEN |
| Bio-Rad Laboratories |
| Others |
Value Chain & Pricing Dynamics
IVDR recalibration timelines in Europe compress both pricing tier spreads and supply chain flexibility by forcing kit manufacturers to absorb twelve-to-eighteen-month validation delays while membrane raw material sourcing clusters in Germany and the United States. This regulatory chokepoint elevates cost structures for probe-based diagnostic products and concentrates procurement power among established vendors with documented quality management systems.
Pricing Analysis
Current-generation automated capillary transfer systems command premium positioning against prior-generation manual tank setups and emerging next-generation silica-membrane hybrid platforms. Pricing stratifies across premium, standard, and economy tiers based on imaging sensitivity specifications and ISO 15189 accreditation status. Cost compression in the economy tier intensifies as academic core facilities unbundle instrument purchases from consumable contracts. Biotechnology start-ups exhibit highest price sensitivity due to capital constraints, while forensic laboratories demonstrate lowest sensitivity given judicial evidence standards.
Supply Chain Analysis
Export-control restrictions on radioactive isotope handling licenses limit probe labeling reagent flows between the United States, Germany, and Japan. Nylon and nitrocellulose membrane manufacturing concentrates in Germany and the United States, while chemiluminescent detection reagents draw from Japanese and South Korean specialty chemical suppliers. Single-source vulnerability permeates the membrane substrate tier where three manufacturers control global output. Distribution runs through authorized life science distributors serving academic and clinical laboratory clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. IVDR and FDA validation requirements create switching costs that lock diagnostic laboratories into established probe kit suppliers.
For Market Incumbents: Insulate core reagent revenue by deepening backward integration into membrane substrate manufacturing and acquiring notified body relationships in Germany and France. Next-generation sequencing substitution threatens fragment analysis volumes, making automation platform R&D the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in United States academic core facility automation where NIH grant accountability demands transparent per-reaction pricing unmet by bundled incumbents. Silica-membrane spin column convergence presents the most penetrable white space, with kit-based workflows offering the clearest go-to-market angle for budget-constrained research universities. For Investors and Strategic Acquirers: IVDR implementation reshapes the acquisition landscape toward kit manufacturers with existing notified body certifications and documented quality systems. Long-term viability favors targets with hybrid workflow capabilities spanning traditional capillary and column-based methods. The signal to monitor is consolidation velocity among mid-tier European probe suppliers facing revalidation cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Platform Launch | Integrated electrophoretic transfer systems eliminate manual handling bottlenecks at NIH-funded core facilities. |
| Silica-Membrane Protocol Convergence | Hybrid workflows combining capillary methods with spin columns open protocol flexibility for sample preparation vendors. |
| Notified Body Certification Investment | IVDR conformity assessment capabilities extend commercialization timelines but lock out uncertified competitors. |
| Per-Reaction Pricing Transparency | Unbundled consumable contracts align with grant accountability requirements at United States research universities. |
| ISO 15189 Accreditation Alignment | Traceable reagent quality systems filter vendor selection for European medical laboratory procurement. |
Study Parameters
Cross-validation between primary fieldwork and secondary regulatory filings anchors the qualitative findings in this study. Core facility directors, diagnostic laboratory managers, reagent procurement officers, and IVDR compliance specialists contributed structured interviews. Secondary sources include FDA analyte-specific reagent classifications, EMA IVDR implementation guidance, NIH grant expenditure databases, and ISO 15189 accreditation registries. Bottom-up instrumentation shipment analysis and top-down reagent revenue triangulation verify segment sizing.
Calibration against historical replacement cycles for UV cross-linking equipment and capillary transfer systems shaped the analytical framework across the projection horizon. Segmentation dimensions encompass product type, application, end user, and technology generation. CAGRs derive from installed base depreciation curves and funding flow projections. Probe synthesis technical expertise gaps and membrane supply concentration serve as industry-specific forecast inputs.
Stress conditions across IVDR timeline extensions, NIH appropriation volatility, and qPCR substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and academic funding continuity. Material shifts in FDA analyte-specific reagent reclassification or EMA notified body capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Ontogenetic Market