
 Middle-East and Africa Drones Market | 2026-2036
Middle-East and Africa Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Drones Market Foresight
Aftermarket service revenue is reshaping profit pools across the Middle-East and Africa Drones Market as operators prioritize fleet uptime over hardware margins. Israel Aerospace Industries Ltd. sustains deep maintenance networks across Israeli defense contracts. Baykar Makina Sanayi ve Ticaret A.S. leverages combat-proven platform reliability to anchor service agreements with North African militaries. Elbit Systems Ltd. dominates avionics refurbishment cycles through captive technical support infrastructure.
Drones in the Middle-East and Africa comprise unmanned aerial vehicles spanning fixed-wing, rotary-wing, hybrid, and nano configurations with operational altitudes from below 400 feet to above 18,000 feet and endurance ranging from 20 minutes to 40-plus hours depending on propulsion architecture. Their primary commercial and industrial purpose spans precision agriculture, perimeter security, infrastructure inspection, and last-mile logistics across challenging terrain. Fixed-wing systems lead long-range surveillance and mapping missions where endurance determines contract value. Rotary-wing platforms capture agriculture and construction end users requiring vertical takeoff in confined spaces. Hybrid architectures represent the fastest-growing product category as buyers seek runway-independent operations with extended range.
The General Authority of Civil Aviation in Saudi Arabia, the South African Civil Aviation Authority, and Israel's Civil Aviation Authority each enforce distinct airworthiness and remote pilot certification standards that fragment market access across jurisdictions. These regulatory regimes shape product localization requirements and create compliance costs that favor established suppliers with dedicated certification teams. Stakeholders must monitor harmonization efforts between Gulf aviation authorities and sub-Saharan regulators to anticipate where unified type-approval processes could unlock cross-border fleet deployments.
Market Dynamics
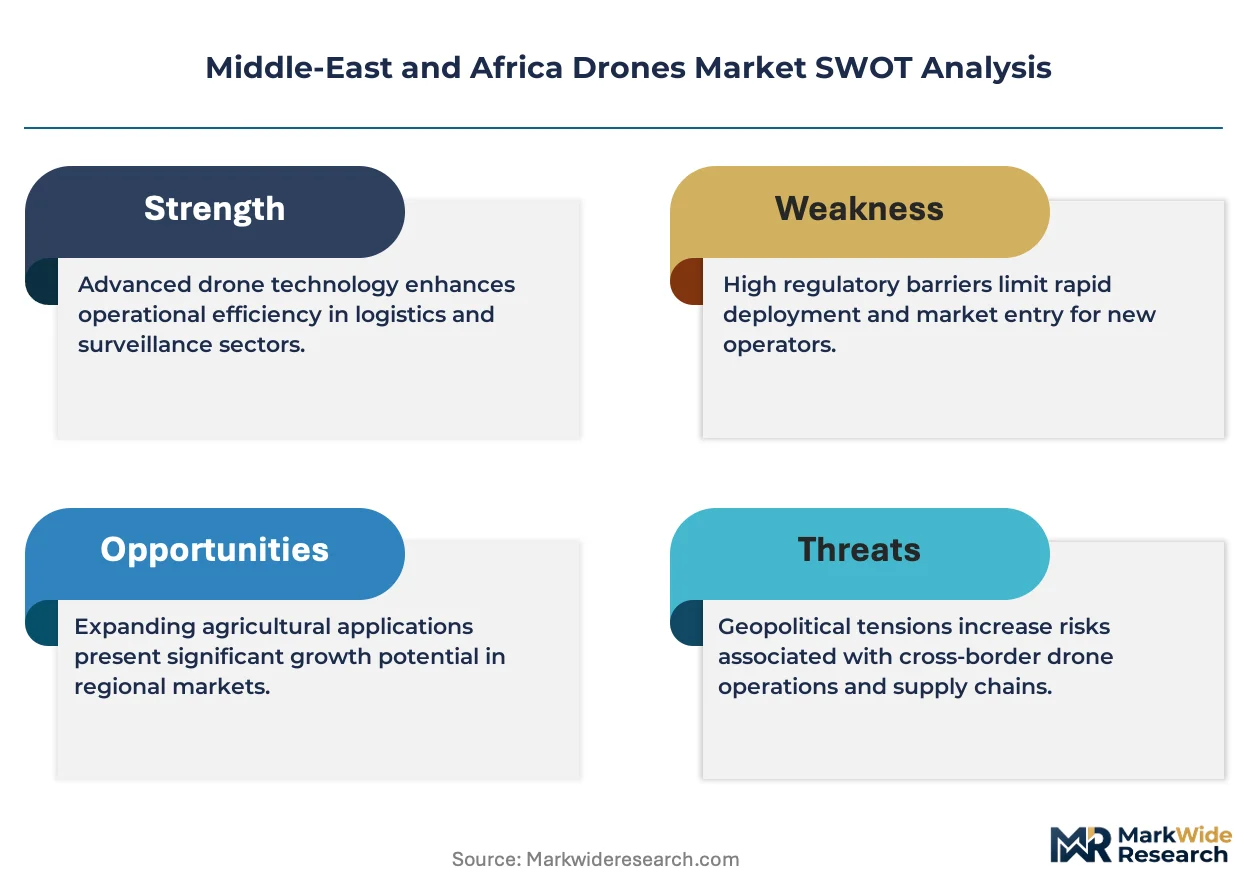
Defense procurement across Gulf states is accelerating fleet modernization programs, while Saudi Arabia's updated remote pilot licensing rules streamline commercial operations and reshape competitive access.
Growth Catalysts
- SFDA-aligned aviation standards:Saudi Arabia's General Authority of Civil Aviation harmonized remote pilot certification with Gulf Cooperation Council frameworks, reducing cross-border operational friction for commercial operators.
- Precision agriculture penetration:Rotary-wing platforms capture agriculture end users across Morocco and Egypt requiring vertical takeoff in confined irrigation zones without runway infrastructure.
- Hybrid propulsion maturation:Runway-independent architectures with extended range are displacing fixed-wing systems in long-range surveillance contracts where endurance determines procurement decisions.
Market Restraints
- Fragmented airworthiness regimes:The South African Civil Aviation Authority, Israel's Civil Aviation Authority, and Saudi GACA enforce non-harmonized certification standards that multiply compliance costs for fleet operators.
- Lithium-polymer supply concentration:Battery pack sourcing concentrates in East Asian contract manufacturers, exposing African operators to currency volatility and extended lead times.
- Radio spectrum allocation delays:Sub-Saharan regulators have not finalized C-band assignments for beyond-visual-line-of-sight operations, freezing corridor development in Kenya and Nigeria.
Strategic Opportunities
- Nigerian logistics corridors:Last-mile delivery networks across Lagos and Kano remain underpenetrated by autonomous aerial systems due to infrastructure gaps that first-movers can bridge with vertiport partnerships.
- UAE-GCC regulatory convergence:Dubai's drone delivery corridor protocols are being adopted by Abu Dhabi and Riyadh regulators, creating unified type-approval pathways for cross-emirate fleet deployment.
- AI-enabled predictive maintenance:Convergence of edge-computing avionics with satellite telemetry is enabling condition-based service contracts that displace scheduled overhaul models in defense procurement.
Industry Challenges
- Certified remote pilot scarcity:The UAE's General Civil Aviation Authority and Israel's CAA each maintain distinct instructor accreditation standards, fragmenting training pipeline scalability across the region.
- Legacy radar integration:Air traffic management systems at Cairo, Johannesburg, and Tel Aviv airports require expensive secondary transponder retrofits to accommodate unmanned traffic management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Drones Market |
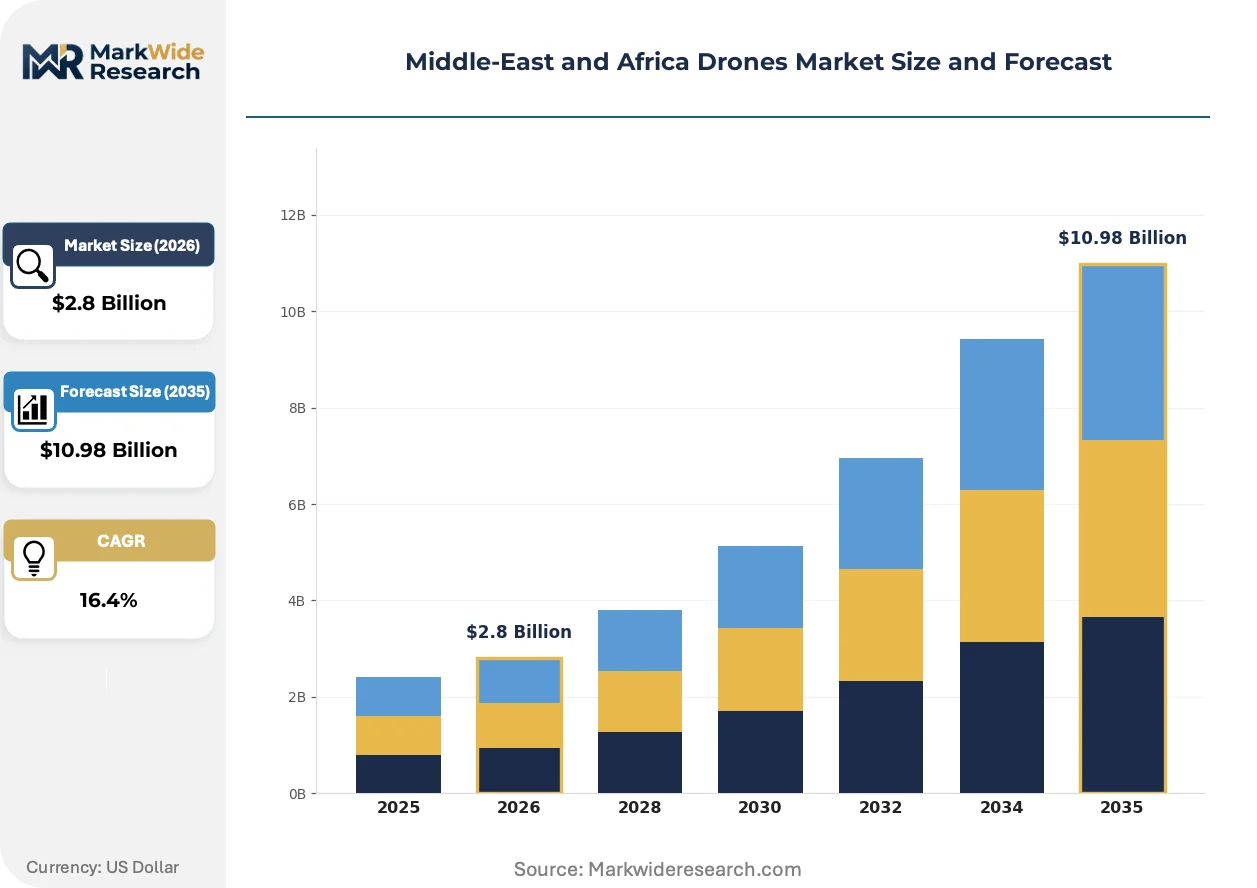
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Nano End User: Agriculture, Defense, Construction, Logistics Application: Aerial Photography, Surveillance, Delivery, Mapping Technology: Remote Sensing, Computer Vision, IoT Connectivity, Autonomous Navigation |
| Companies Covered | SZ DJI Technology Co., Ltd., Israel Aerospace Industries Ltd., AeroVironment Inc., Parrot SA, FalconViz, Elbit Systems Ltd., Baykar Makina Sanayi ve Ticaret A.S., BlueBird Aero Systems Ltd., EDGE Group PJSC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Drones Market Shifts & Advancements
Propulsion architecture decisions now determine contract outcomes across defense and commercial segments, while regulatory harmonization efforts between Gulf aviation authorities reshape market access patterns.
Swappable battery systems with automated ground stations are rendering obsolete manual swap protocols that previously capped daily flight cycles for agricultural spraying operators. Israeli and Moroccan precision agriculture contractors are adopting these systems at scale, compressing per-hectare service costs and enabling multi-shift operations during narrow application windows.
Saudi Arabia's General Authority of Civil Aviation issued updated remote pilot licensing rules that eliminate duplicate medical certification requirements for operators holding equivalent credentials from UAE or Jordanian authorities. This regulatory streamlining reduces onboarding timelines for cross-border commercial fleets and positions Riyadh as a licensing hub for Levant and Gulf operators seeking unified credentials.
Aftermarket service unbundling is accelerating across defense procurement as North African militaries separate platform acquisition from technical support agreements. Baykar Makina and Elbit Systems are responding with standalone maintenance contracts that compete directly with third-party MRO providers, compressing margins on traditional bundled sales models in Egypt and Algerian tenders.
Middle-East and Africa Drones Market Segmentation
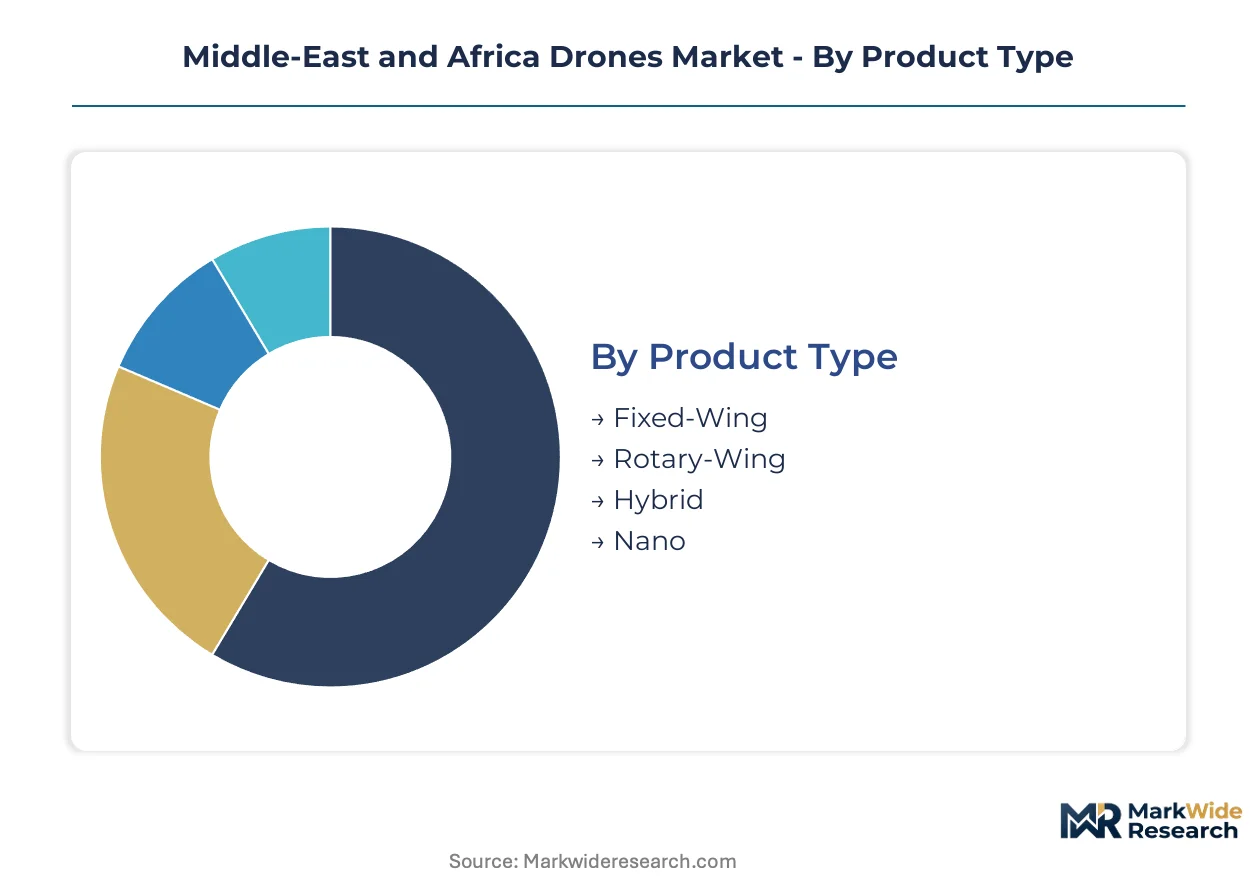
Segmentation across the Middle-East and Africa Drones Market reveals distinct service intensity profiles. Aftermarket revenue concentrates in defense and precision agriculture verticals where fleet uptime dictates contract renewal.
Product Type:
After-sales service intensity varies sharply across propulsion architectures, with hybrid platforms demanding specialized maintenance networks.
- Fixed-Wing:Long-endurance airframes with pusher or tractor propeller configurations dominate border surveillance contracts across Saudi Arabia and Algeria. Israeli defense procurement favors these systems for maritime patrol where loiter time determines mission effectiveness.
- Rotary-Wing:Multirotor configurations with swappable battery systems capture Moroccan and Egyptian agricultural spraying contracts. Vertical takeoff capability eliminates runway dependency in confined irrigation zones.
- Hybrid:Tiltrotor and tailsitter architectures combine runway independence with extended range, gaining share in UAE infrastructure inspection.
- Nano:Sub-250-gram platforms operate below Saudi GACA licensing thresholds for indoor security and confined-space reconnaissance.
By volume, Rotary-Wing leads. By growth pace, Hybrid is climbing the fastest.
End User:
Customer procurement patterns split between defense budget cycles and commercial operational expenditure models.
- Defense:Gulf state militaries prioritize platform reliability and captive technical support over acquisition cost, locking in multi-year service agreements with Israeli and Turkish suppliers.
- Agriculture:Moroccan and Egyptian cooperatives demand per-hectare pricing with guaranteed spray coverage rates, compressing hardware margins toward service-based revenue.
- Construction:UAE and Saudi project developers use drones for progress monitoring and earthwork volume calculations.
- Logistics:Nigerian and Kenyan last-mile operators pilot autonomous delivery corridors pending regulatory clearance.
Defense commands premium pricing. Agriculture shows the steepest volume expansion trajectory.
Application:
Use-case maturity determines whether buyers prioritize sensor payload or airframe endurance.
- Aerial Photography:Media and real estate marketing in Dubai and Cape Town drives demand for high-resolution gimbal systems with automated flight planning.
- Surveillance:Perimeter security contracts across Israeli critical infrastructure and Saudi oil facilities require thermal imaging and encrypted datalinks.
- Delivery:Dubai's drone corridor trials and Riyadh's regulatory sandbox testing shape payload-weight certification standards.
- Mapping:Surveying firms in South Africa and Morocco deploy LiDAR-equipped fixed-wing systems for mining and cadastral applications.
Surveillance generates highest revenue per flight hour. Delivery is gaining share fastest.
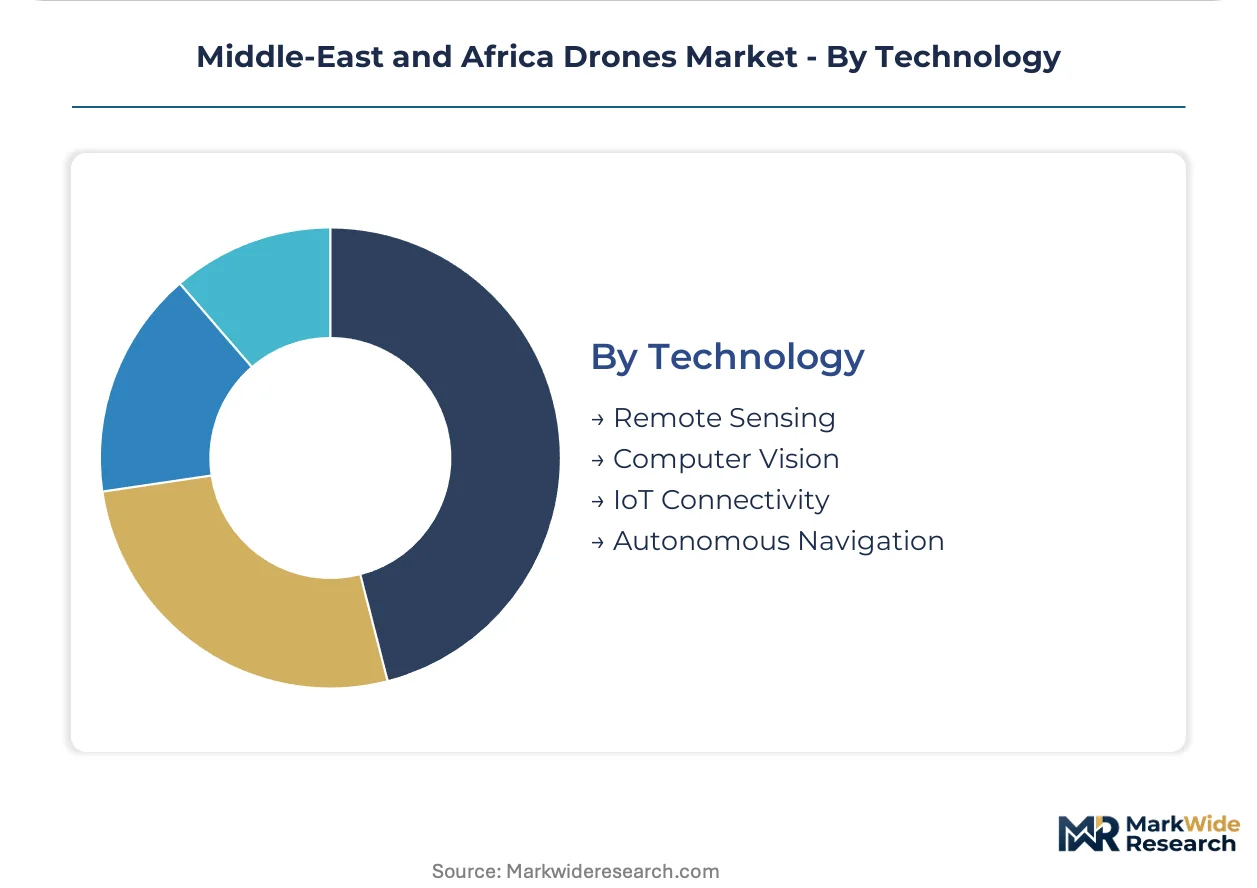
Technology:
Technology stack choices determine integration complexity with existing fleet management systems.
- Remote Sensing:Multispectral and thermal sensors enable crop health monitoring across Israeli kibbutzim and Moroccan agricultural zones.
- Computer Vision:Edge-processing obstacle detection supports autonomous navigation in GPS-denied environments.
- IoT Connectivity:Satellite and cellular datalinks extend command range for beyond-visual-line-of-sight operations in sub-Saharan logistics trials.
- Autonomous Navigation:AI-powered flight planning reduces operator labor costs for repetitive inspection missions.
Remote Sensing dominates current deployments. Autonomous Navigation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement in the Gulf prioritizes long-endurance surveillance platforms, while sub-Saharan operators concentrate on agricultural spraying and logistics trials with shorter-range rotary-wing systems.
United Arab Emirates
Dubai's drone delivery corridors and Abu Dhabi's surveillance infrastructure attract sustained fleet investment. MOHAP and the General Civil Aviation Authority coordinate payload-weight certification standards that shape regional type-approval pathways. The Dubai South logistics cluster hosts vertiport partnerships testing autonomous last-mile networks.
Saudi Arabia
Border surveillance and oil facility perimeter security drive fixed-wing procurement across Eastern Province installations. The General Authority of Civil Aviation issued updated remote pilot licensing rules that streamline commercial operations and eliminate duplicate medical certification for GCC-credentialed operators. Riyadh anchors licensing hub functions for Levant and Gulf cross-border fleets.
Israel
Maritime patrol and critical infrastructure protection prioritize loiter-time performance in defense contracts. The Civil Aviation Authority maintains distinct instructor accreditation standards that fragment training pipeline scalability. Israeli kibbutzim and precision agriculture contractors deploy multispectral sensing across coastal plains and northern irrigation zones.
South Africa
Mining survey firms and cadastral mapping operations deploy LiDAR-equipped systems across platinum and gold extraction regions. The South African Civil Aviation Authority enforces non-harmonized certification standards that multiply compliance costs for fleet operators. Johannesburg and Cape Town concentrate media and real estate aerial photography demand.
Morocco
Agricultural cooperatives demand per-hectare spraying contracts with guaranteed coverage rates across confined irrigation zones. Rotary-wing platforms with swappable battery systems capture volume from operators lacking runway infrastructure. Marrakech and Casablanca anchor precision agriculture service provider networks.
Middle-East and Africa Drones Market Competitive Landscape
Capability concentration sits with defense-specialized tier; scale advantage sits with commercial platform fabricators. The market structures around three tiers: Gulf state defense primes with captive technical support networks, Turkish and Israeli combat-proven suppliers, and Chinese commercial volume producers. Consolidation pressure runs through aftermarket service unbundling and cross-border certification harmonization.
Within the defense-specialized tier, Israel Aerospace Industries Ltd., Elbit Systems Ltd., and Baykar Makina Sanayi ve Ticaret A.S. exemplify archetypes built on sustained maintenance networks and combat-proven platform reliability. These entities anchor service agreements with North African and Gulf militaries where multi-year technical support locks out third-party MRO competition. SZ DJI Technology Co., Ltd. occupies a position representing commercial volume scale, while AeroVironment Inc. and Parrot SA sit within the mid-tier specialist segment addressing precision agriculture and infrastructure inspection.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd. |
| Israel Aerospace Industries Ltd. |
| AeroVironment Inc. |
| Parrot SA |
| FalconViz |
| Elbit Systems Ltd. |
| Baykar Makina Sanayi ve Ticaret A.S. |
| BlueBird Aero Systems Ltd. |
| EDGE Group PJSC |
| Others |
Supply & Pricing Matrix
Undercapacity in East Asian lithium-polymer cell manufacturing is tightening battery pack availability for African operators, compressing procurement timelines and amplifying price volatility across rotary-wing agricultural fleets. This utilization squeeze forces buyers toward longer-term offtake structures while suppliers prioritize Gulf defense contracts with captive technical support bundling.
Pricing Analysis
Long-term offtake agreements dominate defense procurement across Saudi Arabia and the UAE, where multi-year service contracts lock in platform-plus-maintenance pricing that insulates Israeli and Turkish suppliers from spot-market volatility. Price differentiation separates combat-proven platforms with captive MRO networks from commercial volume producers competing on hardware margins. Cost compression in the agricultural spraying tier is intensifying because Moroccan cooperatives demand per-hectare service pricing with guaranteed coverage rates. Agricultural end users exhibit highest price sensitivity, while Gulf militaries prioritize reliability over acquisition cost.
Supply Chain Analysis
Upstream feedstock concentration in Chinese and South Korean lithium-ion cell manufacturing anchors battery pack sourcing for sub-Saharan operators, while Israeli and Turkish airframe fabrication centers on domestic defense supply chains with limited export capacity. Raw material dependencies span lithium carbonate, nickel-manganese-cobalt cathode formulations, and carbon-fiber composite airframes. Single-source vulnerability in East Asian cell production exposes African fleet operators to currency volatility and extended lead times. Distribution runs through Dubai-based logistics hubs serving Gulf markets, with direct manufacturer relationships penetrating North African defense tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. SFDA-aligned certification standards and GACA licensing harmonization erect switching costs that favor established suppliers with dedicated compliance infrastructure.
For Market Incumbents: Entrench position through backward integration into predictive maintenance software and satellite telemetry infrastructure, locking in condition-based service contracts that displace third-party MRO providers. Expand captive technical support networks across Egyptian and Algerian defense tenders before Baykar Makina and Elbit Systems consolidate standalone maintenance agreements. Priority lever rests on vertiport partnerships in Nigerian logistics corridors to preempt autonomous delivery network control. For New Entrants and Emerging Players: Build out precision agriculture service capabilities in Morocco's confined irrigation zones, where rotary-wing spraying contracts remain fragmented among local cooperatives lacking runway infrastructure. Target Kenyan and Nigerian last-mile logistics trials pending C-band spectrum finalization, positioning for first-mover advantage in corridor development. Go-to-market angle centers on swappable battery systems with automated ground stations that compress per-hectare costs below manual-swap competitor offerings. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among defense-specialized tier suppliers with multi-year technical support agreements anchoring North African and Gulf military contracts. Long-term viability over the projection horizon favors platforms with combat-proven reliability and captive MRO networks that resist third-party competition. Acquisition target archetype: mid-tier hybrid platform specialists with UAE-GCC regulatory certification and established vertiport partnerships. Signal to watch is harmonization progress between Saudi GACA and sub-Saharan regulators, which would unlock cross-border fleet deployments and reshape addressable market scale.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | SFDA-aligned GACA licensing streamlines cross-border commercial operations for GCC-credentialed operators. |
| Predictive Maintenance Platform Development | AI-enabled condition-based contracts displace scheduled overhaul models in Saudi defense procurement. |
| Vertiport Infrastructure Partnership | Dubai South logistics cluster anchors autonomous last-mile network testing for MOHAP-coordinated standards. |
| Hybrid Propulsion R&D Scale-Up | Tiltrotor architectures gain share in UAE infrastructure inspection where runway independence determines contract awards. |
| Swappable Battery System Deployment | Automated ground stations compress per-hectare agricultural spraying costs across Moroccan irrigation zones. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with defense procurement officers at Gulf state militaries, commercial drone operators in Moroccan agricultural cooperatives, regulatory affairs leads at Saudi GACA and UAE GCAA, and precision agriculture service providers; alongside secondary validation through civil aviation authority licensing databases, defense tender documentation, and customs trade records for lithium-polymer battery imports. Bottom-up fleet deployment estimates triangulated against top-down defense budget allocation analysis.
Forecast inputs spanned propulsion architecture adoption curves, regulatory harmonization timelines between Gulf and sub-Saharan authorities, and battery chemistry cost trajectories across the analysis window. Segmentation dimensions modeled included product type, end-user procurement pattern, application maturity, and technology stack integration complexity. CAGRs derived from slope analysis of historical fleet deployment data projected through stated policy targets and announced infrastructure investments.
Stress conditions across lithium supply concentration, C-band spectrum allocation delays, and GCC regulatory convergence pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense budget continuity and commercial operator certification pipeline scalability. Quarterly review of GACA-UAE GCAA harmonization progress and Nigerian logistics corridor regulatory clearance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
UAV Simulator Software Market
UAV
Global Smartphone Controlled Drone Market
UAV
Asia Pacific Commercial Drone Market
UAV
Drone Telematics Market
UAV
Ultra-Long Endurance Drone Market
UAV
Europe Tactical UAV Market
UAV
Global Drone Services Market
UAV
Auto-Follow Drone Market
UAV
Micro Drone Market
UAV
Commercial Drone-Enabled Services Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Latin America Small UAV Market
UAV
North America Drone Services Market
UAV
Drone Tracking Antenna Market
UAV
Commercial Drone Market
UAV
Drone Lens Market