
 Microrna (Mirna) Market | 2026-2036
Microrna (Mirna) Market Size, Share, and Industry Trends Forecast 2026-2036
Microrna (Mirna) Market Intelligence
Direct-to-biopharma supply contracts is tilting toward specialized reagent vendors with end-to-end manufacturing capabilities. Thermo Fisher Scientific leverages its integrated instrumentation and consumables platform to dominate research-grade miRNA workflow sales. QIAGEN anchors its position through sample preparation technologies that standardize miRNA isolation across clinical and academic settings. Merck KGaA competes in the high-purity synthetic RNA segment with GMP-compliant manufacturing infrastructure.
MicroRNA constitutes a class of endogenous, non-coding RNA molecules approximately 18-25 nucleotides in length that regulate gene expression post-transcriptionally through complementary base-pairing with target messenger RNA transcripts. These molecules function primarily as fine-tuners of cellular differentiation, proliferation, and apoptosis, making them critical tools for therapeutic intervention and biomarker discovery. Among product types, miRNA mimics and inhibitors command the largest revenue share due to established use in loss-of-function and gain-of-function studies, while exosome-based delivery methods represent the fastest-growing segment as researchers seek cell-specific targeting with reduced immunogenicity. Oncology applications within the therapy area dimension absorb the majority of development investment, though neurological disorder indications are gaining traction as blood-brain barrier penetration technologies mature.
FDA oversight of nucleic acid therapeutics through its Office of Therapeutic Biologics and EMA's Committee for Advanced Therapies establish stringent purity and stability standards that shape manufacturing investments. ISO 13485 quality management requirements and GMP guidelines from national regulators further constrain market entry for suppliers lacking validated production systems. Stakeholders must monitor evolving pharmacovigilance expectations for oligonucleotide drugs as first-generation miRNA therapeutics advance through late-stage clinical evaluation.
Market Dynamics
FDA accelerated approval pathways for nucleic acid therapeutics are compressing clinical trial timelines and forcing CMOs to build GMP-compliant oligonucleotide manufacturing capacity ahead of confirmed demand.
Growth Catalysts
- Oncology pipeline expansion:Pharmaceutical developers are prioritizing miRNA therapeutics for solid tumor indications, with loss-of-function studies driving consistent demand for synthetic mimics and antagomirs.
- EMA Committee for Advanced Therapies guidance:Streamlined quality standards for nucleic acid drugs are reducing regulatory uncertainty and attracting European biotech investment into miRNA platforms.
- Exosome engineering advances:Cell-derived vesicle delivery systems are solving immunogenicity limitations that constrained first-generation lipid nanoparticle formulations.
Market Restraints
- High-purity reagent cost structure:Phosphoramidite monomer prices and GMP-grade solvent costs constrain margin expansion for synthetic RNA suppliers.
- Manufacturing concentration risk:Oligonucleotide synthesis capacity clusters in Germany and Switzerland, creating single-source vulnerability for European clinical programs.
- Stability technical limitation:RNase contamination susceptibility during handling and storage necessitates cold-chain infrastructure that limits distribution reach.
Strategic Opportunities
- Neurological disorder white space:Blood-brain barrier penetration technologies are maturing, opening CNS applications that were previously inaccessible to nucleic acid drugs.
- Direct-to-biopharma channel innovation:Specialized reagent vendors are bypassing traditional distribution layers through end-to-end manufacturing contracts with integrated quality documentation.
- Japan PMDA regenerative medicine framework:Conditional approval pathways for nucleic acid therapies are incentivizing early clinical entry for miRNA candidates in orphan indications.
Industry Challenges
- PhD-level synthesis chemist scarcity:Oligonucleotide manufacturing requires specialized expertise in phosphoramidite chemistry that outpaces academic program output.
- ISO 13485 certification timeline:Diagnostic-grade miRNA assay suppliers face extended validation periods that delay product commercialization.
- IP thickets around seed sequence patents:Freedom-to-operate analyses for miRNA mimics must navigate overlapping university and biotech licensing claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microrna (Mirna) Market |
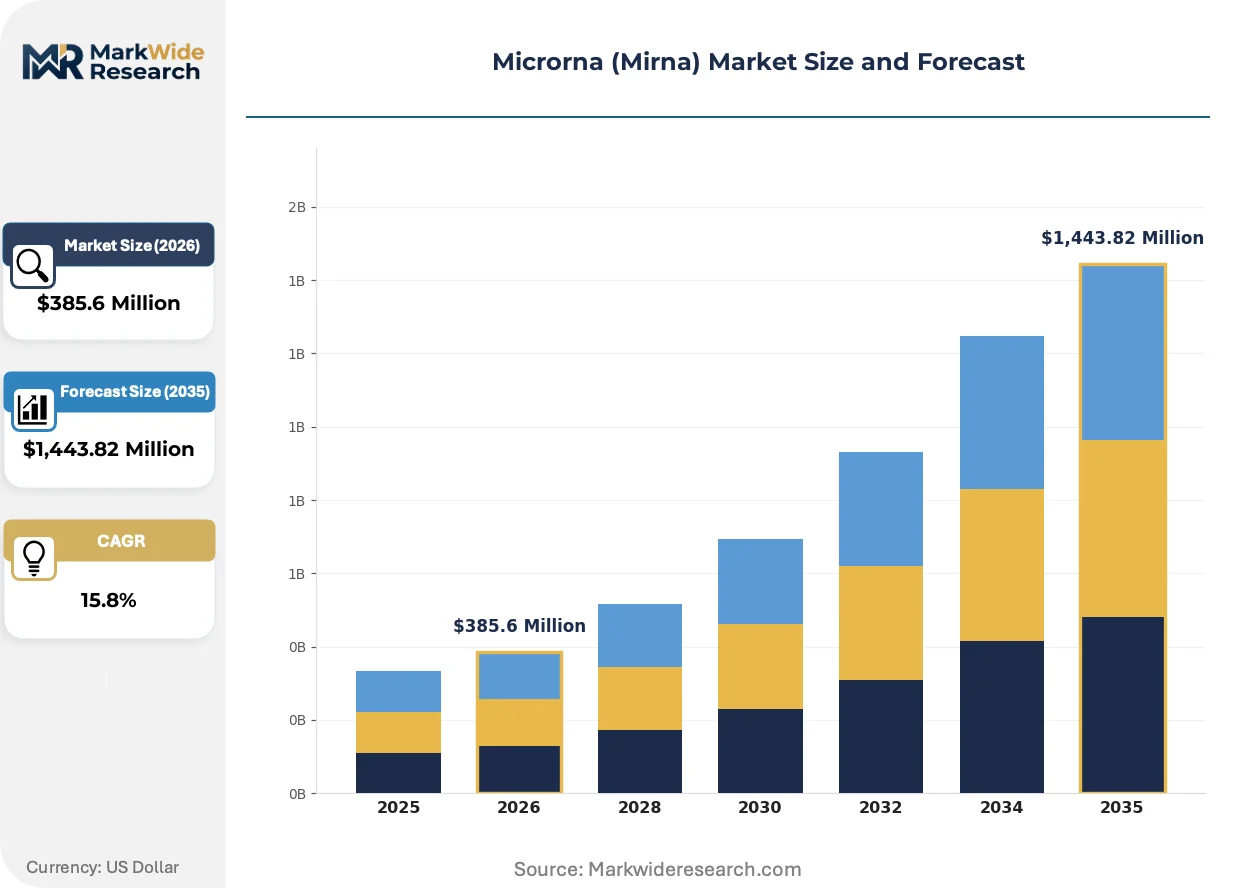
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,443.82 Million |
| CAGR (2026 – 2036) | 15.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mirna Mimics, Mirna Inhibitors, Mirna Sponges, Mirna Reporters, Mirna Vectors Therapy Area: Oncology, Neurological Disorders, Cardiovascular Diseases, Metabolic Disorders, Infectious Diseases End User: Biotechnology Firms, Pharmaceutical Companies, Research Institutions, Academic Laboratories, Contract Research Organizations Delivery Method: Lipid Nanoparticles, Viral Vectors, Exosomes, Polymer-Based Carriers, Electroporation |
| Companies Covered | Thermo Fisher Scientific, QIAGEN, Merck KGaA, Horizon Discovery Group, NanoString Technologies, Takara Bio, Agilent Technologies, New England Biolabs, GeneCopoeia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microrna (Mirna) Market Strategic Shifts & Innovations
Delivery technology convergence and regulatory pathway maturation are redefining competitive advantage in nucleic acid therapeutics, with manufacturing scale and quality documentation becoming primary differentiators.
Lipid nanoparticle-mRNA platforms from COVID-19 vaccine development are hybridizing with miRNA payloads, enabling liver-targeted delivery systems that pharmaceutical developers are repurposing for metabolic disease applications. Large-cap biopharma sponsors are prioritizing these hybrid formulations over traditional viral vectors, compressing development timelines for rare disease programs.
REACH chemical registration requirements in Europe are forcing oligonucleotide manufacturers to document environmental fate and toxicity profiles for synthetic reagents. ECHA compliance costs are disproportionately burdening mid-scale suppliers, pushing consolidation toward integrated chemical producers with dedicated regulatory affairs functions.
Biopharma procurement teams are consolidating vendor panels around suppliers offering combined instrumentation, consumables, and GMP-grade reagents. Academic core facilities and emerging biotechs face reduced negotiating leverage as preferred vendor agreements lock in multi-year supply commitments, particularly visible in United States coastal research clusters.
Microrna (Mirna) Market Segmentation
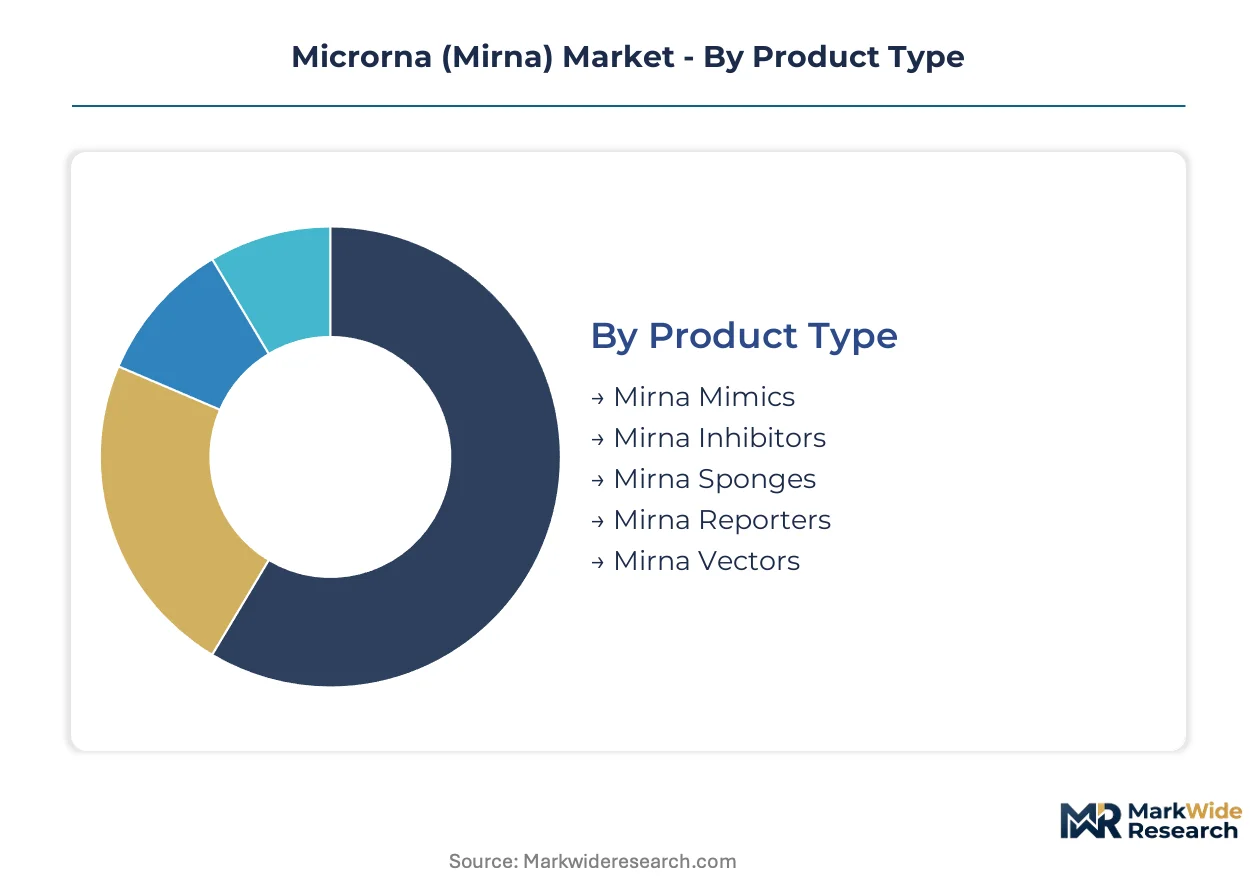
Segmentation in the miRNA market reflects divergent technical requirements across therapeutic development stages. Product specifications vary sharply between research-grade discovery tools and GMP-compliant clinical materials, while delivery technology choices determine addressable patient populations and regulatory pathways.
Product Type:
Cost tiers separate research-grade reagents from clinical-grade materials, with purity specifications and documentation requirements driving price stratification.
- miRNA Mimics:Synthetic double-stranded RNA molecules engineered to restore downregulated miRNA function in disease states. Pharmaceutical companies in the United States concentrate procurement for oncology loss-of-function studies, though phosphoramidite synthesis costs constrain margin expansion.
- miRNA Inhibitors:Chemically modified antagomirs and locked nucleic acid constructs that sequester endogenous miRNA activity. Academic laboratories in Boston and San Francisco clusters drive consistent demand for standardized inhibitor libraries with validated target specificity.
- miRNA Sponges:Decoy transcripts with multiple miRNA binding sites that competitively absorb target molecules. Research institutions deploy these for pathway mapping in complex regulatory networks.
- miRNA Reporters:Sensor constructs linking miRNA recognition to quantifiable output signals. Contract research organizations integrate these into high-throughput screening workflows.
- miRNA Vectors:Plasmid and viral delivery systems encoding precursor miRNA sequences. Biotechnology firms prioritize these for stable expression in hard-to-transfect cell lines.
miRNA mimics and inhibitors command the established base. The steepest expansion runs through exosome-compatible vector formats.
Therapy Area:
Application focus determines investment intensity, with oncology absorbing the majority of clinical-stage capital while neurological indications attract preclinical venture funding.
- Oncology:Solid tumor and hematological malignancy programs targeting oncomiR suppression or tumor suppressor miRNA restoration. FDA accelerated approval pathways for nucleic acid therapeutics are compressing Phase I/II timelines for liver cancer and melanoma candidates.
- Neurological Disorders:Alzheimer's, Parkinson's, and amyotrophic lateral sclerosis applications leveraging blood-brain barrier penetration advances. EMA Committee for Advanced Therapies guidance is reducing regulatory uncertainty for European biotechs pursuing CNS delivery.
- Cardiovascular Diseases:Atherosclerosis and heart failure modulation through endothelial miRNA targeting. Pharmaceutical companies prioritize these for established patient populations with clear clinical endpoints.
- Metabolic Disorders:Type 2 diabetes and non-alcoholic steatohepatitis interventions via liver-directed miRNA regulation. Lipid nanoparticle platforms from COVID-19 vaccine development are repurposing for metabolic applications.
- Infectious Diseases:Viral host factor modulation and antiviral miRNA enhancement. Research institutions concentrate funding on emerging pathogen response capabilities.
Oncology applications anchor current revenue. Neurological disorder programs are climbing the fastest as delivery technologies mature.
End User:
Customer type dictates purchasing patterns, with large-cap biopharma consolidating vendors around integrated supply contracts while academic buyers fragment across specialized catalogs.
- Biotechnology Firms:Emerging and mid-cap developers advancing proprietary miRNA platforms toward clinical proof-of-concept. These organizations prioritize flexible GMP manufacturing partnerships over captive capacity.
- Pharmaceutical Companies:Large-cap sponsors with established nucleic acid therapeutic pipelines. Direct-to-biopharma supply contracts are tilting toward specialized reagent vendors with end-to-end manufacturing capabilities.
- Research Institutions:National laboratories and dedicated RNA research centers. Academic core facilities face reduced negotiating leverage as preferred vendor agreements lock in multi-year supply commitments.
- Academic Laboratories:University-based investigators pursuing mechanistic miRNA biology. These buyers concentrate in United States coastal research clusters with concentrated venture funding access.
- Contract Research Organizations:Service providers supporting pharmaceutical and biotech clients. ISO 13485 certification timelines constrain diagnostic-grade assay commercialization for these suppliers.
Pharmaceutical companies represent the established base. Biotechnology firms are gaining share fastest as venture funding concentrates in RNA platform specialists.
Delivery Method:
Technical maturity and immunogenicity profiles differentiate delivery approaches, with first-generation lipid systems ceding ground to engineered biological vehicles.
- Lipid Nanoparticles:Ionizable lipid formulations enabling endosomal escape and cytoplasmic RNA release. Liver-targeted systems dominate metabolic disease applications, though immunogenicity limitations constrain repeat dosing.
- Viral Vectors:Adeno-associated and lentiviral systems for stable, high-efficiency transduction. Neurological disorder programs in Japan leverage PMDA conditional approval pathways for orphan indication viral delivery candidates.
- Exosomes:Cell-derived extracellular vesicles with intrinsic tissue-targeting properties. Exosome engineering advances are solving immunogenicity limitations that constrained first-generation lipid nanoparticle formulations.
- Polymer-Based Carriers:Cationic and biodegradable synthetic polymers for complexation with nucleic acid payloads. Research institutions utilize these for cost-sensitive screening applications.
- Electroporation:Physical membrane disruption enabling naked RNA entry. Contract research organizations apply this for ex vivo cell therapy modification where vector persistence poses regulatory challenges.
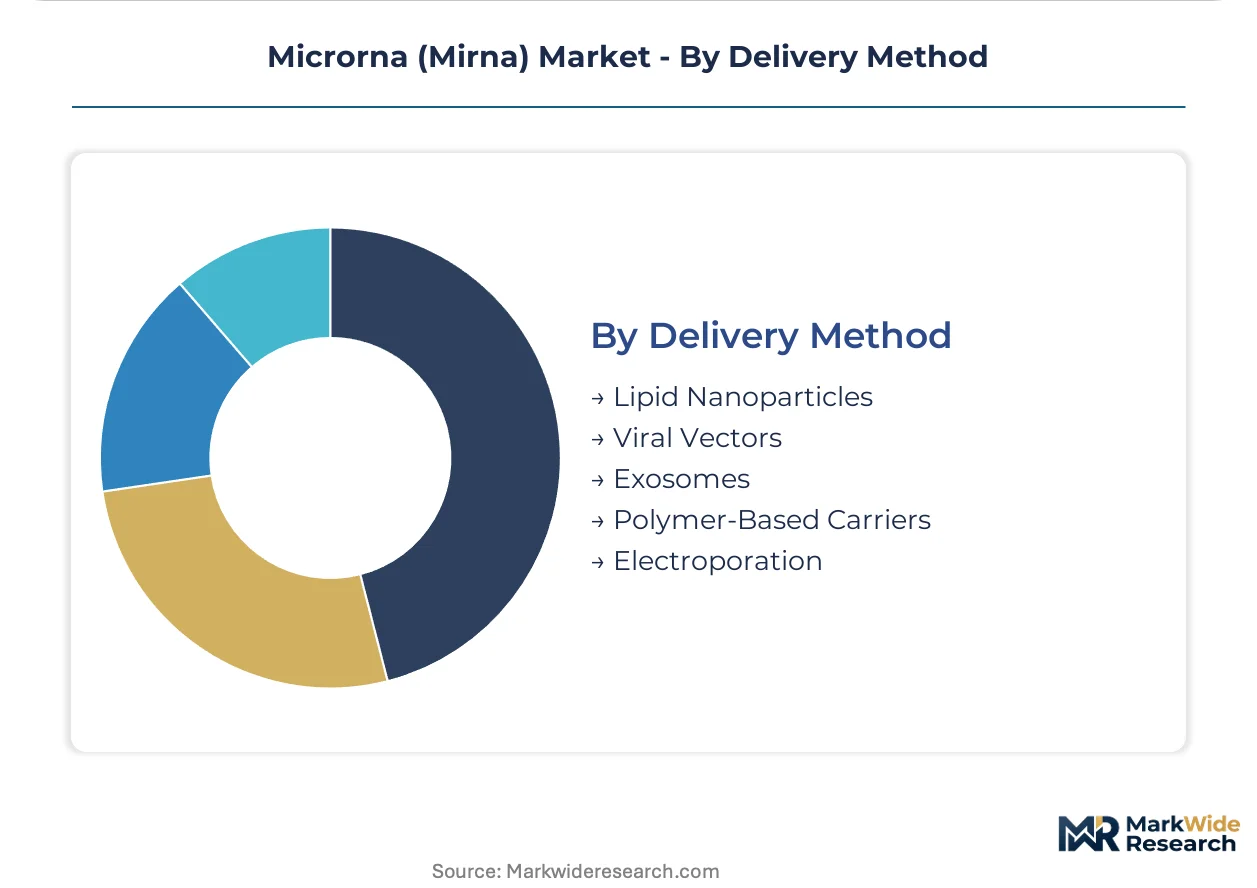
Lipid nanoparticles command the established base. Exosome-based delivery is climbing the fastest as cell-specific targeting capabilities advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for nucleic acid therapeutics anchor United States demand, while EMA and PMDA frameworks reshape competitive positioning across Germany and Japan. National regulators in Switzerland and the United Kingdom complete a five-country concentration spanning North America and Europe.
United States
Boston and San Francisco biotech clusters attract concentrated venture funding for RNA-based drug development. FDA Office of Therapeutic Biologics oversight establishes stringent purity standards that shape manufacturing investments for clinical-grade materials. Massachusetts and California research institutions drive consistent demand for miRNA mimics and inhibitor libraries.
Germany
EMA Committee for Advanced Therapies guidance reduces regulatory uncertainty for European biotech investment into miRNA platforms. REACH chemical registration requirements force manufacturers to document environmental fate profiles for synthetic reagents. Oligonucleotide synthesis capacity clusters in German chemical manufacturing corridors, creating supply concentration for European clinical programs.
Switzerland
Swissmedic quality standards attract GMP-compliant manufacturing infrastructure for high-purity synthetic RNA segments. Basel and Zurich pharmaceutical hubs host specialized reagent vendors with end-to-end production capabilities. Swiss chemical producers leverage dedicated regulatory affairs functions to manage ECHA compliance costs.
Japan
PMDA regenerative medicine framework incentivizes early clinical entry for miRNA candidates in orphan indications. Tokyo and Osaka research centers concentrate academic demand for standardized miRNA isolation technologies. METI funding programs support blood-brain barrier penetration research for neurological disorder applications.
United Kingdom
London and Cambridge biotech clusters pursue nucleic acid therapeutic pipelines with streamlined MHRA approval pathways post-Brexit. UK research institutions fragment purchasing across specialized catalogs for mechanistic miRNA biology studies. ISO 13485 certification timelines constrain diagnostic-grade assay commercialization for domestic contract research organizations.
Microrna (Mirna) Market Key Industry Players
Integrated instrumentation conglomerates and specialized reagent vendors split the market between research-grade workflow dominance and clinical-grade material supply. The vendor base concentrates around three strategic archetypes: diversified life science tools providers, sample preparation technology specialists, and high-purity synthetic RNA manufacturers. Consolidation pressures favor multi-year preferred vendor agreements that lock in supply commitments across coastal United States research clusters. Capacity expansion and GMP certification represent the dominant competitive moves as CMOs build oligonucleotide manufacturing ahead of confirmed demand.
Among diversified life science tools providers, Thermo Fisher Scientific exemplifies the integrated instrumentation and consumables archetype, while QIAGEN anchors the sample preparation technology specialist position. Merck KGaA occupies a position within the high-purity synthetic RNA manufacturing tier. These three companies represent contrasting strategic postures across the research-to-clinical value chain, with each archetype facing distinct margin pressures from phosphoramidite monomer costs and GMP-grade solvent requirements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN |
| Merck KGaA |
| Horizon Discovery Group |
| NanoString Technologies |
| Takara Bio |
| Agilent Technologies |
| New England Biolabs |
| GeneCopoeia |
| Others |
Cost & Logistics Intelligence
Undercapacity in European GMP-grade oligonucleotide synthesis is forcing pharmaceutical sponsors to accept premium pricing for clinical-grade miRNA materials, while simultaneously accelerating backward integration investments among large-cap biopharma manufacturers seeking supply security.
Pricing Analysis
Price spreads between German-manufactured clinical-grade miRNA mimics and research-grade alternatives from United States suppliers reach three-to-one multiples, with ISO 13485 certification and EMA documentation packages driving premium-mid-economy pricing differentiation. Phosphoramidite monomer costs and GMP solvent purity requirements compress margins for synthetic RNA vendors. Pricing pressure stems from biopharma procurement consolidation around preferred vendor agreements. Academic laboratories exhibit highest price sensitivity, while pharmaceutical companies prioritize quality documentation over unit cost.
Supply Chain Analysis
Phosphoramidite monomer production concentrates in Germany, Switzerland, and the United States, with specialized chemical manufacturers controlling upstream feedstock for oligonucleotide synthesis. High-purity solvents and modified nucleosides draw from petrochemical and fine chemical suppliers. Single-source vulnerability runs through German chemical manufacturing corridors for European clinical programs. Distribution runs through direct-to-biopharma contracts that bypass traditional distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The miRNA market rewards organizations that secure scarce phosphoramidite chemistry expertise and validated GMP manufacturing infrastructure, with capability gaps in synthetic RNA production creating durable competitive advantages for early movers.
For Market Incumbents: Build regulatory documentation moats by investing in EMA quality agreements and FDA master file submissions ahead of competitor filings. Consolidate vendor relationships through multi-year preferred supply agreements with biopharma sponsors. Expand captive phosphoramidite synthesis capacity in Switzerland to reduce exposure to German supply concentration. Lock in academic core facility partnerships through integrated instrumentation and consumables bundling.
For New Entrants and Emerging Players: Japan's underpenetrated neurological disorder segment offers accessible entry points via PMDA conditional approval pathways for orphan indication miRNA candidates. Target exosome engineering capabilities as the most penetrable delivery technology niche, with cell-derived vesicle manufacturing expertise scarce among established suppliers. Pursue direct-to-biopharma channel strategies that bypass traditional distribution markups through end-to-end manufacturing contracts with integrated quality documentation.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized CMOs with validated GMP oligonucleotide capacity and existing EMA regulatory relationships. Long-term viability hinges on manufacturing scale and quality documentation capabilities rather than discovery platform breadth. Watch blood-brain barrier penetration technology maturation as the inflection signal for CNS application market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | EMA and FDA quality agreements lock in multi-year biopharma supply commitments. |
| Regulatory Approval Pathway | PMDA conditional approval accelerates orphan indication miRNA candidate entry in Japan. |
| Backward Integration | Captive phosphoramidite synthesis reduces German chemical corridor supply vulnerability. |
| Delivery Technology Licensing | Exosome engineering patents enable cell-specific targeting with reduced immunogenicity profiles. |
| Clinical Trial Advancement | FDA accelerated pathways compress Phase I/II timelines for liver cancer and melanoma programs. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, GMP manufacturing directors, and academic core facility managers. Secondary validation drew from FDA Office of Therapeutic Biologics guidance documents, EMA Committee for Advanced Therapies submissions, ClinicalTrials.gov nucleic acid therapeutic entries, and REACH chemical registration databases. Bottom-up demand modeling across end-user segments was triangulated against top-down market sizing from synthetic RNA production capacity estimates.
Calibration against historical miRNA therapeutic pipeline progression and regulatory approval velocity anchored the analytical framework across the projection horizon. Segmentation dimensions included product type, therapy area, end user category, and delivery method complexity. CAGRs were derived from weighted average growth rates across these segments. Forecast inputs incorporated phosphoramidite monomer cost trajectories and GMP certification timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by large-cap biopharma manufacturers or disruptive delivery technology breakthroughs would shift outcomes beyond modeled ranges. Cross-checking against EMA nucleic acid therapeutic approval databases and venture funding flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
China Computational Biology Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
US Computational Biology Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
Bioinformatics Market
Bioinformatics
North America Computational Biology Market
Bioinformatics
Global Biological Data Visualization Market