
 Global Chemoinformatics Market | 2026-2036
Global Chemoinformatics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemoinformatics Market Foresight
The shift from single-source to multi-source algorithm licensing is rebalancing procurement patterns across pharmaceutical R&D departments. Schrödinger leverages its physics-based simulation engine to anchor high-value contracts with top-tier drug developers. BioSolveIT GmbH differentiates through fragment-based design tools that occupy a specialized niche in early-stage hit identification. Agilent Technologies extends its instrumentation heritage into informatics workflows that compete on integration depth with laboratory hardware systems.
Chemoinformatics encompasses computational methods for storing, indexing, searching, retrieving, and applying chemical information, typically handling molecular structures through SMILES strings, InChI identifiers, and fingerprint algorithms at sub-angstrom resolution. Its primary commercial purpose is accelerating molecular design decisions by predicting properties such as solubility, toxicity, and target binding affinity before synthesis. Software tools command the largest revenue share as persistent licensing models sustain predictable income streams for vendors. Machine learning represents the fastest-expanding technology segment as neural architectures displace traditional QSAR equations in property prediction tasks. Drug discovery absorbs the majority of application-specific spending, though environmental assessment is gaining traction under tightening chemical safety mandates.
FDA guidelines on computational toxicology predictions, REACH registration requirements in Europe, and Japan's PMDA acceptance of in-silico data for regulatory submissions are converging to validate simulation-driven decision-making. These frameworks elevate software auditability and model documentation standards, effectively filtering vendors without rigorous validation protocols. ISO standards for computational chemistry further codify quality benchmarks that shape procurement criteria at multinational pharmaceutical firms. Stakeholders must monitor evolving regulatory acceptance thresholds for AI-generated molecular predictions as agencies develop formal guidance on model interpretability requirements.
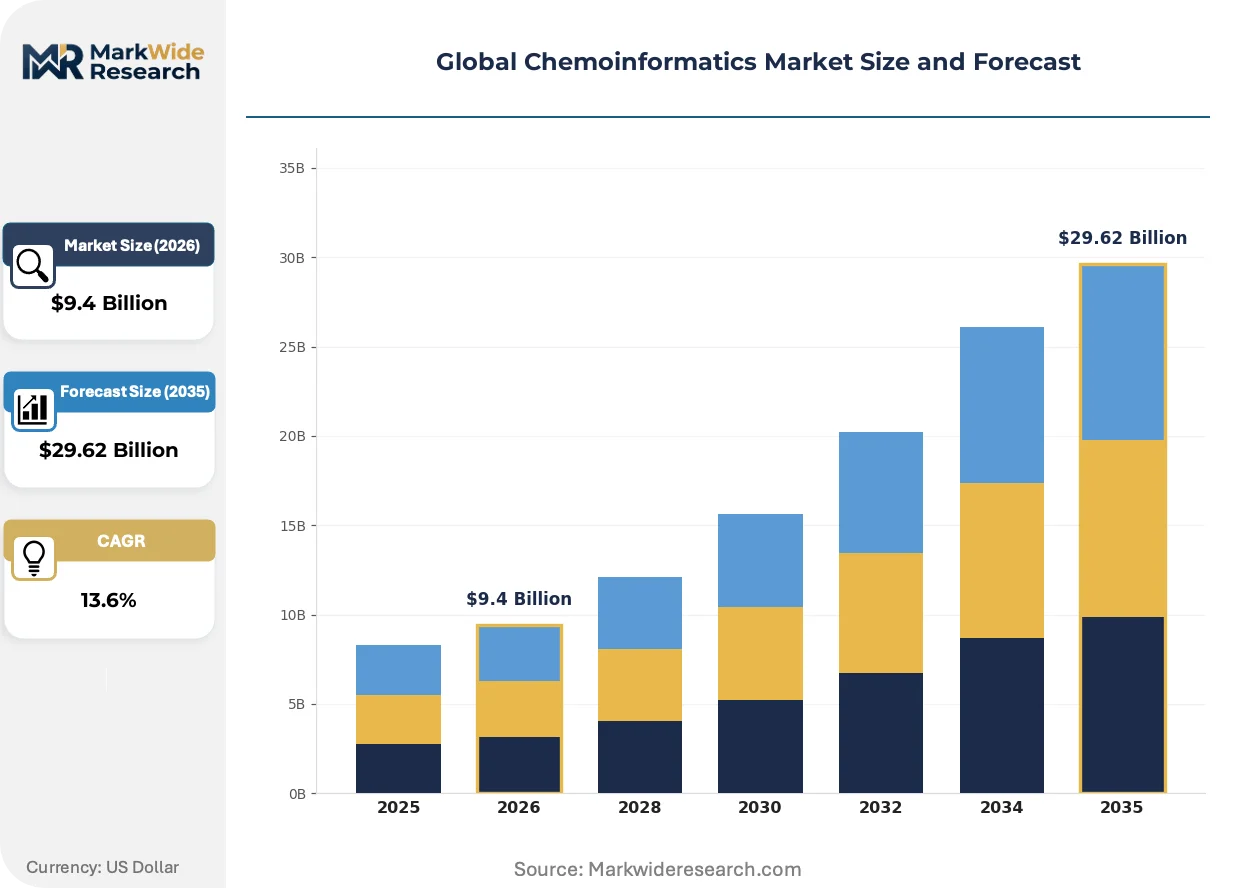
Market Dynamics
Machine learning architectures are compressing molecular property prediction timelines from months to days, forcing pharmaceutical R&D departments to restructure their software procurement criteria around neural model interpretability rather than traditional QSAR validation protocols.
Growth Catalysts
- REACH registration mandates:European chemical safety requirements under ECHA are accelerating demand for predictive toxicology platforms that replace animal testing with computational models.
- Fragment-based drug design:Early-stage hit identification workflows in biotechnology firms are integrating specialized cheminformatics toolkits for scaffold hopping and molecular fragment assembly.
- Japan:PMDA acceptance of in-silico data for regulatory submissions is validating simulation-driven decision-making among domestic pharmaceutical developers.
Market Restraints
- Computational infrastructure costs:GPU clusters required for training large molecular language models impose capital barriers on mid-tier research institutions.
- Data silo fragmentation:Proprietary compound libraries locked behind pharmaceutical firm firewalls limit training data availability for vendor model development.
- FDA interpretability requirements:Emerging guidance on explainable AI for regulatory submissions is creating compliance friction for black-box neural architectures.
Strategic Opportunities
- Environmental toxicology:Industrial chemical safety assessment represents an underpenetrated application segment as manufacturers face tightening discharge monitoring mandates.
- Generative chemistry convergence:Diffusion models combined with physics-based scoring functions are opening new design spaces beyond traditional library enumeration.
- Cloud-native deployment:Subscription-based access models are displacing perpetual licenses among academic consortia in Germany and the United Kingdom.
Industry Challenges
- Cross-functional talent scarcity:Computational chemists with simultaneous expertise in neural architecture design and medicinal chemistry principles command premium compensation packages.
- Legacy system integration:Enterprise LIMS and ELN platforms built on 1990s architectures resist API connectivity with modern Python-based cheminformatics pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemoinformatics Market |
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $29.62 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Tools, Data Analysis Platforms, Visualization Solutions, Predictive Models, Database Management Systems Technology: Machine Learning, Molecular Modeling, Quantitative Structure-Activity Relationship, Virtual Screening, High-Throughput Screening Application: Drug Discovery, Environmental Assessment, Agrochemical Development, Material Science, Cosmetic Formulation End User: Pharmaceutical Firms, Research Institutes, Agricultural Corporations, Chemical Manufacturers, Academic Organizations |
| Companies Covered | ChemAxon, PerkinElmer, Scilligence, Molecular Discovery Ltd., Agilent Technologies, BioSolveIT GmbH, Schrödinger, OpenEye Scientific Software, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemoinformatics Market Shifts & Advancements
Generative molecular design is shifting from rule-based enumeration to neural synthesis planning, compressing the iteration cycle between target identification and validated lead compounds.
Transformer architectures trained on chemical reaction databases are automating retrosynthetic route prediction for medicinal chemistry teams at scale. Major pharmaceutical developers in the United States and Switzerland are deploying these systems for parallel synthesis campaign design. The technology is automating what previously required dedicated computational chemistry FTEs, reallocating human expertise toward biological validation.
EMA qualification opinions on novel methodologies are establishing precedent for accepting quantum mechanical descriptors in regulatory submissions. This framework elevates documentation standards for force field parameterization and basis set selection. European contract research organizations are responding by building dedicated QM validation teams to support client filings.
Consortium-based data sharing is displacing single-firm compound libraries as the primary training resource for property prediction models. The Structural Genomics Consortium and similar pre-competitive collaborations in the United Kingdom and Japan are pooling ADMET data to benchmark algorithm performance. This pooling arrangement is most visible among mid-cap biotechnology firms lacking proprietary archives sufficient for in-house model training.
Global Chemoinformatics Market Segmentation
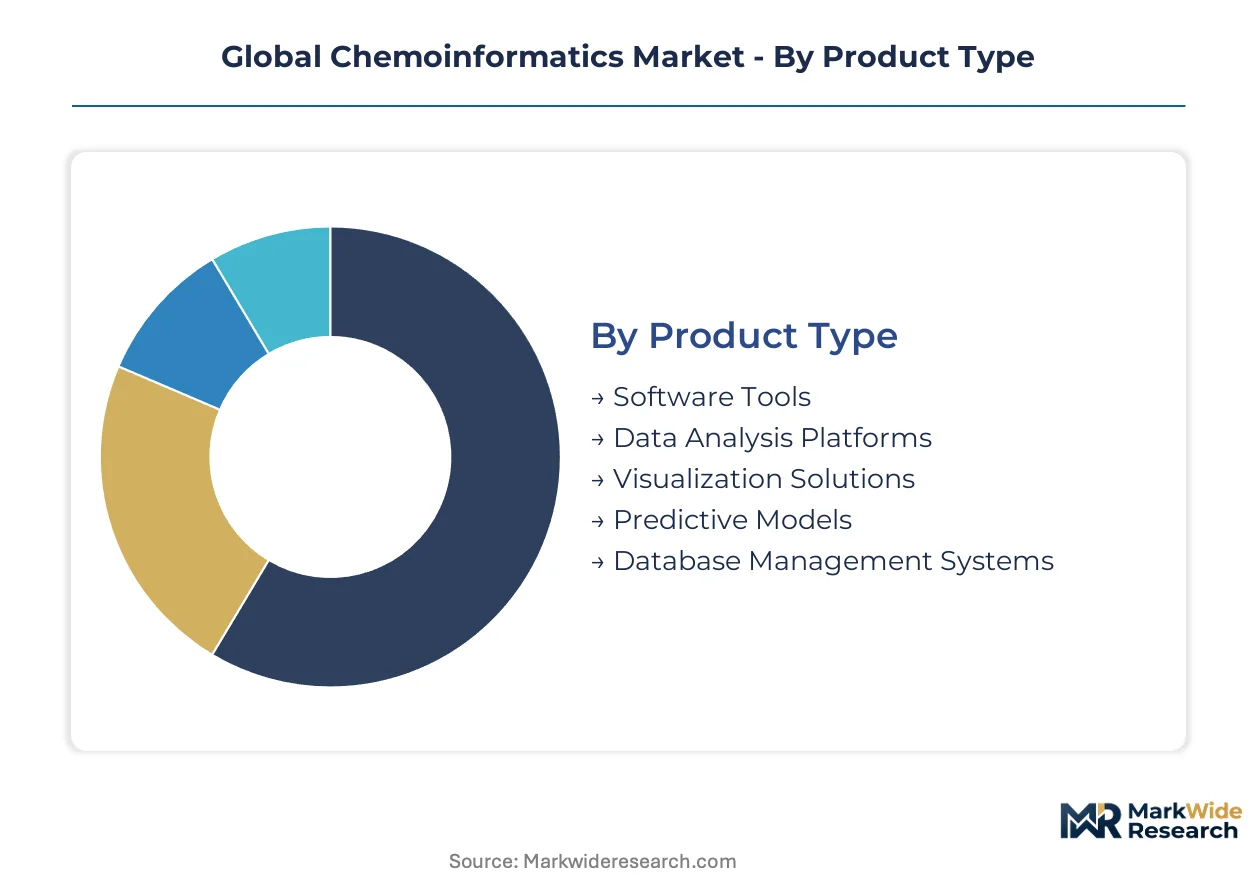
Chemoinformatics procurement varies sharply by technical sophistication and integration depth. Pharmaceutical R&D departments prioritize predictive accuracy and regulatory auditability over cost minimization. Academic consortia trade model complexity for accessibility and training support.
Product Type:
Standardization dominates at the infrastructure layer while customization concentrates at the workflow interface.
- Software Tools:Persistent licensing models for molecular property prediction and compound library management anchor vendor revenue. Demand clusters in United States pharmaceutical clusters where FDA audit trails mandate version-controlled deployment.
- Data Analysis Platforms:Cloud-native architectures with API connectivity to LIMS and ELN systems are displacing desktop installations. German and United Kingdom academic consortia drive subscription adoption for multi-site collaboration.
- Visualization Solutions:3D molecular rendering and interaction mapping for medicinal chemistry teams.
- Predictive Models:Neural architectures for toxicity and ADMET forecasting with interpretability documentation.
- Database Management Systems:Compound registration and chemical inventory infrastructure for enterprise deployments.
Most installed capacity flows through Software Tools. Expansion is steepest in Data Analysis Platforms.
Technology:
Cost tier separation is pronounced: physics-based methods command premium pricing while statistical approaches compete on accessibility.
- Machine Learning:Transformer architectures trained on chemical reaction databases automate retrosynthetic planning and property prediction. United States and Switzerland pharmaceutical developers deploy these systems for parallel synthesis campaign design, reallocating computational chemistry FTEs toward biological validation.
- Molecular Modeling:Quantum mechanical descriptors and force field simulations for binding affinity estimation. EMA qualification opinions on novel methodologies are elevating documentation standards for European contract research organizations supporting client regulatory filings.
- Quantitative Structure-Activity Relationship:Traditional statistical equations for property prediction in resource-constrained settings.
- Virtual Screening:Docking algorithms and pharmacophore matching for hit identification workflows.
- High-Throughput Screening:Integration with automated laboratory infrastructure for experimental validation loops.
Machine Learning absorbs the majority of new R&D investment. Molecular Modeling retains the highest contract values per seat.
Application:
Maturity gradient runs from established pharmaceutical workflows to emerging regulatory-driven segments.
- Drug Discovery:Lead optimization and candidate selection workflows consume the majority of commercial cheminformatics spending. Fragment-based design toolkits for scaffold hopping occupy a specialized niche in early-stage hit identification at biotechnology firms in the United States, Germany, and Japan.
- Environmental Assessment:Predictive toxicology platforms replacing animal testing under ECHA REACH mandates. Industrial chemical safety assessment is gaining traction as manufacturers face tightening discharge monitoring requirements across Europe.
- Agrochemical Development:Crop protection compound design with regulatory submission support.
- Material Science:Polymer and nanomaterial property prediction for industrial applications.
- Cosmetic Formulation:Ingredient safety profiling under EU cosmetics regulation frameworks.
Drug Discovery maintains the deepest installed base. Environmental Assessment is climbing the fastest as regulatory validation of in-silico methods spreads.
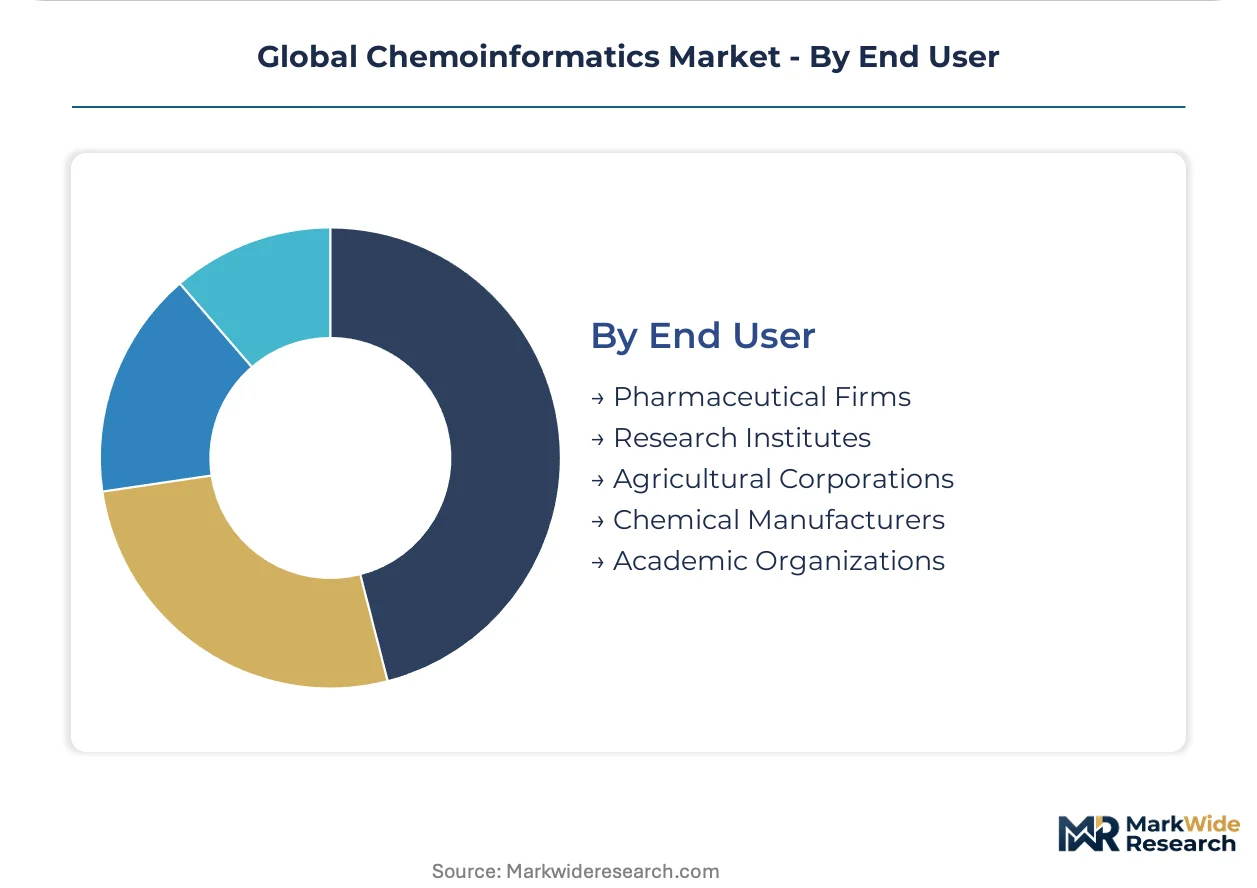
End User:
Volume concentration in large pharmaceutical enterprises contrasts with expanding seat counts in mid-tier research institutions.
- Pharmaceutical Firms:Multi-source algorithm licensing is rebalancing procurement patterns across R&D departments. Physics-based simulation engines anchor high-value contracts with top-tier drug developers requiring regulatory-grade documentation for FDA submissions.
- Research Institutes:GPU cluster access constraints and data sharing consortium participation shape purchasing criteria. The Structural Genomics Consortium and similar pre-competitive collaborations in the United Kingdom and Japan pool ADMET data to benchmark algorithm performance.
- Agricultural Corporations:Crop science divisions with specialized toxicology requirements.
- Chemical Manufacturers:Industrial chemical safety and REACH compliance workflows.
- Academic Organizations:Training-focused deployments with open-source integration preferences.
Pharmaceutical Firms account for the largest contract values. Research Institutes are expanding seat counts most quickly through cloud-native access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge pharmaceutical corridor generates concentrated demand for predictive modeling platforms, with machine learning integration reshaping R&D workflows across multiple national jurisdictions. Regulatory convergence around computational toxicology acceptance is validating simulation-driven decision-making in distinct geographic markets.
United States
FDA guidelines on computational toxicology predictions and AI-generated molecular data are elevating software auditability standards for pharmaceutical developers. Machine learning architectures for property prediction command premium licensing fees in the Boston-Cambridge and San Diego biotechnology clusters. Fragment-based drug design toolkits see concentrated procurement from early-stage biotechnology firms seeking scaffold hopping capabilities.
Germany
ECHA REACH registration mandates are accelerating demand for predictive toxicology platforms that replace animal testing with computational models. The country's national chemical safety regulator validates in-silico data for regulatory submissions, filtering vendors without rigorous validation protocols. Munich and Heidelberg host specialized cheminformatics vendors competing on physics-based simulation engine integration with laboratory hardware systems.
Japan
PMDA acceptance of in-silico data for regulatory submissions is validating simulation-driven decision-making among domestic pharmaceutical developers. The Tokyo-Osaka pharmaceutical belt concentrates procurement of neural architectures for molecular property prediction. Cloud-native deployment models are displacing perpetual licenses among academic consortia seeking multi-site collaboration capabilities.
Switzerland
Swissmedic validation frameworks for computational chemistry methods support regulatory-grade documentation requirements for contract research organizations. Basel's pharmaceutical headquarters drive demand for interpretable AI models with documented validation protocols. The country's precision medicine initiatives are integrating cheminformatics pipelines with clinical biomarker discovery workflows.
United Kingdom
The Structural Genomics Consortium and similar pre-competitive collaborations are pooling ADMET data to benchmark algorithm performance across mid-cap biotechnology firms. London and Cambridge research institutes expand seat counts through subscription-based access models for cloud-native platforms. EMA qualification opinions on novel methodologies are establishing precedent for quantum mechanical descriptors in regulatory submissions.
Global Chemoinformatics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue generative chemistry and environmental toxicology applications as differentiation vectors. The vendor landscape organizes around physics-based simulation engines, fragment-based design specialists, and machine learning platform providers. Three archetypes dominate: integrated instrumentation-informatics hybrids, pure-play software vendors with persistent licensing models, and cloud-native challengers with API-first architectures. Competitive moves concentrate on strategic partnerships for data access and technology licensing for neural architecture integration.
Within the physics-based simulation tier, Schrödinger and BioSolveIT GmbH exemplify divergent specialization strategies—one anchoring high-value contracts through comprehensive molecular mechanics platforms, the other occupying a focused niche in fragment-based hit identification. Agilent Technologies represents the instrumentation-informatics hybrid archetype, extending laboratory hardware heritage into workflow integration. These three entities illustrate how vendor positioning maps to procurement criteria around regulatory documentation depth versus computational accessibility.
| Leading Market Players |
|---|
| ChemAxon |
| PerkinElmer |
| Scilligence |
| Molecular Discovery Ltd. |
| Agilent Technologies |
| BioSolveIT GmbH |
| Schrödinger |
| OpenEye Scientific Software |
| Dassault Systèmes |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up software specialists have consolidated fragmented cheminformatics toolkits into platform suites, tightening pricing discipline while embedding subscription lock-in through API-dependent workflow integration. This ownership pattern concentrates supply-side leverage among three dominant vendors, enabling persistent licensing premiums for physics-based simulation engines while squeezing mid-tier competitors into cloud-native, price-competitive tiers.
Pricing Analysis
Input-cost pass-through from GPU cluster provisioning and specialized quantum chemistry compute resources flows directly into SaaS-tiered subscription structures. Three-tier pricing structure across premium, standard, and economy levels separates regulatory-grade documentation suites from academic-accessible toolkits. Price differentiation hinges on validation protocol depth and FDA submission support bundling. Cost compression in the economy tier is intensifying because cloud-native challengers are undercutting perpetual license premiums. Academic consortia exhibit highest price sensitivity; top-tier pharmaceutical developers demonstrate inelastic demand for audit-ready platforms.
Supply Chain Analysis
Local-content-rule acceleration under Japan's PMDA digital validation framework and Germany's ECHA computational toxicology mandates are reshaping sourcing toward domestic hosting and regional data residency. Development and validation operations concentrate in the United States, Germany, and Switzerland. Raw material dependencies include NVIDIA GPU silicon, specialized force field parameterization expertise, and curated chemical reaction databases. Single-source vulnerability runs through proprietary compound library access controlled by major pharmaceutical developers. Distribution runs through direct enterprise sales for large accounts and academic consortia aggregators for research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Procurement committees at pharmaceutical developers are shifting specification requirements toward interpretable AI documentation and EMA-qualified quantum mechanical descriptors, filtering vendors without rigorous validation protocols.
For Market Incumbents: Acquire specialized fragment-based design boutiques to anchor scaffold-hopping capabilities against BioSolveIT GmbH's niche dominance. Consolidate position by deepening backward integration into proprietary chemical reaction databases, neutralizing the data-silo fragmentation that constrains competitor model training. Prioritize certification investment for ISO computational chemistry standards ahead of anticipated FDA explainable-AI guidance.
For New Entrants and Emerging Players: Generative chemistry diffusion models combined with physics-based scoring functions offer entry leverage against established QSAR incumbents. Environmental toxicology platforms for REACH compliance represent the most penetrable segment, with industrial chemical manufacturers lacking dedicated cheminformatics infrastructure. Go-to-market through German and United Kingdom academic consortia as reference customers for cloud-native deployment credibility.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap platform vendors with FDA audit trail documentation but subscale sales operations. Long-term viability favors entities bridging physics-based simulation with neural architecture interpretability. Target acquisition profile: vendors with EMA qualification opinion precedent and established CRO validation partnerships. The signal to watch is PMDA formal guidance on AI-generated molecular predictions as regulatory acceptance threshold inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity with LIMS and ELN systems anchors enterprise retention at pharmaceutical developers. |
| Regulatory Approval Pathway | EMA qualification opinions on quantum mechanical descriptors elevate documentation standards for CRO client filings. |
| Acquisition of Specialist Firm | Fragment-based design boutiques provide scaffold-hopping capabilities for early-stage biotechnology workflows. |
| Strategic Partnership | Structural Genomics Consortium data-sharing agreements pool ADMET benchmarks for mid-cap algorithm training. |
| Geographic Expansion | Cloud-native deployment in Japan displaces perpetual licenses among academic consortia seeking PMDA-aligned validation. |
Research Methodology
Bottom-up pharmaceutical R&D procurement modeling reconciled against top-down vendor licensing revenue tracking forms the analytical core. Primary interviews with computational chemistry directors, regulatory affairs leads at contract research organizations, platform engineering heads, and academic consortium procurement officers combined with secondary validation from FDA computational toxicology guidance documents, EMA qualification opinions, PMDA submission acceptance criteria, and ISO computational chemistry standards. Top-down and bottom-up triangulation filters outlier assumptions.
Input-output matrix framing maps machine learning architecture adoption rates against regulatory validation milestone achievement across the projection horizon. Segmentation dimensions modeled include deployment model, organization size tier, integration complexity with legacy LIMS infrastructure, and regional regulatory cluster. CAGRs derive from installed base expansion rates and seat-count growth trajectories. Industry-specific forecast inputs incorporate GPU cluster provisioning cost curves and consortium data-sharing participation rates.
The model holds under stable regulatory acceptance trajectories for in-silico submissions; deviation in FDA interpretability requirement stringency or EMA quantum mechanical descriptor precedent would shift vendor competitive positioning. Forecasts reflect documented assumptions regarding machine learning displacement timelines and cloud-native subscription conversion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
North America Computational Biology Market
Bioinformatics
China Computational Biology Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
US Computational Biology Market
Bioinformatics
Bioinformatics Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
Global Biological Data Visualization Market