
 Bioinformatics Software Market | 2026-2036
Bioinformatics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Bioinformatics Software Market Analysis
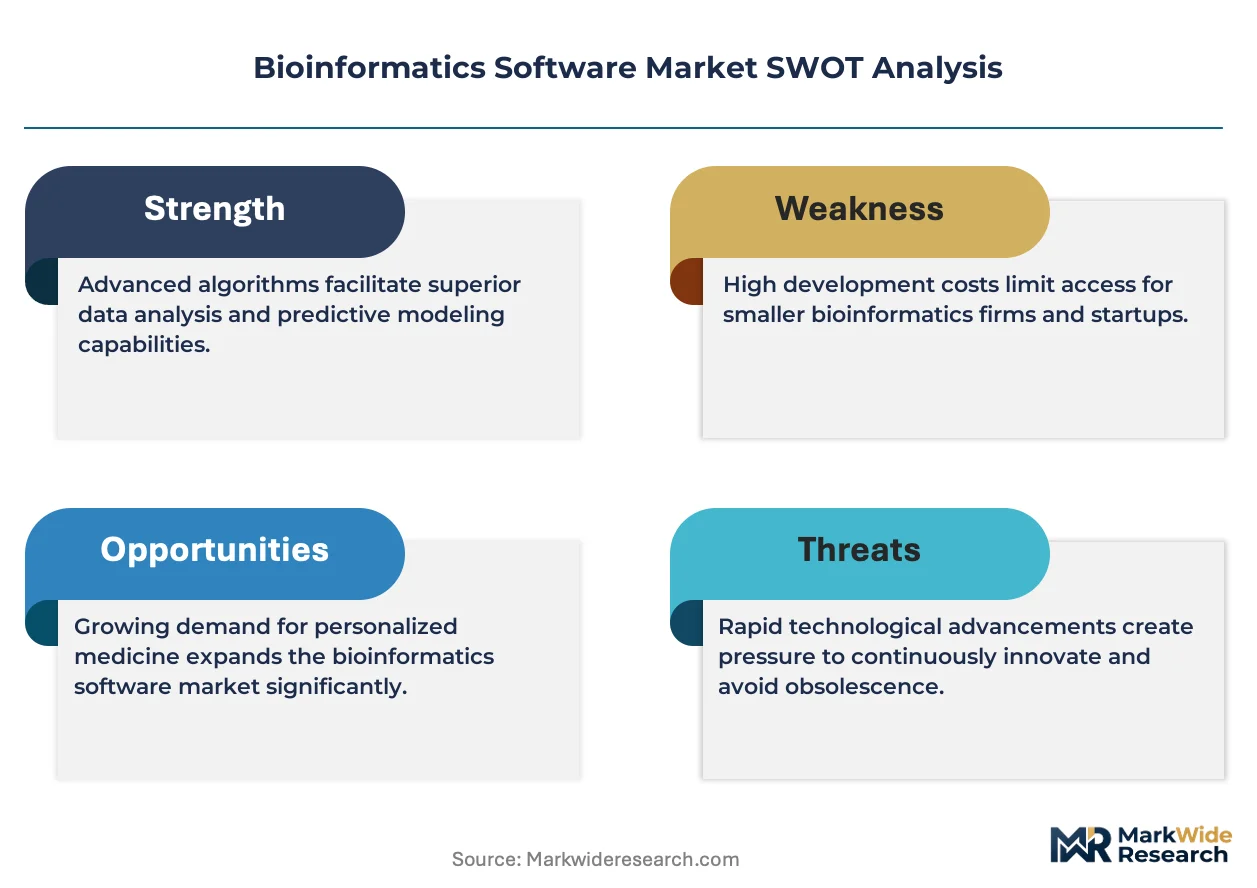
Subscription-based access to software-defined genomic pipelines is rebalancing how bioinformatics capabilities reach end users. Illumina, Inc. leverages its sequencing hardware dominance to anchor cloud-native analytics ecosystems. Thermo Fisher Scientific Inc. competes through integrated instrument-to-software workflows that sustain R&D-intensive customer relationships. QIAGEN N.V. differentiates via specialized clinical-grade interpretation modules that occupy regulated diagnostic laboratories.
Bioinformatics software encompasses computational platforms, algorithms, and databases that process, analyze, and interpret biological data ranging from nucleotide sequences to protein structures, typically operating on Linux-based clusters with memory configurations exceeding 512 GB for whole-genome assemblies. Its primary commercial purpose lies in accelerating target identification, biomarker validation, and patient stratification across pharmaceutical development cycles. Genomic analysis commands the largest product type segment due to the volume of next-generation sequencing data requiring alignment, variant calling, and annotation. Cloud-based delivery models represent the fastest-growing deployment architecture as research institutions and biotechnology firms shift capital expenditure to operational expenditure models. Drug discovery applications concentrate margin pools where molecular dynamics simulations and virtual screening integrate with proprietary compound libraries.
FDA oversight of clinical decision support software shapes product development roadmaps for diagnostic-facing platforms, while HIPAA compliance requirements govern patient data flows across cloud deployments. EMA's In Vitro Diagnostic Regulation and GDPR data localization mandates create dual compliance burdens for vendors serving European clinical laboratories. WHO guidance on genomic surveillance standards further influences public health institution procurement specifications. Stakeholders must monitor evolving regulatory distinctions between research-use-only and clinical-grade software classifications to align product roadmaps with reimbursable diagnostic pathways.
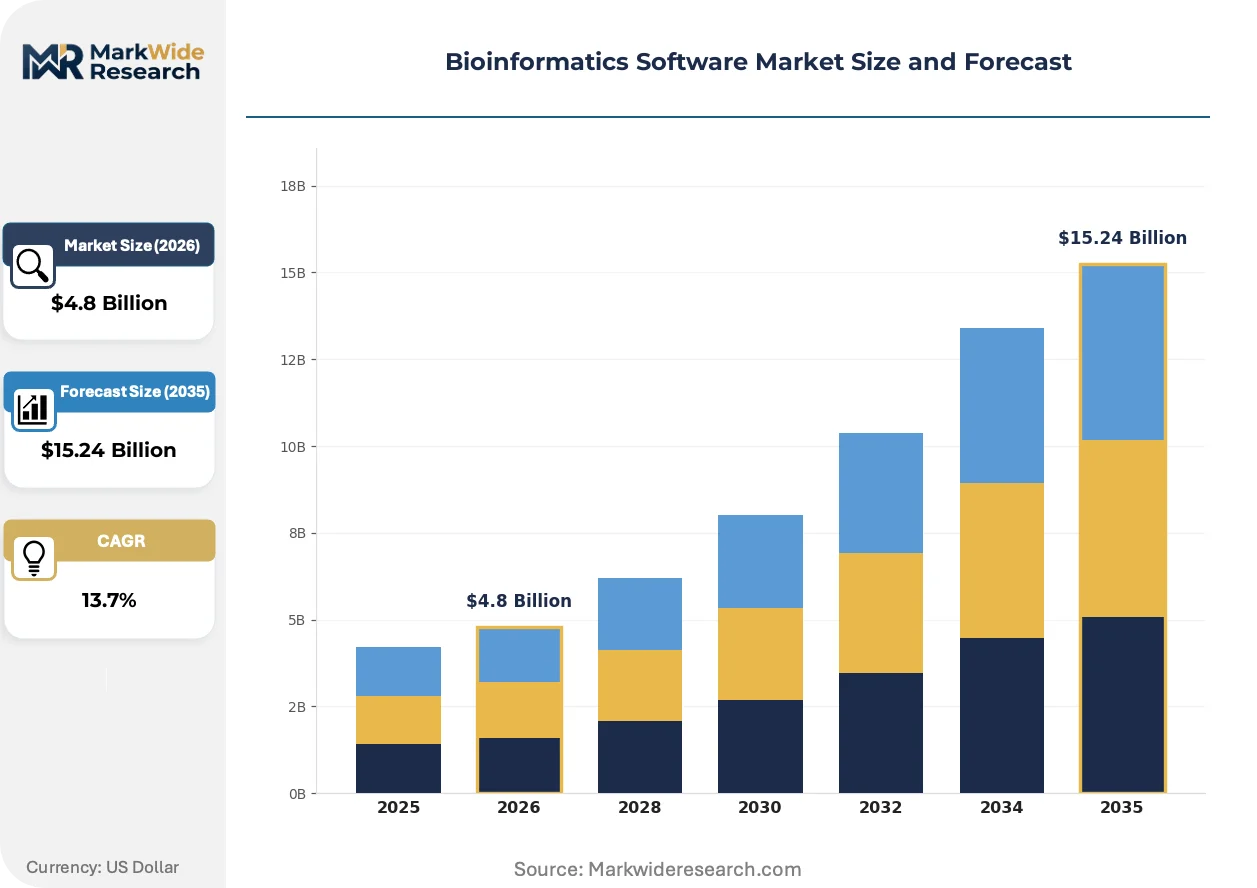
Market Dynamics
Cloud-native deployment architectures are compressing procurement cycles for bioinformatics platforms as pharmaceutical R&D groups trade perpetual licenses for consumption-based access models. This structural shift redistributes vendor power toward orchestration-layer providers and fragments point-solution specialists.
Growth Catalysts
- HIPAA-compliant cloud frameworks:US health systems now route genomic data through federally validated cloud environments, accelerating platform consolidation among hospital networks.
- Precision medicine mandates:National health agencies in Germany and China are embedding bioinformatics pipelines into reimbursable diagnostic pathways, creating institutional demand pull.
- Containerized workflow portability:Kubernetes-orchestrated analysis pipelines enable research institutions to migrate workloads across cloud providers without revalidation delays.
Market Restraints
- Specialized compute infrastructure costs:Whole-genome assemblies require memory configurations exceeding 512 GB, constraining adoption among undercapitalized academic laboratories.
- EMA-GDPR dual compliance burdens:European clinical laboratories face divergent data localization and diagnostic software classification requirements that extend sales cycles.
- Open-source algorithm substitution:Community-developed variant callers and aligners reduce willingness-to-pay for proprietary analysis modules in research-use settings.
Strategic Opportunities
- India's CDSCO diagnostic software pathway:Emerging regulatory clarity for clinical decision support tools creates first-mover positioning for interpretation modules in South Asian reference laboratories.
- Real-world evidence integration:Convergence of electronic health record systems with genomic databases enables prospective cohort studies that pharmaceutical sponsors will underwrite.
- Federated learning architectures:Privacy-preserving multi-site analysis protocols unlock commercial contracts from consortiums unwilling to centralize patient data.
Industry Challenges
- Computational biology talent scarcity:Pipeline development for variant interpretation requires hybrid expertise in statistical genetics and software engineering that academic programs underproduce.
- ISO 13485 certification timelines:Clinical-grade software modules face 18-24 month quality management system validation periods that delay revenue recognition.
- Legacy LIMS integration friction:Hospital laboratory information systems built on 1990s architectures resist API-based connectivity with modern cloud analytics stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioinformatics Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genomic Analysis, Transcriptomics, Proteomics, Metabolomics Application: Drug Discovery, Gene Sequencing, Molecular Diagnostics, Clinical Research End User: Pharmaceutical Companies, Research Institutions, Clinical Laboratories, Biotechnology Firms Delivery Model: Cloud-Based, On-Premises, Hybrid, Web-Based |
| Companies Covered | Illumina, Inc., Agilent Technologies, Inc., Thermo Fisher Scientific Inc., QIAGEN N.V., DNAnexus, Inc., PerkinElmer, Inc., Seven Bridges Genomics, Inc., Genedata AG, Partek Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioinformatics Software Market Emerging Trajectories
Foundation models trained on nucleotide sequences are compressing the traditional algorithm development cycle and enabling zero-shot prediction capabilities that previously required specialized toolchains.
Transformer architectures applied to protein structure prediction are rewriting how therapeutic teams prioritize target validation. Biotechnology firms with limited bioinformatics headcount now access folding accuracy that once required dedicated structural biology units. This capability compression is collapsing the traditional insourcing calculus for molecular dynamics expertise.
FDA's evolving clinical decision support software guidance is forcing diagnostic-facing vendors to reclassify algorithmic outputs as regulated devices. Product teams must now embed predetermined change control plans and lock analytical parameters before commercial distribution. European manufacturers serving US reference laboratories are restructuring quality systems to accommodate this enforcement posture.
Pharmaceutical procurement groups are unbundling sequencing hardware from analytics subscriptions, creating standalone software evaluation committees that bypass traditional vendor relationships. Contract structures now separate instrument capital from per-sample analysis fees, with preferred vendor status awarded to platforms demonstrating interoperable data exchange. This bifurcation is most pronounced among mid-cap drug developers in the Research Triangle and Basel clusters.
Bioinformatics Software Market Segmentation
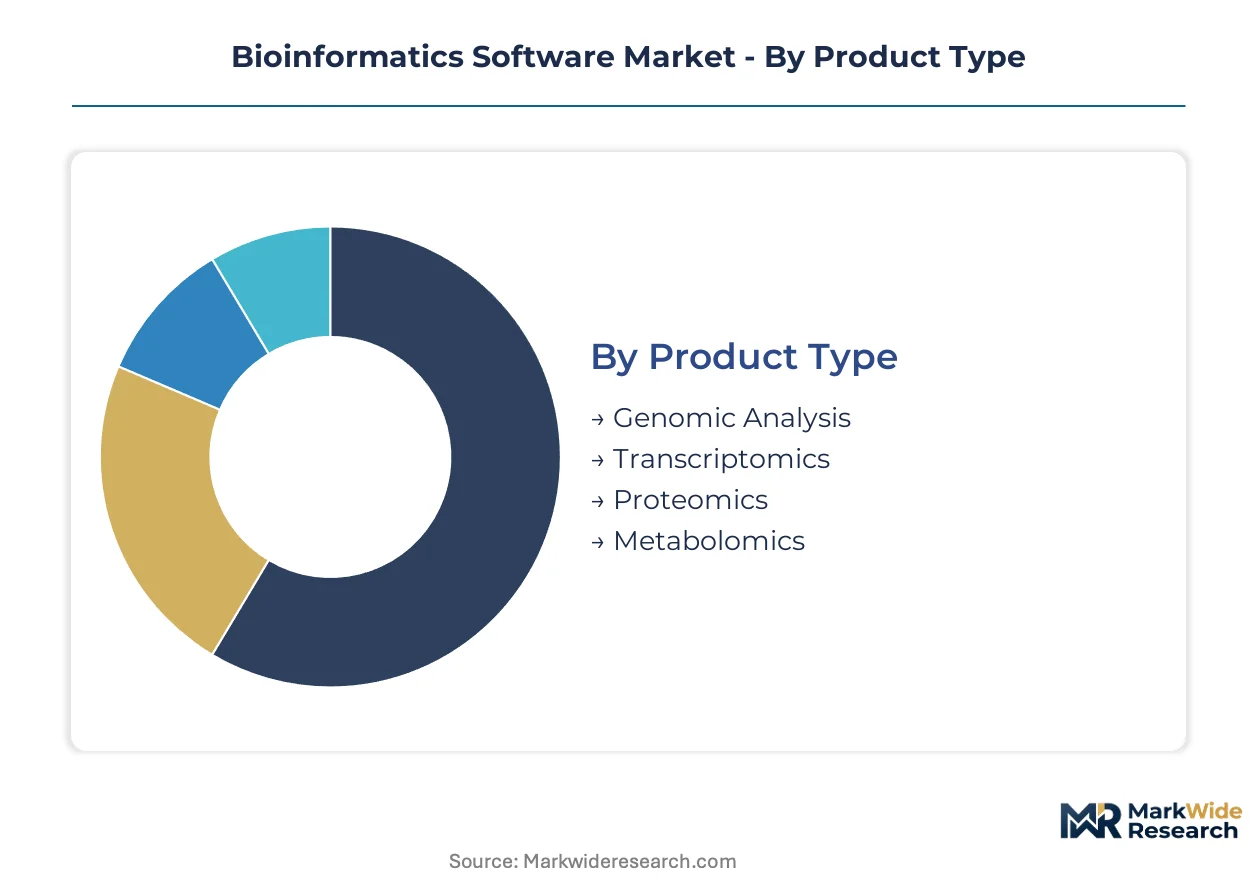
Bioinformatics software vendors configure product roadmaps around four intersecting dimensions that determine pricing architecture and deployment complexity. Each segmentation axis carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Customization intensity spans from standardized sequence alignment modules to bespoke multi-omics integration platforms requiring dedicated implementation teams.
- Genomic Analysis:Platforms processing nucleotide sequence data through alignment, variant calling, and annotation pipelines. Pharmaceutical sponsors in the Research Triangle cluster now mandate API-accessible variant interpretation to embed within automated target identification workflows. Memory configurations exceeding 512 GB constrain deployment at undercapitalized academic sites.
- Transcriptomics:RNA sequencing analysis tools quantifying gene expression and alternative splicing events. German national health agencies embed these pipelines into reimbursable oncology diagnostic pathways, creating institutional procurement pull for ISO 13485-certified modules.
- Proteomics:Mass spectrometry data processing and protein identification algorithms. Thermo Fisher Scientific integrates these with instrument control software to sustain R&D-intensive customer relationships.
- Metabolomics:Small molecule profiling and pathway analysis platforms. Specialized applications in biomarker validation command premium pricing from biotechnology firms with limited in-house metabolomics expertise.
Leading the category by volume: Genomic Analysis. Growing fastest: Transcriptomics.
Application:
Regulatory classification intensity determines commercial pathway complexity, with diagnostic-facing applications facing 18-24 month quality system validation timelines.
- Drug Discovery:Molecular dynamics simulations and virtual screening integrated with proprietary compound libraries. Basel-based pharmaceutical procurement groups unbundle these from sequencing hardware, creating standalone software evaluation committees.
- Gene Sequencing:Base calling, alignment, and quality control pipelines for next-generation sequencing instruments. Cloud-native delivery compresses procurement cycles as research institutions shift capital expenditure to operational expenditure models.
- Molecular Diagnostics:Clinical-grade variant interpretation for patient stratification and treatment selection. FDA oversight of clinical decision support software forces predetermined change control plans and locked analytical parameters before commercial distribution.
- Clinical Research:Prospective cohort study platforms converging electronic health record systems with genomic databases. Real-world evidence integration unlocks pharmaceutical sponsor underwriting for longitudinal analysis infrastructure.
Dominating revenue contribution: Drug Discovery. Expanding most quickly: Clinical Research.
End User:
Procurement sophistication varies from centralized hospital network IT governance to distributed principal investigator purchasing authority.
- Pharmaceutical Companies:Enterprise-scale deployments requiring federated learning architectures and multi-site data residency controls. Mid-cap developers in Basel and Research Triangle clusters drive subscription adoption for consumption-based access models.
- Research Institutions:Kubernetes-orchestrated pipelines enabling workload migration across cloud providers without revalidation delays. Containerized workflow portability addresses budget volatility from federal grant cycles.
- Clinical Laboratories:HIPAA-compliant frameworks routing genomic data through federally validated cloud environments. Legacy LIMS integration friction from 1990s architectures resists API-based connectivity with modern analytics stacks.
- Biotechnology Firms:Limited bioinformatics headcount demands transformer-based protein structure prediction accessible without dedicated structural biology units. Capability compression collapses traditional insourcing calculus.
Commanding largest share: Pharmaceutical Companies. Gaining share fastest: Clinical Laboratories.
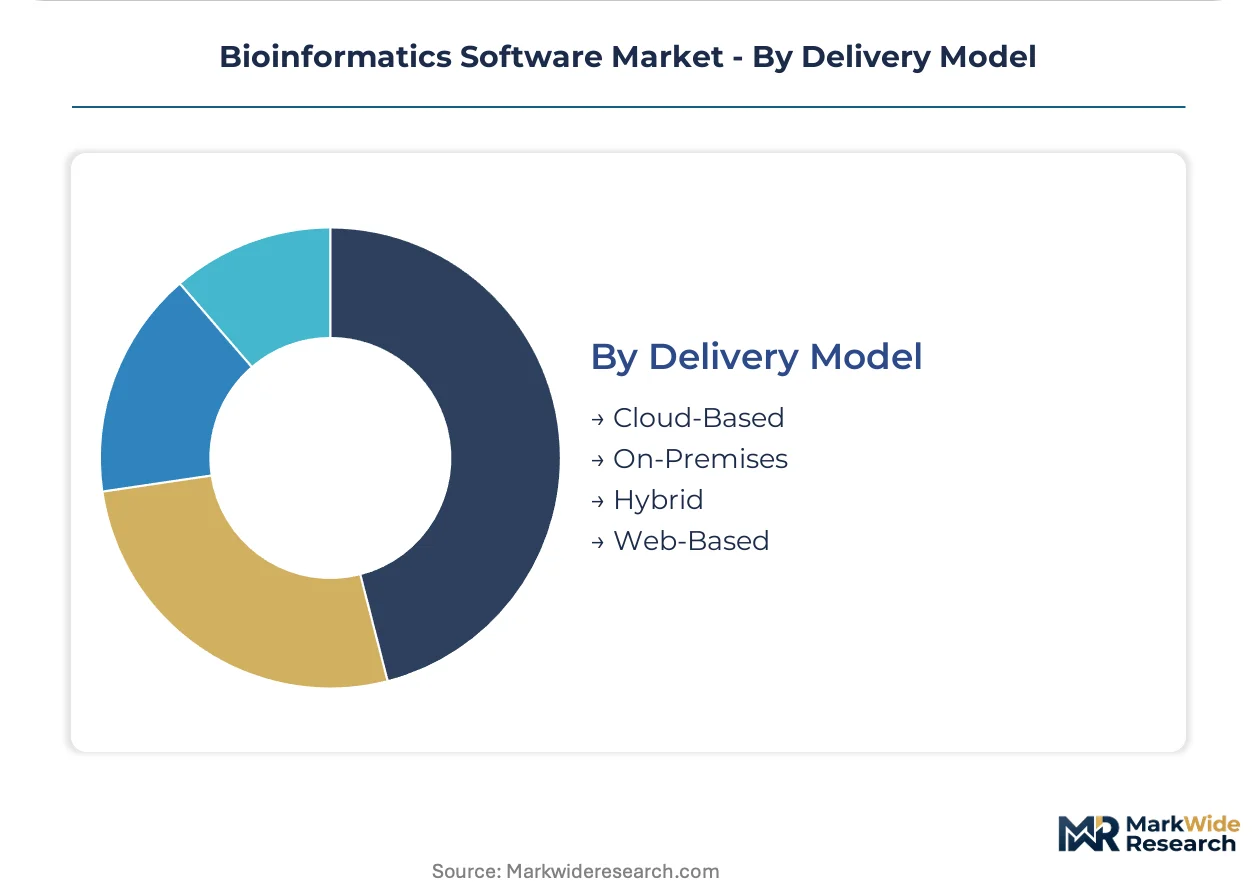
Delivery Model:
Operational expenditure migration redistributes vendor power toward orchestration-layer providers and fragments point-solution specialists.
- Cloud-Based:Consumption-priced access to elastic compute for whole-genome assemblies and population-scale variant databases. US health systems now route genomic data through federally validated environments, accelerating platform consolidation.
- On-Premises:Air-gapped installations satisfying data localization mandates under GDPR and EMA In Vitro Diagnostic Regulation. European clinical laboratories face dual compliance burdens extending sales cycles.
- Hybrid:Tiered data residency with sensitive patient records on-premises and burst compute in cloud environments. Preferred architecture for multi-national pharmaceutical sponsors navigating divergent jurisdictional requirements.
- Web-Based:Browser-accessible analysis portals for collaborative research without local software installation. Academic consortia leverage these for distributed variant interpretation across international boundaries.
Current volume leader: On-Premises. Steepest expansion trajectory: Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development of bioinformatics software concentrates in the United States, Germany, and China, while consumption spreads across pharmaceutical clusters and national health systems seeking precision medicine infrastructure. Production capacity clusters around sequencing hardware manufacturers extending into analytics ecosystems.
United States
Pharmaceutical R&D groups in the Research Triangle and Greater Boston drive subscription adoption for cloud-native genomic platforms. FDA oversight of clinical decision support software forces predetermined change control plans and locked analytical parameters before commercial distribution. Hospital networks in California now route genomic data through HIPAA-compliant cloud environments, accelerating platform consolidation among federated health systems.
Germany
National health agencies embed bioinformatics pipelines into reimbursable oncology diagnostic pathways, creating institutional procurement pull for ISO 13485-certified modules. EMA In Vitro Diagnostic Regulation and GDPR data localization mandates create dual compliance burdens extending sales cycles for foreign vendors. The Rhine-Main cluster around Frankfurt anchors pharmaceutical procurement groups unbundling sequencing hardware from analytics subscriptions.
China
NMPA regulatory pathways for clinical decision support tools are creating first-mover positioning for interpretation modules in reference laboratories serving precision medicine programs. National genomic surveillance initiatives under WHO guidance influence public health institution procurement specifications. The Yangtze River Delta concentration of biotechnology firms demands transformer-based protein structure prediction accessible without dedicated structural biology units.
United Kingdom
Research institutions leverage Kubernetes-orchestrated pipelines enabling workload migration across cloud providers without revalidation delays. MHRA alignment with FDA clinical decision support software guidance shapes product development roadmaps for diagnostic-facing platforms. The Cambridge-London corridor concentrates mid-cap drug developers driving consumption-based access models for genomic analysis infrastructure.
India
CDSCO emerging regulatory clarity for clinical decision support tools creates positioning opportunities for interpretation modules in South Asian reference laboratories. Containerized workflow portability addresses budget volatility from federal grant cycles at research institutions. The Bangalore-Hyderabad biotechnology corridor attracts pharmaceutical sponsors underwriting real-world evidence integration converging electronic health record systems with genomic databases.
Bioinformatics Software Market Vendor Landscape
Top-tier vendors anchor sequencing-hardware-to-software ecosystems, while cloud-native specialists and clinical-grade interpretation module providers occupy differentiated positions. The vendor base stratifies across three tiers: integrated instrument manufacturers, platform orchestration providers, and specialized diagnostic software houses. Two dominant competitive moves are reshaping positioning: pharmaceutical procurement groups unbundling hardware from analytics subscriptions, and vendors embedding federated learning architectures for privacy-preserving multi-site analysis protocols.
Among integrated platform providers, Illumina, Inc., Thermo Fisher Scientific Inc., and QIAGEN N.V. exemplify contrasting strategic archetypes. Illumina leverages sequencing hardware dominance to anchor cloud-native analytics ecosystems. Thermo Fisher competes through instrument-to-software workflows sustaining R&D-intensive customer relationships. QIAGEN occupies a specialized position via clinical-grade interpretation modules serving regulated diagnostic laboratories. These three represent the spectrum from hardware-anchored to software-specialized competitive positioning in pharmaceutical and clinical end markets.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| DNAnexus, Inc. |
| PerkinElmer, Inc. |
| Seven Bridges Genomics, Inc. |
| Genedata AG |
| Partek Incorporated |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical procurement groups unbundling sequencing hardware from analytics subscriptions are forcing vendors to restructure cost bases around pure-software delivery economics, compressing margins for integrated instrument manufacturers while elevating pricing power for cloud-native orchestration specialists.
Pricing Analysis
Margin tightening in clinical-grade modules reflects ISO 13485 certification cost absorption and 18-24 month quality system validation timelines. Three-tier pricing structure across premium, standard, and economy levels separates FDA-locked clinical decision support tools from research-use-only pipelines and open-source community editions. Pricing pressure stems from open-source algorithm substitution reducing willingness-to-pay for proprietary variant callers. Academic laboratories exhibit highest price sensitivity; pharmaceutical sponsors with automated target identification workflows show lowest.
Supply Chain Analysis
Refurbished sequencing instrument redeployment and certified pre-owned hardware programs create secondary supply channels that extend equipment lifecycles and delay new system purchases. Supply concentrates in the United States, Germany, and China where sequencing hardware manufacturers anchor analytics ecosystems. Raw material dependencies span high-memory compute clusters exceeding 512 GB configurations, GPU accelerators for transformer-based protein folding, and HIPAA-compliant cloud infrastructure certifications. Single-source vulnerability sits with Illumina's dominance in sequencing hardware-to-software bundling. Distribution runs through direct enterprise sales for pharmaceutical sponsors and channel partners serving academic consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA oversight of clinical decision support software erects a compliance moat that rewards vendors with predetermined change control plans and locked analytical parameters, penalizing research-use-only players attempting clinical pivot without quality system investment.
For Market Incumbents: Hedge against pharmaceutical procurement committee unbundling by accelerating cloud-native subscription pricing and embedding Kubernetes-orchestrated workload portability that locks customers through orchestration-layer dependence rather than hardware captivity. Invest in federated learning architectures to defend against privacy-preserving multi-site analysis competitors. ISO 13485 certification expansion into transcriptomics modules protects margin pools as German national health agencies embed pipelines into reimbursable pathways. For New Entrants and Emerging Players: CDSCO emerging regulatory clarity in India opens a window for clinical-grade interpretation modules in South Asian reference laboratories where multinational incumbents lack localized quality systems. Target containerized workflow portability for research institutions facing federal grant cycle volatility. Federated learning architectures for consortiums unwilling to centralize patient data offer a go-to-market angle bypassing HIPAA compliance burdens that constrain cloud-native specialists. For Investors and Strategic Acquirers: The window for entry favors cloud-native platform orchestrators with HIPAA-validated infrastructure and API-accessible variant interpretation capabilities over hardware-anchored incumbents facing subscription transition friction. Monitor FDA enforcement posture on clinical decision support software reclassification as the inflection signal separating reimbursable diagnostic pathway vendors from research-use-only stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Expansion | Unlocks German national health agency reimbursement pathways for oncology diagnostics. |
| Federated Learning Architecture Deployment | Captures pharmaceutical sponsor contracts from multi-site consortiums with data residency constraints. |
| API-First Variant Interpretation Platform | Integrates with automated target identification workflows at Research Triangle pharmaceutical clusters. |
| HIPAA-Compliant Cloud Infrastructure | Routes genomic data through federally validated environments consolidating hospital network procurement. |
| Kubernetes-Orchestrated Pipeline Portability | Enables workload migration across cloud providers without revalidation delays for grant-dependent institutions. |
Methodological Framework
Multi-period observation of pharmaceutical procurement committee structures, cloud deployment adoption curves, and regulatory submission pathways anchored the trend analysis, supplemented by interviews with bioinformatics platform engineers, clinical laboratory directors, regulatory affairs specialists at diagnostic software houses, and pharmaceutical R&D procurement leads. Secondary validation drew from FDA 510(k) filings for clinical decision support tools, EMA In Vitro Diagnostic Regulation guidance documents, hospital network procurement databases, and hyperscaler healthcare cloud certification disclosures. Bottom-up triangulation across end-user deployment scales converged with top-down market sizing.
Segment-weighting across product type, application, end user, and delivery model dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from elasticity-adjusted adoption curves incorporating precision medicine program expansion rates, cloud infrastructure capacity buildouts, and ISO 13485 certification pipeline velocities. Industry-specific inputs included Kubernetes containerization penetration at research institutions and unbundling velocity of sequencing hardware from analytics subscriptions.
Caveats apply where FDA enforcement posture shifts on clinical decision support software classification or where open-source algorithm substitution accelerates beyond modeled rates could materially shift the outlook. Practitioners should monitor NMPA regulatory pathway developments in China and CDSCO diagnostic software guidance evolution in India for early signals of geographic demand redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
North America Computational Biology Market
Bioinformatics
US Computational Biology Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
China Computational Biology Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
Bioinformatics Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
In Silico Protein Design Market