
 Oligonucleotide Synthesis Market | 2026-2036
Oligonucleotide Synthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Oligonucleotide Synthesis Market Intelligence
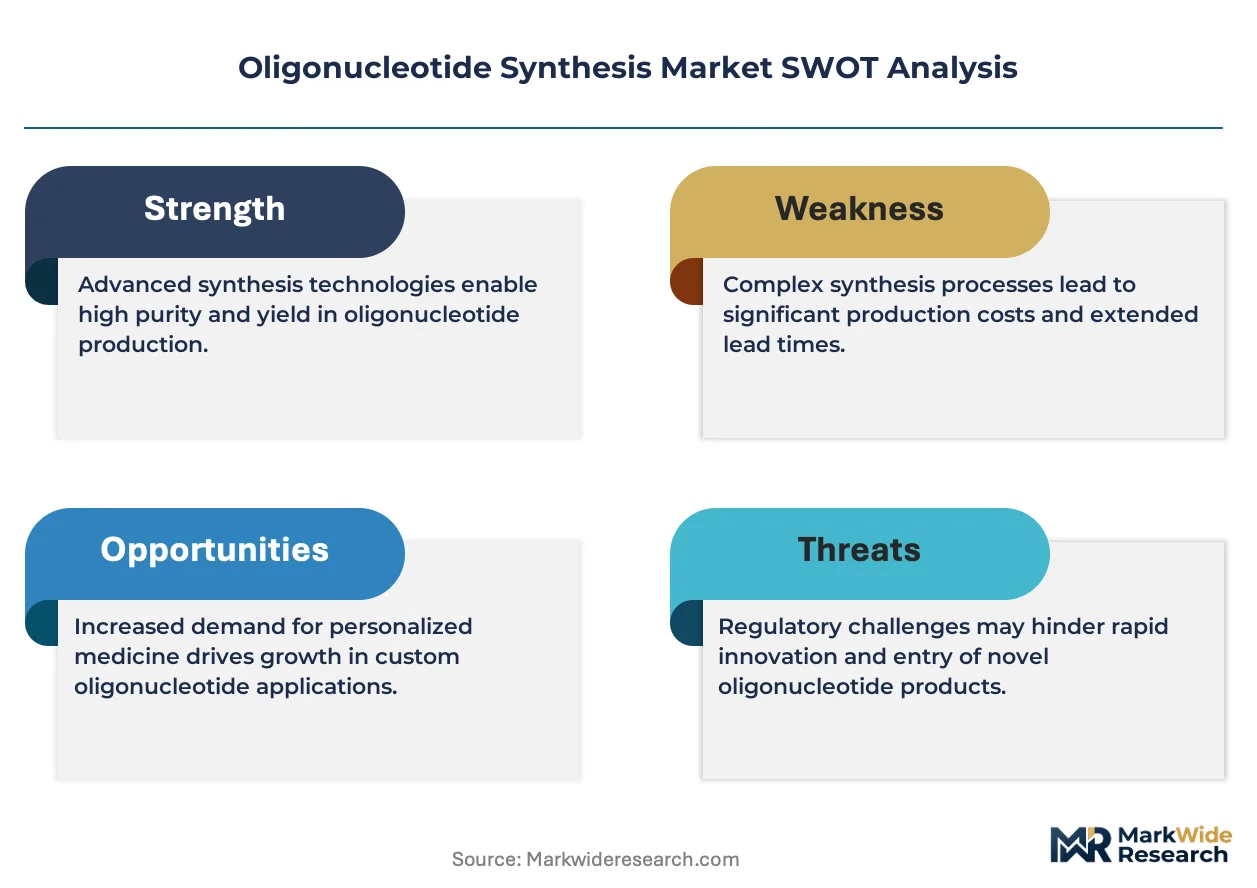
The EU Green Deal's directives on sustainable chemical processes are repositioning the value chain for oligonucleotide synthesis, pushing for less hazardous solvents. Thermo Fisher Scientific leverages its extensive distribution network to serve both research and clinical markets. Danaher Corporation, through its subsidiary Integrated DNA Technologies, specializes in high-throughput custom synthesis for genomics research. Twist Bioscience competes on its unique silicon-based platform for high-density oligo production.
Oligonucleotide synthesis is the chemical process of assembling nucleic acid sequences in a defined order, primarily using solid-phase phosphoramidite chemistry. These custom-built DNA and RNA strands serve as essential tools in life sciences. Applications in antisense therapy and molecular diagnostics are driving significant investment. While DNA oligonucleotides for research constitute a mature segment, RNA oligonucleotides for therapeutic use are experiencing the most rapid expansion.
Regulatory oversight for therapeutic oligonucleotides is stringent. The U.S. FDA and the European Medicines Agency (EMA) define the clinical trial pathways and manufacturing standards. These regulations, including Good Manufacturing Practice (GMP) guidelines, dictate the purity and quality requirements for market entry. Navigating these evolving standards for novel oligo-based drugs is a critical success factor for developers.
Market Dynamics
The fundamental dynamic in the oligonucleotide synthesis market is the bifurcation of demand between low-volume, high-mix research applications and high-volume, GMP-grade therapeutic manufacturing. This split pressures the supply chain to support both rapid-turnaround custom synthesis and large-scale, highly regulated production.
Growth Catalysts
- CRISPR Technology Maturation:The advancement of CRISPR-Cas9 gene editing from academic research to preclinical development creates a substantial and continuous demand for custom single guide RNA (sgRNA) and donor DNA templates.
- Antisense & RNAi Therapeutics:The clinical success and commercialization of antisense and RNA interference drugs for treating rare and chronic diseases are establishing a clear pathway for therapeutic oligonucleotide development, attracting significant investment.
- Diagnostic Proliferation:Molecular diagnostic assays, including PCR-based tests for infectious diseases and oncology panels using next-generation sequencing, rely on a consistent supply of high-fidelity primers and probes.
Market Restraints
- High Reagent Costs:The primary chemical inputs for phosphoramidite synthesis, particularly the amidites and specialized solvents, are expensive and contribute significantly to the final cost per base, limiting use in cost-sensitive applications.
- Synthesis Fidelity Limits:Chemical synthesis of oligonucleotides longer than 200 bases faces challenges with yield and purity, as error rates accumulate with each coupling cycle, complicating production of long DNA or RNA constructs.
- Regulatory Scrutiny:Stringent manufacturing and quality control standards imposed by the FDA and EMA for therapeutic-grade oligonucleotides create high barriers to entry and require substantial capital investment in GMP facilities.
Strategic Opportunities
- Enzymatic Synthesis:Emerging enzymatic DNA and RNA synthesis technologies offer a potential alternative to chemical methods, promising longer sequences, lower environmental impact, and different impurity profiles, creating a new technology frontier.
- Diagnostic Market in Emerging Economies:The expansion of healthcare infrastructure and diagnostic laboratories in regions like Southeast Asia and Latin America opens new markets for oligo-based reagents for infectious disease testing.
- Agricultural Biotechnology:The application of gene editing and synthetic biology in crop development and animal health presents a nascent but potentially large-volume opportunity for custom oligonucleotide synthesis outside of human health.
Industry Challenges
- Process Scale-Up Complexity:Transitioning an oligonucleotide synthesis process from small-scale lab production to large-scale GMP manufacturing is a non-linear challenge, requiring specialized chemical engineering expertise that is in short supply.
- Analytical Method Development:Characterizing impurities in complex therapeutic oligonucleotides requires sophisticated analytical techniques, and developing and validating these methods for regulatory submission is a major bottleneck.
- Intellectual Property Density:The field is crowded with patents covering modifications, conjugation chemistries, and delivery technologies, creating a complex IP landscape that new entrants must navigate carefully to avoid infringement litigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oligonucleotide Synthesis Market |
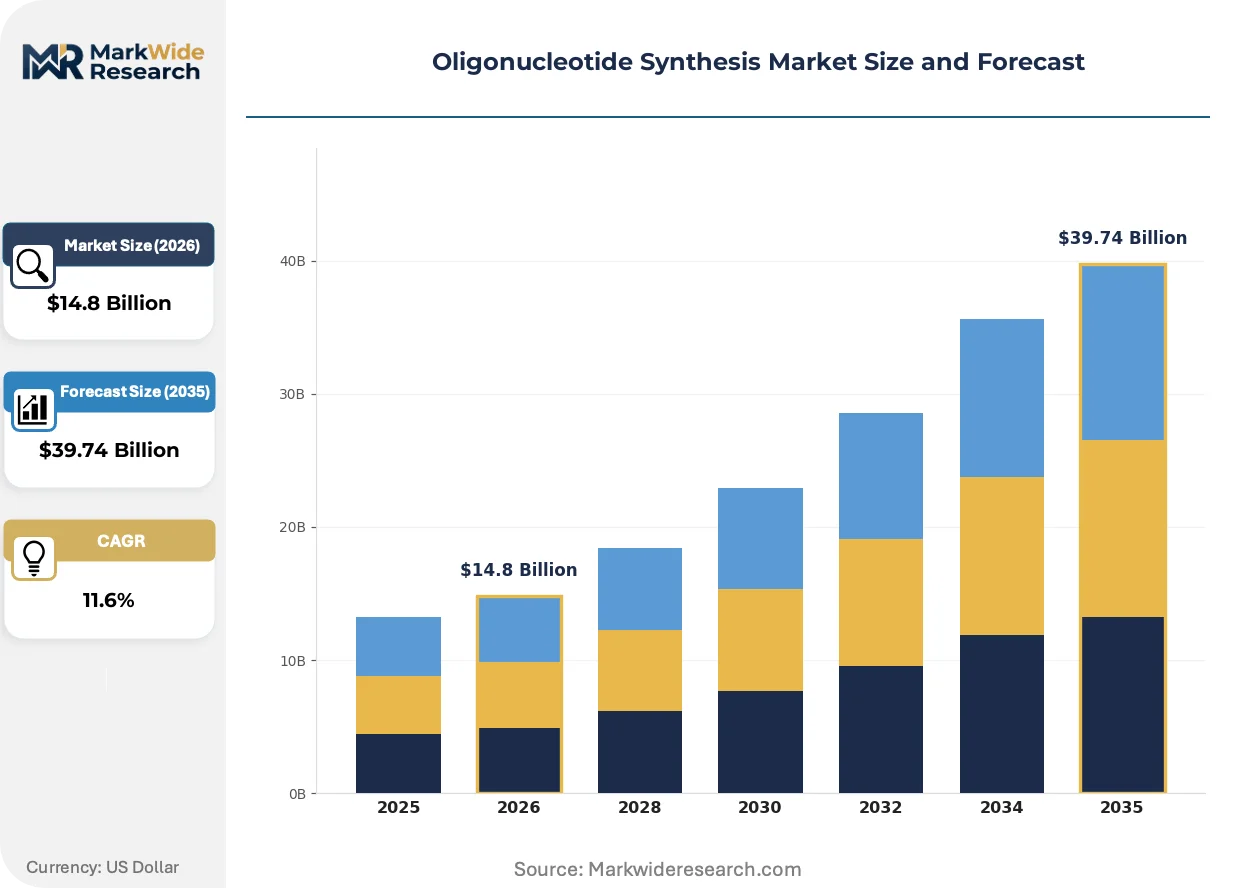
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Oligonucleotides, RNA Oligonucleotides, Peptide Nucleic Acids, Locked Nucleic Acids, Morpholinos Application: Gene Editing, Polymerase Chain Reaction, Antisense Therapy, Molecular Diagnostics, Synthetic Biology Technology: Phosphoramidite Method, Solid Phase Synthesis, Enzymatic Synthesis, Microarray Synthesis, HPLC Purification End User: Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Academic Laboratories, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Danaher Corporation, Agilent Technologies Inc., Eurofins Scientific, Twist Bioscience, Kaneka Eurogentec, LGC Biosearch Technologies, Integrated DNA Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oligonucleotide Synthesis Market Strategic Shifts & Innovations
The industrialization of oligonucleotide synthesis is the dominant theme, shifting the market's focus from laboratory craft to robust, scalable manufacturing processes. This transition is driven by the exacting demands of therapeutic applications, which require unprecedented levels of quality, purity, and consistency at scale.
Silicon-based synthesis platforms enable the miniaturization of reaction volumes for high-density oligonucleotide production. High-throughput genomics and synthetic biology research organizations are rapidly adopting this technology for screening and library generation. This method of parallel synthesis is expanding into the early-stage development of therapeutic candidates, significantly compressing discovery timelines by allowing massive parallel testing of sequences.
The EU Green Deal's directives on sustainable chemical processes are influencing solvent selection across the manufacturing value chain. This forces producers to validate and adopt greener solvents, such as alternatives to acetonitrile, to reduce hazardous waste output. The therapeutic oligonucleotide segment, with its large-scale production runs, is most affected and is investing heavily in process chemistry R&D to maintain compliance without compromising final product purity.
A notable demand-side shift is occurring towards decentralized, on-demand synthesis models for specific research applications. This trend disrupts the traditional centralized, batch-ordering model by enabling researchers to use benchtop synthesis instruments for rapid iteration. This pattern is most visible within academic and biotechnology research clusters in the United States and Europe, where rapid prototyping of new sequences is a critical competitive advantage.
Oligonucleotide Synthesis Market Segmentation
Understanding the market's segmentation is critical for stakeholders to tailor strategies, identify high-growth niches, and navigate the diverse regulatory and technical requirements across the oligonucleotide synthesis landscape. This analysis delineates the market by product type, application, technology, and end-user segments, each presenting distinct demand drivers and competitive dynamics.
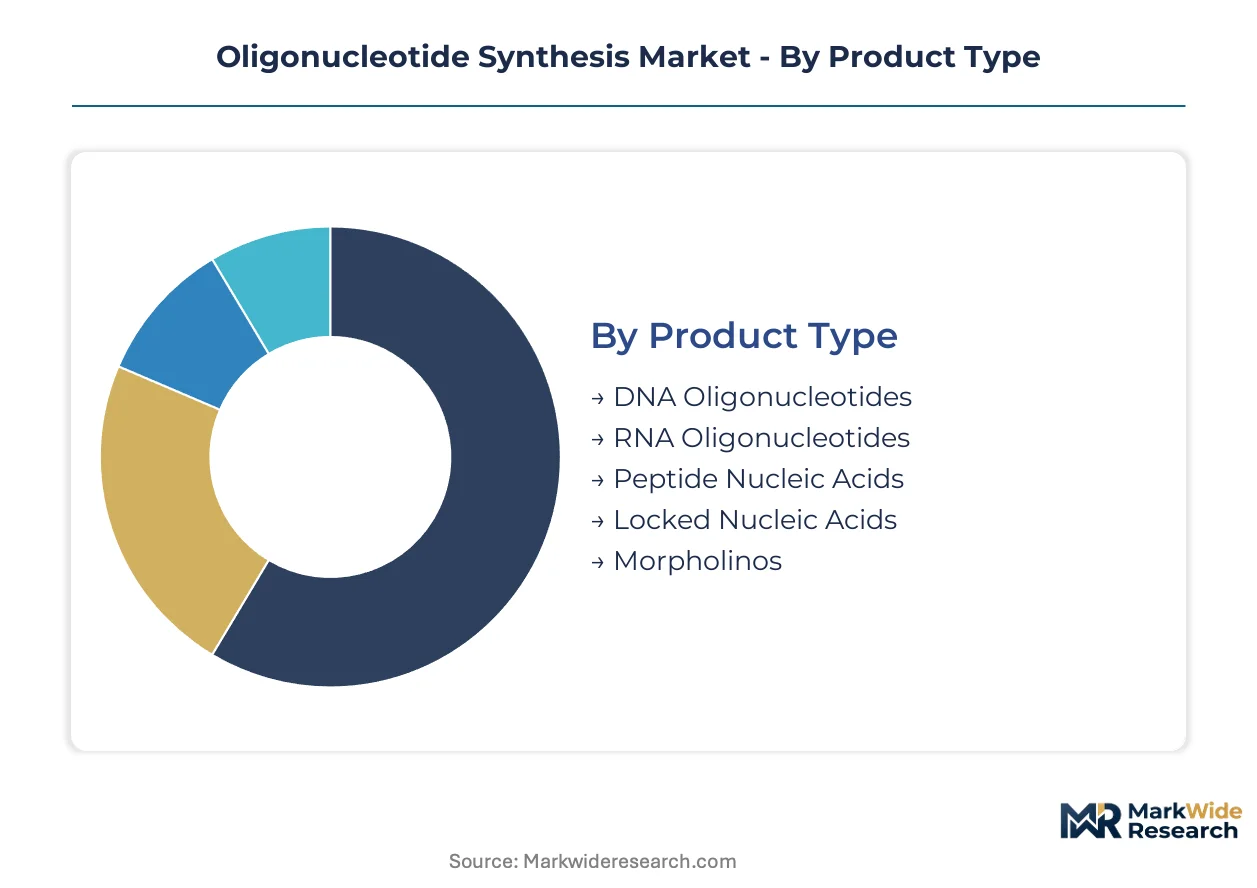
Product Type:
Segments in product type are differentiated by the regulatory hurdles they face, with therapeutic-grade oligonucleotides requiring stringent GMP compliance from agencies like the U.S. FDA and the European Medicines Agency (EMA).
- DNA Oligonucleotides:Short strands of deoxyribonucleic acid, primarily used as primers, probes, and gene fragments for research. Demand concentrates in academic research laboratories and molecular diagnostics for infectious disease testing across North America and Europe.
- RNA Oligonucleotides:Single-stranded ribonucleic acid molecules, crucial for gene silencing (siRNA, miRNA) and CRISPR guide RNA. Significant investment is driven by their expanding role in antisense therapy development in pharmaceutical companies in countries like Germany and Japan.
- Peptide Nucleic Acids:Synthetic DNA mimics with a peptide backbone, used in molecular diagnostics and anti-gene strategies due to high binding affinity.
- Locked Nucleic Acids:Modified RNA nucleotides with enhanced binding affinity and nuclease resistance, valuable in drug discovery and diagnostic assays.
- Morpholinos:Synthetic antisense oligos that block gene expression by steric hindrance, applied in developmental biology and gene function studies.
DNA Oligonucleotides sit at the top of the volume ranking, with RNA Oligonucleotides climbing the fastest.
Application:
This category delineates the primary uses for synthesized oligonucleotides, reflecting diverse functional requirements and market maturity.
- Antisense Therapy:Utilizes synthetic oligonucleotides to modulate gene expression, targeting specific mRNA or pre-mRNA sequences. Clinical success in rare and chronic diseases establishes a clear pathway for therapeutic development, attracting substantial investment from pharmaceutical firms in the United States and Switzerland.
- Molecular Diagnostics:Employs oligonucleotide probes and primers for detecting specific genetic sequences, essential for pathogen identification and cancer screening. Proliferation in clinical laboratories globally for infectious disease surveillance propels demand.
- Gene Editing:Relies on guide RNAs and donor DNA templates for precise genomic modifications, primarily within biotechnology firms and research institutions.
- Polymerase Chain Reaction:A foundational molecular biology technique using DNA primers to amplify specific DNA sequences, widely adopted in research and diagnostic labs.
- Synthetic Biology:Involves designing and constructing new biological parts, devices, and systems, leveraging custom oligonucleotides for gene synthesis and pathway engineering.
Market expansion is heavily influenced by the therapeutic impact of Antisense Therapy, while Molecular Diagnostics drives widespread adoption.
Technology:
Supply concentration within this category varies significantly, influenced by the specialized equipment and chemical expertise required for each method.
- Phosphoramidite Method:The dominant chemical synthesis approach, building oligonucleotides base-by-base on a solid support. Its established reliability and scalability serve high-volume production for both research and therapeutic applications in global markets.
- Enzymatic Synthesis:An emerging method using enzymes (e.g., TdT) to assemble DNA or RNA, promising longer sequences and reduced chemical waste. This technology attracts significant R&D investment for its potential to overcome current synthesis fidelity limits.
- Solid Phase Synthesis:The foundational principle for most chemical oligonucleotide synthesis, involving reactions on an insoluble resin, enabling purification ease.
- Microarray Synthesis:Enables parallel synthesis of thousands of oligonucleotides on a chip, critical for high-throughput screening and gene expression studies.
- HPLC Purification:High-Performance Liquid Chromatography is a standard post-synthesis purification technique ensuring the high purity required for therapeutic and diagnostic oligonucleotides.
While Phosphoramidite Method remains the industry standard, Enzymatic Synthesis represents a significant leap in potential capabilities.
End User:
This category segments the market by the primary entities procuring oligonucleotides, reflecting varied purchasing power and application needs.
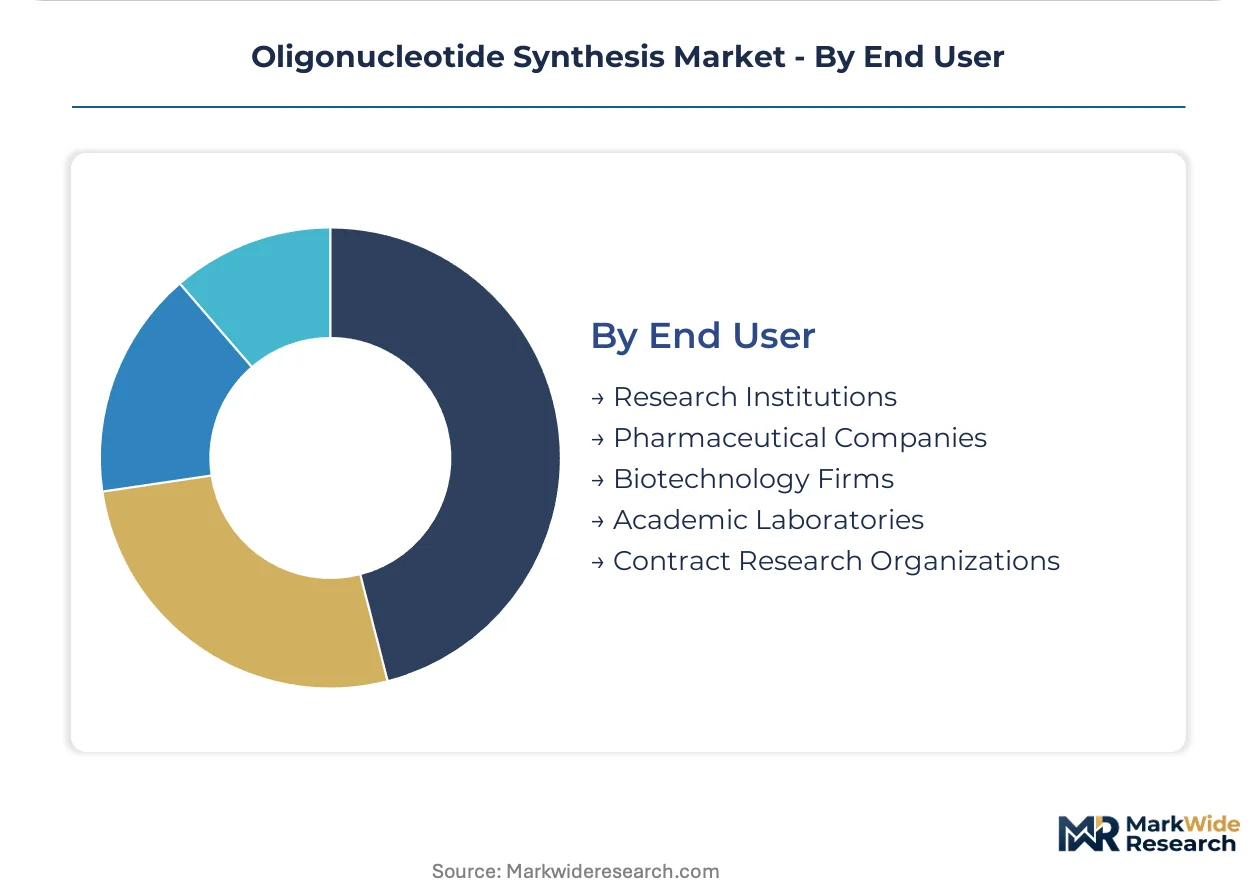
- Pharmaceutical Companies:Large enterprises developing novel drugs, requiring GMP-grade therapeutic oligonucleotides for clinical trials and commercial production. Their demand is concentrated in the United States and Europe, driven by drug development pipelines.
- Biotechnology Firms:Companies focused on R&D and commercialization of bio-based products, utilizing custom oligonucleotides for gene editing, synthetic biology, and early-stage drug discovery. These firms often seek high-throughput, custom synthesis services for rapid innovation in clusters like Boston and Shanghai.
- Research Institutions:Universities and government laboratories conducting fundamental and applied life science research, primarily consuming research-grade DNA and RNA oligos.
- Academic Laboratories:Educational and research settings where oligonucleotides are essential tools for experiments, teaching, and early-stage scientific discovery.
- Contract Research Organizations:Service providers supporting pharmaceutical and biotechnology companies with research, development, and clinical trial activities, including oligonucleotide synthesis and analysis.
The largest volume of procurement originates from Pharmaceutical Companies, with Biotechnology Firms exhibiting the most stringent quality demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The oligonucleotide synthesis industry first scaled significantly in North America, particularly in the United States, driven by foundational molecular biology research. This region established early infrastructure for custom oligo production, supporting academic and nascent biotechnology sectors. European countries like Germany also contributed to early therapeutic advancements.
United States
United States demand for oligonucleotides stems from extensive gene editing research and advanced therapeutic development. The U.S. FDA imposes stringent Good Manufacturing Practice guidelines for therapeutic-grade oligonucleotides. Biotechnology clusters in Boston and San Francisco drive innovation in novel oligo-based drugs and diagnostics.
Germany
Germany exhibits strong demand for RNA oligonucleotides, particularly for therapeutic applications and advanced molecular diagnostics. The European Medicines Agency (EMA) sets rigorous manufacturing standards for therapeutic oligonucleotides impacting German producers. Pharmaceutical companies in Frankfurt and Munich are expanding their capabilities for RNA-based drug development.
Japan
Japan's market is characterized by robust pharmaceutical R&D, focusing on RNA therapeutics and advanced diagnostic assay development. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict quality control for therapeutic oligonucleotides entering the Japanese market. Research institutions and pharmaceutical firms in Tokyo are actively developing new antisense therapy candidates.
China
China's oligonucleotide market expands with significant proliferation of molecular diagnostics and gene editing applications. The National Medical Products Administration (NMPA) is developing guidelines for advanced gene therapies and diagnostic reagents. Biotechnology clusters in Shanghai and Beijing are rapidly increasing custom oligo production for diverse genomics research.
Switzerland
Switzerland represents a hub for specialized drug discovery and antisense therapy development, attracting significant pharmaceutical investment. Swissmedic, the national regulatory authority, enforces high standards for therapeutic oligonucleotide manufacturing and approval. Pharmaceutical firms in Basel and Zurich lead the development of innovative oligonucleotide-based drugs.
Oligonucleotide Synthesis Market Key Industry Players
Premium-margin players sit above commodity-margin players across the oligonucleotide synthesis value chain, differentiated by product purity and regulatory compliance. The market exhibits a tiered structure with specialized providers focusing on high-grade therapeutic oligonucleotides for clinical applications. Strategic archetypes include integrated life science tool providers, custom synthesis specialists, and technology platform innovators leveraging novel chemistries. Capacity expansion and strategic partnerships are dominant competitive moves as firms seek to capture growing therapeutic demand.
Integrated life science tool providers, such as Thermo Fisher Scientific Inc., exemplify broad distribution capabilities across global research and clinical markets. Danaher Corporation, through its subsidiary Integrated DNA Technologies, occupies a significant position in high-throughput custom synthesis, particularly for genomics research applications. Technology platform innovators like Twist Bioscience anchor the segment for high-density oligo production, leveraging unique silicon-based platforms and representing a distinct approach to manufacturing scalability and parallel synthesis.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Danaher Corporation |
| Agilent Technologies Inc. |
| Eurofins Scientific |
| Twist Bioscience |
| Kaneka Eurogentec |
| LGC Biosearch Technologies |
| Integrated DNA Technologies |
| Others |
Cost & Logistics Intelligence
Reagent costs, particularly for phosphoramidites and specialized solvents, represent a significant upstream input that directly influences pricing tiers downstream. These high-purity chemical inputs contribute substantially to the final cost per base, especially for GMP-grade therapeutic oligonucleotides.
Pricing Analysis
Project-based contracts for custom synthesis and per-unit transactional pricing for research-grade oligos dominate the market. Price differentiation stems from product purity, regulatory certification (e.g., GMP), and customization level. Pricing softness affects research-grade segments due to increased competition, while therapeutic-grade pricing remains firm due to stringent quality demands. Academic institutions often exhibit the highest price sensitivity.
Supply Chain Analysis
Regulatory qualification for therapeutic-grade oligonucleotides gates supply chain participation, requiring GMP-compliant facilities in the United States and Europe. Raw material dependencies center on phosphoramidite reagents and specialized solvents, primarily sourced from a limited number of chemical suppliers. A structural risk is the single-source vulnerability for niche, high-purity reagents. Distribution runs through integrated life science tool providers and specialized custom synthesis houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oligonucleotide synthesis market represents a late-cycle quality story, driven by the exacting demands of therapeutic applications. This shift towards GMP-grade therapeutic oligonucleotides necessitates unprecedented levels of purity and consistency.
For Market Incumbents:Acquire specialized process chemistry expertise to overcome process scale-up complexity for therapeutic oligonucleotides. Incumbents must also invest in validating greener solvents to comply with EU Green Deal directives, mitigating the threat of non-compliance and maintaining market access. Deepen vertical integration into phosphoramidite reagent production to reduce reliance on external suppliers and counter margin pressure. Expand GMP manufacturing capacity in regions like the United States and Europe to capture growing therapeutic demand.
For New Entrants and Emerging Players:Biotechnology firms in emerging clusters seek high-throughput, custom synthesis services for rapid innovation. New entrants can target these firms by offering flexible, silicon-based synthesis platforms optimized for early-stage discovery and screening. Focus on developing enzymatic synthesis technologies to overcome current fidelity limits and offer longer, purer sequences. A go-to-market angle involves strategic partnerships with academic research institutions for early technology validation.
For Investors and Strategic Acquirers:Consolidation pressure builds where specialized chemical engineering expertise for GMP scale-up is scarce. The long-term viability hinges on companies that can consistently deliver high-purity, therapeutic-grade oligonucleotides at scale. Target acquisition archetypes include specialized contract manufacturing organizations with proven GMP track records and advanced analytical method development capabilities. A signal to watch is the successful commercialization of novel enzymatic synthesis platforms, indicating a shift in production paradigms.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses rising therapeutic demand and stringent regulatory requirements. |
| Green Manufacturing Transition | Ensures compliance with EU Green Deal and reduces environmental footprint. |
| Technology Licensing | Accelerates adoption of enzymatic synthesis and silicon-based platforms. |
| Strategic Partnership | Facilitates access to specialized analytical method development expertise. |
| Regulatory Approval Pathway | Streamlines market entry for novel oligonucleotide-based drugs. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's market participants. Primary research involved interviews with pharmaceutical R&D leads, biotechnology firm executives, contract manufacturing organization managers, and academic researchers. Secondary data sources included regulatory filings (FDA, EMA, NMPA), scientific publications, and industry association reports. This approach enabled comprehensive bottom-up and top-down triangulation of market data.
Market dimensions were modeled at a granular level by product type, application, technology, and end-user segment. The analytical framework integrated historical data and future projections across the analysis window to derive compound annual growth rates. Forecast inputs included therapeutic pipeline advancements, diagnostic test adoption rates, and R&D spending trends. This allowed for a robust understanding of market dynamics throughout the forecast period.
Underlying measurement precision varies by segment; established DNA oligonucleotide markets carry tighter precision than nascent enzymatic synthesis technologies. Forecasts reflect assumptions regarding regulatory evolution and technological breakthroughs. A model refresh is warranted upon material change in therapeutic approval rates or key reagent supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Europe Exosome Research Products Market