
 Bioinformatics Market | 2026-2036
Bioinformatics Market Size, Share, and Industry Trends Forecast 2026-2036
Bioinformatics Market Intelligence
Cloud-native bioinformatics architecture is fragmenting legacy on-premise deployment models across pharmaceutical and academic workflows. Thermo Fisher Scientific leverages its instrument-to-software ecosystem to anchor enterprise-scale genomics pipelines. Illumina, Inc. competes through proprietary secondary analysis tools tightly coupled to its sequencing hardware. QIAGEN N.V. differentiates via curated biological databases that sustain recurring revenue in clinical interpretation.
Bioinformatics encompasses computational methods, statistical algorithms, and software tools for collecting, storing, analyzing, and interpreting biological data, particularly nucleotide and amino acid sequences, protein structures, and gene expression profiles, operating on high-performance clusters or distributed cloud infrastructure with throughput measured in terabytes per experiment. Its primary purpose is to extract actionable insights from complex biological datasets to support drug target validation, diagnostic biomarker discovery, and personalized therapeutic selection. Software solutions dominate current revenue as recurring-license models displace perpetual deployments, while genomics applications absorb the largest share of analytical compute cycles due to plummeting whole-genome sequencing costs. Services and consulting segments expand fastest as research institutes and mid-tier pharmaceutical firms outsource pipeline development rather than building internal bioinformatics capacity.
FDA guidance on next-generation sequencing-based oncology panels and HIPAA data governance requirements shape clinical bioinformatics product standards and market access conditions in the United States. EMA's In Vitro Diagnostic Regulation and GDPR constraints on cross-border genomic data transfers create parallel compliance architectures for European operators. China's NMPA digital health review pathways and national precision medicine initiatives establish a third regulatory sphere with distinct localization requirements. Stakeholders must monitor evolving interoperability mandates between proprietary cloud platforms and federated national health databases.
Market Dynamics
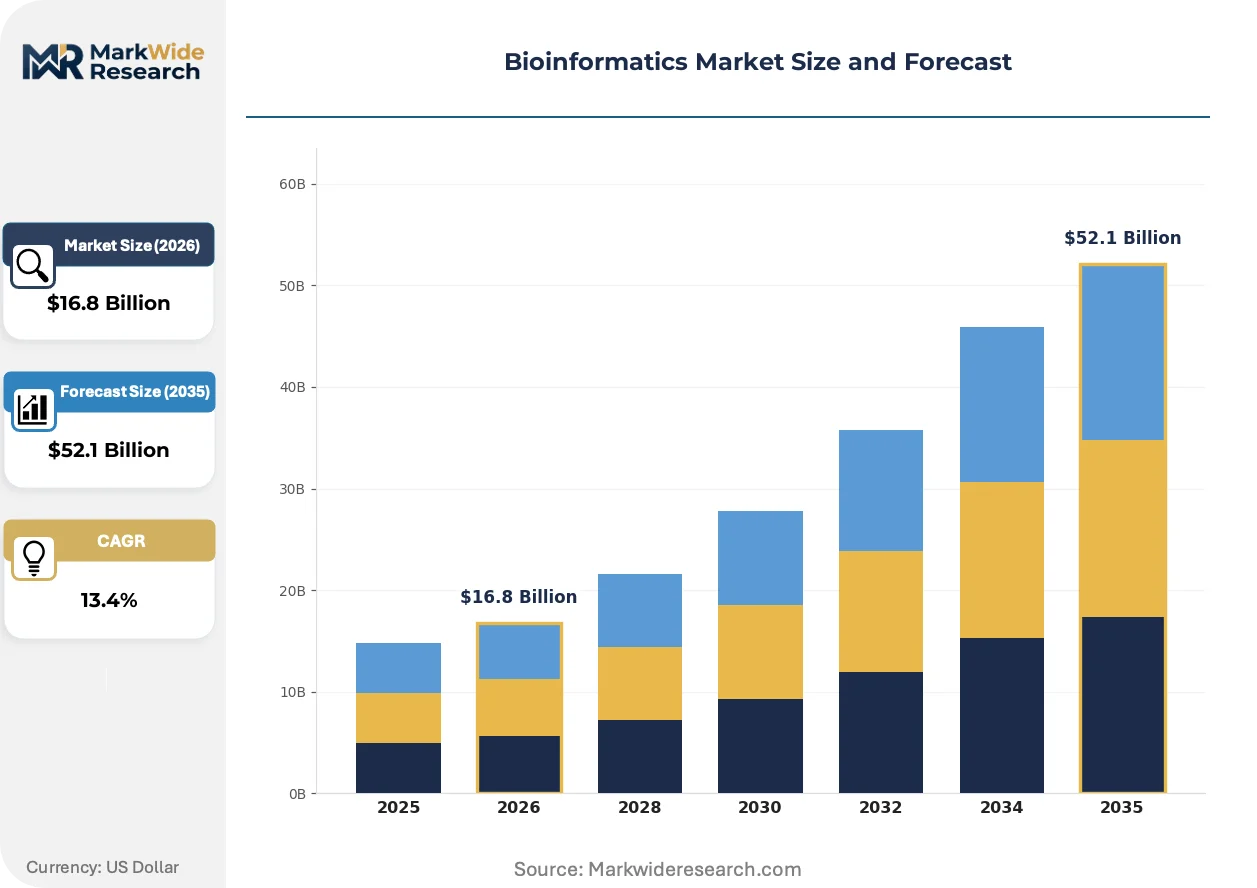
Cloud-native bioinformatics pipelines are fragmenting legacy on-premise deployment models across pharmaceutical and academic workflows, forcing platform vendors to rearchitect delivery around elastic compute and API-first integration.
Growth Catalysts
- FDA NGS Oncology Guidance:The agency's framework for next-generation sequencing-based cancer panels accelerates clinical validation timelines and expands reimbursable test categories for molecular diagnostics laboratories.
- Pharmaceutical Computational Biology Expansion:Major drug developers are scaling internal bioinformatics headcount to compress target identification cycles and reduce reliance on outsourced sequence analysis.
- China National Precision Medicine Initiative:Beijing's billion-patient genomic database project channels public investment into domestic data infrastructure and localization requirements for foreign platform vendors.
Market Restraints
- Cross-Border Genomic Data Transfer Limits:GDPR Article 44-49 restrictions and China's data localization laws fragment global dataset assembly and complicate multi-national clinical trial data pooling.
- Specialized Talent Scarcity:The intersection of computational statistics, molecular biology, and cloud engineering creates persistent hiring bottlenecks for pipeline development teams.
- Sequencing Hardware Vendor Lock-In:Proprietary secondary analysis tools tightly coupled to Illumina and Thermo Fisher instruments limit interoperability and inflate switching costs for enterprise buyers.
Strategic Opportunities
- Federated Learning Architectures:Privacy-preserving machine learning across institutional boundaries without raw data movement addresses GDPR constraints while enabling multi-site biomarker discovery.
- India's Genomics Data Center Buildout:The Department of Biotechnology's national bioinformatics network expansion creates localized infrastructure demand for cloud platform providers.
- AI-Driven Variant Interpretation:Large language models trained on curated clinical databases are automating pathogenicity classification and compressing reporting turnaround for rare disease diagnostics.
Industry Challenges
- Multi-Cloud Pipeline Orchestration Complexity:Research institutes struggle to maintain reproducible analytical workflows across AWS, Azure, and GCP environments with divergent security and cost structures.
- Clinical Interpretation Database Licensing Friction:Curated variant knowledge bases from QIAGEN and others carry per-report fees that accumulate unpredictably at high-throughput diagnostic laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioinformatics Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $52.1 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Platforms Application: Genomics, Proteomics, Drug Discovery, Metabolomics End User: Pharmaceuticals, Academics, Research Institutes, Clinical Laboratories Solution: Data Analysis, Data Management, Cloud Solutions, Consulting |
| Companies Covered | Thermo Fisher Scientific Inc., Illumina, Inc., Agilent Technologies, Inc., QIAGEN N.V., PerkinElmer, Inc., Eurofins Scientific, Bio-Rad Laboratories, Inc., DNAnexus, Inc., BGI Genomics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioinformatics Market Strategic Shifts & Innovations
Artificial intelligence is compressing sequence analysis timelines while regulatory frameworks harden around clinical-grade algorithmic interpretation, reshaping competitive differentiation toward validated, transparent biomarker discovery platforms.
GPU-accelerated de novo assembly algorithms are migrating from academic HPC clusters to managed cloud services offered by AWS HealthOmics and Google Cloud Life Sciences. Mid-tier pharmaceutical firms without captive supercomputing infrastructure are adopting these elastic pipelines for population-scale cohort studies. The shift is migrating from capital-intensive hardware ownership toward consumption-based analytical spend, compressing barriers to enterprise-scale genomics.
EMA's In Vitro Diagnostic Regulation (IVDR) reclassification imposes notified body oversight on bioinformatics software used in clinical decision-making. European diagnostic laboratories must now maintain quality management systems and performance documentation for algorithmic variant calling. Germany's national genomics medicine network is responding by centralizing analytical validation across university hospital consortia to distribute compliance costs.
Contract research organizations are unbundling bioinformatics services from sequencing contracts, selling pipeline development and data interpretation as standalone offerings. Pharmaceutical sponsors increasingly procure sequence generation from one vendor and analytical interpretation from specialized bioinformatics shops. This disintermediation is most visible in the United States, where FDA-cleared oncology panels create demand for independent clinical interpretation services separate from sequencing provision.
Bioinformatics Market Segmentation
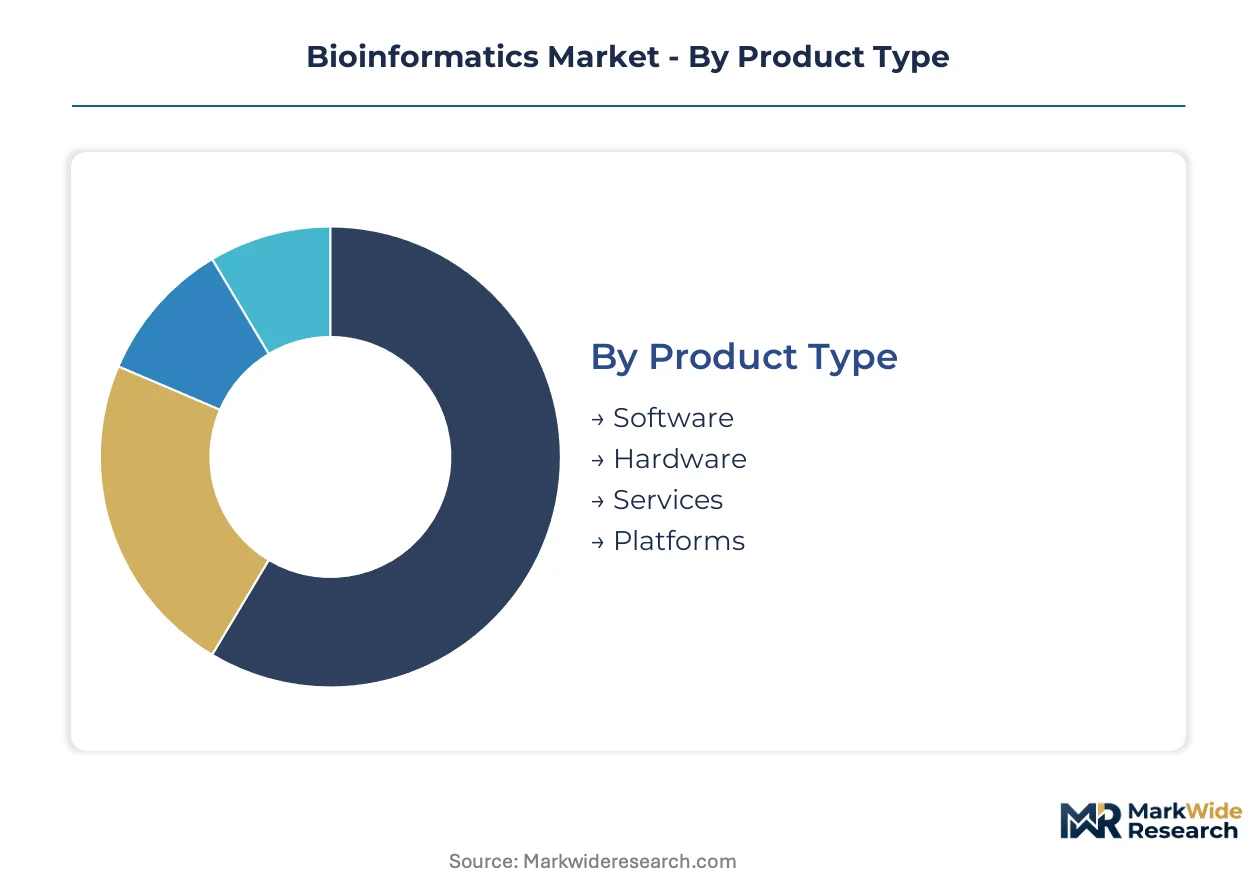
Bioinformatics market segmentation reveals distinct procurement patterns across software-centric versus service-oriented buyers. Pharmaceutical sponsors prioritize validated clinical pipelines while academic users favor open-source flexibility and grant-funded infrastructure.
Product Type:
Use-case spectrum spans perpetual-license enterprise deployments to consumption-based cloud analytics, with hardware procurement concentrating in sequencing instrument bundles.
- Software:Recurring-license models for sequence alignment, variant calling, and pathway analysis tools now dominate pharmaceutical procurement. Thermo Fisher and QIAGEN anchor enterprise contracts through curated database subscriptions tied to analytical modules.
- Services:Pipeline development, managed bioinformatics operations, and clinical interpretation outsourcing are expanding most quickly as mid-tier drug developers avoid captive infrastructure buildout. Contract research organizations now unbundle analytics from sequencing provision.
- Hardware:High-performance computing clusters and GPU-accelerated servers support de novo assembly workloads at population-scale genomics centers.
- Platforms:Integrated instrument-to-software ecosystems from sequencing vendors capture enterprise-scale deployments through bundled secondary analysis tools.
Established volume favors Software; emerging adoption favors Services.
Application:
Cost tier stratification separates high-throughput screening applications from precision diagnostic interpretation workflows.
- Genomics:Whole-genome and exome sequencing analysis consumes the largest share of computational infrastructure across pharmaceutical target identification and rare disease diagnostics. Plummeting sequencing costs continue expanding analytical volumes.
- Drug Discovery:Target validation, biomarker identification, and patient stratification algorithms compress preclinical timelines for oncology and immunology programs. AI-driven molecular docking and pathway simulation are displacing traditional wet-lab screening.
- Proteomics:Mass spectrometry data interpretation and protein structure prediction support biologics development and post-translational modification analysis.
- Metabolomics:Metabolic pathway reconstruction and flux analysis serve nutritional science and precision agriculture applications with smaller current analytical volumes.
Genomics commands infrastructure investment; drug discovery applications show steepest expansion trajectory.
End User:
Customer type determines procurement authority, with pharmaceutical procurement teams favoring enterprise agreements and academic buyers prioritizing modular, grant-funded acquisitions.
- Pharmaceuticals:Computational biology team expansion across major drug developers drives demand for validated, FDA-aligned analytical pipelines. Internal headcount growth reduces historical reliance on outsourced sequence analysis.
- Academics:University genomics centers and principal investigator labs favor open-source tools and federated national infrastructure over commercial platform subscriptions. Grant cycles dictate procurement timing.
- Research Institutes:Independent research organizations balance custom pipeline development against managed service partnerships for specialized cohort studies.
- Clinical Laboratories:Diagnostic labs processing oncology panels and carrier screening require HIPAA-compliant, CLIA-validated interpretation workflows with rapid turnaround requirements.
Pharmaceuticals anchor commercial revenue; clinical laboratories are gaining share fastest.
Solution:
Maturity gradient separates established data management infrastructure from emerging AI-augmented interpretation capabilities.
- Data Analysis:Secondary and tertiary analytical pipelines—variant calling, differential expression, and pathway enrichment—constitute core platform functionality. GPU acceleration and cloud migration reshape delivery economics.
- Cloud Solutions:Elastic compute for population-scale cohort studies and federated learning architectures address GDPR constraints on cross-border genomic data movement. AWS HealthOmics and Google Cloud Life Sciences compete for pharmaceutical workloads.
- Data Management:LIMS integration, sample tracking, and multi-omic data warehousing support reproducibility requirements across regulated environments.
- Consulting:Custom pipeline architecture, regulatory strategy, and computational biology staffing augmentation serve organizations lacking internal bioinformatics capacity.
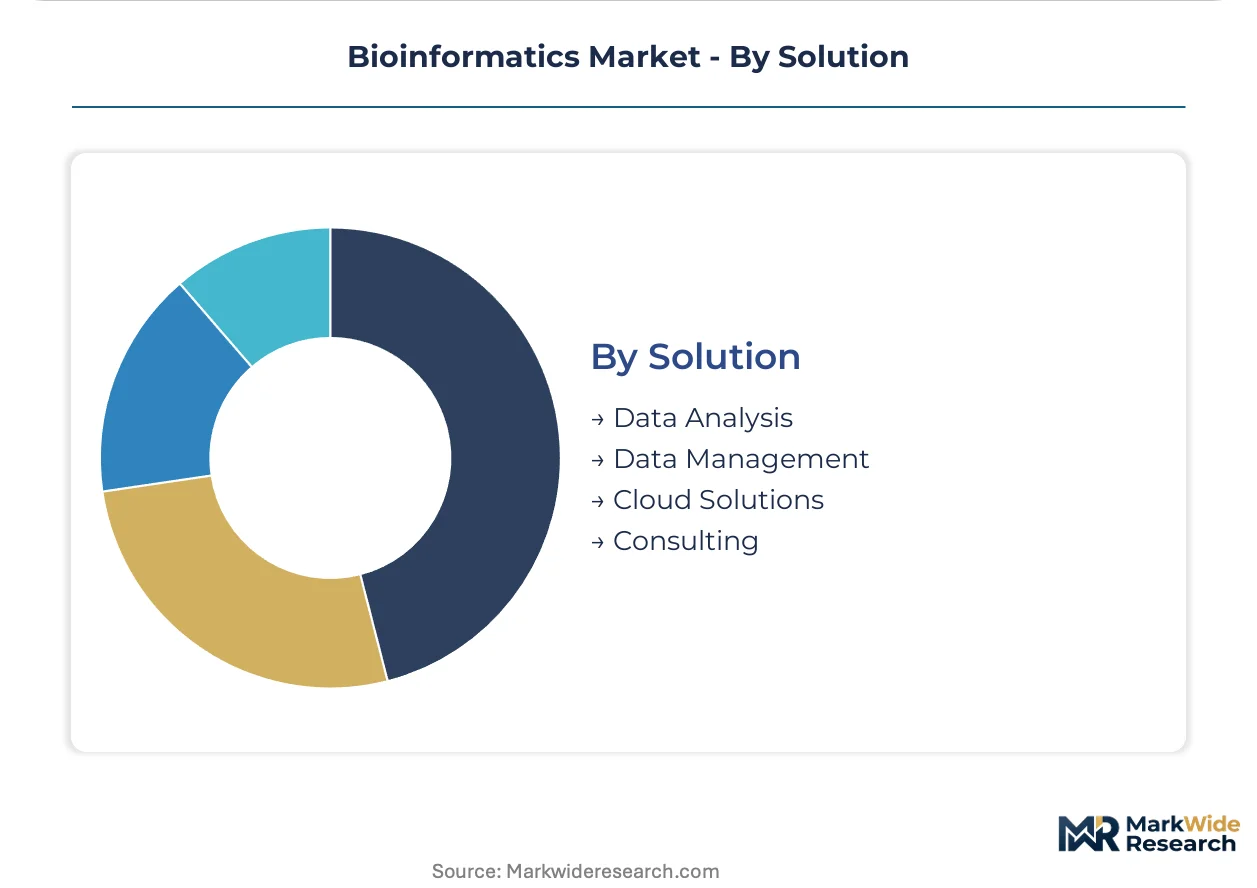
Data analysis retains deployment dominance; cloud solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement teams and academic research centers concentrate bioinformatics infrastructure investment in jurisdictions with aligned regulatory pathways and public genomics funding. National precision medicine programs and data localization requirements reshape vendor selection criteria across major markets.
United States
FDA guidance on next-generation sequencing-based oncology panels accelerates clinical validation timelines for molecular diagnostics laboratories. HIPAA data governance requirements impose strict security architectures on cloud-native bioinformatics deployments. The Boston-Cambridge biotech corridor anchors enterprise-scale computational biology team expansion across major drug developers.
China
Beijing's billion-patient genomic database project channels public investment into domestic data infrastructure and localization mandates. NMPA digital health review pathways establish distinct approval requirements for foreign platform vendors. Shanghai and Shenzhen host concentrated sequencing instrument manufacturing and cloud platform development clusters serving regional demand.
Germany
EMA's In Vitro Diagnostic Regulation imposes notified body oversight on clinical decision-support algorithms. GDPR Article 44-49 restrictions complicate cross-border genomic data pooling for multi-national trials. The Munich-Heidelberg university hospital network centralizes analytical validation to distribute IVDR compliance costs across consortia members.
India
The Department of Biotechnology's national bioinformatics network expansion creates localized infrastructure demand for cloud providers. CDSCO regulatory pathways for software-as-medical-device remain under development, creating uncertainty for clinical interpretation platforms. Bangalore and Hyderabad concentrate bioinformatics services outsourcing operations for international pharmaceutical sponsors.
United Kingdom
NHS Genomic Medicine Service procurement standards prioritize interoperability with federated national health databases. Post-Brexit data transfer arrangements with the EU create parallel compliance architectures for cross-border research collaborations. The Cambridge-London corridor sustains academic-industry partnerships in AI-driven variant interpretation development.
Bioinformatics Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement environments where pharmaceutical buyers favor validated enterprise agreements and academic users prioritize modular open-source flexibility. The vendor base spans three tiers: integrated instrument-to-software ecosystems, standalone analytical platform providers, and specialized database curation services. Dominant competitive moves include strategic partnerships to embed interpretation tools within sequencing workflows and geographic expansion to capture national precision medicine program allocations.
Among integrated ecosystem providers, Thermo Fisher Scientific Inc. and Illumina, Inc. occupy positions anchoring enterprise-scale deployments through bundled hardware-software offerings. QIAGEN N.V. exemplifies the database-centric archetype, sustaining recurring revenue through curated biological knowledge bases that power clinical interpretation workflows. These three entities represent distinct strategic postures: instrument-driven platform control, sequencing hardware anchoring, and biological content monetization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| Agilent Technologies, Inc. |
| QIAGEN N.V. |
| PerkinElmer, Inc. |
| Eurofins Scientific |
| Bio-Rad Laboratories, Inc. |
| DNAnexus, Inc. |
| BGI Genomics Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Boston-Cambridge's computational biology cluster anchors cloud-native platform capacity, concentrating pricing power among instrument-to-software ecosystem providers while forcing mid-tier buyers toward consumption-based analytical spend models.
Pricing Analysis
Cost-plus contracts with cloud infrastructure indexation dominate enterprise pharmaceutical procurement, locking analytical spend to AWS, Azure, and GCP compute pricing. Three-tier pricing structure across premium, standard, and economy levels separates validated clinical pipelines from research-grade tools and open-source alternatives. Cost compression in the mid-tier is intensifying because GPU-accelerated managed services are commoditizing population-scale genomics workloads. Academic buyers exhibit highest price sensitivity, favoring grant-funded open-source flexibility over recurring-license commercial platforms.
Supply Chain Analysis
Upstream feedstock for bioinformatics platforms draws from semiconductor fabrication in Taiwan, GPU manufacturing in South Korea, and cloud data center buildout across the United States and China. Proprietary sequencing instruments, curated clinical databases, and elastic compute infrastructure constitute core component dependencies. Single-source vulnerability concentrates in Illumina's secondary analysis tool ecosystem and QIAGEN's variant knowledge base licensing. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and academic consortia purchasing for research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native bioinformatics sits in early-cycle expansion as pharmaceutical computational biology team buildouts accelerate platform adoption beyond traditional sequencing service outsourcing.
For Market Incumbents: Build switching-cost moats through deeper integration of curated clinical databases with cloud-native analytical workflows. Defensive moves center on embedding interpretation tools within sequencing instrument firmware to limit interoperability with third-party platforms, and securing exclusive licensing arrangements with university hospital consortia for IVDR-aligned validation datasets. Threat from federated learning architectures demands counter-investment in privacy-preserving machine learning capabilities to retain enterprise accounts facing GDPR constraints. For New Entrants and Emerging Players: Build out specialized clinical interpretation services unbundled from sequencing provision, targeting mid-tier diagnostic laboratories overwhelmed by per-report database licensing fees from incumbents. Most penetrable white-space sits in India's national bioinformatics network expansion and AI-driven variant interpretation for rare disease diagnostics. Go-to-market angle emphasizes consumption-based pricing without upfront infrastructure commitment, aligning with grant-funded academic procurement cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-agnostic cloud infrastructure providers over hardware-coupled software vendors over the projection horizon. Long-term viability hinges on regulatory validation depth rather than raw analytical throughput. Acquisition target archetype: specialized bioinformatics services firms with FDA-cleared oncology panel interpretation workflows and established CLIA laboratory partnerships. Signal to watch is EMA IVDR enforcement intensity against non-validated algorithmic variant calling in European diagnostic laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Deployment | Privacy-preserving multi-site biomarker discovery addresses GDPR Article 44-49 constraints without raw data movement. |
| GPU-Accelerated Cloud Pipeline Migration | AWS HealthOmics and Google Cloud Life Sciences compete for pharmaceutical population-scale cohort study workloads. |
| Clinical Database Licensing Restructuring | Per-report fee models face pressure from high-throughput diagnostic laboratories seeking predictable cost structures. |
| IVDR-Centralized Validation Consortia | Germany's Munich-Heidelberg university hospital network distributes compliance costs across multi-institutional quality systems. |
| AI-Driven Variant Interpretation Investment | Large language models trained on curated clinical databases compress reporting turnaround for rare disease diagnostics. |
Research Approach
The analysis maps software platforms, managed services, and integrated instrument ecosystems, each validated through computational biology directors, diagnostic laboratory operations managers, pharmaceutical procurement leads, and cloud platform engineering heads. Primary intelligence combines structured interviews with secondary triangulation against FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov protocol registries, and hyperscaler healthcare vertical revenue disclosures. Bottom-up segment sizing and top-down market reconciliation anchor value estimates.
Assumptions held fixed include regulatory pathway stability for NGS-based oncology panels and continued cloud infrastructure cost decline curves, while variables tested include pharmaceutical captive team buildout rates and GDPR enforcement intensity on cross-border genomic transfers. Segmentation dimensions span deployment model, end-user type, application area, and regional regulatory cluster. CAGRs derive from fitted adoption curves against historical pharmaceutical R&D outsourcing patterns and national precision medicine program budget trajectories.
Sensitivities concentrate around FDA guidance revisions for clinical-grade algorithmic interpretation and China's data localization mandate expansion affecting multi-national trial data pooling. Forecasts reflect documented assumptions on cloud migration velocity and open-source tool penetration in academic settings. Cross-checking against disclosed pharmaceutical computational biology headcount growth and hyperscaler healthcare vertical revenue breakdowns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
China Computational Biology Market
Bioinformatics
US Computational Biology Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
North America Computational Biology Market