
 Biological Derived Devices Market | 2026-2036
Biological Derived Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Biological Derived Devices Market Analysis
The capital-intensity divergence between large-scale CDMOs and specialized biologics developers is redrawing competitive boundaries in biological derived devices. Thermo Fisher Scientific leverages its analytical instrumentation and bioproduction platforms to anchor upstream supply security for device-grade biological materials. Lonza Group sustains differentiated positioning through mammalian cell culture expertise that supports complex tissue-engineered constructs. Samsung Biologics competes aggressively on manufacturing scale, occupying one of the largest single-site biologics production footprints worldwide.
Biological derived devices comprise therapeutic and diagnostic instruments manufactured from living tissues, recombinant proteins, or biodegradable polymers engineered to integrate with host physiology; these products typically incorporate collagen matrices, decellularized extracellular scaffolds, or bioactive ceramic composites designed for controlled resorption and cellular infiltration. Implants and biologics product categories command the deepest margin pools, with orthopedic and cardiovascular applications driving volume concentration as hospitals prioritize durable biological fixation over permanent synthetic alternatives. Biosensors represent the fastest-ascending segment, fueled by continuous glucose monitoring platforms and wearable diagnostic interfaces that merge biological recognition elements with semiconductor fabrication.
FDA's Center for Devices and Radiological Health enforces design controls and biocompatibility testing under 21 CFR Part 820, while the EU Medical Device Regulation mandates notified body oversight and unique device identification for biological implantables. The FDA and EMA frameworks collectively elevate barriers for novel tissue-engineered products, channeling development resources toward predicate-backed regulatory pathways. Stakeholders must monitor evolving reimbursement codes for biological implants and anticipate convergence between software-enabled diagnostics and living-device platforms.
Market Dynamics
Decellularized extracellular matrix sourcing is bifurcating manufacturing economics between porcine-derived collagen suppliers and recombinant protein fermenters, forcing device makers to anchor capacity decisions around species-traceable supply chains rather than cost optimization alone.
Growth Catalysts
- FDA 21 CFR Part 1271 Human Cells, Tissues, and Cellular and Tissue-Based Products:Established risk-tiered frameworks accelerate predicate pathway clearances for xenogeneic scaffolds in orthopedic applications.
- Continuous glucose monitoring biosensors:Wearable diagnostic interfaces merge biological recognition elements with semiconductor fabrication, creating new reimbursement codes for real-time metabolic tracking.
- South Korean MFDS fast-track designations:Seoul-based manufacturing clusters leverage accelerated review timelines to compress commercialization cycles for cardiovascular patches.
Market Restraints
- Porcine tissue input volatility:African swine fever outbreaks in East Asian herds disrupt collagen matrix pricing and force dual-sourcing mandates.
- EMA MDR Class III implantable requirements:Notified body capacity constraints extend clinical evaluation timelines for novel tissue-engineered constructs.
- Synthetic polymer substitution:PEEK and titanium alloys retain cost advantages in load-bearing orthopedic segments where biological resorption kinetics underperform.
Strategic Opportunities
- India CDSCO tissue banking regulations:Emerging domestic scaffold manufacturing incentives open procurement channels for cost-sensitive trauma fixation devices.
- Neurological implant convergence:Bioactive ceramic composites with electrical conductivity properties enable next-generation neural electrode interfaces.
- Direct-to-hospital consignment models:Implant distributors bypass group purchasing organizations to capture margin from high-turnover biological fixation products.
Industry Challenges
- Decellularization technician scarcity:Specialized bioprocessing expertise for extracellular matrix preservation commands premium wages and extends facility ramp timelines.
- ISO 10993 biocompatibility testing bottlenecks:Third-party laboratory capacity constraints delay submission-ready documentation for novel xenogeneic materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological Derived Devices Market |
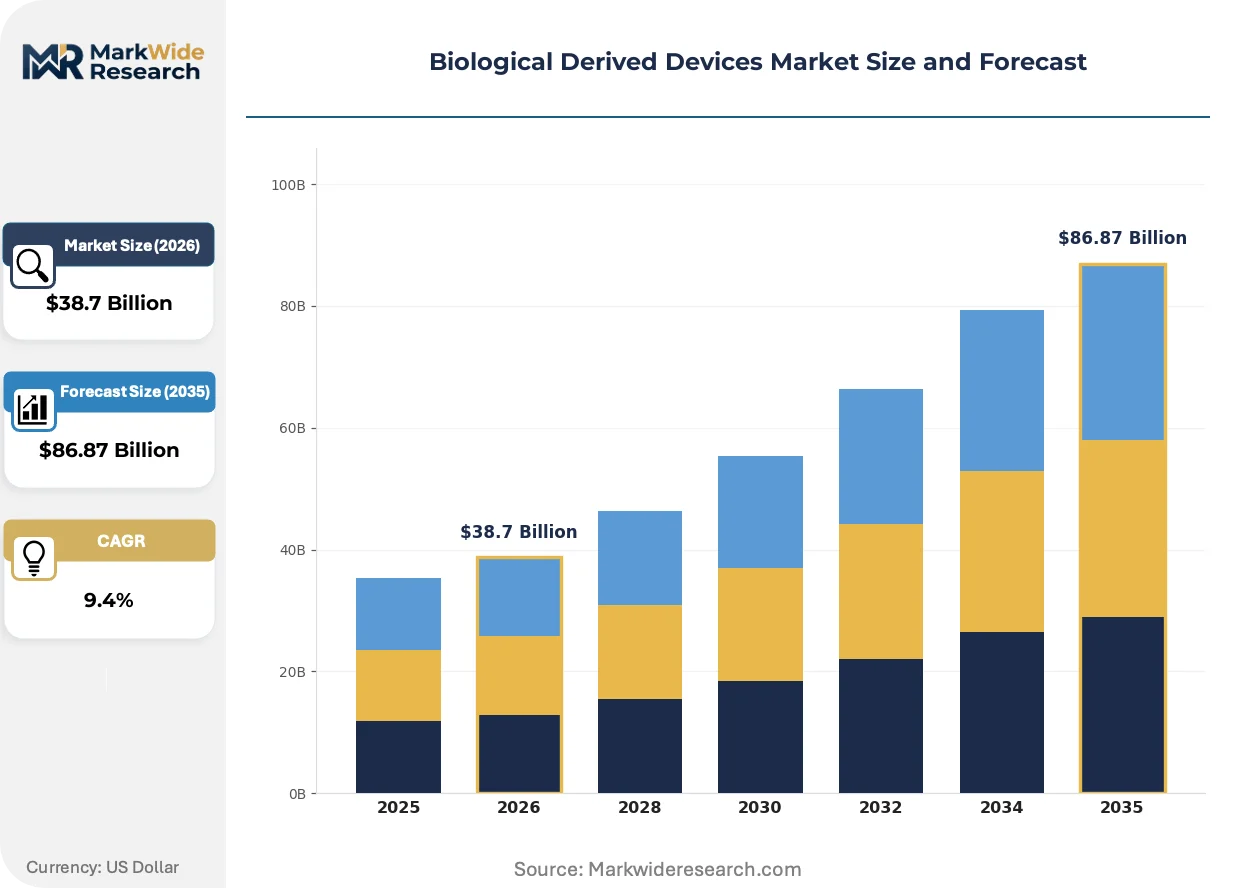
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Prosthetics, Biologics, Biosensors Material: Polymers, Tissues, Metals, Ceramics End User: Hospitals, Clinics, Research Labs, Homecare Application: Orthopedics, Cardiology, Tissue Engineering, Diagnostics |
| Companies Covered | Thermo Fisher Scientific, Becton Dickinson and Company, PHC Holdings Corporation, Qiagen, Merck KGaA, Samsung Biologics, Lonza Group, Celltrion Healthcare, F Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological Derived Devices Market Emerging Trajectories
Biological derived devices are entering a phase where material provenance and processing traceability rival clinical efficacy as competitive differentiators, reshaping how manufacturers architect supply relationships and quality systems.
Decellularized xenograft scaffolds is bifurcating the orthopedic implant landscape between allogeneic human tissue banks and engineered porcine-derived matrices. Academic medical centers in Germany and the United States are adopting species-traceable constructs at accelerated procurement cycles. This technology is compressing margins for traditional cadaveric tissue processors while enabling premium pricing for recombinant collagen platforms with batch-level genomic verification.
EU MDR Article 10.4 on clinical evidence requirements for absorbable implants is forcing manufacturers to generate post-market surveillance data beyond traditional predicate equivalence. The regulation compresses development timelines for cardiovascular patches while elevating documentation burdens for small-scale tissue engineering specialists. German notified bodies are prioritizing review capacity for orthopedic applications, diverting resources from emerging neurological scaffold categories.
Hospital value analysis committees now mandate lifecycle cost modeling that incorporates reoperation risk from biological resorption failures. This purchasing pattern is displacing traditional surgeon preference cards in United States health systems with standardized formularies tied to outcomes data. The shift is most visible in cardiovascular service lines, where Cleveland Clinic and Mayo Clinic procurement frameworks penalize devices lacking five-year durability evidence.
Biological Derived Devices Market Segmentation
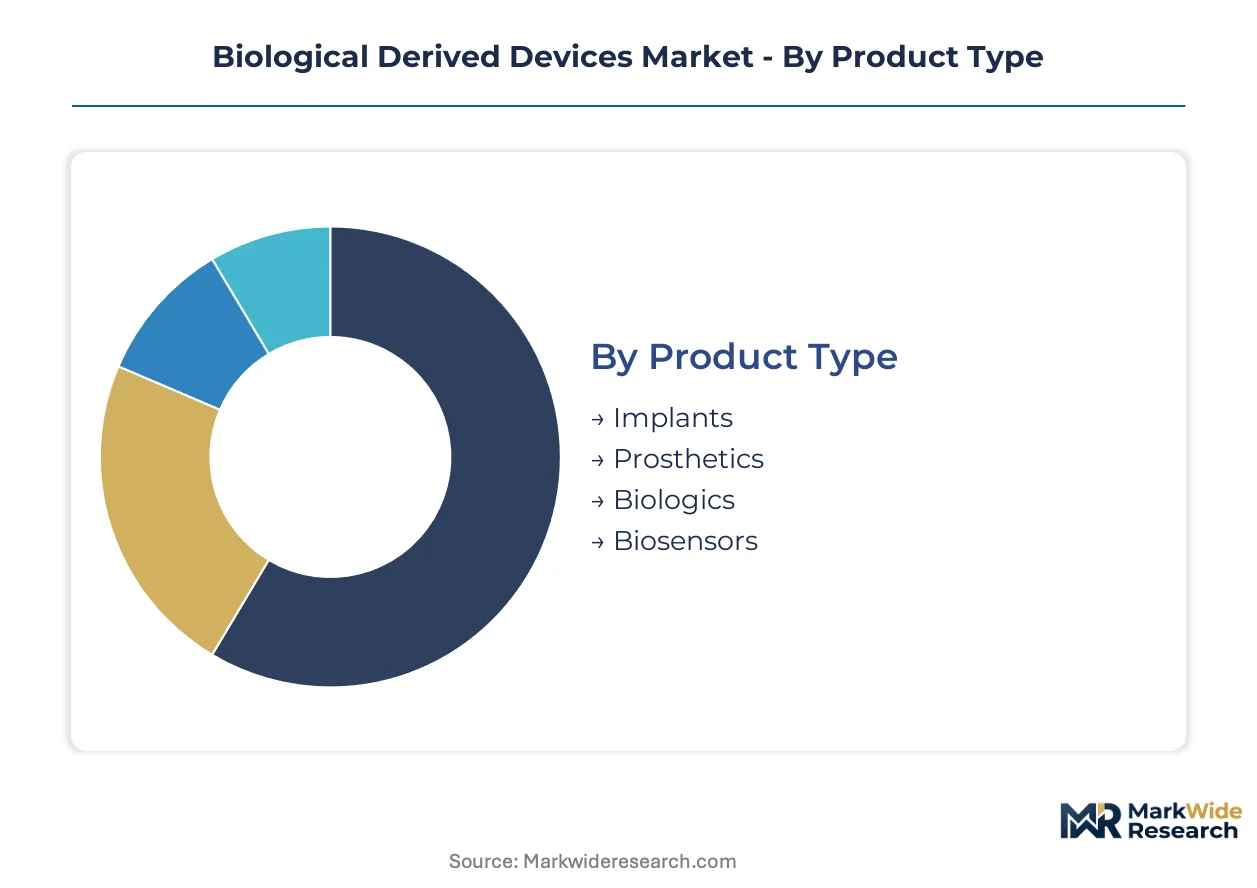
Biological derived devices span heterogeneous material classes and regulatory risk tiers, forcing manufacturers to align product architectures with distinct approval pathways and reimbursement codes. Segmentation clarity determines which development pipelines warrant capital allocation versus partnership structures.
Product Type:
FDA 21 CFR Part 1271 risk-tiering creates divergent commercialization economics across biological device categories, with HCT/P minimal manipulation standards compressing timelines for some segments while PMA pathways extend others.
- Implants:Decellularized extracellular matrix scaffolds and collagen-based fixation devices integrate with host tissue through controlled resorption kinetics. Orthopedic surgical suites in Germany and the United States concentrate procurement for species-traceable constructs that satisfy hospital value analysis committees.
- Biosensors:Wearable diagnostic interfaces merge biological recognition elements with semiconductor fabrication for continuous metabolic monitoring. South Korean manufacturing clusters in Songdo and Incheon dominate production of glucose-responsive enzyme electrodes.
- Prosthetics:Bioactive ceramic composites and tissue-engineered interfaces for limb attachment.
- Biologics:Recombinant protein matrices and growth factor delivery systems for localized tissue regeneration.
Established volume favors implants; emerging adoption favors biosensors.
Material:
Cost tier differentiation separates premium recombinant platforms from commodity tissue derivatives, with pricing stratification tracking supply chain traceability investments.
- Tissues:Porcine-derived collagen matrices and decellularized xenografts command premium positioning when genomic batch verification is available. African swine fever outbreaks in East Asian herds force dual-sourcing mandates that reshape procurement economics.
- Polymers:Biodegradable synthetic scaffolds engineered for tunable degradation profiles. Research labs in Boston and Basel drive demand for customizable resorption kinetics in preclinical tissue engineering.
- Metals:Titanium and magnesium alloys with bioactive surface coatings for load-bearing applications.
- Ceramics:Hydroxyapatite and bioactive glass composites for osteoconductive integration.
Margin concentration sits with tissue-derived platforms; volume scaling favors polymer standardization.
End User:
Customer type determines purchasing authority structures, with hospital procurement committees displacing individual surgeon preference in high-volume categories.
- Hospitals:Integrated delivery networks with value analysis committees mandate lifecycle cost modeling that incorporates reoperation risk. Cleveland Clinic and Mayo Clinic frameworks penalize devices lacking five-year durability evidence.
- Research Labs:Academic medical centers and contract research organizations with specialized bioprocessing requirements. German university hospitals in Heidelberg and Tübingen anchor European demand for experimental scaffold platforms.
- Clinics:Ambulatory surgical centers with streamlined procurement for high-turnover fixation products.
- Homecare:Direct-to-patient distribution channels for wearable diagnostic and monitoring devices.
Procurement centralization favors hospitals; technology access favors research labs.
Application:
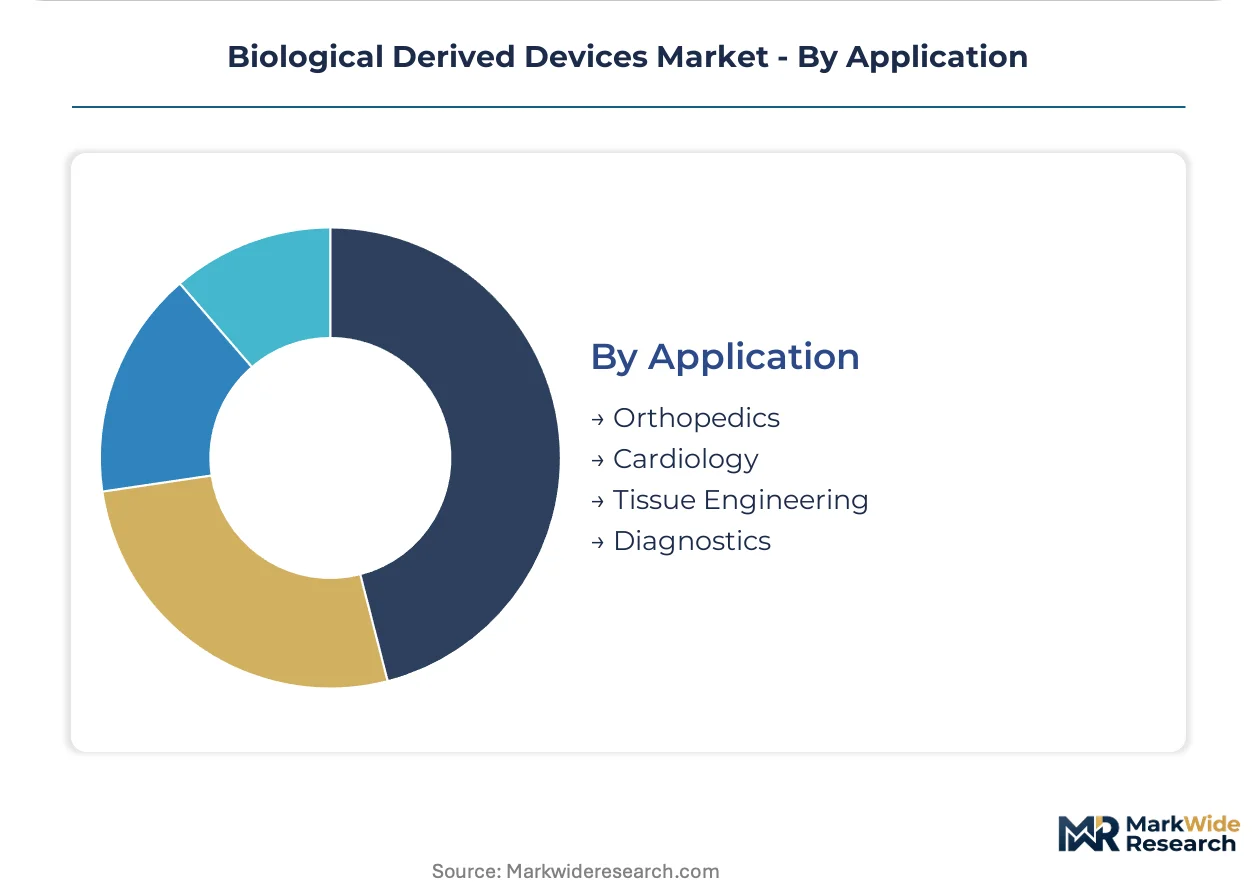
Clinical domain maturity shapes competitive intensity, with well-established orthopedic segments facing margin pressure from novel therapeutic categories.
- Orthopedics:Spinal fusion cages, meniscal scaffolds, and rotator cuff repair matrices represent the deepest revenue pool. FDA predicate pathway clearances accelerate commercialization for xenogeneic constructs in sports medicine.
- Cardiology:Cardiovascular patches and biological vascular grafts face elevated EMA MDR Class III documentation burdens. German notified body capacity constraints extend clinical evaluation timelines for novel tissue-engineered constructs.
- Tissue Engineering:Custom scaffold fabrication for organ regeneration and wound healing applications.
- Diagnostics:Biological recognition elements integrated with microfluidic and semiconductor platforms.
Revenue depth concentrates in orthopedics; steepest expansion trajectory emerges in cardiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany and the United States tolerate premium pricing for species-traceable constructs, while Indian trauma centers and Brazilian public health systems prioritize cost-sensitive polymer alternatives that sacrifice batch-level genomic verification.
United States
Cleveland Clinic and Mayo Clinic value analysis committees mandate five-year durability evidence for cardiovascular biological implants. FDA 21 CFR Part 1271 risk-tiered frameworks accelerate predicate pathway clearances for orthopedic xenogeneic scaffolds. Boston and San Diego manufacturing clusters anchor recombinant protein fermentation capacity for device-grade collagen matrices.
Germany
Heidelberg and Tübingen university hospitals drive European demand for experimental decellularized scaffold platforms. EMA MDR Article 10.4 clinical evidence requirements compress development timelines for absorbable cardiovascular patches. German notified bodies prioritize review capacity for orthopedic applications, diverting resources from neurological scaffold categories.
South Korea
Songdo and Incheon manufacturing clusters dominate production of glucose-responsive enzyme electrodes for wearable biosensors. MFDS fast-track designations compress commercialization cycles for cardiovascular tissue-engineered patches. Seoul-based CDMOs leverage accelerated review timelines to capture contract manufacturing from Western device developers.
India
Domestic trauma fixation device procurement channels expand under CDSCO tissue banking regulation incentives for cost-sensitive hospital systems. Maharashtra and Gujarat manufacturing zones attract scaffold production investments targeting price-elastic emerging market demand. Local producers substitute recombinant platforms with porcine-derived collagen matrices lacking genomic batch verification.
Switzerland
Basel research laboratories drive preclinical demand for customizable polymer resorption kinetics in tissue engineering applications. Swissmedic oversight maintains stringent biocompatibility documentation standards that elevate barriers for novel xenogeneic materials. Zurich-based analytical instrumentation suppliers anchor quality control infrastructure for European biological device manufacturers.
Biological Derived Devices Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where analytical instrumentation specialists and mammalian cell culture experts occupy distinct premium positions. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with bioproduction platforms, specialized CDMOs with single-site scale advantages, and focused tissue engineering developers with decellularization expertise. Dominant competitive moves include backward integration into species-traceable supply chains and geographic expansion into fast-track regulatory jurisdictions.
Among diversified life science conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify the technology-anchored archetype through analytical instrumentation and bioproduction platform breadth. Lonza Group and Samsung Biologics occupy positions on the manufacturing-scale vector, with the former representing specialized mammalian cell culture expertise and the latter exemplifying single-site capacity maximization. These four entities collectively illustrate how capital-intensity divergence redraws competitive boundaries between upstream supply security and downstream manufacturing scale.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Becton Dickinson and Company |
| PHC Holdings Corporation |
| Qiagen |
| Merck KGaA |
| Samsung Biologics |
| Lonza Group |
| Celltrion Healthcare |
| F Hoffmann-La Roche |
| Others |
Supply Flow & Price Mechanics
Ninety-day decellularization facility ramp timelines compress procurement flexibility for device-grade biological materials, concentrating pricing power with species-traceable collagen suppliers in Germany and the United States while forcing cost-sensitive buyers toward unverified porcine derivatives. Hospital value analysis committees exploit this asymmetry to extract volume discounts from recombinant protein platforms, widening spreads between genomic-verified premium tiers and commodity tissue inputs.
Pricing Analysis
After-sales revenue from implant reoperation warranties and extended biological resorption monitoring contracts drives lifetime value for orthopedic device portfolios. Three-tier pricing structure across premium recombinant matrices, standard decellularized xenografts, and economy cadaveric allografts stratifies by FDA 21 CFR Part 1271 risk-tier certification and batch-level genomic traceability. Cost compression in economy tiers intensifies because African swine fever disruptions force dual-sourcing mandates that erode scale advantages. Trauma centers in India and Brazil exhibit highest price sensitivity, while German university hospitals tolerate premium positioning for Heidelberg-sourced experimental scaffolds.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose East Asian porcine collagen shipments to African swine fever quarantine delays, amplifying inventory carrying costs for Boston and San Diego recombinant fermentation facilities. Manufacturing gravity centers on South Korea for glucose-responsive biosensor electrodes, Germany for cardiovascular patch notified body oversight, and Switzerland for analytical instrumentation quality control. Raw material dependencies span porcine dermal matrices, mammalian cell culture media, and bioactive ceramic precursors. Single-source vulnerability concentrates in Seoul-based CDMO capacity for wearable diagnostic interfaces. Distribution runs through direct-to-hospital consignment models that bypass group purchasing organization margin extraction for high-turnover fixation products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological derived devices fragment across incompatible regulatory risk tiers and material provenance standards, creating specialist niches as hospital procurement centralization displaces individual surgeon preference with standardized formularies tied to outcomes data.
For Market Incumbents: Compound defensive positioning through backward integration into species-traceable porcine supply chains and captive recombinant fermentation capacity in Boston or San Diego clusters. Synthetic polymer substitution in load-bearing orthopedic segments threatens biological resorption kinetics; counter by securing FDA predicate pathway clearances for xenogeneic scaffolds that accelerate commercialization velocity versus novel tissue-engineered constructs. For New Entrants and Emerging Players: Differentiate on decellularization technician expertise scarcity by establishing training pipelines with Heidelberg or Tübingen university hospital partnerships. Neurological implant convergence with bioactive ceramic electrical conductivity properties represents the most penetrable white-space category, with Cleveland Clinic and Mayo Clinic procurement frameworks currently underweight in five-year durability evidence requirements for neural electrode interfaces. Pursue direct-to-hospital consignment models that capture margin from high-turnover biological fixation products bypassing group purchasing organization structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mammalian cell culture platform investments as Lonza Group and Samsung Biologics expand single-site biologics production footprints. Long-term viability over the next decade favors acquisition targets with decellularization expertise and notified body relationships in Germany rather than pure manufacturing scale plays. Monitor MFDS fast-track designation velocity in Seoul as the signal to watch for regulatory arbitrage opportunities compressing commercialization cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Capacity Reservation | German orthopedic application prioritization diverts review resources from emerging neurological scaffold categories. |
| Species-Traceable Supply Chain Certification | FDA 21 CFR Part 1271 risk-tiered frameworks reward genomic batch verification with accelerated predicate clearances. |
| Reimbursement Code Development | Continuous glucose monitoring biosensors create new metabolic tracking payment structures with CMS and commercial payers. |
| Decellularization Technician Training Pipeline | Specialized bioprocessing expertise scarcity commands premium wages and extends facility ramp timelines. |
| Direct-to-Hospital Consignment Infrastructure | Implant distributors bypass group purchasing organizations to capture margin from high-turnover biological fixation products. |
Methodological Framework
Cross-validation between primary interviews with hospital value analysis committee members, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) and PMA filings, EMA MDR submission databases, and hospital procurement contract repositories anchors the qualitative findings. Bottom-up triangulation from product-level reimbursement codes and top-down validation from regulatory framework capacity constraints ensure segmentation integrity across implants, biosensors, and biologics categories.
Sensitivity analysis on porcine tissue input volatility and notified body review timeline compression shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material provenance tier, end-user purchasing authority structure, and application-specific clinical evidence requirements. CAGRs derive from installed base erosion rates for synthetic alternatives and biological resorption kinetics adoption curves. Forecast inputs incorporate ISO 10993 biocompatibility testing laboratory capacity constraints and MFDS fast-track designation velocity.
The analysis sits within stated boundaries; outcomes outside sustained FDA predicate pathway availability or EMA MDR Class III implantable documentation burden stability would require recalibration. Forecasts reflect assumptions regarding African swine fever herd recovery trajectories and decellularization technician wage inflation. Practitioners should keep alternative scenarios live as reimbursement code convergence between software-enabled diagnostics and living-device platforms evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioprosthetics Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market