
 AI in Life Science Analytics Market | 2026-2036
AI in Life Science Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Life Science Analytics Market Intelligence
Foundation model integration into multi-omic data pipelines is rewriting how predictive biomarker platforms are architected. IQVIA Inc. leverages its proprietary real-world data networks to train disease progression models across oncology and immunology. Veeva Systems Inc. anchors its competitive position through cloud-native vault platforms that unify clinical and commercial data for top-20 pharmaceutical sponsors. Palantir Technologies Inc. differentiates via ontology-based data integration that maps molecular, clinical, and operational datasets into queryable knowledge graphs.
AI in Life Science Analytics encompasses machine learning, natural language processing, and predictive modeling systems applied to structured and unstructured biomedical data for hypothesis generation, patient stratification, and regulatory decision support. These platforms process genomic sequences, electronic health records, and scientific literature through neural architectures to identify therapeutic targets, optimize trial design, and forecast safety signals before human studies commence. Natural Language Processing applications dominate current deployment as pharmaceutical companies automate regulatory document extraction and adverse event coding from unstructured clinical narratives. Machine Learning segments in genomics and drug discovery attract the fastest investment growth as CRISPR screening data and single-cell atlases expand training corpus scale. Cloud-based deployment captures the largest revenue share among delivery modes, though hybrid architectures gain traction where intellectual property constraints mandate on-premises model training with cloud inference.
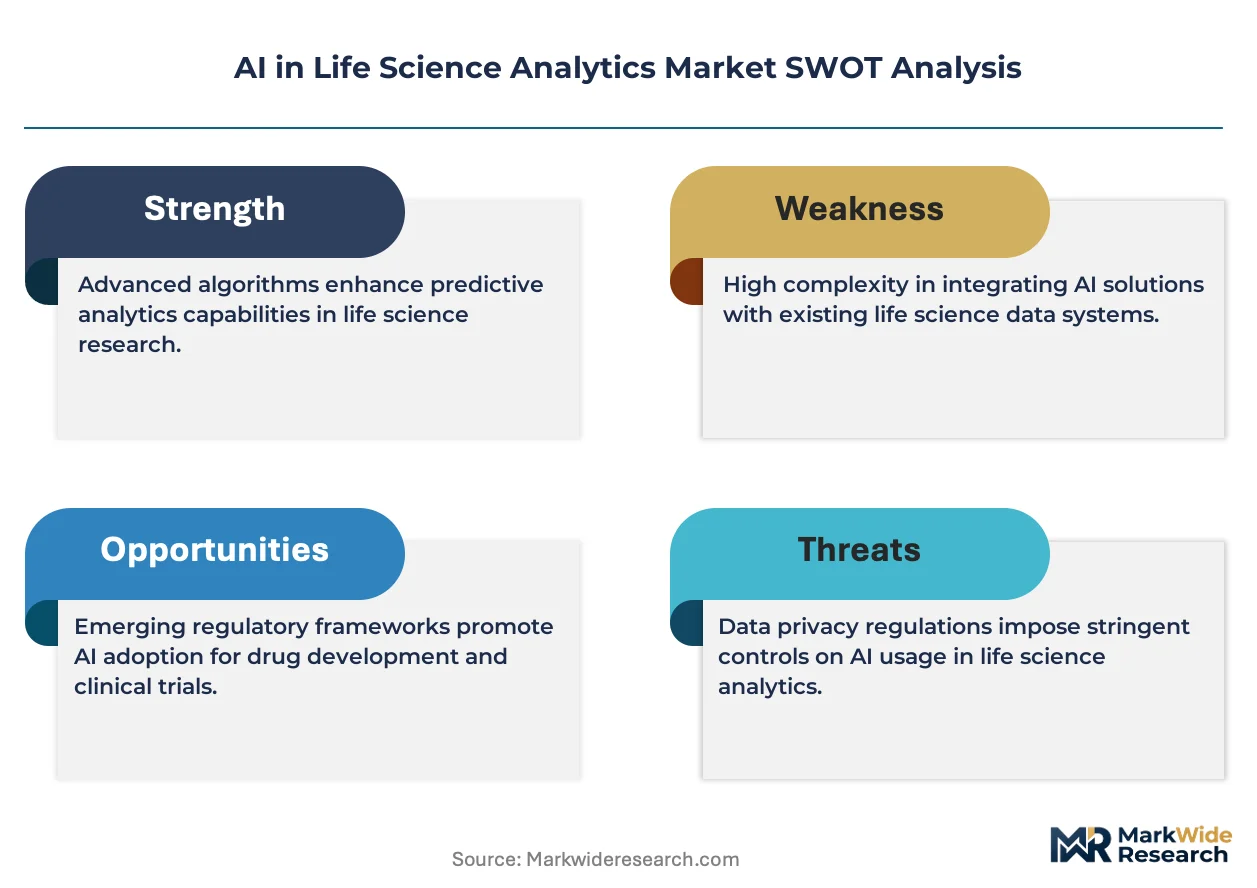
The FDA, EMA, and WHO collectively shape market access through divergent validation requirements for AI as a medical device and algorithmic bias documentation in clinical decision support. FDA guidance on predetermined change control plans forces developers to lock model update protocols before marketing authorization, raising compliance engineering costs. EMA's draft reflection paper on artificial intelligence in medicinal product lifecycle demands traceability matrices linking training data provenance to model outputs for marketing applications. Stakeholders must monitor whether regulatory divergence between Washington and Brussels fragments platform development into geographically siloed compliance stacks.
Market Dynamics
Foundation model architectures are compressing drug discovery timelines by unifying genomic, proteomic, and clinical data streams into single inference pipelines, forcing pharmaceutical sponsors to restructure analytics procurement around multi-modal platform capabilities rather than point solutions.
Growth Catalysts
- FDA Predetermined Change Control Plans:The FDA's guidance on locking model update protocols before marketing authorization creates compliance clarity that accelerates enterprise AI procurement cycles for algorithmic safety tools.
- Single-Cell Atlas Expansion:CRISPR screening datasets and spatial transcriptomics atlases are expanding training corpus scale for machine learning segments in genomics and target identification.
- EMA Traceability Mandates:The EMA's draft reflection paper demanding training data provenance documentation is driving investment in data lineage infrastructure across European pharmaceutical development pipelines.
Market Restraints
- GPU Compute Cost Volatility:Cloud-based foundation model training requires sustained access to NVIDIA H100 clusters, creating input cost exposure that constrains mid-cap biotech AI adoption.
- Regulatory Divergence Friction:Divergent validation requirements between FDA, EMA, and WHO are fragmenting platform development into geographically siloed compliance stacks that duplicate engineering overhead.
- Interpretability Limitations:Black-box neural architectures in biomarker prediction face resistance from regulatory reviewers demanding mechanistic explanations for marketing authorization decisions.
Strategic Opportunities
- Japan's PMDA Digital Transformation:Japan's pharmaceutical regulator is accelerating AI-enabled medical device pathways, creating first-mover advantage for ontology-based knowledge graph platforms in Asian markets.
- Real-World Evidence Convergence:Integration of electronic health record mining with wearable sensor streams is enabling continuous safety signal detection that displaces periodic manual pharmacovigilance reviews.
- Hybrid Deployment Architectures:Intellectual property constraints in antibody discovery are mandating on-premises model training with cloud inference, opening infrastructure service opportunities for specialized life science cloud providers.
Industry Challenges
- Computational Biology Talent Scarcity:The intersection of deep learning expertise with molecular biology domain knowledge remains severely under-supplied, extending hiring timelines for platform engineering teams.
- Legacy LIMS Integration Complexity:Pharmaceutical sponsors operate decades-old laboratory information management systems that resist API-based connectivity to modern AI analytics pipelines.
- Multi-Omic Data Harmonization:Inconsistent metadata standards across genomic, proteomic, and metabolomic datasets require manual curation overhead that consumes 40-60% of analytics project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Life Science Analytics Market |
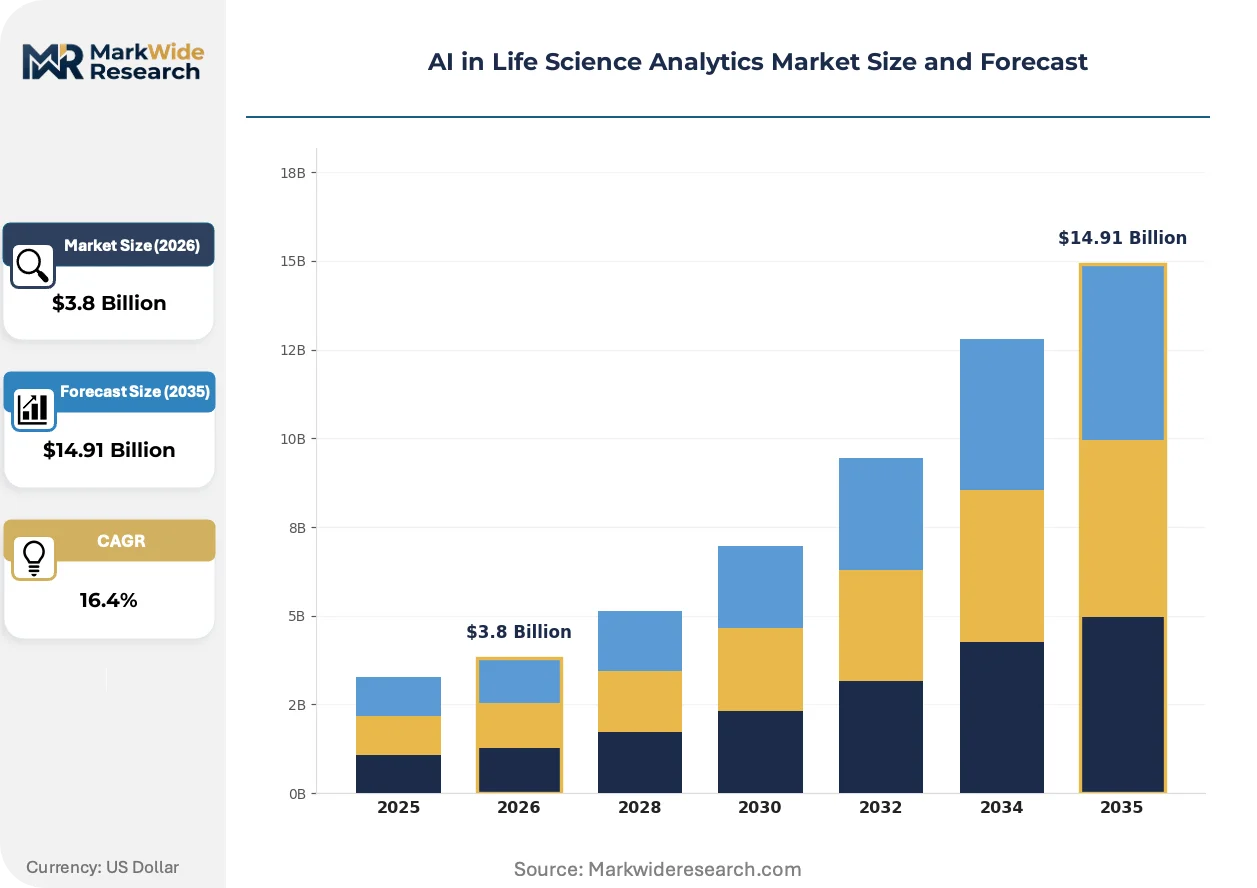
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Clinical Trials, Drug Discovery, Genomics, Drug Repurposing End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research, Contract Research Organizations Deployment: Cloud-based, On-premises, Hybrid, SaaS Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Data Mining |
| Companies Covered | Veeva Systems Inc., Medidata Solutions, IQVIA Inc., Snowflake Inc., Databricks, Oracle, IBM Corporation, Palantir Technologies Inc., SAS Institute Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Life Science Analytics Market Strategic Shifts & Innovations
Computational architectures are pivoting from retrospective statistical analysis toward prospective generative modeling, with pharmaceutical sponsors demanding platforms that simulate molecular behavior rather than merely classify historical patterns.
Transformer-based protein structure prediction is migrating from academic research environments into commercial drug discovery workflows. Mid-cap biotechnology firms are adopting AlphaFold-derived architectures for antibody engineering at compressed 12-18 month procurement cycles. This technology is migrating from structural biology departments into target validation and lead optimization stages, collapsing traditional silos between computational and medicinal chemistry functions.
The EU AI Act's risk classification framework for clinical decision support systems is imposing conformity assessment obligations on algorithmic diagnostic tools. Developers must now maintain technical documentation and human oversight protocols that parallel medical device quality management systems. Oncology biomarker platforms face the steepest compliance burden, with sponsors restructuring algorithm governance committees to satisfy notified body audit requirements.
Pharmaceutical procurement teams are unbundling analytics software licenses from mandatory professional services contracts that previously consumed 60-70% of total contract value. Self-service model deployment interfaces are displacing vendor-managed implementation models, particularly among top-20 sponsors with established data science centers of excellence. This pattern is most visible in the United States, where Boston and San Francisco clusters anchor internal platform engineering capabilities that reduce dependency on external system integrators.
AI in Life Science Analytics Market Segmentation
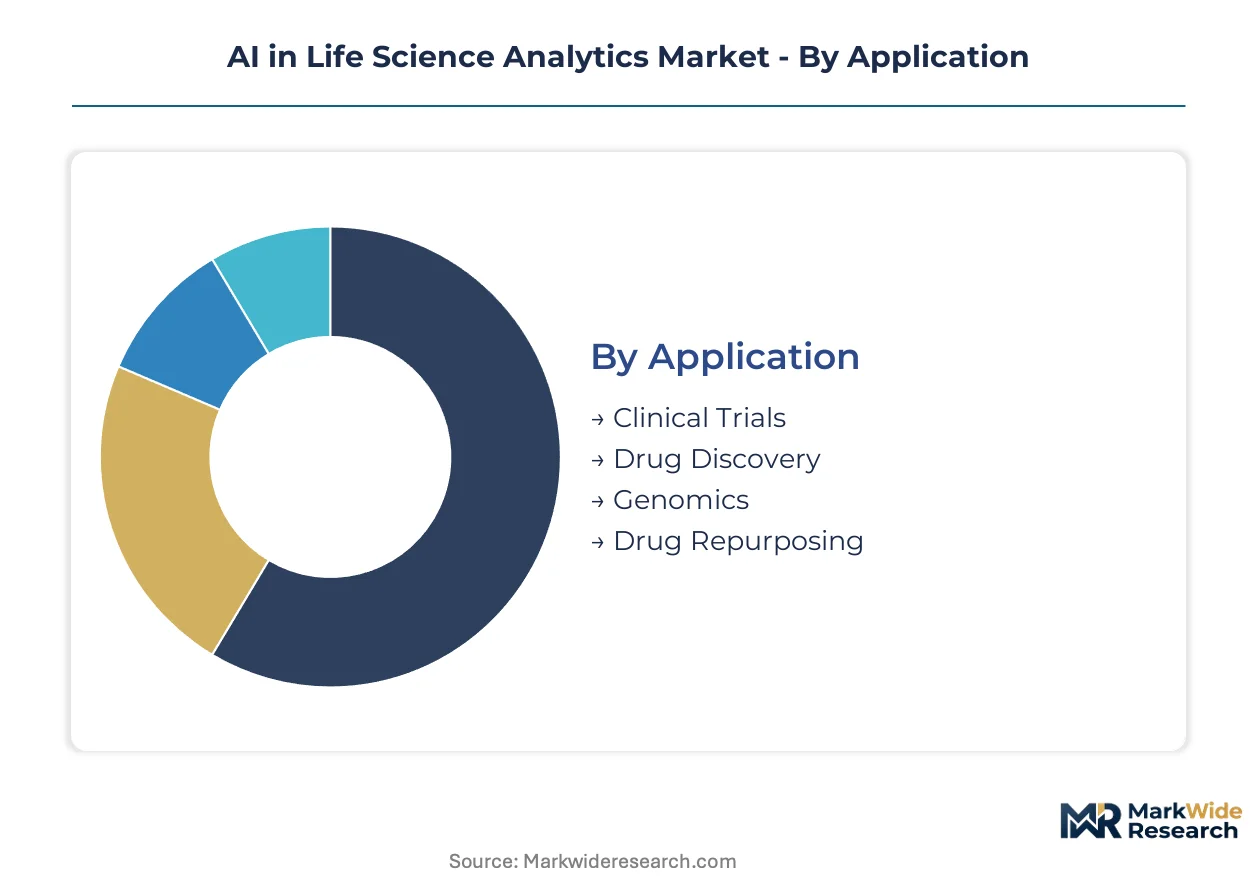
AI in Life Science Analytics Market segmentation reveals how pharmaceutical sponsors prioritize procurement across the analytics value chain. Deployment architecture and technology modality selections directly constrain model training capabilities and regulatory submission pathways.
Application:
Application dimension captures where algorithmic investment concentrates across the pharmaceutical development lifecycle, from target identification through post-market surveillance.
- Clinical Trials:Platforms optimize patient recruitment, site selection, and adaptive trial design through real-world data mining. Demand clusters among top-20 pharmaceutical sponsors operating in the United States, where FDA predetermined change control plans accelerate procurement for algorithmic safety monitoring tools.
- Drug Discovery:Generative models simulate molecular behavior and predict protein-ligand interactions across CRISPR screening datasets. Biotechnology firms in Boston and San Francisco anchor demand, driven by pressure to compress discovery timelines against patent cliffs.
- Genomics:Multi-omic data pipelines integrate single-cell atlases with spatial transcriptomics for biomarker identification.
- Drug Repurposing:Knowledge graph platforms map existing compounds against novel disease indications using electronic health record networks.
Clinical Trials holds installed capacity. Drug Discovery is rotating up the share rankings.
End User:
End user typology determines procurement sophistication, contract structure, and internal platform engineering capacity across the customer base.
- Pharmaceutical Companies:Enterprise-scale deployments demand unified clinical-commercial data vaults with regulatory-grade audit trails. These sponsors in the United States drive cloud-native architecture adoption, constrained by legacy LIMS integration complexity.
- Biotechnology Firms:Mid-cap developers prioritize point solutions for target validation and lead optimization with compressed 12-18 month procurement cycles. GPU compute cost volatility constrains foundation model training ambitions among this cohort.
- Academic Research:Grant-funded investigators access federated data networks and open-source toolkits with limited commercial deployment pathways.
- Contract Research Organizations:Service providers build multi-tenant platforms to serve fragmented sponsor demand across oncology and immunology indications.
Pharmaceutical Companies dominate contract value. Biotechnology Firms are expanding fastest.
Deployment:
Deployment modality reflects intellectual property risk tolerance and computational infrastructure ownership preferences across the customer base.
- Cloud-based:Scalable inference infrastructure supports real-world evidence mining and continuous safety signal detection. United States-based sponsors with established data science centers of excellence drive self-service model deployment interfaces.
- Hybrid:On-premises model training with cloud inference addresses antibody discovery IP constraints while enabling scalable deployment. This architecture gains traction where EMA traceability mandates demand data residency controls.
- On-premises:Captive infrastructure serves proprietary CRISPR screening datasets and single-cell atlases with strict access controls.
- SaaS:Subscription-based access lowers barrier to entry for mid-cap biotechnology firms with limited IT engineering capacity.
Cloud-based holds installed capacity. Hybrid is climbing the fastest.
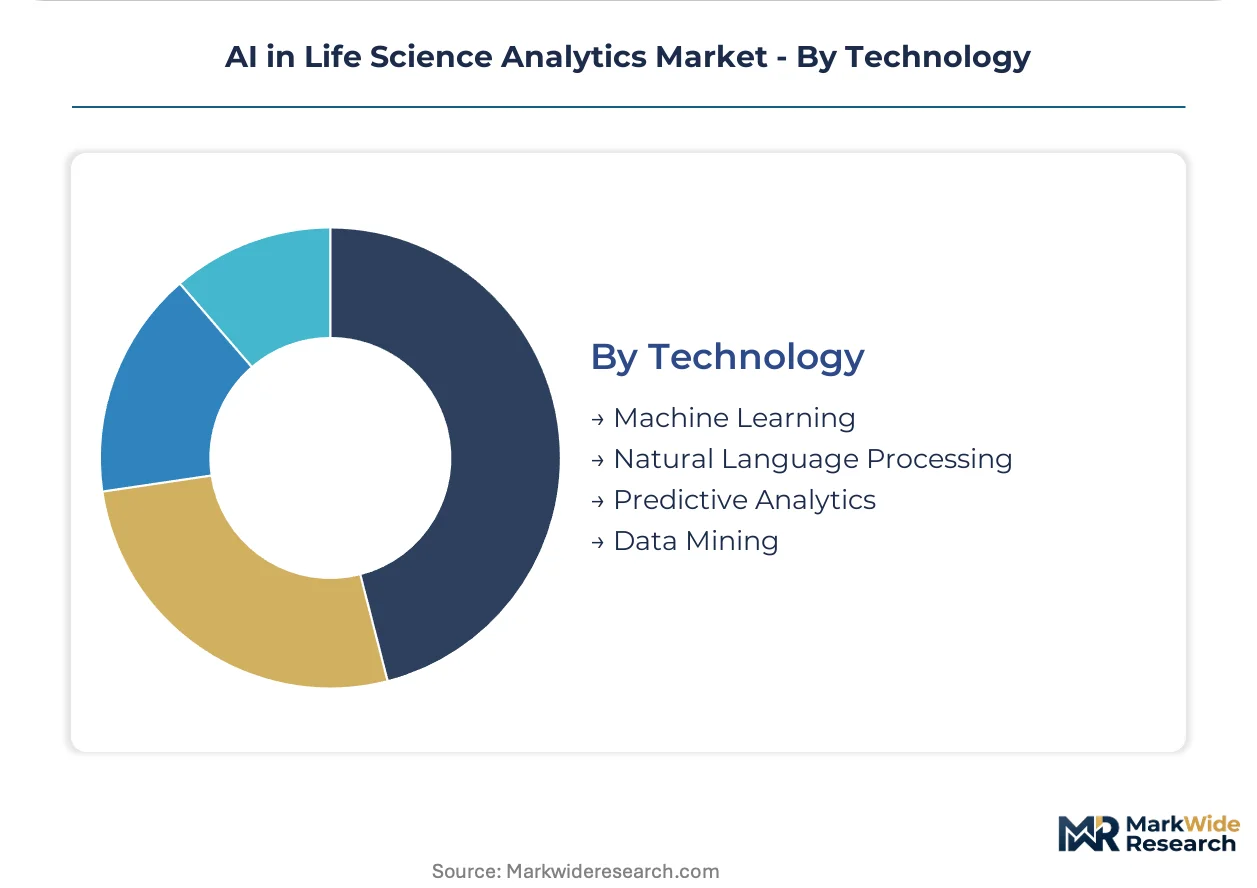
Technology:
Technology modality determines data processing architecture, interpretability characteristics, and regulatory validation burden for marketing authorization.
- Natural Language Processing:Transformer architectures extract regulatory intelligence and automate adverse event coding from unstructured clinical narratives. Pharmaceutical procurement teams in the United States deploy these tools to displace manual pharmacovigilance reviews.
- Machine Learning:Neural architectures process genomic sequences and CRISPR screening data for target identification. EMA draft reflection paper demands on training data provenance documentation elevate compliance engineering costs for European deployments.
- Predictive Analytics:Statistical models forecast disease progression and safety signals across real-world data networks.
- Data Mining:Pattern recognition algorithms identify therapeutic targets from scientific literature and patent corpora.
Natural Language Processing holds installed capacity. Machine Learning is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based pharmaceutical sponsors export AI-enabled clinical trial analytics services to European and Asian biotechnology developers seeking FDA-aligned validation protocols.
United States
Boston and San Francisco anchor the largest clusters of life science data science talent, driving enterprise procurement of cloud-native analytics platforms. FDA guidance on predetermined change control plans accelerates validation timelines for algorithmic drug safety tools. Top-20 pharmaceutical sponsors in these metros are restructuring analytics procurement around multi-modal platform capabilities.
Germany
EMA traceability mandates for training data provenance documentation elevate compliance engineering costs for European deployments. Heidelberg and Munich host specialized computational biology units serving mid-cap biotechnology firms. These clusters focus on hybrid deployment architectures balancing data residency controls with scalable cloud inference.
United Kingdom
London's contract research organizations build multi-tenant platforms serving fragmented sponsor demand across oncology indications. MHRA alignment with FDA validation frameworks streamlines cross-Atlantic regulatory submissions. The Cambridge life science corridor concentrates real-world evidence mining capabilities for adaptive trial design.
Japan
PMDA digital transformation initiatives accelerate AI-enabled medical device pathways, creating first-mover advantage for knowledge graph platforms. Tokyo and Osaka pharmaceutical sponsors demand ontology-based data integration mapping molecular and clinical datasets. Japanese regulators are shortening review cycles for algorithmic diagnostic tools compared to historical benchmarks.
Switzerland
Basel's pharmaceutical headquarters drive demand for unified clinical-commercial data vaults with regulatory-grade audit trails. Swissmedic maintains alignment with EMA reflection papers while offering specialized pathways for digital therapeutics. Geneva-based biotech firms concentrate investment in generative modeling for antibody engineering.
AI in Life Science Analytics Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Enterprise-scale data platform vendors and cloud-native vault providers dominate contract value among top-20 pharmaceutical sponsors. Three archetypes define competitive positioning: real-world data network operators, ontology-based knowledge graph specialists, and cloud infrastructure enablers. Consolidation pressure is intensifying through strategic partnerships between analytics software vendors and specialized system integrators.
Within the real-world data network tier, IQVIA Inc. and Veeva Systems Inc. exemplify divergent approaches to pharmaceutical data unification. IQVIA leverages proprietary real-world data networks to train disease progression models, while Veeva anchors its position through cloud-native vault platforms. Palantir Technologies Inc. occupies a distinct position among ontology-based integration specialists, mapping molecular and operational datasets into queryable knowledge graphs. These three entities represent the primary competitive anchors shaping procurement patterns across United States and European pharmaceutical development pipelines.
| Leading Market Players |
|---|
| Veeva Systems Inc. |
| Medidata Solutions |
| IQVIA Inc. |
| Snowflake Inc. |
| Databricks |
| Oracle |
| IBM Corporation |
| Palantir Technologies Inc. |
| SAS Institute Inc. |
| Others |
Cost & Logistics Intelligence
Boston and San Francisco anchor cloud-native AI platform development, where concentrated data science talent pools create pricing power for vendors serving top-20 pharmaceutical sponsors with multi-modal analytics capabilities.
Pricing Analysis
Current-generation foundation model platforms command substantial premiums over prior-generation statistical analytics tools, while next-generation generative molecular simulation systems are entering at price points that compress legacy margins. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade vault deployments with regulatory audit trails from mid-market SaaS subscriptions and academic research licenses. Cost compression in the standard tier is intensifying because GPU compute cost volatility constrains vendor margin expansion. Biotechnology firms with compressed procurement cycles exhibit highest price sensitivity, while pharmaceutical companies with established data science centers of excellence prioritize capability depth over license cost.
Supply Chain Analysis
Upstream feedstock for AI life science analytics draws from NVIDIA H100 GPU clusters concentrated in the United States, Taiwan, and South Korea, with secondary sourcing from cloud hyperscaler infrastructure in Ireland and Singapore. Raw material dependencies span specialized AI accelerators, high-bandwidth memory modules, and proprietary real-world data network licenses from IQVIA and similar operators. Single-source vulnerability around NVIDIA's advanced GPU architectures creates supply chain concentration risk that vendors hedge through multi-cloud deployment strategies. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and channel partnerships with contract research organizations serving mid-cap biotechnology developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among top-20 pharmaceutical sponsors in the United States, where procurement teams are unbundling analytics software licenses from mandatory professional services contracts that previously captured 60-70% of total contract value.
For Market Incumbents: Pre-empt platform commoditization by deepening proprietary real-world data network moats and accelerating FDA-aligned validation protocol development before EMA traceability mandates fragment European procurement. Self-service model deployment interfaces from cloud-native competitors threaten vendor-managed implementation revenue streams. Priority levers include backward integration into single-cell atlas data generation and hybrid deployment architecture certification for antibody discovery IP constraints. For New Entrants and Emerging Players: Mid-cap biotechnology firms in Boston and San Francisco with 12-18 month procurement cycles represent the most penetrable entry point for point-solution target validation platforms. Japan's PMDA digital transformation pathway offers first-mover positioning for ontology-based knowledge graph specialists seeking Asian market establishment. Go-to-market execution should anchor on GPU-efficient model architectures that sidestep foundation model training cost barriers constraining competitor pricing flexibility. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA predetermined change control plans and EMA traceability mandates are erecting compliance engineering barriers that favor incumbents with established validation infrastructure. Acquisition targets should profile as computational biology talent-dense teams with hybrid deployment capabilities and European regulatory submission experience. The signal to watch is PMDA pathway acceleration for algorithmic diagnostic tools, which would validate Asian market expansion theses.| Strategic Initiative | Industry Significance |
|---|---|
| Foundation Model Integration | Unifies genomic, proteomic, and clinical data streams into single inference pipelines for pharmaceutical sponsors. |
| Hybrid Deployment Architecture | Addresses antibody discovery IP constraints while enabling scalable cloud inference for EMA data residency requirements. |
| Regulatory Validation Pathway | Locks FDA predetermined change control plans before marketing authorization to accelerate enterprise procurement cycles. |
| Real-World Data Network Expansion | Trains disease progression models across oncology and immunology through proprietary electronic health record mining. |
| Ontology-Based Knowledge Graph | Maps molecular, clinical, and operational datasets into queryable structures for Japanese PMDA digital transformation pathways. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up and top-down triangulation cross-checked segment-level demand signals against macro-level pharmaceutical R&D expenditure patterns.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling deployment architecture, application lifecycle stage, end-user sophistication tier, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from fitted growth curves applied to validated baseline estimates, with inputs including CRISPR screening data expansion rates, cloud hyperscaler capex disclosures for GPU infrastructure, and pharmaceutical sponsor AI procurement survey data.
Practitioners should monitor regulatory divergence between FDA, EMA, and WHO validation requirements for early signals of platform fragmentation into geographically siloed compliance stacks. Forecasts reflect assumptions regarding sustained GPU compute cost volatility and stable pharmaceutical R&D budget allocations. Material shifts in foundation model training cost curves or sudden harmonization of international AI medical device standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
North America Computational Biology Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
US Computational Biology Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
China Computational Biology Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
Bioinformatics Market