
 US Computational Biology Market | 2026-2036
US Computational Biology Market Size, Share, and Industry Trends Forecast 2026-2036
US Computational Biology Market Insights
Asset-light cloud subscription models is narrowing the capital barrier for mid-tier biotech firms seeking enterprise-grade simulation infrastructure. Thermo Fisher Scientific leverages its installed base of laboratory instruments to bundle computational workflows with hardware contracts. Illumina anchors genomic data generation, creating downstream demand for analysis platforms that process its sequencing outputs. Schrodinger specializes in physics-based molecular simulation, differentiating through proprietary algorithms that predict binding affinity with high precision.
Computational biology applies mathematical modeling, statistical methods, and algorithmic analysis to interpret complex biological datasets, typically processing genomic sequences, protein structures, and metabolic pathways through high-performance computing clusters to accelerate therapeutic discovery and precision medicine development. Drug discovery applications dominate current spending as pharmaceutical sponsors replace portions of wet-lab screening with in silico prediction, while machine learning capabilities represent the fastest-expanding technology segment as neural architectures improve pattern recognition across multi-omics datasets. Cloud computing infrastructure supports elastic scaling for intermittent workloads such as population-scale genome-wide association studies, where margin pools accrue to platform providers offering compliant data environments.
FDA oversight of AI/ML-based diagnostic algorithms and HIPAA requirements for patient-derived genomic data shape product architecture and go-to-market constraints for solution vendors. The National Institutes of Health data sharing policies and 21st Century Cures Act provisions further dictate how computational tools must handle interoperability and evidence standards. Stakeholders must monitor evolving FDA guidance on adaptive algorithms to determine validation investment timelines and partnership strategies with regulated end users.
Market Dynamics
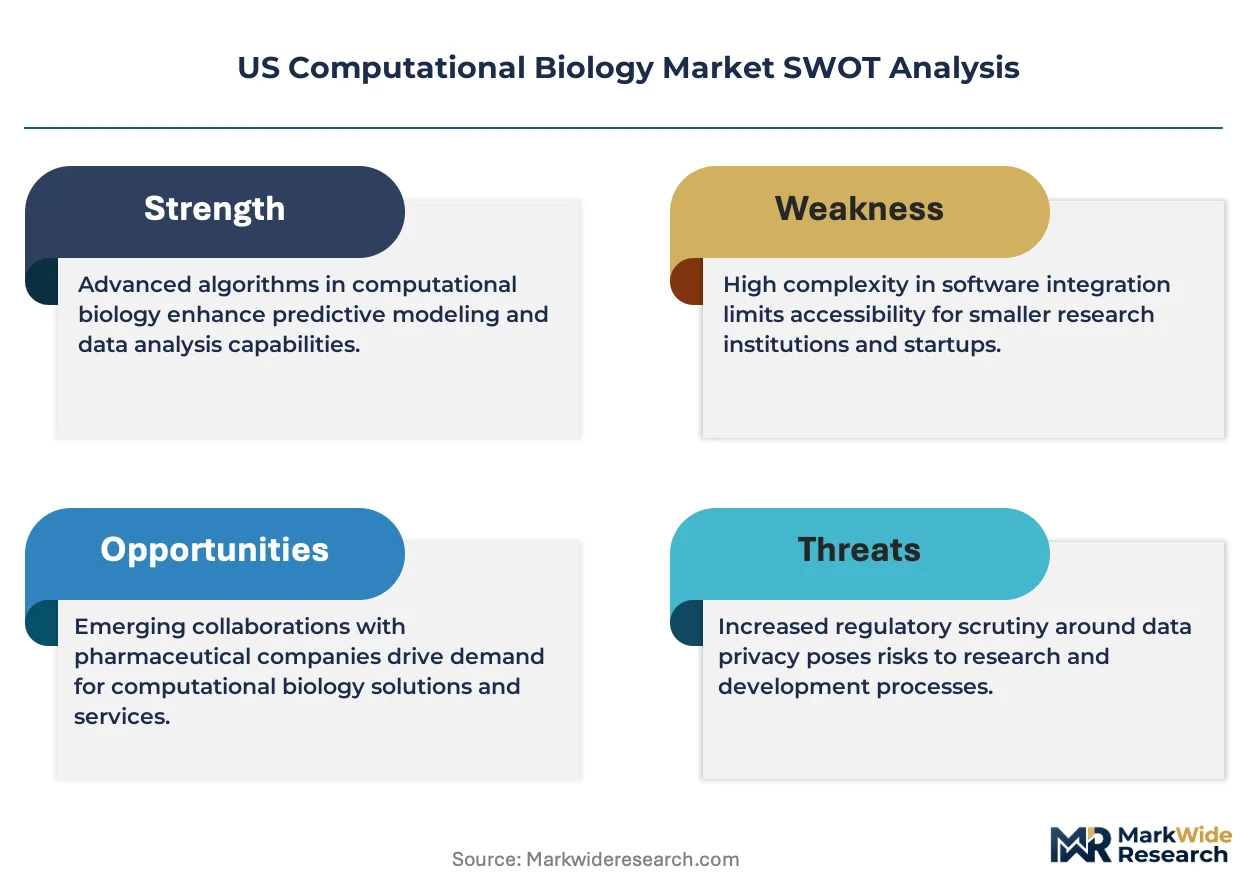
Pharmaceutical sponsors are replacing wet-lab screening with in silico prediction, compressing discovery timelines and reallocating R&D budgets toward algorithmic platforms. This substitution pattern concentrates purchasing power among sponsors with validated AI/ML submission pathways.
Growth Catalysts
- FDA AI/ML Guidance:The agency's evolving framework for adaptive algorithms creates regulatory clarity that accelerates vendor investment in validation infrastructure for diagnostic and therapeutic applications.
- Genomic Data Proliferation:Sequencing cost curves and population-scale biobanks generate petabyte-scale datasets requiring specialized analysis platforms, pulling cloud infrastructure spend toward compliant environments.
- Massachusetts Biotech Density:The Boston-Cambridge corridor sustains concentrated demand for molecular simulation talent, creating localized infrastructure investment loops that attract platform vendors.
Market Restraints
- Specialized Talent Scarcity:The intersection of computational science and biological domain expertise creates hiring bottlenecks that inflate personnel costs and extend implementation timelines.
- HIPAA Compliance Burden:Patient-derived genomic data handling requirements impose architectural constraints on cloud deployments, limiting vendor flexibility and increasing security overhead.
- Validation Cost Intensity:Algorithmic outputs for regulatory submission require extensive prospective validation against clinical outcomes, creating capital barriers for novel platform entrants.
Strategic Opportunities
- Texas Emerging Hub:Houston's Texas Medical Center and Austin's tech migration create underpenetrated demand for computational biology infrastructure outside traditional coastal clusters.
- Real-World Evidence Integration:The 21st Century Cures Act provisions for expanded evidence standards enable platforms that combine trial data with electronic health records to differentiate on predictive accuracy.
- Federated Learning Architectures:Privacy-preserving computation across institutional boundaries addresses HIPAA constraints while enabling multi-site training on restricted patient cohorts.
Industry Challenges
- Interoperability Friction:NIH data sharing policies mandate specific formats and metadata standards that force vendors to maintain multiple pipeline configurations, increasing integration complexity.
- GPU Supply Concentration:Dependence on NVIDIA hardware for neural network training creates procurement vulnerability and cost volatility for platform operators scaling model development.
- Legacy System Integration:Pharmaceutical IT environments built around traditional bioinformatics stacks resist migration to cloud-native architectures, extending sales cycles and implementation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Computational Biology Market |
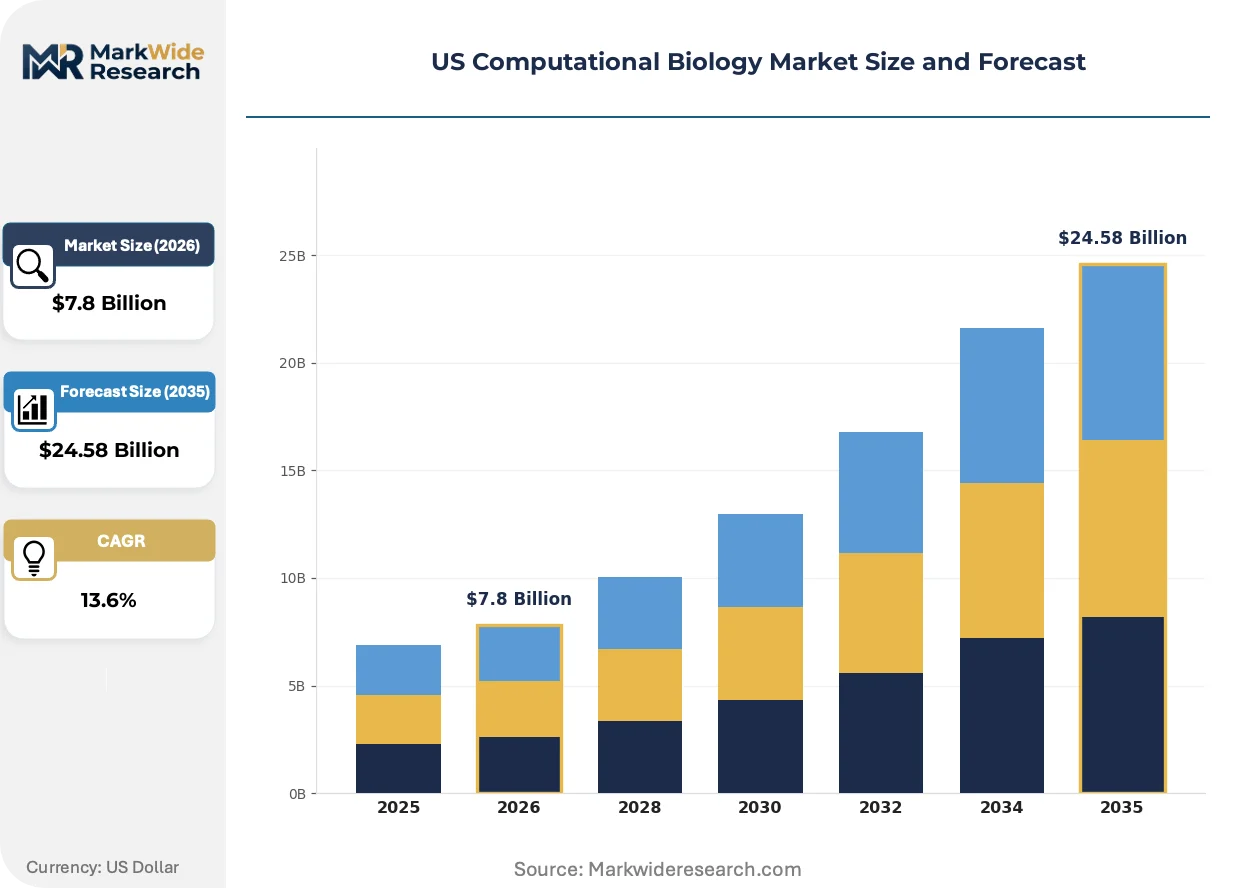
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $24.58 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Genomics, Proteomics, Drug Discovery, Disease Modeling Technology: Machine Learning, Data Mining, Cloud Computing, Bioinformatics Tools End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Hospitals Solution: Software Solutions, Data Analysis Services, Consultation, Outsourcing |
| Companies Covered | Thermo Fisher Scientific, Illumina, QIAGEN, DNAnexus, Schrodinger, Genedata AG, Compugen, Simulations Plus, Fios Genomics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Computational Biology Market Trends and Innovations
Foundation models trained on protein structures and chemical properties are compressing the frontier between sequence prediction and functional validation. This capability shift redefines competitive differentiation around data moats rather than algorithmic novelty.
Transformer architectures applied to protein folding prediction are collapsing the traditional separation between sequence analysis and structural biology. Mid-tier biotech sponsors now access capabilities previously requiring dedicated crystallography teams, forcing incumbent platform vendors to bundle simulation with downstream validation services.
FDA draft guidance on predetermined change control plans for AI/ML-enabled devices is tightening validation requirements for adaptive algorithms. Sponsors must demonstrate locked modification protocols before market entry, shifting vendor development resources toward regulatory documentation and away from feature expansion.
Biopharma procurement teams are unbundling computational platform contracts from hardware and professional services, treating simulation software as a discrete spend category with distinct vendor evaluation criteria. This pattern concentrates purchasing leverage among sponsors with standardized technical requirements, most visible in California's Bay Area where platform-native buyers negotiate direct SaaS terms.
US Computational Biology Market Segmentation
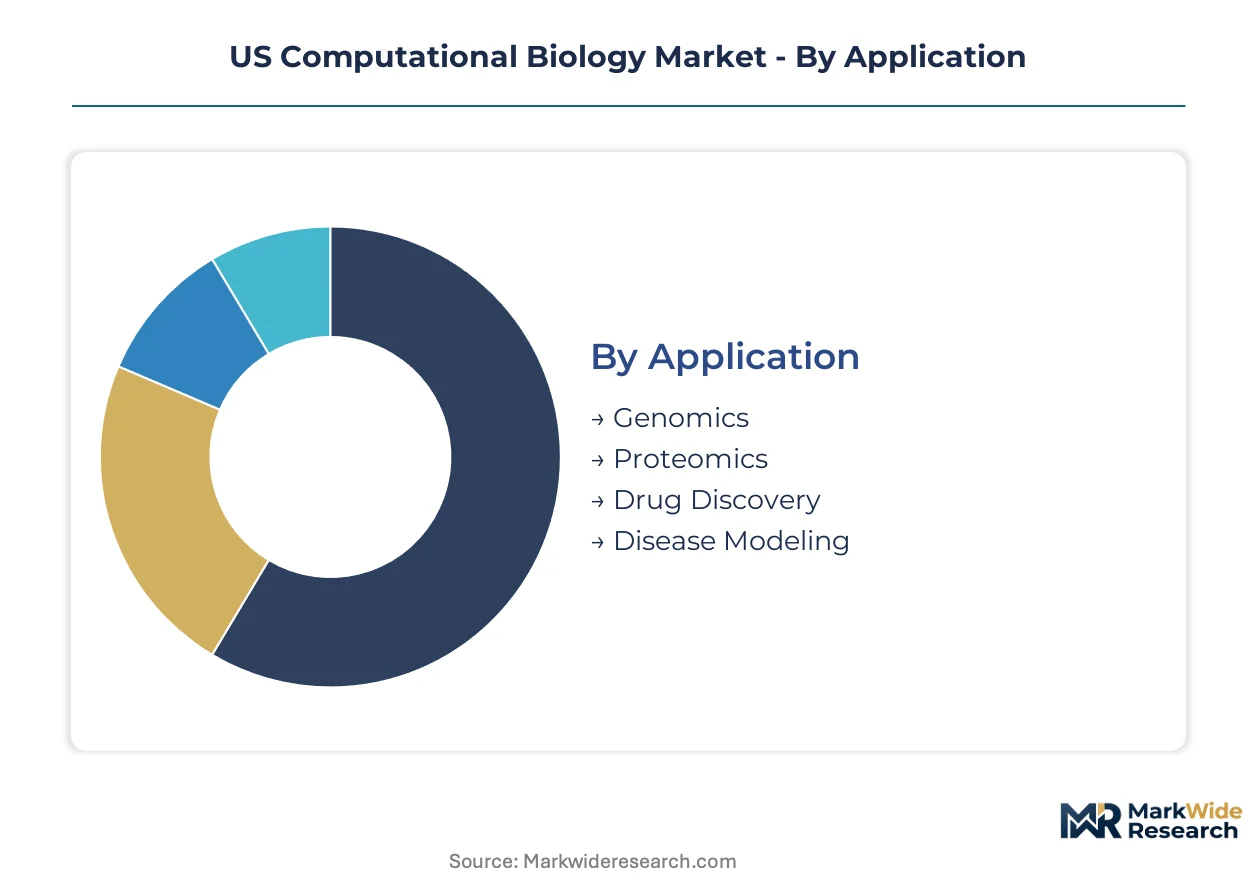
Computational biology vendors structure product portfolios around distinct workflow stages and customer capabilities. Segmentation reveals where platform economics concentrate and which buyer categories drive contract value expansion.
Application:
Mature therapeutic areas coexist with emerging disease modeling capabilities as pharmaceutical sponsors rebalance R&D allocation.
- Drug Discovery:In silico screening and molecular simulation replace wet-lab protocols across target identification and lead optimization phases. Massachusetts and California biotech clusters sustain concentrated demand for binding affinity prediction tools as sponsors compress discovery timelines.
- Genomics:Sequence analysis pipelines process population-scale datasets through variant calling and functional annotation workflows. Cloud infrastructure spend concentrates here as NIH data sharing policies mandate interoperable formats for genomic data repositories.
- Proteomics:Mass spectrometry data interpretation and protein interaction mapping support biomarker development.
- Disease Modeling:Patient-derived genomic data builds predictive models for therapeutic response stratification.
Drug Discovery retains volume leadership; Disease Modeling holds the steepest expansion curve.
Technology:
Cost tiers separate enterprise-grade neural architectures from accessible bioinformatics toolkits serving mid-tier research budgets.
- Machine Learning:Transformer architectures and foundation models trained on protein structures predict functional outcomes from sequence data. FDA guidance on predetermined change control plans shapes validation investment for adaptive algorithms in diagnostic applications.
- Cloud Computing:Elastic infrastructure supports intermittent workloads such as genome-wide association studies with compliant HIPAA environments. GPU supply concentration with NVIDIA creates procurement vulnerability for platform operators scaling model development.
- Bioinformatics Tools:Open-source and commercial software stacks for sequence alignment and phylogenetic analysis.
- Data Mining:Pattern extraction across multi-omics datasets for hypothesis generation and target prioritization.
Cloud Computing dominates current infrastructure spend; Machine Learning claims the fastest value capture rate.
End User:
Customer type determines contract structure, with procurement sophistication varying across regulated pharmaceutical sponsors and academic research institutions.
- Pharmaceutical Companies:Enterprise platforms integrate with existing LIMS and ELN infrastructure through validated AI/ML submission pathways. Bay Area sponsors unbundle software contracts from hardware and professional services, negotiating direct SaaS terms with platform vendors.
- Biotech Firms:Asset-light cloud subscriptions narrow capital barriers for molecular simulation access previously requiring dedicated infrastructure. Texas emerging hubs in Houston and Austin create underpenetrated demand outside traditional coastal clusters.
- Research Institutions:NIH-funded academic centers drive open-source tool adoption and data sharing compliance.
- Hospitals:Clinical deployment of AI/ML-enabled diagnostic algorithms requires FDA-cleared validation protocols.
Pharmaceutical Companies anchor enterprise contract value; Biotech Firms expand most quickly as cloud adoption accelerates.
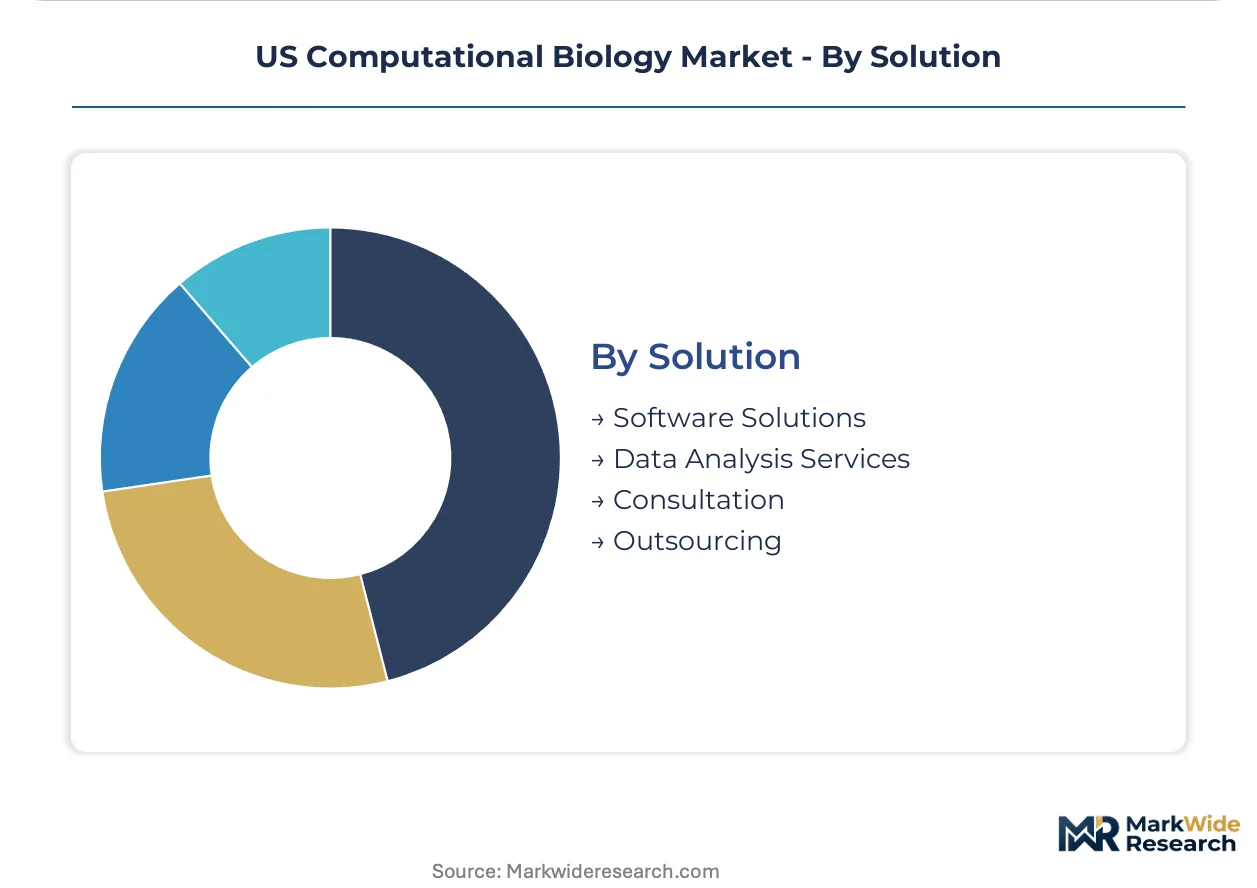
Solution:
Margin structure separates high-touch professional services from scalable software delivery models.
- Software Solutions:Platform licenses and SaaS subscriptions for molecular simulation and sequence analysis workflows. Subscription models concentrate recurring revenue as biopharma procurement teams treat simulation software as a discrete spend category.
- Data Analysis Services:Managed bioinformatics pipelines and custom analytical workflows for sponsors lacking internal computational expertise. HIPAA compliance burdens increase security overhead for patient-derived genomic data handling.
- Consultation:Strategic advisory on experimental design and regulatory submission strategies for AI/ML-enabled devices.
- Outsourcing:Full-service computational biology partnerships transferring target identification and validation risk to platform vendors.
Software Solutions capture the largest revenue pool; Data Analysis Services climb the fastest as talent scarcity drives outsourcing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Massachusetts and California where biotech density sustains premium infrastructure spend, while Texas and emerging interior hubs negotiate from positions of supply abundance and lower operational costs.
Massachusetts
The Boston-Cambridge corridor anchors enterprise demand for molecular simulation platforms as pharmaceutical sponsors compress discovery timelines through in silico workflows. NIH data sharing policies mandate interoperable formats for genomic repositories housed at Broad Institute and Harvard Medical School facilities. Kendall Square and Seaport District clusters attract platform vendors establishing localized sales and support infrastructure.
California
Bay Area sponsors unbundle software contracts from hardware and professional services, negotiating direct SaaS terms that concentrate purchasing leverage among platform-native buyers. FDA guidance on predetermined change control plans for AI/ML-enabled devices shapes validation investment timelines for South San Francisco and Menlo Park biotech sponsors. San Diego's Torrey Pines and La Jolla clusters sustain specialized demand for proteomics and structural biology applications.
Texas
Houston's Texas Medical Center and Austin's tech migration create underpenetrated demand for computational biology infrastructure outside traditional coastal clusters. HIPAA compliance burdens for patient-derived genomic data handling impose architectural constraints on cloud deployments serving MD Anderson and Baylor College of Medicine research programs. Dallas-Fort Worth's emerging life sciences corridor attracts talent migration from higher-cost markets.
Washington
The Pacific Northwest sustains concentrated demand for cloud-native bioinformatics platforms serving Fred Hutchinson Cancer Center and University of Washington research programs. State-level privacy regulations supplement federal HIPAA requirements for genomic data handling across multi-institutional collaborations. Seattle's South Lake Union cluster concentrates platform vendor development centers proximate to Amazon Web Services and Microsoft Azure infrastructure teams.
North Carolina
Research Triangle Park anchors mid-Atlantic demand for computational biology infrastructure serving GlaxoSmithKline, Biogen, and emerging gene therapy sponsors. State economic development incentives for life sciences capital investment attract platform vendors establishing regional support operations. Durham and Chapel Hill academic medical centers drive open-source tool adoption and NIH-funded data sharing compliance.
US Computational Biology Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying algorithmic modules and data infrastructure. The vendor base stratifies across three tiers: diversified laboratory instrumentation conglomerates bundling computational workflows with hardware contracts; pure-play simulation software vendors differentiating through proprietary physics-based algorithms; and cloud-native bioinformatics platforms scaling elastic infrastructure for intermittent genomic workloads. Competitive moves concentrate on strategic partnerships with pharmaceutical sponsors seeking validated AI/ML submission pathways, and portfolio expansion into adjacent disease modeling capabilities.
Within the instrumentation-anchored tier, Thermo Fisher Scientific exemplifies the bundled-service archetype, leveraging installed laboratory equipment relationships to cross-sell computational workflows. Illumina occupies a position as the genomic data generation anchor, creating downstream demand for analysis platforms processing sequencing outputs. Schrodinger represents the specialized simulation archetype, differentiating through physics-based molecular modeling capabilities that predict binding affinity with high precision.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| QIAGEN |
| DNAnexus |
| Schrodinger |
| Genedata AG |
| Compugen |
| Simulations Plus |
| Fios Genomics |
| Others |
Pricing and Supply Chain Analysis
NVIDIA GPU supply concentration determines both pricing tier spreads and supply chain shape for computational biology platform vendors, compressing margins for mid-tier entrants while enabling premium capture by cloud hyperscalers with captive infrastructure access.
Pricing Analysis
Pharmaceutical sponsors anchor three-tier pricing structure across premium, standard, and economy levels in computational biology platform procurement. Price differentiation rests on validation depth for FDA submission pathways and integration complexity with existing LIMS infrastructure. Cost compression in the standard tier is intensifying because biotech firms unbundle software from professional services, negotiating direct SaaS terms. Academic research institutions exhibit highest price sensitivity; enterprise pharmaceutical sponsors with validated AI/ML submission pathways show lowest.
Supply Chain Analysis
Tariff exposure between the US and China dominates supply chain risk planning for computational hardware procurement in this sector. GPU manufacturing concentrates in Taiwan, South Korea, and the United States, while cloud infrastructure draws from domestic hyperscaler facilities and international data center networks. Raw material dependencies span advanced semiconductor lithography equipment, high-bandwidth memory modules, and specialized cooling systems. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and channel partners serving mid-tier biotech firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US computational biology sector rewards platforms that control scarce cross-disciplinary talent pools combining deep learning expertise with molecular biology domain knowledge. Organizations that secure this capability compound advantage faster than capital alone permits.
For Market Incumbents: Build data moats through exclusive biobank partnerships and longitudinal patient cohort access. Incumbents should deepen backward integration into genomic data generation infrastructure to lock out pure-play software entrants. FDA predetermined change control plan requirements create regulatory chokepoints where validated submission pathways become defensible assets. Channel control through embedded integration with Thermo Fisher and Illumina hardware ecosystems reinforces switching costs. For New Entrants and Emerging Players: Establish a beachhead in Texas emerging hubs where Houston's Texas Medical Center and Austin's tech migration create underpenetrated demand outside coastal talent markets. Federated learning architectures represent the most penetrable technology segment, addressing HIPAA constraints while enabling multi-site training on restricted patient cohorts. A direct SaaS go-to-market angle targeting mid-tier biotech firms with asset-light cloud subscriptions bypasses incumbent enterprise sales complexity. For Investors and Strategic Acquirers: FDA draft guidance on adaptive algorithm validation reshapes the acquisition landscape by elevating regulatory documentation capabilities above raw technical performance. Long-term viability over the coming decade hinges on platforms that combine proprietary physics-based simulation with machine learning augmentation rather than either alone. Acquisition targets should display vertical integration into data generation or downstream validation services. The signal to watch is biopharma procurement team unbundling patterns, which indicate when platform-native buyers gain sufficient leverage to reshape vendor economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan Submission | Locks adaptive algorithm validation protocols before market entry, creating regulatory defensibility. |
| Biobank Data Partnership | Secures exclusive longitudinal patient cohort access that compounds model accuracy advantages. |
| Federated Learning Architecture Deployment | Enables multi-site training across MD Anderson and Baylor while preserving HIPAA compliance boundaries. |
| Hardware Ecosystem Integration | Embeds computational workflows within Thermo Fisher and Illumina installed bases to increase switching costs. |
| Real-World Evidence Platform Launch | Combines trial data with electronic health records to differentiate on predictive accuracy per 21st Century Cures Act provisions. |
Research Methodology
The analysis maps molecular simulation platforms, genomic analysis pipelines, and disease modeling capabilities, each validated through drug development executives, regulatory affairs leads, computational biology directors, and hospital procurement managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, NIH data sharing policy documents, ClinicalTrials.gov records, and hyperscaler capex disclosures. Bottom-up contract value analysis triangulates against top-down market sizing across application, technology, end user, and solution dimensions.
Assumptions held fixed include current FDA guidance trajectories for AI/ML-enabled devices, HIPAA enforcement patterns for genomic data handling, and NVIDIA GPU supply availability. Variables modeled across the analysis window encompass cloud adoption rates among mid-tier biotech firms, unbundling velocity in pharmaceutical procurement, and federated learning technology maturation. Segmentation dimensions span drug discovery versus disease modeling applications, machine learning versus bioinformatics technology tiers, and pharmaceutical versus academic end user categories. CAGRs derive from regression against historical contract value expansion and forward-looking pipeline density indicators.
Sensitivities concentrate around FDA guidance revisions on adaptive algorithms, NIH data sharing policy enforcement shifts, and GPU supply disruption scenarios. Forecasts reflect these documented assumptions with acknowledged uncertainty bands. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
Bioinformatics Market
Bioinformatics
China Computational Biology Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
North America Computational Biology Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
Global Chemoinformatics Market