
 PCR and NGS Based Diagnostic Testing Market | 2026-2036
PCR and NGS Based Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
PCR and NGS Based Diagnostic Testing Market Analysis
Modular assay panel bundling is expanding buyer choice in the PCR and NGS Based Diagnostic Testing Market, allowing laboratories to configure disease-specific workflows without full platform replacement. Thermo Fisher Scientific leverages its integrated instrument-reagent ecosystem to anchor high-throughput clinical contracts. Illumina, Inc. competes through sequencing chemistry leadership in oncology applications. Qiagen Inc specializes in sample-to-insight automation that sustains margins in mid-volume hospital labs.
PCR and NGS Based Diagnostic Testing encompasses nucleic acid amplification and massively parallel sequencing technologies used to detect pathogenic mutations, quantify viral loads, and characterize tumor genomes with analytical sensitivity reaching single-digit variant allele frequencies. These platforms serve precision medicine by matching patients to targeted therapies and monitoring minimal residual disease. Digital PCR segments command premium positioning in liquid biopsy validation where absolute quantification matters, while infectious disease applications represent the highest throughput volume pool. Oncology testing generates the fastest expansion in interpretation services as variant classification complexity deepens.
The FDA, CMS, and CAP shape market access through clinical laboratory improvement amendments, sequencing-based test reimbursement determinations, and proficiency testing mandates that dictate laboratory operational costs. The EU In Vitro Diagnostic Regulation and FDA's growing LDT enforcement posture are forcing manufacturers to bridge research-use-only and clinical-grade product lines. Stakeholders must monitor how payer coverage policies for whole-genome sequencing reshape the economic boundary between PCR reflex testing and upfront NGS panels.
Market Dynamics
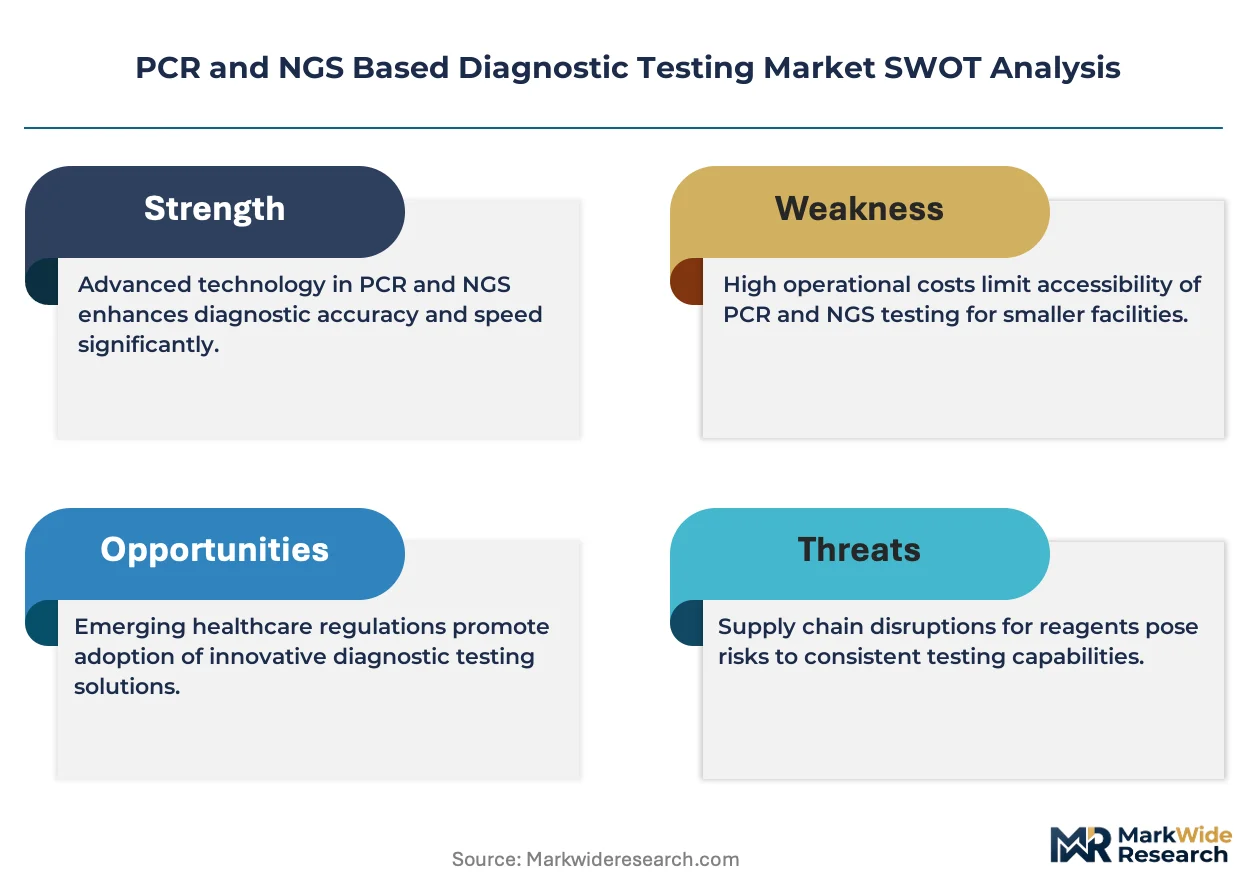
The FDA's escalating enforcement against laboratory-developed tests is forcing molecular diagnostic laboratories to either seek full IVD clearance or pivot toward research-use-only workflows, compressing operational flexibility and raising compliance costs across the clinical NGS value chain.
Growth Catalysts
- Reimbursement expansion for tumor profiling:CMS coverage determinations for comprehensive genomic profiling in solid tumors are accelerating adoption of NGS-based oncology panels at community hospital laboratories.
- Sample-to-answer automation:Integrated PCR platforms with walk-away workflows are reducing hands-on time requirements, enabling mid-volume hospital labs to bring infectious disease testing in-house.
- Minimal residual disease monitoring protocols:Clinical guidelines from oncology societies are embedding circulating tumor DNA testing into post-treatment surveillance, creating sustained demand for high-sensitivity digital PCR assays.
Market Restraints
- Reagent supply concentration:Taq polymerase and modified nucleotide supply chains cluster among a handful of specialized chemical manufacturers, exposing assay producers to input cost volatility.
- Bioinformatics bottleneck:Variant interpretation for rare mutations requires specialized computational infrastructure and curated knowledge bases that smaller clinical laboratories cannot sustain independently.
- IVD-CDx pathway friction:FDA's companion diagnostic co-development requirements are extending time-to-market for targeted therapy-aligned NGS panels, favoring large IVD manufacturers with regulatory affairs scale.
Strategic Opportunities
- Point-of-care molecular testing:CLIA-waived PCR platforms are penetrating urgent care and retail clinic settings where rapid infectious disease diagnosis commands premium reimbursement.
- Pharmacogenomic panel expansion:Payer coverage for preemptive genotyping in cardiovascular and psychiatric medication management is creating new addressable volume beyond oncology.
- Cloud-based variant interpretation:SaaS platforms with automated ACMG classification are enabling community laboratories to offer NGS-based testing without building in-house bioinformatics teams.
Industry Challenges
- Bioinformatics specialist scarcity:Clinical laboratories face acute hiring pressure for variant scientists capable of interpreting complex structural variants and splice-site alterations.
- Legacy LIS integration:Hospital information systems built for single-gene PCR workflows require expensive middleware development to accommodate NGS data volumes and HL7 FHIR reporting standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR and NGS Based Diagnostic Testing Market |
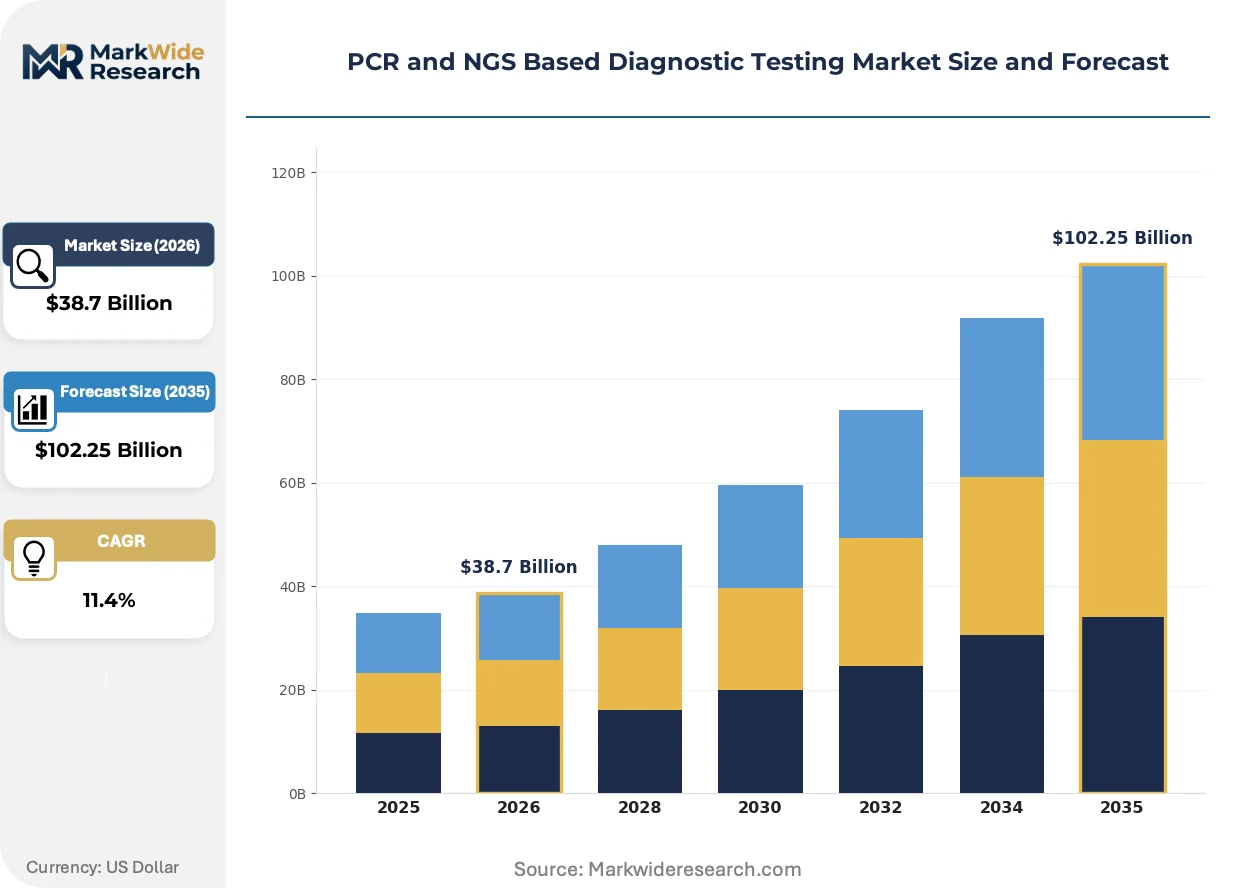
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: PCR, NGS, Multiplex PCR, Digital PCR Application: Infectious Diseases, Genetic Testing, Oncology, Pharmacogenomics End User: Hospitals, Laboratories, Research Institutes, Clinics Service Type: Testing Services, Interpretation Services, Quality Control, Consultative Services |
| Companies Covered | Thermo Fisher Scientific, Illumina, Inc., Qiagen Inc, Agilent Technologies, Inc., F. Hoffmann-La Roche Ltd., Bio-Rad Laboratories, Inc., Danaher Corporation, Abbott Laboratories, Hologic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR and NGS Based Diagnostic Testing Market Emerging Trajectories
CRISPR-based diagnostics and AI-augmented variant calling are compressing assay development cycles while reshaping where molecular testing occurs along the care continuum.
CRISPR-Cas12 and Cas13 detection systems are decentralizing infectious disease diagnostics from centralized reference laboratories toward near-patient settings. Urgent care networks and retail health clinics are piloting these platforms for respiratory panel and sexually transmitted infection screening. The technology is compressing turnaround times from days to under an hour, eroding the volume base that historically sustained hospital-based molecular microbiology laboratories.
The EU In Vitro Diagnostic Regulation's performance evaluation requirements are forcing manufacturers to generate clinical evidence for NGS-based assays that previously operated under self-certification. IVD companies are restructuring product development pipelines to prioritize Class C device submissions over research-use-only launches. Medium-sized European laboratories are responding by consolidating send-out testing into fewer accredited reference centers capable of supporting post-market surveillance obligations.
Integrated delivery networks are consolidating reference molecular testing into centralized genomics hubs, displacing the distributed hospital-lab model that dominated the 2010s. Health systems in the United States are negotiating exclusive long-term contracts with single-platform vendors, locking in reagent pricing and interpretation services. This concentration is most visible in oncology, where multi-hospital networks are standardizing on unified NGS panels to enable cross-facility clinical trial enrollment and therapeutic decision support.
PCR and NGS Based Diagnostic Testing Market Segmentation
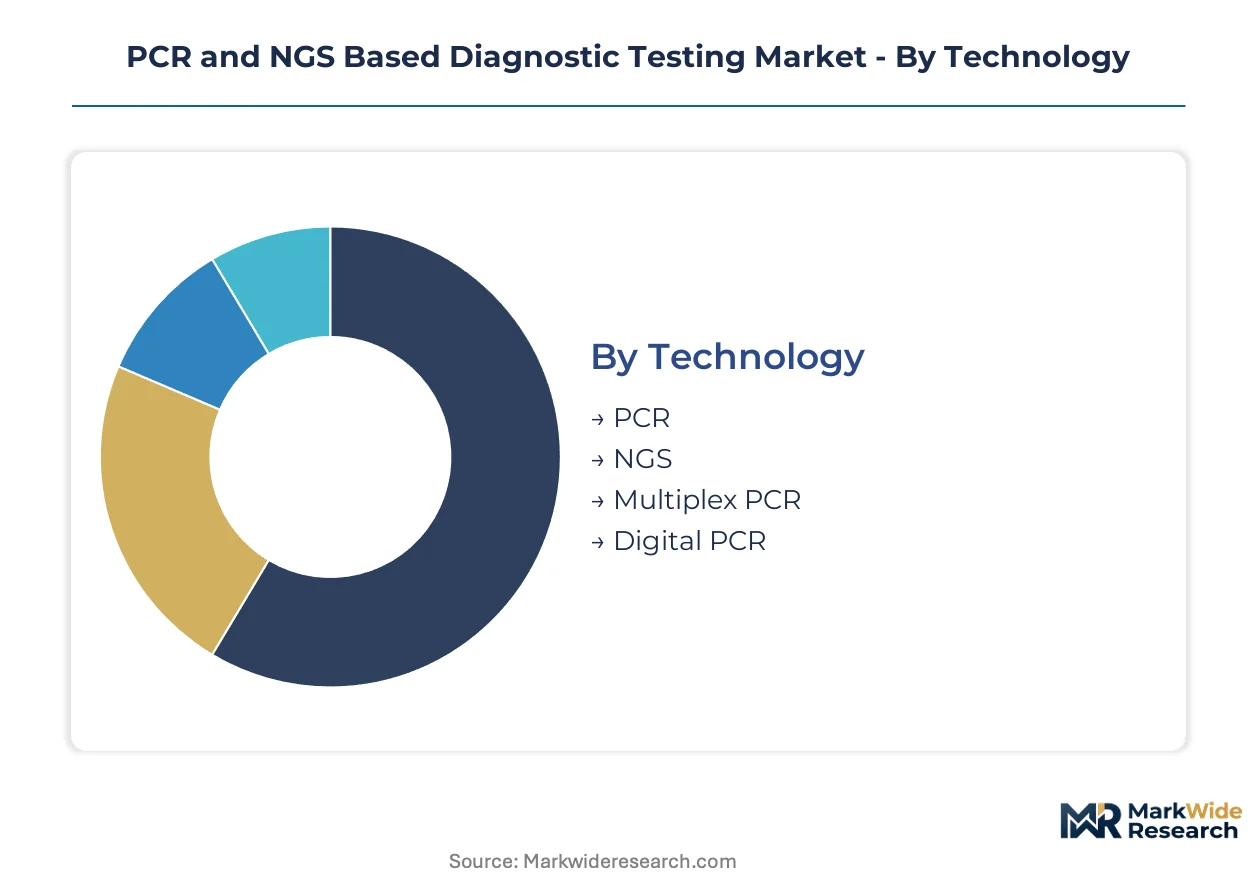
Laboratory procurement decisions in molecular diagnostics hinge on workflow integration, regulatory compliance burden, and per-sample economics. Segmentation reveals where platform investments concentrate versus where outsourced services retain viability.
Technology:
Capital deployment intensity separates buyers choosing between instrument acquisition and send-out testing models.
- PCR:Thermal cycling amplification dominates infectious disease screening with established CLIA-waived platforms. Hospital microbiology labs in the United States prioritize these systems for respiratory panel throughput.
- NGS:Massively parallel sequencing enables comprehensive genomic profiling with analytical sensitivity to single-digit variant allele frequencies. Academic medical centers anchor demand as tumor board protocols mandate broader molecular characterization.
- Multiplex PCR:Simultaneous pathogen detection in syndromic panels reduces reflex testing cascades.
- Digital PCR:Absolute quantification without standard curves supports liquid biopsy validation workflows.
PCR leads on scale; digital PCR leads on momentum.
Application:
Reimbursement velocity determines which disease areas attract platform investment versus remain reference-lab dependent.
- Infectious Diseases:Syndromic respiratory and gastrointestinal panels generate highest sample volumes with compressed turnaround requirements. Community hospitals bring these assays in-house as CLIA-waived instruments reduce technical staffing needs.
- Oncology:Solid tumor and hematologic malignancy profiling commands premium pricing with complex variant interpretation requirements. Comprehensive genomic profiling coverage determinations from CMS are accelerating NGS panel adoption at non-academic sites.
- Genetic Testing:Carrier screening and rare disease diagnosis utilize targeted NGS or exome sequencing.
- Pharmacogenomics:Preemptive genotyping for cardiovascular and psychiatric medication management is gaining payer coverage traction.
Infectious diseases leads on scale; oncology leads on momentum.
End User:
Operational complexity tolerance shapes whether testing centralizes or distributes across care settings.
- Hospitals:Integrated delivery networks consolidate molecular testing into genomics hubs with unified instrument platforms. Multi-hospital systems negotiate exclusive vendor contracts locking in reagent pricing and interpretation services.
- Laboratories:Reference laboratories process complex NGS workflows requiring specialized bioinformatics infrastructure. CAP proficiency testing mandates and FDA LDT enforcement are raising compliance costs that favor larger operators.
- Research Institutes:Translational research programs bridge discovery and clinical validation.
- Clinics:Urgent care and retail health settings pilot point-of-care molecular platforms.
Laboratories leads on scale; clinics leads on momentum.
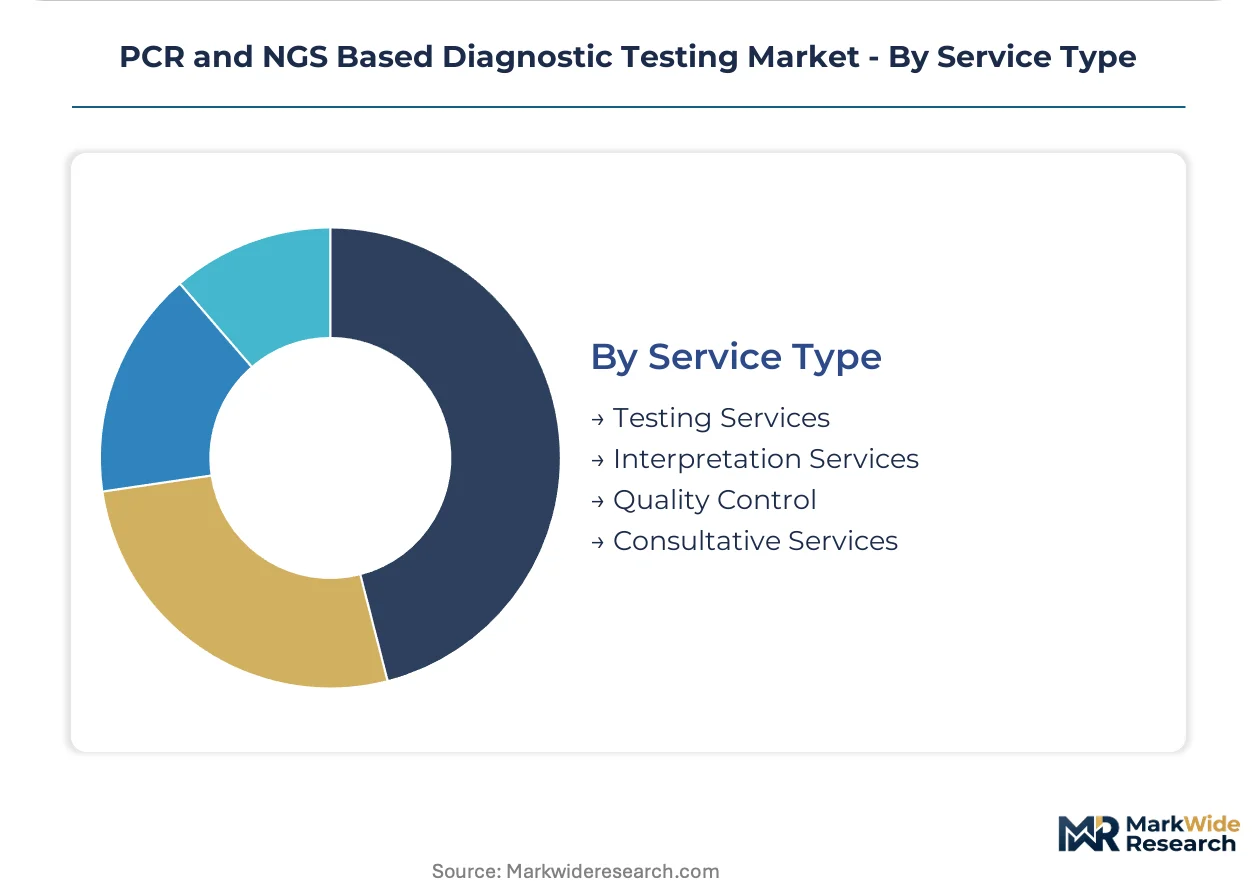
Service Type:
Value capture shifts from wet lab execution toward data interpretation as assay commoditization pressures margins.
- Testing Services:Nucleic acid extraction, amplification, and sequencing execution remains volume-dependent with reagent cost sensitivity. Automated sample-to-answer platforms are compressing the addressable market for manual processing services.
- Interpretation Services:Variant classification and clinical report generation require specialized expertise in ACMG guidelines. Cloud-based SaaS platforms are enabling community laboratories to offer NGS testing without in-house bioinformatics teams.
- Quality Control:Proficiency testing and validation support ensures regulatory compliance.
- Consultative Services:Molecular tumor board participation and therapeutic matching guidance adds clinical decision support value.
Testing services leads on scale; interpretation services leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molecular diagnostics originated in academic medical centers clustered around Boston and San Francisco before scaling through integrated health networks. The United States remains the primary demand center where reimbursement frameworks determine platform adoption velocity. Germany, China, Japan, and the United Kingdom now anchor regional expansion as regulatory pathways mature.
United States
Integrated delivery networks in Texas and California are consolidating reference molecular testing into centralized genomics hubs with exclusive vendor contracts. FDA enforcement against laboratory-developed tests is compressing operational flexibility for hospital-based laboratories. The Boston-Cambridge corridor anchors oncology panel development as academic medical centers expand comprehensive genomic profiling menus.
Germany
University hospitals in Munich and Heidelberg are driving adoption of NGS-based tumor profiling as the EU In Vitro Diagnostic Regulation raises compliance thresholds. The country's national pharmaceutical regulator is restructuring product development pipelines toward Class C device submissions. The Rhine-Main cluster around Frankfurt is consolidating mid-sized laboratories into accredited reference centers.
China
Top-tier hospitals in Beijing and Shanghai are deploying digital PCR platforms for liquid biopsy validation in post-treatment cancer surveillance. NMPA oversight of sequencing-based diagnostics is extending time-to-market for targeted therapy-aligned panels. The Yangtze River Delta biotech corridor is attracting contract research organizations supporting clinical evidence generation.
Japan
Metropolitan medical centers in Tokyo and Osaka are embedding pharmacogenomic testing into cardiovascular medication management protocols. PMDA guidance on companion diagnostic co-development is favoring large IVD manufacturers with regulatory affairs scale. The Kansai region is consolidating cancer genomic profiling into designated core hospitals.
United Kingdom
NHS genomic medicine service alliances in London and Manchester are standardizing NGS panels across multi-hospital networks. MHRA recognition of FDA-cleared devices is accelerating platform adoption timelines for community laboratories. The Cambridge-London corridor is concentrating bioinformatics interpretation services into specialized commercial providers.
PCR and NGS Based Diagnostic Testing Market Vendor Landscape
Premium-margin players sit above commodity-margin players across reagent-instrument bundling and interpretation service depth. The vendor base clusters around three structural positions: integrated life science conglomerates with full workflow control, sequencing chemistry specialists anchoring oncology applications, and sample-to-answer automation providers serving mid-volume hospital laboratories. Strategic moves concentrate on exclusive long-term contracting with health systems and cloud-based variant interpretation partnerships that extend reach without platform replacement.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify instrument-reagent ecosystem strategies that lock in reagent pricing through multi-year service agreements. Illumina, Inc. occupies a position as the sequencing chemistry anchor in oncology applications. Qiagen Inc represents the sample-to-insight automation archetype sustaining margins in mid-volume European and Asian hospital laboratories through walk-away workflow platforms.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina, Inc. |
| Qiagen Inc |
| Agilent Technologies, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Bio-Rad Laboratories, Inc. |
| Danaher Corporation |
| Abbott Laboratories |
| Hologic, Inc. |
| Others |
Supply Flow & Price Mechanics
Sample-to-answer automation platforms are compressing wet-lab service margins while concentrating purchasing power among integrated delivery networks that negotiate multi-year reagent bundles. This technology shift simultaneously lowers per-test cost floors for high-volume hospital laboratories and raises barriers for smaller reference labs unable to match contract scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates comprehensive genomic profiling services from targeted PCR panels and commodity infectious disease screening. Price differentiation hinges on FDA clearance tier and interpretation depth, with oncology NGS panels commanding substantial premiums over CLIA-waived respiratory assays. Cost compression in standard-tier PCR reagents is intensifying because Chinese manufacturers are expanding into mid-volume hospital contracts. Community hospital laboratories exhibit highest price sensitivity, while academic medical centers prioritize analytical performance over per-test economics.
Supply Chain Analysis
Single-source vulnerability sits with modified nucleotide chemistries manufactured primarily in Germany, Switzerland, and the United States. Taq polymerase production draws from specialized fermentation facilities in Denmark and the United States, with sequencing flowcell fabrication anchored in Singapore and California. Tariff exposure on Chinese-sourced plastic consumables threatens cost structures for syndromic panel producers. Distribution runs through regional distribution centers operated by major IVD conglomerates that lock in reagent pricing through exclusive health system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in molecular diagnostics rests on cloud-based variant interpretation SaaS models that transform fixed bioinformatics costs into scalable subscription revenue. Automation of sample-to-answer workflows further compresses unit economics for mid-volume laboratories.
For Market Incumbents: Anticipate FDA enforcement against laboratory-developed tests by accelerating IVD-CDx pathway submissions for oncology panels. Deepen backward integration into modified nucleotide chemistry to insulate margins from supplier concentration. Lock in exclusive multi-year contracts with consolidating integrated delivery networks before competing platforms gain trial access.
For New Entrants and Emerging Players: Urgent care networks represent the most penetrable channel partner type for CLIA-waived point-of-care molecular platforms. White-space opportunities concentrate in pharmacogenomic testing for cardiovascular medication management and retail clinic STI screening. Pursue white-label manufacturing partnerships with established IVD distributors to bypass direct hospital procurement barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized European reference laboratories struggling with EU In Vitro Diagnostic Regulation compliance costs. Long-term viability favors operators with cloud-native interpretation infrastructure and exclusive health system contracts. Watch for CMS coverage determinations on whole-genome sequencing as the inflection signal distinguishing premium-tier from commodity-positioned platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | IVD clearance anchors reimbursement eligibility for comprehensive genomic profiling panels in oncology. |
| Hospital System Partnership | Exclusive contracts with integrated delivery networks lock in multi-year reagent pricing and interpretation services. |
| Software Companion Development | Cloud-based ACMG classification platforms extend NGS testing reach to community laboratories lacking bioinformatics teams. |
| Reimbursement Strategy | CMS coverage determinations for tumor profiling accelerate adoption at non-academic hospital sites. |
| CE Marking Pathway | EU In Vitro Diagnostic Regulation compliance enables continued market access for European reference laboratories. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with laboratory directors, regulatory affairs specialists at IVD manufacturers, hospital procurement managers, and molecular pathologists with secondary validation against FDA 510(k) filings, CMS national coverage determinations, CAP proficiency testing records, and EU In Vitro Diagnostic Regulation guidance documents. Bottom-up instrument placement tracking and top-down reagent revenue estimates were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic baselines through recent reimbursement expansion phases anchored the forecast window across technology, application, end user, and service type dimensions. CAGRs were derived from segmented growth rate modeling incorporating NGS platform replacement cycles, CLIA-waiver expansion timelines, and payer coverage velocity for pharmacogenomic testing. Forecast inputs included laboratory capital expenditure surveys and health system consolidation patterns.
Revisions become necessary when FDA enforcement timelines, CMS coverage determinations, or supply chain disruptions for critical reagents materialize differently than modeled assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Global NGS Sample Preparation Market
Genomics
Mitochondrial DNA Market
Genomics
North America Genetic Testing Market
Genomics
Reproductive Genetics Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Glycan Sequencing Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Genome Sequencing Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Global Microarray Analysis Market
Genomics
Animal Genetics Market
Genomics
Whole Genome Amplification Market
Genomics
Mrna Sequencing Market
Genomics
North America Whole Exome Sequencing Market