
 Synthetic Stem Cells Market | 2026-2036
Synthetic Stem Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Stem Cells Market Analysis
CRISPR-engineered synthetic stem cell platforms are reshaping how therapeutic developers manufacture and scale cell-based interventions. Athersys, Inc. leverages proprietary MultiStem technology to anchor its position in off-the-shelf regenerative therapies. Pluristem Therapeutics Inc. specializes in placenta-derived mesenchymal-like cell products for ischemic and inflammatory indications. Sangamo Therapeutics controls zinc finger nuclease editing capabilities that differentiate its synthetic cell pipeline from conventional approaches.
Synthetic stem cells comprise laboratory-engineered, non-biological or biologically derived cellular mimics designed to replicate the therapeutic functions of natural stem cells without the sourcing constraints of donor tissue. These constructs typically incorporate biomaterial scaffolds, synthetic mRNA payloads, or engineered exosomes to direct differentiation toward target lineages for tissue repair, disease modeling, or drug screening applications. Mesenchymal synthetic stem cells occupy the dominant revenue position due to their established immunomodulatory profile and broader manufacturing scalability. Hematopoietic variants represent the fastest-expanding category, driven by CAR-T and gene therapy developers seeking standardized, off-the-shelf starting materials. CRISPR and 3D bioprinting technologies command premium positioning as end users prioritize precision editing and spatially organized tissue architectures.
FDA cell therapy guidance and EMA Advanced Therapy Medicinal Products frameworks shape product standards and market access pathways for synthetic stem cell developers. ISO 10993 biocompatibility testing and WHO cell-based medicinal product guidelines further constrain manufacturing protocols and quality systems. Stakeholders must monitor how evolving preclinical evidence requirements and reimbursement determinations for regenerative therapies will reshape competitive timelines and capital allocation priorities.
Market Dynamics
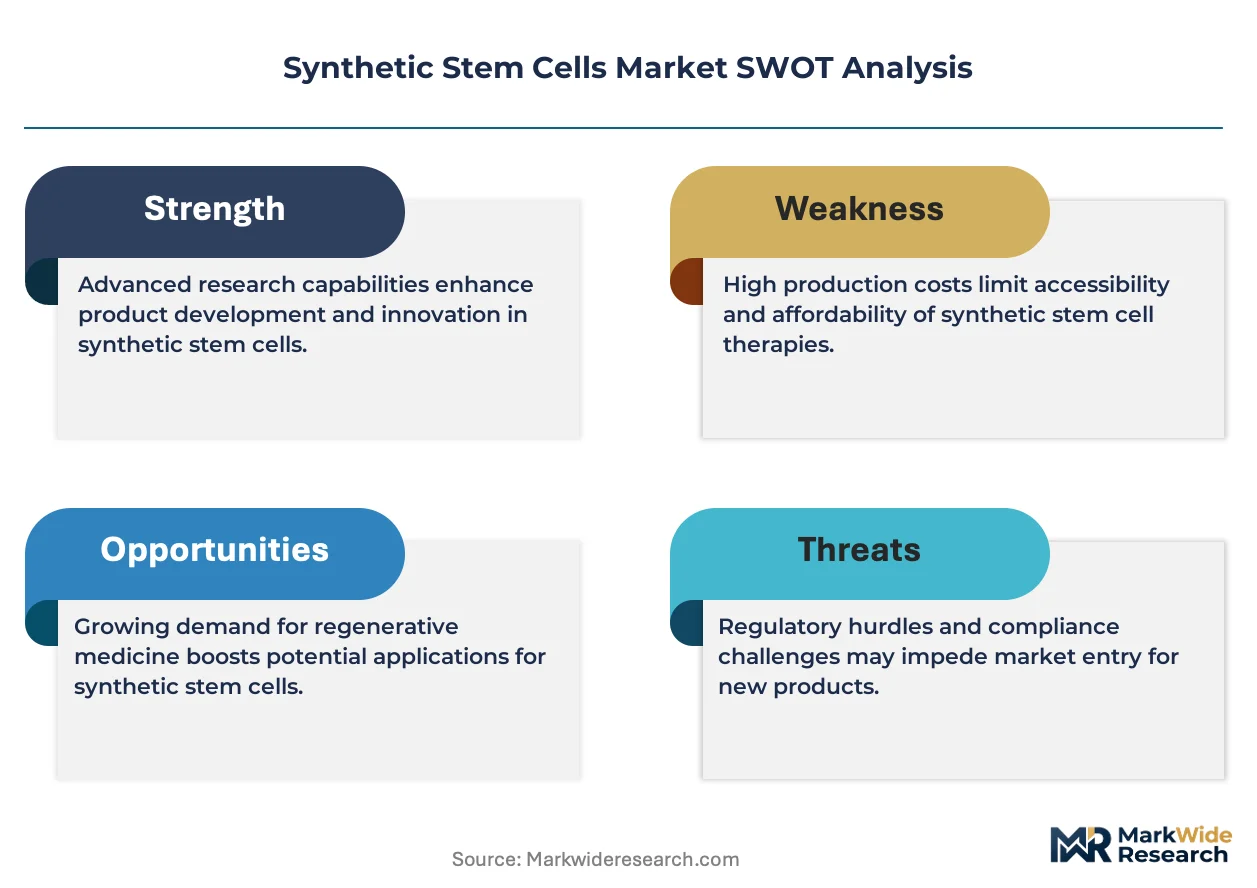
CRISPR-engineered synthetic stem cell platforms are compressing development timelines while FDA fast-track designations accelerate commercialization pathways, creating a structural velocity mismatch between manufacturing scale-up and regulatory clearance capacity.
Growth Catalysts
- FDA Expedited Programs:Regenerative Medicine Advanced Therapy and Breakthrough Therapy designations compress clinical trial phases for synthetic stem cell developers targeting ischemic conditions.
- Off-the-Shelf Manufacturing:Allogeneic synthetic stem cell platforms eliminate patient-matching logistics, enabling centralized production at GMP facilities in Massachusetts and North Carolina.
- Bioprinting Convergence:3D bioprinting integration with synthetic stem cell seeding creates vascularized tissue constructs for organ-on-chip applications in pharmaceutical toxicology screening.
Market Restraints
- Plasmid DNA Supply Concentration:Limited GMP-grade plasmid manufacturers in California and Germany create bottleneck risks for CRISPR payload production.
- ISO 10993 Testing Burden:Extended biocompatibility validation timelines for novel biomaterial scaffolds delay IND submissions by 8-14 months.
- Autologous Cell Therapy Competition:Patient-derived iPSC platforms retain reimbursement advantages in oncology settings, constraining synthetic stem cell penetration.
Strategic Opportunities
- Japan PMDA Sakigake Pathway:Priority review designation for synthetic stem cell therapies targeting aging-related macular degeneration opens accelerated market access.
- Exosome Engineering:Synthetic exosome payloads for neurological indications represent white space with minimal competitive saturation.
- Direct-to-Clinic Distribution:Hospital-based cell therapy centers in Texas and Florida enable bypass of traditional specialty pharmacy networks.
Industry Challenges
- Cold Chain Integrity:Cryopreserved synthetic stem cell products require liquid nitrogen logistics that exceed capabilities of standard biologics distributors.
- Cellular Potency Assay Standardization:Lack of harmonized release criteria across FDA and EMA jurisdictions forces duplicate validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Stem Cells Market |
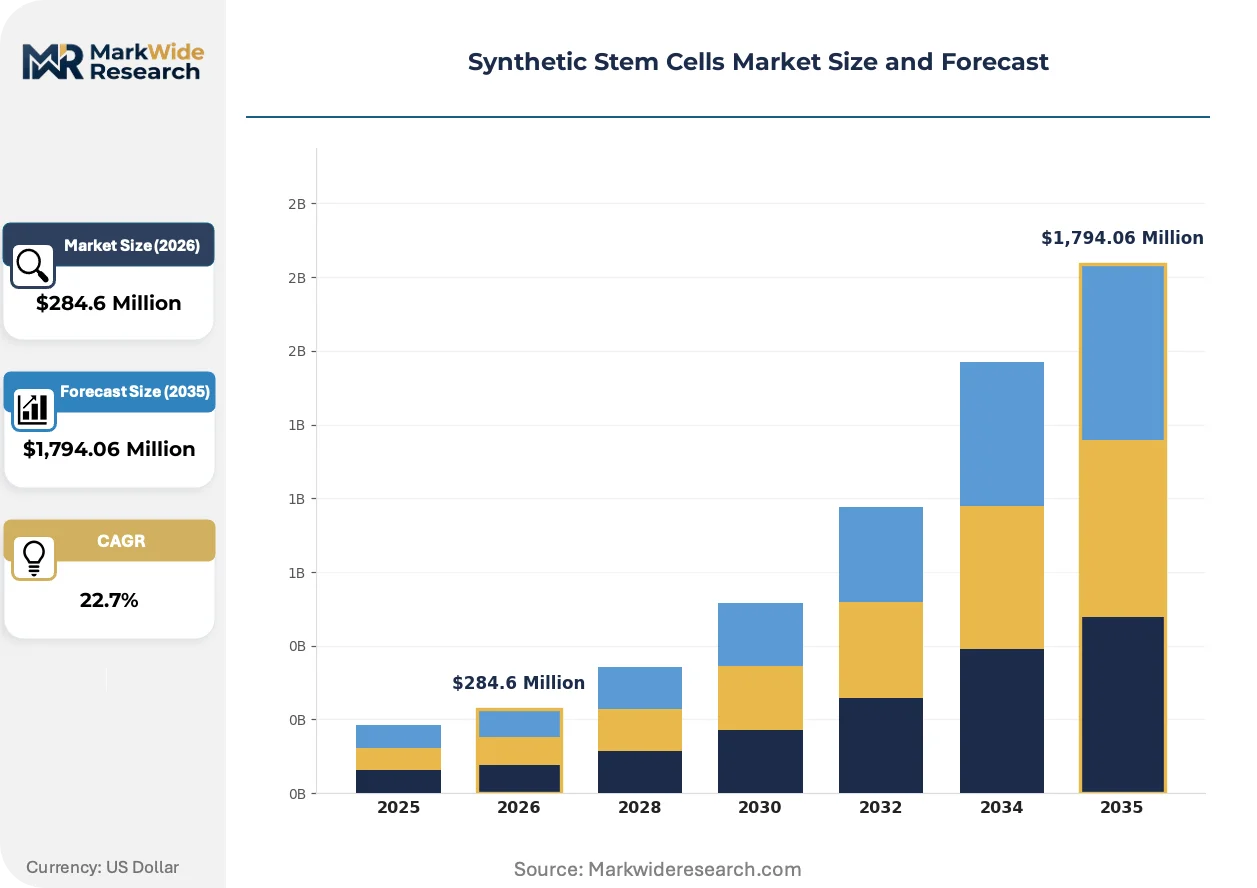
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $1,794.06 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesenchymal, Hematopoietic, Neural, Endothelial Application: Regenerative Medicine, Drug Discovery, Clinical Trials, Cell Therapy Technology: 3D Bioprinting, Microfluidics, Nanotechnology, CRISPR End User: Academics, Pharmaceuticals, Biotech Firms, Research Institutions |
| Companies Covered | Athersys, Inc., BrainStorm Cell Limited, Pluristem Therapeutics Inc., ThermoGenesis Corp., Vericel Corporation, Sangamo Therapeutics, Cellular Biomedicine Group, Gamida Cell, Caladrius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Stem Cells Market Emerging Trajectories
Synthetic stem cell manufacturing is abandoning planar culture surfaces in favor of bioreactor-based expansion systems that enable continuous processing and real-time quality monitoring.
Synthetic mRNA reprogramming is migrating from transient transfection methods toward stable episomal systems that reduce cytotoxicity and improve differentiation fidelity. Contract development organizations in Switzerland and Singapore are adopting these platforms for client programs targeting cardiovascular regeneration. The shift is compressing process development timelines from 18 months to 9 months while reducing GMP facility occupancy rates.
EMA's Advanced Therapy Medicinal Products regulation revision tightens comparability requirements for manufacturing changes, forcing synthetic stem cell developers to lock process parameters earlier in development. The framework now mandates extended stability data for cryopreserved products. German and Dutch regulators are applying these standards most stringently, pushing developers toward single-use bioreactor technologies with validated closed-system architectures.
Academic medical centers are consolidating synthetic stem cell procurement through centralized biobanking arrangements that aggregate demand across multiple principal investigators. The University of California system and Mayo Clinic network have established preferred supplier agreements that displace individual laboratory sourcing. This concentration is visible most acutely in hematopoietic synthetic stem cell categories where CAR-T developers seek batch-to-batch consistency guarantees.
Synthetic Stem Cells Market Segmentation
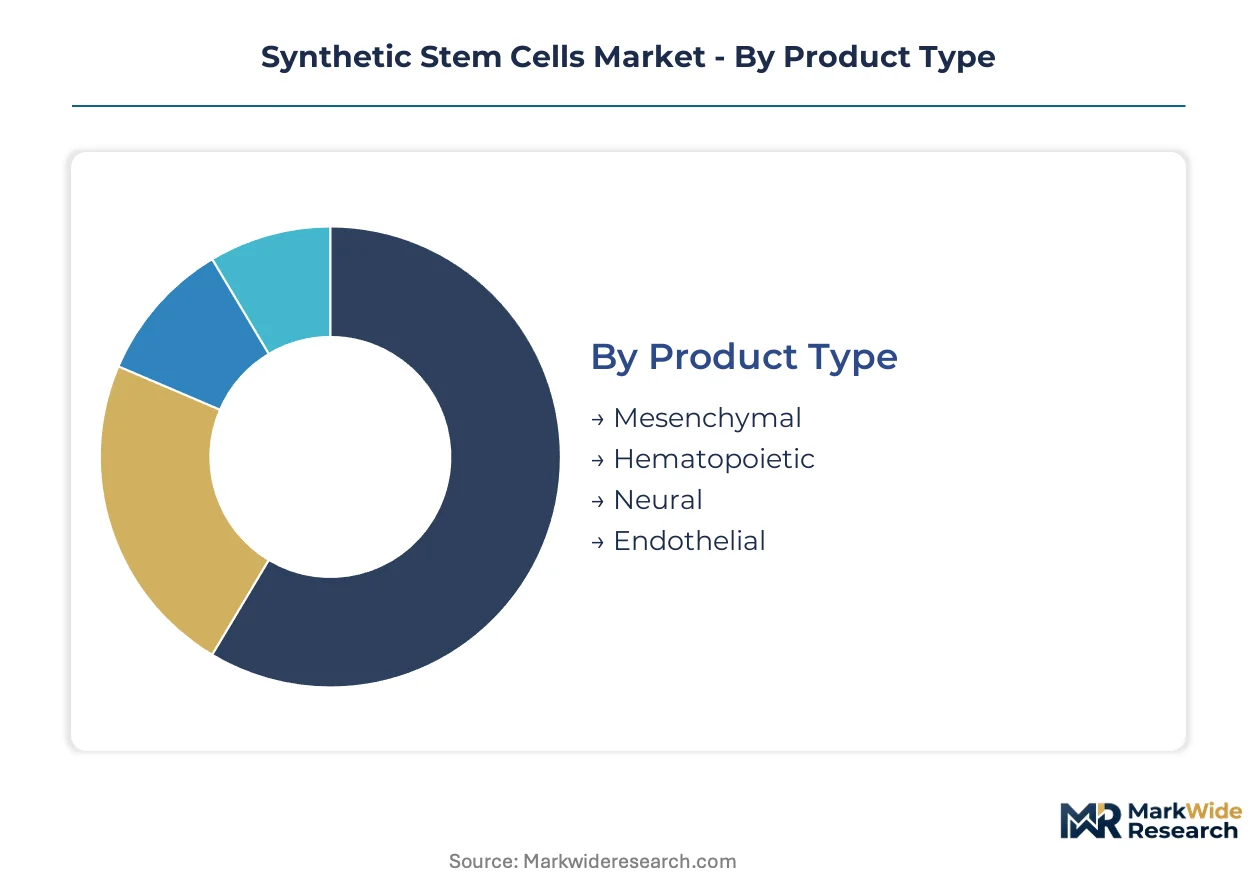
Synthetic stem cell procurement patterns diverge sharply across product categories, with regenerative medicine developers prioritizing immunomodulatory profiles while drug discovery teams demand standardized potency assays. Technology selection and end-user sophistication create distinct service intensity requirements that reshape vendor engagement models.
Product Type:
After-sales service intensity varies dramatically across synthetic stem cell categories, with cryopreservation support and batch consistency guarantees driving contract renewal rates for high-value therapeutic applications.
- Mesenchymal:Engineered from biomaterial scaffolds or placenta-derived mimics, these cells replicate immunomodulatory and tissue repair functions of natural mesenchymal stem cells. Demand concentrates in United States regenerative medicine pipelines where FDA fast-track designations prioritize off-the-shelf manufacturing scalability.
- Hematopoietic:Synthetic constructs mimicking blood-forming stem cell capabilities, typically incorporating CAR-T compatible surface markers. CAR-T developers in Massachusetts and North Carolina drive procurement as these platforms eliminate donor-matching logistics for standardized starting materials.
- Neural:Laboratory-engineered cell mimics designed for neurological regeneration applications.
- Endothelial:Vascular-targeted synthetic constructs for angiogenesis and tissue perfusion indications.
By volume, Mesenchymal leads. By growth pace, Hematopoietic is ahead.
Application:
Cost tier stratification separates premium therapeutic applications from screening-focused deployments, with regenerative medicine commanding five- to ten-fold pricing multiples over toxicology screening contracts.
- Regenerative Medicine:Clinical-grade synthetic stem cells for tissue repair, organ regeneration, and disease modification. Japanese PMDA Sakigake pathway accelerates demand for aging-related macular degeneration therapies.
- Drug Discovery:Standardized synthetic stem cell platforms for pharmaceutical toxicology and efficacy screening. Contract development organizations in Switzerland adopt these for cardiovascular regeneration client programs.
- Clinical Trials:GMP-compliant synthetic stem cell batches for investigational new drug studies.
- Cell Therapy:Finished therapeutic products incorporating synthetic stem cell active ingredients.
Regenerative Medicine captures the highest absolute spending. Drug Discovery shows the steepest expansion trajectory as toxicology screening volumes climb.
Technology:
Customer type sophistication determines technology adoption sequencing, with pharmaceutical manufacturers leading CRISPR integration while academic laboratories favor accessible microfluidic platforms.
- 3D Bioprinting:Additive manufacturing systems depositing synthetic stem cells within spatially organized biomaterial architectures. German and Dutch regulators mandate single-use bioreactor compatibility for vascularized tissue constructs under revised EMA ATMP frameworks.
- CRISPR:Precision genome editing protocols for synthetic stem cell engineering. United States developers leverage FDA regenerative medicine advanced therapy designations to compress development timelines.
- Microfluidics:Chip-based platforms for high-throughput synthetic stem cell processing and analysis.
- Nanotechnology:Engineered nanoparticle delivery systems for synthetic stem cell payload modulation.
3D Bioprinting dominates current installed base. CRISPR is gaining share fastest as editing fidelity improves.
End User:
Supply concentration shapes procurement behavior, with biotech firms consolidating through preferred supplier agreements while research institutions maintain fragmented laboratory-level sourcing.
- Pharmaceuticals:Large-scale synthetic stem cell procurement for therapeutic pipeline development. Mayo Clinic network and University of California system have established centralized biobanking arrangements that aggregate demand across multiple principal investigators.
- Biotech Firms:Venture-backed developers prioritizing rapid platform validation and partnership-driven manufacturing scale-up.
- Academics:University-based researchers utilizing synthetic stem cells for fundamental biology and proof-of-concept studies.
- Research Institutions:Government and nonprofit laboratories focusing on disease modeling and mechanism elucidation.
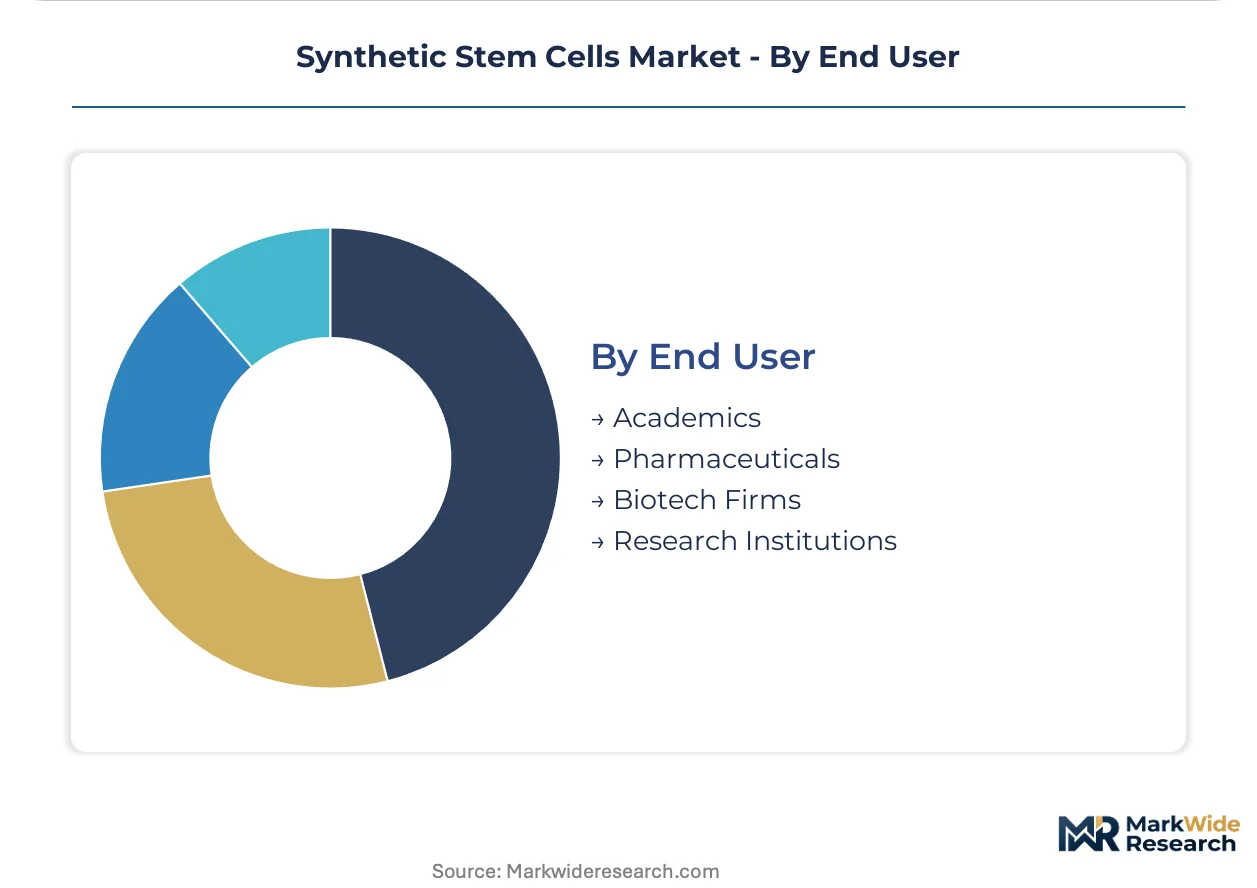
Pharmaceuticals account for the largest contract values. Biotech Firms are expanding most quickly as venture financing flows into cell therapy platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German synthetic stem cell developers export CRISPR-engineered platforms to Japanese pharmaceutical buyers through established biotech trade corridors. Swiss contract manufacturers supply GMP-grade plasmids to United States cell therapy developers in Massachusetts and North Carolina. Singapore-based bioreactor specialists serve Australian regenerative medicine researchers seeking standardized starting materials.
United States
FDA fast-track designations for ischemic condition therapies drive procurement from regenerative medicine developers. The Regenerative Medicine Advanced Therapy designation compresses clinical trial phases for synthetic stem cell platforms. GMP facilities in Massachusetts and North Carolina anchor centralized production for allogeneic off-the-shelf manufacturing.
Germany
EMA Advanced Therapy Medicinal Products framework revisions tighten comparability requirements for manufacturing changes. German regulators apply stringent stability data mandates for cryopreserved products most forcefully. Single-use bioreactor technologies with validated closed-system architectures concentrate in Baden-Württemberg and Bavaria manufacturing clusters.
Japan
PMDA Sakigake priority review designation accelerates market access for aging-related macular degeneration therapies. METI funding programs support synthetic exosome engineering for neurological applications. Tokyo and Osaka academic medical centers consolidate procurement through centralized biobanking arrangements across multiple principal investigators.
Switzerland
Swissmedic oversight of cell-based medicinal products attracts contract development organizations serving cardiovascular regeneration client programs. ISO 10993 biocompatibility testing capabilities cluster around Basel and Zurich. Synthetic mRNA reprogramming platforms migrate from transient transfection toward stable episomal systems in Swiss CMO facilities.
Singapore
Bioreactor-based expansion systems enable continuous processing for real-time quality monitoring in regional manufacturing. The country's national pharmaceutical regulator aligns with WHO cell-based medicinal product guidelines for export certification. Bioprinting convergence with synthetic stem cell seeding concentrates in research parks serving pharmaceutical toxicology screening demand from Australia and South Korea.
Synthetic Stem Cells Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Large pharmaceutical manufacturers leverage centralized biobanking arrangements to aggregate demand across multiple research institutions. Three archetypes dominate: CRISPR-editing platform developers, placenta-derived mesenchymal cell specialists, and zinc finger nuclease differentiation players. Competitive moves center on strategic partnerships for manufacturing scale-up and technology licensing for payload delivery systems.
Among United States-based developers, Athersys, Inc. and Sangamo Therapeutics occupy positions within the engineered platform tier. Pluristem Therapeutics Inc. represents the placenta-derived specialization archetype. These entities exemplify how proprietary editing capabilities and biomaterial scaffold technologies anchor competitive differentiation without reliance on donor tissue sourcing constraints.
| Leading Market Players |
|---|
| Athersys, Inc. |
| BrainStorm Cell Limited |
| Pluristem Therapeutics Inc. |
| ThermoGenesis Corp. |
| Vericel Corporation |
| Sangamo Therapeutics |
| Cellular Biomedicine Group |
| Gamida Cell |
| Caladrius |
| Others |
Supply Flow & Price Mechanics
Liquid nitrogen logistics corridors connecting Massachusetts GMP facilities to Texas hospital-based cell therapy centers impose freight premiums that compound supply concentration effects and widen price spreads between premium cryopreserved tiers and standard cold-chain products.
Pricing Analysis
CRISPR-engineered next-generation platforms command substantial premiums over planar culture prior-generation products, while emerging bioprinting-convergent offerings anchor the premium tier. Pricing stratifies across premium, standard, and economy tiers based on ISO 10993 certification completion status and after-sales cryopreservation support bundling. Cost compression in the standard tier intensifies as California and German plasmid manufacturers expand GMP-grade capacity. Academic laboratories exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize batch consistency guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from Massachusetts and North Carolina GMP facilities to Swiss contract manufacturers are reshaping working capital structures across the value chain. Supply concentrates in the United States, Germany, and Switzerland for CRISPR payload production and biocompatibility testing. Raw material dependencies center on GMP-grade plasmid DNA, biomaterial scaffolds, and synthetic mRNA reagents. Single-source vulnerability in California plasmid manufacturing creates structural risk. Distribution runs through centralized biobanking arrangements at academic medical centers rather than traditional specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through preferred supplier agreements at the University of California system and Mayo Clinic network, fragmenting procurement leverage away from individual laboratories toward consolidated institutional purchasing.
For Market Incumbents: Insulate manufacturing margins by deepening backward integration into plasmid DNA production and securing captive supply of GMP-grade biomaterial scaffolds. Lock in preferred supplier status with centralized biobanking arrangements before EMA comparability requirement revisions force process parameter commitments. Prioritize ISO 10993 certification investments to maintain pricing power against emerging microfluidic platform competitors. For New Entrants and Emerging Players: Synthetic exosome engineering for neurological indications represents the most penetrable entry point, with minimal competitive saturation and METI funding program eligibility in Japan. Japan's PMDA Sakigake pathway offers regulatory acceleration for aging-related macular degeneration therapies. Direct-to-clinic distribution partnerships with Texas and Florida hospital-based cell therapy centers provide go-to-market bypass of established specialty pharmacy networks. For Investors and Strategic Acquirers: FDA regenerative medicine advanced therapy designation milestones reshape the acquisition landscape by compressing clinical trial timelines and validating platform scalability. Five-to-ten-year viability hinges on manufacturing scale-up execution rather than discovery-stage asset accumulation. Target acquisition archetypes include CRISPR-editing platform developers with validated closed-system bioreactor architectures. Watch for EMA ATMP framework revision implementation as the signal indicating regulatory clarity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA fast-track designation compresses clinical trial phases for ischemic condition therapies. |
| Manufacturing Scale-Up | GMP facility expansion in Massachusetts and North Carolina anchors centralized allogeneic production. |
| Technology Licensing | CRISPR payload delivery system partnerships accelerate synthetic stem cell platform differentiation. |
| Clinical Trial Advancement | Japanese PMDA Sakigake priority review accelerates aging-related macular degeneration therapy access. |
| Pipeline Diversification | Synthetic exosome engineering for neurological indications opens white-space expansion opportunities. |
Methodological Framework
Operator-level perspectives from cell therapy manufacturing executives, regulatory affairs leads at synthetic stem cell developers, hospital procurement managers at academic medical centers, and payer access specialists anchored the qualitative base. Secondary validation drew from FDA filings, EMA Advanced Therapy Medicinal Products submissions, ClinicalTrials.gov records, and ISO 10993 biocompatibility testing databases. Bottom-up procurement volume estimates and top-down market sizing triangulated across these sources.
Scenario-bracketing around regulatory pathway acceleration and manufacturing scale-up constraints bounded the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application, technology platform, and end-user sophistication tier. CAGRs derived from trajectory analysis of procurement volumes and pricing tier evolution. Industry-specific forecast inputs incorporated plasmid DNA supply expansion timelines and EMA comparability requirement implementation schedules.
Practitioners should monitor FDA regenerative medicine advanced therapy designation grant rates and EMA ATMP framework revision enforcement intensity for early signals. Forecasts reflect assumptions around regulatory pathway stability and plasmid manufacturing capacity expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Biology
Mutation Generation Systems Market
Synthetic Biology
Transient Protein Expression Market
Synthetic Biology
Global Cell-Free Protein Expression Market
Synthetic Biology
Synthetic Genomics Market
Synthetic Biology
DNA Synthesizer Market
Synthetic Biology
Difficult-To-Express Proteins Market
Synthetic Biology
Synthetic Hormones Market
Synthetic Biology
Asia-Pacific Gene Synthesis Market
Synthetic Biology
Gene Synthesis (Research Use) Market