
 Global Bioinformatics Services Market | 2026-2036
Global Bioinformatics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioinformatics Services Market Foresight
The EU AI Act is restructuring compliance burdens for bioinformatics platforms processing genomic and clinical data, forcing service providers to invest in algorithmic auditability and data governance. Illumina, Inc. leverages its sequencing hardware dominance to anchor downstream analytics demand. QIAGEN competes through specialized bioinformatics software bundled with sample preparation workflows. Thermo Fisher Scientific Inc. extends its laboratory informatics footprint into cloud-based genomic data interpretation.
Bioinformatics services encompass computational analysis, management, and interpretation of biological data using software tools, statistical methods, and machine learning algorithms operating on nucleotide sequences, protein structures, and metabolic pathways with throughput metrics often exceeding terabytes per sequencing run. These services enable target identification, biomarker discovery, and patient stratification across pharmaceutical and agricultural value chains. Genome sequencing commands the largest revenue share among service types due to declining per-base costs and expanding clinical applications. Machine learning within the technology dimension attracts the fastest investment growth as vendors automate variant calling and pathway prediction. Drug discovery applications retain mature, high-margin contracts from pharmaceutical companies seeking to compress preclinical timelines.
The FDA governs bioinformatics tools supporting diagnostic and therapeutic decisions through software-as-medical-device pathways, while the EMA coordinates centralized assessments for genomic-based therapies across EU member states. China's NMPA accelerates review timelines for AI-assisted diagnostic algorithms, reshaping where vendors prioritize regulatory submissions. Stakeholders must monitor divergence between FDA, EMA, and NMPA evidentiary standards for computational biomarkers to avoid fragmented compliance architectures.
Market Dynamics
Machine learning pipelines are compressing variant-to-interpretation timelines from weeks to hours, forcing service providers to rebuild computational infrastructure around GPU clusters and federated learning architectures.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic auditability requirements for clinical decision-support tools are creating captive demand for validated bioinformatics workflows across European healthcare systems.
- Pharmaceutical target identification:Contract research organizations are embedding multi-omics analysis into early-stage discovery programs to reduce preclinical attrition rates.
- China NMPA accelerated pathways:Streamlined review timelines for AI-assisted diagnostic algorithms are pulling vendor investment toward regulatory submissions in Shanghai and Beijing clusters.
Market Restraints
- GPU compute cost volatility:Cloud-based genomic analysis faces margin pressure from NVIDIA hardware shortages and energy pricing spikes in hyperscale data centers.
- Sequencing hardware concentration:Illumina's installed base dominance in the United States and China creates vendor lock-in risk for downstream analytics providers.
- FDA software-as-medical-device evidentiary thresholds:Prolonged validation requirements for diagnostic algorithms delay commercialization timelines by 18-36 months.
Strategic Opportunities
- India CDSCO emerging framework:Draft guidelines for AI-based medical devices present first-mover positioning for cloud-native bioinformatics platforms.
- Agricultural genomics extension:CRISPR-edited crop trait validation is opening service contracts with seed companies and food security programs.
- Federated learning architectures:Privacy-preserving multi-institutional analysis is integrating with hospital IT systems without raw data migration.
Industry Challenges
- Computational biology talent scarcity:PhD-level bioinformaticians with both genomic domain expertise and production software engineering skills command premium compensation in Boston and San Francisco.
- Legacy LIMS integration friction:Pharmaceutical IT departments face 12-18 month deployment cycles connecting cloud analytics to on-premise sample tracking systems.
- Multi-jurisdiction data residency:GDPR, HIPAA, and China's PIPL create conflicting requirements for cross-border genomic dataset movement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioinformatics Services Market |
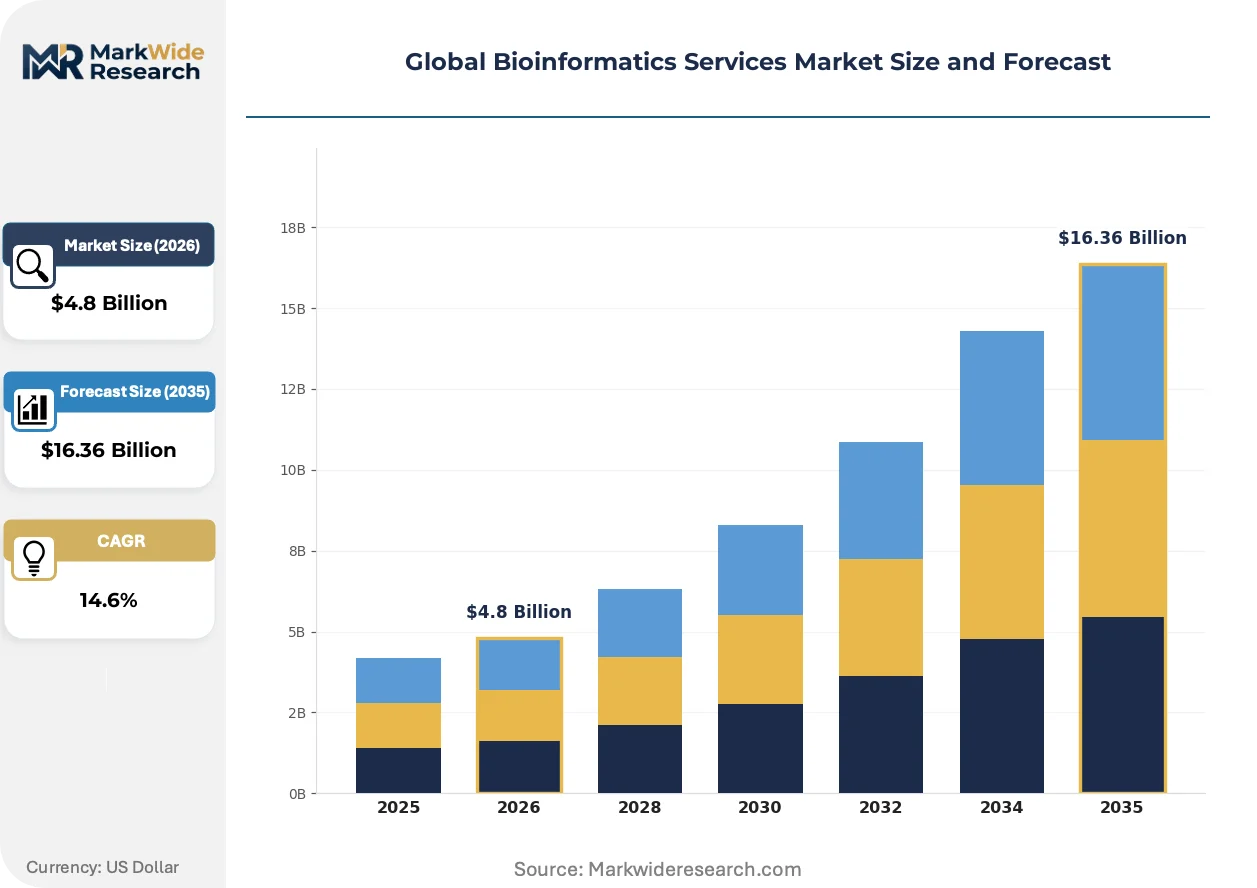
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analysis, Genome Sequencing, Software Development, Database Management, Consulting, Customization Technology: Next-Generation Sequencing, Cloud Computing, Machine Learning, Artificial Intelligence, High-Performance Computing, Blockchain Application: Drug Discovery, Precision Medicine, Agricultural Genomics, Proteomics, Metabolomics, Epidemiology End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Laboratories, Contract Research Organizations |
| Companies Covered | Illumina, Inc., QIAGEN, Thermo Fisher Scientific Inc., BGI Group, Agilent Technologies, Inc., DNAnexus Inc., CD Genomics Inc., Fios Genomics Ltd., PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioinformatics Services Market Shifts & Advancements
Foundation models trained on nucleotide sequences are displacing rule-based variant callers, compressing the expertise gap between specialized bioinformatics cores and generalist service providers.
Transformer architectures for protein structure prediction are integrating with cryo-EM data pipelines, enabling pharmaceutical companies to prioritize crystallography targets before wet-lab investment. Structural biology departments at contract research organizations are adopting these hybrid workflows within 6-12 month procurement cycles. The technology is integrating physics-based simulation with statistical learning, collapsing the iteration loop between in silico screening and experimental validation.
The EU AI Act's risk classification system for clinical decision-support algorithms is forcing vendors to rebuild quality management systems around post-market monitoring obligations. High-risk bioinformatics tools face mandatory conformity assessments through notified bodies before CE marking. European academic medical centers are restructuring procurement criteria to prioritize vendors with established EU AI Act technical documentation.
Pharmaceutical buyers are unbundling sequencing and analysis contracts, creating direct procurement relationships with specialized bioinformatics vendors independent of hardware providers. Large-cap biopharma companies are establishing preferred vendor panels for computational biology services, displacing the bundled model where sequencing vendors captured downstream analytics. This pattern is most visible in the United States, where Merck, Pfizer, and Bristol Myers Squibb have issued separate RFPs for variant interpretation and pathway analysis in 2024.
Global Bioinformatics Services Market Segmentation
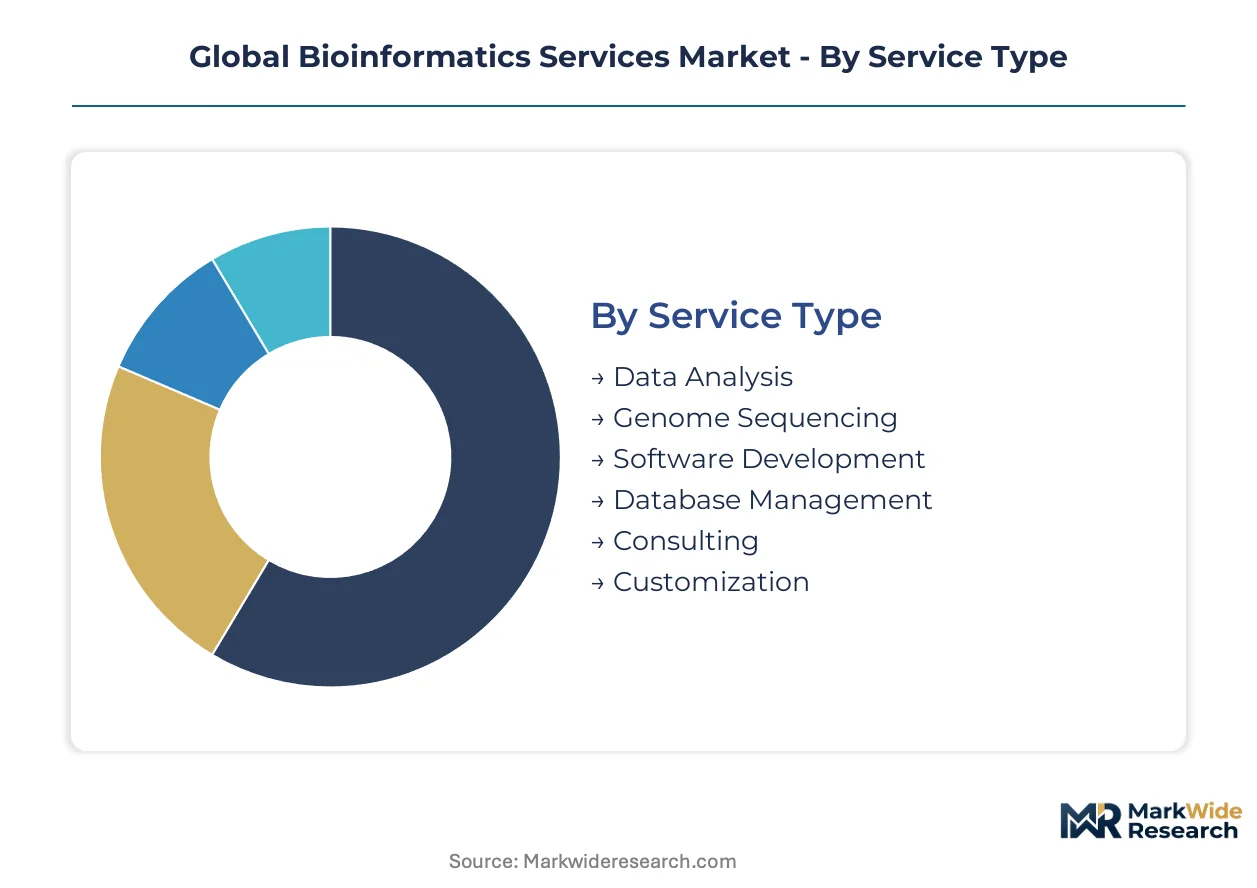
Bioinformatics services fragment across service delivery modes, underlying technologies, clinical applications, and buyer archetypes. Each dimension carries distinct margin profiles and regulatory exposure. Understanding these boundaries clarifies where vendors concentrate R&D investment versus where they pursue scale through standardization.
Service Type:
Standalone analytics contracts command premium pricing while embedded software subscriptions lock in recurring revenue across multi-year pharmaceutical partnerships.
- Data Analysis:Computational pipelines transform raw sequencing output into variant calls, expression profiles, and pathway enrichments using containerized workflows on cloud infrastructure. Pharmaceutical companies in the United States and Germany outsource these functions to compress timelines for IND-enabling studies.
- Genome Sequencing:End-to-end services span library preparation, instrument operation, and primary data generation with throughput metrics measured in terabytes per run. Academic medical centers in China and the United States drive demand for clinical-grade whole-genome and whole-exome protocols.
- Software Development:Custom algorithm builds for proprietary biomarker discovery platforms.
- Database Management:Curated repositories of genomic, proteomic, and phenotypic datasets with API access tiers.
- Consulting:Regulatory strategy and experimental design advisory for multi-omics study architectures.
- Customization:Workflow adaptation for legacy LIMS integration and institution-specific quality protocols.
Genome Sequencing leads volumes today; Data Analysis is gaining share fastest.
Technology:
Cost tiering separates capital-intensive hardware-dependent layers from software-only solutions with minimal marginal delivery costs.
- Next-Generation Sequencing:Short-read and emerging long-read platforms from Illumina, Pacific Biosciences, and Oxford Nanopore anchor upstream data generation. Sequencing hardware concentration in the United States and China creates vendor lock-in dynamics that downstream analytics providers must navigate through API abstraction layers.
- Machine Learning:Deep learning architectures for variant calling, protein structure prediction, and drug-target interaction modeling attract the steepest venture investment. FDA software-as-medical-device pathways and EU AI Act conformity assessments impose validation burdens that favor well-capitalized platform vendors.
- Cloud Computing:Scalable storage and compute orchestration for petabyte-scale genomic datasets.
- Artificial Intelligence:Rule-based and statistical methods preceding neural network adoption in legacy installations.
- High-Performance Computing:On-premise GPU and CPU clusters for institutions with data residency constraints.
- Blockchain:Distributed ledger pilots for genomic data provenance and consent management in European research networks.
Next-Generation Sequencing dominates installed base; Machine Learning is climbing the fastest.
Application:
Maturity gradients separate decades-old pharmaceutical workflows from emerging agricultural and public health use cases with divergent procurement cycles.
- Drug Discovery:Target identification, lead optimization, and biomarker qualification across preclinical phases. Contract research organizations in the United States and Germany embed multi-omics analysis to reduce attrition rates before candidate nomination.
- Precision Medicine:Patient stratification, companion diagnostic co-development, and pharmacogenomic interpretation. China's NMPA accelerated review pathways for AI-assisted diagnostics pull vendor investment toward regulatory submissions in Shanghai and Beijing clusters.
- Agricultural Genomics:CRISPR-edited crop trait validation and marker-assisted breeding programs.
- Proteomics:Mass spectrometry data interpretation for protein quantification and post-translational modification mapping.
- Metabolomics:Small-molecule profiling for biomarker discovery and metabolic pathway reconstruction.
- Epidemiology:Pathogen genomic surveillance and outbreak tracing for public health agencies.
Drug Discovery retains the largest contract values; Precision Medicine is expanding most quickly.
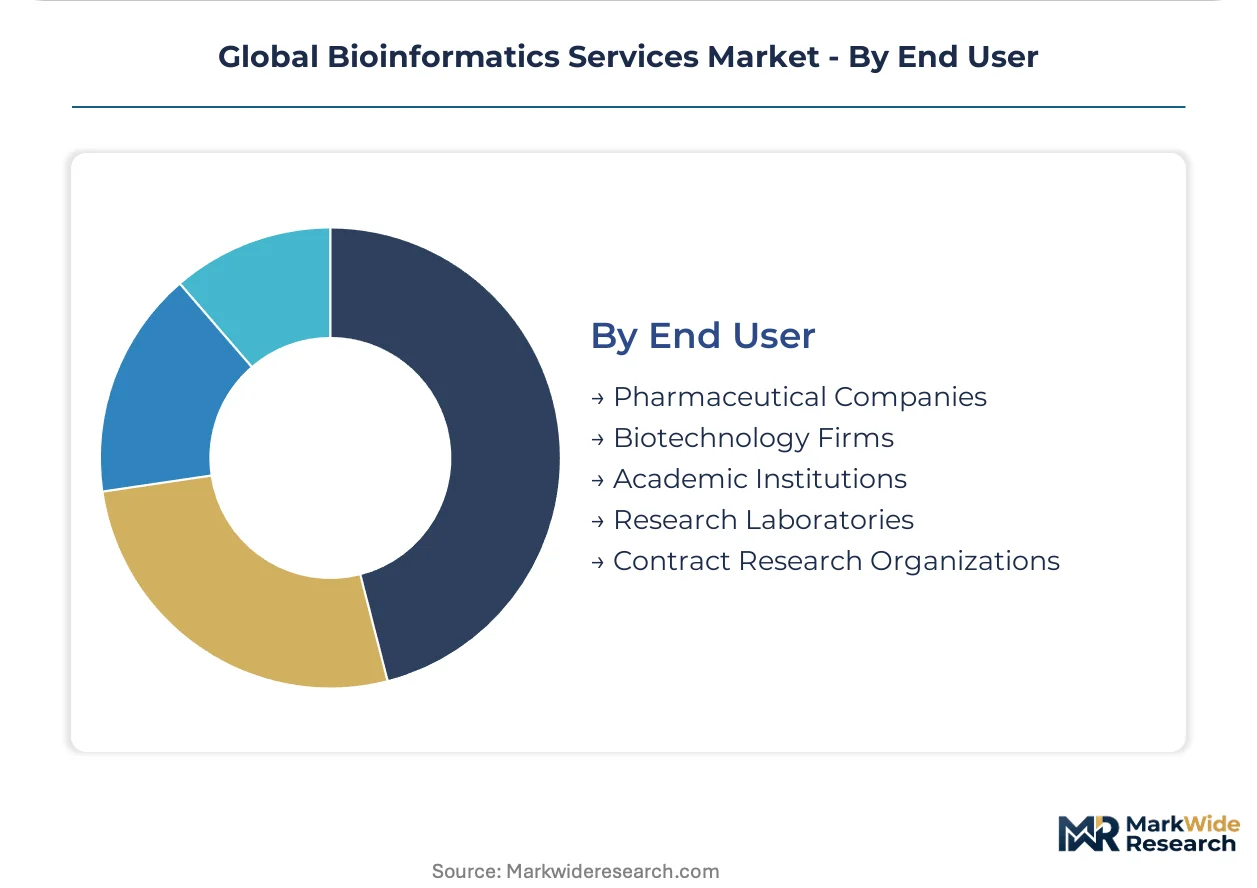
End User:
Customer type dictates pricing power, with large-cap pharmaceutical buyers unbundling services while academic institutions prioritize cost efficiency over turnaround speed.
- Pharmaceutical Companies:Merck, Pfizer, and Bristol Myers Squibb have issued separate RFPs for variant interpretation and pathway analysis, displacing bundled procurement models where sequencing vendors captured downstream analytics. These buyers demand validated workflows with FDA 21 CFR Part 11 compliance and audit trails.
- Academic Institutions:Research universities and medical schools with grant-funded projects and publication-driven incentives. European academic medical centers are restructuring procurement criteria to prioritize vendors with established EU AI Act technical documentation.
- Biotechnology Firms:Venture-backed startups with asset-specific computational needs and limited internal bioinformatics capacity.
- Research Laboratories:Government and nonprofit institutes with standardized analysis requirements and pooled purchasing agreements.
- Contract Research Organizations:Full-service providers integrating computational biology into broader discovery and development offerings.
Pharmaceutical Companies anchor revenue concentration; Biotechnology Firms are scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bioinformatics services industry traces its commercial origins to the Human Genome Project scaling in the United States during the late 1990s, with subsequent infrastructure buildout spreading to Germany and China as sequencing costs collapsed and pharmaceutical R&D outsourcing accelerated.
United States
FDA software-as-medical-device pathways and HIPAA compliance requirements shape vendor investment priorities for diagnostic algorithm validation. The 21 CFR Part 11 audit trail mandates force service providers to maintain extensive documentation for pharmaceutical clients. The Greater Boston and San Francisco Bay Area clusters concentrate both venture-backed bioinformatics startups and established sequencing hardware operations.
Germany
EMA centralized assessments for genomic-based therapies and the EU AI Act's high-risk algorithm classification create dual compliance burdens for clinical decision-support tools. Germany's national pharmaceutical regulator enforces stringent post-market surveillance obligations under the MDR framework. The Munich and Heidelberg life science corridors host major contract research organizations integrating multi-omics analysis into pharmaceutical pipelines.
China
NMPA accelerated review timelines for AI-assisted diagnostic algorithms pull vendor investment toward regulatory submissions in Shanghai and Beijing clusters. The country's dual carbon goals intersect with data center energy consumption limits for genomic cloud computing infrastructure. Shenzhen's hardware manufacturing ecosystem supports domestic sequencing instrument development competing with established platforms.
United Kingdom
The Medicines and Healthcare products Regulatory Agency coordinates with the EMA on genomic therapy assessments while maintaining independent software-as-medical-device pathways post-Brexit. NHS England's genomic medicine service creates institutional demand for validated bioinformatics workflows. The Cambridge-London corridor concentrates academic medical centers and biotech venture activity.
India
CDSCO draft guidelines for AI-based medical devices present first-mover positioning opportunities for cloud-native bioinformatics platforms. The country's PLI scheme for pharmaceuticals indirectly supports computational biology outsourcing from multinational drug developers. Hyderabad and Bangalore clusters emerge as delivery centers for genomic data analysis services.
Global Bioinformatics Services Market Competitive Landscape
The competitive structure tilts toward sequencing-hardware-anchored ecosystems competing against cloud-native software specialists. Tier-one players leverage installed base dominance to capture downstream analytics contracts, while mid-tier vendors differentiate through regulatory validation depth and therapeutic area specialization. Two strategic archetypes dominate: integrated hardware-software platforms and standalone computational service providers. Competitive moves concentrate on unbundling analytics from sequencing procurement and establishing preferred vendor panels with large-cap pharmaceutical buyers.
Among hardware-anchored providers, Illumina, Inc. and QIAGEN exemplify the integrated platform archetype, with geographic identifiers in their naming conventions suggesting United States and European origins respectively. Thermo Fisher Scientific Inc. occupies a position representing the diversified laboratory conglomerate model. These three entities anchor the competitive landscape as reference points for structure analysis, with their respective positions illustrating the tension between captive hardware ecosystems and open analytics architectures.
| Leading Market Players |
|---|
| Illumina, Inc. |
| QIAGEN |
| Thermo Fisher Scientific Inc. |
| BGI Group |
| Agilent Technologies, Inc. |
| DNAnexus Inc. |
| CD Genomics Inc. |
| Fios Genomics Ltd. |
| PerkinElmer Inc. |
| Others |
Supply & Pricing Matrix
NVIDIA GPU spot pricing volatility cascades through cloud-based genomic analysis tiers, compressing margins for mid-tier service providers while reinforcing premium positioning for vendors with captive compute infrastructure and long-term hyperscaler contracts.
Pricing Analysis
Subscription-based SaaS tiers with usage-scaled compute credits dominate pharmaceutical procurement, with price differentiation anchored in FDA 21 CFR Part 11 validation depth and EU AI Act technical documentation completeness. Cost compression in standard-tier variant interpretation services is intensifying because hyperscale cloud providers are passing through energy pricing spikes. Academic institutions exhibit highest price sensitivity; large-cap pharmaceutical buyers prioritize audit trail robustness over per-sample cost.
Supply Chain Analysis
PhD-level bioinformatician scarcity in Greater Boston and San Francisco Bay Area clusters constrains service expansion velocity for cloud-native platforms. Hardware dependencies center on Illumina sequencing instruments manufactured in San Diego, NVIDIA GPU accelerators sourced from Taiwan and South Korea, and cryo-EM equipment from the Netherlands. Single-source vulnerability in short-read sequencing platforms exposes downstream analytics providers to vendor lock-in risk. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and channel partnerships with academic core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bioinformatics services rests on GPU cost pass-through mechanisms and premium-tier regulatory validation bundling that commands 40-60% pricing premiums over standard analytical workflows.
For Market Incumbents: To counter unbundling pressure from pharmaceutical buyers separating sequencing and analytics procurement, anchor downstream demand through exclusive API integration with installed sequencing hardware and accelerate EU AI Act conformity assessment investments to capture European hospital procurement restructuring. For New Entrants and Emerging Players: Contract research organizations with limited internal bioinformatics capacity present the most penetrable white-space target, particularly in agricultural genomics extension where CRISPR-edited crop validation workflows remain undersupplied; pursue federated learning architecture partnerships with hospital IT departments as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platforms possessing established FDA software-as-medical-device validation pathways and EU AI Act technical documentation; long-term viability hinges on regulatory moat durability rather than pure computational scale; monitor NMPA approval velocity for AI-assisted diagnostic algorithms as the inflection signal for vendor geographic prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | CE marking for high-risk clinical decision-support algorithms unlocks European hospital procurement pipelines. |
| Federated Learning Architecture Deployment | Privacy-preserving multi-institutional analysis integrates with hospital IT systems without raw data migration. |
| Pharmaceutical Preferred Vendor Panel Inclusion | Separate RFPs from Merck, Pfizer, and Bristol Myers Squibb displace bundled sequencing-analytics contracts. |
| GPU Cluster Infrastructure Investment | Captive compute capacity insulates margin pressure from NVIDIA hardware shortages and energy pricing spikes. |
| Agricultural Genomics Service Extension | CRISPR-edited crop trait validation opens service contracts with seed companies and food security programs. |
Research Methodology
Multiple input streams — primary interviews with bioinformatics platform executives, pharmaceutical R&D procurement leads, and academic core facility directors; secondary validation through FDA 510(k) filings, EMA centralized assessment records, and NMPA AI-assisted diagnostic algorithm approvals; plus hyperscaler capex disclosures and sequencing hardware shipment data — were reconciled through bottom-up service line build-ups and top-down market sizing triangulation.
Data-stream reconciliation across service type, technology layer, application area, and end-user archetype dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated pharmaceutical preclinical outsourcing trends, EU AI Act implementation timelines, and NMPA regulatory pathway velocity for AI-assisted diagnostics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GPU cost volatility, sequencing hardware market structure shifts, and divergence between FDA, EMA, and NMPA evidentiary standards for computational biomarkers. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
Bioinformatics Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
China Computational Biology Market
Bioinformatics
North America Computational Biology Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
US Computational Biology Market