
 Europe AI in Life Science Analytics Market | 2026-2036
Europe AI in Life Science Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe AI in Life Science Analytics Market Analytics
Regulatory-grade algorithm validation is rotating the Europe AI in Life Science Analytics market toward higher-assurance deployment tiers. IQVIA leverages its clinical data infrastructure to anchor real-time analytics services across European pharmaceutical networks. Siemens Healthineers sustains technology leadership in AI-powered diagnostic imaging analytics, while SAS Institute competes through specialized prescriptive analytics platforms for biostatistical modeling.
Europe AI in Life Science Analytics encompasses machine learning algorithms, natural language processing engines, and neural network architectures trained on multimodal biomedical datasets to extract predictive patterns from genomic, proteomic, and clinical trial data. These systems process structured and unstructured health records at throughput rates exceeding traditional biostatistical methods, enabling automated hypothesis generation and patient stratification for pharmaceutical research. Predictive analytics dominates current deployment value as pharmaceutical companies prioritize forecast models for molecule behavior and market access outcomes. Prescriptive analytics represents the fastest-expanding segment, with biotechnology firms demanding optimization engines that recommend specific trial designs and dosing protocols. Cloud-based deployment captures growing share among mid-sized research institutions seeking scalable computational resources without capital-intensive on-premises infrastructure.
The EU AI Act and EMA's guidance on artificial intelligence in medicinal product lifecycle management establish conformity requirements that shape product development roadmaps and market access conditions for analytics vendors. GDPR and the Clinical Trials Regulation impose data governance standards that directly influence architecture choices for cross-border patient data integration. Stakeholders must monitor how the European Health Data Space implementation alters data portability rules and whether national competent authorities harmonize inspection protocols for AI-enabled clinical decision support systems.
Market Dynamics
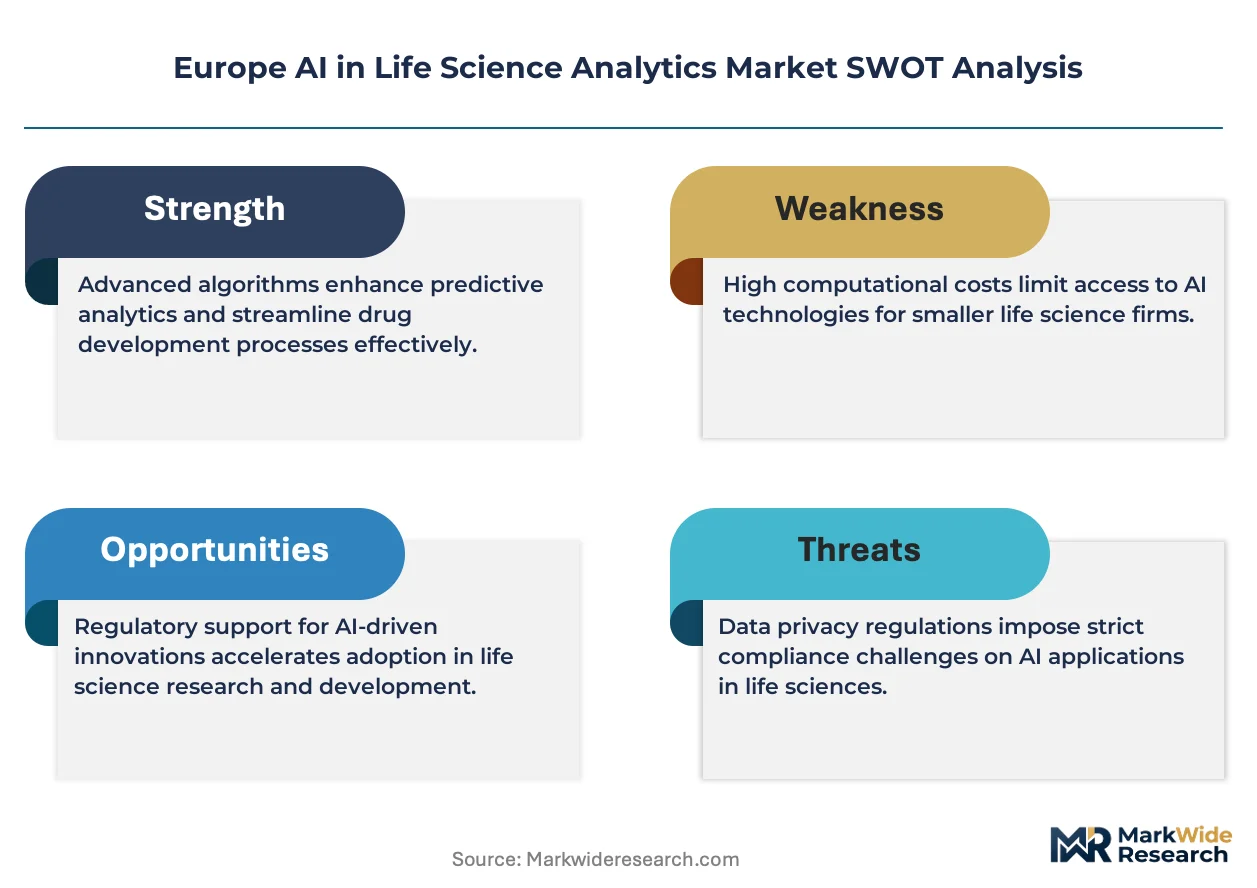
The EU AI Act is fragmenting deployment pathways by risk classification, forcing vendors to rebuild validation pipelines for high-risk clinical decision support systems while lower-risk applications face lighter conformity burdens.
Growth Catalysts
- EMA's AI guidance framework:The European Medicines Agency's lifecycle management guidance creates regulatory clarity that accelerates pharmaceutical adoption of algorithmic trial design tools across Germany and France.
- Biotech corridor concentration:Munich and Cambridge research clusters generate dense demand for real-time genomic analytics, concentrating procurement power among precision medicine networks.
- Federated learning architectures:Privacy-preserving computation methods enable cross-border patient data integration without GDPR violations, unlocking multi-site clinical studies.
Market Restraints
- GPU compute cost volatility:Specialized accelerator hardware for neural network training faces supply concentration among Taiwan-based foundries, inflating operational expenditure for mid-sized research institutions.
- Conformity assessment bottlenecks:Notified body capacity constraints under MDR and EU AI Act timelines delay market entry for novel diagnostic algorithms by 18-24 months.
- Interoperability limitations:Proprietary data formats from legacy electronic health record systems block seamless ingestion into cloud-native analytics platforms.
Strategic Opportunities
- European Health Data Space implementation:Secondary use provisions for health data create new licensing revenue streams for hospital networks and research biobanks in Spain and Italy.
- Digital biomarker convergence:Wearable sensor data fused with proteomic signatures enables continuous patient monitoring applications in decentralized clinical trials.
- CE marking harmonization:Streammed conformity routes for software-as-medical-device reduce duplication costs for vendors seeking multi-country deployment.
Industry Challenges
- Computational biology talent scarcity:Shortage of professionals trained in both machine learning architectures and molecular biology constrains model development velocity for biotechnology firms.
- Algorithmic audit complexity:Explainability requirements under GDPR Article 22 demand documentation pipelines that extend development cycles for deep learning-based diagnostic tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe AI in Life Science Analytics Market |
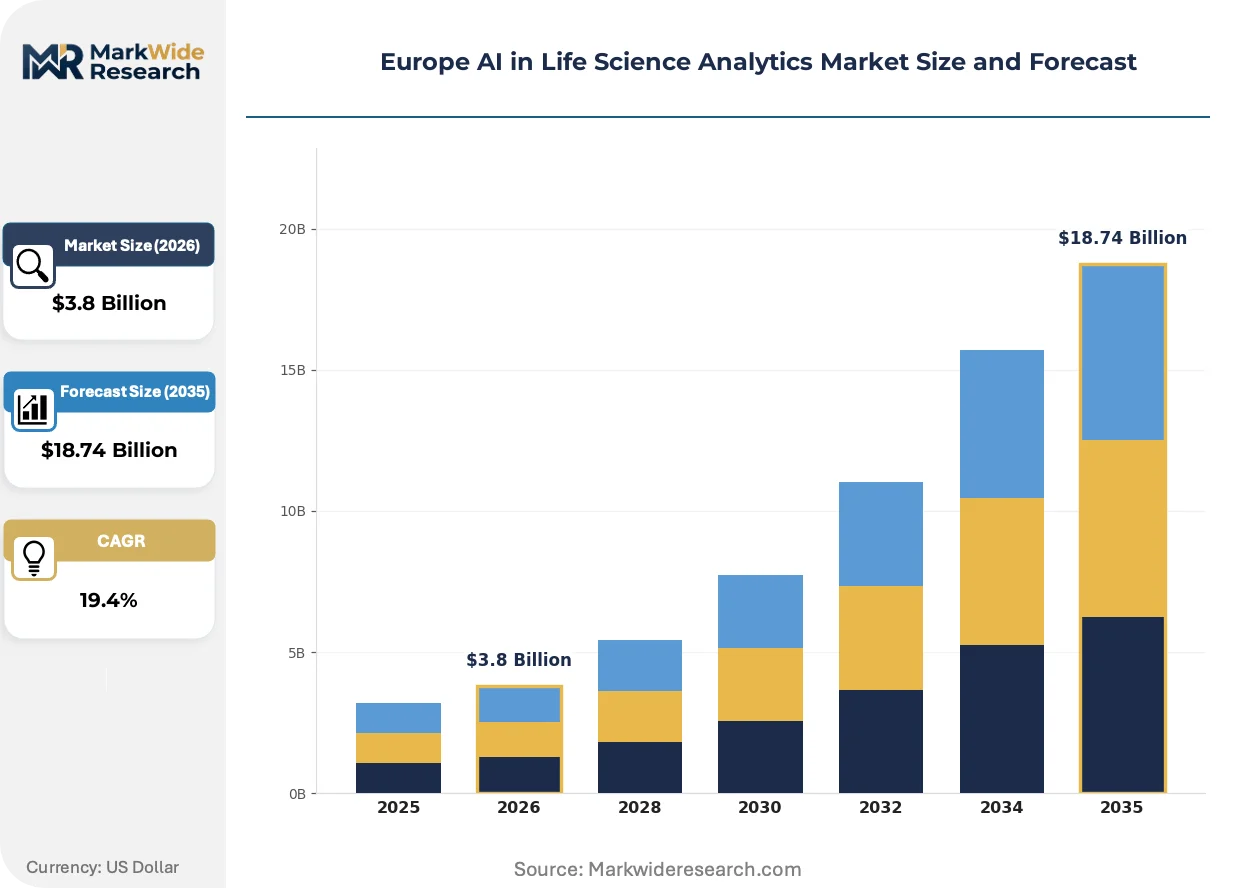
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Analytics, Prescriptive Analytics, Descriptive Analytics, Real-Time Analytics End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Clinical Laboratories Deployment: On-Premises, Cloud-Based, Hybrid Solutions, SaaS Application: Drug Discovery, Patient Monitoring, Fraud Detection, Clinical Trials |
| Companies Covered | Databricks, Accenture, IQVIA, ZS Associates, Oracle, SAS Institute, Siemens Healthineers, Axtria, IBM, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe AI in Life Science Analytics Market Evolving Landscape
Foundation models trained on multimodal biomedical corpora are compressing hypothesis generation timelines, while regulatory sandboxes in France and Germany test adaptive approval pathways for continuously learning algorithms.
Transformer architectures for protein structure prediction are fragmenting traditional crystallography workflows. Biotechnology firms in Basel and Oxford deploy these models for lead optimization, collapsing months of laboratory screening into computational cycles. The structural shift favors platform vendors offering API-accessible molecular simulation over on-premises bioinformatics suites.
EMA's qualification opinion process for novel methodologies is tightening evidentiary standards for real-world evidence integration. Pharmaceutical sponsors must now demonstrate algorithmic transportability across European healthcare systems before label expansion. German regulatory science networks respond by building synthetic data validation frameworks that simulate cross-population performance.
Research procurement teams now unbundle analytics subscriptions from full-service clinical research organization contracts. Mid-sized biotechs in the Netherlands and Sweden directly license specialized natural language processing engines for regulatory document mining, bypassing traditional vendor intermediaries. This disintermediation concentrates price pressure on integrated service providers while expanding addressable market for point-solution vendors.
Europe AI in Life Science Analytics Market Segmentation
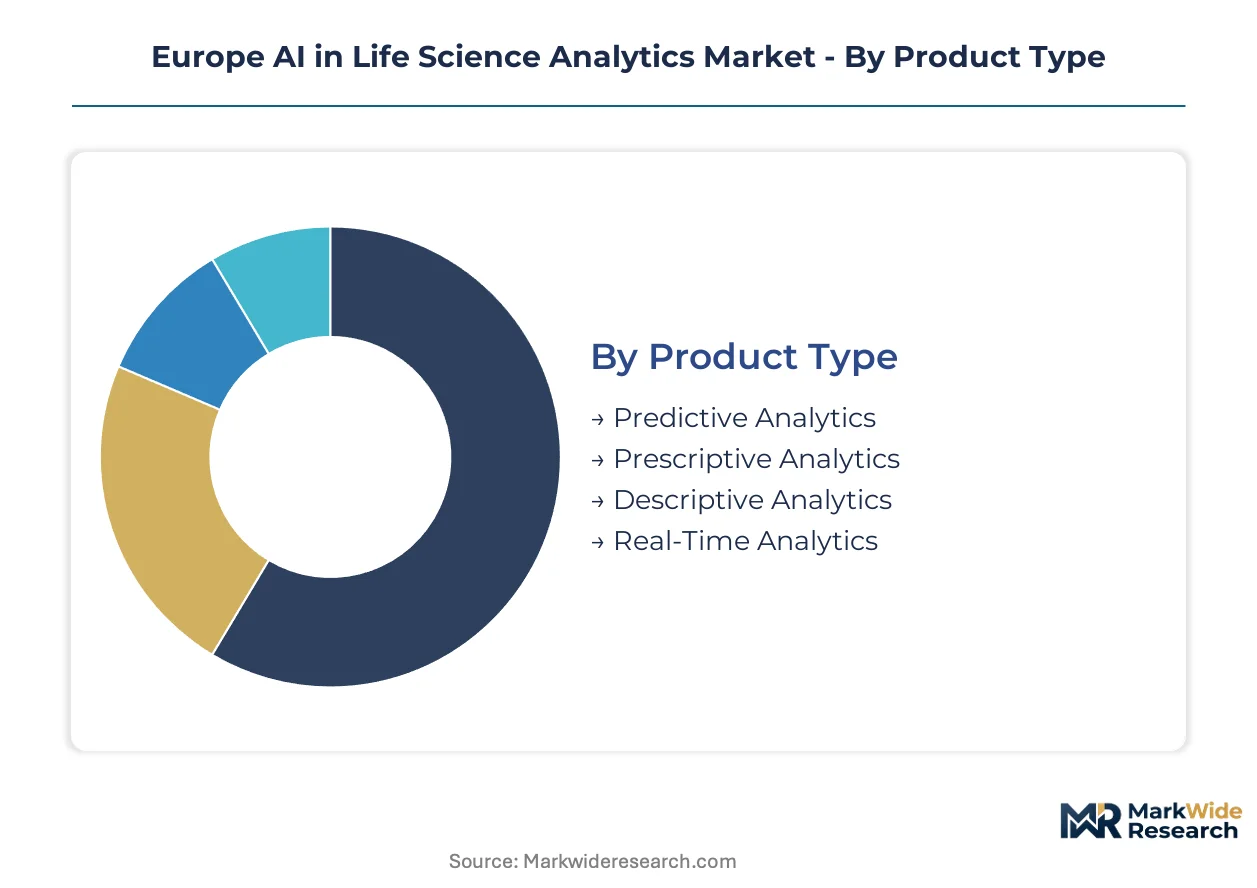
Segmentation reveals how pharmaceutical procurement teams unbundle analytics services from full-service contracts, redirecting spending toward specialized point solutions. The channel mix varies sharply across deployment modes and end-user sophistication, with cloud-native platforms capturing mid-tier research institutions while enterprise-grade on-premises systems anchor Big Pharma infrastructure.
Product Type:
Predictive and prescriptive platforms flow through direct enterprise sales channels, while descriptive and real-time modules increasingly route through cloud marketplaces and API-based licensing.
- Predictive Analytics:Machine learning algorithms trained on historical clinical trial outcomes and genomic datasets to forecast molecule behavior and patient response probabilities. Demand concentrates among German pharmaceutical headquarters in Frankfurt and Munich, where pipeline risk quantification drives procurement budgets amid EMA's tightened evidentiary standards for algorithmic transportability.
- Prescriptive Analytics:Optimization engines that recommend specific trial designs, dosing protocols, and resource allocation strategies based on multi-constraint modeling. Biotechnology firms in Cambridge and Basel represent the fastest-expanding customer base, seeking automated decision support for adaptive clinical trial frameworks under EU AI Act high-risk system classifications.
- Descriptive Analytics:Retrospective data aggregation tools for regulatory reporting and historical performance benchmarking, primarily licensed by mid-sized clinical laboratories in France and Italy through SaaS subscriptions.
- Real-Time Analytics:Stream processing architectures enabling instantaneous patient stratification and safety signal detection, deployed via hybrid cloud configurations at major research hospitals in the Netherlands and Sweden.
Predictive Analytics dominates installed base. Prescriptive Analytics is where expansion concentrates.
End User:
Cost tier segmentation separates enterprise-grade platform investments from departmental point solutions, with procurement authority increasingly decentralized to research unit leaders.
- Pharmaceutical Companies:Multinational sponsors with integrated data science teams deploying end-to-end analytics stacks across discovery, clinical, and commercial functions. German and UK headquarters drive largest contract values, prioritizing regulatory-grade validation documentation for EMA qualification opinion submissions.
- Biotechnology Firms:Venture-backed specialists licensing modular AI components for specific therapeutic programs, favoring usage-based pricing and rapid deployment timelines over capital-intensive infrastructure.
- Research Institutions:Academic medical centers and university hospitals in France and Spain combining public funding with industry partnerships to access federated learning networks for multi-site genomic studies.
- Clinical Laboratories:Diagnostic service providers automating quality control and test interpretation workflows, constrained by interoperability limitations with legacy electronic health record systems.
Pharmaceutical Companies capture majority revenue share. Biotechnology Firms are climbing the fastest.
Deployment:
Volume concentration tilts toward cloud-based delivery among institutions lacking dedicated GPU infrastructure, while hybrid architectures gain traction for GDPR-sensitive genomic data processing.
- On-Premises:Dedicated server clusters and private data centers housing proprietary training datasets and custom model architectures. Retains dominance at Swiss pharmaceutical campuses and German Max Planck Institute facilities where data sovereignty requirements override cost considerations.
- Cloud-Based:Scalable computational resources via hyperscale providers, capturing growing procurement share among mid-sized research institutions in Denmark and Norway seeking neural network training capacity without Taiwan-foundry GPU supply exposure.
- Hybrid Solutions:Split architectures keeping sensitive patient data on-premises while offloading compute-intensive training to cloud infrastructure, preferred by UK NHS research networks navigating European Health Data Space implementation timelines.
- SaaS:Pre-configured analytics applications with standardized interfaces, penetrating clinical laboratory segments through rapid deployment and predictable operational expenditure profiles.
On-Premises retains highest average contract value. Cloud-Based is gaining share fastest.
Application:
Customer maturity varies by therapeutic domain, with oncology and rare disease programs leading algorithmic adoption while infectious disease applications lag regulatory framework development.
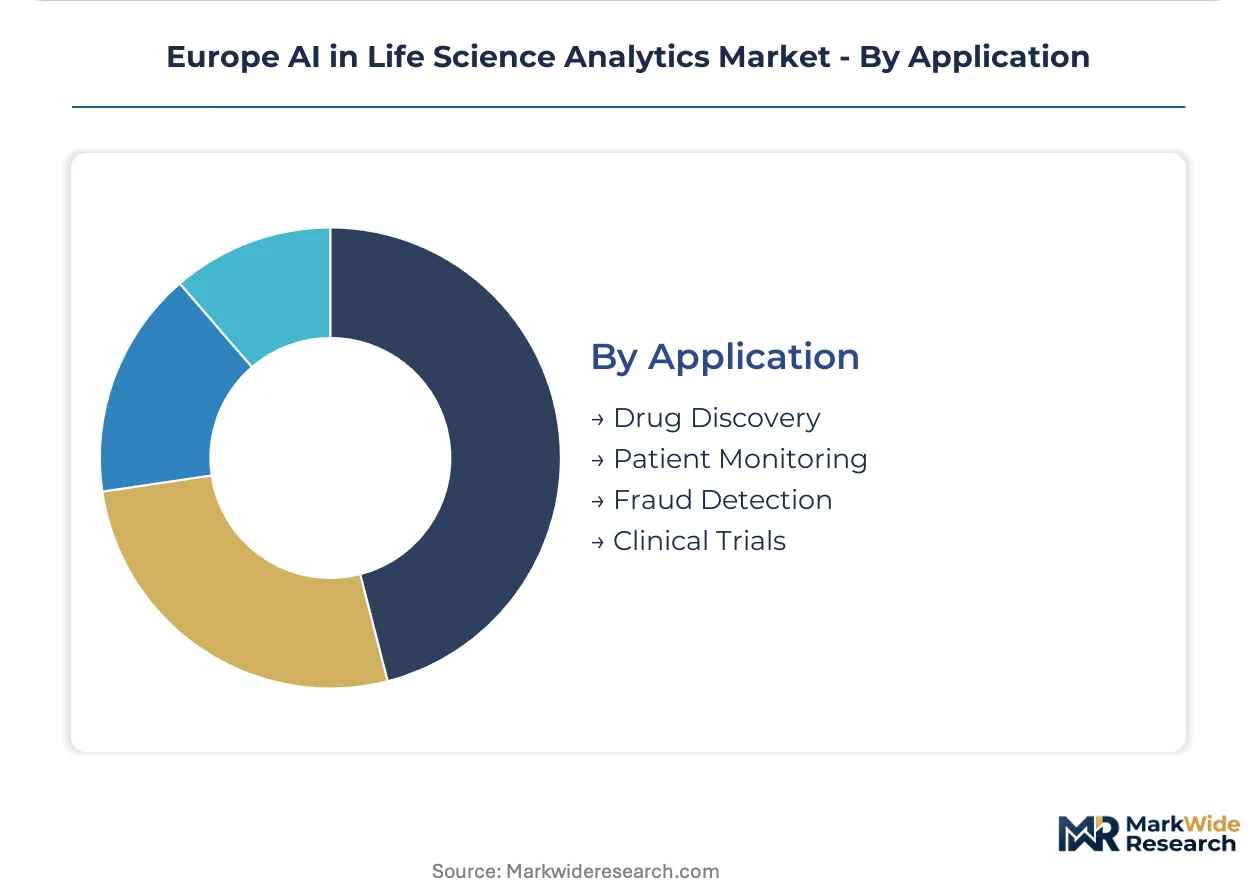
- Drug Discovery:Target identification, lead optimization, and toxicity prediction workflows compressing traditional screening timelines. Munich and Oxford biotech clusters deploy transformer-based protein structure models, fragmenting legacy crystallography vendor relationships.
- Clinical Trials:Patient recruitment optimization, adaptive dosing algorithms, and decentralized trial monitoring. EMA's AI guidance framework accelerates adoption across German and French sponsor organizations seeking regulatory clarity for algorithmic protocol amendments.
- Patient Monitoring:Continuous biomarker tracking through wearable sensor fusion, emerging at Dutch and Swedish sites testing digital biomarker qualification pathways.
- Fraud Detection:Anomaly detection in claims data and supply chain verification, primarily deployed by national health systems in Italy and Spain under CSRD-aligned transparency mandates.
Drug Discovery commands largest development investment. Clinical Trials is where procurement velocity is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German AI analytics vendors export validation-grade platforms to pharmaceutical sponsors across France and the United Kingdom, establishing a westward trade corridor that concentrates procurement authority in Frankfurt and Munich headquarters before radiating to satellite research clusters.
Germany
EMA qualification opinion processes and BfArM digital health fast-tracks drive pharmaceutical procurement of algorithmic trial design tools. The EU AI Act high-risk system classifications reshape conformity assessment timelines for Bavarian diagnostic algorithm developers. Munich's biotech corridor integrates real-time genomic analytics into precision medicine workflows at Max Planck Institute facilities.
United Kingdom
NHS research networks and MHRA software-as-medical-device guidance accelerate adoption of hybrid cloud architectures for sensitive patient data processing. GDPR Article 22 explainability requirements extend development cycles for London-based deep learning diagnostic ventures. The Cambridge research cluster generates dense demand for federated learning networks spanning multi-site genomic studies.
France
ANSM regulatory sandboxes and CNIL AI audit frameworks test adaptive approval pathways for continuously learning algorithms in Parisian pharmaceutical headquarters. CSRD-aligned transparency mandates push national health systems toward automated claims anomaly detection. The Île-de-France precision medicine networks concentrate procurement power for API-accessible molecular simulation platforms.
Netherlands
EMA's location in Amsterdam anchors regulatory-grade validation documentation demand among Dutch clinical research organizations. The European Health Data Space implementation timelines drive hybrid deployment preferences at Leiden and Utrecht university hospitals. Dutch and Swedish sites jointly test digital biomarker qualification pathways for wearable sensor fusion applications.
Switzerland
Swissmedic's streamlined software-as-medical-device routes reduce duplication costs for Basel-based biotechnology firms seeking multi-country deployment. Data sovereignty requirements at Swiss pharmaceutical campuses sustain dominance of on-premises GPU clusters over Taiwan-foundry supply-exposed cloud alternatives. The Basel-Oxford molecular simulation corridor fragments legacy crystallography vendor relationships through transformer-based protein structure models.
Europe AI in Life Science Analytics Market Competitive Landscape
Listed leaders compete with private specialists across regulatory validation capabilities, creating a tiered structure where scale-driven platform vendors anchor enterprise pharmaceutical contracts while modular point-solution providers capture mid-sized biotechnology procurement. Strategic archetypes separate into full-stack clinical data infrastructure operators, specialized biostatistical modeling firms, and API-first molecular simulation vendors. Competitive moves concentrate on M&A for regulatory science capabilities and federated learning network partnerships that unlock cross-border patient data integration.
Within the full-stack infrastructure tier, IQVIA and Oracle occupy positions anchoring real-time analytics services across European pharmaceutical networks. Siemens Healthineers exemplifies the diagnostic imaging analytics archetype, while SAS Institute sits within the specialized prescriptive modeling segment competing through biostatistical optimization engines. These three companies represent distinct competitive vectors—clinical data infrastructure, diagnostic hardware-software integration, and statistical software platforms—that collectively span the deployment spectrum from on-premises enterprise systems to cloud-native API licensing.
| Leading Market Players |
|---|
| Databricks |
| Accenture |
| IQVIA |
| ZS Associates |
| Oracle |
| SAS Institute |
| Siemens Healthineers |
| Axtria |
| IBM |
| Others |
Value Network & Pricing Analysis
GPU cluster utilization rates at hyperscale cloud facilities anchor cost structures across the Europe AI in Life Science Analytics market, compressing price floors for mid-sized research institutions while elevating premiums for sovereign data center deployments. Taiwan-foundry supply concentration for specialized accelerators forces German pharmaceutical sponsors toward long-term reservation contracts that reshape procurement economics.
Pricing Analysis
Next-generation transformer-based molecular simulation platforms command 40-60% premiums over legacy bioinformatics suites, while prior-generation statistical software faces accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation documentation depth and EMA qualification opinion support. Cost compression in the economy tier intensifies because cloud-native entrants disintermediate traditional vendor relationships. Mid-sized biotechnology firms in the Netherlands and Sweden exhibit highest price sensitivity, whereas Swiss pharmaceutical campuses prioritize data sovereignty over cost optimization.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for neural network training accelerators, while Germany and the United Kingdom concentrate regulatory-grade validation software development. Supply chains draw from Taiwan Semiconductor Manufacturing Company foundry capacity, NVIDIA GPU silicon, and specialized European biostatistical talent pools. Single-source vulnerability around Taiwan-based accelerator production exposes mid-sized research institutions to allocation constraints. Distribution runs through direct enterprise sales for pharmaceutical sponsors, cloud marketplaces for mid-tier institutions, and API licensing for modular point-solution procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act high-risk system classification creates a regulatory inflection that fragments competitive positioning between validation-grade incumbents and agile point-solution entrants.
For Market Incumbents: Shield enterprise pharmaceutical contracts through accelerated MDR and EU AI Act conformity documentation investments. Acquire regulatory science capabilities in Germany and France to compress 18-24 month notified body bottlenecks. Deepen backward integration into federated learning network infrastructure to lock out modular competitors from cross-border patient data integration. For New Entrants and Emerging Players: Anchor in prescriptive analytics optimization engines for adaptive clinical trial frameworks, the fastest-expanding segment with lightest incumbent saturation. Target mid-sized biotechnology procurement in Cambridge and Basel clusters where usage-based pricing tolerance exceeds enterprise vendor loyalty. Deploy API-first molecular simulation platforms that fragment legacy crystallography relationships through transformer-based protein structure prediction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform vendors with regulatory-grade validation pipelines over point-solution specialists facing conformity assessment delays. Five-to-ten year viability hinges on European Health Data Space implementation capture and synthetic data validation framework ownership. Watch EMA qualification opinion throughput rates as the inflection signal for algorithmic transportability premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Science Acquisition | Compresses EU AI Act conformity timelines for Bavarian diagnostic algorithm developers. |
| Federated Learning Network Partnership | Unlocks GDPR-compliant cross-border patient data integration for multi-site genomic studies. |
| Synthetic Data Validation Framework | Simulates cross-population algorithmic performance for EMA qualification opinion submissions. |
| API-First Molecular Simulation Launch | Fragments legacy crystallography vendor relationships at Munich and Oxford biotech clusters. |
| Hybrid Cloud Architecture Deployment | Navigates European Health Data Space timelines at UK NHS research networks. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers and secondary sources including EMA submissions, ClinicalTrials.gov records, and EU AI Act implementation guidance anchors the qualitative findings. Bottom-up triangulation across pharmaceutical sponsor procurement databases and top-down validation through hyperscaler cloud capex disclosures establish segment-level estimates. Synthetic data validation framework adoption rates and federated learning network participation metrics inform technology penetration assumptions.
Sensitivity analysis around GPU supply concentration, notified body capacity constraints, and European Health Data Space implementation timelines tests forecast robustness across the projection horizon. Segmentation modeling spans product type, deployment mode, end-user sophistication, and therapeutic application domain. CAGRs derive from algorithmic transportability requirement tightening and prescriptive analytics procurement velocity acceleration. Transformer architecture adoption curves and digital biomarker qualification pathway progression serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained EU AI Act implementation and Taiwan-foundry supply stability assumptions; material deviation would warrant model refresh. Forecasts incorporate EMA guidance framework evolution and GDPR Article 22 explainability documentation burden trajectories. Recalibration cycles align with material shifts in notified body capacity expansion and European Health Data Space secondary use provision activation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
North America Computational Biology Market
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
Bioinformatics Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
US Computational Biology Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
China Computational Biology Market