
 Global Mirna Sequencing and Assay Market | 2026-2036
Global Mirna Sequencing and Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mirna Sequencing and Assay Market Foresight
Synthetic oligonucleotide chemistry is hardening as the dominant substrate for library preparation kits, displacing earlier enzymatic-only workflows and compressing per-sample reagent costs. Illumina, Inc. leverages its installed base of sequencers to anchor consumable pull-through across clinical and research accounts. Thermo Fisher Scientific sustains vertical integration from reverse transcription enzymes through cloud analytics, while QIAGEN differentiates through automated sample-to-insight workflows that reduce hands-on time in clinical laboratories.
MiRNA sequencing and assay refers to the targeted detection, quantification, and analysis of microRNA molecules—typically 18-25 nucleotides in length—using reverse transcription, adapter ligation, and massively parallel sequencing or hybridization-based readout, primarily to identify expression signatures for disease classification and therapeutic monitoring. Library preparation kits and RT-PCR assay kits capture the dominant share of product-type revenue due to recurring consumable demand, while digital PCR represents the fastest-expanding technology segment as laboratories seek absolute quantification without standard curve dependency. Cancer research commands the largest application volume, though biomarker discovery is widening as pharmaceutical sponsors integrate miRNA panels into early-stage target validation.
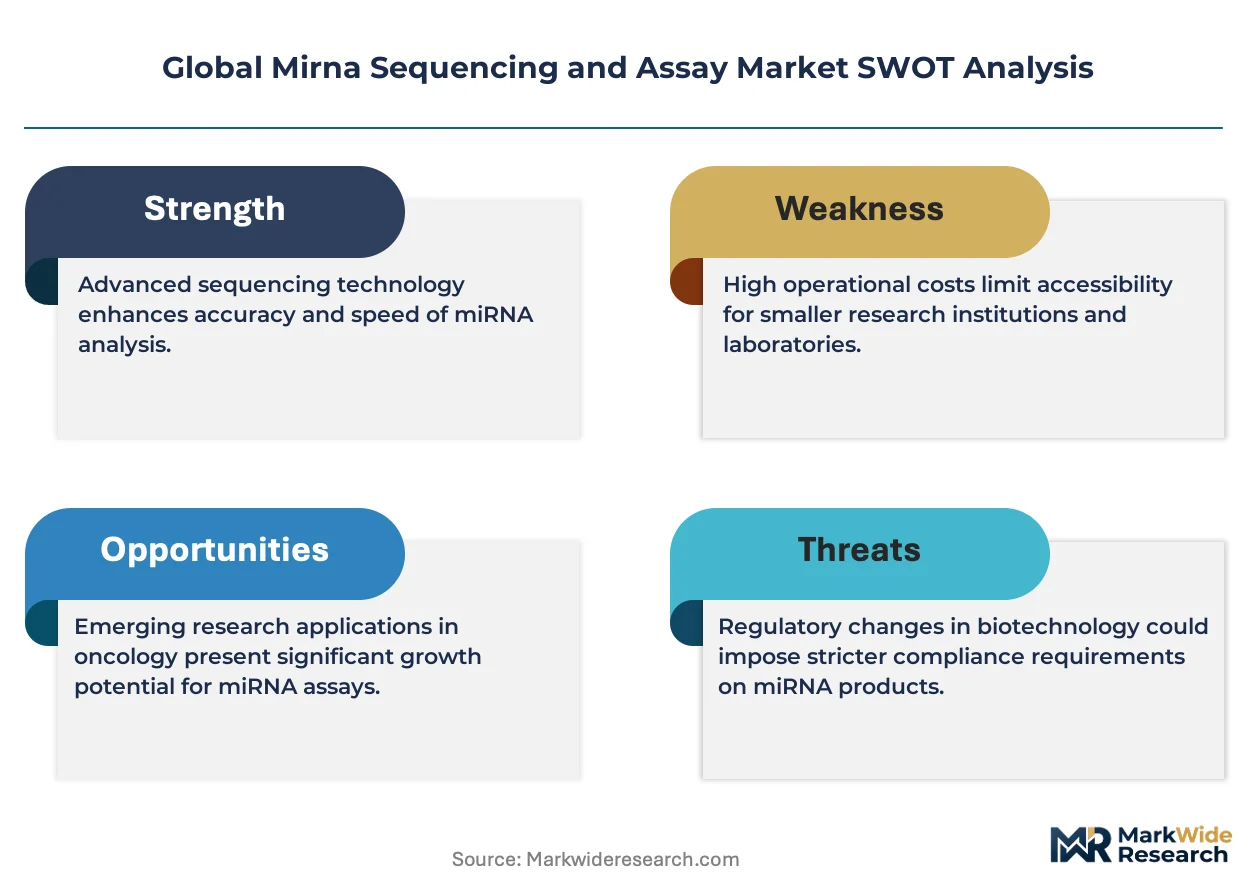
The FDA regulates miRNA-based in vitro diagnostics through its Center for Devices and Radiological Health, requiring analytical and clinical validation that shapes product development timelines and submission strategies for assay manufacturers. The EMA's In Vitro Diagnostic Medical Devices Regulation in Europe imposes additional conformity assessment burdens that filter market access for smaller kit vendors. The EU AI Act's risk-classification framework will increasingly govern algorithmic components of sequencing data interpretation pipelines. Stakeholders must monitor evolving premarket review harmonization between the FDA and notified bodies, as divergent evidentiary standards threaten to fragment go-to-market strategies across jurisdictions.
Market Dynamics
Synthetic oligonucleotide chemistry is compressing per-sample reagent costs while enzymatic workflows face displacement, fundamentally altering kit economics and vendor margin structures across library preparation segments.
Growth Catalysts
- Precision Medicine Initiatives:NIH-funded academic medical centers in the United States are expanding miRNA panel deployment for patient stratification, creating sustained consumable demand.
- IVDR Conformity Pathways:The EMA's In Vitro Diagnostic Medical Devices Regulation is filtering smaller vendors and concentrating market access among validated manufacturers.
- Digital PCR Migration:Laboratories are abandoning standard curve-dependent quantification for absolute copy number determination, accelerating instrument refresh cycles.
Market Restraints
- Reagent Cost Volatility:Modified nucleotide and adapter oligonucleotide inputs face price instability from specialty chemical suppliers concentrated in Germany and Switzerland.
- Validation Burden:The FDA's analytical and clinical validation requirements for nucleic acid-based tests extend product development timelines by 18-36 months.
- Hybridization Assay Substitution:Nanostring and Luminex platforms retain cost advantages for targeted panels under 100 targets, limiting sequencing penetration in routine screening.
Strategic Opportunities
- Companion Diagnostic Integration:Pharmaceutical sponsors are embedding miRNA biomarkers into oncology trial protocols, opening recurring revenue streams for assay developers.
- Cloud Analytics Convergence:Bioinformatics pipelines are integrating with AWS and Azure health data architectures, enabling subscription-based interpretation services.
- India's CDSCO Pathway:The country's streamlined medical device registration is attracting kit manufacturers seeking lower-cost manufacturing bases for Asian distribution.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories lack computational biologists capable of validating variant calling pipelines for regulatory submission.
- Inter-platform Standardization:Absence of ISO reference materials for miRNA quantification forces laboratories to run costly cross-instrument correlation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mirna Sequencing and Assay Market |
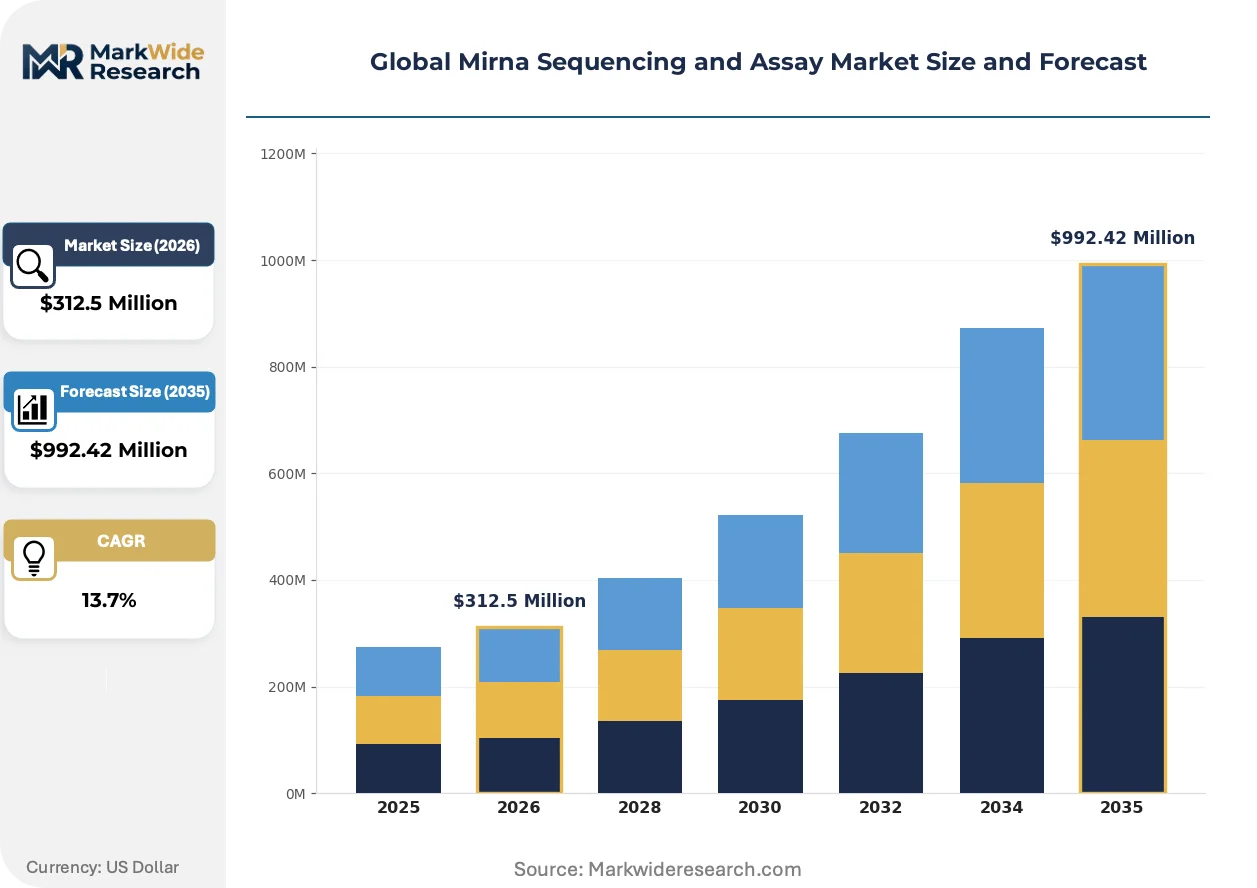
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $992.42 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Library Preparation Kits, Sequencers, Hybridization Arrays, RT-PCR Assay Kits Technology: Next Generation Sequencing, Microarray, Quantitative PCR, Digital PCR Application: Cancer Research, Biomarker Discovery, Drug Development, Molecular Diagnostics End User: Academic Institutions, Pharmaceutical Companies, CROs, Clinical Laboratories |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific, QIAGEN, PerkinElmer, Takara Bio Inc., Abcam plc, New England Biolabs, Revvity, Lexogen GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mirna Sequencing and Assay Market Shifts & Advancements
Workflow automation and regulatory algorithm governance are converging to reshape how miRNA data moves from sample to clinical decision, with implications for vendor business models and laboratory staffing.
Automated sample-to-insight platforms are integrating liquid handlers, thermal cyclers, and cloud-based variant interpretation to reduce hands-on time in high-throughput clinical laboratories. Hospital systems in the United States and Germany are adopting these closed systems to minimize batch-to-batch variability and compress turnaround times for oncology panels. This integration is enabling mid-volume laboratories to enter miRNA testing without expanding specialized molecular pathology headcount.
The EU AI Act's risk-classification framework is imposing conformity assessment obligations on algorithmic components of sequencing interpretation pipelines. Kit vendors serving European markets must now document training data provenance and performance metrics for machine learning modules previously treated as research-use-only software. CDx developers in France and the Netherlands are restructuring quality management systems to capture this documentation burden.
Pharmaceutical sponsors are unbundling biomarker discovery from central laboratory contracts, establishing direct relationships with sequencing providers for longitudinal patient monitoring. This disintermediation of traditional CRO channels concentrates purchasing power among sponsor procurement teams and pressures assay vendors to demonstrate interoperability with multiple data platforms. The shift is most visible in immuno-oncology trials where miRNA response signatures require real-time analysis across investigator sites in Massachusetts, Basel, and Singapore.
Global Mirna Sequencing and Assay Market Segmentation
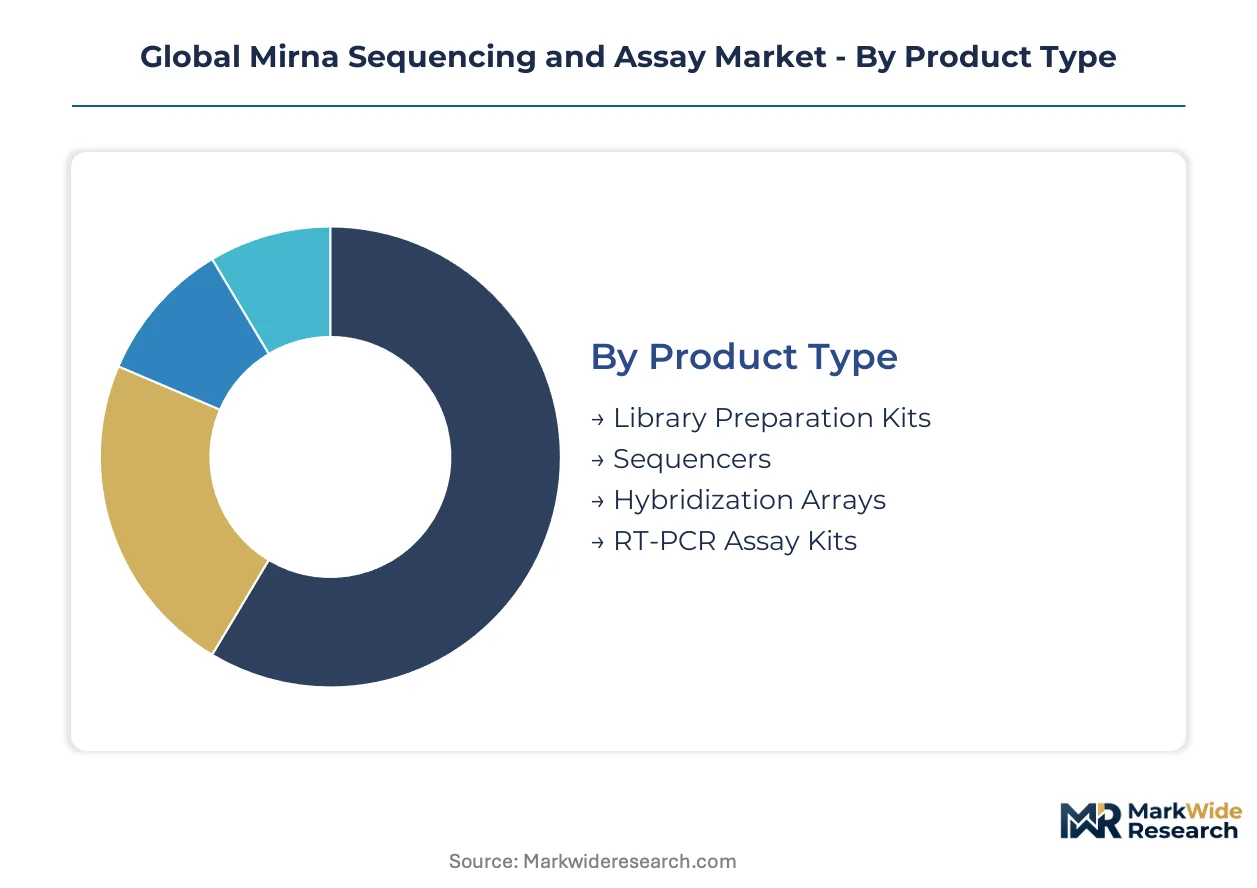
Segmentation in the miRNA sequencing and assay market reveals distinct procurement patterns across product tiers and customer types. Laboratory directors weigh consumable recurring costs against capital instrument depreciation, while regulatory compliance requirements fragment vendor selection criteria by end-use setting.
Product Type:
Reagent chemistry sophistication and per-sample economics drive purchasing committee decisions across hospital and commercial laboratory settings.
- Library Preparation Kits:Synthetic oligonucleotide-based workflows dominate clinical adoption due to compressed turnaround times and reduced batch failure rates. Academic medical centers in Massachusetts and California anchor volume demand as NIH precision medicine grants sustain panel deployment.
- RT-PCR Assay Kits:These consumables capture steady replacement demand from clinical laboratories validating miRNA biomarkers under FDA nucleic acid test guidance. Pharmaceutical sponsors in Basel and Singapore embed these assays into oncology trial protocols for longitudinal patient monitoring.
- Sequencers:Capital equipment purchases concentrate among high-throughput reference laboratories seeking Illumina platform standardization.
- Hybridization Arrays:Nanostring and Luminex-based systems retain cost advantages for targeted panels under 100 targets in routine screening applications.
Volume sits with library preparation kits; growth tilts toward RT-PCR assay kits.
Technology:
Quantification accuracy requirements and regulatory submission pathways shape platform selection across research and diagnostic environments.
- Digital PCR:Absolute copy number determination without standard curve dependency is accelerating instrument refresh cycles in clinical laboratories. The technology's analytical precision supports FDA companion diagnostic submissions, attracting pharmaceutical sponsor investment in Massachusetts and Basel.
- Next Generation Sequencing:Massively parallel readout enables discovery-phase miRNA profiling with broad dynamic range. Academic institutions in Heidelberg and Singapore deploy these platforms for biomarker discovery under national precision medicine initiatives.
- Quantitative PCR:Established workflows persist in mid-volume laboratories with limited bioinformatics infrastructure.
- Microarray:Hybridization-based readout retains niche applications for retrospective sample analysis in biobank settings.
Installed base concentrates in next generation sequencing; expansion is steepest in digital PCR.
Application:
Therapeutic development timelines and reimbursement pathways determine assay development prioritization across sponsor and diagnostic company portfolios.
- Cancer Research:Oncology dominates miRNA panel deployment as tumor classification signatures enter clinical validation. Immuno-oncology trials in France and the Netherlands require real-time miRNA response analysis across investigator sites.
- Biomarker Discovery:Early-stage target validation is widening miRNA integration into pharmaceutical pipelines. Sponsors are unbundling discovery from central laboratory contracts, establishing direct sequencing provider relationships.
- Drug Development:Toxicology and pharmacodynamic monitoring applications are emerging in preclinical contract research.
- Molecular Diagnostics:Clinical laboratory-developed tests face IVDR conformity assessment burdens in European markets.
Revenue concentrates in cancer research; biomarker discovery is climbing the fastest.
End User:
Capital availability and regulatory sophistication fragment customer requirements across institutional and commercial settings.
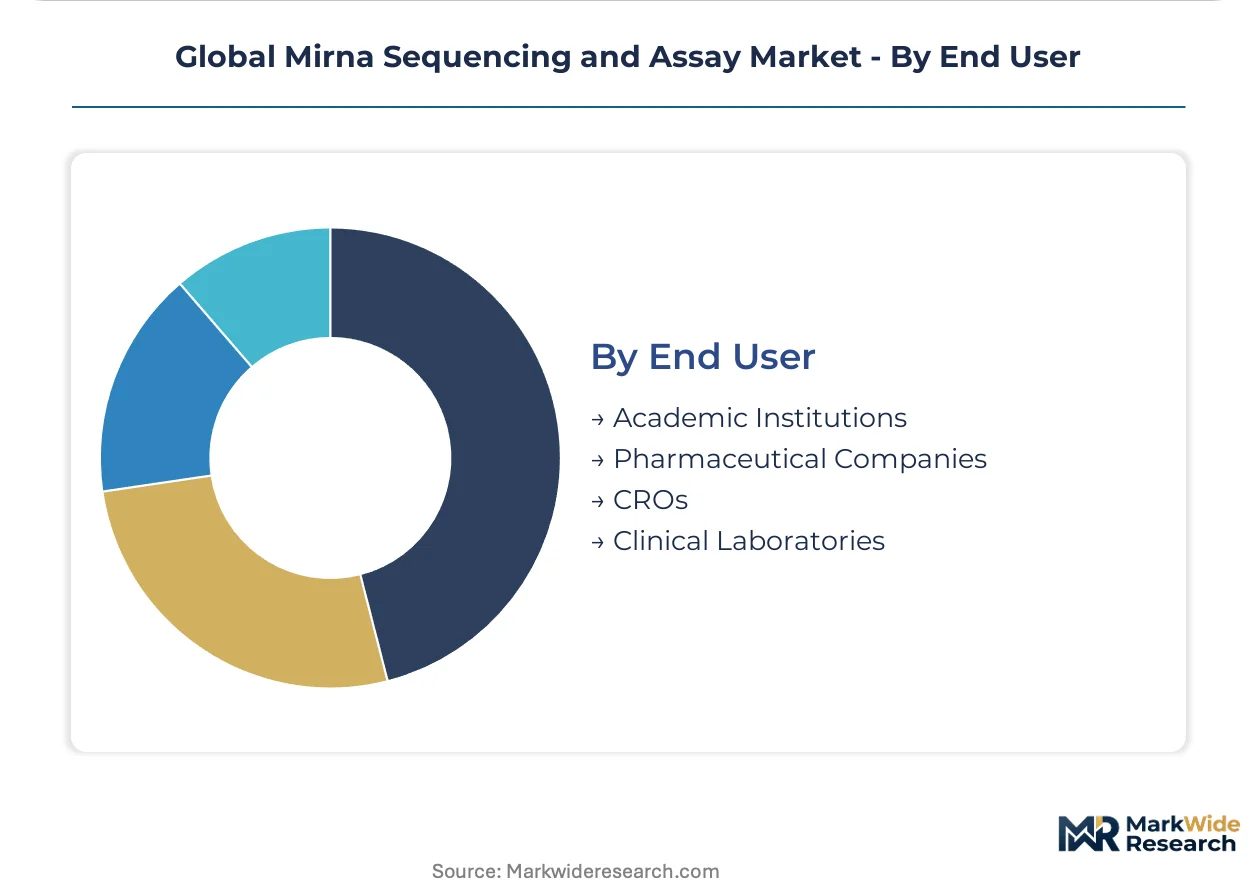
- Academic Institutions:NIH-funded medical centers in the United States sustain consumable demand through precision medicine grant programs. These laboratories prioritize discovery flexibility over regulatory compliance documentation.
- Pharmaceutical Companies:Sponsor procurement teams are consolidating purchasing power as they embed miRNA biomarkers into trial protocols. Basel and Massachusetts headquarters anchor global assay standardization efforts.
- Clinical Laboratories:Mid-volume hospital systems adopt automated sample-to-insight platforms to minimize specialized molecular pathology headcount.
- CROs:Traditional central laboratory channels face disintermediation as sponsors establish direct sequencing relationships.
Spend concentrates with academic institutions; pharmaceutical company adoption is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States where NIH-funded academic medical centers anchor precision medicine deployment, while pharmaceutical sponsors in Basel and Singapore drive companion diagnostic standardization across trial networks.
United States
FDA nucleic acid test guidance shapes validation timelines for assay developers in Massachusetts and California. The agency's Center for Devices and Radiological Health mandates analytical and clinical evidence that extends product development cycles. Boston-Cambridge biotech clusters sustain consumable pull-through as pharmaceutical sponsors embed miRNA biomarkers into oncology protocols.
Germany
Specialty chemical suppliers in Baden-Württemberg and Bavaria manufacture modified nucleotide inputs for library preparation chemistry. EMA's In Vitro Diagnostic Medical Devices Regulation imposes conformity assessment burdens that filter smaller kit vendors. Heidelberg academic institutions deploy next-generation sequencing platforms under national precision medicine frameworks.
Switzerland
Pharmaceutical procurement teams in Basel consolidate global assay standardization for longitudinal patient monitoring. Swissmedic oversees medical device registration for sequencing workflows entering European distribution. Zurich-Geneva biotech corridors attract kit manufacturers seeking regulatory sophistication for IVDR compliance.
Singapore
National precision medicine initiatives fund biomarker discovery deployments at academic medical centers. The country's national pharmaceutical regulator streamlines medical device registration for Asian distribution. Investigator sites participate in real-time miRNA response analysis for immuno-oncology trials spanning Massachusetts, Basel, and Singapore.
France
ANSM and CNIL govern algorithmic components of sequencing interpretation pipelines under the EU AI Act risk-classification framework. CDx developers in Paris and the Netherlands restructure quality management systems to capture documentation burdens. French immuno-oncology trials require real-time miRNA analysis across European investigator networks.
Global Mirna Sequencing and Assay Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform-anchored consumable vendors commanding recurring revenue streams while reagent-only suppliers face margin compression. The structure concentrates around three strategic archetypes: integrated platform-consumable providers, automated workflow specialists, and modular reagent vendors. M&A activity targets bioinformatics capabilities, while capacity expansion focuses on synthetic oligonucleotide manufacturing for library preparation chemistry.
Among platform-anchored providers, Illumina, Inc. and Thermo Fisher Scientific exemplify the integrated archetype through captive instrument bases and consumable pull-through. QIAGEN occupies a position within the automated workflow tier, representing specialists in sample-to-insight integration that reduces clinical laboratory hands-on time. These three entities anchor the competitive structure without exhausting its configuration.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific |
| QIAGEN |
| PerkinElmer |
| Takara Bio Inc. |
| Abcam plc |
| New England Biolabs |
| Revvity |
| Lexogen GmbH |
| Others |
Supply & Pricing Matrix
EU IVDR sustainability documentation mandates now gate qualified supply access and premium-tier pricing eligibility for miRNA assay manufacturers seeking European market entry. Kit vendors without ISO 13485-certified manufacturing and EMA-notified body conformity assessments face exclusion from hospital procurement frameworks in Germany and Switzerland, compressing their pricing power to standard-tier levels.
Pricing Analysis
Volume concentrates in library preparation consumables while margins compress fastest in modular reagent segments lacking platform anchoring. Pricing stratifies across premium, standard, and economy tiers based on IVDR certification status and automated workflow integration depth. Cost compression in standard-tier RT-PCR kits stems from specialty chemical supplier concentration in Baden-Württemberg and Bavaria. Mid-volume clinical laboratories exhibit highest price sensitivity, whereas pharmaceutical sponsors in Basel and Massachusetts prioritize analytical precision over per-sample economics.
Supply Chain Analysis
CE marking and FDA 510(k) clearance now function as mandatory gating criteria for modified nucleotide and adapter oligonucleotide suppliers serving diagnostic-grade kit manufacturers. Manufacturing concentrates in Germany, Switzerland, and the United States for synthetic chemistry inputs, with Singapore emerging for Asian distribution hubs. The supply chain draws from specialty chemical feedstocks, enzymatic reagents, and sequencing platform consumables. Single-source vulnerability persists for Illumina flowcell supply. Distribution runs through direct vendor relationships with academic medical centers and pharmaceutical procurement teams, bypassing traditional distributor channels for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Mirna Sequencing and Assay Market sits in a technology-transition phase as digital PCR platforms displace quantitative PCR workflows dependent on standard curve calibration. Synthetic oligonucleotide chemistry is hardening platform economics while enzymatic-only workflows face accelerated obsolescence.
For Market Incumbents: Extend consumable pull-through from installed sequencing bases by embedding miRNA panels into pharmaceutical companion diagnostic protocols under FDA nucleic acid test guidance. Anchor cloud analytics subscriptions to AWS and Azure health data architectures to capture recurring revenue beyond reagent sales. Defend against hybridization assay substitution from Nanostring and Luminex platforms by demonstrating superior dynamic range in oncology biomarker validation.
For New Entrants and Emerging Players: Mid-volume hospital systems in France and the Netherlands lacking specialized molecular pathology headcount represent the most penetrable buyer archetype for automated sample-to-insight platforms. Target India's CDSCO streamlined registration pathway for lower-cost manufacturing bases serving Asian distribution. Establish direct relationships with immuno-oncology trial sponsors seeking real-time miRNA response analysis across Massachusetts, Basel, and Singapore investigator sites.
For Investors and Strategic Acquirers: FDA companion diagnostic approval for a miRNA-based oncology panel is the leading indicator that platform-anchored consumable economics will concentrate market power among validated manufacturers. Long-term viability favors integrated providers with captive instrument bases and bioinformatics capabilities over modular reagent vendors facing margin compression. Watch for pharmaceutical sponsor unbundling of biomarker discovery from central laboratory contracts as the signal for sequencing provider consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Embedding miRNA biomarkers into FDA-guided oncology trial protocols secures recurring pharmaceutical sponsor revenue. |
| Cloud Analytics Convergence | AWS and Azure health data architecture integration enables subscription-based interpretation services beyond consumable sales. |
| Automated Workflow Development | Sample-to-insight platforms reduce hands-on time for mid-volume clinical laboratories under IVDR compliance pressure. |
| Asian Manufacturing Footprint | India's CDSCO streamlined registration attracts kit manufacturers seeking lower-cost bases for regional distribution. |
| Bioinformatics Capability Acquisition | Machine learning modules for sequencing interpretation face EU AI Act conformity assessment documentation burdens. |
Research Methodology
Multi-period observation of miRNA assay kit pricing trajectories, pharmaceutical trial protocol embedding rates, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with laboratory directors, regulatory affairs leads at kit manufacturers, pharmaceutical biomarker specialists, and hospital procurement managers. Secondary validation drew from FDA 510(k) filings, EMA IVDR conformity assessments, ClinicalTrials.gov protocol registrations, and NIH precision medicine grant disbursement records. Bottom-up segment sizing triangulated against top-down market aggregation across product type, technology, application, and end-user dimensions.
Input-output matrix framing structured the forecast architecture, with demand drivers mapped to segment-level consumption coefficients across the projection horizon. Segmentation dimensions modeled included library preparation chemistry tier, quantification technology platform, oncology versus non-oncology application, and institutional versus commercial end-user setting. CAGRs were derived from fitted growth curves applied to base-year estimates, with cross-validation against instrument install base refresh cycles and pharmaceutical pipeline miRNA biomarker integration rates.
Revisions become necessary when FDA nucleic acid test guidance timelines shift materially, EMA IVDR notified body capacity constraints deepen, or pharmaceutical sponsor disintermediation of central laboratory contracts accelerates beyond modeled rates. Forecasts reflect documented assumptions regarding synthetic oligonucleotide cost compression trajectories and cloud analytics subscription attach rates. A model refresh is warranted upon material change in EU AI Act algorithmic conformity assessment enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Hereditary Testing Market
Genomics
Sequencing Electrophoresis Systems Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Microbiome Sequencing Market
Genomics
United States DNA Sequencing Products Market
Genomics
Immunogenetics Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
Next Generation Molecular Assay Market
Genomics
Kearns-Sayre Syndrome Market
Genomics
Prenatal Genetic Testing Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Alagille Syndrome Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Predisposition Biomarkers Market
Genomics
Molecular Breeding Market
Genomics
Global NGS Sample Preparation Market