
 North America Computational Biology Market | 2026-2036
North America Computational Biology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Computational Biology Market Analytics
The EPA's computational toxicology mandate under Tox21 is decoupling traditional wet-lab validation from software-based risk prediction, expanding the addressable base for predictive modeling platforms. Illumina, Inc. anchors genomic data generation infrastructure across North American sequencing centers. Thermo Fisher Scientific, Inc. extends cloud-integrated laboratory informatics that bridge experimental and computational workflows. Schrodinger, Inc. specializes in physics-based molecular simulation platforms that differentiate on accuracy benchmarks for small-molecule design.
Computational biology applies algorithmic modeling, statistical inference, and high-performance simulation to analyze biological systems at molecular, cellular, and organismal scales, relying on machine learning architectures, structural bioinformatics pipelines, and multi-omics data integration frameworks to accelerate hypothesis generation and experimental prioritization. Its primary commercial purpose centers on reducing time-to-insight in therapeutic discovery, agricultural biotechnology, and precision medicine development. Services command premium pricing due to embedded expertise in custom pipeline architecture and regulatory submission support. Drug discovery applications dominate current deployment volumes, while proteomics segments gain traction as mass spectrometry data throughput expands. Cloud deployment models are displacing on-premise installations among mid-tier biotech firms seeking elastic compute access without capital infrastructure commitments.
FDA's emerging framework for AI/ML-based software as a medical device intersects with HIPAA data governance requirements to shape platform validation standards and cross-border data handling protocols for North American vendors. The National Institutes of Health data sharing policy reinforces demand for interoperable database architectures and federated analytics capabilities across multi-institutional research consortia. Stakeholders must monitor evolving FDA guidance on model interpretability and bias documentation as these standards crystallize into de facto market access barriers.
Market Dynamics
FDA's AI-enabled drug development guidance is compressing validation timelines for in silico models while fragmenting vendor capabilities across interpretability documentation requirements. This regulatory pressure is forcing platform providers to restructure their evidence-generation workflows around model bias auditing and cross-study reproducibility standards.
Growth Catalysts
- EPA Tox21 Mandate:The computational toxicology framework decouples wet-lab validation from software-based risk prediction, expanding the addressable base for predictive modeling platforms across chemical safety assessment.
- Massachusetts Biotech Corridor:Concentrated pharmaceutical R&D investment in Cambridge-Boston creates clustered demand for molecular simulation services and federated data infrastructure.
- Multi-Omics Integration:Converging genomics, proteomics, and metabolomics data streams is generating compound analytical workloads that require cloud-native pipeline architectures.
Market Restraints
- GPU Compute Cost Volatility:Fluctuating NVIDIA H100 availability and pricing creates margin pressure for physics-based simulation providers dependent on specialized hardware clusters.
- HIPAA-GDPR Data Friction:Cross-border genomic data handling restrictions between US and Canadian research consortia fragment federated analytics deployments and increase compliance overhead.
- Wet-Lab Validation Bottleneck:Persistent dependency on experimental confirmation for AI-generated hypotheses limits full automation of discovery pipelines and extends customer implementation cycles.
Strategic Opportunities
- California Precision Medicine Hubs:Underpenetrated mid-tier biotech firms in San Diego and South San Francisco seek elastic cloud compute without capital infrastructure commitments.
- NIH Data Sharing Policy:Mandated interoperability requirements create demand for federated database architectures across multi-institutional research networks.
- Quantum-Classical Hybrid Simulation:Early convergence of quantum computing with molecular dynamics algorithms offers first-mover positioning for next-generation binding affinity prediction.
Industry Challenges
- Computational Biology Talent Scarcity:Shortage of professionals bridging machine learning engineering with domain-specific biological expertise constrains platform customization velocity.
- Legacy LIMS Integration Complexity:On-premise laboratory information management systems resist API-native connectivity, forcing expensive middleware development for hybrid cloud deployments.
- Model Interpretability Documentation Burden:FDA's emerging explainability standards require extensive metadata collection that slows algorithm deployment and increases regulatory submission preparation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Computational Biology Market |
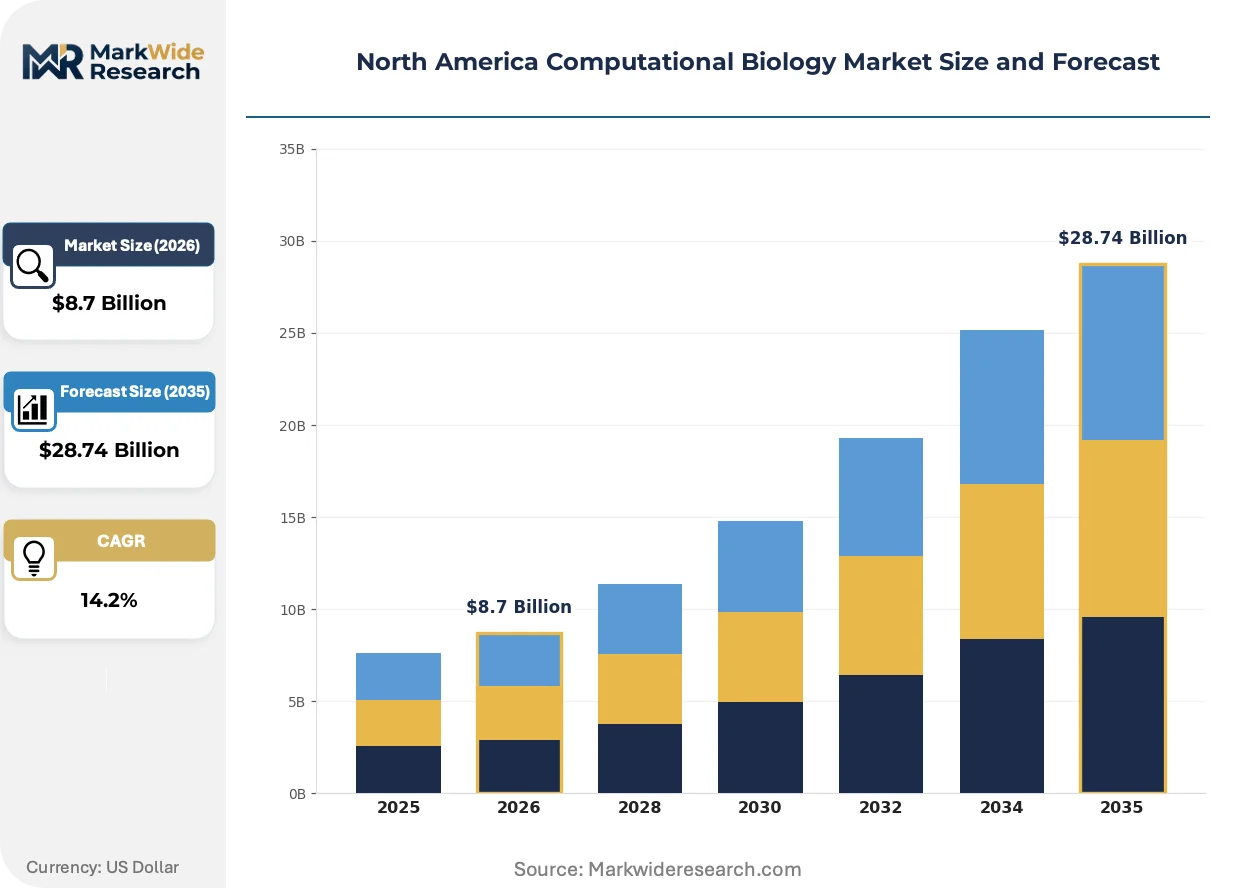
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
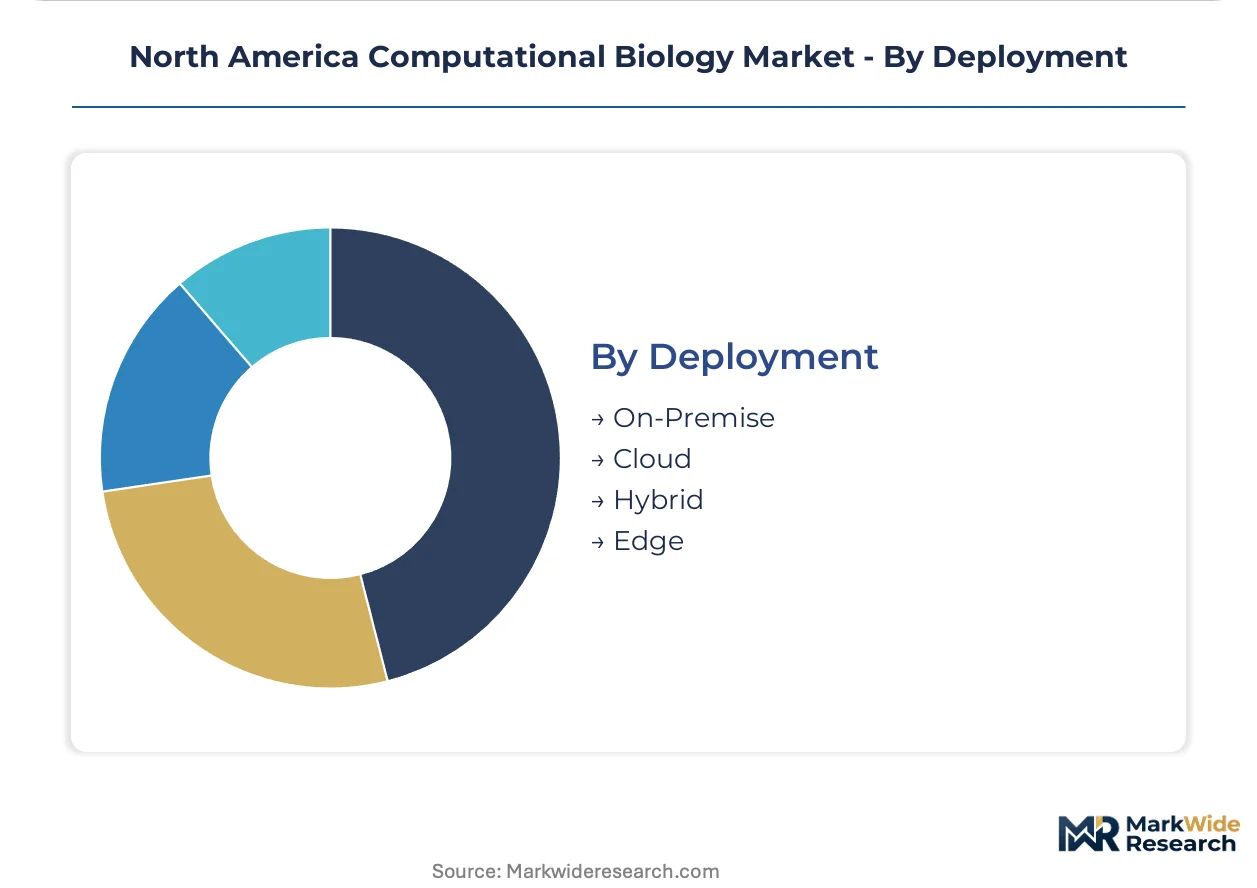
| Segmentation | Product Type: Software, Tools, Databases, Services End User: Pharmaceutical Companies, Research Institutions, Academic Institutions, Biotech Firms Application: Drug Discovery, Genomics, Proteomics, Systems Biology Deployment: On-Premise, Cloud, Hybrid, Edge |
| Companies Covered | DNAnexus, Inc., Illumina, Inc., Thermo Fisher Scientific, Inc., Schrodinger, Inc., QIAGEN, Simulations Plus, Inc., Fios Genomics, Genedata AG, Aganitha AI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Computational Biology Market Evolving Landscape
Cloud-native deployment architectures are fragmenting traditional software licensing models while compressing the timeline from data ingestion to actionable biological insight. Platform providers are restructuring around consumption-based pricing and API-first delivery to capture mid-market biotech demand.
Physics-based molecular simulation is overtaking empirical screening as the primary method for small-molecule lead optimization in pharmaceutical R&D. Large-cap drug developers are adopting GPU-accelerated free energy perturbation calculations at scale, displacing high-throughput crystallography for early-stage binding affinity estimation. This technology shift is compressing the traditional hit-to-lead timeline from months to weeks.
FDA's emerging framework for AI/ML-based software as a medical device is restructuring validation requirements for predictive toxicology platforms. The guidance mandates documented model interpretability and bias assessment, forcing vendors to reengineer their algorithmic transparency layers. Drug discovery applications face the steepest compliance curve, with Massachusetts and California clusters experiencing the earliest enforcement pressure.
Subscription-based access to pre-configured bioinformatics pipelines is displacing perpetual license purchases among mid-tier research institutions. Contract research organizations and regional biotech firms are adopting pay-per-analysis models for variant calling and pathway enrichment, replacing in-house server farms with elastic cloud provisioning. This behavioral shift is most visible in the San Diego and Research Triangle Park clusters, where capital efficiency pressures dominate procurement decisions.
North America Computational Biology Market Segmentation
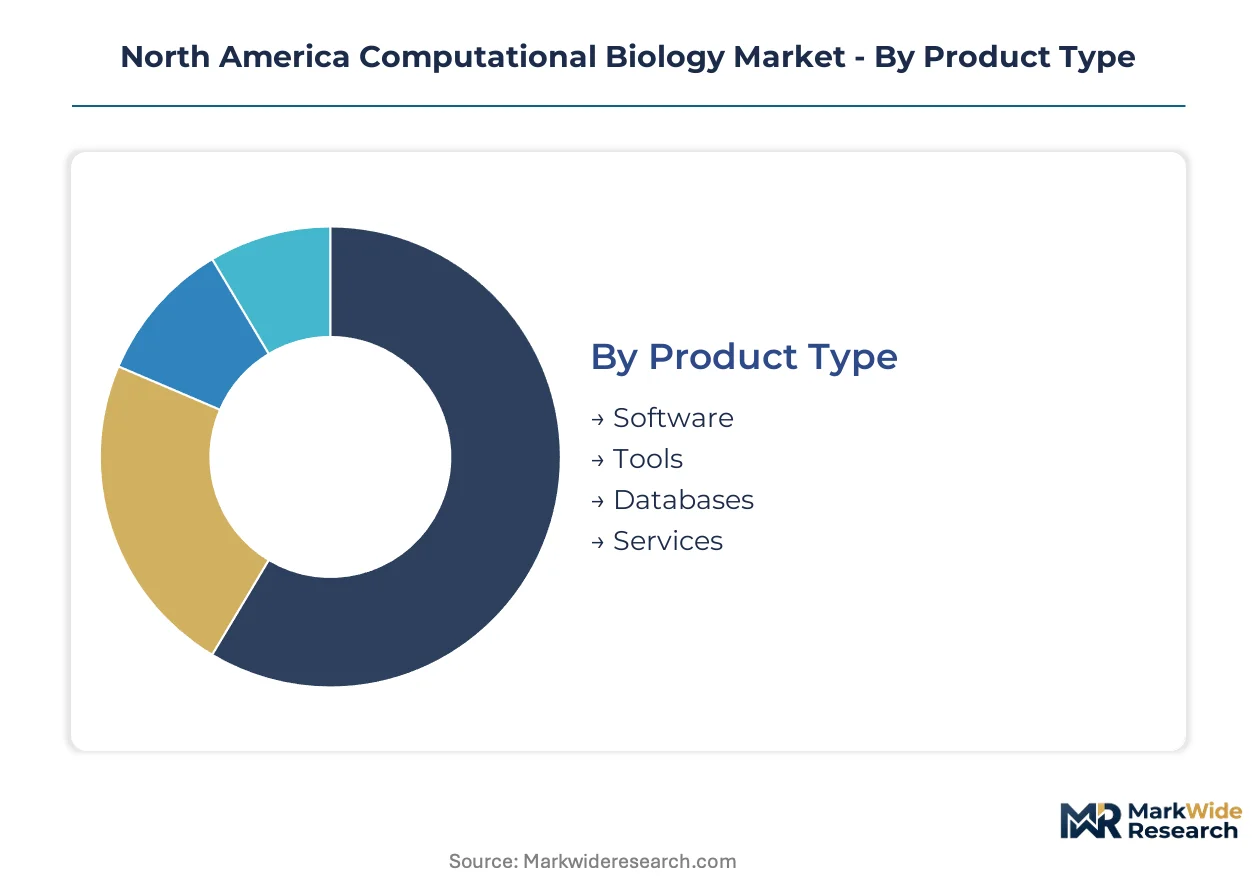
Segmentation in computational biology reveals divergent regulatory pathways and procurement behaviors across product architectures and customer types. FDA validation requirements for AI-enabled drug discovery tools compress timelines for some segments while fragmenting vendor capabilities across interpretability documentation standards.
Product Type:
Certification burdens concentrate heaviest on software platforms seeking FDA recognition as drug development tools, while services face lighter premarket scrutiny but heavier ongoing audit requirements. Databases and tools occupy intermediate compliance tiers depending on their integration into regulated workflows.
- Software:Physics-based molecular simulation suites and machine learning platforms for target identification carry FDA validation mandates under emerging AI/ML-based software guidance. Massachusetts and California biotech corridors drive concentrated procurement of these validated platforms.
- Services:Custom pipeline architecture and regulatory submission support command premium pricing due to embedded expertise scarcity. Research institutions and mid-tier biotech firms in San Diego and Research Triangle Park outsource these capabilities to avoid hiring computational biology talent directly.
- Tools:Pre-configured bioinformatics pipelines for variant calling and pathway analysis face lighter validation burdens when deployed as research-use-only products.
- Databases:Federated genomic data repositories must satisfy NIH data sharing policy interoperability requirements and HIPAA governance standards for cross-institutional access.
Leading the category by volume: Services. Growing fastest: Software.
End User:
Procurement patterns diverge sharply by capital intensity and regulatory exposure, with pharmaceutical companies driving validation-heavy platform adoption while academic institutions prioritize cost elasticity.
- Pharmaceutical Companies:Large-cap developers in Cambridge-Boston and South San Francisco deploy GPU-accelerated free energy perturbation calculations at scale, displacing crystallography for binding affinity estimation. These firms absorb premium pricing for FDA-validated platforms to compress hit-to-lead timelines.
- Biotech Firms:Mid-tier companies across California precision medicine hubs seek consumption-based cloud access without capital infrastructure commitments, favoring API-first delivery models.
- Research Institutions:Multi-institutional consortia require federated analytics architectures compliant with NIH data sharing mandates.
- Academic Institutions:Subscription-based pipeline access displaces perpetual licenses as capital efficiency pressures dominate procurement decisions.
Pharmaceutical companies dominate absolute spending. Biotech firms are expanding most quickly.
Application:
Technology maturity and regulatory clarity vary dramatically across biological scales, with molecular-level applications commanding the steepest compliance investment.
- Drug Discovery:In silico target identification and lead optimization face the steepest FDA compliance curve under emerging AI/ML guidance. Physics-based simulation is overtaking empirical screening as the primary method for small-molecule optimization.
- Proteomics:Mass spectrometry data throughput expansion is generating compound analytical workloads requiring cloud-native architectures.
- Genomics:Variant calling and pathway enrichment analysis operate under established bioinformatics standards with lighter regulatory friction.
- Systems Biology:Multi-omics integration frameworks remain pre-competitive research tools with limited commercial validation requirements.
Drug discovery anchors current revenue concentration. Proteomics is gaining share fastest.
Deployment:
Infrastructure commitments and data governance architectures determine deployment selection, with HIPAA compliance and cross-border data friction shaping hybrid and edge strategies.
- Cloud:Elastic compute provisioning dominates among mid-tier biotech firms seeking to avoid NVIDIA H100 capital commitments. Pay-per-analysis models for genomics and proteomics workloads are displacing in-house server farms.
- Hybrid:On-premise LIMS integration complexity forces expensive middleware development for research institutions bridging legacy systems with cloud-native pipelines.
- On-Premise:Large pharmaceutical developers maintain captive GPU clusters for physics-based simulation requiring low-latency data access.
- Edge:Federated learning architectures for multi-institutional consortia deploy computation at data source to minimize HIPAA-GDPR cross-border transfer restrictions.
Cloud deployment leads current installations. Hybrid architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the majority of computational biology platform consumption while Canada and Mexico supply specialized data infrastructure and nearshore research operations. This production-consumption asymmetry concentrates vendor investment in American biotech corridors while distributing compliance costs across integrated North American research networks.
United States
FDA's AI-enabled drug development guidance and EPA Tox21 mandates drive platform validation demand across pharmaceutical and chemical safety applications. Massachusetts and California biotech corridors anchor concentrated procurement of physics-based molecular simulation and cloud-native bioinformatics pipelines. NIH data sharing policies enforce federated analytics architectures among multi-institutional research consortia spanning Cambridge-Boston and San Diego-South San Francisco clusters.
Canada
Health Canada and PMRA regulatory alignment with FDA frameworks enables cross-border platform deployment for pharmaceutical developers operating integrated North American supply chains. The country's national data governance standards create friction for genomic data transfers with US research networks. Toronto-Waterloo and Vancouver clusters specialize in AI/ML talent pipelines feeding computational biology platform development for multinational vendors.
Mexico
Nearshore research operations for US pharmaceutical companies generate demand for Spanish-language regulatory submission support and localized bioinformatics services. Mexico's federal health regulator COFEPRIS maintains evolving digital health guidance that lags FDA validation standards. Mexico City and Guadalajara metro areas host contract research organizations providing cost-elastic computational support for mid-tier North American biotech firms.
North America Computational Biology Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with captive cloud infrastructure and specialized molecular simulation boutiques. Platform providers fragment across three tiers: integrated instrumentation-software hybrids, pure-play algorithm developers, and contract research service layers. Dominant competitive moves include strategic partnerships bridging legacy laboratory information systems with API-native pipelines and portfolio diversification into adjacent proteomics and metabolomics analytics.
Among instrumentation-software hybrids, Illumina, Inc. and Thermo Fisher Scientific, Inc. anchor genomic data generation and cloud-integrated laboratory informatics respectively. Schrodinger, Inc. occupies a distinct position within physics-based molecular simulation, representing the specialized algorithm developer archetype that competes on accuracy benchmarks for small-molecule design rather than hardware scale.
| Leading Market Players |
|---|
| DNAnexus, Inc. |
| Illumina, Inc. |
| Thermo Fisher Scientific, Inc. |
| Schrodinger, Inc. |
| QIAGEN |
| Simulations Plus, Inc. |
| Fios Genomics |
| Genedata AG |
| Aganitha AI Inc. |
| Others |
Value Network & Pricing Analysis
GPU-accelerated free energy perturbation adoption is simultaneously compressing customer willingness-to-pay for crystallography-based services and concentrating vendor pricing power among NVIDIA H100 cluster operators. This technology transition fragments procurement budgets across legacy hardware depreciation and elastic cloud commitments.
Pricing Analysis
Margin tightening in physics-based simulation reflects NVIDIA H100 availability constraints and specialized talent scarcity. Three-tier pricing structure across FDA-validated platforms, research-use-only tools, and custom consulting services segments procurement by regulatory exposure. Cost compression in on-premise installations accelerates as mid-tier biotech firms abandon capital commitments for pay-per-analysis cloud models. Academic institutions exhibit highest price sensitivity; large-cap pharmaceutical developers absorb premium validated-platform pricing.
Supply Chain Analysis
Refurbished GPU clusters and remanufactured sequencing hardware flow through secondary markets serving mid-tier research institutions with depreciated capital budgets. Supply concentrates in the United States for cloud infrastructure, Taiwan for NVIDIA GPU fabrication, and China for rare earth components in magnetic storage systems. Raw material dependencies span high-bandwidth memory modules, specialized cooling systems, and genomic reagent chemicals. Single-source vulnerability in NVIDIA H100 production creates procurement risk. Distribution runs through direct vendor relationships for large pharmaceutical developers and channel partners for regional biotech firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational biology platform supply is constrained by GPU cluster scarcity and cross-trained machine learning-biology talent shortages, propping pricing power for validated-platform vendors. Capacity expansion in cloud-native architectures remains the critical bottleneck.
For Market Incumbents: Anchor FDA validation timelines as competitive moats against emerging algorithm developers lacking regulatory submission experience. Deepen backward integration into captive GPU cluster operations to defend margin position against NVIDIA supply volatility. Incumbent platform providers face substitution threat from quantum-classical hybrid simulation startups. For New Entrants and Emerging Players: Capture underpenetrated mid-tier biotech firms in California precision medicine hubs seeking consumption-based cloud access without capital infrastructure. Target federated analytics deployments for multi-institutional consortia constrained by HIPAA-GDPR data friction. Go-to-market angle: API-first delivery with pre-configured bioinformatics pipelines displacing in-house server farms. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life science conglomerates seeking algorithmic capabilities complementary to captive instrumentation hardware. Long-term viability favors specialized molecular simulation boutiques with FDA-validated platforms over generic bioinformatics service layers. Signal to watch: quantum computing convergence with molecular dynamics algorithms as inflection indicator for next-generation binding affinity prediction relevance.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Validation Pathway Investment | Compresses time-to-market for AI-enabled drug development tools in Massachusetts and California corridors. |
| Cloud-Native Platform Integration | Captures mid-tier biotech demand through elastic compute provisioning without NVIDIA H100 capital commitments. |
| Strategic Partnership with LIMS Vendors | Bridges legacy on-premise laboratory systems with API-native pipelines for hybrid deployment architectures. |
| Acquisition of Quantum Simulation Specialist | Positions first-mover advantage in quantum-classical hybrid binding affinity prediction algorithms. |
| Geographic Expansion to Research Triangle Park | Accesses subscription-based pipeline demand from capital-constrained academic institutions. |
Research Methodology
SEC filings, FDA guidance documents, and NIH data sharing policy frameworks formed the secondary backbone for market sizing and regulatory trajectory assessment. Primary interviews with drug development executives, regulatory affairs leads, computational biology platform engineers, and hospital procurement managers validated demand assumptions. Bottom-up triangulation across vendor revenue disclosures and top-down cross-check against pharmaceutical R&D expenditure trends anchored forecast confidence.
Historical trendline analysis of bioinformatics platform adoption rates informed projection modeling across the analysis window. Segmentation dimensions included product type, end user archetype, application area, and deployment model complexity. CAGRs derived from weighted averaging of technology diffusion curves and regulatory timeline acceleration. Industry-specific inputs incorporated EPA Tox21 mandate implementation pace and FDA AI/ML software guidance evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to quantum computing commercialization timelines and HIPAA-GDPR regulatory harmonization progress. Practitioners should monitor NVIDIA GPU supply allocation policies and FDA model interpretability standard crystallization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
Bioinformatics Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
US Computational Biology Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
China Computational Biology Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
Europe AI in Life Science Analytics Market