
 Mexico Diabetes Drugs Market | 2026-2036
Mexico Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Diabetes Drugs Market Foresight
Continuous glucose monitoring integration with smart insulin delivery systems is reconfiguring diabetes management protocols across Mexican healthcare networks. Novo Nordisk A/S leverages its established insulin manufacturing infrastructure to anchor supply security for public sector tenders. Eli Lilly and Company competes through differentiated GLP-1 receptor agonist portfolios targeting Type 2 diabetes progression. Sanofi S.A. sustains broad channel coverage across both hospital formulary placements and retail pharmacy networks.
Mexico diabetes drugs encompass pharmaceutical agents engineered to regulate blood glucose through hormonal modulation, enzymatic inhibition, or renal glucose excretion, with formulations requiring precise bioequivalence standards and cold-chain stability for biologic products. These therapies serve to prevent microvascular complications, reduce hospitalization rates, and extend patient survival in chronic metabolic disease management. Insulin formulations retain dominant volume share due to universal Type 1 diabetes necessity and late-stage Type 2 diabetes progression, while SGLT2 inhibitors represent the fastest-expanding margin pool driven by cardiovascular outcome benefits. Oral administration routes command preference for early-stage Type 2 diabetes therapy initiation, though subcutaneous delivery sustains premium positioning for GLP-1 agonists in weight-managed care protocols.
COFEPRIS maintains centralized authority over pharmaceutical registration, with specific biosimilar approval pathways that shape competitive entry timelines for insulin analogue manufacturers. Mexico's national health institutes, including IMSS and ISSSTE, operate procurement frameworks that directly determine volume allocation across public hospital and clinic networks. Stakeholders must monitor evolving reimbursement negotiations between federal health institutions and international pharmaceutical suppliers, as pricing settlements will determine accessible patient volumes and manufacturer revenue realization across the forecast horizon.
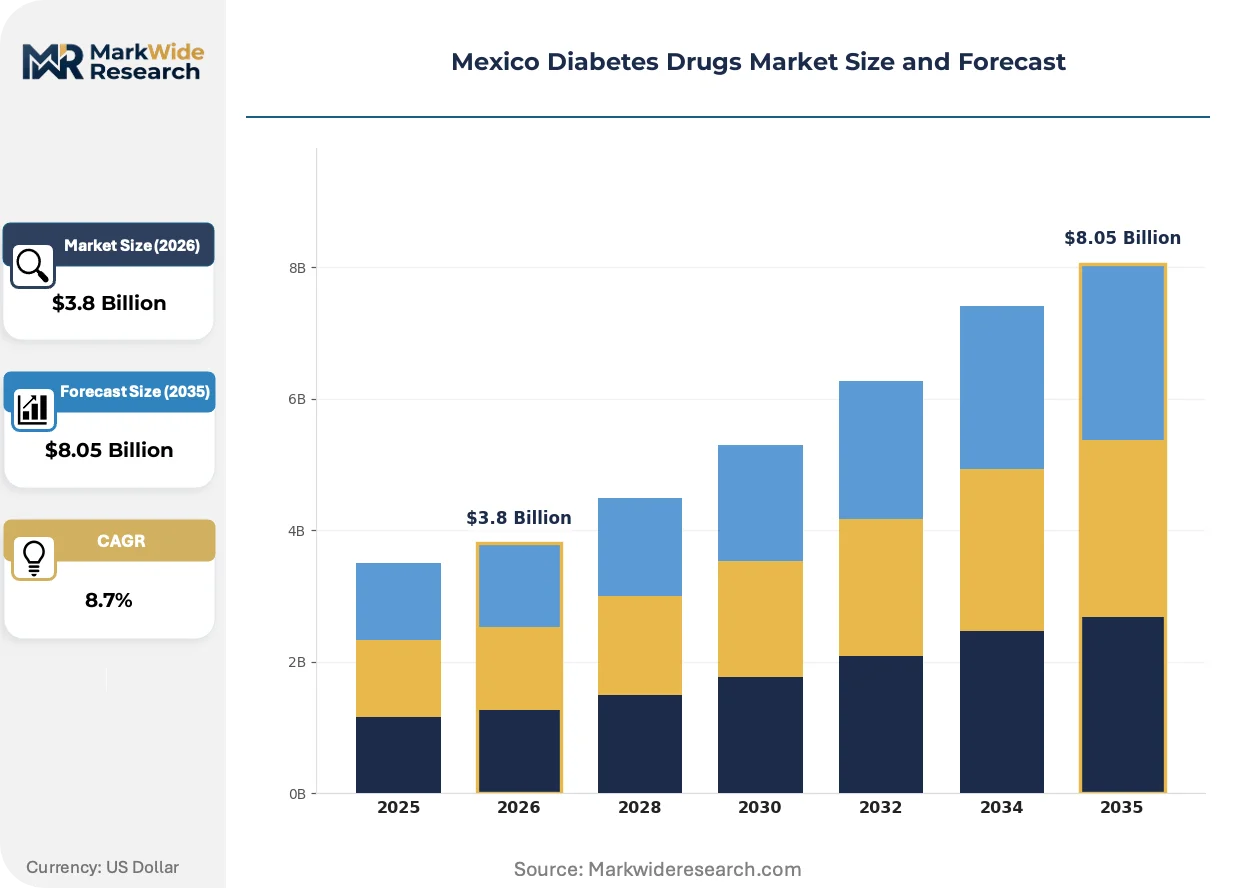
Market Dynamics
COFEPRIS biosimilar approval streamlining is compressing insulin analogue entry timelines while IMSS procurement centralization concentrates volume allocation power within Mexico's public hospital networks.
Growth Catalysts
- COFEPRIS Regulatory Streamlining:The centralized pharmaceutical regulator has established dedicated biosimilar pathways that accelerate insulin analogue registrations. Public hospital systems now access expanded therapeutic options faster.
- Specialized Endocrinology Clustering:Mexico City and Guadalajara concentrate advanced diabetes care infrastructure. Private insurance penetration in these metropolitan zones supports premium therapy uptake.
- Continuous Glucose Monitoring Integration:Smart insulin delivery systems are reconfiguring management protocols across Mexican healthcare networks. Hospital formulary placements increasingly favor device-drug combinations.
Market Restraints
- Cold-Chain Infrastructure Gaps:Biologic insulin formulations require precise temperature stability that rural pharmacy networks struggle to maintain. Distribution losses concentrate in southern Mexican states.
- Public Procurement Price Compression:IMSS and ISSSTE tender frameworks impose aggressive cost ceilings on international suppliers. Margin pressure intensifies for premium analogue portfolios.
- Substitution Threat from Traditional Sulfonylureas:Generic oral agents retain formulary preference in early-stage Type 2 diabetes. Physician prescribing inertia delays GLP-1 agonist adoption.
Strategic Opportunities
- Underpenetrated Northern Border States:Chihuahua and Baja California exhibit lower specialist density per capita. Cross-border health infrastructure investments could expand access corridors.
- Retail Pharmacy Channel Expansion:Private pharmacy chains are building chronic disease management capabilities. Direct-to-patient dispensing bypasses hospital procurement bottlenecks.
- Cardiovascular Outcome Labeling:SGLT2 inhibitors with proven heart failure benefits command premium positioning. COFEPRIS is accelerating reviews for therapies with outcome data.
Industry Challenges
- Endocrinology Specialist Scarcity:Mexico trains insufficient diabetologists relative to patient prevalence. Rural primary care physicians manage complex insulin regimens without specialist backup.
- Bioequivalence Certification Complexity:COFEPRIS requires extensive local clinical data for biosimilar approvals. Study execution timelines extend registration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Diabetes Drugs Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors Administration Route: Oral, Subcutaneous, Intravenous, Inhalation End User: Hospitals, Clinics, Home Care, Pharmacy Patient Type: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Others |
| Companies Covered | Novo Nordisk A/S, Sanofi S.A., Eli Lilly and Company, Boehringer Ingelheim, AstraZeneca plc, Merck & Co., Inc., Takeda Pharmaceutical Company Limited, Novartis AG, Bayer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Diabetes Drugs Market Shifts & Advancements
Technology convergence between glucose sensors and automated insulin delivery is collapsing traditional care boundaries while regulatory acceleration and procurement centralization reshape competitive access.
Smart insulin pens integrated with mobile glucose data are collapsing the distinction between hospital-managed and self-directed diabetes care. IMSS pilot programs in Mexico City are deploying these connected devices to reduce hypoglycemic emergency admissions. The technology is collapsing reimbursement silos as payers recognize remote monitoring cost offsets.
COFEPRIS has implemented expedited review tracks for therapies demonstrating cardiovascular or renal protective outcomes beyond glucose lowering. SGLT2 inhibitors and select GLP-1 agonists benefit from compressed evaluation timelines. Manufacturers are prioritizing Mexico submissions for agents with outcome trial data to capture formulary preference.
Hospital pharmacy directors are consolidating insulin purchasing through IMSS national tenders rather than facility-level procurement. Volume concentration enables price negotiation leverage but reduces formulary flexibility for individual hospitals. The shift is most visible in Mexico City metropolitan hospitals where procurement centralization completed in 2024.
Mexico Diabetes Drugs Market Segmentation
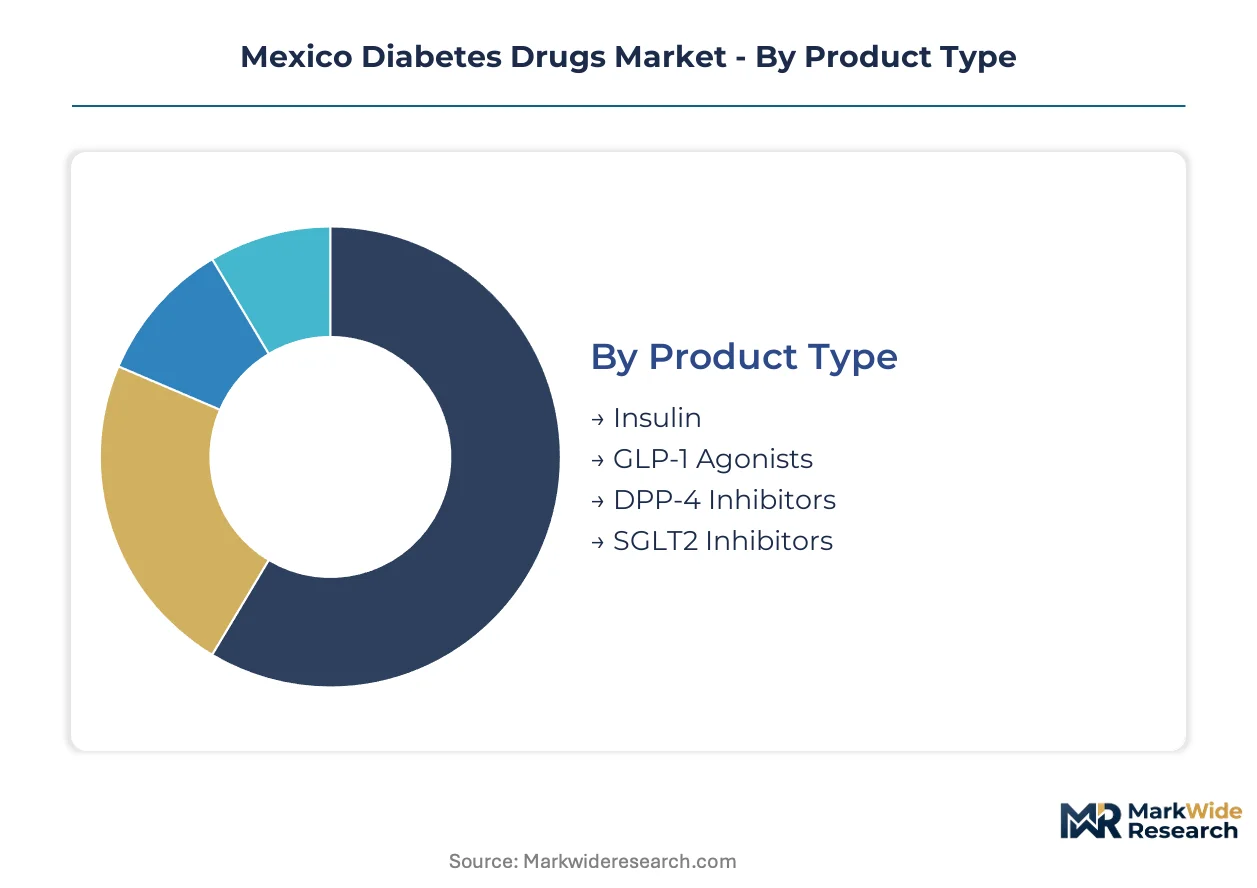
Segmentation reveals how therapeutic positioning, delivery modality, and care setting intersect to determine pricing power and patient access across Mexico's fragmented health system. Each dimension carries distinct regulatory, reimbursement, and infrastructure requirements that shape manufacturer go-to-market strategy.
Product Type:
Cycle times vary sharply across therapeutic classes, with biologic insulins requiring extended cold-chain logistics while small-molecule inhibitors turn through retail pharmacy channels rapidly.
- Insulin:Recombinant human and analogue formulations requiring precise bioequivalence certification through COFEPRIS pathways. Demand concentrates in IMSS hospital networks where centralized tenders allocate volume to qualified suppliers, though cold-chain gaps in Chiapas and Oaxaca limit rural penetration.
- SGLT2 Inhibitors:Oral sodium-glucose cotransporter-2 blockers with demonstrated cardiovascular outcome benefits. Prescribing clusters in Mexico City endocrinology centers where private insurance reimbursement supports premium positioning, with COFEPRIS accelerating reviews for agents with heart failure data.
- GLP-1 Agonists:Injectable glucagon-like peptide-1 receptor agonists for weight-managed Type 2 diabetes protocols.
- DPP-4 Inhibitors:Oral dipeptidyl peptidase-4 inhibitors competing with generics in early-stage therapy.
Insulin anchors the volume base while SGLT2 inhibitors gain share at the steepest rate.
Administration Route:
Cost tiers separate hospital-administered intravenous therapies from self-managed oral and subcutaneous options, with reimbursement differentials driving channel selection.
- Oral:Small-molecule tablets and capsules dominating early Type 2 diabetes management. Patient preference for non-injectable therapy sustains formulary placement despite glycemic efficacy limitations, with retail pharmacy dispensing bypassing hospital procurement bottlenecks in Guadalajara metropolitan zones.
- Subcutaneous:Injectable delivery for insulin and GLP-1 agonists requiring patient training. Smart pen integration with mobile glucose monitoring is reconfiguring self-care protocols across ISSSTE beneficiary populations in northern border states.
- Intravenous:Hospital-controlled infusion for acute hyperglycemic emergencies and perioperative management.
- Inhalation:Alternative delivery for rapid-acting insulin analogues with limited formulary uptake.
Oral administration captures the broadest patient base while subcutaneous delivery commands the premium pricing tier.
End User:
Customer type determines procurement leverage, with federal health institutions imposing price compression that private channels escape.
- Hospitals:Public and private acute-care facilities managing complex insulin regimens and diabetic complications. IMSS national tender consolidation in Mexico City metropolitan hospitals has compressed formulary flexibility while concentrating volume allocation power.
- Pharmacy:Retail chains and independent dispensaries serving chronic medication refills. Private pharmacy expansion into chronic disease management is building direct-to-patient dispensing capabilities that circumvent hospital procurement delays.
- Clinics:Outpatient specialty and primary care settings for therapy initiation and monitoring.
- Home Care:Self-directed management with remote monitoring support for stable patients.
Hospitals anchor the volume base while pharmacy channels expand most quickly as dispensing bypasses institutional procurement.
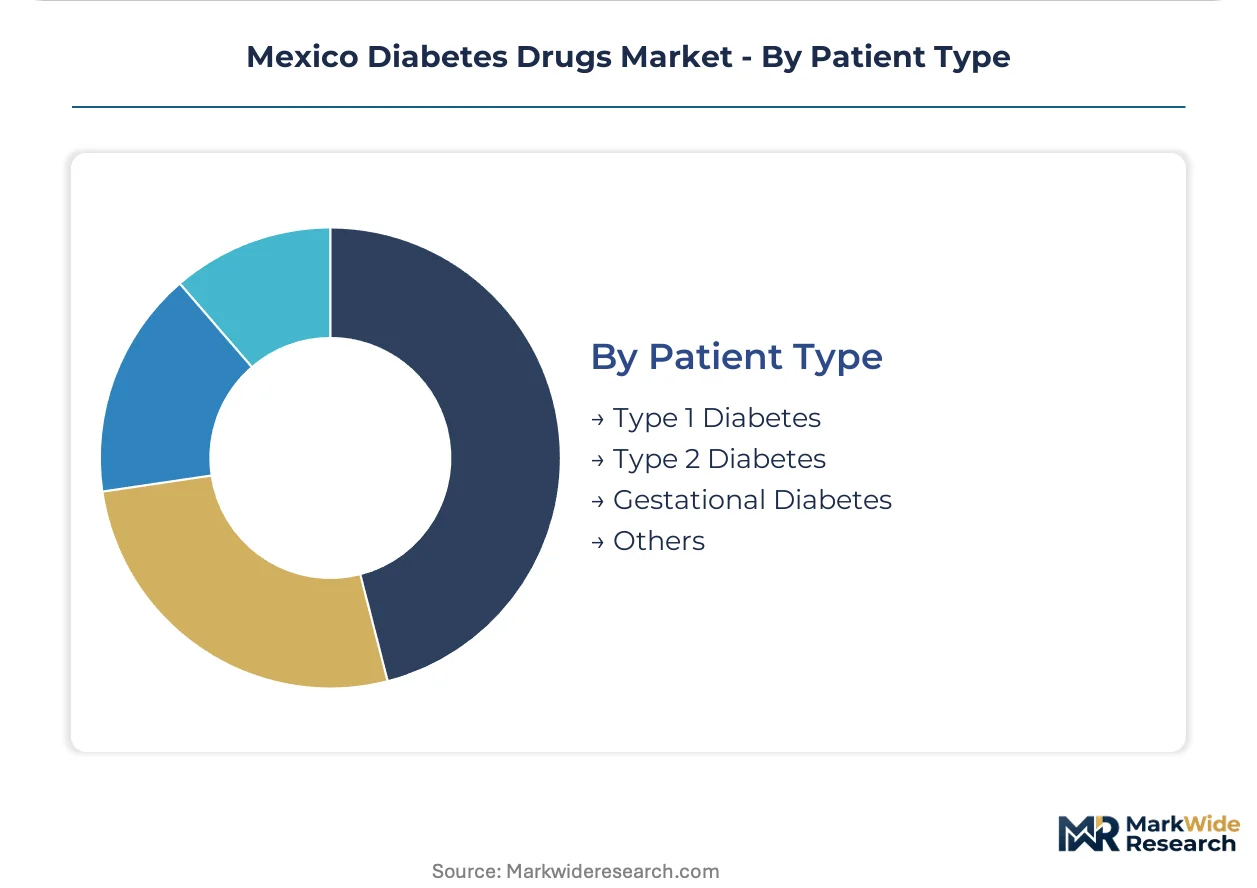
Patient Type:
Maturity separates established Type 1 and Type 2 diabetes populations from emerging gestational diabetes protocols requiring distinct clinical pathways.
- Type 2 Diabetes:Progressive insulin resistance and beta-cell dysfunction representing the dominant patient population. Late-stage progression to insulin dependence concentrates demand in public hospital systems where IMSS formulary decisions determine analogue access.
- Type 1 Diabetes:Autoimmune beta-cell destruction requiring lifelong exogenous insulin. Absolute insulin necessity shields this population from substitution pressure, though supply security depends on COFEPRIS-registered manufacturing infrastructure.
- Gestational Diabetes:Glucose intolerance during pregnancy with specific maternal-fetal risk protocols.
- Others:Secondary diabetes forms including pancreatic and steroid-induced variants.
Type 2 diabetes anchors the volume base while gestational diabetes protocols gain specialist attention for early intervention expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border pharmaceutical flows from the United States supply insulin analogues and GLP-1 agonists to northern Mexican states, while domestic manufacturing clusters in Mexico City and Guadalajara anchor distribution networks serving central and southern regions.
Mexico City Metro
Specialized endocrinology centers concentrate patient volume for advanced glucose-lowering therapies. COFEPRIS regulatory headquarters accelerates biosimilar approvals for insulin manufacturers. Hospital procurement centralization through IMSS national tenders completed in 2024, compressing formulary flexibility while concentrating volume allocation power.
Jalisco
Guadalajara hosts the second-largest diabetes care infrastructure cluster after the capital. Private insurance penetration supports premium therapy uptake for SGLT2 inhibitors and GLP-1 agonists. Retail pharmacy chains are building chronic disease management capabilities that bypass hospital procurement bottlenecks.
Nuevo León
Monterrey's industrial base attracts pharmaceutical distribution investments serving northeastern states. The state's higher per-capita income correlates with earlier adoption of continuous glucose monitoring systems. Cross-border health infrastructure with Texas creates access corridors for device-drug combinations.
Northern Border States
Chihuahua and Baja California exhibit lower endocrinology specialist density per capita relative to patient prevalence. Cold-chain infrastructure gaps limit biologic insulin penetration into rural pharmacy networks. Federal health institutions are piloting telemedicine protocols to extend specialist reach.
Bajío Region
Guanajuato and Querétaro manufacturing zones host pharmaceutical packaging and distribution facilities. Generic oral agent dispensing dominates early-stage Type 2 diabetes management through retail channels. Physician prescribing inertia delays GLP-1 agonist adoption despite cardiovascular outcome benefits.
Mexico Diabetes Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Mexico's fragmented procurement environment. The market structure tilts toward consolidated supply through IMSS national tenders, yet retail pharmacy expansion creates parallel access corridors. Three archetypes dominate: multinational biopharmaceuticals with established insulin manufacturing infrastructure, mid-scale generic specialists capturing oral agent volume, and emerging biosimilar challengers leveraging COFEPRIS streamlining. Competitive moves concentrate on securing hospital formulary placement and building direct-to-patient dispensing capabilities.
Among the established multinational tier, Novo Nordisk A/S and Sanofi S.A. occupy positions anchored by insulin supply security for public sector tenders. Eli Lilly and Company exemplifies the differentiated portfolio archetype through GLP-1 receptor agonist positioning. These three entities represent the dominant competitive anchors shaping pricing negotiations with federal health institutions.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi S.A. |
| Eli Lilly and Company |
| Boehringer Ingelheim |
| AstraZeneca plc |
| Merck & Co., Inc. |
| Takeda Pharmaceutical Company Limited |
| Novartis AG |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Overcapacity in recombinant insulin manufacturing across Mexican domestic facilities is compressing supplier margins while amplifying IMSS tender leverage. This utilization dynamic forces international manufacturers toward cost-plus contract structures indexed to active pharmaceutical ingredient benchmarks, reshaping how volume allocations translate into realized revenue.
Pricing Analysis
Cost-plus contracts with API indexation dominate IMSS national tenders, binding supplier margins to international raw material benchmarks. Price differentiation rests on cold-chain certification tiers and bioequivalence study completion status, with fully certified analogue portfolios commanding premium positioning against provisional registrations. Cost compression in the public hospital tier is intensifying because IMSS consolidated procurement eliminated facility-level negotiation flexibility. Generic oral agent manufacturers exhibit the highest price sensitivity due to substitution-ready sulfonylurea alternatives, while GLP-1 agonist suppliers face lower sensitivity given weight-management protocol stickiness.
Supply Chain Analysis
Export-control restrictions on continuous glucose monitoring sensor technology from the United States limit northern border state access corridors. Active pharmaceutical ingredient supply concentrates in India and China for small-molecule inhibitors, while biologic insulin fermentation draws from Denmark, France, and domestic Mexican fill-finish operations. Distribution runs through IMSS central warehouses for hospital networks and Grupo Farmacéutico Maypo regional depots for retail channels. Single-source vulnerability in temperature-controlled last-mile logistics for rural Chiapas and Oaxaca pharmacy networks constitutes the primary structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's diabetes drugs market functions as a service-attach opportunity where remote patient monitoring subscriptions and smart pen data analytics expand faster than standalone pharmaceutical volumes. This recurring-revenue layer justifies capital deployment toward integrated device-drug combination platforms.
For Market Incumbents: Pre-empt biosimilar challengers by securing exclusive IMSS tender line extensions for insulin analogue portfolios with cardiovascular outcome labeling. Anchor supply security through backward integration into active pharmaceutical ingredient fermentation within Mexican industrial parks. The priority lever is cold-chain infrastructure investment in southern states where distribution losses currently exclude rural populations from biologic access. For New Entrants and Emerging Players: Northern border state specialist scarcity presents the most penetrable white-space target, with Chihuahua and Baja California exhibiting endocrinologist density gaps relative to patient prevalence. Retail pharmacy chronic disease management capabilities in Guadalajara metropolitan zones offer a secondary entry corridor. The optimal go-to-market angle pairs telemedicine-enabled insulin titration support with direct-to-patient dispensing bypassing hospital procurement bottlenecks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale biosimilar specialists with COFEPRIS registration momentum and established hospital formulary relationships. Long-term viability across the analysis window hinges on cardiovascular outcome trial data positioning for SGLT2 inhibitor and GLP-1 agonist portfolios. The signal to watch is IMSS reimbursement negotiation outcomes for device-drug combinations, which would validate integrated platform economics. Cross-checking against COFEPRIS biosimilar approval velocity is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Biosimilar Registration Pathway | Accelerated insulin analogue approvals compress competitive entry timelines against originator portfolios. |
| IMSS Hospital System Partnership | National tender consolidation concentrates volume allocation power for formulary placement security. |
| Smart Insulin Pen Software Companion | Mobile glucose data integration collapses reimbursement silos through remote monitoring cost offsets. |
| Backward Integration into API Manufacturing | Domestic fermentation capacity anchors supply security for public sector tender participation. |
| Cardiovascular Outcome Labeling Strategy | COFEPRIS expedited review tracks reward heart failure data with formulary preference positioning. |
Research Methodology
Operator-level perspectives from formulary directors at IMSS and ISSSTE institutions, COFEPRIS regulatory affairs leads, hospital procurement managers, and retail pharmacy chain category heads anchored the qualitative base. Secondary validation drew from COFEPRIS registration databases, IMSS tender documentation, ClinicalTrials.gov outcome trial records, and SEC 10-K pharmaceutical segment disclosures. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation converged on segment-level estimates.
Scenario-bracketing around IMSS reimbursement negotiation outcomes and COFEPRIS biosimilar approval velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include therapeutic class, administration route, end-user setting, and regional regulatory cluster. CAGRs derived from treatment line progression rates and formulary adoption curves. Forecast inputs incorporated diabetes prevalence projections from national health surveys and specialist density mapping by metropolitan zone.
The forecast holds incumbent behavior within observed patterns; aggressive moves by emerging biosimilar challengers with vertical integration into API manufacturing would shift outcomes beyond modeled ranges. Cross-checking against IMSS national health expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market