
 Contract Pharmaceutical Fermentation Services Market | 2026-2036
Contract Pharmaceutical Fermentation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Pharmaceutical Fermentation Services Market Analysis
The capital-intensity divergence between microbial and mammalian cell culture capabilities is redrawing competitive boundaries among contract fermentation providers. Lonza leverages its integrated biologics network to sustain multi-thousand-liter stainless steel capacity across European and North American sites. Boehringer Ingelheim anchors its position through captive microbial fermentation expertise tied to veterinary and human health APIs. Fujifilm Diosynth Biotechnologies differentiates via single-use platform investments that reduce cross-contamination risks for multiproduct facilities.
Contract pharmaceutical fermentation services encompass the outsourced production of active pharmaceutical ingredients, intermediates, and biologics using microbial or cell-based culture systems, typically operating at scales from 1,000 to 20,000 liters with precise control of temperature, pH, dissolved oxygen, and nutrient feed rates to maximize titer and yield. These services supply therapeutic proteins, antibiotics, and enzymes to developers lacking in-house biomanufacturing infrastructure. Fed-batch fermentation dominates current revenue contribution due to its proven scalability for high-cell-density E. coli and yeast processes. Biopharmaceuticals represent the fastest-expanding product category as gene therapy and vaccine developers outsource plasmid DNA and viral vector production. Continuous fermentation occupies a niche but growing position where real-time process analytical technology enables steady-state operation for commodity APIs.
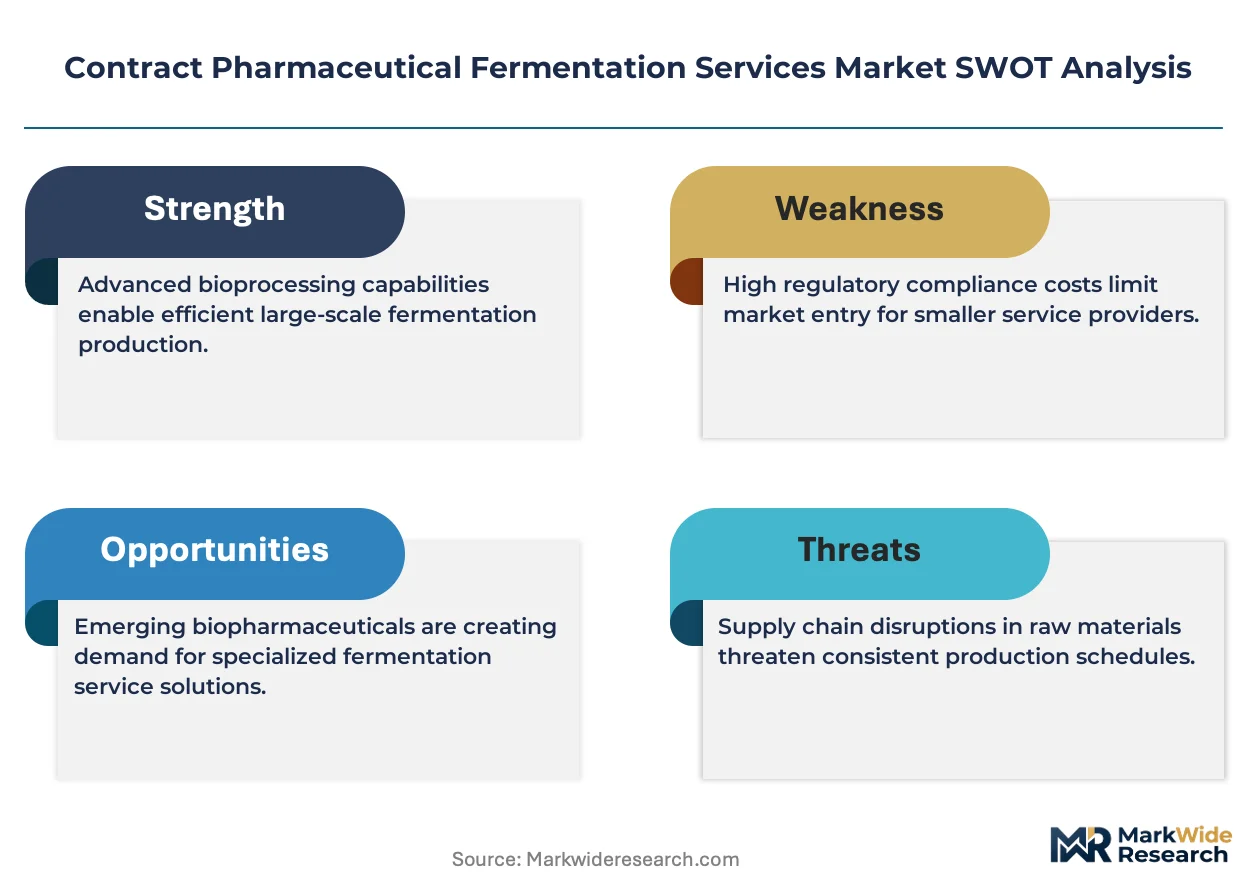
FDA current Good Manufacturing Practice requirements and EMA's Annex 1 revisions on sterile manufacturing impose validation burdens that filter out smaller fermentation contractors. The EPA regulates discharge from antibiotic fermentation facilities through effluent limitations guidelines, particularly affecting bulk manufacturing sites in the United States. India's CDSCO mandates fermentation-derived drug master file submissions that align with WHO prequalification standards for export-oriented suppliers. Stakeholders must monitor how regulatory divergence between FDA process validation expectations and EMA's quality-by-design enforcement affects site selection and technology transfer timelines.
Market Dynamics
Biopharmaceutical developers are consolidating manufacturing partnerships around single-use bioreactor platforms that compress facility changeover timelines from weeks to days. This technology pivot is redrawing supplier qualification hierarchies and forcing capital reallocation toward flexible capacity.
Growth Catalysts
- Domestic Manufacturing Incentives:The IRA's production tax credits for U.S.-based biologics manufacturing are accelerating site qualification decisions among contract fermentation providers serving FDA-regulated sponsors.
- Cell and Gene Therapy Pipelines:Viral vector and plasmid DNA demand from gene therapy developers is pulling capacity investments toward mammalian and microbial platforms capable of GMP-grade nucleic acid production.
- Process Analytical Technology Integration:Real-time titer monitoring and automated nutrient feed control are elevating batch consistency metrics that determine contract renewal rates.
Market Restraints
- Stainless Steel Capital Lock-In:Legacy multi-thousand-liter fixed bioreactor installations impose depreciation burdens that constrain rapid platform transitions toward single-use alternatives.
- Specialized Talent Scarcity:Fermentation scientists with hybrid expertise in both microbial and mammalian culture systems command compensation premiums that compress contract margins.
- Antibiotic Fermentation Effluent Rules:EPA discharge limitations for bulk antibiotic manufacturing sites impose wastewater treatment capex that filters out smaller contractors in the United States.
Strategic Opportunities
- India Export Manufacturing:CDSCO-aligned drug master file pathways for fermentation-derived APIs position Indian contractors to capture WHO prequalification-driven volume from African and Southeast Asian procurement programs.
- Continuous Processing Platforms:Steady-state perfusion bioreactor technology offers titer advantages for commodity therapeutic proteins that fed-batch systems cannot match.
- Dual-Use Microbial Capacity:Fermentation infrastructure qualified for both veterinary and human health APIs enables revenue diversification across product lifecycle volatility.
Industry Challenges
- Technology Transfer Timeline Compression:Sponsor demands for 12-month campaign initiation are colliding with 18-24 month EMA Annex 1 validation requirements for sterile manufacturing suites.
- Single-Use Supply Concentration:Film and bag assembly sourcing from limited qualified suppliers creates vulnerability to resin allocation disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Pharmaceutical Fermentation Services Market |
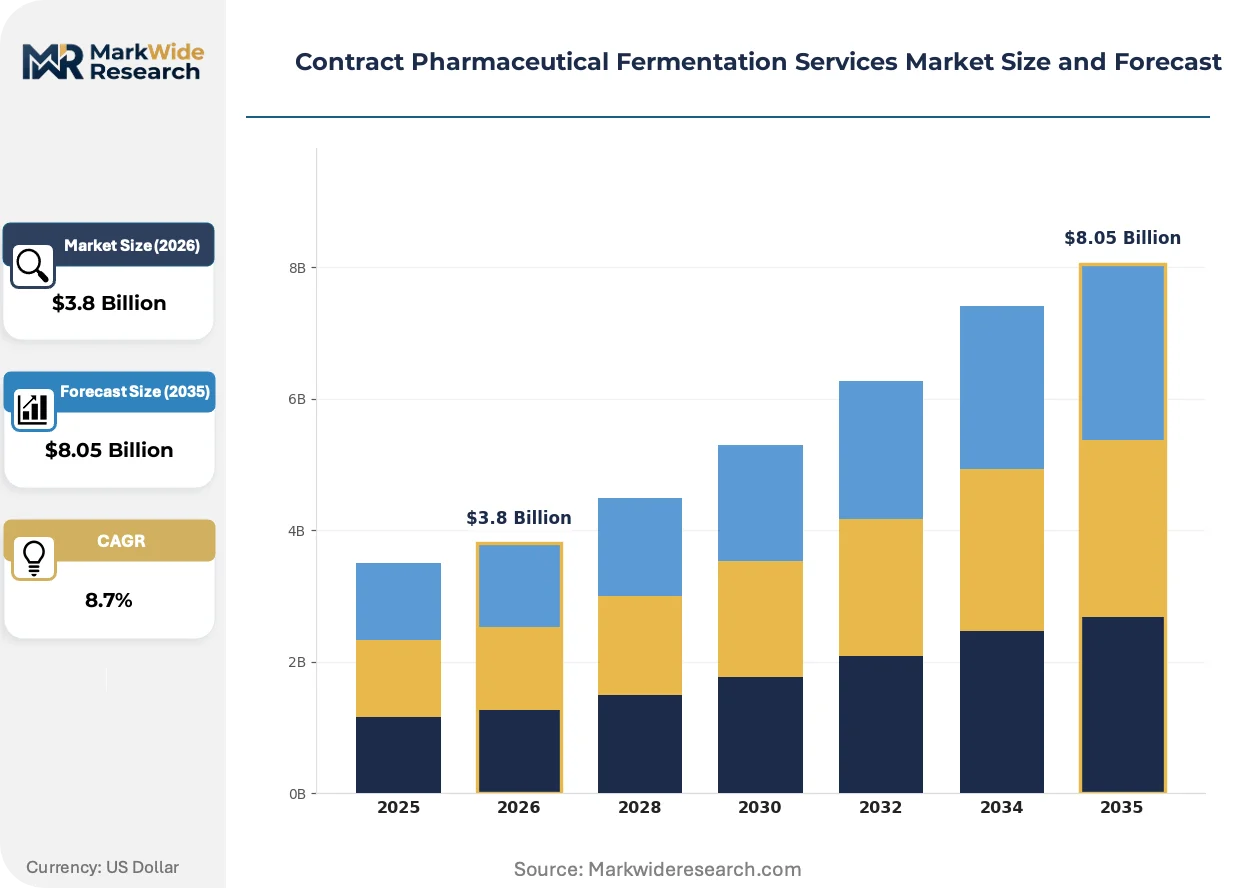
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Batch Fermentation, Continuous Fermentation, Fed-Batch Fermentation, Solid-State Fermentation Product Type: Antibiotics, Amino Acids, Biopharmaceuticals, Enzymes End User: Biotech Companies, Pharmaceutical Companies, Research Institutions, Contract Manufacturing Organizations Application: Therapeutics, Vaccines, Diagnostics, Agrochemicals |
| Companies Covered | AMRI, Biocon, Lonza, Fujifilm Diosynth Biotechnologies, Aumgene Biosciences, Boehringer Ingelheim, CordenPharma, Pfizer CentreOne, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Pharmaceutical Fermentation Services Market Emerging Trajectories
Process intensification strategies are compressing facility footprints while elevating output density, forcing contract providers to reengineer spatial economics and automation architectures simultaneously.
Single-use bioreactor assemblies are supplanting stainless steel trains in multiproduct facilities where campaign flexibility outweighs unit cost minimization. Gene therapy sponsors are specifying disposable platforms for Phase III viral vector manufacturing to eliminate cross-contamination documentation burdens. This shift is compressing the payback period justification for fixed capital investments and elevating supplier relationships with film and sensor component vendors.
EMA's Annex 1 revision on sterile manufacturing is mandating barrier technology and continuous environmental monitoring systems that extend facility qualification timelines. The regulation imposes contamination control strategy documentation requirements that favor contractors with established quality management system maturity. Mammalian cell culture suites in European facilities are prioritizing isolator-based filling lines over conventional cleanroom architectures to preempt inspection findings.
Biopharmaceutical sponsors are unbundling analytical testing from manufacturing contracts and awarding CMC packages to specialized bioanalytical providers with platform method validation libraries. This disaggregation is fragmenting the traditional full-service CDMO value proposition and compressing the addressable revenue per development program. United States-based emerging biotechnology companies are driving this pattern most aggressively as they conserve capital for clinical trial execution.
Contract Pharmaceutical Fermentation Services Market Segmentation
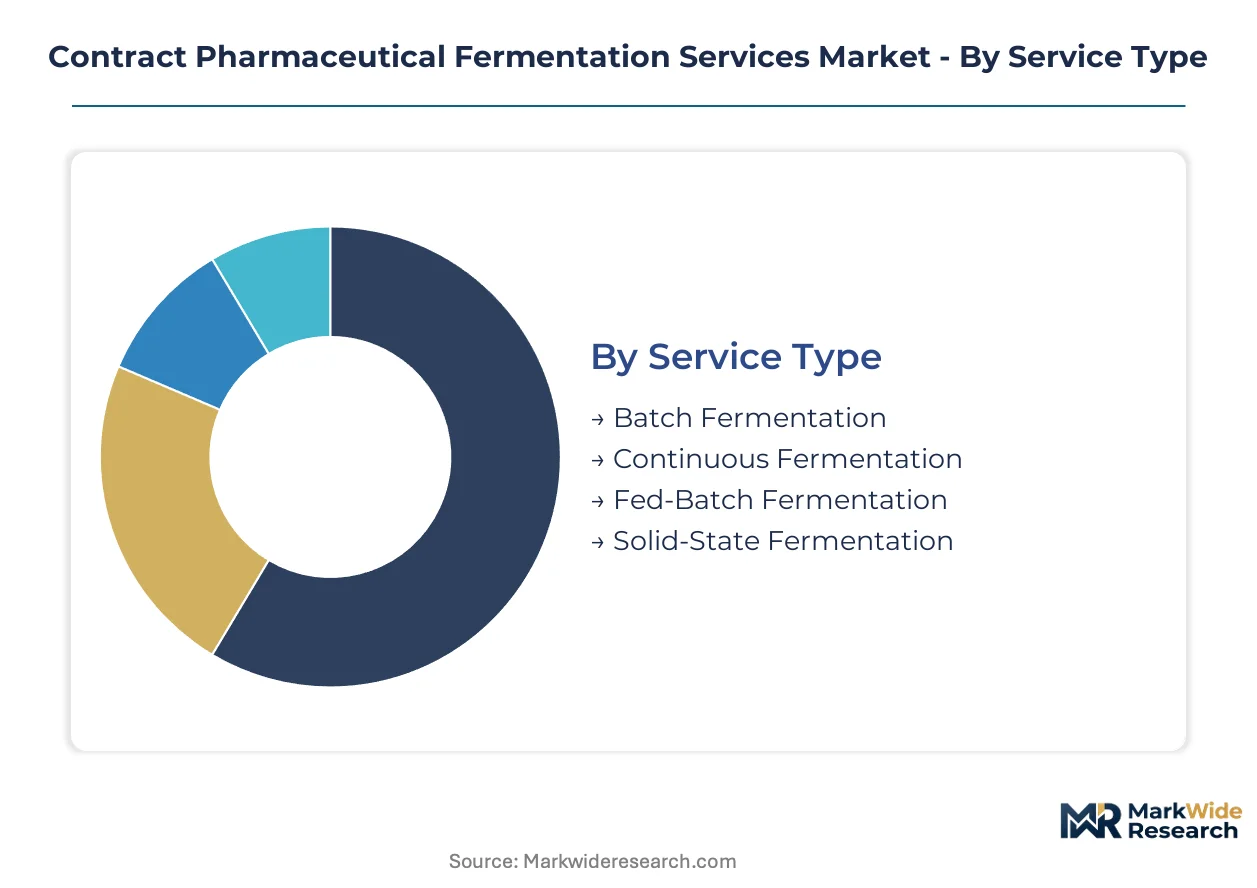
Contract fermentation services fragment across production modes, molecule classes, and sponsor types with distinct qualification requirements. Each segmentation axis carries implications for facility capital allocation, regulatory pathway complexity, and margin structure.
Service Type:
Batch configuration determines how sponsors access capacity—multi-product facilities favor disposable platforms while dedicated campaigns anchor on fixed stainless steel trains.
- Fed-Batch Fermentation:Intermittent nutrient feeding sustains high-cell-density cultures of E. coli and yeast strains at scales exceeding 10,000 liters. Pharmaceutical sponsors in the United States specify this mode for Phase III monoclonal antibody production where titer consistency determines commercial viability.
- Continuous Fermentation:Steady-state perfusion bioreactor operation with real-time process analytical technology maintains cell viability over extended durations. Gene therapy developers in Massachusetts and North Carolina clusters are specifying this mode for viral vector manufacturing where volumetric productivity outweighs capital intensity.
- Batch Fermentation:Conventional fill-and-harvest cycles dominate legacy antibiotic and enzyme production.
- Solid-State Fermentation:Moist solid substrate cultivation supports specialized fungal metabolite and enzyme manufacturing.
Fed-batch systems dominate installed base. Continuous processing is where expansion concentrates.
Product Type:
Cost tier stratification separates high-margin biologics from commodity APIs with divergent facility economics.
- Biopharmaceuticals:Recombinant therapeutic proteins, plasmid DNA, and viral vectors require mammalian or microbial platforms with GMP-grade documentation. CDMOs serving Boston and San Francisco biotechnology clusters command premium pricing for cell and gene therapy intermediates where cross-contamination protocols determine sponsor qualification.
- Antibiotics:Bulk beta-lactam and macrolide fermentation operates at massive scale with thin margins. EPA effluent limitations for antibiotic manufacturing discharge constrain site selection to contractors with advanced wastewater treatment infrastructure, particularly filtering smaller players in the United States.
- Enzymes:Industrial and therapeutic biocatalysts span microbial expression systems with varying purity requirements.
- Amino Acids:Nutraceutical and pharmaceutical-grade fermentation supplies parenteral nutrition and infusion therapy markets.
Antibiotics dominate installed fermentation volume. Biopharmaceuticals are climbing the fastest.
End User:
Customer type dictates contracting structure—emerging biotechnology firms seek flexible milestone-based agreements while established pharmaceutical sponsors negotiate multi-year capacity reservations.
- Pharmaceutical Companies:Large-cap sponsors with in-house biologics manufacturing still outsource overflow capacity and specialized modalities. Merck and Bristol Myers Squibb reserve multi-thousand-liter stainless steel trains at Lonza for legacy monoclonal antibody campaigns while retaining internal capacity for novel formats.
- Biotech Companies:Venture-backed developers without manufacturing infrastructure drive single-use platform adoption. Cambridge and South San Francisco emerging companies specify disposable bioreactors to compress campaign initiation timelines and conserve capital for clinical execution.
- Contract Manufacturing Organizations:CDMOs subcontract fermentation steps requiring specialized microbial expertise or mammalian capabilities outside their core competency.
- Research Institutions:Academic medical centers and national laboratories access GMP-adjacent capacity for early-phase material generation.
Pharmaceutical companies anchor long-term capacity contracts. Biotech companies are where demand volatility concentrates.
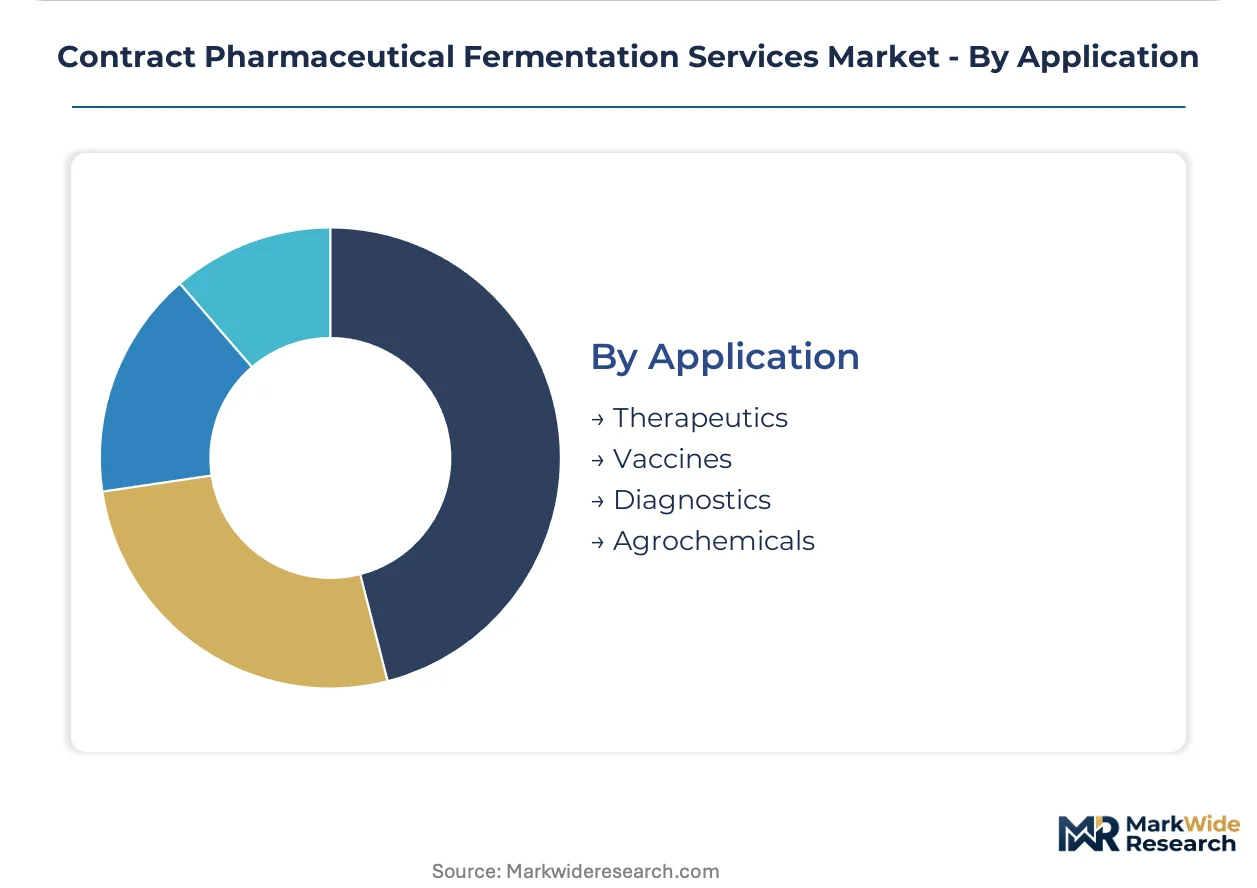
Application:
Volume and maturity separate established therapeutic categories from emerging modalities with divergent regulatory pathways.
- Therapeutics:Monoclonal antibodies, recombinant hormones, and enzyme replacement therapies constitute the revenue base. FDA process validation requirements for commercial biologics manufacturing impose 18-24 month facility qualification timelines that favor contractors with established quality management systems.
- Vaccines:Viral vector and recombinant protein vaccines require dedicated containment infrastructure. BARDA and HHS preparedness contracts are pulling capacity investments toward surge-responsive platforms capable of pandemic-scale output.
- Diagnostics:Enzyme and antigen production for in vitro diagnostic kits operates at smaller scale with faster turnaround requirements.
- Agrochemicals:Biopesticide and biocontrol agent fermentation leverages microbial platforms with lower purity thresholds than human health applications.
Therapeutics dominate revenue contribution. Vaccines are where capacity expansion is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for mammalian cell culture campaigns concentrates in Swiss and German facilities, while Indian microbial fermentation contractors capture volume through WHO prequalification pathways for generic APIs. This asymmetry shapes site selection patterns among sponsors balancing speed-to-clinic against cost minimization objectives.
United States
Gene therapy developers in Massachusetts and North Carolina drive demand for viral vector manufacturing capacity. FDA process validation requirements and IRA production tax credits are accelerating domestic site qualification timelines. The Greater Boston cluster hosts the highest concentration of emerging biotechnology companies specifying single-use platforms for Phase III campaigns.
Germany
Established pharmaceutical sponsors reserve multi-thousand-liter stainless steel capacity for legacy monoclonal antibody production. EMA Annex 1 revisions on sterile manufacturing mandate barrier technology investments that extend facility qualification periods. The Rhine-Main region anchors continental European biologics manufacturing with integrated fill-finish infrastructure.
Switzerland
High-margin biopharmaceutical contracts concentrate in facilities serving Basel and Zürich pharmaceutical headquarters. Swissmedic oversight aligns with FDA expectations, reducing regulatory friction for sponsors seeking dual-approval pathways. The country's precision manufacturing heritage supports complex therapeutic protein production at premium pricing tiers.
India
CDSCO-aligned drug master file submissions position contractors to capture WHO prequalification-driven procurement from African and Southeast Asian markets. Fermentation-derived API exports concentrate in Maharashtra and Gujarat industrial corridors. Domestic manufacturers leverage cost structures that undercut European and North American alternatives for commodity antibiotic and enzyme production.
China
NMPA regulatory convergence with ICH standards is expanding access for domestic fermentation contractors to international sponsor audits. Yangtze River Delta biotech clusters are attracting capacity investments for plasmid DNA and viral vector production. The country's central pharmaceutical regulator continues harmonizing GMP inspection protocols with FDA and EMA benchmarks.
Contract Pharmaceutical Fermentation Services Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Swiss and German integrated biologics networks command premium pricing for mammalian cell culture expertise, while Indian and Chinese contractors capture microbial fermentation volume through scale economics. Three archetypes dominate: integrated multi-modality platforms, microbial fermentation specialists, and single-use technology pioneers. Capacity reservation agreements and technology licensing partnerships represent the primary competitive moves reshaping supplier hierarchies.
Among integrated platform providers, Lonza and Boehringer Ingelheim occupy positions that exemplify the premium-tier archetype through captive biologics networks spanning multiple continents. Fujifilm Diosynth Biotechnologies represents the single-use technology vector, anchoring demand from gene therapy sponsors seeking campaign flexibility. These three entities illustrate how geographic origin and technology positioning stratify competitive access to sponsor pipelines.
| Leading Market Players |
|---|
| AMRI |
| Biocon |
| Lonza |
| Fujifilm Diosynth Biotechnologies |
| Aumgene Biosciences |
| Boehringer Ingelheim |
| CordenPharma |
| Pfizer CentreOne |
| AbbVie |
| Others |
Supply Flow & Price Mechanics
Single-use bioreactor assemblies displacing stainless steel trains simultaneously redraw supply geography toward film and sensor component hubs in Germany and Massachusetts while compressing pricing premiums for campaign-flexible capacity. This substitution dynamic elevates supplier relationships with disposable platform vendors and erodes depreciation-based cost advantages at legacy fixed-installation sites.
Pricing Analysis
The customization-premium spread separates standard fed-batch campaigns from viral vector manufacturing with isolator-based containment and real-time process analytical technology integration. Three-tier pricing structure across premium mammalian cell culture, standard microbial fermentation, and economy antibiotic bulk API tiers reflects certification grade and cross-contamination protocol intensity. Cost compression in commodity antibiotic fermentation runs through EPA effluent compliance burdens that filter smaller contractors. Emerging biotechnology companies in the Greater Boston cluster exhibit highest price sensitivity, while established pharmaceutical sponsors reserve capacity with least negotiation leverage.
Supply Chain Analysis
Inventory lead times for single-use film assemblies stretch 16-24 weeks, forcing contractors to pre-position buffer stock against resin allocation disruptions. Supply concentrates in the United States for gene therapy viral vectors, Switzerland for high-margin biologics, and India for WHO-prequalified generic APIs. Raw material dependencies span cell culture media formulations, chromatography resins, and sterilized disposable bioreactor bags. Single-source vulnerability concentrates in qualified film suppliers for disposable platforms. Distribution runs through direct sponsor-contractor relationships with milestone-based payment structures rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract pharmaceutical fermentation services are entering a cyclical recovery phase as post-pandemic capacity absorption normalizes and gene therapy pipeline maturation restarts capacity reservation timelines. Sponsor consolidation around single-use platforms is compressing technology transition windows for lagging facilities.
For Market Incumbents: Secure multi-year capacity reservation agreements with emerging biotechnology sponsors before competitor single-use platform investments reach operational status. Deepen backward integration into cell culture media formulation to insulate margins from raw material cost volatility. Prioritize EMA Annex 1 barrier technology upgrades at European mammalian cell culture suites to preempt inspection-driven sponsor disqualification.
For New Entrants and Emerging Players: Plasmid DNA manufacturing for cell and gene therapy developers represents the most penetrable service-layer gap where incumbent capacity constraints create qualification bottlenecks. Target CDSCO-aligned Indian export corridors for WHO-prequalified antibiotic API procurement programs. Deploy continuous fermentation technology as a differentiated go-to-market angle for commodity therapeutic protein sponsors seeking volumetric productivity advantages.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale single-use platform operators with established GMP documentation libraries and sponsor audit histories. Long-term viability across the analysis window hinges on technology flexibility rather than stainless steel scale. Watch for inflection when BARDA and HHS pandemic preparedness contracts accelerate viral vector capacity investments beyond current gene therapy demand baselines.
| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Platform Conversion | Reduces cross-contamination documentation burdens for multiproduct gene therapy facilities. |
| EMA Annex 1 Barrier Technology Upgrade | Extends facility qualification timelines but prevents sponsor disqualification from sterile manufacturing findings. |
| CDSCO-Aligned Drug Master File Pathway | Unlocks WHO prequalification-driven procurement volume from African and Southeast Asian markets. |
| Continuous Processing Platform Investment | Delivers titer advantages for commodity therapeutic proteins that fed-batch systems cannot match. |
| Dual-Use Microbial Capacity Qualification | Enables revenue diversification across veterinary and human health API lifecycle volatility. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with biopharmaceutical development executives, regulatory affairs leads, CDMO procurement managers, and fermentation scientists; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CDSCO drug master file databases. Bottom-up capacity modeling triangulated against top-down sponsor spending pattern analysis.
The projection horizon spans the full forecast period with analytical frameworks segmenting by production mode, molecule class, sponsor type, and regional regulatory cluster. CAGRs derive from installed base depreciation schedules, pipeline-stage transition probabilities, and capacity utilization assumptions across mammalian and microbial platform categories. Model inputs incorporate single-use technology adoption curves, EPA effluent compliance cost trajectories, and IRA production tax credit qualification rates.
Forecasts assume regulatory continuity in FDA cGMP, EMA Annex 1, and CDSCO submission frameworks; material policy shifts in sterile manufacturing requirements or environmental discharge rules would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Postmenopausal Vaginal Atrophy Drugs Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Global Low Molecular Weight Heparin Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market