
 Global Angina Pectoris Drugs Market | 2026-2036
Global Angina Pectoris Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Angina Pectoris Drugs Market Foresight
Hospital pharmacy buyers are reorganizing procurement priorities around chronic coronary syndrome management, shifting volume toward outpatient and homecare channels. AstraZeneca leverages its cardiovascular portfolio depth to sustain formulary positioning across integrated delivery networks. Pfizer competes through manufacturing scale in beta-blocker supply, while Novartis differentiates via specialty channel control in injectable antianginal therapies.
Angina pectoris drugs comprise pharmaceutical agents that modulate myocardial oxygen demand through vasodilation, heart rate reduction, or platelet inhibition, formulated for oral, sublingual, injectable, or transdermal delivery with bioavailability parameters dictating route selection. These therapies serve to relieve ischemic chest pain and prevent acute coronary events in chronic coronary syndrome patients. Beta-blockers occupy the largest revenue pool due to decades of clinical validation and generic availability, while transdermal delivery modes represent the fastest-growing structural segment as patient adherence programs drive patch-based nitrate adoption. The stable angina indication category remains mature with entrenched prescribing habits, whereas unstable angina applications command premium positioning through hospital-critical care protocols.
The FDA maintains stringent bioequivalence standards for generic antianginal substitutions, while the EMA's MDR framework shapes device-drug combination requirements for transdermal systems in Europe. Japan's PMDA enforces localized cardiovascular safety databases that condition market entry timelines for novel agents. Stakeholders must monitor evolving pharmacovigilance requirements across these jurisdictions to anticipate approval pathway complexity and post-market surveillance obligations.
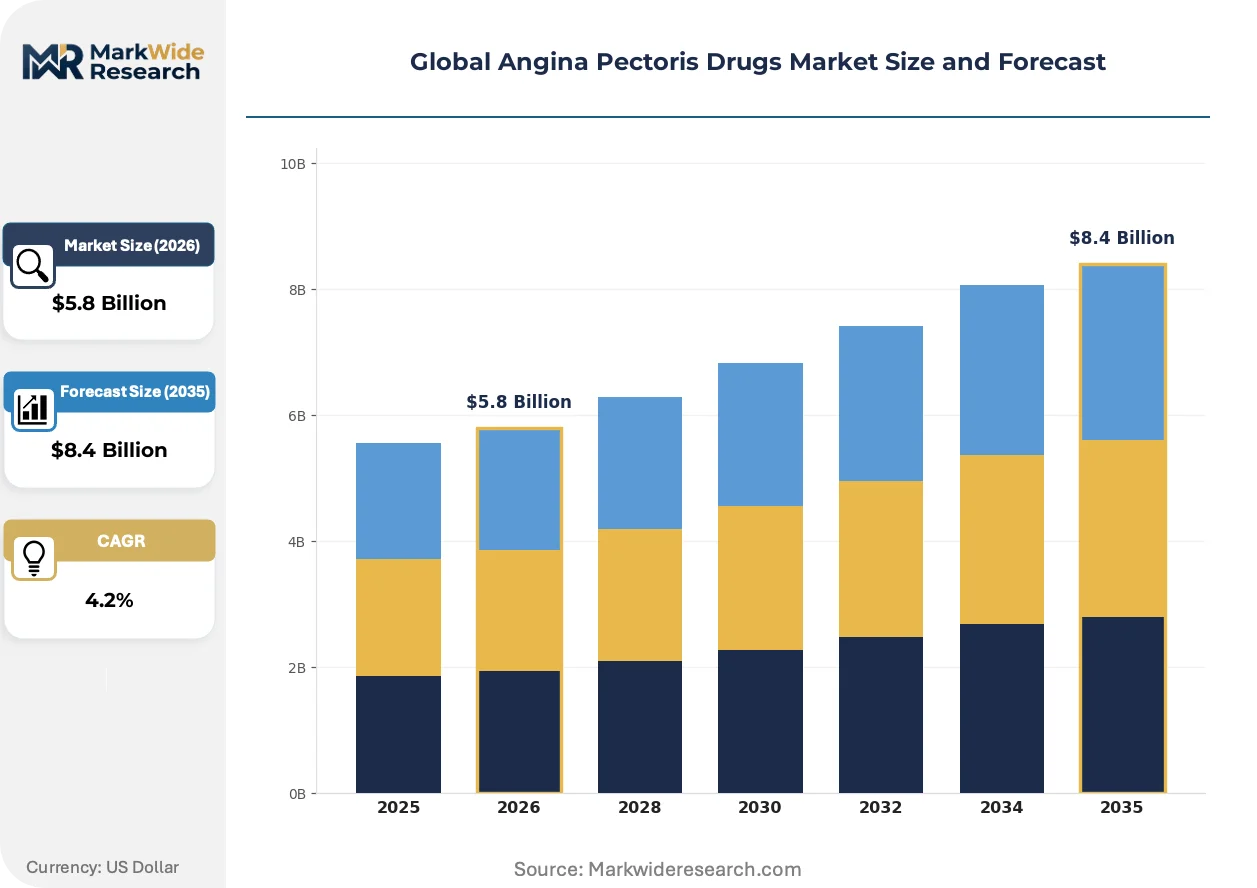
Market Dynamics
Hospital procurement departments are consolidating formulary decisions around chronic coronary syndrome management, compressing supplier margins while rewarding manufacturers with integrated cardiovascular portfolios. This buyer-side concentration is restructuring competitive positioning across beta-blocker, nitrate, and antiplatelet categories.
Growth Catalysts
- Outpatient Protocol Expansion:United States health systems are scaling ambulatory angina management programs, redirecting stable patient volumes from emergency departments to specialty clinics with dedicated pharmaceutical protocols.
- EMA MDR Clarity:The European Medicines Agency's finalized Medical Device Regulation guidance for transdermal drug-device combinations has reduced regulatory uncertainty, accelerating patch-based nitrate development timelines.
- PMDA Safety Database Harmonization:Japan's Pharmaceuticals and Medical Devices Agency is streamlining cardiovascular safety data requirements, enabling faster novel agent entry for unstable angina indications.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for beta-blockers concentrates in Indian and Chinese chemical hubs, exposing formulators to geopolitical disruption and input cost volatility.
- FDA Bioequivalence Stringency:The Food and Drug Administration maintains narrow therapeutic index requirements for generic antianginal substitutions, limiting rapid price competition in oral nitrate segments.
- Transdermal Technical Limits:Nitroglycerin patch formulations face stability degradation challenges that constrain extended-wear duration and patient adherence program effectiveness.
Strategic Opportunities
- German Homecare Integration:Germany's statutory health insurance system is expanding reimbursement for home-based angina monitoring with remote pharmaceutical adjustment, creating channel expansion potential.
- Injectable-Oral Convergence:Combination therapies merging sublingual rapid-onset nitrates with extended-release oral beta-blockers address both acute relief and chronic prevention in single regimens.
- Japan Elderly Protocol Tailoring:PMDA guidance on geriatric cardiovascular dosing is opening formulation opportunities for reduced-strength, titration-friendly presentations in Japan's aging population.
Industry Challenges
- Cardiovascular Pharmacology Talent Scarcity:Specialized expertise in antianginal mechanism modeling and pharmacokinetic optimization remains concentrated among a limited pool of academic and industry researchers.
- Multinational Trial Complexity:Coordinating Phase III studies across FDA, EMA, and PMDA jurisdictions demands extended timelines and fragmented patient recruitment strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Angina Pectoris Drugs Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrates, Beta-Blockers, Calcium Channel Blockers, Antiplatelet Agents Indication: Stable Angina, Unstable Angina, Prinzmetal's Angina, Effort Angina Delivery Mode: Oral, Injectable, Sublingual, Transdermal End User: Hospitals, Clinics, Homecare Settings, Pharmacies |
| Companies Covered | AstraZeneca, Pfizer, Novartis, Bayer, Sanofi, Gilead Sciences, GlaxoSmithKline, Merck & Co., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Angina Pectoris Drugs Market Shifts & Advancements
Pharmaceutical delivery technology and procurement model evolution are restructuring how angina therapies reach patients. Manufacturers are responding with formulation innovations and channel strategies that address adherence gaps and cost containment pressures.
Transdermal nitroglycerin patch technology is fragmenting the traditional oral nitrate market by enabling steady-state plasma levels without first-pass metabolism degradation. Integrated delivery networks in the United States are adopting patch protocols for stable angina patients with demonstrated compliance challenges. The technology is fragmenting prescribing patterns between acute relief and chronic prevention segments, forcing oral manufacturers to defend position through combination formulations.
The FDA's streamlined cardiovascular review pathway is compressing approval timelines for novel antianginal mechanisms with demonstrated mortality benefit. This regulatory efficiency is attracting development investment toward unstable angina and refractory chronic coronary syndrome indications. Hospital pharmacy buyers are responding by pre-negotiating access agreements for pipeline agents, securing formulary positioning ahead of commercial launch.
Specialty pharmacy distribution is displacing traditional wholesale channels for high-cost injectable antianginal therapies. United States payers are mandating limited distribution networks with outcomes tracking for hospital-to-home transition protocols. Germany and Japan are piloting similar concentration models, though with stronger hospital pharmacy autonomy protections.
Global Angina Pectoris Drugs Market Segmentation
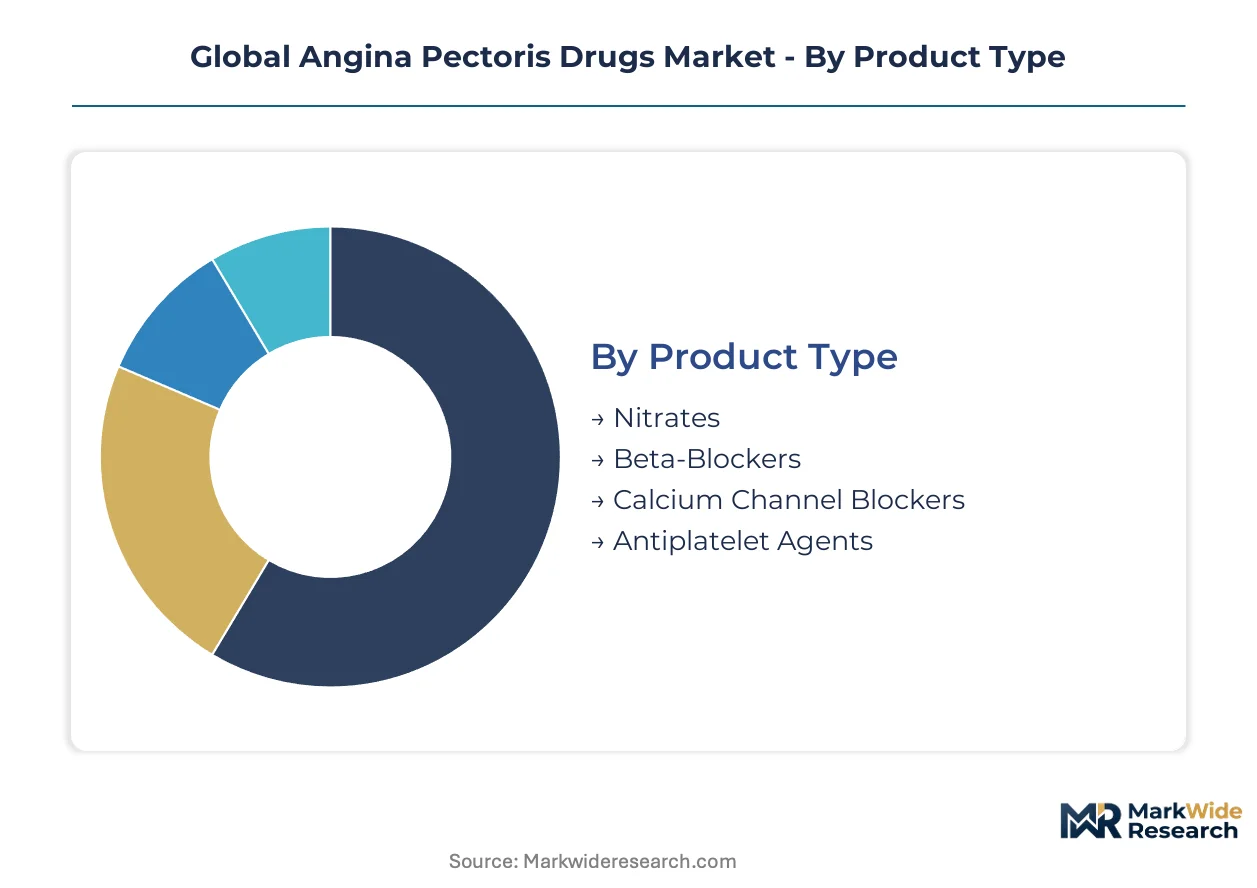
Angina pectoris drug segmentation reflects divergent regulatory pathways across delivery technologies and clinical settings. Manufacturers configure portfolio depth around FDA bioequivalence tiers, EMA device-drug combination rules, and PMDA geriatric dosing protocols.
Product Type:
FDA maintains distinct bioequivalence standards for each pharmacological class, with narrow therapeutic index designations constraining generic substitution pathways for select agents.
- Beta-Blockers:These agents reduce myocardial oxygen demand through selective beta-1 adrenergic receptor antagonism, with metoprolol and carvedilol formulations dominating hospital formularies. Demand concentrates in United States integrated delivery networks where outpatient chronic coronary syndrome protocols prioritize heart rate control for stable angina patients with comorbid hypertension.
- Nitrates:Organic nitrate esters such as nitroglycerin and isosorbide dinitrate induce venous and arterial vasodilation via nitric oxide-mediated smooth muscle relaxation. German statutory health insurance reimbursement for home-based angina monitoring is expanding sublingual and transdermal nitrate dispensing through specialty pharmacy channels.
- Calcium Channel Blockers:Dihydropyridine and non-dihydropyridine classes inhibit L-type calcium channels, reducing coronary vasospasm and afterload.
- Antiplatelet Agents:P2Y12 inhibitors and aspirin formulations target platelet aggregation pathways for acute coronary event prevention.
Established volume favors beta-blockers; emerging adoption favors transdermal nitrate formulations.
Indication:
Clinical indication stratification determines pricing architecture, with acute care protocols commanding premium positioning against chronic maintenance therapies.
- Stable Angina:Predictable chest pain triggered by exertion, managed through chronic pharmaceutical protocols emphasizing symptom prevention. United States ambulatory care expansion is redirecting stable patient volumes from emergency departments to specialty clinics with standardized beta-blocker and nitrate regimens.
- Unstable Angina:Acute coronary syndrome without biomarker elevation, requiring hospital-critical care intervention with injectable antiplatelet and anticoagulant combinations. Japan's PMDA streamlined safety database requirements are accelerating novel agent entry for this high-acuity segment.
- Prinzmetal's Angina:Vasospastic disorder characterized by coronary artery spasm, typically responsive to calcium channel blockers.
- Effort Angina:Exercise-induced ischemic symptoms managed through pre-emptive nitrate administration and activity-modified beta-blocker dosing.
Revenue concentration sits with unstable angina hospital protocols; patient volume expansion is climbing the fastest in stable angina outpatient management.
Delivery Mode:
Route selection dictates manufacturing complexity, with first-pass metabolism considerations and bioavailability parameters determining formulation investment priorities.
- Oral:Extended-release tablets and capsules dominate chronic maintenance therapy, offering dosing convenience for stable angina patients. FDA bioequivalence stringency for generic antianginal substitutions limits rapid price competition in oral nitrate segments.
- Transdermal:Nitroglycerin patches provide steady-state plasma levels without hepatic first-pass degradation, addressing adherence gaps in elderly populations. EMA MDR clarity on drug-device combination requirements has reduced regulatory uncertainty for patch-based systems in Europe.
- Injectable:Intravenous formulations reserve for acute coronary syndrome management in hospital-critical care settings.
- Sublingual:Rapid-onset nitroglycerin tablets and sprays deliver acute relief through buccal mucosa absorption, bypassing gastrointestinal metabolism.
Volume leadership remains with oral formulations; steepest expansion trajectory belongs to transdermal delivery as adherence programs gain institutional adoption.
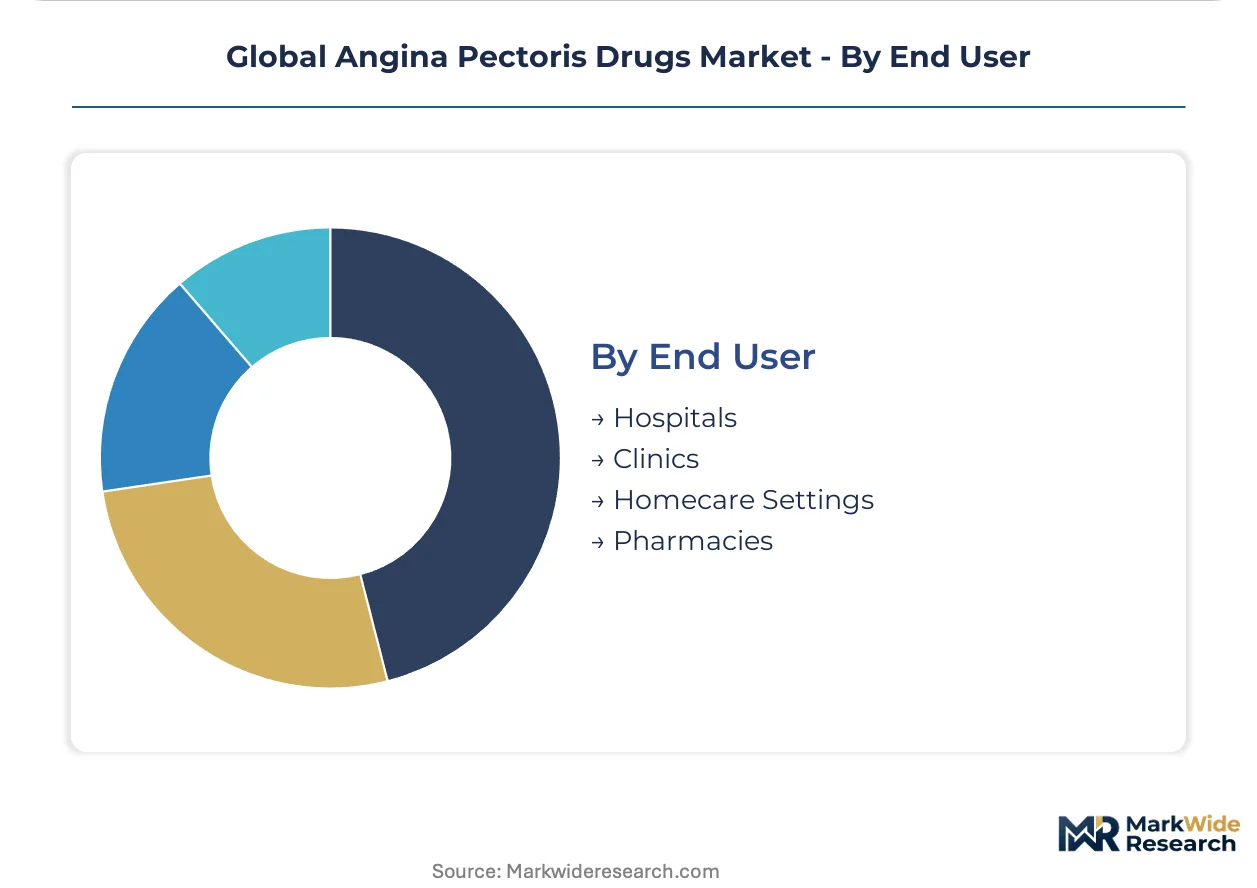
End User:
Procurement authority is consolidating around integrated delivery network pharmacy directors and specialty pharmacy benefit managers, restructuring channel economics.
- Hospitals:Inpatient and emergency department formulary decisions concentrate purchasing power for injectable antianginal therapies and acute care protocols. United States hospital procurement departments are pre-negotiating access agreements for pipeline agents with demonstrated mortality benefit.
- Homecare Settings:Remote patient monitoring with pharmaceutical adjustment protocols is expanding in Germany's statutory health insurance system, creating channel expansion for patch-based nitrates and combination oral regimens.
- Clinics:Ambulatory cardiology practices manage stable angina patients through standardized pharmaceutical protocols with outcomes tracking.
- Pharmacies:Retail and specialty pharmacy dispensing faces margin compression from payer-mandated limited distribution networks for high-cost therapies.
Procurement gravity centers on hospital pharmacy buyers; patient preference and reimbursement incentives are gaining share fastest in homecare channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive cardiovascular therapies. United States hospital procurement networks leverage the Port of Long Beach's trans-Pacific container throughput to maintain formulary stockpiles. Japan's Chubu Centrair International Airport anchors just-in-time API deliveries for domestic formulation facilities.
United States
Ambulatory angina management programs redirect stable patient volumes from emergency departments to specialty clinics with standardized pharmaceutical protocols. FDA streamlined review pathways compress approval timelines for novel antianginal mechanisms with demonstrated mortality benefit. Hospital procurement departments in the Cleveland Clinic and Mayo Clinic networks pre-negotiate access agreements for pipeline agents ahead of commercial launch.
Germany
Statutory health insurance reimbursement expansion for home-based angina monitoring creates channel growth for patch-based nitrates and combination oral regimens. EMA MDR clarity on drug-device combination requirements accelerates transdermal system development timelines. The Rhine-Main metropolitan cluster hosts integrated delivery networks consolidating formulary decisions around chronic coronary syndrome management.
Japan
PMDA streamlined cardiovascular safety database requirements enable faster novel agent entry for unstable angina indications. METI geriatric dosing guidance opens formulation opportunities for reduced-strength, titration-friendly presentations. The Kansai region's pharmaceutical manufacturing corridor concentrates injectable antianginal production for hospital-critical care protocols.
India
Domestic API manufacturing capacity for beta-blocker intermediates supplies formulation hubs serving export markets. CDSCO accelerated approval pathways for generic antianginal substitutions attract investment toward oral nitrate segment expansion. The Hyderabad-Visakhapatnam pharmaceutical belt concentrates contract manufacturing for transdermal patch technologies.
Switzerland
Specialty pharmacy distribution networks for high-cost injectable therapies leverage Geneva's logistics infrastructure for hospital-to-home transitions. Swissmedic alignment with EMA pharmacovigilance standards reduces regulatory friction for cardiovascular drug-device combinations. The Basel biopharmaceutical cluster anchors European headquarters operations for multinational antianginal portfolio management.
Global Angina Pectoris Drugs Market Competitive Landscape
Listed leaders compete with private specialists across cardiovascular portfolio depth and manufacturing scale. The market exhibits tiered concentration with integrated pharmaceutical conglomerates occupying hospital formulary gatekeeper positions while regional generics manufacturers capture outpatient volume through price-competitive oral formulations. Three archetypes dominate: portfolio-integrated conglomerates with cardiovascular therapeutic depth, scale-driven generics manufacturers with beta-blocker supply advantages, and specialty channel controllers with injectable antianginal focus. Competitive moves center on M&A for cardiovascular pipeline assets and strategic partnerships with integrated delivery networks for formulary pre-positioning.
Within the portfolio-integrated tier, AstraZeneca and Pfizer exemplify divergent competitive approaches. AstraZeneca leverages cardiovascular therapeutic depth to sustain formulary positioning across United States integrated delivery networks. Pfizer competes through manufacturing scale in beta-blocker supply, capturing volume in price-sensitive outpatient segments. Novartis occupies a distinct position via specialty channel control in injectable antianginal therapies, securing premium positioning in hospital-critical care protocols.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer |
| Novartis |
| Bayer |
| Sanofi |
| Gilead Sciences |
| GlaxoSmithKline |
| Merck & Co. |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
FDA bioequivalence tiers gate both supplier qualification and price differentiation simultaneously, with narrow therapeutic index designations creating protected pricing corridors for originator beta-blockers while enabling aggressive generic substitution in standard oral nitrate segments. Hospital procurement consolidation concentrates buyer power, compressing margins for undifferentiated formulations while rewarding manufacturers with integrated cardiovascular portfolios.
Pricing Analysis
Volume-discount tiering structures dominate hospital formulary negotiations, with integrated delivery networks extracting scaled rebates for beta-blocker and nitrate commitments. Price differentiation rests on FDA narrow therapeutic index certification and hospital-critical care protocol inclusion, with unstable angina injectables commanding premium positioning against outpatient stable angina maintenance therapies. Cost compression in oral generic segments is intensifying because of Indian and Chinese API oversupply. Retail pharmacy buyers exhibit highest price sensitivity; hospital pharmacy directors prioritize clinical outcomes data over unit cost.
Supply Chain Analysis
Strategic stockpiling preferences dominate hospital procurement for injectable antianginal therapies, with United States integrated delivery networks maintaining 60-90 day critical care inventories against API disruption risks. Active pharmaceutical ingredient manufacturing draws from Indian chemical hubs for beta-blocker intermediates and Chinese facilities for nitrate precursors. Single-source vulnerability concentrates in specialized cardiovascular pharmacology talent pools and transdermal patch polymer substrates. Distribution runs through specialty pharmacy networks for high-cost hospital-to-home transitions, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital pharmacy directors and specialty pharmacy benefit managers, with formulary decision concentration restructuring supplier economics across beta-blocker, nitrate, and antiplatelet categories.
For Market Incumbents: Shield formulary positioning through backward integration into API supply for beta-blocker intermediates and exclusive channel partnerships with United States integrated delivery networks. Biologic substitute threats from PCSK9 inhibitors and SGLT2 cardiovascular outcomes data demand reinforced clinical evidence generation for mortality benefit claims. Certification investment in FDA narrow therapeutic index maintenance represents the critical defensive lever. For New Entrants and Emerging Players: Homecare monitoring service-layer gaps expose white-space opportunities in Germany's statutory health insurance reimbursement expansion for remote pharmaceutical adjustment. Patch-based nitrate adherence programs in elderly populations offer the most penetrable entry vector. A go-to-market angle anchored in outcomes-based contracts with specialty pharmacy networks bypasses entrenched hospital formulary gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across transdermal drug-device combination manufacturing as EMA MDR compliance requirements elevate facility standards. Long-term viability favors platform players with cardiovascular therapeutic depth over single-product specialists. Acquisition targets should demonstrate formulary pre-positioning with United States integrated delivery networks. The signal to monitor is FDA streamlined review pathway utilization rates for novel antianginal mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Formulary Pre-Positioning Agreements | Hospital procurement directors at Cleveland Clinic and Mayo Clinic networks secure pipeline access ahead of commercial launch. |
| Transdermal Manufacturing Scale-Up | EMA MDR clarity reduces regulatory uncertainty for patch-based nitrate systems in European markets. |
| Specialty Pharmacy Network Partnership | United States payers mandate limited distribution with outcomes tracking for hospital-to-home transitions. |
| API Backward Integration | Indian and Chinese chemical hub concentration creates geopolitical disruption exposure for beta-blocker supply. |
| Geriatric Formulation Development | PMDA dosing guidance opens reduced-strength presentations for Japan's aging cardiovascular patient population. |
Research Methodology
The analysis maps beta-blocker, nitrate, calcium channel blocker, and antiplatelet therapeutic segments, each validated through formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases support bottom-up and top-down triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, indication, delivery mode, and end user segmentation dimensions. CAGRs were derived through trend extrapolation anchored in outpatient protocol expansion rates and regulatory pathway efficiency improvements. Forecast inputs incorporated PMDA safety database harmonization timelines and German homecare reimbursement policy trajectories.
Forecasts assume regulatory continuity in FDA bioequivalence standards, EMA MDR enforcement, and PMDA geriatric dosing guidance; material policy shifts would require re-modeling. Revision becomes warranted when API supply disruption events or novel antianginal mortality benefit data cross clinical adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Middle East and Africa Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market