
 2-Valent HPV Vaccine (2vHPV) Market | 2026-2036
2-Valent HPV Vaccine (2vHPV) Market Size, Share, and Industry Trends Forecast 2026-2036
2-Valent HPV Vaccine (2vHPV) Market Insights
The capital-intensity divergence between live-virus manufacturing and recombinant protein platforms is unwinding competitive hierarchies in 2vHPV supply. GlaxoSmithKline plc leverages decades of adjuvant expertise to sustain premium positioning in European tender markets. Serum Institute of India anchors volume economics through bulk antigen production for UN procurement channels. Walvax Biotechnology differentiates via domestic fill-finish capacity serving China's provincial CDC schedules.
The 2-Valent HPV Vaccine (2vHPV) is a recombinant protein subunit vaccine containing purified L1 virus-like particles of HPV types 16 and 18, formulated with AS04 or aluminum adjuvant and administered via intramuscular injection to prevent persistent infection and precancerous cervical lesions. Its primary commercial purpose centers on population-level cervical cancer prevention through national immunization programs and targeted catch-up campaigns in high-burden regions. The intramuscular delivery mode dominates procurement tenders due to established cold-chain compatibility and healthcare worker familiarity, while public health programs represent the deepest margin pool where multi-year Gavi commitments lock in volume offtake. Adolescent end-user targeting remains structurally central to cost-effectiveness models, though young adult catch-up segments show fastest policy momentum as countries expand age-eligible cohorts.
FDA batch release protocols and WHO prequalification standards jointly determine manufacturer access to donor-funded procurement pools, creating a dual-hurdle compliance architecture that filters supplier participation. EMA marketing authorization requirements for variant-adapted formulations shape R&D allocation across European-headquartered developers. China's NMPA vaccine lot-release system and national immunization program inclusion criteria control market entry timing for domestic producers like Walvax and Xiamen Innovax Biotech. Stakeholders must monitor WHO Strategic Advisory Group of Experts policy shifts on single-dose scheduling, as this technical recommendation carries immediate procurement volume implications across Gavi-eligible countries without requiring explicit forecast-year references.
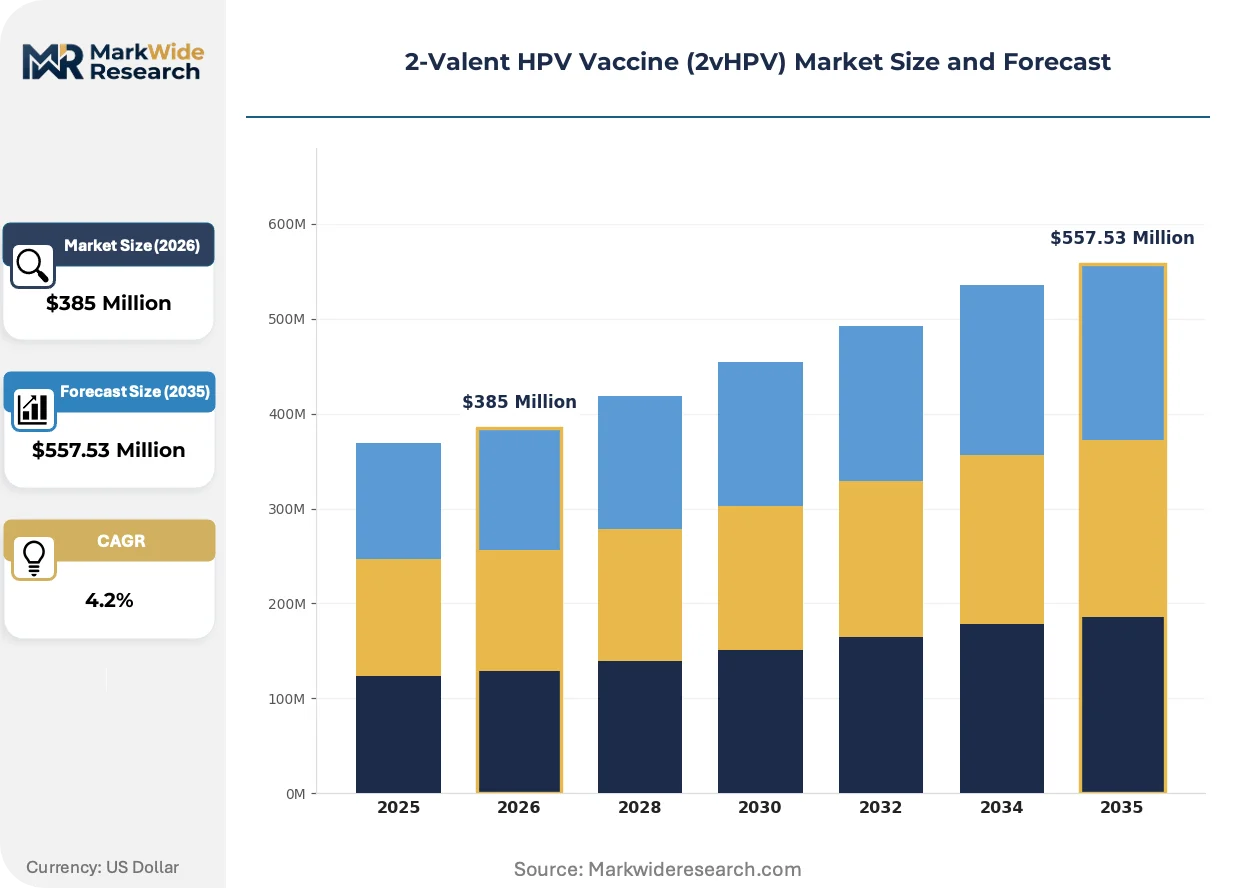
Market Dynamics
Single-dose scheduling recommendations from WHO's Strategic Advisory Group of Experts are compressing procurement volumes while expanding addressable populations across Gavi-eligible countries, fundamentally altering manufacturer revenue-per-dose economics and inventory planning horizons.
Growth Catalysts
- National immunization program expansion:Low- and middle-income countries are incorporating 2vHPV into routine adolescent vaccination schedules, creating predictable multi-year demand pipelines through Gavi financing commitments.
- WHO prequalification pathways:Accelerated prequalification review processes enable faster manufacturer access to donor-funded procurement pools, reducing time-to-market for new suppliers.
- Cervical cancer elimination targets:National cancer control programs in Sub-Saharan Africa and South Asia are prioritizing HPV vaccination as primary prevention, aligning procurement with disease burden metrics.
Market Restraints
- Cold-chain infrastructure gaps:Last-mile distribution in rural geographies requires 2-8°C maintenance across fragmented health systems, limiting effective coverage in thermally unstable regions.
- Antigen manufacturing concentration:Bulk L1 VLP production capacity clusters among established biologics suppliers, creating supply vulnerability during demand surges or facility disruptions.
- Regulatory divergence:EMA variant-adapted formulation requirements differ from FDA stability protocols, forcing parallel development tracks that extend registration timelines.
Strategic Opportunities
- Young adult catch-up segments:Countries expanding age-eligible cohorts beyond 9-14 year-olds unlock incremental volume through school-based and healthcare facility campaigns.
- Domestic fill-finish partnerships:Technology transfer agreements enable regional manufacturers to complete final formulation and packaging, reducing import dependency and customs clearance delays.
- Digital immunization registries:Integration with national health information systems improves coverage tracking and enables targeted reminder-recall interventions for dropout completion.
Industry Challenges
- Adjuvant supply security:AS04 component sourcing depends on limited qualified suppliers, exposing formulation continuity to raw material availability fluctuations.
- Lot-release timing variability:NMPA batch testing protocols in China create unpredictable release schedules that disrupt provincial CDC distribution calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Valent HPV Vaccine (2vHPV) Market |
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $557.53 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Healthcare Provider, Public Health Programs, Travel Clinics, Pharmacies Delivery Mode: Intradermal, Subcutaneous, Intramuscular, Oral End User: Adolescents, Young Adults, Adults, Women Indication: Prevention, Immunization, Screening, Therapeutic |
| Companies Covered | GlaxoSmithKline plc, Merck & Co., Inc., Serum Institute of India, Sanofi Pasteur, Walvax Biotechnology, Xiamen Innovax Biotech, Beijing Wantai BioPharm, Bharat Biotech, Instituto Butantan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Valent HPV Vaccine (2vHPV) Market Trends and Innovations
Manufacturing platform diversification and dosing regimen simplification are converging to reshape competitive economics and public health program design across procurement channels.
Recombinant protein expression systems utilizing yeast and insect cell lines are displacing traditional mammalian cell culture for L1 VLP production, cutting capital intensity and batch-to-batch variability. Emerging market manufacturers adopting these platforms compress cost structures sufficiently to compete in UN tender processes previously dominated by legacy suppliers. This platform shift is displacing high-cost bioreactor infrastructure as the default production standard.
WHO's updated position on single-dose primary series scheduling removes the logistical burden of multi-visit completion, altering cost-effectiveness calculations in resource-constrained settings. National immunization programs are recalibrating cold-chain requirements and health worker deployment models around one-visit delivery. Sub-Saharan African countries with high cervical cancer mortality are fastest to adopt this policy revision into procurement specifications.
Public health programs are unbundling vaccine supply from bundled service contracts, separating product procurement from implementation support. Gavi-eligible countries now tender antigen supply independently of cold-chain logistics and community mobilization services, enabling specialized vendor selection. This unbundling is most advanced in South Asian national programs with mature procurement capabilities.
2-Valent HPV Vaccine (2vHPV) Market Segmentation
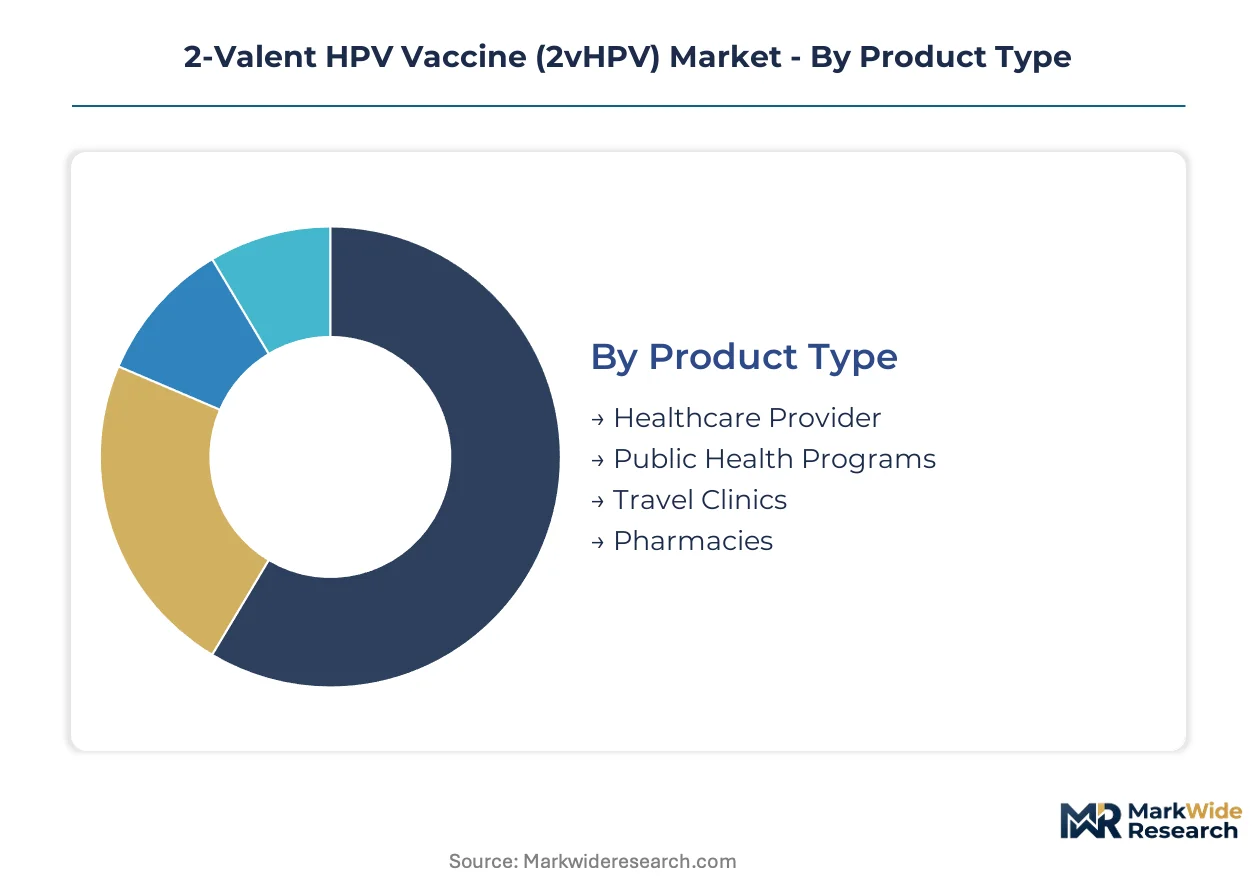
2vHPV procurement flows through distinct channels with divergent margin structures and regulatory requirements. Channel-specific tender designs and end-user targeting strategies determine manufacturer competitive positioning across national programs and private markets.
Product Type:
FDA batch release protocols and WHO prequalification standards create tiered compliance burdens across procurement channels.
- Healthcare Provider:Private clinic networks and hospital outpatient departments administer 2vHPV through fee-for-service arrangements. Concentrated demand in urban Brazil and Mexico City clusters around gynecology practices serving insured populations with AS04-adjuvanted formulations.
- Public Health Programs:National immunization schedules and Gavi-subsidized campaigns generate volume offtake through centralized tender processes. Sub-Saharan African ministries of health in Kenya, Tanzania, and Ethiopia anchor procurement through multi-year supply agreements.
- Travel Clinics:Pre-departure vaccination services target outbound travelers from high-income countries to endemic regions. Compact cold-chain requirements suit airport-adjacent facilities in London Heathrow and Dubai International corridors.
- Pharmacies:Retail vaccination services expand access through pharmacist-administered delivery. Regulatory scope varies—German Apotheken hold broader immunization authority than US retail chains.
Established volume favors Public Health Programs; emerging adoption favors Pharmacies.
Delivery Mode:
Route selection hinges on cold-chain infrastructure maturity and healthcare worker training depth.
- Intramuscular:Standard 2-8°C stability and established administration protocols dominate procurement tenders. WHO prequalified supply chains in India, Bangladesh, and Nigeria default to deltoid injection for school-based campaigns.
- Subcutaneous:Reduced needle length and simplified technique suit community health worker deployment. Emerging traction in Indonesian archipelago programs with limited refrigeration reach.
- Intradermal:Dose-sparing potential drives evaluation in cost-constrained settings. Pilot programs in Thailand and Vietnam assess Mantoux technique adaptation for L1 VLP delivery.
- Oral:Thermostable formulation research targets last-mile elimination of cold-chain dependency. Preclinical platforms at Indian and South Korean institutes explore mucosal immune response induction.
Procurement specifications concentrate on Intramuscular; formulation innovation centers on Oral.
End User:
Age-cohort targeting shapes cost-effectiveness modeling and campaign logistics design.
- Adolescents:9-14 year-old scheduling prior to sexual debut delivers optimal immunogenicity. School-based delivery in Rwanda, Uganda, and Malawi achieves coverage rates above 80% through grade-linked enrollment.
- Young Adults:15-26 year catch-up campaigns expand eligible populations in Chile, Colombia, and Malaysia. Workplace and university health services drive incremental volume.
- Adults:Extended age eligibility in Australia and Canada captures previously unvaccinated cohorts. Screening integration guides targeted outreach.
- Women:Gender-specific procurement prioritization aligns with cervical cancer elimination goals. National cancer control programs in Ghana and Zambia structure demand around female population registers.
Program design centers on Adolescents; policy momentum builds fastest among Young Adults.
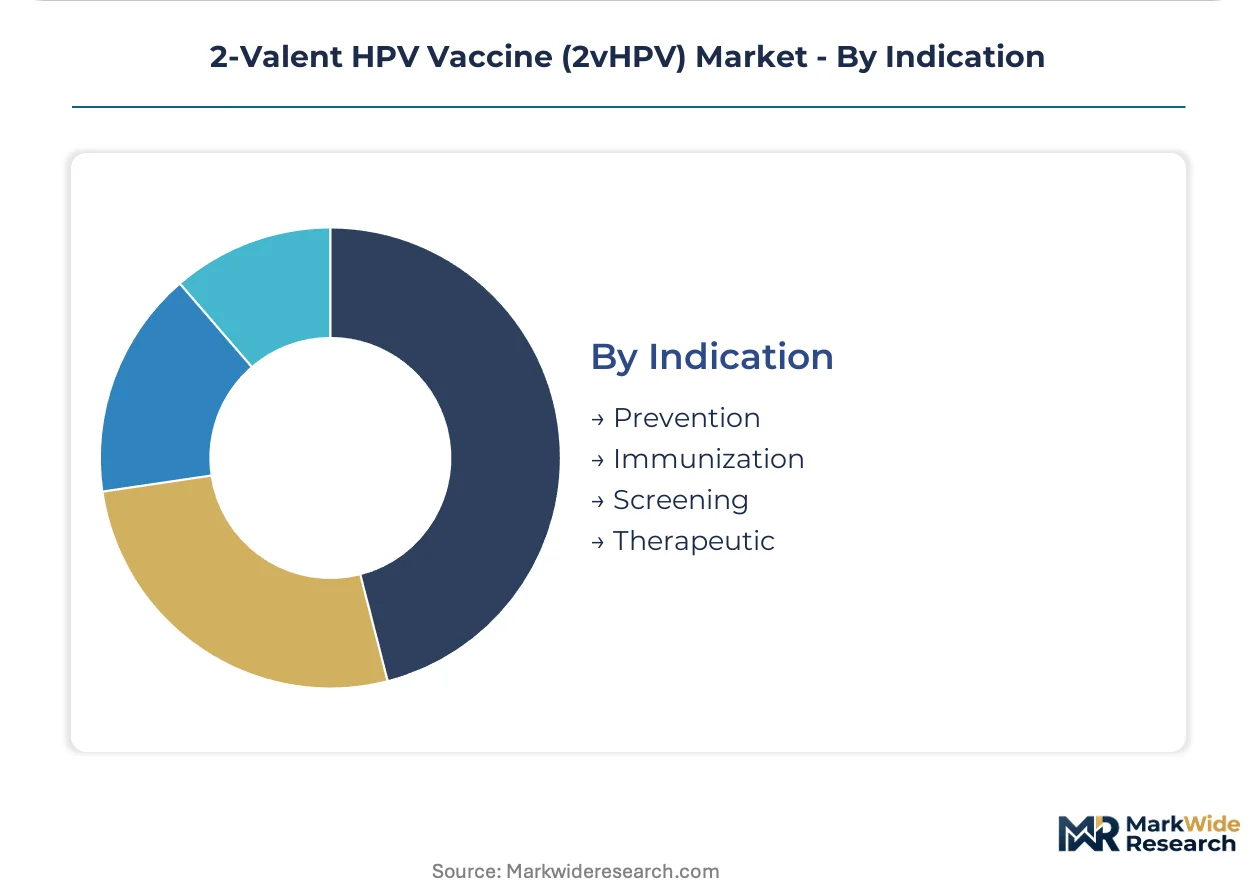
Indication:
Clinical positioning spans prophylaxis through therapeutic adjuvant applications.
- Prevention:Primary prophylaxis against HPV 16/18 infection constitutes core market function. National immunization technical advisory groups in South Africa and Mozambique prioritize incident infection reduction.
- Immunization:Routine schedule integration and booster policy define procurement cadence. Single-dose primary series recommendations from WHO SAGE compress multi-year demand curves.
- Screening:Co-testing protocols link vaccination status to cytology programs. Digital registries in Estonia and Israel match immunization records to screening invitations.
- Therapeutic:Adjuvant post-surgical applications remain investigational. Early-phase trials in US academic medical centers explore lesion regression endpoints.
Prevention commands procurement budgets; Therapeutic represents exploratory positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European tender markets where EMA marketing authorization commands premium positioning, while procurement volumes aggregate in Sub-Saharan African and South Asian national immunization programs where Gavi financing compresses per-dose economics.
Kenya
School-based delivery campaigns target 9-14 year-old cohorts through grade-linked enrollment systems. The Ministry of Health integrates 2vHPV into routine immunization schedules with Gavi co-financing commitments. Nairobi anchors procurement coordination through centralized cold-chain distribution to county health facilities.
India
Domestic bulk antigen production capacity serves UN procurement channels through Serum Institute of India's recombinant protein platforms. CDSCO vaccine lot-release protocols govern provincial CDC distribution calendars. Hyderabad and Pune clusters concentrate fill-finish operations for national immunization program supply.
Brazil
ANVISA registration pathways enable regional manufacturer participation in Pan American Health Organization tenders. Instituto Butantan maintains technology transfer partnerships for local formulation capacity. São Paulo state health secretariats pilot subcutaneous delivery in archipelago regions with limited refrigeration reach.
China
NMPA batch testing protocols control market entry timing for domestic producers serving provincial CDC schedules. Walvax Biotechnology leverages domestic fill-finish capacity for national immunization program inclusion. Beijing-Tianjin-Hebei corridor concentrates regulatory review and quality control infrastructure.
Tanzania
Sub-Saharan cervical cancer elimination targets prioritize HPV vaccination in national cancer control programs. The Ministry of Health adopts WHO single-dose scheduling recommendations to expand addressable populations. Dar es Salaam coordinates multi-year supply agreements with donor-funded procurement pools.
2-Valent HPV Vaccine (2vHPV) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across procurement channels. European-headquartered developers leverage decades of adjuvant expertise to sustain premium positioning in tender markets, while emerging market manufacturers compress cost structures through recombinant protein platform adoption. Three archetypes dominate: legacy biologics suppliers with established WHO prequalification, domestic fill-finish specialists serving national immunization programs, and bulk antigen producers anchoring UN procurement volumes. Capacity expansion and strategic partnerships represent the dominant competitive moves, with technology transfer agreements enabling regional manufacturers to complete final formulation and packaging.
Within the legacy supplier tier, GlaxoSmithKline plc exemplifies adjuvant-anchored premium positioning, while Serum Institute of India occupies the volume-driven procurement channel. Walvax Biotechnology represents the domestic specialist archetype serving provincial CDC schedules through captive fill-finish infrastructure.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Serum Institute of India |
| Sanofi Pasteur |
| Walvax Biotechnology |
| Xiamen Innovax Biotech |
| Beijing Wantai BioPharm |
| Bharat Biotech |
| Instituto Butantan |
| Others |
Pricing and Supply Chain Analysis
WHO prequalification standards gate both supply qualification and price differentiation simultaneously, creating a dual-hurdle architecture where only AS04-adjuvanted and aluminum-adjuvanted formulations meeting stability protocols access Gavi-subsidized procurement pools. Manufacturers without this certification face exclusion from the deepest volume channels regardless of cost position, while qualified suppliers command tiered premiums based on adjuvant sophistication and cold-chain reliability.
Pricing Analysis
The customization-premium spread separates AS04-adjuvanted formulations commanding tender premiums in European markets from aluminum-adjuvanted standard supply in Gavi-eligible countries. Price differentiation hinges on WHO prequalification tier and adjuvant sourcing security, with European tender markets showing lowest price sensitivity and Sub-Saharan African ministries of health exhibiting highest budget constraint. Pricing pressure stems from single-dose scheduling recommendations compressing per-patient revenue, forcing manufacturers to recapture margin through volume scale rather than dose multiplication.
Supply Chain Analysis
Inventory lead-times stretch unpredictably due to NMPA batch testing variability in China and WHO prequalification renewal cycles. Bulk L1 VLP production concentrates in India, China, and Belgium, with fill-finish operations drawing from captive regional facilities. Raw material dependencies center on qualified AS04 component suppliers, yeast expression system nutrients, and pharmaceutical-grade aluminum salts. Single-source vulnerability in adjuvant supply exposes formulation continuity to disruption. Distribution runs through UN procurement channels, national CDC cold-chain networks, and private clinic direct purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-dose scheduling recommendations from WHO SAGE constitute a high-growth disruption, collapsing multi-visit completion logistics while expanding addressable populations across Gavi-eligible countries and fundamentally altering manufacturer revenue-per-dose economics.
For Market Incumbents: Shield premium positioning in European tender markets by accelerating variant-adapted formulation development under EMA pathways, while consolidating adjuvant supply security through backward integration into AS04 component production. Capacity addition in Sub-Saharan African fill-finish partnerships defends volume share against emerging market manufacturers compressing cost structures through recombinant protein platform adoption. For New Entrants and Emerging Players: WHO prequalification fast-track pathways unlock access to donor-funded procurement pools previously closed to unqualified suppliers. Young adult catch-up segments in Latin American national programs represent the most penetrable white-space, with workplace and university health service delivery offering lower cold-chain infrastructure requirements than school-based adolescent campaigns. Target domestic fill-finish partnerships in South Asian markets with mature procurement capabilities to bypass bulk antigen manufacturing capital barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across recombinant protein platform manufacturing, displacing traditional mammalian cell culture infrastructure as the default production standard. Long-term viability over the projection horizon favors acquisition targets possessing WHO prequalification status and captive adjuvant supply arrangements, with single-dose policy adoption velocity serving as the critical inflection indicator for procurement volume trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Accelerated review processes reduce time-to-market for Gavi-subsidized procurement access. |
| Domestic Fill-Finish Partnership | Technology transfer agreements enable regional manufacturers to complete final formulation and packaging locally. |
| Single-Dose Scheduling Adoption | National immunization program recalibration expands addressable populations while compressing dose economics. |
| Adjuvant Supply Security Investment | Backward integration into AS04 component production reduces raw material availability exposure. |
| Digital Immunization Registry Integration | National health information system linkage improves coverage tracking and targeted reminder-recall interventions. |
Research Methodology
Initial hypotheses were tested against primary input from vaccine development executives, national immunization program managers, donor agency procurement officers, and regulatory affairs specialists, then refined through secondary validation against WHO prequalification databases, Gavi disbursement records, CDSCO and NMPA filing repositories, and national health information system coverage reports. Bottom-up demand modeling from country-level procurement tenders was triangulated with top-down supply capacity assessments across recombinant protein manufacturing platforms.
Variance decomposition across the analysis window isolated volume drivers by procurement channel, adjuvant formulation tier, and end-user age cohort, with segmentation dimensions spanning delivery mode, product type, and regional regulatory cluster. CAGRs were derived from multi-year supply agreement trajectories and policy adoption curves for single-dose scheduling, incorporating antigen manufacturing capacity expansion timelines and cold-chain infrastructure investment flows as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained Gavi financing commitment and WHO prequalification pathway continuity; material deviation in donor funding levels or regulatory scheduling recommendations would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market