
 Gestational Diabetes Market | 2026-2036
Gestational Diabetes Market Size, Share, and Industry Trends Forecast 2026-2036
Gestational Diabetes Market Analysis
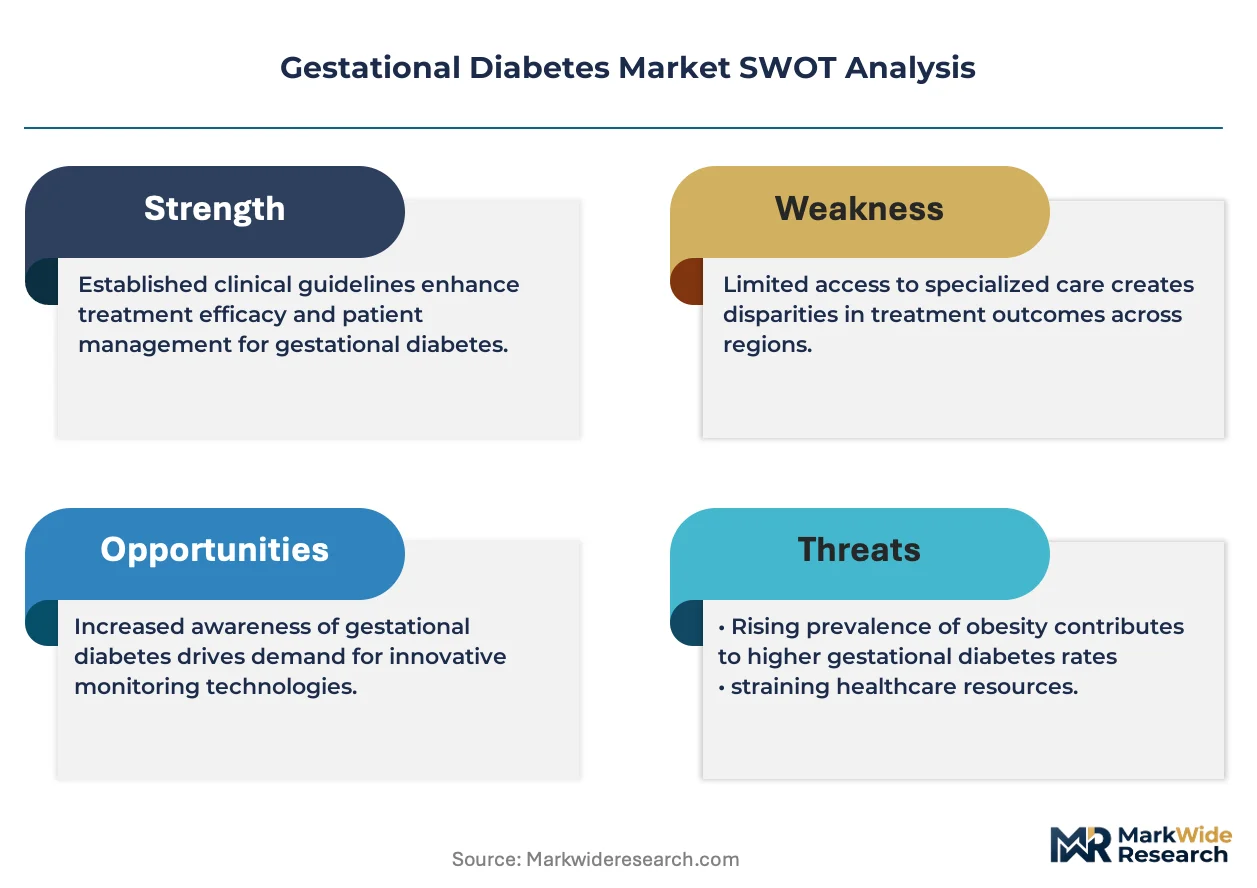
WHO prenatal care standards is hardening clinical expectations for glucose screening coverage. Novo Nordisk A/S leverages its insulin portfolio depth to sustain leadership in pregnancy-specific formulations. Eli Lilly and Company anchors North American supply through specialized manufacturing infrastructure. Sanofi S.A. competes across European and Asian markets with established distribution networks.
Gestational diabetes mellitus (GDM) constitutes glucose intolerance first recognized during pregnancy, typically diagnosed via oral glucose tolerance testing between 24 and 28 weeks gestation, with fasting plasma glucose thresholds of 92 mg/dL or higher triggering clinical intervention to prevent macrosomia and preeclampsia. Continuous glucose monitors are capturing margin pools as real-time data integration with telehealth platforms reduces clinic visit dependency. Automated insulin delivery systems represent the fastest-growing technology segment as closed-loop algorithms advance maternal glycemic safety. Test kits retain volume dominance in emerging markets where cost barriers limit device penetration.
FDA pregnancy drug labeling rules and EMA pharmacovigilance frameworks shape product development timelines and indication expansion for GDM therapeutics. WHO diagnostic criteria create harmonization pressure across national screening programs, while HIPAA and GDPR data provisions constrain how mobile health platforms transmit continuous glucose data. Stakeholders must monitor regulatory divergence between real-time device approval pathways and traditional pharmaceutical review cycles.
Market Dynamics
Automated insulin delivery systems are compressing clinical visit frequency while WHO diagnostic harmonization pressures national screening protocols to expand coverage thresholds. These dual forces reshape how glucose management technology penetrates prenatal care networks.
Growth Catalysts
- HIPAA-compliant data transmission:Regulatory clarity on maternal health data portability accelerates telehealth platform integration with continuous glucose monitors across United States prenatal networks.
- Oral glucose tolerance testing standardization:WHO diagnostic criteria harden clinical expectations for 24-28 week screening windows, expanding addressable patient pools in markets adopting harmonized protocols.
- Specialized manufacturing infrastructure:Concentrated production capacity for pregnancy-specific insulin formulations in North America reduces supply bottlenecks for high-purity active pharmaceutical ingredients.
Market Restraints
- Device cost barriers:Continuous glucose monitor hardware and sensor replacement cycles limit penetration in emerging markets where test kits dominate volume.
- EMA-FDA pharmacovigilance divergence:Pregnancy drug labeling rule differences between European and United States regulators extend product development timelines for cross-border indications.
- Distribution network fragmentation:Cold-chain requirements for insulin formulations concentrate supply control among established European and Asian logistics providers.
Strategic Opportunities
- Closed-loop algorithm advancement:Artificial intelligence-driven glycemic prediction is converging with pump hardware to create autonomous maternal safety systems.
- GDPR-constrained mobile health expansion:European data protection frameworks create compliant architecture templates exportable to privacy-sensitive markets.
- Integrated diabetes management programs:United States healthcare providers are bundling screening, monitoring, and therapeutic intervention into single-contract prenatal packages.
Industry Challenges
- Regulatory approval cycle misalignment:Real-time device approval pathways at FDA operate on fundamentally different timelines than traditional pharmaceutical review cycles.
- Telehealth platform integration complexity:Legacy electronic health record systems resist seamless continuous glucose data ingestion, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gestational Diabetes Market |
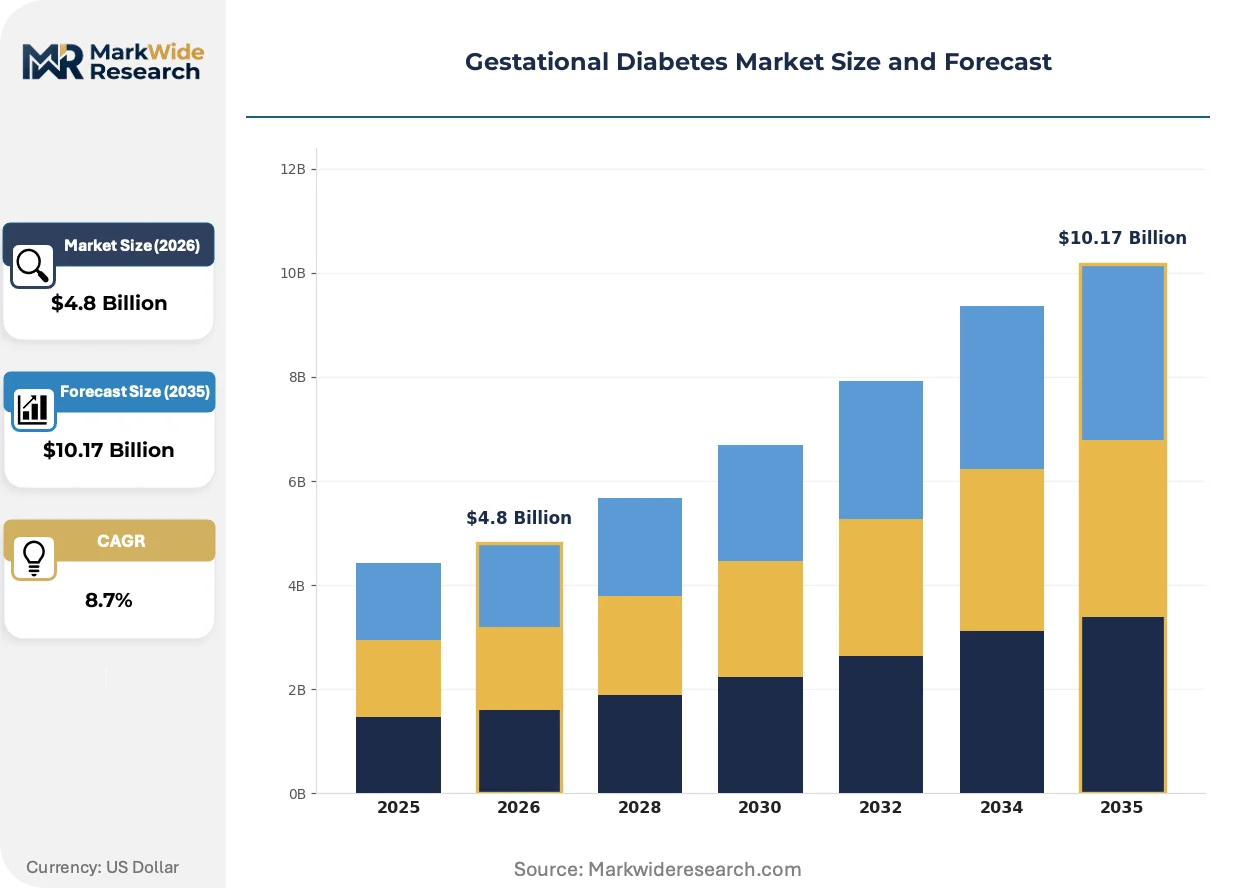
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kit, Continuous Glucose Monitor, Insulin, Medication Technology: Blood Glucose Monitoring, Automated Insulin Delivery, Wearable Devices, Mobile Health End User: Pregnant Women, Healthcare Providers, Diabetes Educators, Clinics Delivery Mode: Home Care, Hospital Care, Telehealth Services, Community Health |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Novo Nordisk A/S, Boehringer Ingelheim GmbH, AstraZeneca plc, Biocon Limited, Eli Lilly and Company, Johnson & Johnson, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gestational Diabetes Market Emerging Trajectories
Real-time glycemic data streams are restructuring how prenatal care teams intervene, with algorithmic decision support displacing reactive glucose management protocols. This shift compresses the gap between glucose excursion and clinical response.
Continuous glucose monitoring hardware is converging with cloud-based analytics platforms to enable predictive hypoglycemia alerts. Maternal-fetal medicine specialists in United States academic medical centers are adopting these systems at accelerating rates. The technology is converging with existing electronic health infrastructure to create closed-loop care pathways that reduce nursing labor intensity.
FDA pregnancy drug labeling rules are hardening evidentiary requirements for teratogenicity assessment in glucose-lowering therapies. Pharmaceutical developers must now generate trimester-specific safety data before indication expansion. United States sponsors are responding by front-loading reproductive toxicology studies earlier in development pipelines.
After-sales service unbundling is fragmenting how hospitals procure glucose management technology. Procurement teams now separate device acquisition from sensor subscription and algorithm licensing. United States integrated delivery networks are pioneering this disaggregation to optimize capital versus operational expenditure allocation.
Gestational Diabetes Market Segmentation
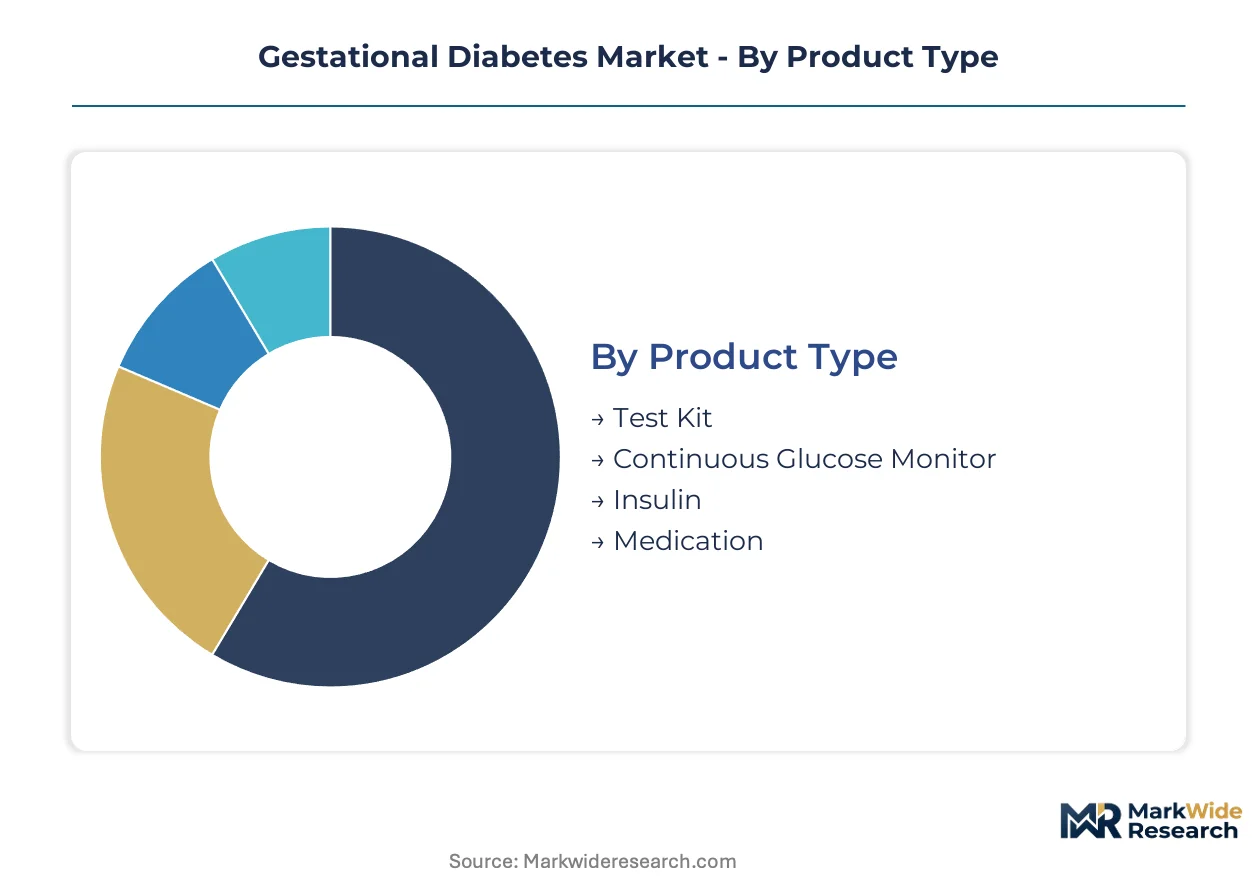
Segmentation in the gestational diabetes market reveals how clinical workflows, patient risk profiles, and reimbursement structures fragment demand across distinct product and service categories. Understanding these divisions exposes where margin pools concentrate versus where volume flows commoditize.
Product Type:
Standardization dominates glucose monitoring hardware while pregnancy-specific insulin formulations require deep customization for pharmacokinetic safety profiles.
- Test Kit:Disposable strip-based glucose measurement systems using capillary blood sampling. Demand concentrates in India, Brazil, and Southeast Asian markets where out-of-pocket payment limits device penetration. WHO diagnostic guideline adoption expands screening program procurement.
- Continuous Glucose Monitor:Subcutaneous sensor-transmitter systems providing real-time interstitial glucose readings. United States integrated delivery networks bundle these with telehealth platforms to reduce clinic visit frequency. FDA device approval pathways accelerate faster than pharmaceutical review cycles.
- Insulin:Pregnancy-specific formulations including human insulin and rapid-acting analogs with established teratogenicity profiles. Cold-chain distribution requirements concentrate supply control among established logistics providers.
- Medication:Oral glucose-lowering agents including metformin and glyburide used when insulin is declined or contraindicated. EMA-FDA pharmacovigilance divergence extends cross-border indication timelines.
Leading the category by volume: Test Kit. Growing fastest: Continuous Glucose Monitor.
Technology:
Cost tier stratification separates premium closed-loop systems from basic monitoring, with reimbursement thresholds determining technology access across patient populations.
- Blood Glucose Monitoring:Conventional fingerstick meters and test strips for periodic glucose assessment. Emerging markets retain volume dominance due to hardware affordability and minimal training requirements.
- Automated Insulin Delivery:Closed-loop pump-sensor systems with algorithmic basal rate adjustment. United States academic medical centers adopt these at accelerating rates as maternal-fetal medicine specialists prioritize hypoglycemia prevention. HIPAA-compliant data transmission enables telehealth integration.
- Wearable Devices:Non-invasive or minimally invasive glucose sensors integrated with consumer electronics. GDPR-constrained European markets export privacy-compliant architecture templates.
- Mobile Health:Smartphone applications for glucose logging, dietary tracking, and remote clinician communication. Legacy electronic health record systems resist seamless data ingestion, requiring costly middleware development.
Volume leader: Blood Glucose Monitoring. Steepest expansion trajectory: Automated Insulin Delivery.
End User:
Application-specific requirements fragment procurement, with institutional buyers prioritizing workflow integration while individual patients value convenience and discretion.
- Pregnant Women:Individual patients managing glucose through self-monitoring and lifestyle modification. United States demand for discrete wearable form factors drives miniaturization investment.
- Healthcare Providers:Obstetricians, maternal-fetal medicine specialists, and endocrinologists directing clinical care. Reimbursement for remote patient monitoring expands addressable service revenue.
- Diabetes Educators:Certified professionals delivering structured self-management training. Bundled prenatal program contracts in United States integrated delivery networks concentrate demand.
- Clinics:Outpatient facilities conducting screening, diagnosis, and routine management. WHO diagnostic harmonization pressures procurement standardization across national programs.
Dominant by patient contact volume: Healthcare Providers. Expanding most quickly: Telehealth-integrated remote monitoring services for Pregnant Women.
Delivery Mode:
Maturity gradients separate established hospital-based care from emerging distributed models, with capital intensity and regulatory burden determining expansion feasibility.
- Home Care:Self-administered glucose monitoring and insulin management outside clinical facilities. United States payer coverage for remote patient monitoring accelerates technology deployment.
- Hospital Care:Inpatient glycemic management during labor, delivery, and postpartum complications. Specialized insulin protocols and intensive monitoring requirements sustain premium pricing.
- Telehealth Services:Virtual consultations, remote glucose data review, and algorithm-driven intervention recommendations. After-sales service unbundling enables procurement teams to separate device acquisition from subscription licensing.
- Community Health:Screening and basic management through public health infrastructure and non-specialist providers. WHO prenatal care standards harden expectations for 24-28 week glucose screening coverage.
Current volume concentration: Hospital Care. Gaining share fastest: Telehealth Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insulin formulation manufacturing concentrates in North America and Western Europe while glucose monitoring device demand concentrates in East Asian and North American metropolitan health systems. Consumption patterns diverge sharply between premium continuous glucose monitor markets and cost-sensitive test kit regions.
United States
Integrated diabetes management programs at academic medical centers in Boston and the San Francisco Bay Area drive premium device procurement. FDA pregnancy drug labeling rules harden evidentiary requirements for teratogenicity assessment, extending development timelines for glucose-lowering therapies. Maternal-fetal medicine specialists at Johns Hopkins and Mayo Clinic anchor adoption of closed-loop automated insulin delivery systems.
Germany
EMA pharmacovigilance frameworks shape cross-border indication timelines for pregnancy-specific therapeutics. Cold-chain distribution networks centered on Frankfurt and Munich sustain insulin formulation supply control across Central European markets. Bavarian medical technology clusters advance wearable glucose sensor miniaturization for discrete maternal monitoring.
India
Out-of-pocket payment structures limit continuous glucose monitor penetration while expanding test kit volume through national screening programs. CDSCO regulatory pathways for pregnancy drug indications create parallel review tracks distinct from FDA and EMA timelines. Manufacturing concentration in Maharashtra and Gujarat supplies affordable insulin analogs to Southeast Asian and African markets.
Japan
PMDA device approval pathways accelerate faster than pharmaceutical review cycles, favoring technology-led glucose management solutions. METI industrial policy supports domestic production of high-precision glucose sensors for export to Asia-Pacific healthcare systems. Osaka-based medical device clusters specialize in miniaturized wearable form factors for maternal discretion.
Brazil
ANVISA harmonization pressures with FDA and EMA standards reshape import requirements for pregnancy-specific insulin formulations. Public health infrastructure in São Paulo and Rio de Janeiro expands community-based glucose screening under WHO prenatal care mandates. Cost barriers sustain test kit dominance despite growing private insurance coverage for continuous monitoring devices.
Gestational Diabetes Market Vendor Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established insulin portfolios rather than device-pure specialists. Market concentration reflects regulatory barrier height rather than manufacturing scale economies. Two strategic archetypes dominate: integrated diabetes care platforms bundling screening through therapy, and specialized maternal-fetal medicine technology suppliers. Competitive moves center on strategic partnerships between device manufacturers and telehealth platforms, plus geographic expansion of cold-chain distribution networks for temperature-sensitive biologics.
Within the pharmaceutical archetype, Novo Nordisk A/S and Eli Lilly and Company exemplify integrated insulin portfolio depth, while Sanofi S.A. occupies a position bridging European and Asian distribution networks. Among diversified health technology conglomerates, Johnson & Johnson represents the device-drug convergence strategy through its glucose monitoring and therapeutic intervention capabilities. Roche Holdings through F. Hoffmann-La Roche Ltd anchors the diagnostics-led entry path, leveraging testing infrastructure relationships to capture downstream therapeutic decisions.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Novo Nordisk A/S |
| Boehringer Ingelheim GmbH |
| AstraZeneca plc |
| Biocon Limited |
| Eli Lilly and Company |
| Johnson & Johnson |
| Sanofi S.A. |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient purity grades for pregnancy-specific insulin formulations cascade through three pricing tiers as cold-chain logistics costs accumulate across North American and European distribution networks. Test kit manufacturers in India and Southeast Asia compete on strip production economics while continuous glucose monitor suppliers extract premiums through sensor subscription bundling.
Pricing Analysis
Outcome-based reimbursement anchors value-based pricing for closed-loop automated insulin delivery systems in United States integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved pregnancy formulations from CE-marked European alternatives and emerging market test kit volumes. Pricing pressure stems from out-of-pocket payment structures in India and Brazil where test kit affordability dominates procurement decisions. Public health programs exhibit highest price sensitivity while academic medical centers absorb premium device costs through bundled prenatal contracts.
Supply Chain Analysis
Dual-sourcing requirements for high-purity insulin active pharmaceutical ingredients mandate qualification of both North American and European manufacturing sites to mitigate regulatory approval risk. Supply concentrates in Denmark, the United States, and Germany for finished insulin formulations while sensor components originate from Japan, South Korea, and Taiwan. Raw material dependencies span glucose oxidase enzymes, platinum electrode substrates, and specialized polymer membranes. Single-source vulnerability in subcutaneous sensor-transmitter assembly creates concentration risk. Distribution runs through temperature-controlled logistics networks anchored by Frankfurt, Indianapolis, and Singapore cold-chain hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EMA-FDA pharmacovigilance divergence is forcing subscale device manufacturers to exit or seek acquisition, concentrating margin capture among integrated insulin-delivery platforms.
For Market Incumbents: Deepen vertical integration into subcutaneous sensor manufacturing to capture margin pools currently flowing to Asian component suppliers. Expand cold-chain distribution capacity in India and Brazil to preempt emerging market entrants. Insulin portfolio breadth at Novo Nordisk and Eli Lilly creates defensive moats against device-pure competitors lacking pregnancy-specific formulation depth. For New Entrants and Emerging Players: Telehealth platform partnerships offer the lowest-friction entry path for algorithm developers seeking hospital system procurement relationships. White-space opportunity concentrates in GDPR-compliant mobile health architecture for European market export and middleware solutions for legacy electronic health record integration. Target United States community health clinics with subscription-based remote patient monitoring bundles priced below academic medical center contracts. For Investors and Strategic Acquirers: FDA breakthrough device designation for closed-loop maternal glucose management is the leading indicator that automated insulin delivery valuations will detach from traditional pump multiples. Long-term viability favors platform plays combining hardware, software, and therapeutic content over device-pure specialists facing reimbursement compression. Watch for CDSCO pregnancy indication approvals signaling emerging market insulin formulation consolidation candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | CMS remote patient monitoring codes unlock United States hospital system procurement at scale. |
| Regulatory Approval Pathway | FDA pregnancy drug labeling investments extend competitive exclusivity for teratogenicity-tested formulations. |
| Strategic Partnership | Telehealth platform alliances compress sales cycles for continuous glucose monitor hospital adoption. |
| Backward Integration | Captive sensor production insulates margins from Asian component supplier concentration. |
| Geographic Expansion | ANVISA harmonization investments position suppliers for Brazilian public health program procurement. |
Methodological Framework
Independent corroboration across maternal-fetal medicine specialists, hospital GPO contracts managers, diabetes educator networks, and regulatory affairs leads underwrites the qualitative findings on technology adoption patterns. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EMA centralized procedure assessments, CMS reimbursement databases, and WHO prenatal care guideline documents anchored supply-side and demand-side estimates. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation converged on segment-level projections.
Comparable-period anchoring to historical glucose monitoring device adoption curves and insulin formulation volume trends established the forecast window baseline across the analysis window. Segmentation dimensions modeled include product type, technology platform, end-user archetype, and delivery mode, with regional regulatory cluster as an additional healthcare-specific dimension. CAGRs derived from fitted growth curves applied to addressable patient pools and average revenue per user assumptions, incorporating continuous glucose monitor sensor replacement cycles and test kit strip consumption rates as industry-specific forecast inputs.
The model holds under stable WHO diagnostic guideline harmonization and sustained payer coverage for remote patient monitoring; deviation in FDA-EMA pharmacovigilance divergence or emerging market currency volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Mexico Oral Anti-Diabetic Drug Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market