
 Global Methane Hydrate Market | 2026-2036
Global Methane Hydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Methane Hydrate Market Foresight
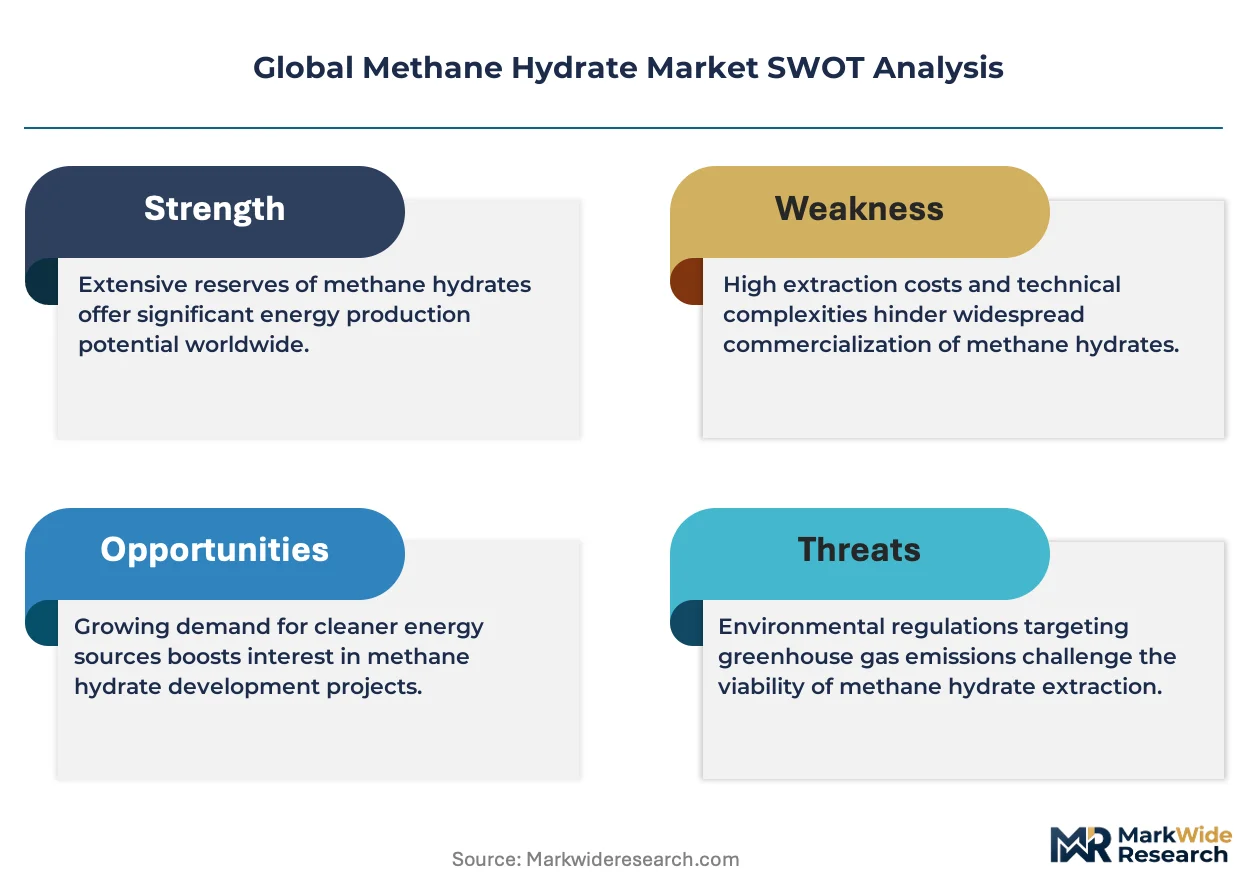
Conventional natural gas is hardening as a reference point against which methane hydrate economics must compete, pushing operators toward cost-intensive extraction technologies. Chevron Corporation leverages its deepwater drilling expertise to sustain pilot programs in hydrate-rich basins. JOGMEC anchors Japan's national research program through sustained public funding of offshore test production. ConocoPhillips competes via its Alaska-based thermal stimulation research, while Schlumberger dominates subsurface monitoring tool development for hydrate reservoirs.
Methane hydrate consists of methane molecules trapped within crystalline water structures under high-pressure, low-temperature conditions typically found in marine sediments and permafrost zones, requiring thermal stimulation or depressurization to release commercially viable gas flows. Gas extraction systems occupy the largest product category due to capital intensity and extended deployment cycles in subsea environments. Reservoir simulation technology leads R&D spending as operators model dissociation behavior before committing to field development. Energy recovery applications command the dominant revenue share, though carbon sequestration pilot projects are attracting capital from operators seeking dual-use reservoir strategies.
Japan's METI regulates offshore test production through strict environmental impact assessments, while the US Bureau of Ocean Energy Management governs lease access in Alaska and Gulf of Mexico hydrate provinces. China's MEE imposes marine ecosystem safeguards on South China Sea exploration campaigns, and South Korea's MFDS coordinates research permits through national energy research institutes. Stakeholders must monitor which regulatory body first streamlines commercial extraction licensing, as this jurisdiction will attract disproportionate capital deployment and equipment procurement.
Market Dynamics
Japan's METI-funded depressurization trials are compressing commercialization timelines while forcing operators to prove extraction economics against plummeting LNG spot prices. This regulatory acceleration is diverting capital toward subsea monitoring and reservoir simulation capabilities.
Growth Catalysts
- Japan's national extraction program:Sustained public funding of offshore test production creates guaranteed demand for specialized drilling equipment and subsurface monitoring systems.
- Carbon sequestration pilot projects:Dual-use reservoir strategies are attracting capital from operators seeking to monetize depleted hydrate formations for CO2 storage.
- Reservoir simulation technology:Advanced modeling of dissociation behavior is reducing field development risk and accelerating pilot-to-commercial transitions.
Market Restraints
- Conventional natural gas substitution:Hard LNG pricing benchmarks force hydrate projects to absorb cost-intensive thermal stimulation or depressurization capex without premium recovery.
- Permafrost zone concentration:Alaska and Siberian deposits require seasonal operational windows that compress effective drilling calendars and inflate equipment standby costs.
- Marine ecosystem safeguards:China's MEE regulations impose extended environmental impact timelines on South China Sea exploration, delaying permit-to-spud intervals.
Strategic Opportunities
- South Korea's MFDS research coordination:National energy research institutes are consolidating fragmented pilot permits into streamlined multi-year exploration licenses.
- US Bureau of Ocean Energy Management lease access:Gulf of Mexico hydrate provinces are opening competitive bidding rounds for integrated production-carbon storage projects.
- Subsea robotics convergence:Autonomous underwater vehicles are integrating with real-time reservoir monitoring to reduce manned intervention costs in deepwater basins.
Industry Challenges
- Geomechanical specialist scarcity:Reservoir engineers with hydrate-specific dissociation modeling expertise command premium compensation and extended recruitment cycles.
- Extended certification timelines:Subsea wellhead equipment must satisfy both API standards and jurisdiction-specific environmental bonds before deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Methane Hydrate Market |
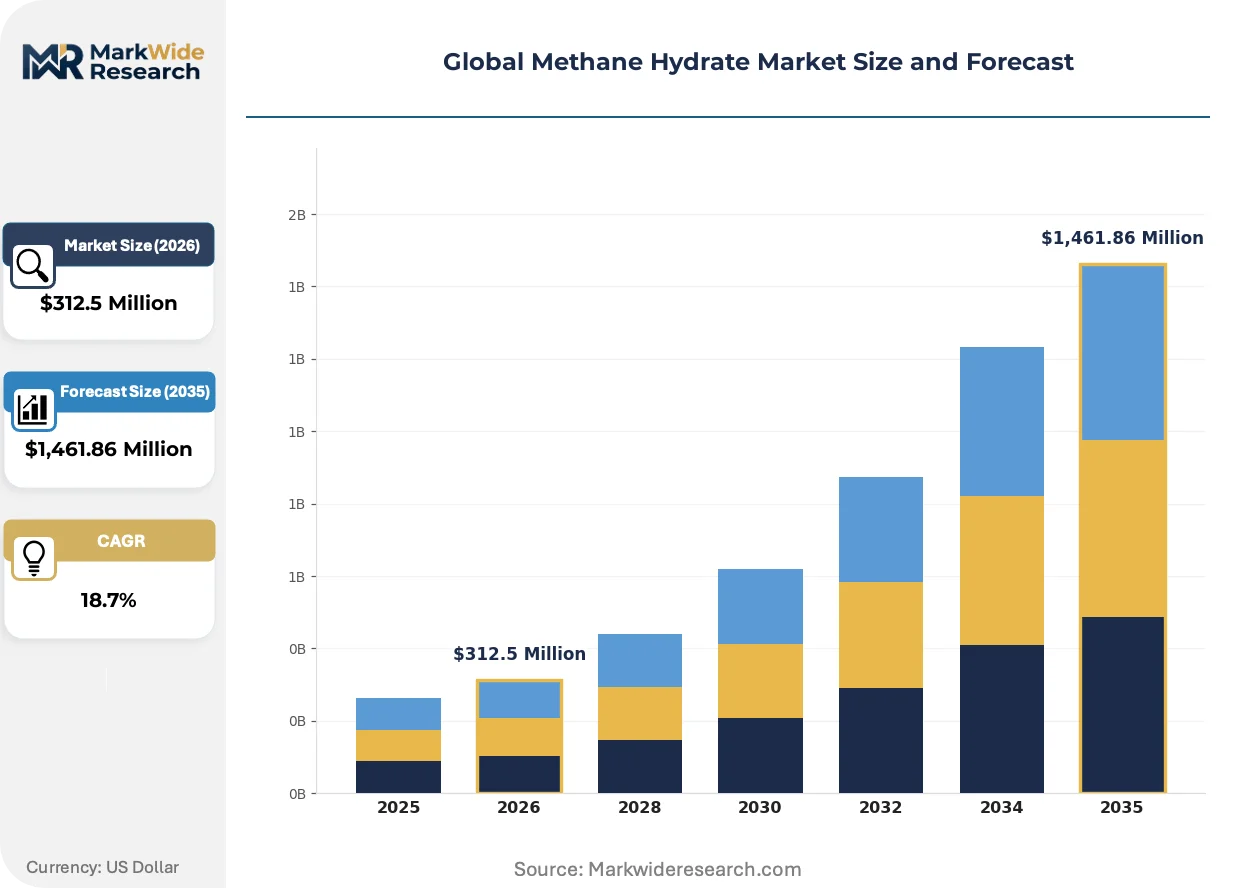
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Extraction Systems, Subsea Drilling Equipment, Pressure Control Devices, Hydrate Inhibitors, Monitoring Sensors Technology: Seismic Imaging, Reservoir Simulation, Thermal Stimulation, Gas Hydrate Dissociation, Remote Sensing Application: Energy Recovery, Carbon Sequestration, Environmental Monitoring, Marine Research, Pipeline Integrity End User: Oil & Gas Operators, Research Institutions, Environmental Agencies, Energy Service Companies, Offshore Contractors |
| Companies Covered | PetroChina Company Limited, Japan Oil, Gas and Metals National Corporation, Japan Petroleum Exploration Company Limited, Chevron Corporation, ConocoPhillips, Oil and Natural Gas Corporation, Schlumberger Limited, Shell Plc., Sinopec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Methane Hydrate Market Shifts & Advancements
Extraction methodologies are pivoting from thermal stimulation toward depressurization systems that reduce energy input intensity. Equipment suppliers are embedding fiber-optic sensing into production strings to capture real-time dissociation front movement.
Depressurization wellbore architecture is converging with subsea tieback systems developed for ultra-deepwater oil production. Japanese operators are piloting these hybrid configurations in Nankai Trough test fields. The structural compression of development capex is enabling project sanctioning at lower gas price assumptions than thermal alternatives required.
The US Bureau of Ocean Energy Management is finalizing integrated carbon storage lease amendments that allow hydrate producers to repurpose depleted reservoirs. This regulatory expansion is attracting integrated energy majors with dual competencies in gas production and sequestration operations. Alaska-based pilots are filing combined production-injection permit applications to capture this framework.
Japanese electric utilities are contracting directly with hydrate developers under take-or-pay structures that bypass traditional LNG trading intermediaries. This disintermediation is concentrating offtake negotiation leverage with a small pool of creditworthy buyers. Tokyo-based procurement teams are demanding reservoir performance guarantees that shift subsurface risk back to operators.
Global Methane Hydrate Market Segmentation
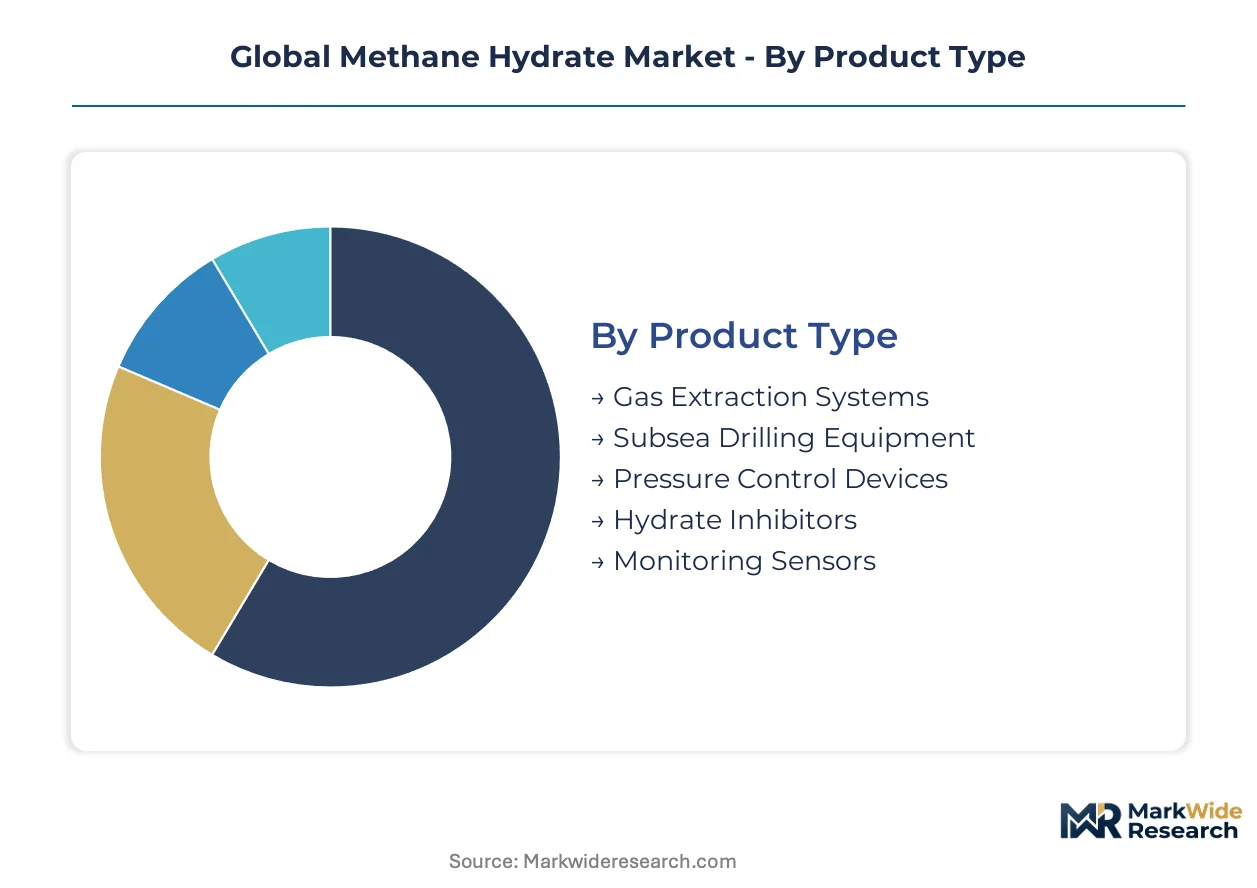
Methane hydrate commercialization demands specialized equipment and analytical capabilities that vary sharply by extraction environment and regulatory jurisdiction. Buyers prioritize proven subsea performance over cost minimization given the catastrophic failure risks in high-pressure marine sediments. This segmentation reveals where capital deployment concentrates and which technical competencies command premium pricing.
Product Type:
Capital intensity and subsea reliability requirements drive procurement decisions across all product categories.
- Gas Extraction Systems:Integrated wellhead assemblies combine depressurization pumps with subsea separation modules to sustain commercial gas flows from dissociating hydrate deposits. Japanese operators in the Nankai Trough anchor procurement volumes through METI-funded test production programs that mandate redundant system architectures.
- Subsea Drilling Equipment:Pressure-rated riser systems and blowout preventers adapted from ultra-deepwater oil operations require metallurgical modifications for hydrate-specific thermal cycling. Demand clusters in Alaska's permafrost zones where ConocoPhillips pilots thermal stimulation wells through seasonally constrained operational windows.
- Pressure Control Devices:Choke manifolds and subsea safety valves manage dissociation front propagation rates.
- Hydrate Inhibitors:Thermodynamic and kinetic chemical additives prevent secondary hydrate formation in production flowlines.
- Monitoring Sensors:Distributed temperature and pressure arrays track reservoir behavior during extended test production phases.
Volume sits with Gas Extraction Systems; growth tilts toward Monitoring Sensors as real-time reservoir intelligence becomes critical for project sanctioning.
Technology:
Risk mitigation through predictive modeling determines technology investment priority across operator portfolios.
- Reservoir Simulation:Finite-element models of dissociation kinetics and geomechanical response enable operators to optimize well spacing and production rates before committing to field development. Schlumberger dominates tool deployment through proprietary hydrate-specific modules that integrate with legacy petroleum engineering workflows.
- Thermal Stimulation:Downhole heating systems and warm water injection circuits release methane through controlled temperature elevation rather than pressure reduction. Alaska-based pilots favor this approach for onshore permafrost deposits where surface infrastructure supports energy-intensive thermal operations.
- Seismic Imaging:Ocean-bottom node surveys map hydrate saturation and free gas zones beneath marine sediments.
- Gas Hydrate Dissociation:Depressurization wellbore architectures reduce formation pressure to induce methane release.
- Remote Sensing:Satellite and aerial platforms monitor surface deformation and seafloor stability indicators.
Revenue concentrates in Reservoir Simulation; capability gaps are expanding most quickly in Gas Hydrate Dissociation as depressurization methods displace thermal alternatives.
Application:
Dual-use reservoir strategies are redirecting capital toward carbon-negative project architectures.
- Energy Recovery:Commercial gas production from hydrate deposits targets Japanese utilities seeking supply diversification beyond LNG import dependence. Tokyo Electric and other regional power companies structure take-or-pay contracts that transfer subsurface performance risk to developers.
- Carbon Sequestration:Repurposing depleted hydrate formations for CO2 storage attracts integrated majors with combined production and injection competencies. The US Bureau of Ocean Energy Management's integrated lease amendments enable Gulf of Mexico operators to monetize both extraction and sequestration phases.
- Environmental Monitoring:Baseline ecosystem assessment and operational impact tracking satisfy regulatory mandates.
- Marine Research:Academic and government programs characterize hydrate deposits for resource estimation and climate science.
- Pipeline Integrity:Hydrate plug prevention in conventional gas transport infrastructure sustains niche chemical demand.
Investment flows heaviest into Energy Recovery; regulatory momentum is accelerating fastest for Carbon Sequestration as jurisdictions amend lease frameworks.
End User:
Procurement authority and technical sophistication vary dramatically across buyer categories.
- Oil & Gas Operators:Supermajors and national oil companies control field development decisions and integrated project economics. Chevron leverages deepwater drilling expertise to sustain pilot programs in hydrate-rich basins while evaluating commercial thresholds against conventional gas benchmarks.
- Research Institutions:JOGMEC and South Korea's national energy research institutes coordinate government-funded exploration programs. These entities consolidate fragmented permits into multi-year licenses that guarantee equipment utilization for specialized drilling contractors.
- Environmental Agencies:Regulatory bodies mandate monitoring and mitigation standards through permit conditions.
- Energy Service Companies:Schlumberger and specialized contractors provide subsurface monitoring and reservoir engineering services.
- Offshore Contractors:Drilling and installation firms execute subsea construction under operator direction.
Procurement volume aggregates with Oil & Gas Operators; contract velocity is climbing fastest among Research Institutions as national programs advance from characterization to test production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's national hydrate research zones concentrate pilot project deployment through METI-funded depressurization trials, while the US Gulf of Mexico special lease areas attract integrated carbon storage developers seeking dual-use reservoir frameworks.
United States
Alaska's North Slope permafrost deposits and Gulf of Mexico marine basins host parallel thermal stimulation and depressurization pilots. The Bureau of Ocean Energy Management governs lease access through integrated carbon storage amendments that enable combined production-injection permits. Houston-based engineering clusters supply subsea monitoring equipment for hydrate-specific reservoir characterization.
Japan
Tokyo Electric and regional utilities structure take-or-pay contracts that transfer subsurface performance risk to hydrate developers. METI regulates offshore test production through strict environmental impact assessments that compress commercialization timelines. The Nankai Trough test fields anchor national procurement volumes for redundant gas extraction system architectures.
China
South China Sea exploration campaigns face extended environmental impact timelines under MEE marine ecosystem safeguards that delay permit-to-spud intervals. The country's dual carbon goals redirect capital toward hydrate deposits as alternative hydrocarbon sources to conventional LNG imports. Shenzhen-based research institutes coordinate seismic imaging programs for hydrate saturation mapping.
South Korea
National energy research institutes consolidate fragmented pilot permits into streamlined multi-year exploration licenses through MFDS coordination. The country's limited domestic conventional reserves accelerate government-funded extraction research comparable to Japan's program. Busan-Ulsan industrial clusters manufacture pressure-rated riser systems adapted for hydrate-specific thermal cycling.
India
The Oil and Natural Gas Corporation evaluates hydrate deposits in the Krishna-Godavari Basin as supply diversification beyond conventional LNG import dependence. The Ministry of Petroleum and Natural Gas frames exploration policy through national energy security priorities rather than commercial extraction timelines. Mumbai-based offshore contractors execute subsea construction under operator direction for characterization campaigns.
Global Methane Hydrate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy majors controlling field development decisions while national research institutes coordinate government-funded exploration programs. The vendor base clusters around three strategic archetypes: supermajors with deepwater drilling expertise, state-backed entities with sustained public funding access, and energy service companies dominating subsurface monitoring tool development. Competitive moves concentrate on strategic partnerships for pilot-to-commercial transitions and technology licensing for reservoir simulation capabilities.
Within the state-backed tier, Japan Oil, Gas and Metals National Corporation and Oil and Natural Gas Corporation exemplify national champion models that anchor government-funded research programs through sustained public capital deployment. Chevron Corporation represents the integrated major archetype, leveraging existing deepwater drilling competencies to sustain pilot programs in hydrate-rich basins while evaluating commercial thresholds against conventional gas benchmarks. These three entities occupy positions that reflect the market's bifurcation between publicly coordinated research phases and privately capitalized commercial development.
| Leading Market Players |
|---|
| PetroChina Company Limited |
| Japan Oil, Gas and Metals National Corporation |
| Japan Petroleum Exploration Company Limited |
| Chevron Corporation |
| ConocoPhillips |
| Oil and Natural Gas Corporation |
| Schlumberger Limited |
| Shell Plc. |
| Sinopec |
| Others |
Supply & Pricing Matrix
Marine ecosystem safeguards under China's MEE regulations gate both qualified supply and premium-tier pricing access, forcing equipment vendors to absorb extended certification timelines and environmental bonding costs that compress margins on standard-tier offerings while rewarding compliant suppliers with utility offtake premiums.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as Japanese utilities under METI-mandated test production schedules penalize equipment delays with contract termination clauses. Project-based long-term offtake structures prevail, with pricing differentiation driven by API certification tier and reservoir performance guarantee terms. Cost compression in standard-tier subsea equipment is intensifying because ConocoPhillips and Chevron are consolidating supplier panels around proven Nankai Trough performers. Research institutions prove least price-sensitive due to guaranteed public funding, while independent offshore contractors face acute margin pressure.
Supply Chain Analysis
Freight costs for pressure-rated riser systems and blowout preventers inflate procurement budgets as specialized metallurgical suppliers cluster in Japan, South Korea, and the US Gulf Coast. Raw material dependencies center on high-strength steel alloys, fiber-optic sensing cables, and thermodynamic hydrate inhibitors. Single-source vulnerability concentrates in Japanese electric arc furnace capacity for subsea-grade forgings. Distribution runs through integrated energy majors with captive project logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where reservoir simulation software capabilities and subsea monitoring tool development represent the decisive upstream levers players are pursuing to capture pilot-to-commercial transition economics.
For Market Incumbents: Acquire geomechanical modeling specialist teams to internalize dissociation expertise that Schlumberger currently monetizes through premium service contracts. Secure backward integration into fiber-optic sensing manufacturing to reduce dependence on third-party production string suppliers. Thermal stimulation research from Alaska-based competitors threatens depressurization-focused incumbents if LNG price benchmarks sustain downward pressure.
For New Entrants and Emerging Players: Depressurization wellbore architecture patents offer a technology-first wedge against established thermal stimulation incumbents. White-space targets include South Korea's consolidated multi-year exploration licenses and India's Krishna-Godavari Basin characterization campaigns. Carbon sequestration pilot project engineering represents the most penetrable application segment. A go-to-market angle through JOGMEC-funded equipment procurement channels bypasses direct competition with Chevron and ConocoPhillips.
For Investors and Strategic Acquirers: First commercial extraction licensing streamlining by any major regulator is the leading indicator that capital deployment velocity will accelerate beyond research-phase returns. Long-term viability hinges on hydrate production cost curves intersecting LNG spot price floors sustained across a multi-decade horizon. Acquisition target archetypes include reservoir simulation software vendors with hydrate-specific modules and subsea robotics developers with autonomous underwater vehicle integration capabilities. The signal to monitor is METI approval of sustained production periods exceeding current test-phase limitations.
| Strategic Initiative | Industry Significance |
|---|---|
| Depressurization Technology Licensing | Japanese operators in the Nankai Trough accelerate commercialization timelines through proven wellbore architectures. |
| Integrated Carbon Storage Lease Amendment | The US Bureau of Ocean Energy Management enables Gulf of Mexico operators to monetize dual-use reservoir strategies. |
| Reservoir Simulation Specialist Acquisition | Schlumberger's proprietary hydrate modules command premium pricing that integrated majors seek to internalize. |
| Subsea Robotics Convergence Partnership | Autonomous underwater vehicle integration with real-time monitoring reduces manned intervention costs in deepwater basins. |
| Take-or-Pay Utility Contract Structuring | Tokyo Electric and regional Japanese utilities transfer subsurface performance risk to hydrate developers through guaranteed offtake. |
Research Methodology
Multi-period observation of METI-funded test production milestones, JOGMEC equipment procurement cycles, and Bureau of Ocean Energy Management lease amendment progressions anchored the trend analysis, supplemented by interviews with deepwater drilling project managers, subsea equipment procurement leads at integrated majors, reservoir simulation software engineers, environmental compliance officers at national research institutes, and carbon sequestration project developers. Secondary validation drew from EIA unconventional resource assessments, IEA methane hydrate technology roadmaps, FERC LNG pricing benchmarks, and Japanese government energy white papers. Bottom-up equipment procurement volume estimates triangulated against top-down national program budget allocations.
Input-output matrices mapped depressurization pump deployment rates, subsea monitoring sensor installation counts, and reservoir simulation software license sales against projected commercial production timelines across the analysis window. Segmentation dimensions modeled included extraction methodology, product system architecture, application end-use, and regulatory jurisdiction framework. CAGRs derived from fitted growth curves applied to equipment procurement trajectories observed in Japan's Nankai Trough program and Alaska's permafrost zone pilots. Industry-specific forecast inputs incorporated LNG spot price volatility assumptions and carbon credit market development scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt LNG price collapse or accelerated regulatory licensing streamlining by competing jurisdictions. Forecasts reflect documented assumptions regarding dissociation kinetics, geomechanical reservoir response, and environmental impact assessment timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gas to Liquid (GTL) Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Biobutanol Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
Renewable Heating Fuels Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
China LNG Market
Fuels
Coal Briquette Box Market
Fuels
Gas Hydrates Market
Fuels
Chafing Fuel Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Canada Coal Market
Fuels
Fuel Conditioning System Market