
 Oil & Gas Defoaming Separator Market | 2026-2036
Oil & Gas Defoaming Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Oil & Gas Defoaming Separator Market Insights
Market Context with Strategic Players
North American pressure-pumping capacity is decoupling from traditional three-phase separator procurement patterns as operators prioritize integrated defoaming systems for unconventional wells. Schlumberger Limited leverages its integrated drilling and completions portfolio to bundle separator technology with digital monitoring platforms. Baker Hughes competes through specialized high-pressure vertical separators designed for Permian Basin gas-lift operations. Halliburton Company sustains its position via chemical-mechanical hybrid systems that reduce foam-induced downtime in tight-oil formations.
Technical Definition and Structural Segments
Oil and gas defoaming separators are pressure vessels engineered to destabilize foam interfaces through mechanical agitation, chemical injection, or thermal conditioning, typically operating at pressures from 150 to 5,000 psi and temperatures up to 200°C to separate entrained gas from liquid hydrocarbon streams. These units serve the primary commercial purpose of protecting downstream compressors and processing equipment while maximizing liquid yield from foam-prone production fluids. Centrifugal separators dominate capital deployment in offshore environments where space constraints and high throughput requirements favor compact rotational designs, while horizontal separators anchor onshore infrastructure in the Middle East due to superior gas-liquid residence time and easier maintenance access. Chemical treatment technology is displacing purely mechanical approaches in shale plays where variable foam stability demands adaptive antifoam dosing integrated with real-time sensors.
Regulatory Framework and Forward Outlook
EPA effluent limitation guidelines and MARPOL Annex I standards enforced by flag-state maritime administrations are mandating reduced oil-in-water discharge limits, directly shaping separator performance specifications and retrofit timelines across US coastal and international shipping-adjacent facilities. OSHA process safety management requirements and API 12J design standards further constrain equipment certification pathways, elevating engineering validation costs for new market entrants. Stakeholders must monitor how methane-emission detection rules and evolving Scope 3 reporting obligations redirect capital toward separators with sealed foam-breaking chambers and integrated vapor-recovery units.
Market Dynamics
Offshore operators in the Gulf of Mexico and North Sea are accelerating replacement of legacy gravity separators with integrated defoaming systems to handle high-gas-fraction crude from maturing reservoirs and unconventional completions.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Tightening oil-in-water discharge standards in US coastal waters force facility upgrades, expanding retrofit demand for separators with real-time foam monitoring.
- Shale formation chemistry:Variable surfactant loading in Permian and Bakken tight-oil streams requires adaptive antifoam injection systems, pulling chemical-mechanical hybrid units into field development plans.
- Norwegian offshore cluster:Aging field redevelopment at Johan Sverdrup and Snøhvit drives procurement of compact centrifugal separators with sealed foam-breaking chambers for platform space constraints.
Market Restraints
- Specialized alloy costs:Sour service applications require Inconel and duplex stainless steel pressure vessels, exposing manufacturers to nickel price volatility and extended mill lead times.
- Fabrication concentration:Heavy-wall pressure vessel manufacturing clusters in South Korea and China create single-source risk for integrated separator packages above 3,000 psi design pressure.
- API 12J certification friction:Third-party validation of novel foam-breaking internals adds 6-12 months to commercialization timelines for mechanically intensive designs.
Strategic Opportunities
- Brazil pre-salt expansion:Petrobras development of Búzios and Mero fields creates demand for high-pressure vertical separators handling CO2-rich foamy crude at 2,000+ meter water depths.
- Methane detection rules:EPA super-emitter response program and evolving Scope 3 reporting obligations redirect capital toward separators with integrated vapor recovery and sealed chambers.
- Digital twin convergence:Coupling CFD-modeled foam dynamics with live sensor feeds enables predictive antifoam dosing, opening subscription revenue streams for separator OEMs.
Industry Challenges
- Multiphase flow modeling expertise:Separator vendors face acute shortage of computational fluid dynamics specialists capable of validating foam-breaking internals under field-relevant pressure-temperature conditions.
- Legacy system integration:Brownfield installations require custom manifold modifications to accommodate compact centrifugal units within existing platform footprint and structural load limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil & Gas Defoaming Separator Market |
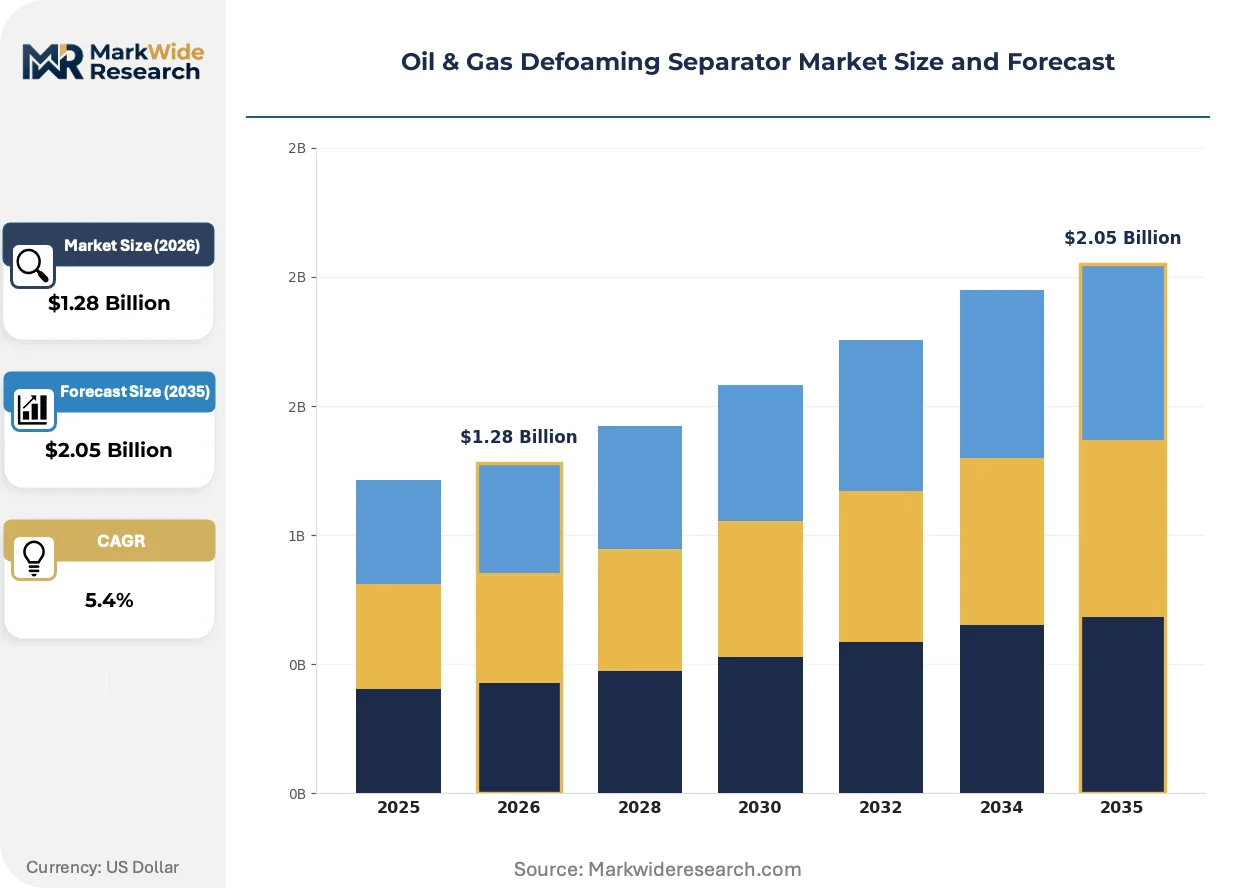
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.05 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Separators, Plate Separators, Vertical Separators, Horizontal Separators Application: Oil Recovery, Gas Processing, Wastewater Treatment, Chemical Processing End User: Oil Producers, Gas Utilities, Petrochemical Plants, Refineries Technology: Mechanical Separation, Chemical Treatment, Thermal Treatment, Membrane Filtration |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes, TechnipFMC plc, Alfa Laval AB, GEA Group AG, National Oilwell Varco, Honeywell International Inc., Exterran Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil & Gas Defoaming Separator Market Trends and Innovations
Real-time sensing and adaptive chemical injection are compressing the traditional separation train, collapsing discrete process steps into unified vessels that respond dynamically to inlet foam stability variations.
Machine learning algorithms trained on multiphase flow patterns are integrating with acoustic foam detection sensors to automate antifoam dosing rates. Permian Basin operators deploy these systems on pad sites with high water-cut variability, reducing chemical consumption by eliminating overdosing during stable production periods. The technology is integrating formerly separate process control and mechanical separation disciplines into unified vendor offerings.
REACH restrictions on perfluorinated surfactants are eliminating legacy antifoam chemistries from European offshore procurement specifications. Operators in the Norwegian North Sea now require biodegradable foam-breaking formulations certified under OSPAR Convention guidelines, forcing chemical suppliers to reformulate active ingredients. This regulatory pivot elevates mechanical foam-breaking methods in EU waters while chemical-dependent systems retain advantage in jurisdictions with less stringent environmental frameworks.
Integrated service contracts now bundle separator hardware with chemical supply and performance guarantees, displacing traditional equipment-only procurement. Major independents in the Permian and Eagle Ford negotiate throughput-based pricing where vendors assume foam-related downtime risk. This model concentrates most visibly among private equity-backed operators seeking to minimize upfront capital deployment and transfer operational liability to equipment suppliers.
Oil & Gas Defoaming Separator Market Segmentation
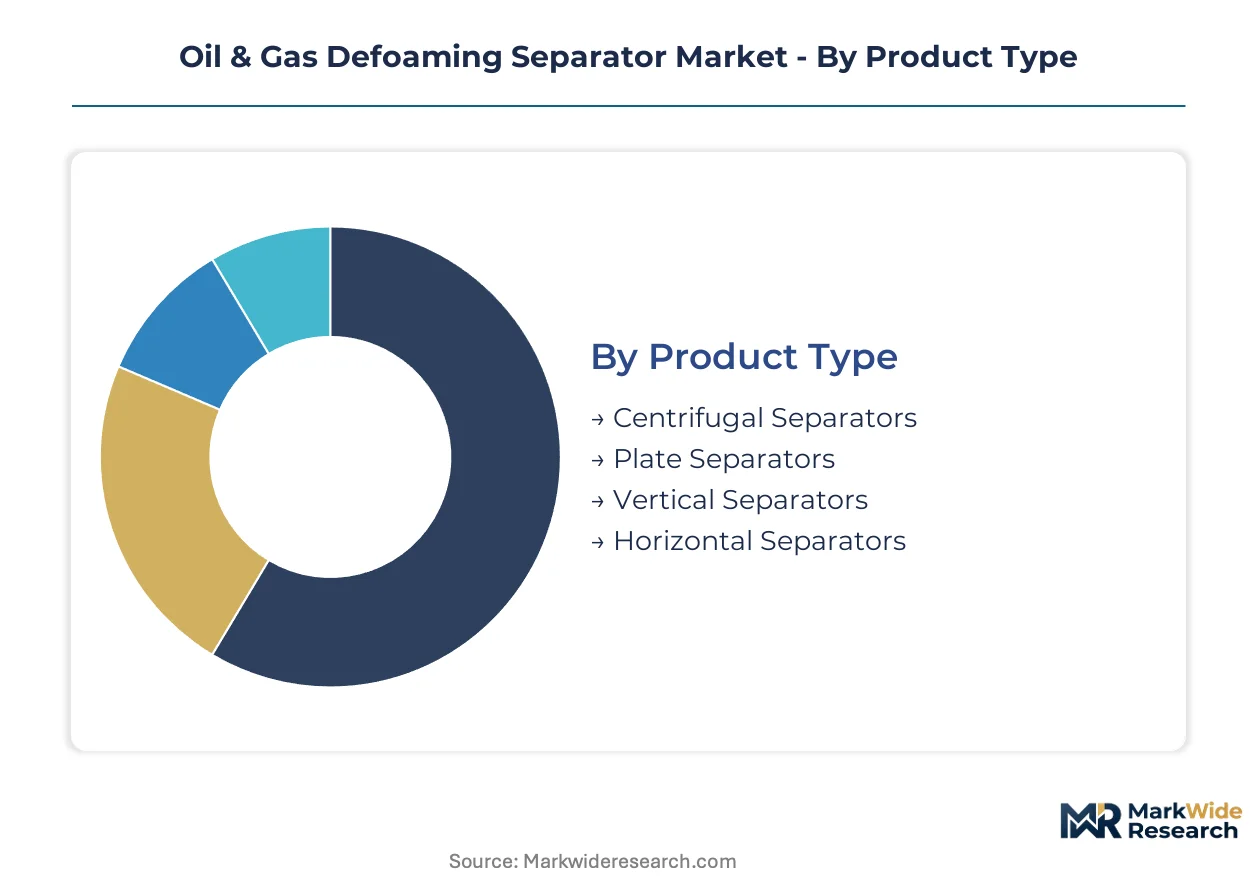
Defoaming separator procurement varies sharply across product configurations and operational contexts. Upgrade cycles differ by segment: offshore platforms favor compact centrifugal units for space-constrained retrofits, while onshore shale operators prioritize chemical-mechanical hybrids for variable foam stability.
Product Type:
Replacement cycles for legacy gravity separators are accelerating in the Gulf of Mexico and North Sea, driving divergent equipment preferences by installation environment.
- Centrifugal Separators:Rotational designs exploit centrifugal force to separate entrained gas from liquid streams at high throughput rates. Norwegian offshore cluster operators at Johan Sverdrup and Snøhvit specify these units for platform space constraints and sealed foam-breaking chamber requirements.
- Horizontal Separators:Extended gas-liquid residence time and easier maintenance access characterize these vessels. Middle Eastern onshore infrastructure anchors demand here, though brownfield integration challenges slow retrofit adoption.
- Vertical Separators:High-pressure configurations serve gas-lift operations in the Permian Basin.
- Plate Separators:Compact footprint suits modular processing trains in tight-oil pad developments.
Volume placements concentrate in Horizontal Separators; the faster expansion belongs to Centrifugal Separators.
Application:
Cost tier differentiation separates capital-intensive offshore gas processing from chemical-intensive onshore oil recovery operations.
- Gas Processing:High-gas-fraction crude streams from maturing reservoirs demand integrated defoaming systems to protect downstream compressors. Brazil pre-salt fields at Búzios and Mero create demand for high-pressure vertical separators handling CO2-rich foamy crude at extreme water depths.
- Oil Recovery:Maximizing liquid yield from foam-prone production fluids drives tight-oil operator procurement. Permian and Bakken producers specify adaptive antifoam injection systems for variable surfactant loading in unconventional completions.
- Wastewater Treatment:EPA effluent limitation guidelines mandate oil-in-water discharge reductions at US coastal facilities.
- Chemical Processing:Petrochemical integration requires corrosion-resistant alloy specifications for sour service applications.
Capital deployment clusters in Gas Processing; Oil Recovery is gaining share fastest.
End User:
Customer type determines procurement model: integrated majors negotiate performance-based contracts while independents prioritize capital efficiency.
- Oil Producers:Independent operators in the Permian and Eagle Ford drive adoption of throughput-based pricing models where vendors assume foam-related downtime risk.
- Gas Utilities:Pipeline operators specify separators with integrated vapor recovery to address EPA super-emitter response program requirements.
- Refineries:Downstream integration demands API 12J certified vessels with extended validation timelines.
- Petrochemical Plants:Process safety management requirements under OSHA constrain equipment certification pathways.
Contract volumes concentrate with Oil Producers; Gas Utilities show the steepest expansion trajectory.
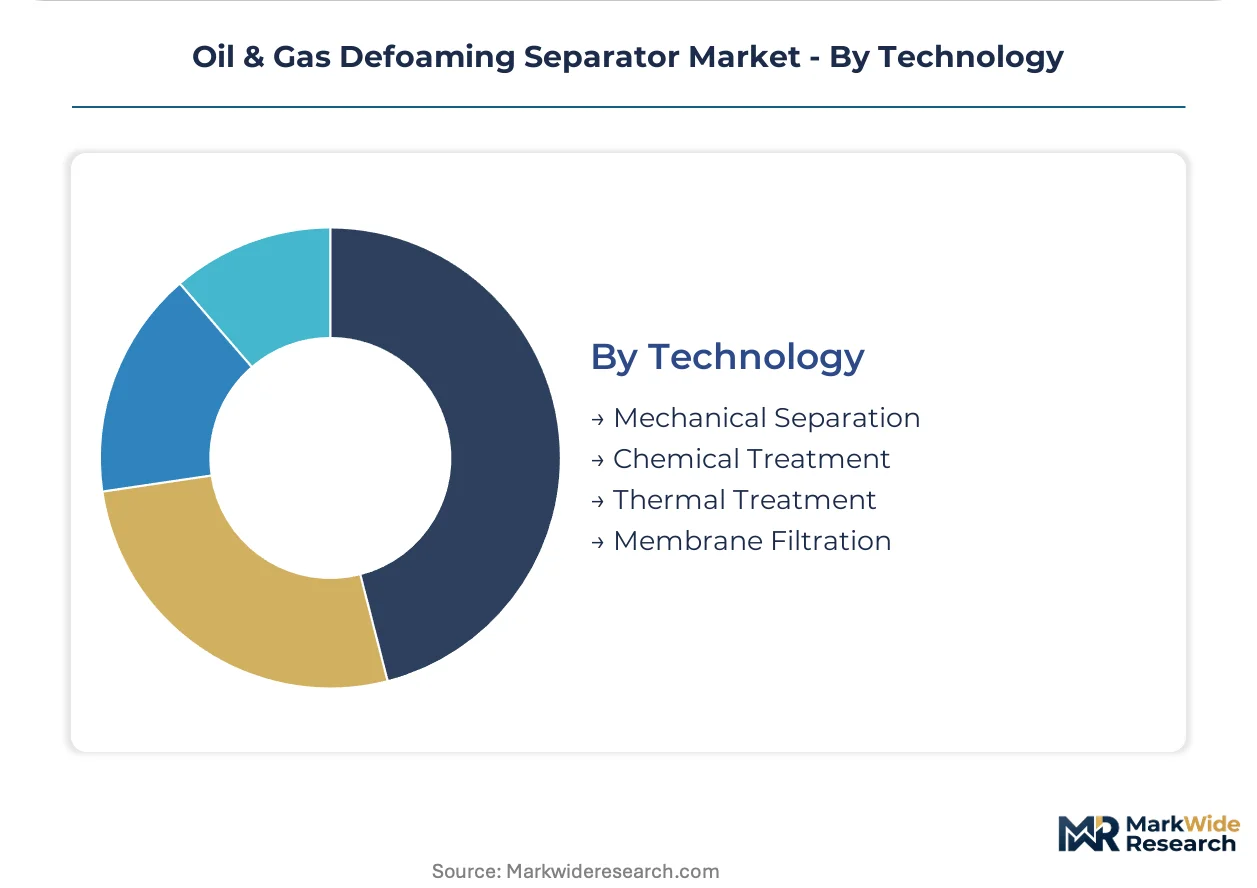
Technology:
Maturity curves separate established mechanical methods from digitally-enabled chemical treatment systems.
- Chemical Treatment:Adaptive antifoam dosing integrated with real-time sensors is displacing purely mechanical approaches in shale plays. REACH restrictions on perfluorinated surfactants force reformulation for European offshore procurement, elevating biodegradable alternatives under OSPAR Convention guidelines.
- Mechanical Separation:Centrifugal and gravity-based methods retain advantage in jurisdictions with less stringent environmental frameworks. Fabrication concentration in South Korean and Chinese heavy-wall pressure vessel manufacturing creates single-source risk for integrated packages above 3,000 psi design pressure.
- Thermal Treatment:Temperature conditioning serves heavy oil processing with elevated viscosity challenges.
- Membrane Filtration:Emerging applications in produced water polishing face membrane fouling constraints.
Installed base concentrates in Mechanical Separation; Chemical Treatment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel deposits in Indonesia and sulfide ore bodies in Canada anchor raw-material supply chains for corrosion-resistant alloys used in high-pressure separator fabrication. Procurement patterns track these metal flows toward fabrication clusters in East Asia and North American assembly points.
United States
Gulf of Mexico offshore operators replace legacy gravity separators with integrated defoaming systems for high-gas-fraction crude streams. EPA effluent limitation guidelines mandate oil-in-water discharge reductions at coastal facilities. Houston anchors engineering procurement for Permian Basin gas-lift operations requiring high-pressure vertical configurations.
Norway
Aging field redevelopment at Johan Sverdrup and Snøhvit drives demand for compact centrifugal units with sealed foam-breaking chambers. OSPAR Convention guidelines under the country's national environmental regulator enforce biodegradable antifoam formulations. Stavanger concentrates platform engineering expertise for North Sea retrofit campaigns.
Brazil
Petrobras development of Búzios and Mero pre-salt fields creates demand for separators handling CO2-rich foamy crude at extreme water depths. ANVISA-equivalent maritime safety requirements constrain equipment certification pathways. Rio de Janeiro hosts project management for deepwater separator packages.
China
Heavy-wall pressure vessel manufacturing clusters supply integrated separator packages above 3,000 psi design pressure. MEE enforcement of marine pollution standards shapes export specifications for offshore equipment. Dalian and Qingdao anchor fabrication capacity serving domestic shale and international project demand.
Saudi Arabia
Sour service applications in mature onshore fields require Inconel and duplex stainless steel specifications for hydrogen sulfide resistance. SFDA-aligned process safety requirements elevate engineering validation costs for new market entrants. Dhahran concentrates procurement decision-making for Aramco field redevelopment programs.
Oil & Gas Defoaming Separator Market Competitive Landscape
Global majors compete with regional champions across technology integration and fabrication geography. The vendor base organizes around three tiers: integrated oilfield service conglomerates with bundled digital platforms, specialized separation equipment fabricators with alloy expertise, and regional pressure-vessel shops serving brownfield retrofit demand. Dominant competitive moves include capacity expansion in South Korean and Chinese heavy-wall manufacturing, plus strategic partnerships pairing chemical suppliers with mechanical OEMs for hybrid system offerings.
Among US-based oilfield service providers, Schlumberger Limited, Halliburton Company, and Baker Hughes occupy positions spanning the integrated services archetype. These entities exemplify bundled procurement models where separator hardware converges with chemical supply and performance guarantees. European industrial conglomerates TechnipFMC plc, Alfa Laval AB, and GEA Group AG represent specialized equipment fabrication expertise. National Oilwell Varco anchors North American manufacturing capacity for high-pressure configurations. Honeywell International Inc. and Exterran Corporation sit within process control and modular system integration tiers respectively.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes |
| TechnipFMC plc |
| Alfa Laval AB |
| GEA Group AG |
| National Oilwell Varco |
| Honeywell International Inc. |
| Exterran Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive fabrication of heavy-wall pressure vessels in South Korean and Chinese mill clusters anchors supplier pricing power through nickel alloy sourcing control and extended lead-time premiums for sour-service specifications.
Pricing Analysis
Warranty and performance-guarantee bundling now separates vendor tiers in separator procurement, with integrated service contracts commanding premium positioning over equipment-only sales. Three-tier pricing structure across premium, standard, and economy levels reflects API 12J certification status, alloy grade specifications, and real-time monitoring integration. Cost compression in standard-tier horizontal vessels is intensifying because fabrication capacity expansion in Dalian and Qingdao has compressed lead times for onshore Middle Eastern orders. Independent operators in Permian tight-oil plays exhibit highest price sensitivity, while Norwegian offshore cluster procurement teams prioritize sealed-chamber reliability over unit cost.
Supply Chain Analysis
Refurbishment flows for legacy gravity separators create secondary material streams that feed brownfield retrofit programs in the Gulf of Mexico and North Sea, extending vessel lifecycle economics for cash-constrained independents. Raw material procurement draws from Indonesian nickel deposits, Canadian sulfide ore bodies, and Finnish stainless steel mills to supply Inconel and duplex specifications for hydrogen sulfide resistance. Component fabrication concentrates in South Korea, China, and Germany, exposing the market to single-source vulnerability when design pressures exceed 3,000 psi. Distribution runs through EPC contractors and integrated oilfield service providers rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 12J certification friction and specialized alloy cost volatility are forcing sub-scale fabricators toward exit or acquisition, consolidating vendor tiers around integrated service conglomerates and regional alloy specialists.
For Market Incumbents: Deploy digital twin convergence as the primary defensive lever. Integrate CFD-modeled foam dynamics with live sensor feeds to lock in subscription revenue streams and raise switching costs for Permian operators. Acquire specialist chemical suppliers to secure biodegradable antifoam formulations ahead of OSPAR Convention expansion. This counters emerging pure-play sensor vendors and REACH-driven chemistry disruption. For New Entrants and Emerging Players: Chemical suppliers with OSPAR-certified biodegradable formulations represent the most penetrable partnership channel for mechanical OEMs seeking European offshore qualification. Target Brazil pre-salt procurement through Petrobras-approved local content partnerships, where ANVISA-equivalent maritime safety requirements create certification barriers for established vendors. White-space exists in methane-detection-integrated vapor recovery systems for EPA super-emitter compliance. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated oilfield service providers seeking alloy expertise and regional fabrication capacity. Long-term viability favors vendors with captive access to nickel supply chains and certified biodegradable chemistry portfolios. Monitor EPA methane rule enforcement intensity and Scope 3 reporting mandate expansion as inflection signals for vapor-recovery-integrated separator demand.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Heavy-Wall Fabrication | South Korean and Chinese mill investments address 3,000+ psi design pressure bottlenecks for pre-salt applications. |
| Backward Integration into Nickel Alloy Supply | Indonesian ore access and Finnish stainless partnerships reduce Inconel price volatility exposure for sour-service specifications. |
| Digital Twin Platform Development | CFD-modeled foam dynamics with predictive antifoam dosing create recurring revenue from Permian pad operators. |
| Biodegradable Chemistry Certification | OSPAR Convention alignment opens Norwegian offshore cluster procurement while REACH restrictions eliminate legacy competitors. |
| Integrated Vapor Recovery Partnership | EPA super-emitter response program compliance positions separators for methane detection rule expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by structured interviews with separator procurement managers at integrated majors, fabrication engineers at South Korean and Chinese heavy-wall vessel mills, chemical supply technical directors, and offshore platform maintenance supervisors. Primary fieldwork combined with API 12J certification databases, EPA effluent guideline enforcement records, MARPOL Annex I flag-state inspection reports, and OSPAR Convention discharge permit filings. Bottom-up equipment shipment tracking and top-down EPC contract value analysis were triangulated against alloy price indices and regional fabrication capacity utilization.
Data-stream reconciliation across primary interview transcripts and secondary regulatory databases shaped the analytical framework. Segmentation dimensions modeled include product configuration, application context, end-user procurement model, and technology maturity curve across the projection horizon. CAGRs were derived from equipment shipment trajectories, retrofit cycle timing, and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated nickel price volatility scenarios and REACH chemistry restriction timelines.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting alloy tariffs, unanticipated breakthroughs in membrane foam-breaking technology, and force majeure disruptions to South Korean or Chinese fabrication clusters. Forecasts reflect documented assumptions about regulatory enforcement intensity and offshore field redevelopment pacing. Practitioners should monitor EPA methane rule litigation outcomes and Petrobras local content requirement adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Mud Balance Market