
 Europe Seismic Services Market | 2026-2036
Europe Seismic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Seismic Services Market Foresight
Aftermarket monitoring revenue is rewriting margin economics across the Europe seismic services landscape. CGG SA leverages its subsurface imaging software ecosystem to sustain recurring licensing income from North Sea operators. Fugro NV anchors its competitive stance through integrated offshore vessel ownership and seabed-to-surface data acquisition control. Schlumberger Ltd dominates the high-end 4D reservoir monitoring segment through proprietary ocean-bottom node technology deployment.
Seismic services encompass the acquisition, processing, and interpretation of elastic-wave propagation data using arrays of geophones, hydrophones, and accelerometers deployed across land, marine, and borehole environments, with source energies ranging from vibroseis trucks to controlled marine air-gun arrays generating acoustic impulses from 10 to 300 Hz. These services enable subsurface structural mapping, hydrocarbon prospect de-risking, and time-lapse reservoir surveillance for extraction optimization. Offshore seismic surveying claims the dominant value share as operators prioritize deep-water Norway and UK Atlantic margin plays, while microseismic technology represents the fastest-expanding technology segment driven by induced-seismicity monitoring requirements and carbon capture storage site characterization. Data processing services concentrate margin pools through proprietary algorithm suites and high-performance computing clusters that transform raw shot gathers into migrated depth images.
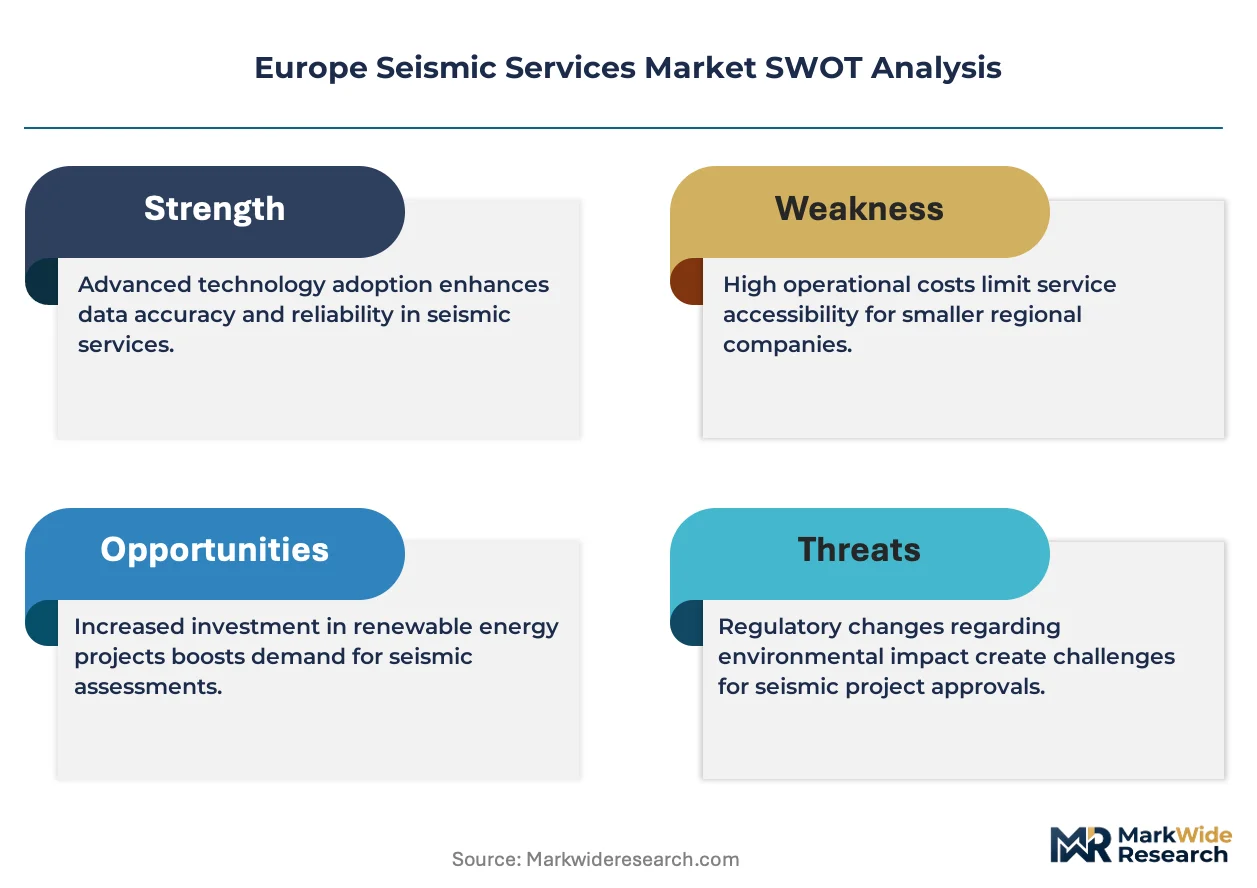
The EU Green Deal and REACH frameworks mandate methane leak detection and subsurface integrity verification for hydrocarbon and CO2 storage operations, directly expanding passive seismic and microseismic monitoring procurement. Norway's Petroleum Safety Authority and the UK North Sea Transition Authority enforce stringent baseline seismicity monitoring before hydraulic stimulation or injection activities, embedding continuous monitoring into operational permits. Stakeholders must weigh technology portfolio bets between traditional hydrocarbon exploration services and emerging carbon storage site characterization contracts as European energy transition policy redefines addressable demand.
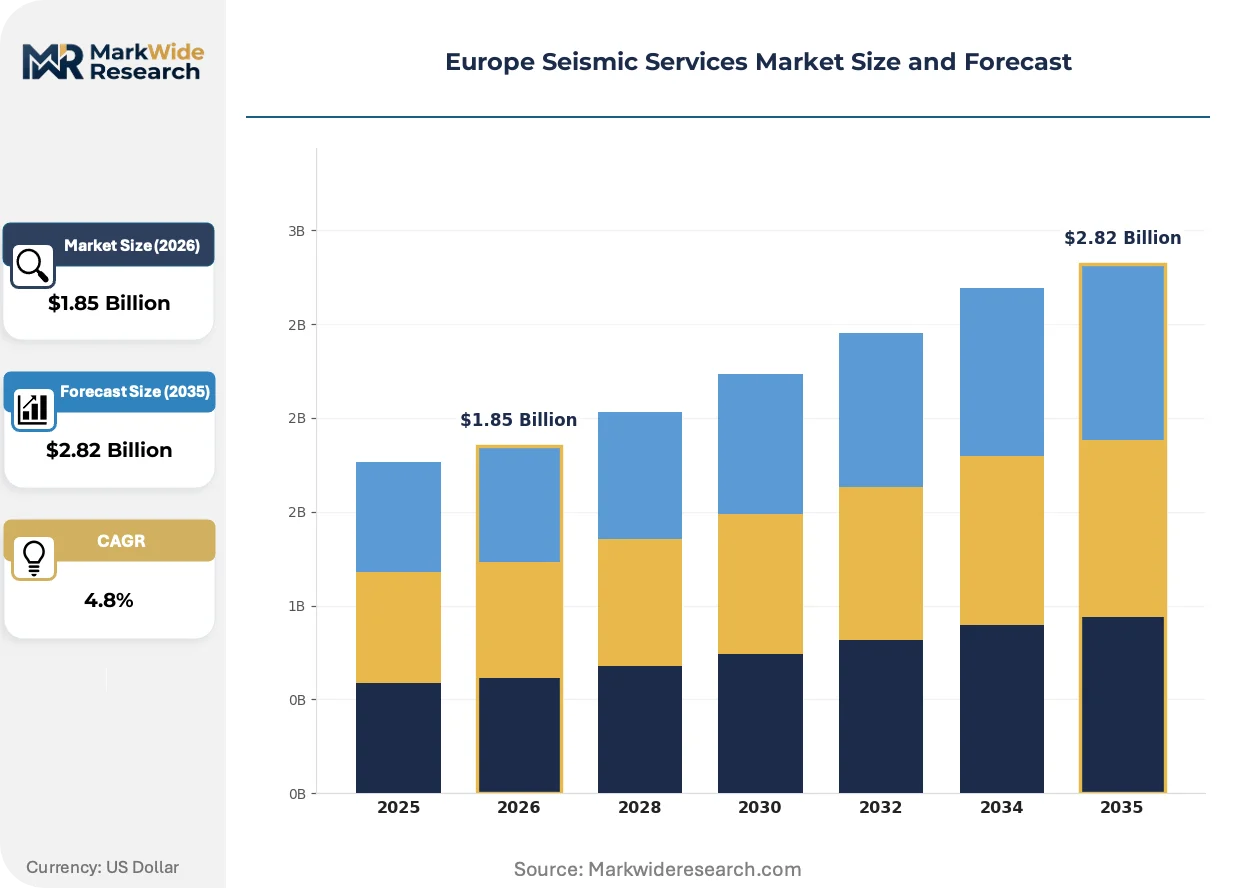
Market Dynamics
The EU Green Deal's methane monitoring mandates are compressing procurement cycles for passive seismic systems as North Sea operators retrofit legacy infrastructure with continuous monitoring arrays before 2027 compliance deadlines.
Growth Catalysts
- REACH Subsurface Integrity Mandates:The EU Green Deal framework requires real-time CO2 storage site verification, embedding microseismic monitoring into carbon capture permits across Norway, the UK, and the Netherlands.
- Barents Sea Deep-Water Exploration:Norway's continental shelf investment programs concentrate demand for high-resolution 4D seismic surveys in frontier basins with complex salt geometries.
- Ocean-Bottom Node Technology:Permanent reservoir monitoring systems are displacing conventional streamer surveys for time-lapse surveillance of mature UK North Sea fields.
Market Restraints
- Specialized Vessel Scarcity:The global fleet of ice-class seismic vessels capable of Barents Sea operations remains concentrated among three European contractors, creating capacity bottlenecks during summer acquisition windows.
- Air-Gun Array Regulatory Friction:Germany's Federal Agency for Nature Conservation and France's environmental prefectures impose seasonal operational bans protecting marine mammals, compressing viable survey periods in the North Sea.
- High-Performance Computing Input Costs:Proprietary depth-migration algorithms require dedicated GPU clusters, with energy-intensive processing centers facing electricity price volatility across European grid markets.
Strategic Opportunities
- Polish Baltic Sea Carbon Storage:Poland's emerging offshore CO2 injection projects lack established site characterization protocols, creating first-mover contracts for integrated seismic monitoring consortiums.
- AI-Accelerated Processing Convergence:Machine learning algorithms trained on North Sea legacy datasets are compressing interpretation timelines from months to weeks, enabling competitive differentiation for processing boutiques.
- EU Innovation Fund Deployment:The European Commission's carbon capture financing mechanism subsidizes up to 60 percent of site characterization costs for storage developers in Denmark, the Netherlands, and Romania.
Industry Challenges
- Geophysicist Talent Compression:European universities produce fewer than 200 specialized seismic interpreters annually, while retirement waves across UK and Norwegian operator technical departments accelerate skills gaps.
- Multi-Vendor Integration Complexity:Ocean-bottom node deployments require synchronization between seabed sensor contractors, vessel operators, and processing houses, with misaligned data formats causing project delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Seismic Services Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Onshore, Offshore, Monitoring, Data Processing Technology: 3D Seismic Imaging, 2D Seismic Surveying, Microseismic Technology, Passive Seismic Application: Oil & Gas Exploration, Mining, Civil Engineering, Environmental Studies End User: Energy Companies, Construction Firms, Government Agencies, Research Institutions |
| Companies Covered | Schlumberger Ltd, Halliburton Company, CGG SA, Fugro NV, Petroleum Geo-Services (PGS), TGS, Spectrum ASA, SeaBird Exploration Group, WGP Exploration Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Seismic Services Market Shifts & Advancements
Distributed acoustic sensing is compressing the cost structure of permanent reservoir monitoring while regulatory deadlines force technology refresh cycles across North Sea mature basins.
Optical fiber sensing technology is digitizing subsurface surveillance by converting existing subsea cables into continuous seismic arrays. Equinor and Shell are deploying fiber-optic systems across Norwegian Sea infrastructure at accelerating pace. This technology is digitizing the economics of 4D monitoring by eliminating repeat vessel mobilizations.
The EU Green Deal's methane emissions monitoring framework is mandating continuous passive seismic surveillance for all hydrocarbon production and CO2 storage operations. Industrial consequence includes embedded monitoring clauses in Norwegian Petroleum Safety Authority permits and UK North Sea Transition Authority site authorizations. Offshore carbon storage site characterization contracts are most affected, with developers pre-purchasing decade-long monitoring service agreements.
Integrated service contracting is consolidating procurement decisions as operators bundle acquisition, processing, and interpretation under single-vessel, single-contractor arrangements. The channel being disrupted is the traditional split between seismic vessel contractors and independent processing boutiques, replaced by full-asset-life-cycle partnerships. This pattern is most visible in Norway's Barents Sea corridor, where Equinor and Aker BP have consolidated supplier panels.
Europe Seismic Services Market Segmentation
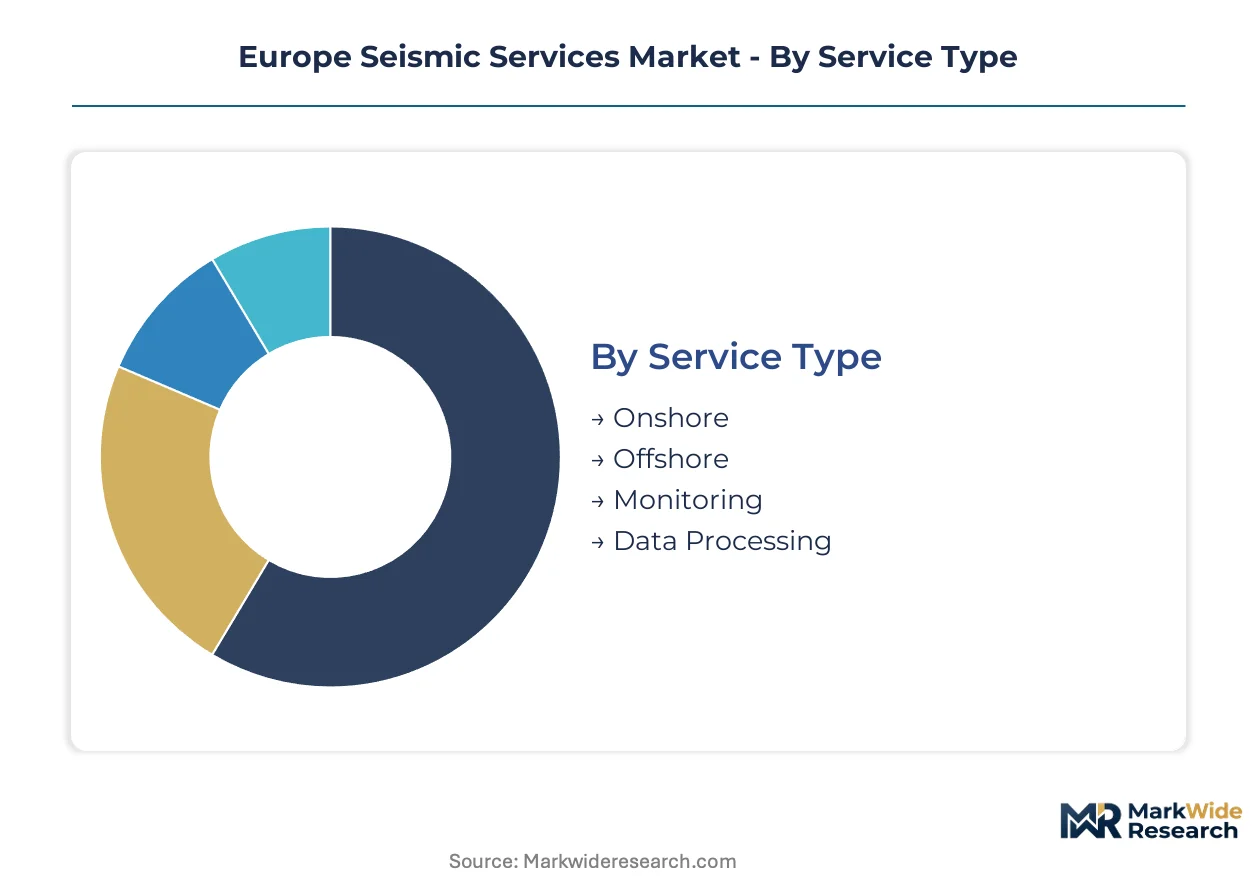
Segmentation in Europe's seismic services market reveals how technology portfolios and procurement patterns diverge across energy transition phases. Service providers must align capabilities with offshore hydrocarbon decommissioning timelines while building carbon storage site characterization competencies.
Service Type:
Mature vessel-based operations coexist with emerging continuous monitoring contracts as North Sea operators restructure procurement.
- Onshore:Vibroseis truck arrays and wireless nodal systems dominate terrain-constrained surveys across Poland's Baltic shale and Romania's Carpathian basins. Demand concentrates in geothermal exploration and mining site characterization as hydrocarbon onshore licensing contracts.
- Offshore:Marine streamer vessels and ocean-bottom cable deployments command premium day-rates in Norway's Barents Sea and UK Atlantic margin frontier blocks. Equinor and Shell tender multi-year framework agreements prioritizing ice-class vessel availability for summer acquisition windows.
- Monitoring:Permanent reservoir surveillance and induced-seismicity arrays embed long-term recurring revenue into operator budgets.
- Data Processing:Depth migration and full-waveform inversion services concentrate margin pools through proprietary algorithm licensing.
Offshore commands the majority of contract value; Monitoring is expanding most quickly as EU Green Deal mandates take effect.
Technology:
Cost tiers separate legacy survey methods from capital-intensive permanent monitoring infrastructure requiring fiber-optic or nodal sensor networks.
- 3D Seismic Imaging:Multi-azimuth and wide-azimuth acquisition geometries resolve complex salt structures beneath Norway's Nordkapp basin. TGS and PGS tender integrated acquisition-processing bundles for Barents Sea exploration licenses.
- 2D Seismic Surveying:Regional reconnaissance lines support frontier basin screening where 3D coverage remains uneconomical. UK North Sea Transition Authority mandates 2D baseline surveys before carbon storage permit issuance.
- Microseismic Technology:Hydraulic fracture monitoring and CO2 plume tracking require high-frequency geophone arrays deployed in borehole configurations.
- Passive Seismic:Continuous ambient noise monitoring satisfies EU methane emissions verification requirements without active source deployment.
3D Imaging handles the majority of survey expenditure; Passive Seismic is gaining share fastest through regulatory embedding.
Application:
Customer type determines project scale and duration, from multi-decade oil field surveillance to single-event civil engineering surveys.
- Oil & Gas Exploration:4D time-lapse reservoir monitoring and pre-drill prospect de-risking consume the largest absolute budgets. Norway's state-backed exploration incentives sustain demand despite European hydrocarbon phase-down commitments.
- Mining:Deep ore body delineation and blast optimization surveys utilize high-resolution 3D methods in Sweden's Kiruna iron district and Finland's Sotkamo nickel belt.
- Civil Engineering:Tunnel route surveys and foundation stability assessments employ shallow seismic refraction across Alpine rail corridor projects.
- Environmental Studies:Subsurface integrity verification for CO2 storage and geothermal reservoir characterization embed seismic methods into permit compliance.
Oil & Gas Exploration retains dominant budget share; Environmental Studies shows the steepest expansion trajectory as carbon storage licensing accelerates.
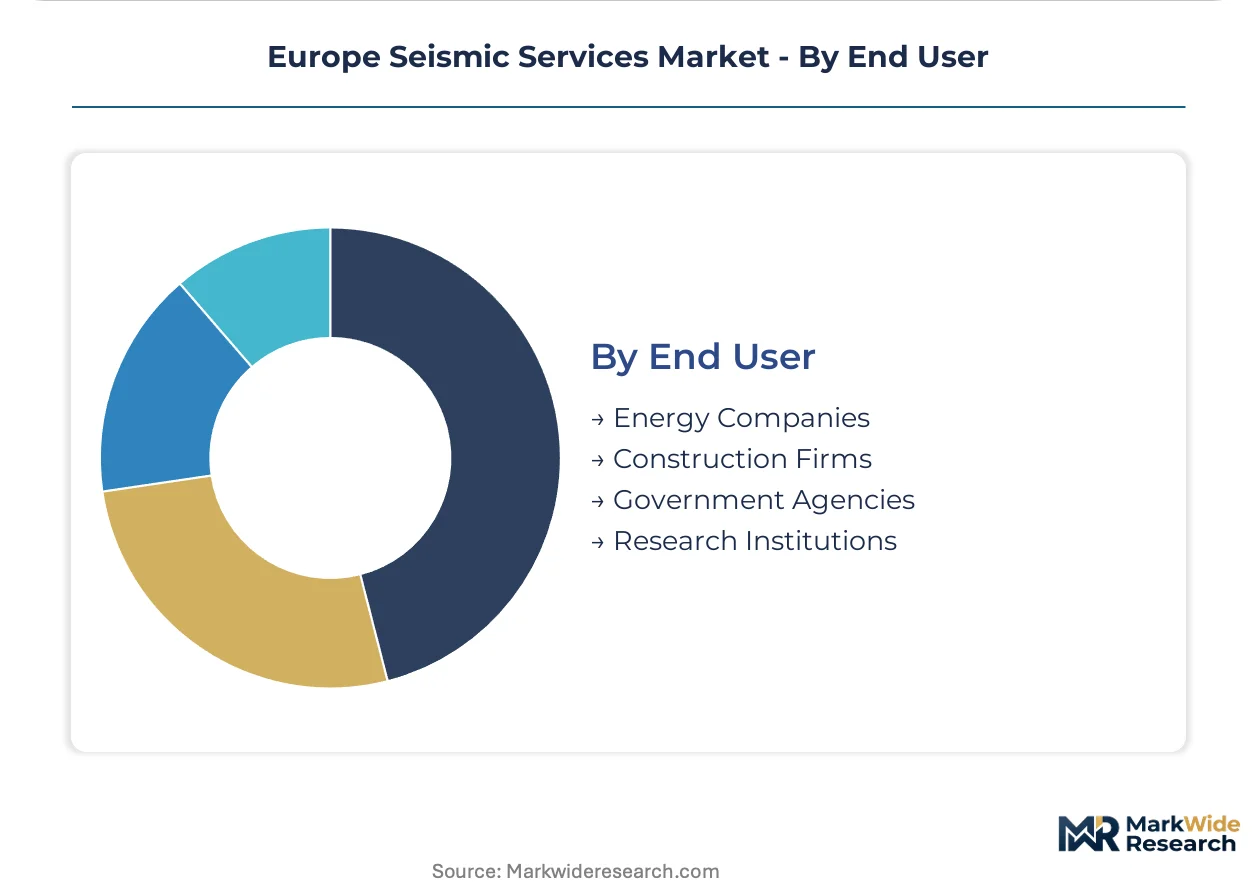
End User:
Procurement sophistication varies from integrated energy majors with captive geoscience teams to government agencies requiring turnkey interpretation deliverables.
- Energy Companies:International oil companies and national champions specify integrated acquisition-to-interpretation contracts with performance guarantees on drilling success rates. Equinor's supplier consolidation in Norway reduces vendor panels to three seismic contractors.
- Construction Firms:Infrastructure developers procure geotechnical seismic surveys for tunnel boring machine route optimization and bedrock stability assessment.
- Government Agencies:National geological surveys and carbon storage licensing authorities tender baseline site characterization with decade-long monitoring obligations.
- Research Institutions:University consortia and EU-funded programs access seismic data through national repository licenses for crustal structure and earthquake hazard studies.
Energy Companies control the majority of procurement volume; Government Agencies are climbing fastest as carbon storage site licensing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian operators demonstrate the lowest price elasticity, locking in multi-year framework agreements for ice-class vessel capacity, while Polish and Romanian buyers negotiate project-by-project with acute cost sensitivity. UK procurement sits between these poles, balancing premium 4D monitoring against budget-constrained decommissioning timelines. The EU Green Deal's regulatory embedding is compressing regional variance as methane monitoring mandates standardize service specifications.
Norway
Equinor and Aker BP sustain the region's deepest contract backlogs through state-backed exploration incentives in the Barents Sea and Norwegian Sea corridors. The Norwegian Petroleum Safety Authority mandates continuous passive seismic surveillance as a permit condition for all injection activities. Tromsø and Stavanger anchor the continental shelf service cluster, where contractors pre-position ice-class vessels for compressed summer acquisition windows.
United Kingdom
North Sea Transition Authority licensing deadlines are accelerating carbon storage site characterization tenders ahead of 2025 injection permit rounds. The UK North Sea Transition Authority embeds baseline 2D seismic surveys into carbon storage authorizations. Aberdeen concentrates processing and interpretation capacity, while Liverpool Bay and Humber clusters emerge as CO2 storage monitoring demand centers.
Netherlands
Rotterdam port industrial clusters are contracting integrated seismic monitoring for depleted gas field CO2 conversion projects. The EU Green Deal's methane emissions framework applies REACH-equivalent subsurface integrity verification to all onshore and offshore operations. The Groningen seismicity crisis has entrenched microseismic monitoring procurement into geothermal and conventional reservoir management contracts.
Germany
North Sea carbon storage licensing is constrained by Federal Agency for Nature Conservation seasonal air-gun array bans protecting marine mammals. The Federal Agency for Nature Conservation compresses viable marine survey periods into narrow summer windows, elevating vessel day-rate premiums. Hamburg anchors data processing capacity, while Kiel research consortia drive distributed acoustic sensing technology validation for offshore wind foundation monitoring.
Poland
Baltic Sea carbon storage developers lack established site characterization protocols, creating first-mover contract opportunities for integrated monitoring consortiums. The EU Innovation Fund subsidizes up to 60 percent of seismic characterization costs for Polish offshore CO2 injection projects. Gdańsk and Szczecin port clusters are positioning as service hubs for emerging Baltic carbon capture infrastructure.
Europe Seismic Services Market Competitive Landscape
Capability concentration sits with specialized geoscience technology developers; scale advantage sits with integrated energy service conglomerates. The market structure tiers across three distinct player categories: proprietary hardware developers controlling ocean-bottom node and streamer vessel fleets, software-centric processing boutiques licensing algorithm suites, and bundled service providers offering acquisition-through-interpretation contracts. Dominant competitive moves include panel consolidation by Norwegian operators reducing approved vendor lists, and fiber-optic sensing partnerships between seabed infrastructure owners and monitoring specialists.
Among European-anchored integrated service providers, CGG SA and Fugro NV exemplify contrasting strategic positions. CGG SA occupies a position within the subsurface imaging software tier, sustaining recurring licensing income through proprietary algorithm ecosystems. Fugro NV anchors the offshore vessel ownership archetype, controlling seabed-to-surface data acquisition through integrated marine asset deployment. Schlumberger Ltd represents the scale-driven conglomerate tier, though its dominance in 4D reservoir monitoring faces displacement pressure from permanent fiber-optic systems.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| CGG SA |
| Fugro NV |
| Petroleum Geo-Services (PGS) |
| TGS |
| Spectrum ASA |
| SeaBird Exploration Group |
| WGP Exploration Ltd |
| Others |
Supply & Pricing Matrix
Ice-class vessel undercapacity in the Barents Sea corridor concentrates pricing power among Norwegian and UK fleet operators, compressing summer acquisition windows and elevating day-rate premiums for compliant contractors while forcing buyers into multi-year framework commitments.
Pricing Analysis
Aftermarket monitoring service contracts drive lifetime value through decade-long passive seismic surveillance agreements embedded in Norwegian Petroleum Safety Authority permits. Three-tier pricing structure across premium, standard, and economy levels separates proprietary ocean-bottom node deployments from conventional streamer surveys and legacy 2D reconnaissance lines. Cost compression in data processing tiers is intensifying because GPU cluster electricity costs face European grid volatility. National oil companies in Norway demonstrate lowest price sensitivity, while Polish Baltic Sea carbon storage developers negotiate with acute cost consciousness.
Supply Chain Analysis
Extended payment terms from North Sea operators strain working capital for seabed sensor contractors and processing boutiques. Manufacturing concentrates in Norway, the United Kingdom, and the Netherlands, drawing from specialized geophone arrays, marine streamer cables, and high-performance computing clusters. Single-source vulnerability sits with ice-class vessel availability during compressed regulatory windows. Distribution runs through integrated service contracts bundling acquisition, processing, and interpretation under single-vessel arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's methane monitoring mandates are reshaping competitive positioning, embedding continuous seismic surveillance as a permit condition and converting one-time exploration contracts into recurring revenue streams.
For Market Incumbents: Harden proprietary algorithm moats through AI-accelerated processing suites trained on legacy North Sea datasets. Expand fiber-optic sensing partnerships with Equinor and Shell infrastructure owners to preempt displacement by permanent monitoring systems. Lock in ice-class vessel capacity through backward integration into marine asset ownership or captive long-term charter agreements.
For New Entrants and Emerging Players: Establish a beachhead in Polish Baltic Sea carbon storage site characterization, where established protocols remain absent and EU Innovation Fund subsidies offset upfront contract costs. Target microseismic monitoring for induced-seismicity compliance in the Groningen region and Romanian geothermal projects. Lead with integrated processing-interpretation bundles to bypass vessel ownership barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-centric processing boutiques licensing proprietary depth-migration algorithms to North Sea operators. Long-term viability hinges on carbon storage licensing velocity across northern Europe. Monitor Norwegian Petroleum Safety Authority permit issuance rates as the inflection signal for monitoring contract acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-Optic Sensing Deployment | Equinor and Shell infrastructure partnerships eliminate repeat vessel mobilizations for 4D monitoring. |
| AI-Accelerated Processing Development | Machine learning algorithms compress interpretation timelines from months to weeks for competitive differentiation. |
| Ice-Class Vessel Capacity Expansion | Norwegian and UK fleet additions address summer acquisition window bottlenecks in the Barents Sea. |
| Carbon Storage Site Characterization | Polish Baltic Sea first-mover contracts exploit absent protocols and EU Innovation Fund subsidies. |
| Integrated Service Contracting | Single-vendor acquisition-through-interpretation bundles displace split procurement between vessel operators and processing houses. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with seismic acquisition managers, reservoir surveillance engineers, carbon storage project developers, and regulatory compliance officers at North Sea operators; and secondary validation through EU Green Deal implementation documents, Norwegian Petroleum Safety Authority permit databases, UK North Sea Transition Authority licensing records, and seismic vessel fleet registries. Bottom-up project pipeline triangulation against top-down regulatory mandate sizing anchored volume estimates.
Forecast inputs included modeled deployment rates across service type, technology tier, application segment, and end-user category, with specific weighting for carbon storage licensing velocity and fiber-optic sensing adoption curves. CAGRs were derived from segment-level growth differentials applied across the projection horizon. Industry-specific inputs encompassed ice-class vessel utilization schedules, EU Innovation Fund disbursement trajectories, and REACH subsurface integrity mandate compliance timelines.
Stress conditions across vessel availability constraints, electricity price volatility for processing centers, and regulatory deadline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding carbon storage licensing acceleration and methane monitoring mandate enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Coal Mining Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Crown Block Market
Oil & Gas
Integrated Gas System Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Pumpjack Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Natural Gas Market