
 SCADA Oil and Gas Market | 2026-2036
SCADA Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
SCADA Oil and Gas Market Analysis
Buyer concentration among upstream operators is shifting as independent shale producers fragment across the Permian, Bakken, and Eagle Ford while supermajors consolidate midstream control. Siemens leverages its digital twin platforms to anchor automation contracts across North American pipeline networks. Honeywell International Inc. competes through its Experion SCADA suite, sustaining deep ties with refiners seeking real-time process optimization.
SCADA Oil and Gas denotes supervisory control and data acquisition systems engineered for hydrocarbon extraction, transport, and processing, typically integrating remote terminal units, programmable logic controllers, and human-machine interfaces operating across temperatures from minus 40 to 70 degrees Celsius. These systems enable centralized monitoring of geographically dispersed assets spanning thousands of square miles. Hardware dominates current revenue as replacement cycles accelerate for aging RTU and PLC infrastructure installed during the 2010s shale boom. Cloud-based deployment represents the fastest-expanding segment as operators seek to reduce on-site IT footprint while enabling predictive analytics. Edge computing is capturing margin pools where sub-second latency proves critical for emergency shutdown systems.
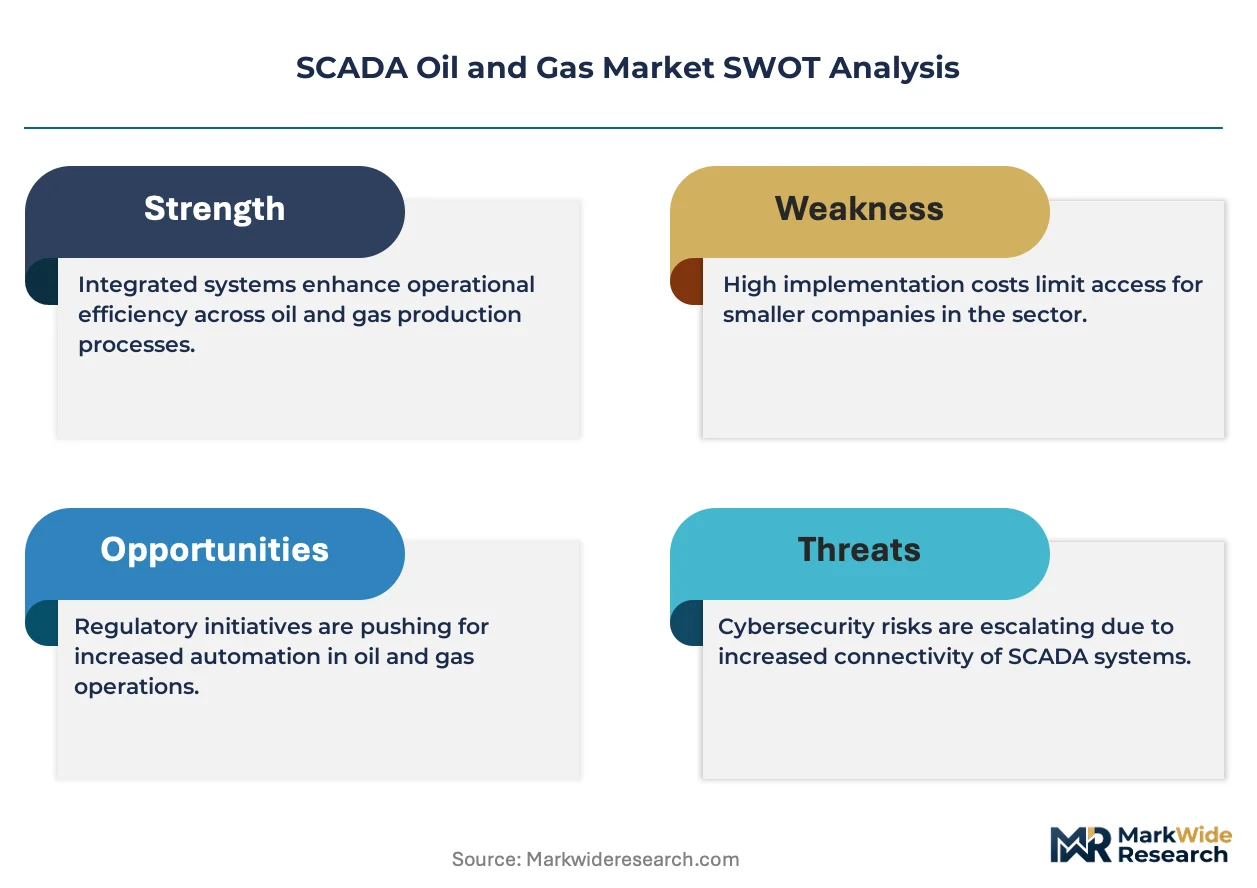
The US EPA mandates methane monitoring under New Source Performance Standards, compelling operators to upgrade SCADA with continuous emissions detection. OSHA process safety management rules enforce alarm rationalization and operator training, shaping procurement specifications for HMI software. The EU F-Gas Regulation restricts fluorinated greenhouse gases used in compressor cooling circuits, affecting sensor and actuator selection for European installations. Stakeholders must weigh cybersecurity certification against operational technology refresh timelines as IT-OT convergence expands attack surfaces.
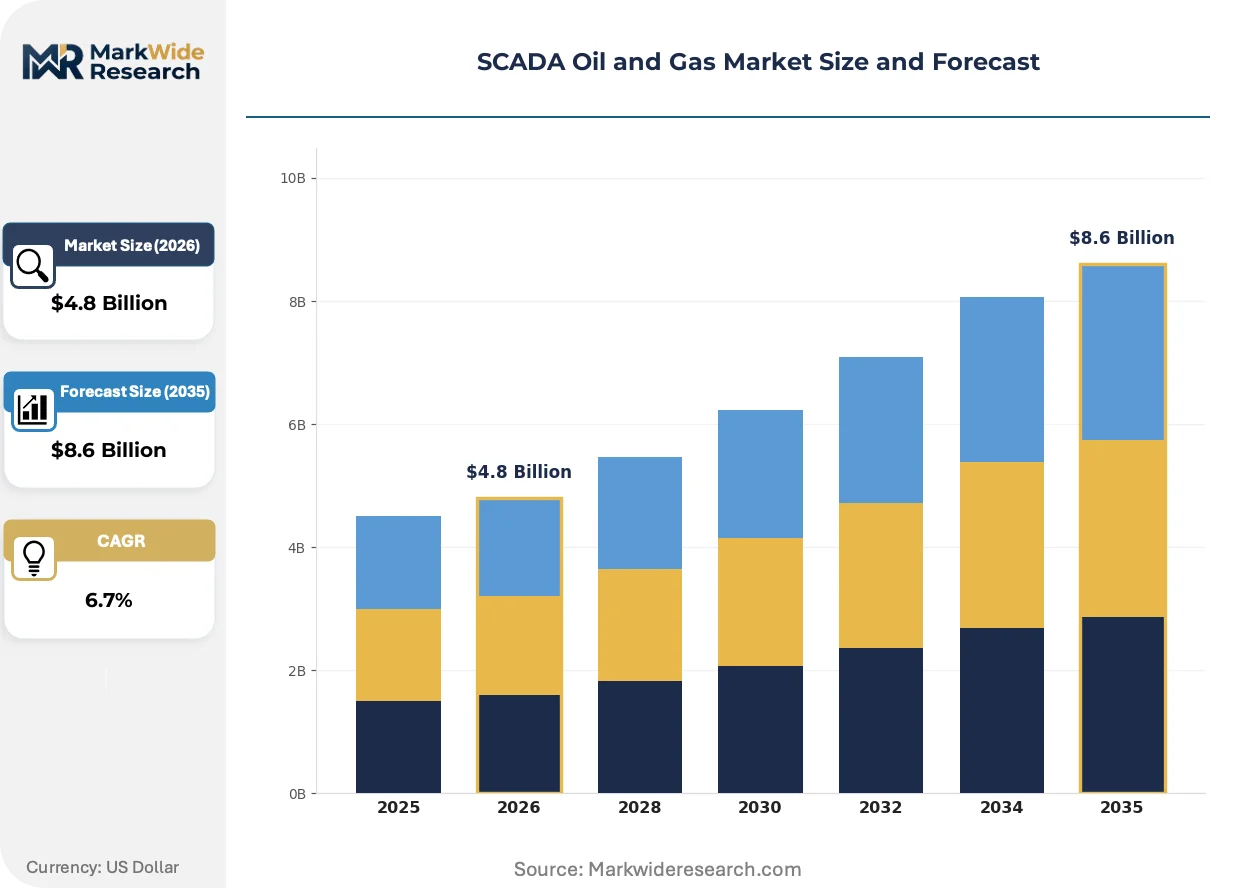
Market Dynamics
The US EPA methane monitoring mandates under New Source Performance Standards are forcing upstream operators to replace legacy RTU infrastructure with continuous emissions detection systems, compressing replacement cycles and redistributing vendor relationships across Permian Basin well pads.
Growth Catalysts
- EPA methane rules:The US EPA mandates continuous emissions monitoring, compelling operators to upgrade SCADA with leak detection sensors and real-time telemetry across wellhead infrastructure.
- Permian Basin concentration:Independent shale producers fragmenting across West Texas and New Mexico drive demand for standardized remote monitoring platforms.
- Edge computing integration:Sub-second latency requirements for emergency shutdown systems push adoption of localized processing units at compressor stations and pipeline junctions.
Market Restraints
- Semiconductor supply concentration:PLC and RTU production depends on concentrated Asian foundry capacity, creating input volatility for North American system integrators.
- EU F-Gas Regulation friction:Restrictions on fluorinated greenhouse gases limit compressor cooling circuit options for European installations, constraining sensor and actuator selection.
- Cybersecurity certification timelines:IT-OT convergence expands attack surfaces while NERC CIP and IEC 62443 compliance extends procurement cycles by 8-14 months.
Strategic Opportunities
- Cloud deployment white space:Mid-size Permian operators lag supermajors in cloud migration, creating margin pools for hosted SCADA platforms with predictive analytics bundles.
- OSHA process safety tailwind:Alarm rationalization and operator training mandates under OSHA PSM rules shape HMI software procurement specifications for refiners.
- Digital twin convergence:Integration of SCADA data streams with physics-based simulation models enables virtual commissioning of Gulf of Mexico offshore platforms.
Industry Challenges
- OT cybersecurity skill scarcity:Pipeline operators face acute shortages of engineers credentialed in both industrial control systems and network security protocols.
- Legacy system integration friction:Brownfield installations require protocol gateways to bridge 1990s-era Modbus RTU networks with modern OPC-UA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SCADA Oil and Gas Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Integration Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Upstream, Midstream, Downstream, Oilfield Services Technology: Wireless, IoT, PLC, RTU |
| Companies Covered | Rockwell Automation, Yokogawa Electric Corporation, Siemens, Honeywell International Inc., Mitsubishi Electric Corporation, Schneider Electric, Emerson Electric Co., General Electric, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SCADA Oil and Gas Market Emerging Trajectories
Cloud-native SCADA architectures are displacing on-premise server rooms as operators seek to externalize IT maintenance and enable centralized data lakes for machine learning applications across dispersed production assets.
Edge intelligence is absorbing computational workloads previously routed to centralized data centers. Remote terminal units now embed ARM-based processors capable of executing anomaly detection algorithms locally. Permian Basin independents deploy these units at well pads to trigger autonomous shutdowns before cloud latency permits remote intervention, compressing response windows from seconds to milliseconds.
REACH and RoHS compliance requirements in the European Union restrict hazardous substance content in SCADA hardware destined for North Sea platforms. Manufacturers reformulate printed circuit board solder alloys and capacitor electrolytes to maintain CE marking eligibility. German system integrators now require material disclosure documentation upstream of component procurement, filtering supplier pools before assembly begins.
After-sales service unbundling disrupts traditional automation vendor relationships. Eagle Ford shale producers now procure SCADA hardware through distributors while contracting predictive maintenance separately through specialized OT cybersecurity firms. This bifurcation squeezes integrated solution margins and forces original equipment manufacturers to defend attachment rates through software licensing rather than bundled service contracts.
SCADA Oil and Gas Market Segmentation
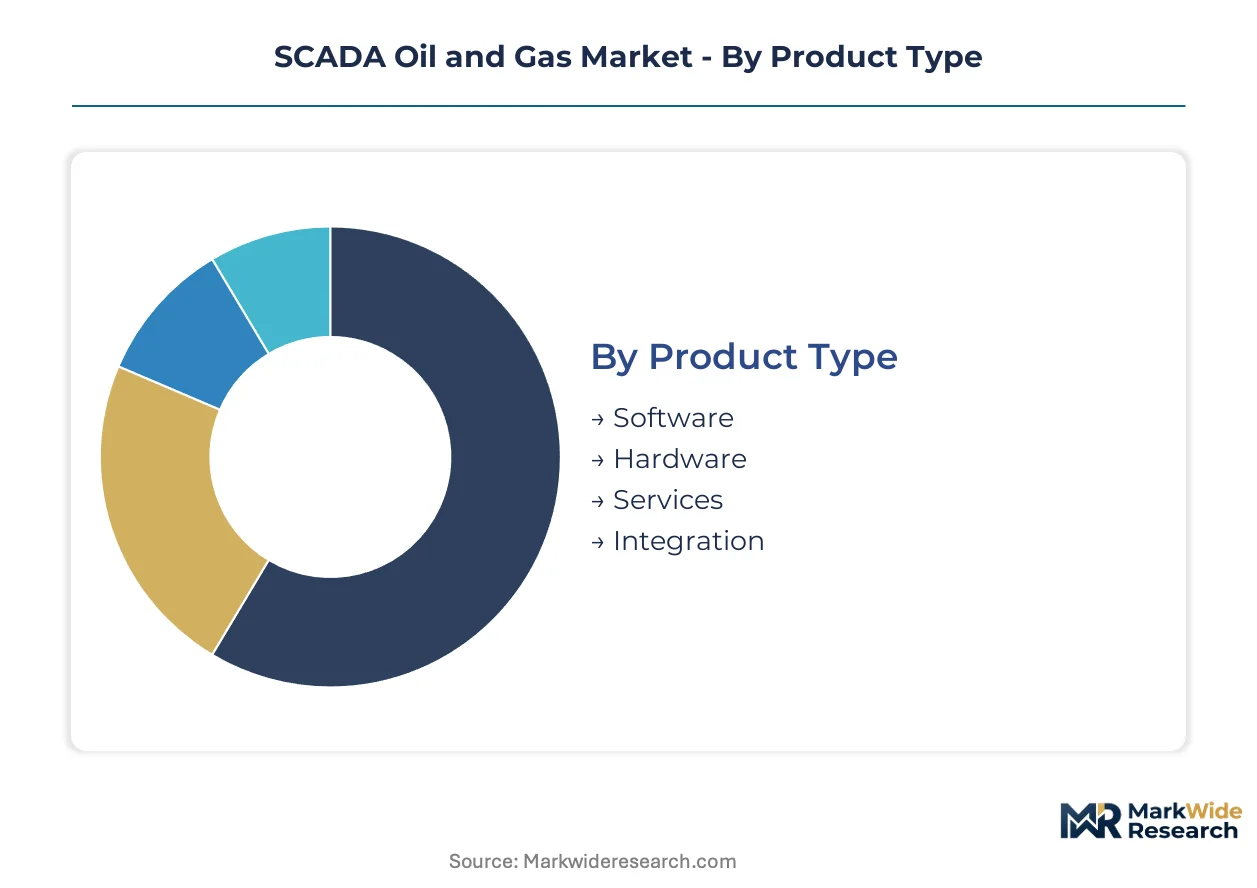
SCADA system procurement patterns diverge sharply across deployment architectures and operational layers. Hardware replacement cycles, cloud migration timelines, and edge latency requirements create distinct margin pools that reshape vendor contracting strategies.
Product Type:
Standalone software licenses dominate brownfield retrofits, while embedded hardware-software bundles anchor greenfield installations.
- Software:Human-machine interface platforms and historian databases enable centralized visualization across dispersed assets. Permian Basin independents prioritize subscription-based HMI licensing to reduce capital deployment. EPA methane monitoring mandates accelerate alarm management and emissions analytics module procurement.
- Hardware:Remote terminal units, programmable logic controllers, and industrial servers form the physical control layer. Aging infrastructure installed during the 2010s shale boom drives replacement demand across West Texas well pads. Semiconductor supply constraints from concentrated Asian foundry capacity create input volatility for North American system integrators.
- Services:Engineering, commissioning, and training contracts support deployment lifecycle.
- Integration:Protocol gateway configuration and legacy system bridging for brownfield sites.
Hardware leads volumes today; software is gaining share fastest through recurring revenue models.
Deployment:
Cost tier structures separate capital-intensive on-premise installations from operational-expense cloud contracts favored by mid-size operators.
- On-Premises:Dedicated server rooms and local data historians maintain air-gapped security for critical infrastructure. Gulf of Mexico offshore platforms require hardened server enclosures rated for marine environments. OSHA process safety management rules enforce redundant local control to prevent single-point failures.
- Cloud-Based:Hosted SCADA platforms externalize IT maintenance while enabling centralized data lakes. Eagle Ford shale producers adopt cloud telemetry to aggregate production data across fragmented well portfolios. Cybersecurity certification timelines under NERC CIP extend procurement cycles by 8-14 months.
- Hybrid:Split architectures retain local control for safety systems while cloudifying non-critical monitoring.
- Edge Computing:Sub-second latency for emergency shutdown systems pushes ARM-based processing to compressor stations.
On-premises retains the largest installed base; edge computing is expanding most quickly at pipeline junctions.
End User:
Application intensity varies from remote wellhead monitoring through complex refinery process optimization.
- Upstream:Well pad automation and artificial lift control dominate SCADA deployment. Independent shale producers across the Permian, Bakken, and Eagle Ford drive standardization for remote monitoring platforms. EPA continuous emissions detection requirements compress replacement cycles for legacy RTU infrastructure.
- Midstream:Pipeline leak detection and compressor station automation require geographically distributed control networks. Supermajors consolidate control room consolidation across interstate transmission corridors. FERC pipeline safety regulations mandate integrity management system integration.
- Downstream:Refinery process optimization and alarm rationalization under OSHA PSM rules.
- Oilfield Services:Rental equipment telemetry and frac fleet monitoring for temporary deployments.
Upstream commands the greatest node count; midstream shows the steepest expansion trajectory per mile of new pipeline.
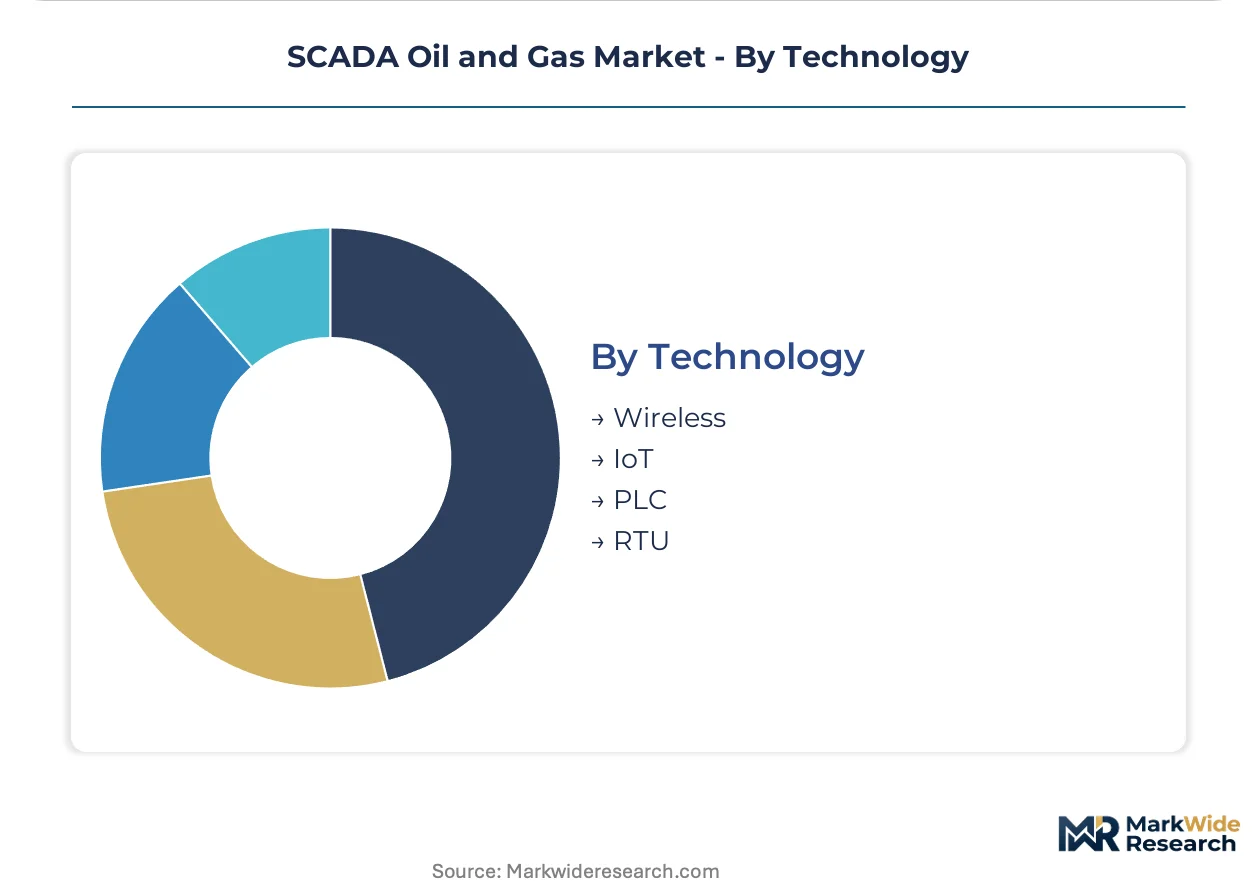
Technology:
Maturity curves separate established wired architectures from emerging wireless and IoT protocols.
- Wireless:Licensed radio and cellular networks eliminate trenching costs for remote well connections. New Mexico well pads deploy private LTE networks to bypass public infrastructure dependency. Spectrum allocation delays from the FCC constrain deployment timelines in certain production corridors.
- IoT:Low-power sensors and LPWAN protocols enable battery-operated monitoring at unmanned sites. Permian Basin operators instrument wellhead pressure and temperature for predictive maintenance. Cybersecurity skill scarcity complicates secure IoT gateway configuration.
- PLC:Programmable logic controllers remain the workhorse for deterministic process control.
- RTU:Remote terminal units bridge field signals to central control for geographically dispersed assets.
PLC and RTU anchor current installations; IoT is climbing the fastest among greenfield deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys SCADA infrastructure at roughly triple the intensity of Saudi Arabia, though both markets concentrate spending on methane compliance and remote automation. Canada and Norway pursue Arctic-hardened systems for extreme-climate extraction. China's state-backed energy majors consolidate digital control platforms across Sichuan shale and Xinjiang coalbed methane.
United States
Permian Basin independents fragment across West Texas and New Mexico well pads, each requiring standardized remote monitoring. EPA New Source Performance Standards mandate continuous emissions detection, compressing replacement cycles for legacy RTU infrastructure. Houston anchors system integration services for Gulf of Mexico offshore platforms.
Saudi Arabia
Aramco's Master Gas System expansion drives demand for pipeline SCADA across the Eastern Province. The country's national petroleum regulator enforces facility integrity management rules modeled on API standards. Dhahran hosts engineering centers configuring digital twin platforms for Ghawar field automation.
Canada
Oil sands operators in Alberta deploy edge computing for autonomous froth treatment control at remote extraction sites. Alberta Energy Regulator directives mandate leak detection and repair protocols for steam-assisted gravity drainage facilities. Calgary concentrates vendor engineering offices serving the Montney and Duvernay shale corridors.
Norway
Equinor's Johan Sverdrup platform exemplifies integrated operations centers linking offshore assets to onshore control rooms. Petroleum Safety Authority Norway regulations enforce functional safety standards for emergency shutdown systems. Stavanger hosts system integrators specializing in subsea production control networks.
China
PetroChina and Sinopec consolidate SCADA procurement for Sichuan Basin shale gas development under national energy security directives. Ministry of Ecology and Environment rules tighten fugitive emissions monitoring for oilfield equipment. Xinjiang's Tarim Basin hosts pilot deployments of IoT-enabled wellhead sensors.
SCADA Oil and Gas Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across contract tiers, creating a tiered structure where scale-driven integrators anchor mega-projects while regional boutiques capture brownfield retrofits. Three archetypes dominate: full-stack automation conglomerates bundling hardware-software-services, cybersecurity-forward specialists securing IT-OT convergence, and edge-computing purists optimizing sub-second latency. M&A activity concentrates on OT cybersecurity capabilities, while strategic partnerships between cloud hyperscalers and industrial vendors reshape deployment economics.
Among diversified conglomerates, Siemens and Honeywell International Inc. occupy positions exemplifying integrated platform strategies, with Schneider Electric representing the European engineering-centric archetype. These entities anchor competitive dynamics through bundled automation contracts spanning upstream through downstream verticals, their scale enabling sustained R&D commitment across hardware refresh cycles and cloud-native migration roadmaps.
| Leading Market Players |
|---|
| Rockwell Automation |
| Yokogawa Electric Corporation |
| Siemens |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Schneider Electric |
| Emerson Electric Co. |
| General Electric |
| ABB |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up system integrators now dominate North American SCADA deployment, compressing vendor margins through centralized procurement while passing semiconductor cost volatility downstream to upstream operators locked in multi-year automation contracts.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for ARM-based edge processors embedded in next-generation remote terminal units. Subscription-based HMI licensing dominates software procurement, with pricing stratifying across premium cybersecurity-certified tiers, standard compliance bundles, and economy bare-metal configurations. Cost compression in economy tiers intensifies because mid-size Permian operators demand cloud telemetry without predictive analytics modules. Independent shale producers exhibit highest price sensitivity; supermajors absorbing full-stack digital twin contracts show least.
Supply Chain Analysis
Automation engineering talent scarcity in Germany and Japan constrains throughput at European system integration hubs. PLC and RTU production draws from concentrated Asian foundry capacity in Taiwan, South Korea, and China. Raw material dependencies span silicon wafers, rare-earth magnets for actuator motors, and fluorinated cooling gases for compressor circuits. Single-source vulnerability around advanced node semiconductors creates procurement risk. Distribution runs through authorized distributor networks serving fragmented well pad operators alongside direct enterprise contracts anchoring supermajor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SCADA Oil and Gas Market functions as a geographic-arbitrage play: EPA methane compliance costs in the United States run substantially higher than Saudi Arabia's API-aligned facility integrity rules, creating divergent automation investment timelines and vendor margin profiles.
For Market Incumbents: Deploy cloud-native platform consolidation to absorb mid-size Permian operators migrating from on-premise server rooms. OT cybersecurity specialists threaten attachment rates for bundled service contracts; defend through predictive maintenance software licensing rather than hardware-service bundling. Capacity addition in Singapore for marine-hardened server enclosures secures Gulf of Mexico offshore platform contracts. For New Entrants and Emerging Players: Capture cloud deployment white space among Eagle Ford shale producers lacking supermajor IT infrastructure. Mid-size independent operators with fragmented well portfolios represent the most penetrable segment. Go-to-market through OT cybersecurity firms unbundling after-sales service from traditional automation vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with brownfield retrofit expertise but limited digital twin capabilities. Long-term viability hinges on IT-OT convergence execution across the analysis window. Target acquisition archetype: edge-computing purists with sub-second latency optimization for compressor station emergency shutdown systems. Signal to watch: NERC CIP certification timeline compression as indicator of procurement cycle normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Externalizes IT maintenance for Permian Basin independents while enabling centralized predictive analytics. |
| Edge Computing Deployment | ARM-based processors at compressor stations compress emergency shutdown response windows to milliseconds. |
| OT Cybersecurity Certification | NERC CIP and IEC 62443 compliance extends procurement cycles but anchors supermajor contract renewals. |
| Digital Twin Integration | Physics-based simulation models enable virtual commissioning of Gulf of Mexico offshore platforms. |
| After-Sales Service Unbundling | Eagle Ford producers now procure hardware through distributors while contracting predictive maintenance separately. |
Methodological Framework
Bottom-up upstream operator modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with automation engineering directors, SCADA procurement leads at independent shale producers, system integration project managers, and OT cybersecurity specialists inform demand-side assumptions. Secondary validation draws from EPA enforcement databases, FERC pipeline safety filings, EIA production statistics, and customs records for industrial control equipment imports. Top-down and bottom-up estimates triangulate through cross-referencing hardware replacement cycle data against cloud subscription growth metrics.
Input-output matrices map deployment architecture adoption curves against regulatory compliance timelines across the projection horizon. Segmentation dimensions span product type, deployment model, end-use vertical, and technology protocol. CAGRs derive from regression analysis of historical replacement cycles and forward-looking regulatory mandate schedules. Forecast inputs incorporate semiconductor supply constraints and EPA methane monitoring enforcement intensity variations.
Underlying measurement precision varies by segment; cloud-based deployment and edge computing carry tighter precision than legacy on-premise retrofits where brownfield integration complexity introduces uncertainty. Forecasts reflect documented assumptions around regulatory enforcement continuity and supply chain normalization. Material deviation in EPA rulemaking timelines or Taiwan semiconductor export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Algeria Oil and Gas Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Delayed Coker Unit Process Technology Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Algeria Oil and Gas Downstream Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Global Drilling Jars Market