
 South America Intelligent Pigging Market | 2026-2036
South America Intelligent Pigging Market Size, Share, and Industry Trends Forecast 2026-2036
South America Intelligent Pigging Market Insights
Midstream operators are reorganizing procurement priorities around predictive maintenance contracts rather than reactive inspection schedules. Baker Hughes Company leverages its ultrasonic technology portfolio to anchor long-term service agreements across Brazilian pipeline networks. NDT Global competes through specialized electromagnetic inspection capabilities tailored to corrosion detection in aging infrastructure. SGS SA extends its geographic footprint by operating certified inspection laboratories in São Paulo and Buenos Aires.
Intelligent pigging deploys self-propelled inspection devices equipped with magnetic flux leakage sensors, ultrasonic transducers, or electromagnetic acoustic arrays to detect metal loss, cracks, and geometric anomalies within pressurized pipelines without flow interruption. These systems traverse pipelines using the product stream as propulsion while recording wall-thickness measurements at sub-millimeter resolution for integrity assessment. Magnetic technology dominates current deployment volumes due to lower operational complexity and established calibration protocols across South American crude oil trunk lines. Ultrasonic inspection commands premium positioning where precise crack sizing determines remaining life calculations for high-pressure gas transmission systems. Electromagnetic methods represent the fastest-expanding category as operators seek combined wall-thickness and crack-detection capability in single tool runs.
Brazil's ANP mandates periodic inline inspection for pipelines transporting hazardous liquids above specified diameter thresholds, directly stimulating demand for certified intelligent pigging services. Argentina's national gas regulator enforces integrity management standards aligned with regional pressure equipment directives, while Colombia's Ministry of Mines imposes environmental contingency requirements that favor leak-prevention technologies. Stakeholders must evaluate how evolving national content requirements affect tool importation and local calibration facility development.
Market Dynamics
ANP inspection frequency mandates are compressing operator maintenance cycles from triennial to biennial intervals across Brazil's pre-salt trunk lines. This regulatory compression forces capital reallocation toward predictive integrity systems and away from reactive repair budgets.
Growth Catalysts
- ANP Mandate Tightening:Brazil's national petroleum regulator now requires inline inspection for all hazardous liquid pipelines above 10-inch diameter. Operators must deploy magnetic flux leakage or ultrasonic tools to maintain operating licenses.
- Pre-Salt Basin Expansion:Petrobras and international joint ventures are commissioning new gathering lines across the Santos Basin. Each greenfield installation triggers baseline intelligent pigging runs for integrity baselining.
- Corrosion Detection Sensitivity:Electromagnetic acoustic transducer arrays now resolve metal loss features below 3 millimeters. This precision enables remaining life calculations that extend asset service intervals.
Market Restraints
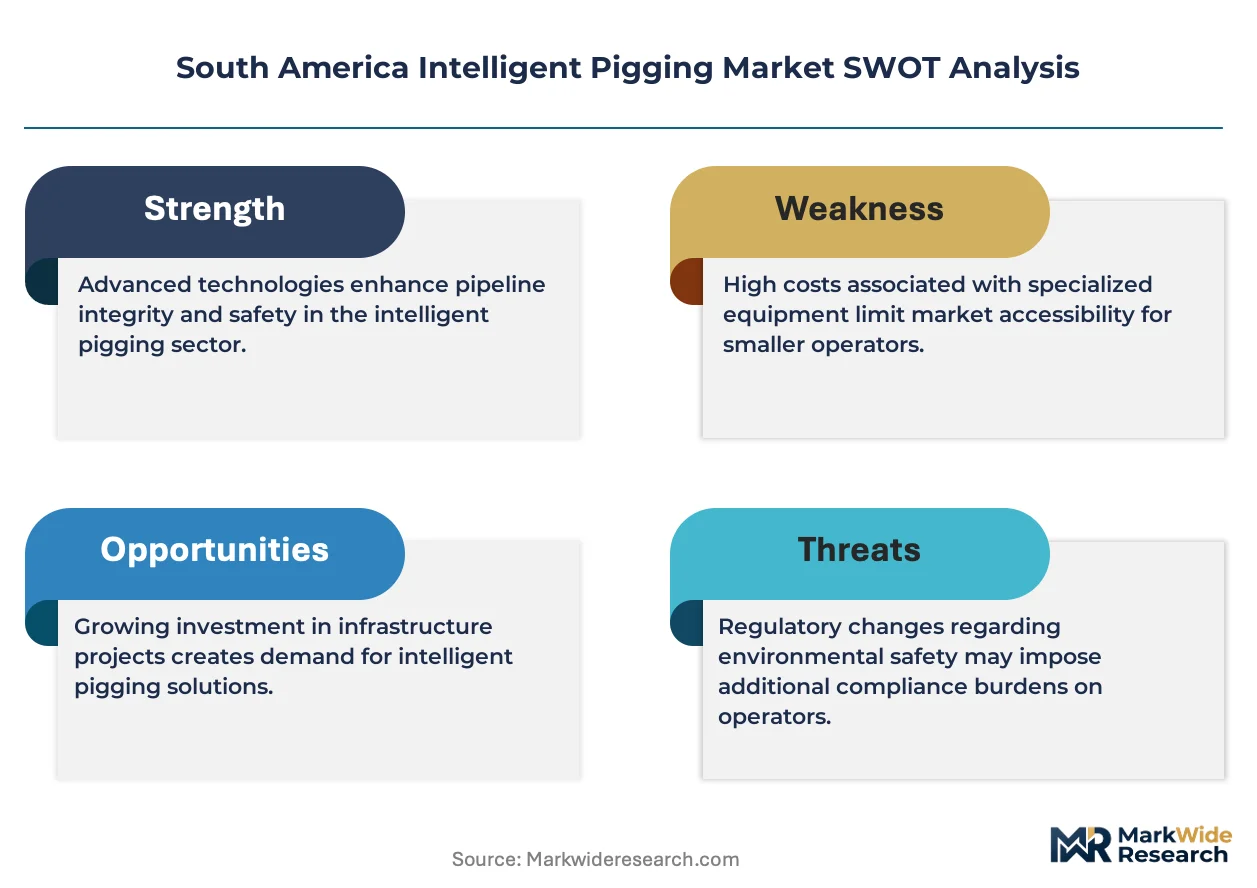
- Tool Import Dependency:Magnetic flux leakage sensor modules and ultrasonic transducer arrays originate primarily from North American and European suppliers. Currency volatility against the Brazilian real inflates landed equipment costs.
- Calibration Facility Scarcity:Certified pull-through test loops for tool verification exist only in São Paulo and Rio de Janeiro. Operators in Colombia and Argentina face 72-hour transit windows for pre-run validation.
- Specialized Labor Bottleneck:Pipeline integrity engineers with electromagnetic data interpretation certification number fewer than 200 across the entire region. Training programs at regional universities remain underdeveloped.
Strategic Opportunities
- Argentina Vaca Muerta Buildout:Shale oil gathering systems in Neuquén Province lack existing inline inspection infrastructure. First-mover service providers can anchor long-term maintenance contracts during field development.
- Combined Technology Runs:Single-tool platforms integrating magnetic flux leakage with ultrasonic crack detection reduce pipeline downtime. Operators in high-pressure gas transmission corridors value this efficiency premium.
- Local Content Incentives:Brazil's ANP awards exploration blocks based on national supply chain participation. Intelligent pigging vendors establishing calibration laboratories and tool maintenance facilities gain competitive scoring advantages.
Industry Challenges
- Data Interpretation Bottleneck:Raw inspection logs from electromagnetic tools generate terabytes per run. Qualified analysts capable of discriminating crack signals from weld anomalies remain concentrated in São Paulo and Houston.
- Legacy Pipeline Geometry:Argentina's northern crude oil network contains 1950s-era bends and diameter transitions. Modern high-resolution tools require modification or bypass for these non-piggable segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Intelligent Pigging Market |
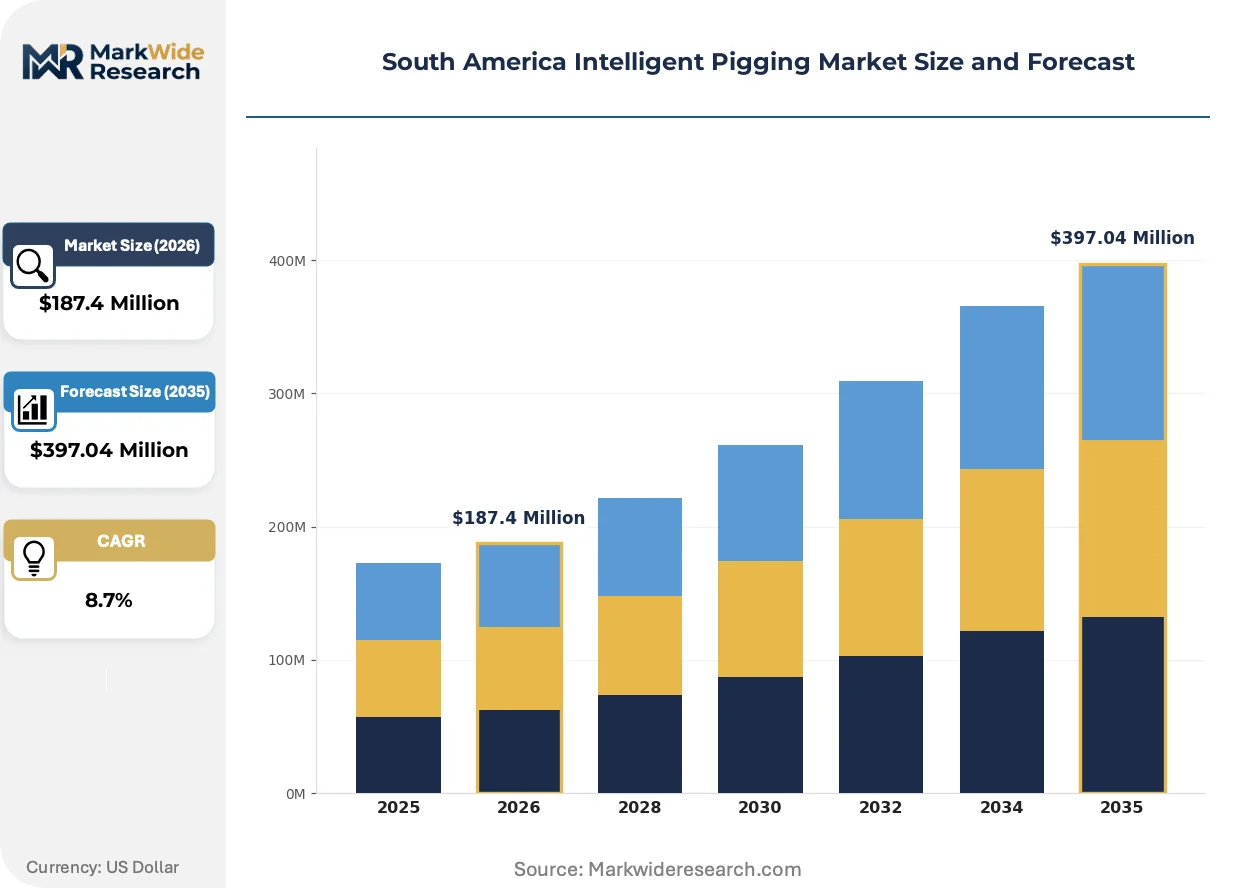
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic, Magnetic, Electromagnetic, Laser Application: Pipelines, Storage Tanks, Offshore Rigs, Refineries End User: Oil & Gas Companies, Utilities, Industrial Plants, Inspection Services Service Type: Data Analysis, Maintenance, Consulting, Training |
| Companies Covered | NDT Global, Pigtek Ltd, SGS SA, Baker Hughes Company, Penspen Limited, ROSEN Group, T.D. Williamson, Enduro Pipeline Services, Intertek Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Intelligent Pigging Market Trends and Innovations
Inspection technology trajectories in South America are diverging between high-resolution premium systems for pre-salt operators and cost-optimized configurations for mature basin producers. This divergence reflects capital allocation pressures and regulatory stringency gradients across national markets.
Ultrasonic phased-array inspection tools are bifurcating the service tier structure. These systems emit angled sound pulses that construct three-dimensional wall-thickness maps. Petrobras and international majors operating Brazil's pre-salt gas pipelines have adopted this technology for crack-sizing precision. The capability gap between electromagnetic and ultrasonic platforms is widening contract value spreads and fragmenting vendor competitive sets.
Colombia's Ministry of Mines has imposed environmental contingency bonding requirements that scale with pipeline failure risk exposure. Operators must demonstrate leak-prevention technology deployment to qualify for reduced bond rates. This policy structure accelerates intelligent pigging adoption in the Llanos Basin, where independent producers face capital constraints.
Service contracting patterns among midstream operators are consolidating around multi-year predictive maintenance agreements. Discrete inspection purchase orders are yielding to bundled subscriptions covering baseline surveys, anomaly re-inspection, and fitness-for-service assessments. This shift is most pronounced in Brazil, where ANP compliance documentation requirements favor continuous vendor relationships over transactional procurement.
South America Intelligent Pigging Market Segmentation
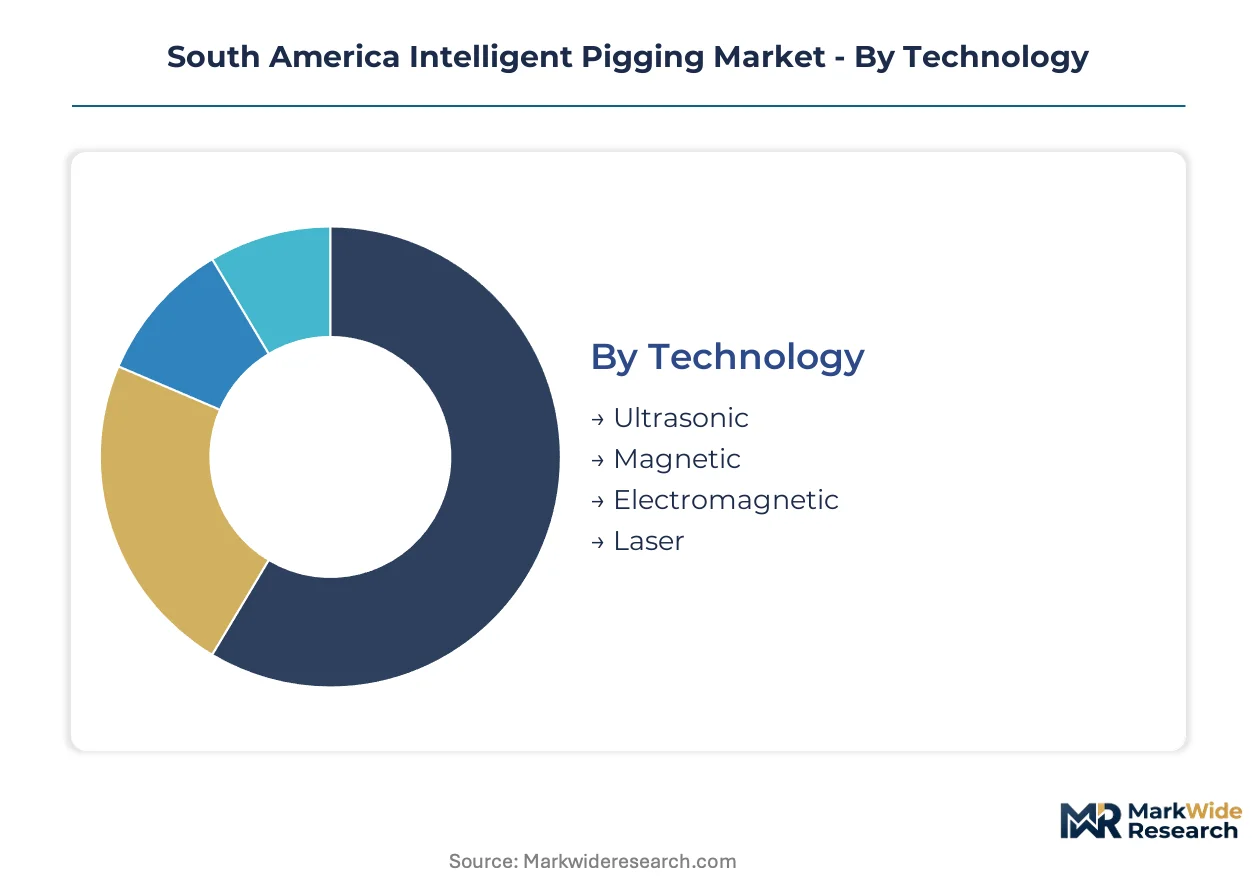
Intelligent pigging procurement decisions in South America fragment across technology performance tiers, asset-specific applications, and contracting models. Understanding where operators allocate capital across these dimensions reveals vendor positioning opportunities and margin concentration zones.
Technology:
Margin pools concentrate in high-resolution inspection systems where crack-sizing precision commands service premiums and long-term vendor lock-in.
- Ultrasonic:Phased-array systems emit angled sound pulses to construct three-dimensional wall-thickness maps. Petrobras and international majors operating Brazil's pre-salt gas pipelines have adopted this technology for crack-sizing precision that determines remaining life calculations.
- Magnetic:Magnetic flux leakage sensors detect metal loss through magnetic field perturbations without direct coupling to pipe wall. This technology dominates current deployment volumes across South American crude oil trunk lines due to lower operational complexity and established calibration protocols.
- Electromagnetic:Electromagnetic acoustic transducer arrays resolve metal loss features below three millimeters, enabling operators to extend asset service intervals through precise remaining life calculations.
- Laser:Laser-based geometric measurement tools map pipeline ovality and dent profiles for deformation assessment in high-pressure transmission corridors.
Ultrasonic holds installed capacity in premium gas transmission corridors. Electromagnetic is rotating up the share rankings as operators seek combined wall-thickness and crack-detection in single tool runs.
Application:
Contract values scale with pipeline pressure ratings and environmental risk exposure rather than simple asset count.
- Pipelines:Pressurized trunk lines and gathering systems constitute the core inspection demand base. ANP mandates for hazardous liquid pipelines above ten-inch diameter directly stimulate magnetic flux leakage and ultrasonic tool deployment across Brazil's pre-salt basin corridor.
- Storage Tanks:Above-ground storage tank floor inspection employs modified magnetic flux leakage platforms adapted for non-pressurized environments. Colombia's Ministry of Mines environmental contingency bonding requirements scale with failure risk exposure, accelerating adoption among Llanos Basin independent producers.
- Offshore Rigs:Subsea riser and flowline inspection requires pressure-rated tool carriers and specialized launch recovery systems. Brazil's Santos Basin pre-salt developments generate baseline intelligent pigging runs for each greenfield installation.
- Refineries:Process piping networks within refining complexes demand smaller-diameter tool configurations and frequent inspection cycles due to corrosive process streams.
Pipelines anchor vendor revenue stability. Offshore rigs deliver the steepest expansion trajectory as pre-salt developments multiply.
End User:
Procurement authority concentrates with national oil companies that bundle inspection services into integrated integrity management programs.
- Oil & Gas Companies:Integrated operators like Petrobras and international joint ventures commission baseline surveys, anomaly re-inspection, and fitness-for-service assessments through multi-year predictive maintenance agreements rather than discrete purchase orders.
- Utilities:Gas distribution utilities in Argentina enforce integrity management standards aligned with regional pressure equipment directives, stimulating electromagnetic inspection demand for corrosion detection in aging infrastructure.
- Industrial Plants:Petrochemical and fertilizer facilities operate captive pipeline networks requiring periodic inspection under process safety management protocols.
- Inspection Services:Third-party service providers extend geographic coverage by operating certified inspection laboratories in São Paulo and Buenos Aires, capturing outsourced integrity management contracts from smaller operators.
Oil & gas companies control capital deployment volume. Inspection services are gaining share fastest as midstream operators outsource specialized electromagnetic data interpretation.
Service Type:
Revenue mix is shifting from hardware rental toward recurring analytics and advisory subscriptions.
- Data Analysis:Raw inspection logs from electromagnetic tools generate terabytes per run. Qualified analysts capable of discriminating crack signals from weld anomalies remain concentrated in São Paulo and Houston, creating scarcity premiums for interpretation services.
- Maintenance:Tool maintenance facilities and calibration laboratories in Brazil gain competitive scoring advantages under ANP national content requirements for exploration block awards.
- Consulting:Fitness-for-service assessments translate inspection findings into remaining life calculations and repair prioritization schedules for operator capital planning.
- Training:Pipeline integrity engineer certification programs remain underdeveloped across regional universities, with fewer than two hundred electromagnetic data interpretation specialists available across the entire continent.
Data analysis commands margin expansion. Training represents the fastest-growing trajectory as labor bottlenecks force capability building investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian crude exports flow predominantly to Chinese refineries and US Gulf Coast terminals, anchoring trunk line inspection demand across the Santos Basin corridor. Argentina's Vaca Muerta shale oil feeds Chilean and Brazilian thermal power plants, requiring gathering system integrity investments. Colombian pipeline networks transport heavy crude to Pacific export terminals.
Brazil
Petrobras operates the world's largest deepwater production system across the Santos and Campos basins. ANP mandates now require biennial inline inspection for all hazardous liquid pipelines above 10-inch diameter. São Paulo hosts the region's only certified calibration laboratories, concentrating tool verification and data interpretation services.
Argentina
YPF and international joint ventures are expanding gathering infrastructure across Neuquén Province's Vaca Muerta formation. The national gas regulator enforces integrity management standards aligned with regional pressure equipment directives. Pipeline construction in Mendoza Province connects shale oil production to domestic refineries and Chilean export routes.
Colombia
Ecopetrol and independent producers operate heavy crude networks from the Llanos Basin to Pacific Coast terminals. The Ministry of Mines imposes environmental contingency bonding requirements that scale with pipeline failure risk exposure. Bogotá-based service coordination centers manage inspection logistics for remote Andean and jungle terrain.
Chile
Enap operates the country's sole refinery and associated crude import terminals at Quintero and San Vicente. National content requirements favor service providers establishing local engineering capabilities. The Bio-Bío Region concentrates petrochemical pipeline networks requiring corrosion monitoring.
Peru
Pluspetrol and Hunt Oil manage natural gas liquids pipelines from the Camisea field to Lima's coastal processing facilities. The hydrocarbon regulator mandates periodic integrity assessments for pipelines crossing Andean seismic zones. Callao serves as the primary logistics hub for inspection equipment importation and technical service deployment.
South America Intelligent Pigging Market Competitive Landscape
Player mix skews toward integrated energy technology conglomerates with diversified inspection portfolios. Market structure concentrates around three tiers: global oilfield service majors with captive intelligent pigging divisions, specialized pipeline integrity contractors with regional calibration infrastructure, and third-party inspection laboratories offering outsourced data interpretation. Dominant competitive moves include strategic partnerships for combined-technology tool development and geographic expansion through certified facility establishment under national content scoring systems.
Within the integrated technology tier, Baker Hughes Company and NDT Global exemplify archetypes competing through ultrasonic and electromagnetic platform differentiation. SGS SA anchors the third-party laboratory segment with certified facilities in São Paulo and Buenos Aires. These three occupy positions spanning hardware deployment, data analytics, and regulatory compliance documentation.
| Leading Market Players |
|---|
| NDT Global |
| Pigtek Ltd |
| SGS SA |
| Baker Hughes Company |
| Penspen Limited |
| ROSEN Group |
| T.D. Williamson |
| Enduro Pipeline Services |
| Intertek Group |
| Others |
Pricing and Supply Chain Analysis
Ultrasonic phased-array modules displacing magnetic flux leakage sensors in Brazil's pre-salt contracts simultaneously concentrate procurement authority with São Paulo-based calibration facilities and compress pricing premiums for legacy electromagnetic tools. This substitution dynamic reshapes vendor margins as operators demand combined crack-detection and wall-thickness capability in single runs.
Pricing Analysis
Next-generation ultrasonic pricing gaps against prior-generation magnetic tools now exceed fifty percent contract value spreads across Brazilian gas transmission corridors. Three-tier pricing structure across premium phased-array, standard electromagnetic, and economy magnetic flux leakage levels reflects certification grade and data interpretation bundling. Pricing pressure stems from currency volatility inflating North American and European sensor import costs. National oil companies demonstrate lowest price sensitivity where ANP compliance documentation requirements favor continuous vendor relationships; independent Llanos Basin producers exhibit highest sensitivity due to environmental contingency bonding capital constraints.
Supply Chain Analysis
Inventory lead times for ultrasonic transducer arrays now stretch twelve to sixteen weeks from North American and European fabrication centers to Brazilian port terminals. Magnetic flux leakage sensor modules and electromagnetic acoustic transducer arrays originate primarily from Germany, the United States, and Japan. Supply chain risk centers on single-source vulnerability for high-resolution phased-array components where qualified alternative suppliers remain uncertified under ANP national content scoring systems. Distribution runs through São Paulo and Rio de Janeiro calibration facilities with satellite logistics coordination from Bogotá for Andean operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent pigging procurement fragmentation across technology tiers, service contracting models, and national regulatory regimes creates multiple entry niches for specialized competitors. ANP mandate tightening and Vaca Muerta infrastructure buildout simultaneously expand addressable demand while preventing vendor consolidation.
For Market Incumbents: Compound calibration infrastructure advantages by establishing satellite verification loops in Neuquén Province and Bogotá before first-movers capture Vaca Muerta and Llanos Basin contracts. Defend against electromagnetic specialist entrants through exclusive data interpretation partnerships with São Paulo engineering universities. Prioritize ANP national content scoring investments to maintain exploration block award eligibility. For New Entrants and Emerging Players: Anchor in Argentina's Vaca Muerta gathering system segment where existing inline inspection infrastructure remains undeveloped and YPF joint ventures seek integrity baselining partners. Target electromagnetic data interpretation services where fewer than two hundred certified analysts operate across the entire continent. Pursue go-to-market positioning as combined-technology run specialists reducing pipeline downtime for high-pressure gas transmission operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed pipeline integrity contractors holding São Paulo calibration facilities but lacking ultrasonic phased-array technology portfolios. Long-term viability hinges on regulatory compliance documentation requirements favoring continuous vendor relationships over transactional procurement. Watch ANP exploration block award announcements as inflection indicator for national content scoring premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Combined-Technology Tool Development | Single-platform integration of magnetic flux leakage with ultrasonic crack detection reduces Santos Basin pipeline downtime. |
| Calibration Laboratory Expansion | Certified pull-through test loops in Neuquén Province capture Vaca Muerta baseline inspection demand before competitors. |
| Electromagnetic Data Interpretation Training | University certification programs address the fewer than two hundred qualified analysts across South America. |
| Predictive Maintenance Contract Conversion | Multi-year bundled subscriptions displace discrete purchase orders under ANP compliance documentation requirements. |
| National Content Scoring Optimization | ANP exploration block awards favor vendors with Brazilian tool maintenance and calibration infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pipeline integrity managers at Petrobras and YPF, procurement officers at Ecopetrol and Pluspetrol, electromagnetic data interpretation specialists in São Paulo, and calibration laboratory directors in Rio de Janeiro. Secondary validation drew from ANP regulatory filings, Colombian Ministry of Mines environmental contingency bond rate schedules, Argentine national gas regulator integrity management standards, SEC 10-K disclosures from listed energy technology conglomerates, and customs import records for magnetic flux leakage sensor modules. Bottom-up project pipeline tracking across Santos Basin pre-salt developments and Vaca Muerta gathering system expansions triangulated against top-down national oil company capital expenditure allocations.
Across the analysis window, the forecasting framework modeled technology segmentation across ultrasonic, magnetic, electromagnetic, and laser platforms; application segmentation across pipelines, storage tanks, offshore rigs, and refineries; end-user segmentation across oil and gas companies, utilities, industrial plants, and inspection services; and service type segmentation across data analysis, maintenance, consulting, and training. CAGRs were derived from regression analysis of historical inspection run volumes against regulatory mandate implementation timelines and greenfield infrastructure commissioning schedules. Industry-specific inputs included ANP biennial inspection frequency mandate compliance rates and Vaca Muerta gathering system kilometer additions.
Decision-makers should treat outputs as directional under assumptions of continued ANP regulatory stringency and stable Brazilian real exchange rates against dollar-denominated equipment costs; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Well Completion Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Exploration and Drilling Security Market