
 Nigeria Oil and Gas Midstream Market | 2026-2036
Nigeria Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Oil and Gas Midstream Market Foresight
Industrial power generators and fertilizer manufacturers is collapsing as the dominant demand anchor for Nigeria's gas processing and pipeline infrastructure, while domestic LPG distributors gain share as a buyer archetype. Nigerian National Petroleum Company Limited anchors national pipeline networks through its joint venture equity positions. Shell PLC leverages deepwater terminal expertise at Bonny and Forcados export points. Oando PLC competes across the retail storage and downstream logistics layer with independent depot holdings.
The Nigeria oil and gas midstream sector covers transportation, storage, and processing infrastructure that bridges upstream production with downstream refining and distribution, encompassing pipeline systems rated for sweet crude and associated gas at pressures typically between 50-150 bar. Pipelines dominate service type revenue due to trunk line obligations under production sharing contracts, while storage facilities command premium margins where jetty access and coastal land scarcity constrain new entrants. Natural gas processing leads technology deployment as associated gas monetization mandates tighten, and liquefaction capacity expansion at Bonny Island reinforces Nigeria LNG Limited's position in Atlantic basin supply.
The Petroleum Industry Act and Department of Petroleum Resources licensing protocols reshape asset ownership rules, compelling joint venture restructuring and domestic supply obligations. Nigerian Midstream and Downstream Petroleum Regulatory Authority standards for gas flare elimination and metering accuracy directly determine infrastructure investment timelines. Stakeholders must weigh feedstock security commitments against export parity economics when committing capital to greenfield processing trains.
Market Dynamics
The Nigerian Midstream and Downstream Petroleum Regulatory Authority is enforcing gas flare elimination mandates that are compressing investment timelines for processing infrastructure. Pipeline operators must now meter associated gas flows with certified accuracy or face operational suspensions. This regulatory pressure is accelerating capital deployment toward gas monetization assets while constraining crude-focused trunk line expansions.
Growth Catalysts
- Domestic LPG Distribution Networks:Independent depot operators are building coastal storage clusters near Lagos and Port Harcourt to capture rising household cooking fuel demand. Jetty access scarcity creates defensive moats for early movers.
- Petroleum Industry Act Licensing Reform:Restructured asset ownership rules are compelling joint venture partners to clarify midstream equity positions. This legal certainty unlocks dormant pipeline maintenance capital.
- Power Generation Offtake Expansion:Industrial electricity producers are signing firm supply contracts with gas processing plants. These long-term purchase commitments de-risk processing train investments.
Market Restraints
- Coastal Land Scarcity:New storage terminal entrants face prohibitive site acquisition costs in the Lagos-Port Harcourt corridor. Existing jetty infrastructure concentrates in legacy operator hands.
- Associated Gas Supply Volatility:Upstream crude production fluctuations directly constrain gas processing feedstock security. Processing plant operators cannot contract independent gas reserves under current joint venture structures.
- Deepwater Terminal Access:Export point capacity at Bonny and Forcados remains controlled by upstream-major equity holders. Independent midstream players lack guaranteed offtake slots.
Strategic Opportunities
- Rivers State Industrial Corridor:Fertilizer manufacturers near Onne are seeking dedicated pipeline lateral connections. Captive industrial demand offers tolling revenue visibility.
- Small-Scale LNG Distribution:Road tanker loading facilities at stranded gas processing sites can serve remote power clusters. This bypasses trunk pipeline coverage gaps.
- Carbon Credit Monetization:Flare gas capture projects qualify for international offset certification. Associated gas-to-power installations generate dual revenue streams from electricity sales and credit retirement.
Industry Challenges
- Pipeline Integrity Assessment Expertise:Sweet crude corrosion monitoring requires specialized inline inspection tool deployment. Local technical capacity for 50-150 bar pressure system diagnostics remains thin.
- Joint Venture Governance Friction:Nigerian National Petroleum Company Limited equity positions create decision paralysis on maintenance scheduling. Operating committees struggle to align on capital prioritization.
- Liquefaction Train Feedstock Coordination:Bonny Island capacity expansion requires synchronized upstream gas field development. Timeline misalignment between exploration and processing commitments delays project financial close.
Report Scope
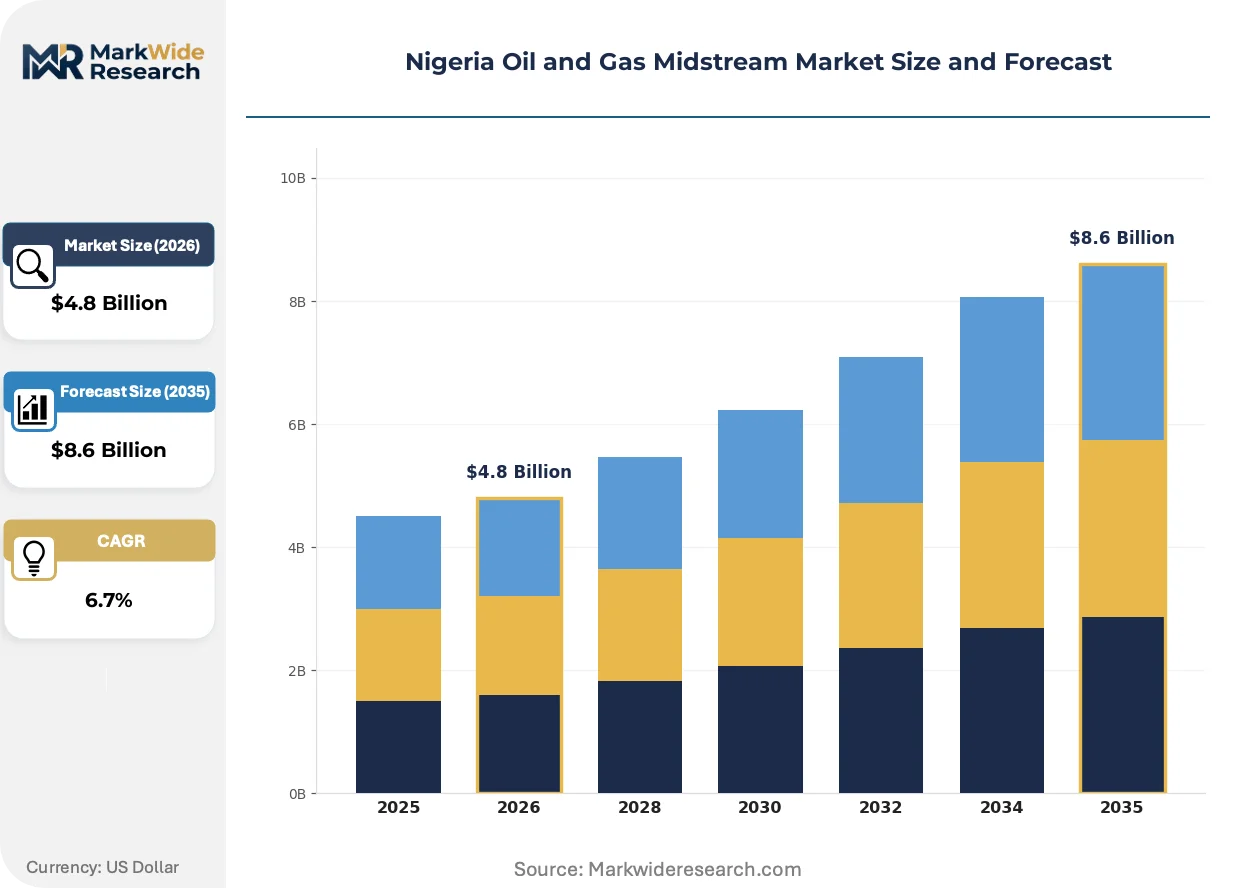
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Oil and Gas Midstream Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pipelines, Storage Facilities, Transportation, Terminal Operations Technology: Natural Gas Processing, Liquefaction, Compression, Separation Infrastructure: Onshore Facilities, Offshore Platforms, Refineries, Pump Stations Supplier Type: Oil Companies, Independent Operators, Government Agencies, Service Providers |
| Companies Covered | Duport Midstream Company Limited, Nigerian National Petroleum Company Limited, Chevron Nigeria Limited, Shell PLC, Eni SPA, Oando PLC, TotalEnergies SE, Nigeria LNG Limited, Sahara Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Oil and Gas Midstream Market Shifts & Advancements
Digital metering infrastructure is compressing revenue leakage in custody transfer operations while enabling real-time pipeline surveillance. Equipment suppliers are responding with integrated pressure-monitoring packages. Three developments are restructuring competitive positioning.
Smart pigging technology for corrosion detection is bifurcating maintenance planning across Nigeria's aging trunk line network. Pipeline operators with predictive analytics capabilities are extending inspection intervals while competitors face emergency shutdown frequency. This capability gap is concentrating operational excellence premiums among technology-advanced asset holders.
The Petroleum Industry Act's domestic supply obligation framework is mandating processed gas reservation for power and industrial users before export allocation. Gas processing license applicants must demonstrate firm local offtake contracts to secure regulatory approval. This policy is redirecting investment toward integrated processing-generation complexes rather than standalone export terminals.
Industrial power generators are consolidating procurement through master service agreements with single gas processing suppliers. Long-term tolling contracts with take-or-pay structures are displacing spot market purchases. This concentration is most visible among cement and steel producers in the Lagos-Port Harcourt corridor seeking feedstock price predictability.
Nigeria Oil and Gas Midstream Market Segmentation
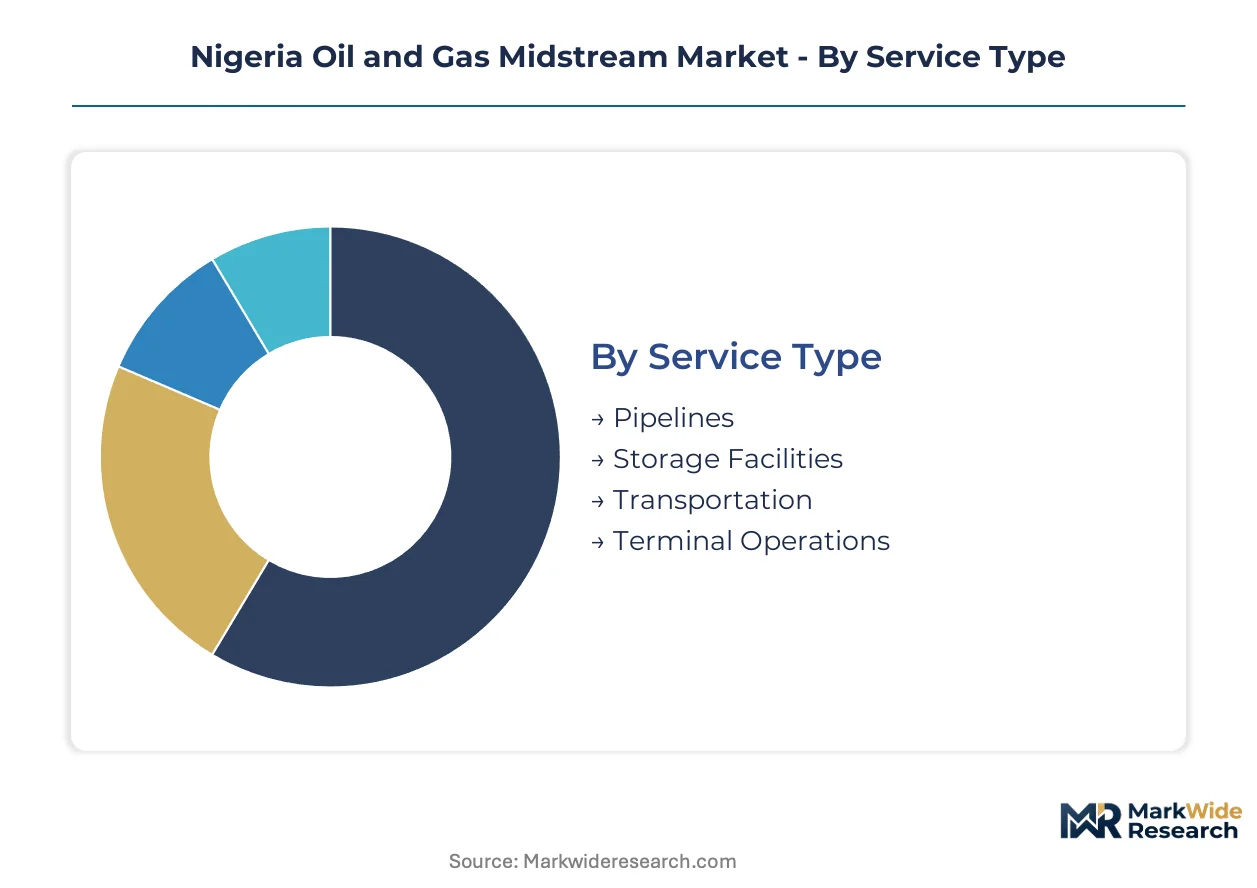
Nigeria's midstream infrastructure divides across service delivery modes, processing technologies, facility locations, and ownership structures. Each segmentation axis reveals distinct investment patterns shaped by coastal geography, regulatory mandates, and joint venture governance.
Service Type:
Export corridors dominate revenue concentration, while domestic distribution networks capture policy-driven expansion.
- Pipelines:Trunk line systems rated 50-150 bar pressure transport sweet crude and associated gas from production fields to coastal terminals. Lagos-Port Harcourt corridor operators command premium tariffs under production sharing contract obligations.
- Storage Facilities:Coastal tank farms and underground caverns buffer supply volatility for refineries and export points. Jetty access scarcity at Lagos and Port Harcourt constrains new entrant capacity additions.
- Transportation:Road tanker fleets and marine vessels bridge pipeline gaps to remote demand clusters. Small-scale LNG road distribution is gaining traction for stranded gas monetization.
- Terminal Operations:Export loading facilities at Bonny and Forcados handle crude liftings and LNG carrier berthing. Deepwater terminal slots remain controlled by upstream-major equity holders.
Pipelines hold the largest share; momentum sits with storage facilities.
Technology:
Cost tier differentiation separates capital-intensive liquefaction from modular processing alternatives.
- Natural Gas Processing:Associated gas treatment plants strip liquids and condition fuel for power generation offtake. Nigerian Midstream and Downstream Petroleum Regulatory Authority flare elimination mandates are accelerating deployment timelines.
- Liquefaction:Cryogenic trains at Bonny Island convert feedstock to LNG for Atlantic basin export. Nigeria LNG Limited capacity expansion requires synchronized upstream gas field development.
- Compression:Gas turbine and electric-driven compressors maintain pipeline pressure across trunk line networks. Metering accuracy certification now determines operational compliance.
- Separation:Phase separation units recover condensate and NGLs from wet gas streams. Rivers State industrial corridor fertilizer manufacturers drive captive demand for dedicated lateral connections.
Natural gas processing anchors current investment; liquefaction shows the steepest expansion trajectory.
Infrastructure:
Volume concentration favors coastal assets, while onshore brownfield expansions offer lower capital intensity.
- Onshore Facilities:Tank farms, pump stations, and processing plants cluster along the Lagos-Port Harcourt corridor. Land scarcity is pushing greenfield development toward secondary port locations.
- Offshore Platforms:Fixed and floating production facilities with integrated midstream handling serve deepwater oil fields. Subsea tieback infrastructure reduces surface facility footprints.
- Refineries:Downstream processing complexes source crude through dedicated pipeline laterals and storage agreements. Domestic supply obligations under the Petroleum Industry Act reshape feedstock allocation priorities.
- Pump Stations:Pressure maintenance infrastructure spaced at intervals across trunk line networks ensures continuous flow. Inline inspection tool deployment requires specialized technical capacity.
Onshore facilities command the largest share; offshore platforms are climbing the fastest.
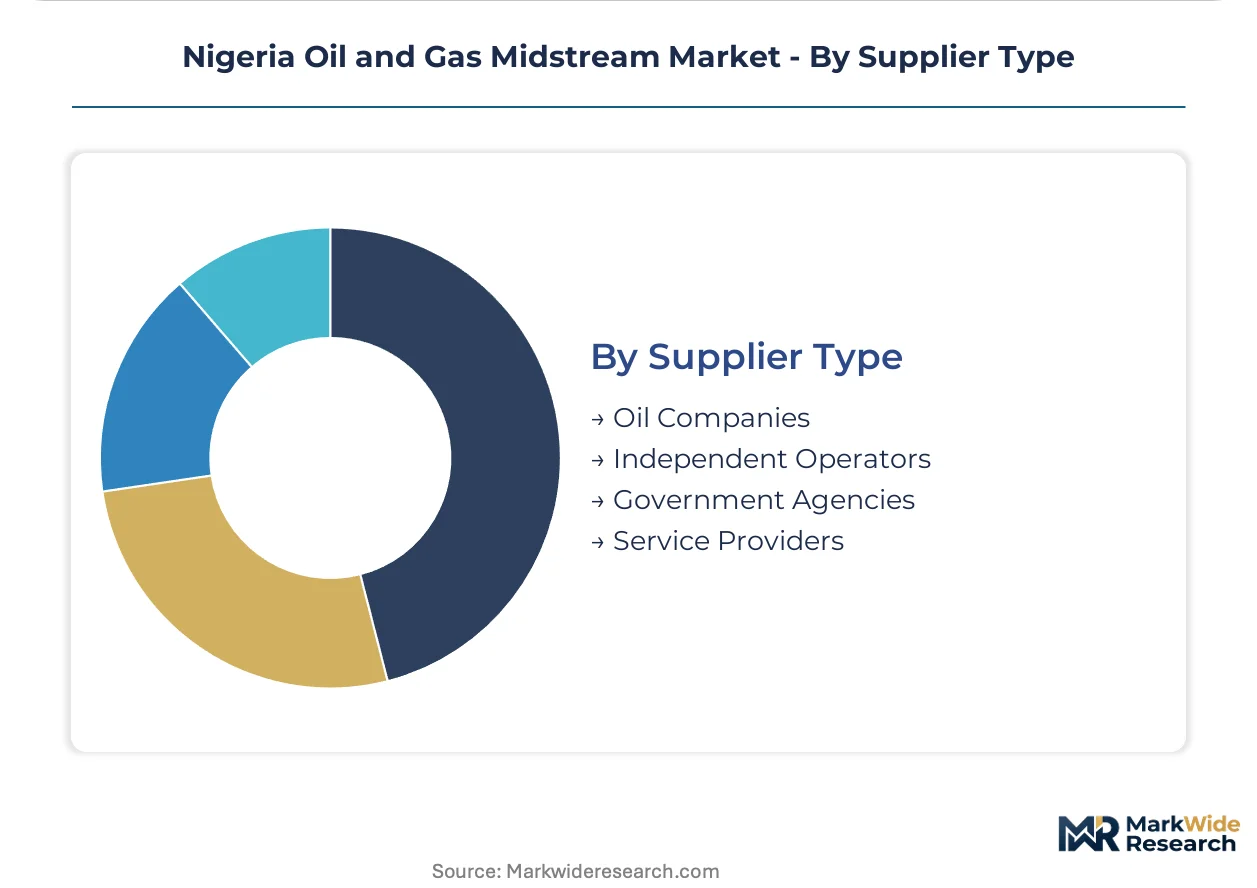
Supplier Type:
Customer type segmentation reveals state equity dominance versus independent operator flexibility.
- Oil Companies:Integrated majors operate captive midstream assets tied to upstream production sharing contracts. Shell PLC leverages deepwater terminal expertise at Bonny and Forcados export points.
- Independent Operators:Non-integrated depot and storage specialists compete on logistics efficiency and customer service. Oando PLC holds retail storage and downstream logistics positions across independent depot holdings.
- Government Agencies:Nigerian National Petroleum Company Limited anchors national pipeline networks through joint venture equity positions. Operating committee governance friction creates decision paralysis on maintenance scheduling.
- Service Providers:Technical contractors supply pipeline integrity assessment, metering calibration, and digital infrastructure. Smart pigging technology deployment is bifurcating maintenance planning capabilities across the aging trunk line network.
Oil companies retain the largest share; independent operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Escravos-Lagos Pipeline System anchors Nigeria's midstream infrastructure backbone, threading through the Niger Delta to coastal export terminals and domestic demand centers. This trunk line network underwrites the country's role as West Africa's primary hydrocarbon logistics hub.
Lagos State
Apapa and Tin Can Island port complexes handle refined product imports and LPG vessel discharge for national distribution. The Nigerian Midstream and Downstream Petroleum Regulatory Authority enforces metering accuracy standards at coastal storage terminals. Ijora and satellite depot clusters around Lagos Harbor are expanding jetty capacity to capture rising household cooking fuel demand.
Rivers State
Onne and Port Harcourt industrial zones drive captive gas demand from fertilizer manufacturers and petrochemical complexes. The Petroleum Industry Act mandates domestic supply obligations before export allocation for gas processing license holders. Bonny Island liquefaction trains and Forcados export terminal concentrate deepwater terminal capacity under upstream-major equity structures.
Delta State
Warri and Kaduna refinery pipeline laterals source crude through the Trans-Forcados system and Escravos trunk lines. Department of Petroleum Resources licensing protocols compel joint venture restructuring for midstream asset ownership clarity. Sapele and Koko storage depots buffer supply volatility for northern distribution networks.
Bayelsa State
Brass River terminal and associated gas gathering systems serve offshore production tiebacks from shallow-water fields. Gas flare elimination mandates compress investment timelines for associated gas monetization infrastructure. Yenagoa logistics bases support subsea pipeline maintenance and inline inspection tool deployment.
Nigeria Oil and Gas Midstream Market Competitive Landscape
Listed leaders compete with private specialists across equity structure and capital access dimensions. State equity positions through Nigerian National Petroleum Company Limited anchor national pipeline networks, while international majors retain deepwater terminal control. Three archetypes dominate: integrated upstream-majors with captive midstream assets, independent depot operators competing on logistics efficiency, and state-backed entities holding joint venture governance positions. Competitive moves concentrate on joint venture restructuring clarity and coastal storage cluster expansion near demand centers.
Within the state-backed tier, Nigerian National Petroleum Company Limited occupies a position exemplifying joint venture equity dominance over trunk line networks. Shell PLC and Oando PLC represent contrasting archetypes: the former anchors deepwater terminal expertise at Bonny and Forcados export points, while the latter sits within independent retail storage and downstream logistics positioning across depot holdings.
| Leading Market Players |
|---|
| Duport Midstream Company Limited |
| Nigerian National Petroleum Company Limited |
| Chevron Nigeria Limited |
| Shell PLC |
| Eni SPA |
| Oando PLC |
| TotalEnergies SE |
| Nigeria LNG Limited |
| Sahara Group |
| Others |
Supply & Pricing Matrix
Escravos terminal throughput scale shapes both supply concentration along the Lagos-Port Harcourt corridor and price floors for coastal storage services. Nigerian National Petroleum Company Limited joint venture positions anchor tariff benchmarks across trunk line networks while jetty access scarcity defends incumbent margins against new storage terminal entrants.
Pricing Analysis
Volume-discount tiering structures separate major industrial offtakers from household LPG distributors across gas processing contracts. Pricing stratifies across premium firm-supply tiers, standard interruptible arrangements, and economy spot-market access based on metering certification and take-or-pay commitment length. Cost compression in standard-tier tolling runs through Nigerian Midstream and Downstream Petroleum Regulatory Authority flare elimination compliance investments. Industrial power generators exhibit lowest price sensitivity due to feedstock security requirements, while independent LPG distributors face acute margin pressure from jetty queue competition.
Supply Chain Analysis
Escravos terminal jetty queues bottleneck crude evacuation before Bonny Island liquefaction feedstock aggregation. Equipment supply draws from Germany, South Korea, and the United States for 50-150 bar pressure-rated pipeline components. Single-source vulnerability concentrates in smart pigging inspection tool providers with limited local technical capacity. Distribution runs through Nigerian National Petroleum Company Limited equity-controlled trunk lines to coastal export terminals and domestic refinery laterals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
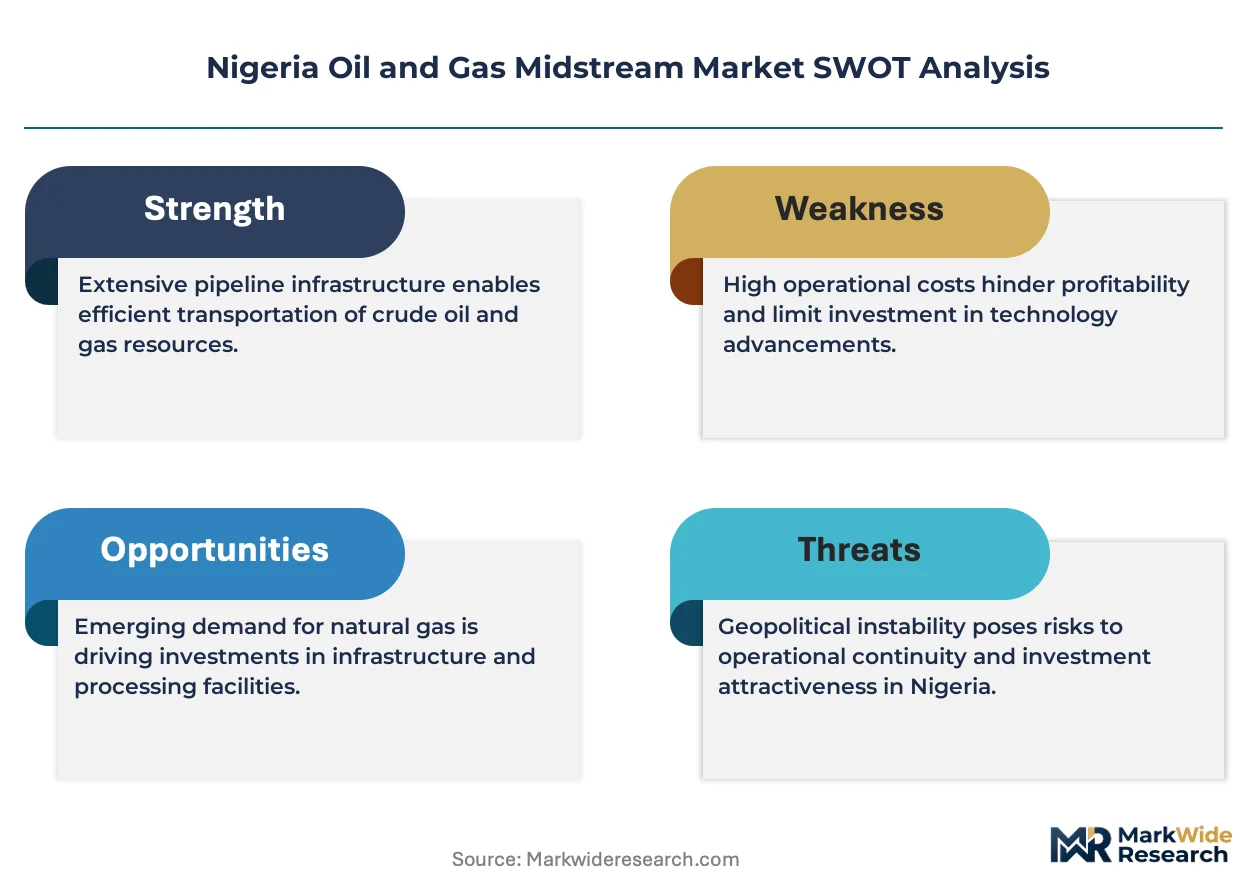
Nigeria's oil and gas midstream market operates as a defensive-moat story anchored in regulatory entrenchment. Petroleum Industry Act licensing protocols and coastal land scarcity create structural barriers that protect incumbent returns against price erosion.
For Market Incumbents: Consolidate coastal storage cluster positions through jetty capacity expansion at Lagos and Port Harcourt before land scarcity intensifies. Deepen backward integration into gas processing trains to capture flare elimination mandate premiums. Joint venture governance friction at Nigerian National Petroleum Company Limited-operated pipelines presents maintenance deferral risks that disciplined operators can exploit through predictive analytics deployment.
For New Entrants and Emerging Players: Nigerian Midstream and Downstream Petroleum Regulatory Authority certification fast-tracks for small-scale LNG road distribution unlock stranded gas monetization without trunk pipeline dependence. Target Rivers State industrial corridor fertilizer manufacturers seeking dedicated lateral connections bypassing congested mainlines. Pursue tolling partnerships with captive industrial offtakers rather than competing for export terminal slots controlled by upstream-major equity holders.
For Investors and Strategic Acquirers: Independent depot operators with established jetty access and Nigerian National Petroleum Company Limited offtake relationships represent the most defensible acquisition archetype. Long-term viability across the analysis window hinges on Petroleum Industry Act implementation clarity and domestic supply obligation enforcement consistency. Watch Nigerian National Petroleum Company Limited joint venture restructuring announcements as inflection indicators for dormant pipeline maintenance capital activation.
| Strategic Initiative | Industry Significance |
|---|---|
| Jetty Capacity Expansion | Coastal land scarcity at Lagos and Port Harcourt defends incumbent storage terminal margins against new entrants. |
| Gas Processing Train Addition | Flare elimination mandates compress investment timelines while securing firm power generation offtake contracts. |
| Smart Pigging Technology Deployment | Predictive analytics capabilities extend inspection intervals and concentrate operational excellence premiums. |
| Small-Scale LNG Distribution Buildout | Road tanker loading facilities bypass trunk pipeline coverage gaps to serve remote industrial power clusters. |
| Carbon Credit Certification Program | Associated gas-to-power installations generate dual revenue streams from electricity sales and offset retirement. |
Research Methodology
Operator-level perspectives from pipeline control room engineers, gas processing plant managers, coastal terminal logistics coordinators, and Nigerian Midstream and Downstream Petroleum Regulatory Authority licensing officers anchored the qualitative base. Secondary validation drew from Department of Petroleum Resources regulatory filings, Nigerian National Petroleum Company Limited joint venture disclosure documents, Petroleum Industry Act statutory instruments, and Escravos-Lagos Pipeline System operational bulletins. Bottom-up segmentation sizing and top-down macroeconomic anchor triangulation cross-checked volume and value estimates.
Sensitivity analysis tested forecast robustness across upstream production volatility scenarios and regulatory implementation pace variations. The analytical framework modeled service type, technology tier, infrastructure location, and supplier ownership structure dimensions throughout the forecast period. CAGRs derived from historical trajectory analysis, policy mandate impact assessment, and industrial demand elasticity calibration against power generation and fertilizer manufacturing capacity expansion plans.
Decision-makers should treat outputs as directional under sustained Petroleum Industry Act enforcement and Escravos terminal throughput stability; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as Nigerian National Petroleum Company Limited joint venture governance restructuring and Bonny Island liquefaction feedstock coordination timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Sand Control Screens Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Wireline Services Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Canada LNG Market
Oil & Gas
India AI in Oil and Gas Market