
 Land Drilling Rig Market | 2026-2036
Land Drilling Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Land Drilling Rig Market Foresight
Gas companies is recalibrating land rig demand as LNG export capacity expansions in the US Gulf Coast sustain long-haul horizontal drilling programs. Nabors Industries Ltd leverages its SmartRig platform to automate repetitive drilling sequences and reduce crew exposure on multi-well pads. Helmerich & Payne Inc. anchors the US super-spec segment with a fleet weighted toward AC-powered walking rigs purpose-built for Permian and DJ Basin operators. Schlumberger Limited competes through integrated well construction contracts that bundle rig services with directional drilling and logging-while-drilling technologies.
A land drilling rig is a self-propelled or skid-mounted mechanical assembly designed to rotate drill strings, circulate drilling fluid, and hoist tubulars at depths exceeding 20,000 feet in onshore hydrocarbon formations. The system integrates a mast or derrick, drawworks, top drive or rotary table, mud pumps, and blowout preventer stack to maintain wellbore pressure integrity during exploration and production phases. Mobile rigs and modular rigs command expanding share as operators prioritize rapid rig-up/rig-down cycles and component standardization across dispersed leaseholds. Diesel power source configurations still dominate installed fleets, though hybrid power source units are penetrating environmentally sensitive basins where flaring restrictions and noise ordinances limit conventional generator runtime. Exploration application demand fluctuates with lease expiration schedules and federal land permitting timelines, while production application work sustains more predictable utilization through infill drilling and lateral re-drill programs.
EPA New Source Performance Standards for greenhouse gas emissions and OSHA Process Safety Management requirements shape rig design mandates, particularly around closed-loop mud systems and automated pipe handling to reduce crew count at the wellsite. API Specification 4F and ISO 13628-7 provide structural and subsea equipment standards that manufacturers must certify against for market access in North American and international jurisdictions. Stakeholders must weigh capital allocation between newbuild AC rigs with battery-hybrid power packs and rig refurbishment programs that extend mechanical life without full replacement, as basin economics and carbon intensity benchmarks tighten simultaneously.
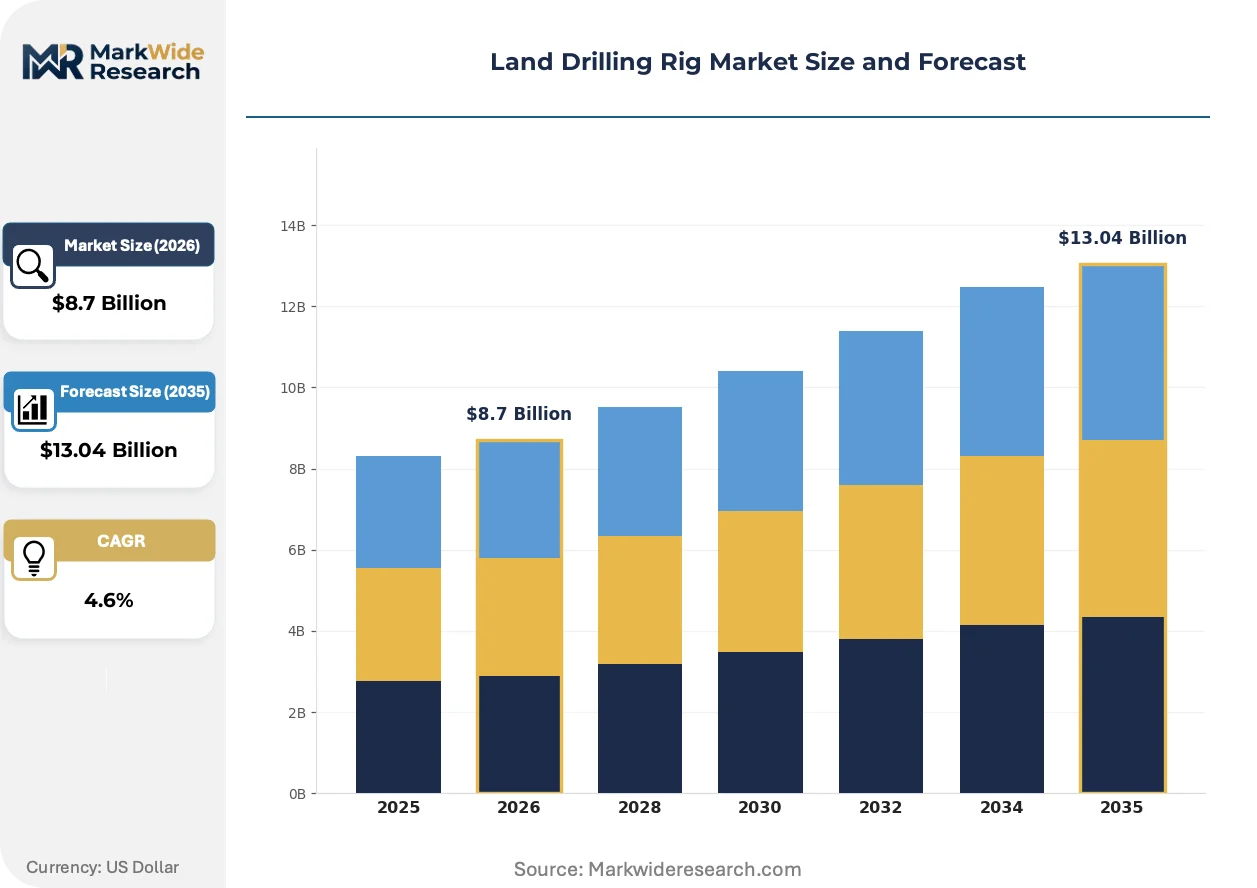
Market Dynamics
AC-powered walking rigs with integrated battery-hybrid power packs are compressing pad-to-pad mobilization cycles while EPA methane emissions rules force capital redeployment toward closed-loop mud systems and automated pipe handling.
Growth Catalysts
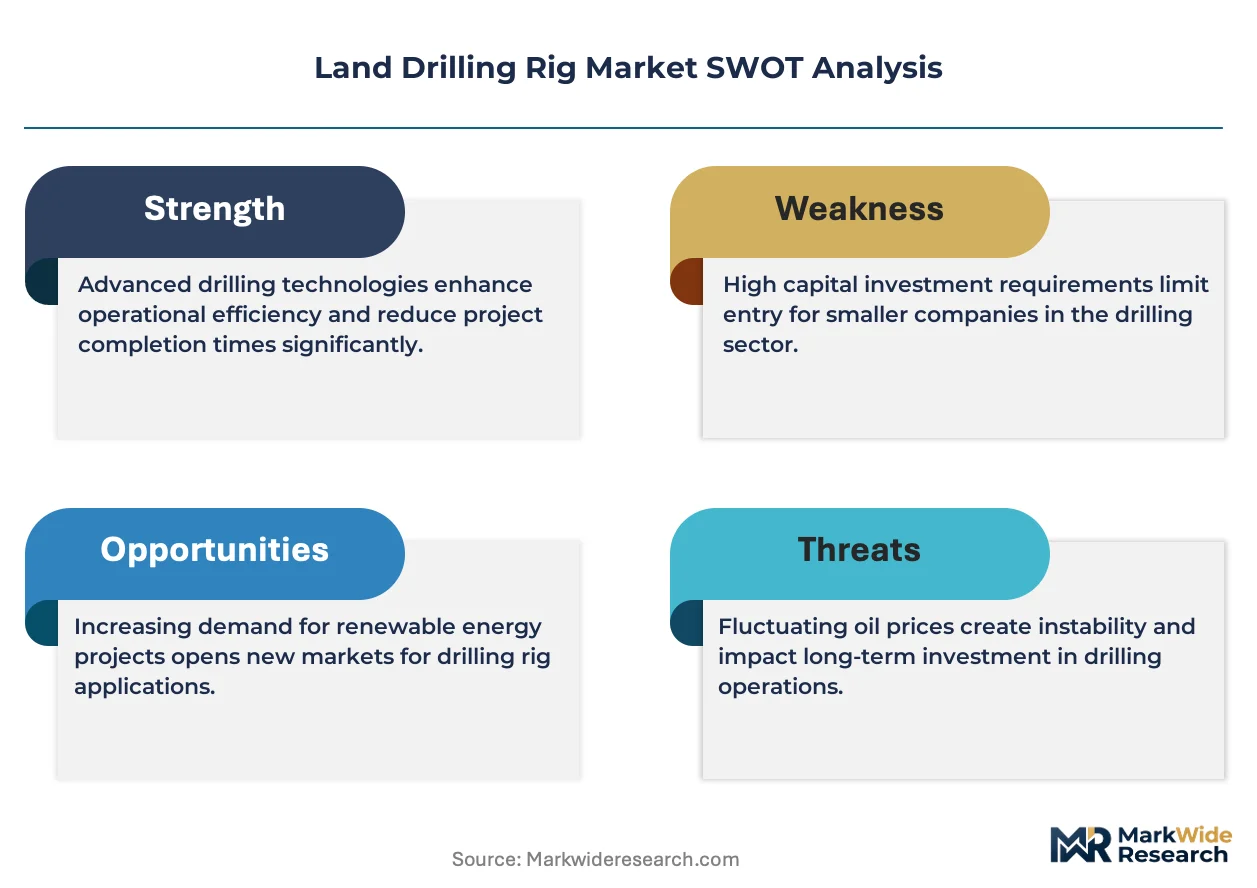
- EPA New Source Performance Standards:Tightening greenhouse gas thresholds for onshore oil and gas operations mandate automated drilling sequences and reduced wellsite crew counts, accelerating rig modernization cycles in US shale basins.
- Permian Basin stacked-pay geology:Multi-zone horizontal targets sustain multi-year drilling programs that favor high-spec AC rigs with walking systems capable of batch-drilling 20+ wells per pad.
- Rig automation platforms:SmartRig-class systems reduce non-productive time through automated tripping and connection sequences, cutting exposure hours and insurance liabilities for multi-well pad operators.
Market Restraints
- Steel and alloy input volatility:Mast and derrick fabrication depends on high-strength structural steel and chromium-molybdenum alloys subject to commodity price swings that compress newbuild margins.
- Specialized component supply concentration:Top drive assemblies and advanced drawworks originate from a narrow supplier base concentrated in Texas and Oklahoma, creating single-source vulnerability during demand surges.
- Skilled rig mechanic scarcity:Electrified AC drive systems and battery-hybrid power architectures require technicians trained in high-voltage maintenance, a skill set in short supply across Appalachian and Rocky Mountain basins.
Strategic Opportunities
- Argentina Vaca Muerta shale:Underpenetrated unconventional resource development creates demand for mobile super-spec rigs capable of extended-reach laterals in remote Neuquén Basin locations lacking established service infrastructure.
- OSHA Process Safety Management alignment:Automated blowout preventer testing and remote monitoring capabilities position rig lessors for premium dayrate tiers as operators seek compliance documentation automation.
- Digital twin convergence with predictive maintenance:Integration of real-time sensor telemetry with cloud-based asset modeling enables condition-based overhaul scheduling, extending mechanical life without full rig replacement.
Industry Challenges
- API Specification 4F certification timelines:Third-party structural validation for mast and substructure designs extends 14-18 months, delaying newbuild deliveries during demand windows.
- Legacy mechanical rig integration:Retrofitting SCR-powered fleets with battery-hybrid power packs requires dc-ac conversion architecture that conflicts with existing generator control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land Drilling Rig Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Static Rigs, Mobile Rigs, Modular Rigs, Carrier Rigs Power Source: Diesel, Electric, Hybrid, Solar End User: Oil Producers, Gas Companies, Mining Operations, Research Institutions Application: Exploration, Production, Maintenance, Decommissioning |
| Companies Covered | Nabors Industries Ltd, Helmerich & Payne Inc., Schlumberger Limited, Patterson-UTI Energy Inc, Precision Drilling Corp., Ensign Energy Services Inc., Weatherford International PLC, KCA Deutag Group, Eurasia Drilling Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land Drilling Rig Market Shifts & Advancements
Electrification and automation are compressing the traditional tradeoff between mobility and horsepower, enabling pad drilling economics to penetrate thinner-margin formations previously reserved for high-volume conventional targets.
AC variable-frequency drive systems with integrated energy storage modules are overtaking traditional diesel-mechanical powertrains as the dominant rig architecture. Permian and DJ Basin operators now specify 1,500+ horsepower AC walking rigs for 95% of new pad developments. The technology is overtaking legacy mechanical fleets by eliminating fuel consumption during standby operations and enabling regenerative braking energy recovery during tripping sequences.
EPA methane emissions monitoring and repair protocols are mandating continuous optical gas imaging at wellsite perimeters. Closed-loop mud systems with vacuum degassing units now accompany automated rig packages to eliminate atmospheric venting during connections. Land rig lessors in the Permian and Bakken formations are retrofitting existing fleets with flare gas capture skids to maintain permit eligibility under state implementation plans.
Dayrate contracting with integrated performance bonuses is displacing traditional footage-based agreements in horizontal shale programs. US independents now bundle directional drilling, logging-while-drilling, and rig services under single-source well construction contracts that penalize non-productive time. This model concentrates procurement authority with super-major operators in the Delaware Basin and Midland Basin sub-plays, squeezing standalone rig contractors into subcontractor roles.
Land Drilling Rig Market Segmentation
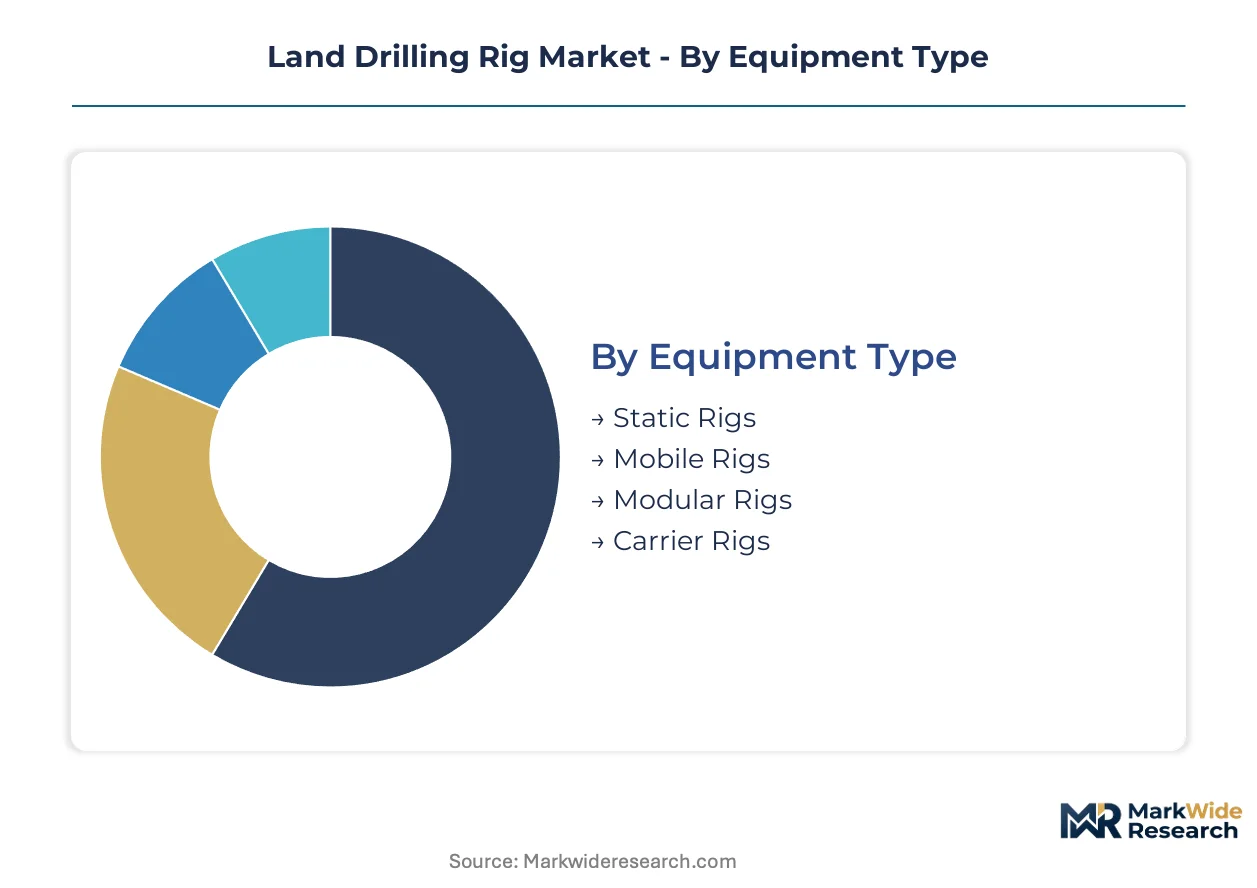
Equipment specifications and power configurations determine dayrate premiums and pad economics in unconventional basins. Operators match rig class to well complexity, lateral length, and batch-drilling intensity.
Equipment Type:
AC-powered walking architectures and modular component designs are compressing mobilization cycles while extending reach into multi-well pad developments.
- Static Rigs:Fixed-position mast and substructure assemblies anchor high-horsepower drilling in Permian Basin super-pads where 20+ laterals are batch-drilled from single surface locations. These configurations sacrifice mobility for structural capacity, commanding premium dayrates in Delaware Basin stacked-pay zones.
- Mobile Rigs:Self-propelled carrier-mounted systems with rapid rig-up/rig-down protocols serve dispersed leaseholds in Appalachian shale where pad density remains lower. EPA methane monitoring requirements favor these units for exploratory programs requiring frequent relocation.
- Modular Rigs:Component-standardized architectures enable helicopter or truck transport into remote Neuquén Basin locations lacking established road infrastructure.
- Carrier Rigs:Truck-mounted assemblies with telescoping masts address vertical drilling programs in mature conventional fields across the Rocky Mountain basins.
Static rigs lead on scale; mobile rigs lead on momentum.
Power Source:
Capital allocation between fuel architectures reflects flaring restrictions, carbon intensity benchmarks, and basin-specific noise ordinances.
- Diesel:Mechanical and SCR-electrified diesel configurations still dominate installed fleet hours, particularly in Bakken and Powder River Basin operations where cold-weather reliability outweighs emissions considerations. These units face permit pressure under state implementation plans targeting wellsite greenhouse gas intensity.
- Electric:Grid-tied or generator-powered AC variable-frequency drives eliminate fuel consumption during standby and enable regenerative braking during tripping. Permian operators now specify electric power for 95% of newbuild super-spec rigs.
- Hybrid:Battery-hybrid power packs with diesel backup penetrate environmentally sensitive basins where flaring restrictions limit conventional generator runtime.
- Solar:Photovoltaic-augmented auxiliary power serves remote monitoring and lighting loads in Middle Eastern desert drilling programs.
Electric configurations lead on scale; hybrid architectures are gaining share fastest.
End User:
Procurement authority concentrates with integrated operators bundling rig services into well construction contracts.
- Oil Producers:Permian and DJ Basin independents drive super-spec AC rig demand for 10,000+ foot laterals in Wolfcamp and Niobrara formations. These operators prioritize walking systems and automated pipe handling to reduce crew exposure and non-productive time.
- Gas Companies:Appalachian and Haynesville shale operators favor high-pressure-capable rigs for extended-reach horizontal programs feeding Gulf Coast LNG export capacity.
- Mining Operations:Geothermal and potash exploration programs in Utah and Saskatchewan repurpose underutilized mechanical rigs for coring and slim-hole applications.
- Research Institutions:Academic and government geoscience programs operate shallow-depth modular rigs for crustal sampling and carbon sequestration pilot wells.
Oil producers lead on scale; gas companies lead on momentum.
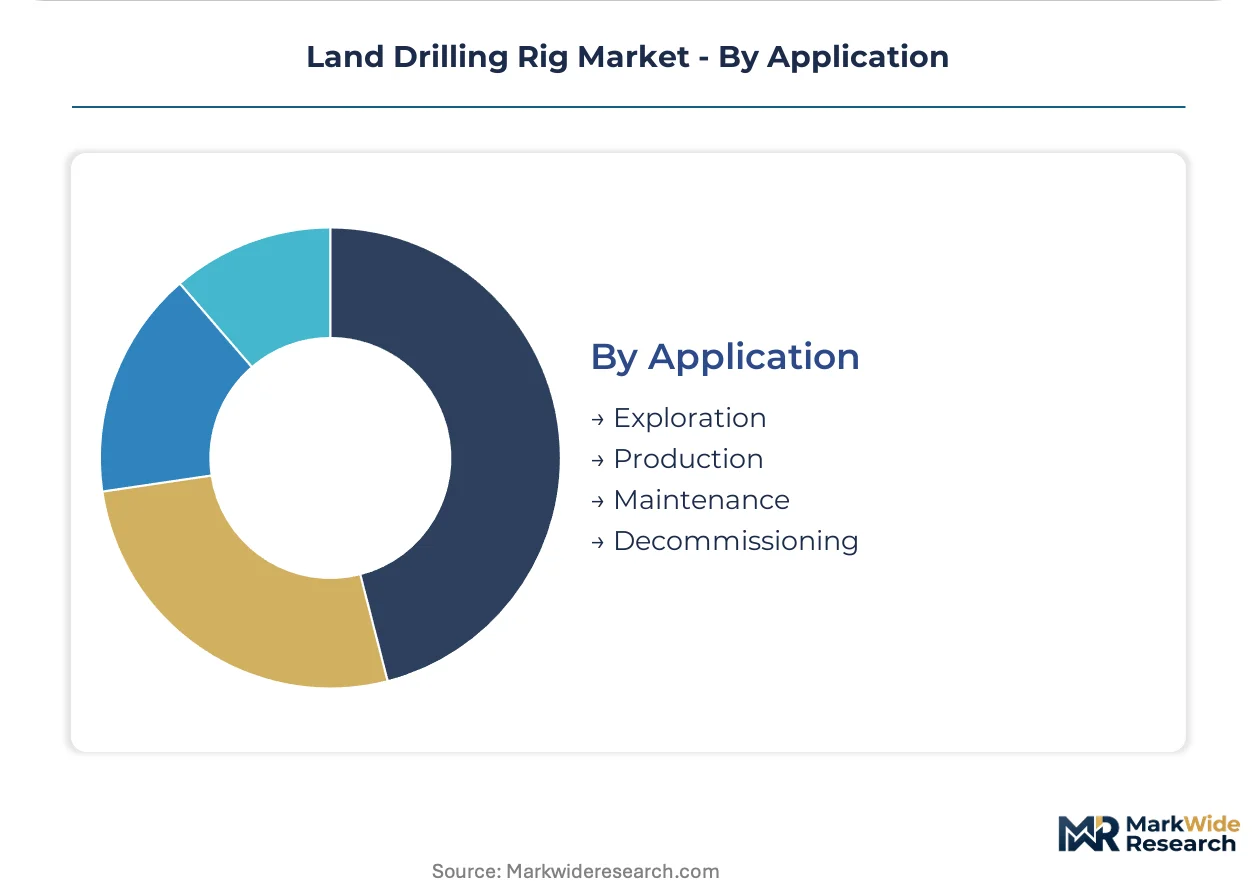
Application:
Work type determines rig specification, contract duration, and utilization predictability across the well lifecycle.
- Exploration:Wildcat and step-out drilling in underpenetrated basins such as Vaca Muerta requires mobile super-spec rigs capable of extended-reach laterals without established service infrastructure. Lease expiration schedules and federal permitting timelines create demand volatility.
- Production:Infill drilling and lateral re-drill programs in Midland Basin Spraberry and Wolfcamp zones sustain more predictable utilization through multi-year pad development contracts.
- Maintenance:Workover and recompletion operations on existing wellbores utilize smaller carrier rigs for artificial lift installation and stimulation re-entries.
- Decommissioning:Plugging and abandonment programs in mature California and Appalachian fields deploy lightweight modular rigs for regulatory compliance and site restoration.
Production applications lead on scale; exploration commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting capital toward jurisdictions with streamlined permitting and lower compliance costs, while mature basins face equipment obsolescence pressures from tightening emissions standards. Operators migrate fleet deployments based on methane monitoring requirements and state-level flaring restrictions.
United States
Permian Basin stacked-pay geology sustains multi-year drilling programs favoring AC-powered walking rigs with automated pipe handling. EPA New Source Performance Standards mandate closed-loop mud systems and reduced wellsite crew counts, accelerating rig modernization cycles. West Texas and southeastern New Mexico anchor super-spec rig demand where batch-drilling 20+ wells per pad compresses capital efficiency.
Argentina
Vaca Muerta shale development creates demand for mobile super-spec rigs capable of extended-reach laterals in remote Neuquén Basin locations lacking established service infrastructure. Federal hydrocarbon investment incentives under the Plan Gas.Ar program subsidize unconventional exploration activity. Neuquén Province concentrates drilling permits where modular rig architectures enable helicopter transport into road-constrained leaseholds.
Saudi Arabia
Gas field development programs sustain land rig demand for high-pressure horizontal drilling in tight sandstone formations. The Ministry of Energy's gas production targets require expanded onshore drilling capacity beyond offshore-centric legacy operations. Eastern Province fields around Ghawar and Khurais anchor rig deployment schedules tied to domestic gas supply commitments.
Canada
Montney and Duvernay shale operators prioritize AC rigs with battery-hybrid power packs to meet provincial carbon intensity benchmarks and noise ordinances in populated areas. Alberta's Technology Innovation and Emissions Reduction regulation imposes facility-level emissions caps that favor electrified rig architectures. Grande Prairie and Fort St. John serve as rig mobilization hubs for winter drilling windows in northern leaseholds.
China
Sichuan Basin shale gas development drives demand for high-spec rigs targeting marine-continental transitional facies at depths exceeding 3,500 meters. National Energy Administration production targets for unconventional gas prioritize domestic rig manufacturing and technology transfer partnerships. Chongqing municipality anchors drilling activity where state-owned operators batch-develop Fuling and Weirong field blocks.
Land Drilling Rig Market Competitive Landscape
Capacity expansion dominates the current landscape as rig lessors rebuild fleets around AC variable-frequency drive architectures and battery-hybrid power packs. The vendor base stratifies between integrated oilfield service conglomerates bundling rig services with directional drilling, and specialized rig contractors focused on super-spec AC walking systems. Three archetypes occupy distinct competitive positions: full-service well construction integrators, premium-tier rig lessors with proprietary automation platforms, and regional mechanical rig operators serving conventional vertical programs. M&A activity concentrates on automation technology acquisition and basin-specific fleet consolidation, while strategic partnerships between rig contractors and directional drilling specialists reshape contracting structures.
Among North American rig lessors, Nabors Industries Ltd, Helmerich & Payne Inc., and Patterson-UTI Energy Inc. exemplify divergent strategic positions. Nabors anchors the automation-integrated tier through proprietary SmartRig-class platforms that reduce non-productive time via automated tripping sequences. Helmerich & Payne occupies the super-spec AC rig specialist position with fleet concentration in Permian and DJ Basin walking systems. Patterson-UTI represents the scale-driven consolidator archetype, leveraging fleet breadth across multiple shale basins to capture integrated well construction contracts. These three entities collectively illustrate how technology differentiation, geographic concentration, and contracting model innovation define competitive separation in modern land rig markets.
| Leading Market Players |
|---|
| Nabors Industries Ltd |
| Helmerich & Payne Inc. |
| Schlumberger Limited |
| Patterson-UTI Energy Inc |
| Precision Drilling Corp. |
| Ensign Energy Services Inc. |
| Weatherford International PLC |
| KCA Deutag Group |
| Eurasia Drilling Company Limited |
| Others |
Supply & Pricing Matrix
AC variable-frequency drive adoption and battery-hybrid power pack integration are simultaneously elevating capital intensity for rig lessors and concentrating component sourcing among Texas and Oklahoma-based suppliers with certified high-voltage assembly capabilities. This technology transition compresses margins for mechanical rig operators while rewarding early movers with EPA-compliant fleet positions that command dayrate premiums in Permian and DJ Basin contracting.
Pricing Analysis
Distributor margins on replacement top drive assemblies and drawworks components typically run 15-25 points above direct OEM procurement, though integrated well construction contracts increasingly bypass channel intermediaries. Dayrate structures stratify across premium AC walking rigs with automation packages, standard SCR-electrified units, and economy mechanical rigs serving vertical programs. Pricing pressure stems from steel and alloy input volatility eroding newbuild margins. Independent Permian operators exhibit highest price sensitivity, while super-majors prioritize non-productive time reductions over dayrate differentials.
Supply Chain Analysis
Argentina's Plan Gas.Ar local-content mandates are reshaping sourcing patterns for Vaca Muerta development, requiring foreign rig contractors to partner with Neuquén Basin fabrication shops or face permit disqualification. Mast and derrick fabrication draws from high-strength structural steel mills in the United States, China, and South Korea. Chromium-molybdenum alloy dependence creates single-source vulnerability during demand surges. Distribution runs through Houston and Oklahoma City equipment yards serving North American shale basins, with regional stocking points in Grande Prairie for Canadian winter programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Land drilling rig deployment economics represent a geographic-arbitrage play where Argentina's federal hydrocarbon subsidies and streamlined permitting under Plan Gas.Ar contrast with EPA compliance costs compressing returns in US shale basins.
For Market Incumbents: To counter skilled rig mechanic scarcity for electrified AC systems, anchor fleet modernization programs around automation platform differentiation and captive technician training academies in the Permian and DJ Basin. Secure backward integration into battery-hybrid power pack assembly through partnerships with Texas-based energy storage specialists. For New Entrants and Emerging Players: Enter via Argentina's Vaca Muerta shale where underpenetrated unconventional resource development and federal investment incentives create demand for mobile super-spec rigs without established service infrastructure. Target Neuquén Basin operators through modular rig architectures enabling helicopter transport into road-constrained leaseholds. For Investors and Strategic Acquirers: Valuations sit cheapest among legacy mechanical rig operators with stranded assets in mature conventional fields, though long-term viability over a five-to-ten year window hinges on successful AC conversion or scrap recovery. Watch EPA methane enforcement intensity as the inflection indicator for forced fleet retirement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Platform Development | Nabors SmartRig-class systems reduce non-productive time through automated tripping sequences in multi-well pad operations. |
| Battery-Hybrid Power Pack Integration | AC rigs with energy storage modules eliminate fuel consumption during standby and enable regenerative braking during tripping. |
| Argentina Market Entry | Plan Gas.Ar subsidies and Vaca Muerta geology create demand for mobile super-spec rigs in infrastructure-constrained Neuquén Basin. |
| Technician Training Academy Buildout | High-voltage maintenance skills scarcity in Appalachian and Rocky Mountain basins favors captive workforce development programs. |
| Integrated Well Construction Contracting | Single-source bundling of rig services with directional drilling concentrates procurement authority with super-major Delaware Basin operators. |
Research Methodology
Multiple input streams — rig utilization databases, equipment procurement records, and regulatory filing repositories — were reconciled to construct market estimates. Primary interviews with rig lessor fleet managers, E&P drilling engineers, EPA compliance officers, and oilfield service procurement leads were cross-validated against secondary sources including EIA drilling productivity reports, OSHA enforcement data, SEC 10-K filings from listed contractors, and API specification certification records. Bottom-up rig count and dayrate modeling was triangulated with top-down capital expenditure analysis across major shale basins.
Data-stream reconciliation anchored volume projections to segmented rig class deployment patterns across the analysis window. Segmentation dimensions modeled include equipment type, power source architecture, end-user category, and application work type. CAGRs were derived from rig fleet expansion schedules and replacement cycle assumptions tied to EPA compliance deadlines. Industry-specific forecast inputs incorporated Permian Basin stacked-pay drilling intensity and Argentina Vaca Muerta permit approval velocity.
Inputs from EIA drilling reports and API certification databases were available through the study window; gaps in private rig contractor financial disclosures introduce uncertainty bands around dayrate elasticity estimates. Forecasts reflect assumptions regarding methane regulation enforcement timing and steel input cost trajectories. Regulatory rulemaking delays, basin-specific permitting backlogs, and battery supply chain constraints constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
Oil, Gas and Chemicals Software Market
Oil & Gas
Proppant Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Oil Hose Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Europe Hydraulic Fracturing Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Global Seismic Survey Market