
 Oil and Gas Logistics Market | 2026-2036
Oil and Gas Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Logistics Market Intelligence
The reliance on fragmented, regional service providers for specialized equipment transport is narrowing as integrated, end-to-end logistics solutions become standard. Kuehne + Nagel leverages its global network to offer comprehensive project logistics for large-scale energy projects. DHL Group differentiates through its expertise in customs brokerage and compliance for cross-border hydrocarbon shipments, particularly for refinery managers.
Oil and gas logistics encompasses the planning, execution, and control of moving equipment, materials, and personnel across the energy value chain. The practice involves coordinating multimodal transport, including heavy-lift cargo and hazardous materials, under strict safety protocols. Transportation services represent the core cost component, while integrated freight forwarding and warehousing solutions provide higher-margin opportunities. Upstream supply chain activities, particularly for offshore installations, demand the most sophisticated logistics.
Environmental regulations from bodies like the US EPA influence fleet modernization and emissions reporting. Concurrently, international standards from the IMO govern safety and pollution prevention for the maritime transport of oil and gas products. A provider's ability to integrate digital fleet management systems with sustainable transport options will determine future market leadership.
Market Dynamics
The central force shaping the oil and gas logistics market is the convergence of digitalization with the operational demands of increasingly remote and complex extraction projects. Integrated, cloud-based platforms are becoming essential for managing supply chain visibility and efficiency.
Growth Catalysts
- Offshore Expansion:Deepwater exploration and production activities, particularly in Brazil's pre-salt basins and Guyana, necessitate sophisticated and large-scale project logistics for subsea equipment and floating production systems.
- Shale Production:Sustained drilling and completion activity in North American shale plays like the Permian Basin requires a continuous and high-volume supply chain for proppants, water, and production equipment, supporting regional logistics providers.
- Digital Adoption:The use of IoT sensors and cloud-based logistics management platforms enhances real-time tracking of high-value assets and materials, reducing downtime and improving planning accuracy for upstream operators.
Market Restraints
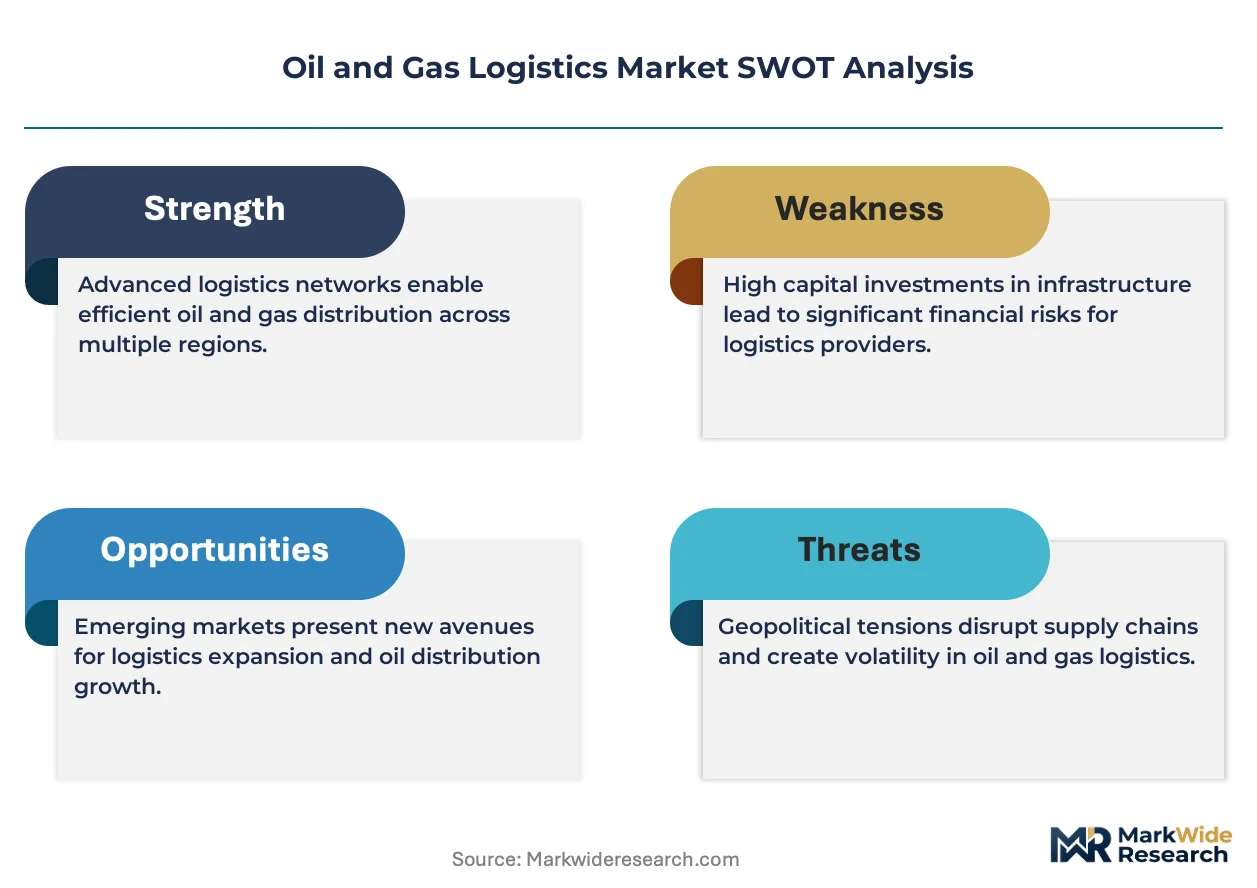
- Fuel Price Volatility:Transportation services, the largest cost component, are directly exposed to fluctuations in global diesel and bunker fuel prices, which can compress margins for logistics providers on fixed-price contracts.
- Infrastructure Gaps:In certain emerging production zones in Africa and South America, inadequate port capacity, limited road networks, and a lack of specialized warehousing create significant logistical bottlenecks and increase project costs.
- Regulatory Complexity:Navigating the patchwork of international and national regulations for transporting hazardous materials, such as those from the US Department of Transportation, creates significant compliance overhead and risk of delays.
Strategic Opportunities
- Decommissioning Services:The growing inventory of aging offshore platforms and onshore facilities presents an opportunity to develop specialized reverse logistics services for asset dismantling, removal, and environmentally compliant disposal.
- LNG Infrastructure Logistics:The global build-out of liquefied natural gas (LNG) export and import terminals requires project logistics expertise for moving large-scale modular components, cryogenic equipment, and related infrastructure.
- Sustainable Logistics Solutions:Offering logistics services that incorporate lower-emission transport options, such as biofuel-powered vessels or electric trucks for last-mile delivery, aligns with the ESG goals of major energy companies.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of personnel with specific skills, including certified heavy-lift equipment operators, experienced project logistics managers, and data scientists for supply chain optimization, hampers operational execution.
- Systems Integration Friction:Integrating modern, digital logistics platforms with the often-outdated legacy ERP and procurement systems of oil and gas clients creates technical challenges, data silos, and implementation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Logistics Market |
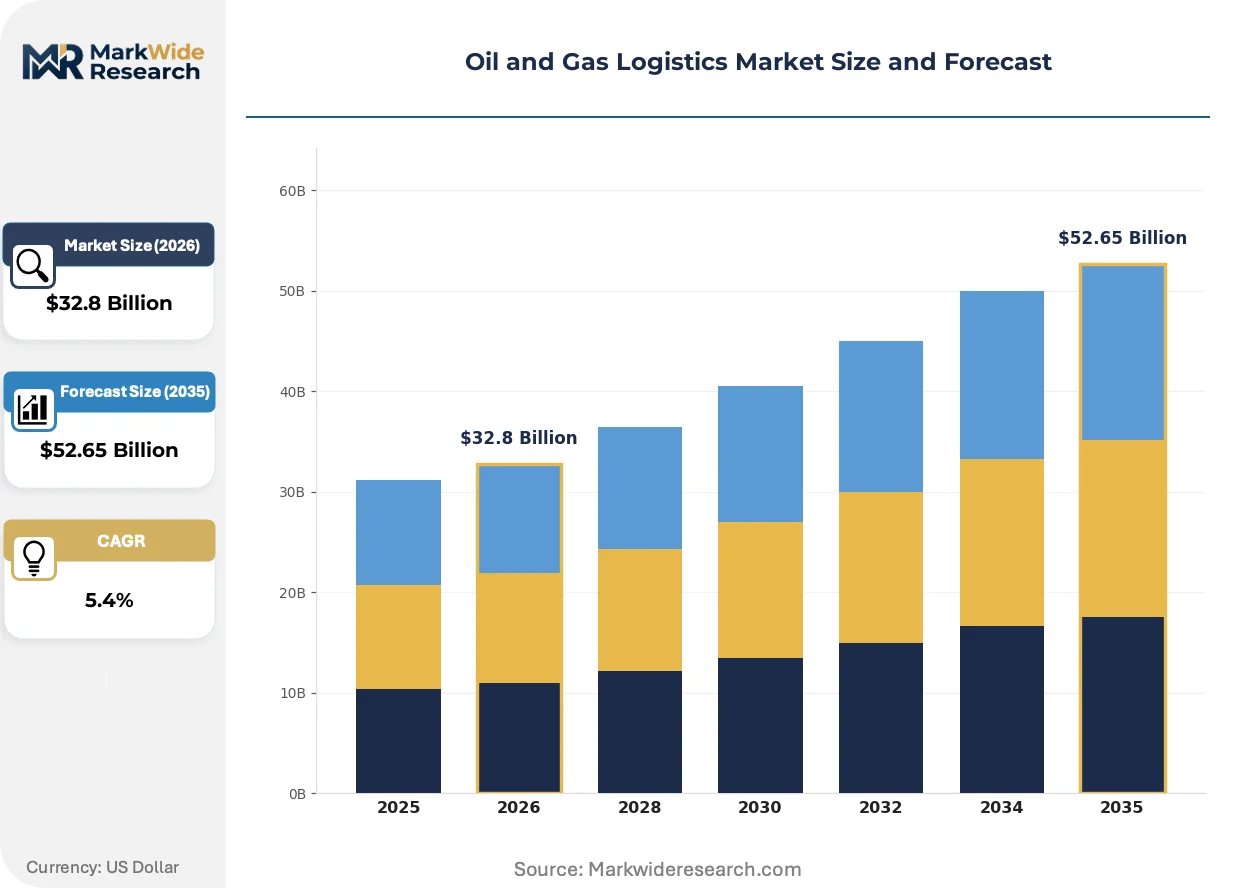
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Freight Forwarding, Customs Brokerage Application: Upstream Supply Chain, Midstream Distribution, Downstream Operations, Equipment Maintenance, Emergency Response End User: Exploration Firms, Pipeline Operators, Refinery Managers, Storage Providers, Offshore Installations Deployment Mode: Onsite Coordination, Remote Monitoring, Cloud-based Platforms, Fleet Management Systems, Mobile Integration |
| Companies Covered | CMA CGM Group, Gulf Agency Company Limited, Maersk Energy, Nippon Express, C.H. Robinson, DHL Group, DB Schenker, CEVA Logistics, Kuehne + Nagel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Logistics Market Strategic Shifts & Innovations
Digitalization and sustainability are creating a dual mandate for logistics providers. The industry is adopting technologies for greater efficiency and visibility while simultaneously responding to regulatory pressure on environmental performance, fundamentally changing operational priorities and investment roadmaps.
Digital twin technology creates dynamic, virtual models of the entire supply chain, from manufacturing facilities to remote well sites. Major exploration and production companies are adopting this for planning complex offshore projects and de-risking mobilization. This technology is virtualizing supply chain stress-testing, allowing planners to simulate disruptions like port closures or vessel delays and optimize contingency plans without physical trials.
International Maritime Organization (IMO) regulations targeting reduced carbon intensity and sulfur emissions are impacting maritime logistics. This forces vessel operators, including those with platform supply vessels and tankers, to invest in cleaner fuels like LNG or install exhaust gas cleaning systems. The offshore support vessel fleet is most affected, with charter contracts from energy majors increasingly specifying strict emissions compliance as a prerequisite.
A demand-side shift from transactional, spot-market contracting toward longer-term, integrated service agreements is redefining vendor relationships. This model displaces the use of multiple niche suppliers with a single lead logistics provider responsible for end-to-end supply chain management. This consolidation of responsibility is most visible in large-scale deepwater projects in the Gulf of Mexico and for national oil companies in the Middle East.
Oil and Gas Logistics Market Segmentation
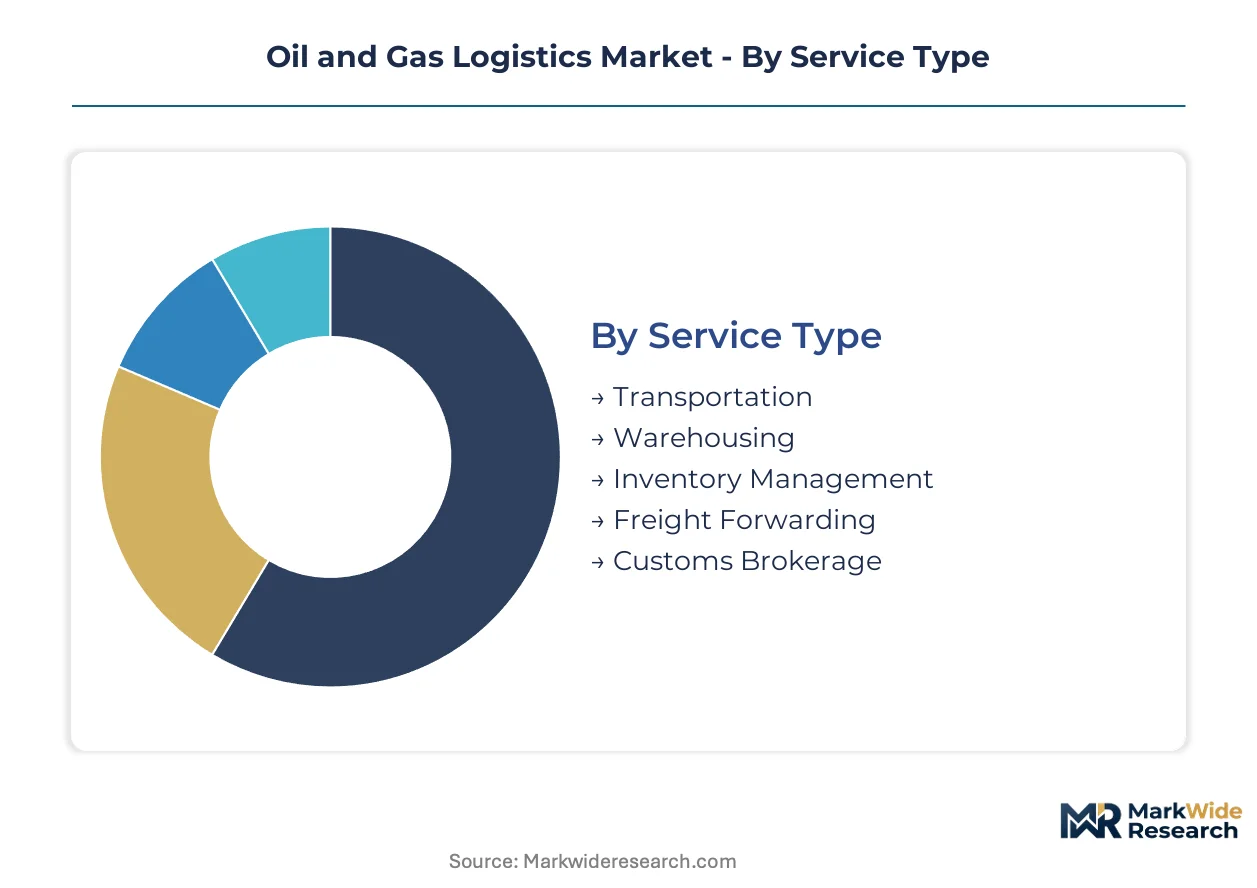
The oil and gas logistics market offers diverse services and solutions tailored to the energy sector's unique operational demands. Understanding these segments helps providers align their capabilities with specific client requirements and optimize resource allocation across the complex energy value chain.
Service Type:
The use-case spectrum for oil and gas logistics ranges from basic material movement to highly specialized compliance-driven operations.
- Transportation:This core service involves multimodal transport, including heavy-lift cargo and hazardous materials, under strict safety protocols. Demand concentrates in North American shale plays like the Permian Basin and for offshore installations requiring continuous supply.
- Freight Forwarding:These integrated solutions provide higher-margin opportunities by managing complex cross-border movements and optimizing routes. Demand from refinery managers and for large-scale deepwater projects requires comprehensive coordination.
- Warehousing:This segment provides secure storage facilities for equipment, spare parts, and materials, particularly in proximity to production zones.
- Inventory Management:Services optimize stock levels and material flow, reducing capital tied up in inventory for exploration firms.
- Customs Brokerage:This involves navigating international trade regulations and ensuring compliance for cross-border hydrocarbon shipments and equipment.
Established volume favors Transportation; emerging adoption favors Freight Forwarding.
Application:
Operational complexity dictates the specific logistics solutions required across the energy value chain.
- Upstream Supply Chain:This application demands the most sophisticated logistics, particularly for offshore installations and deepwater exploration. It involves subsea equipment, floating production systems, and continuous supply to remote well sites in regions like Brazil's pre-salt basins.
- Midstream Distribution:This segment focuses on pipelines, rail, and marine transport for crude oil and natural gas products. It requires specialized infrastructure and adherence to strict safety protocols for bulk movement between production and processing facilities.
- Downstream Operations:This involves logistics for refineries, petrochemical plants, and distribution centers, managing inbound raw materials and outbound refined products.
- Equipment Maintenance:Logistics supports the timely delivery of spare parts and specialized tools for maintaining drilling rigs and processing facilities.
- Emergency Response:This application provides rapid deployment of personnel, equipment, and supplies during critical incidents or natural disasters.
Operational complexity drives demand for Upstream Supply Chain, while routine requirements support Downstream Operations.
End User:
The operational scale and specific needs of various energy sector participants shape their logistics requirements.
- Offshore Installations:These require sophisticated project logistics for deepwater exploration and production activities. This involves specialized vessels, subsea equipment, and stringent safety standards in areas like the Gulf of Mexico.
- Refinery Managers:These professionals need precise logistics for inbound crude, outbound refined products, and compliance for cross-border hydrocarbon shipments. They often leverage customs brokerage expertise for international movements.
- Exploration Firms:These companies require logistics for geological surveys, drilling equipment, and personnel transport in remote and challenging environments.
- Pipeline Operators:These entities need consistent logistics support for infrastructure maintenance, material transport, and emergency repair services along extensive pipeline networks.
- Storage Providers:These businesses require efficient logistics for managing the intake and outflow of crude oil, natural gas, and refined products at large-scale storage facilities.
Strategic procurement by Offshore Installations influences market dynamics, alongside consistent operational needs from Pipeline Operators.
Deployment Mode:
Technology adoption influences how logistics operations are managed and monitored across the oil and gas sector.
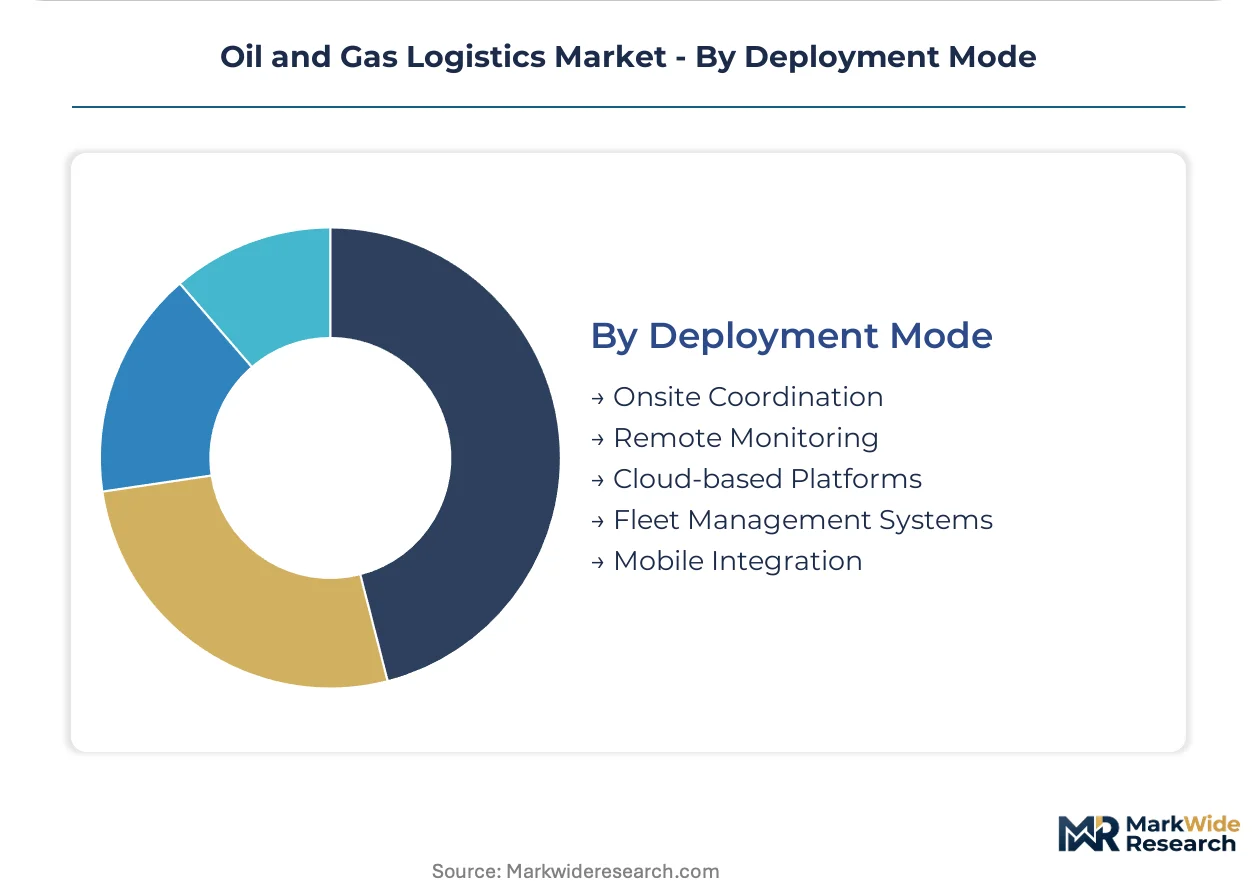
- Cloud-based Platforms:These are essential for managing supply chain visibility and efficiency across dispersed operations. They integrate data from various sources for enhanced planning and decision-making, particularly for large energy companies.
- Remote Monitoring:This utilizes IoT sensors and digital tools for real-time tracking of high-value assets and materials. This reduces downtime and improves accuracy for upstream operators in remote well sites.
- Onsite Coordination:This traditional method involves physical presence and direct management of logistics activities at specific operational sites.
- Fleet Management Systems:These digital tools optimize vehicle routing, scheduling, and maintenance for transportation assets.
- Mobile Integration:This enables real-time access to logistics data and operational controls via mobile devices for field personnel.
Digitalization accelerates demand for Cloud-based Platforms, complementing traditional Onsite Coordination approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive port infrastructure and established energy corridors underpin the global oil and gas logistics landscape. These critical assets facilitate the movement of equipment, materials, and products, enabling efficient supply chains for energy operations. Regional dynamics reflect varied production profiles, regulatory environments, and infrastructure maturity, influencing logistics demand and service specialization across different geographies.
United States
Sustained drilling activity in the Permian Basin drives demand for high-volume logistics services for proppants and water. The US Department of Transportation regulates hazardous material transport, impacting fleet compliance and operational safety. Houston, Texas, serves as a central hub for upstream and offshore logistics, coordinating extensive supply chains for the Gulf of Mexico.
Brazil
Deepwater exploration in the pre-salt basins necessitates sophisticated project logistics for subsea equipment and floating production systems. Brazil's environmental agency, IBAMA, influences offshore operational permits and environmental compliance for support vessels. Rio de Janeiro acts as a primary staging point for offshore supply, supporting complex deepwater projects.
Saudi Arabia
Large-scale crude oil production and export operations generate consistent demand for bulk material handling and tanker logistics. The Kingdom's Ministry of Energy oversees compliance for transport infrastructure and energy sector operations. Industrial cities like Jubail and Ras Tanura are critical nodes for refining and export logistics, managing vast volumes of hydrocarbons.
Norway
North Sea offshore installations require specialized logistics for subsea infrastructure and arctic-grade equipment. The Norwegian Environment Agency enforces strict emissions and waste management regulations for maritime operations. Stavanger remains a vital center for offshore supply vessel operations, supporting platforms across the Norwegian Continental Shelf.
China
Growing energy import needs and LNG infrastructure development create demand for large-scale project logistics and specialized vessel charters. China's Ministry of Ecology and Environment (MEE) influences port emissions standards and green logistics initiatives. Major port cities like Shanghai and Tianjin are crucial for handling energy imports and facilitating regional distribution.
Oil and Gas Logistics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing niche services within the oil and gas logistics market. The market structure exhibits a tiered approach, with global players offering end-to-end solutions and regional providers specializing in specific geographic or service niches. Strategic archetypes include large-scale freight forwarders, specialized project logistics firms, and technology-driven supply chain optimizers. Geographic expansion and strategic partnerships remain dominant competitive moves, enabling broader service reach and integrated offerings.
Among global integrated logistics providers, Kuehne + Nagel and DHL Group exemplify comprehensive service portfolios spanning freight forwarding, customs brokerage, and project logistics. DB Schenker also occupies a significant position, leveraging its extensive network for multimodal transport and warehousing solutions. These companies anchor the high-value segment by offering end-to-end supply chain management for complex energy projects. Their capabilities address the intricate demands of upstream, midstream, and downstream operations, from remote well sites to refinery distribution.
| Leading Market Players |
|---|
| CMA CGM Group |
| Gulf Agency Company Limited |
| Maersk Energy |
| Nippon Express |
| C.H. Robinson |
| DHL Group |
| DB Schenker |
| CEVA Logistics |
| Kuehne + Nagel |
| Others |
Cost & Logistics Intelligence
Fuel price volatility in global diesel and bunker markets directly influences pricing tier spreads for transportation services and shapes the strategic choices within the oil and gas logistics supply chain.
Pricing Analysis
Volume-based contracts dominate pricing for oil and gas logistics, reflecting the scale of operations in shale plays and deepwater projects. Price differentiation stems from specialized equipment handling and geographic delivery costs, particularly for remote offshore installations. Margins are tightening due to diesel and bunker fuel price fluctuations, impacting providers on fixed-price agreements. Large energy companies procuring complex project logistics demonstrate lower price sensitivity compared to regional exploration firms seeking basic transport services.
Supply Chain Analysis
Export control regimes, particularly for advanced subsea equipment, limit the flow of specialized technology into certain regions. Geographic supply concentration for critical components rests in countries like the United States for proppants, China for LNG infrastructure modules, and specialized vessel manufacturing in South Korea. Single-source vulnerability for heavy-lift shipping represents a structural risk. Integrated end-to-end logistics solutions form the dominant distribution model across the energy value chain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a substitution defense, as traditional logistics providers must navigate the threat of integrated energy companies insourcing specialized services and digital platform disintermediation.
For Market Incumbents: Harden core competencies in hazardous materials transport and customs compliance to counter digital platform disintermediation. Invest in advanced digital fleet management systems and specialized certifications for complex project logistics. Expand service offerings for decommissioning to leverage existing infrastructure and client relationships, addressing the aging asset inventory.
For New Entrants and Emerging Players: Underpenetration in emerging production zones in Africa and South America offers significant market entry opportunities for specialized logistics providers. Target sustainable logistics solutions, such as biofuel-powered vessels, to align with the ESG goals of major energy companies. A go-to-market angle focused on integrated, cloud-based platforms for real-time visibility will attract upstream operators.
For Investors and Strategic Acquirers: IMO 2020 regulations reshaping maritime emissions compliance reshapes the acquisition landscape, favoring firms with green fleet technologies. Long-term viability in this sector hinges on acquiring specialized project logistics firms with strong digital integration capabilities and expertise in complex cross-border movements. A signal to watch is the rate of adoption of digital twin technology by major exploration and production companies, indicating future demand for advanced logistics planning.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Fleet Management System Implementation | Enhances real-time tracking and operational efficiency for upstream operators and offshore installations. |
| Specialized Decommissioning Service Development | Addresses the growing inventory of aging offshore platforms, creating new reverse logistics revenue streams. |
| LNG Infrastructure Logistics Expansion | Supports the global build-out of liquefied natural gas terminals, requiring expertise in large-scale modular transport. |
| Cross-border Customs Compliance Enhancement | Streamlines hydrocarbon shipments for refinery managers, reducing delays and regulatory risks. |
| Sustainable Transport Option Integration | Aligns logistics services with the ESG goals of major energy companies, impacting charter contracts and fleet modernization. |
Research Approach
Operator-level perspectives from project logistics managers, upstream operators, refinery managers, and customs brokers anchored the qualitative base for this analysis. This approach combined in-depth primary interviews with rigorous secondary validation using US EPA reports, IMO regulations, energy company annual reports, and trade association publications. Bottom-up and top-down triangulation ensured data consistency and comprehensive market understanding.
Scenario-bracketing framed the analytical framework, projecting market trajectories across the analysis window under various economic and regulatory conditions. This model segmented the market by service type, application, end-user, deployment mode, and regional regulatory environment. Compound Annual Growth Rates were derived from historical data trends and projected demand, integrating inputs like crude oil price trends and the global LNG project pipeline.
Practitioners should monitor geopolitical conflicts and major technological disruptions in extraction for early signals of market shifts. Forecasts reflect assumptions documented at the time of publication. Material shifts in new international trade agreements or environmental policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
South America Oil and Gas Storage Tank Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Frac Stack Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Republic of Congo Oil and Gas Market