
 Tetrahedron Carton Market | 2026-2036
Tetrahedron Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Tetrahedron Carton Market Analytics
Foodservice operators and institutional buyers are bifurcating from traditional retail-centric demand as on-the-go consumption reshapes carton procurement. Tetra Pak International S.A. leverages its aseptic technology leadership to dominate high-volume dairy contracts across Southeast Asia. SIG Group AG competes through regional manufacturing scale in Europe and Latin America. Huhtamaki Oyj differentiates via flexible coating technologies that extend barrier performance for ambient distribution.
A tetrahedron carton is a geometrically stable, three-sided pyramid package formed from laminated paperboard with aluminum oxide or ethylene vinyl alcohol barrier layers, sealed through ultrasonic or heat-seal bonding to enable aseptic filling without refrigeration. The structure maximizes cube efficiency during palletization while minimizing material use per unit volume. High Barrier Tetrahedron leads value capture due to extended shelf-life requirements for ambient dairy and nutritional beverages. Biodegradable Tetrahedron records the fastest trajectory as brand owners face Scope 3 emissions disclosure obligations. Composite material configurations anchor margin pools where polymer-foil-paperboard lamination demands precision coextrusion capability.
The EU Packaging and Packaging Waste Regulation and FDA food contact substance notifications shape material migration limits and recyclability claims across export markets. China's GB standards for composite packaging and the EU Green Deal circular economy action plan are forcing substrate redesign toward monomaterial or fiber-dominant constructions. Stakeholders must monitor how extended producer responsibility fee structures alter total cost of ownership for multilayer versus simplified barrier designs.
Market Dynamics
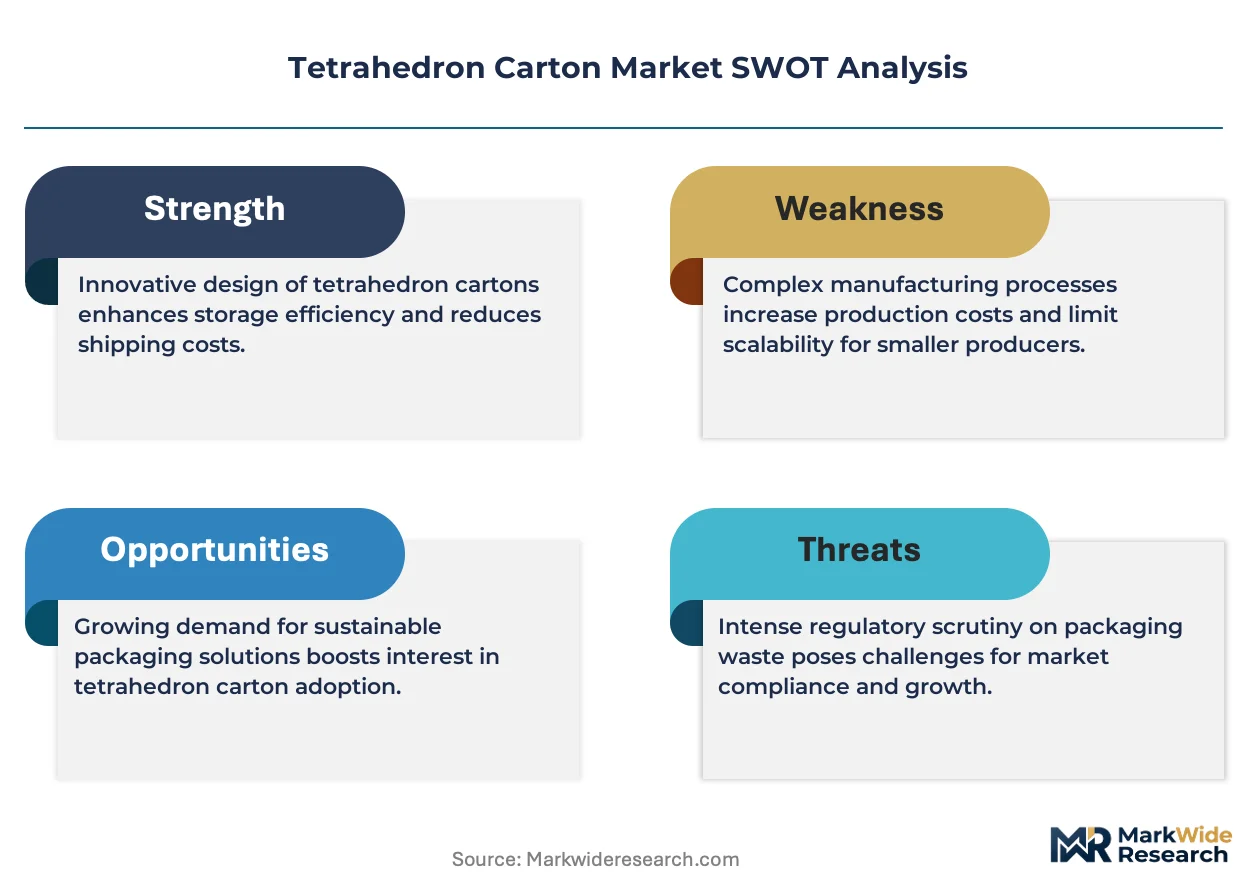
The EU Packaging and Packaging Waste Regulation is forcing substrate redesign toward monomaterial constructions, compressing margin pools for multilayer barrier specialists while rewarding fiber-dominant innovators with simplified recycling pathways.
Growth Catalysts
- Aseptic filling infrastructure expansion:Dairy and plant-based beverage producers in Brazil and China are scaling automated filling lines that require geometrically stable tetrahedron formats for ambient distribution networks.
- Extended producer responsibility frameworks:The EU Green Deal circular economy action plan mandates higher material recovery targets, creating procurement pull for biodegradable and fiber-dominant carton designs.
- Aluminum oxide barrier migration:High-barrier coating technologies are replacing conventional foil laminations in nutritional beverage packaging to meet FDA food contact substance notification requirements.
Market Restraints
- Pulp fiber cost volatility:Kraft linerboard and bleached hardwood pulp prices fluctuate with Nordic and Brazilian supply disruptions, squeezing converter margins on fixed-price annual contracts.
- Ethylene vinyl alcohol supply concentration:EVOH resin production clusters in Japan and South Korea create input vulnerability for high-barrier laminate producers outside Northeast Asia.
- Multilayer delamination limits:Polymer-foil-paperboard composites face mechanical recycling rejection at European sorting facilities due to incompatible melting points.
Strategic Opportunities
- Underpenetrated ambient nutrition in Southeast Asia:Indonesia and Vietnam lack sufficient aseptic filling capacity for pediatric and elderly nutritional beverages, creating white space for carton-plus-filler system bundles.
- Ultrasonic bonding convergence with biodegradable films:Heat-sensitive bio-based sealant layers pair with ultrasonic sealing equipment to enable compostable certification without aluminum oxide.
- Foodservice channel bypass models:Institutional buyers in German healthcare and Brazilian education sectors are contracting directly with converters, disintermediating traditional retail-packaging distributors.
Industry Challenges
- Precision coextrusion talent scarcity:Composite barrier engineers capable of managing polymer-foil-paperboard lamination tolerances command premium compensation in European and Chinese labor markets.
- GB standards compliance timeline compression:China's national standards for composite packaging migration testing require 18-month certification cycles that delay product launches for export-focused converters.
- Legacy heat-seal equipment retrofit costs:Converters with sunk capital in thermal bonding lines face capex burdens to accommodate ultrasonic or laser sealing for next-generation biodegradable structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetrahedron Carton Market |
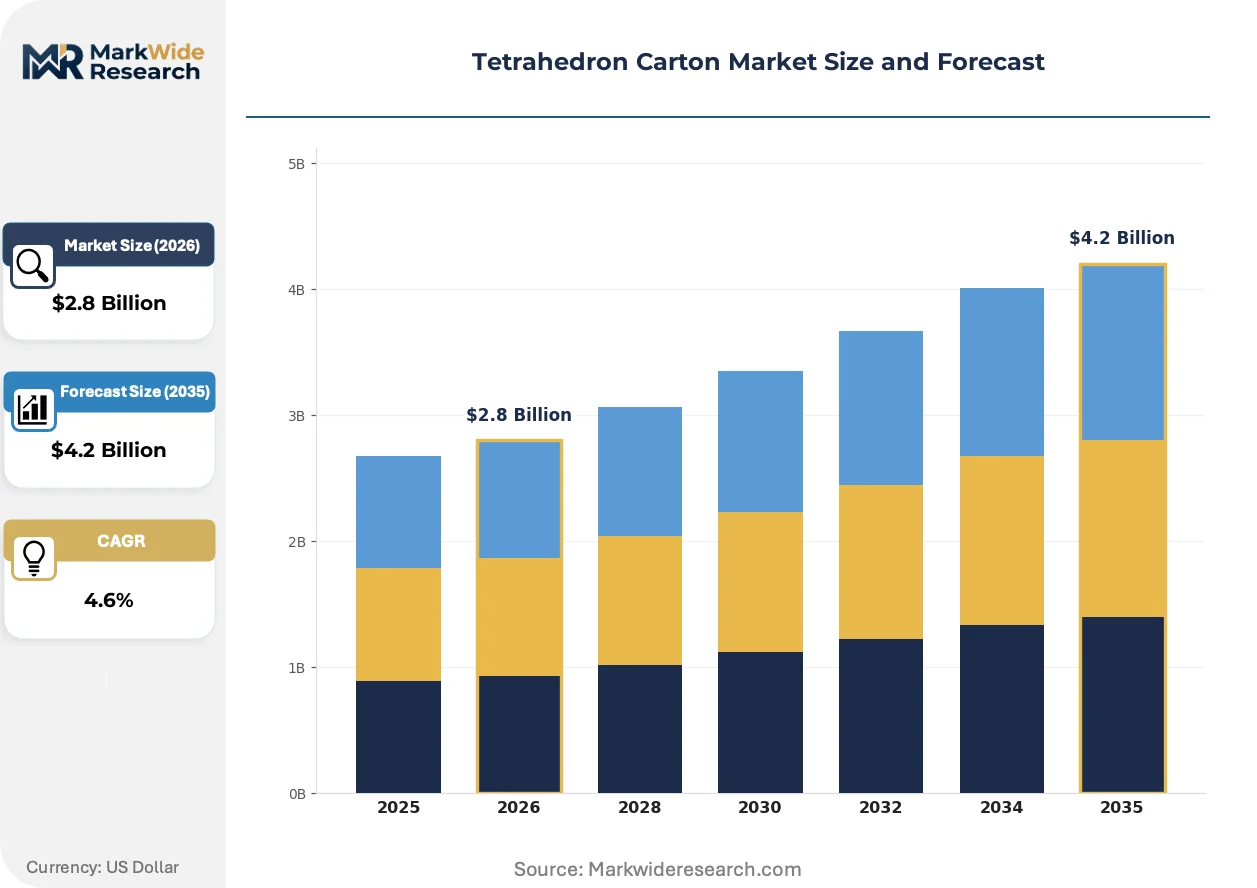
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tetrahedron, Custom Tetrahedron, Biodegradable Tetrahedron, High Barrier Tetrahedron Material: Cardboard, Plastic, Composite, Recyclable Material End User: Food Industry, Beverage Industry, Personal Care, Household Products Distribution Channel: Retail, Online, Wholesalers, Direct Sales |
| Companies Covered | Tetra Pak International S.A., Elopak AS, SIG Group AG, Stora Enso Oyj, ProAmpac Intermediate, Inc., Mondi Group, Huhtamaki Oyj, Asepto, Lamipak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetrahedron Carton Market Evolving Landscape
Barrier material science and filling technology are converging to redefine shelf-life extension capabilities. Procurement patterns are fragmenting as direct institutional contracting bypasses traditional retail channels. Regulatory pressure on recyclability claims is accelerating substrate simplification.
Ultrasonic sealing technology is decomposing the dominance of heat-seal bonding in aseptic carton manufacturing. Dairy processors in Germany and nutritional beverage packagers in China are retrofitting filling lines at 15-20% annual rates to capture energy savings and enable bio-based sealant compatibility. This shift is decomposing the technical moat of incumbents with captive heat-seal expertise while opening procurement to ultrasonic equipment specialists.
The EU Packaging and Packaging Waste Regulation tightens recyclability claim verification and mandates minimum recycled content thresholds. Industrial consequence falls heaviest on multilayer laminate producers whose polymer-foil-paperboard constructions fail fiber-dominant sorting criteria. High-barrier dairy cartons destined for German and French retail are reformulating toward aluminum oxide coatings or ethylene vinyl alcohol monolayers to maintain performance while satisfying ECHA substance restriction protocols.
Direct contracting between institutional foodservice operators and carton converters is fragmenting traditional distributor-mediated procurement. Hospital systems in São Paulo and school districts in Shanghai are negotiating volume commitments with regional manufacturers for custom-printed, smaller-batch tetrahedron formats. This pattern concentrates in Brazil and China where aseptic filling infrastructure scale permits flexible production runs without minimum order penalties that retail channels impose.
Tetrahedron Carton Market Segmentation
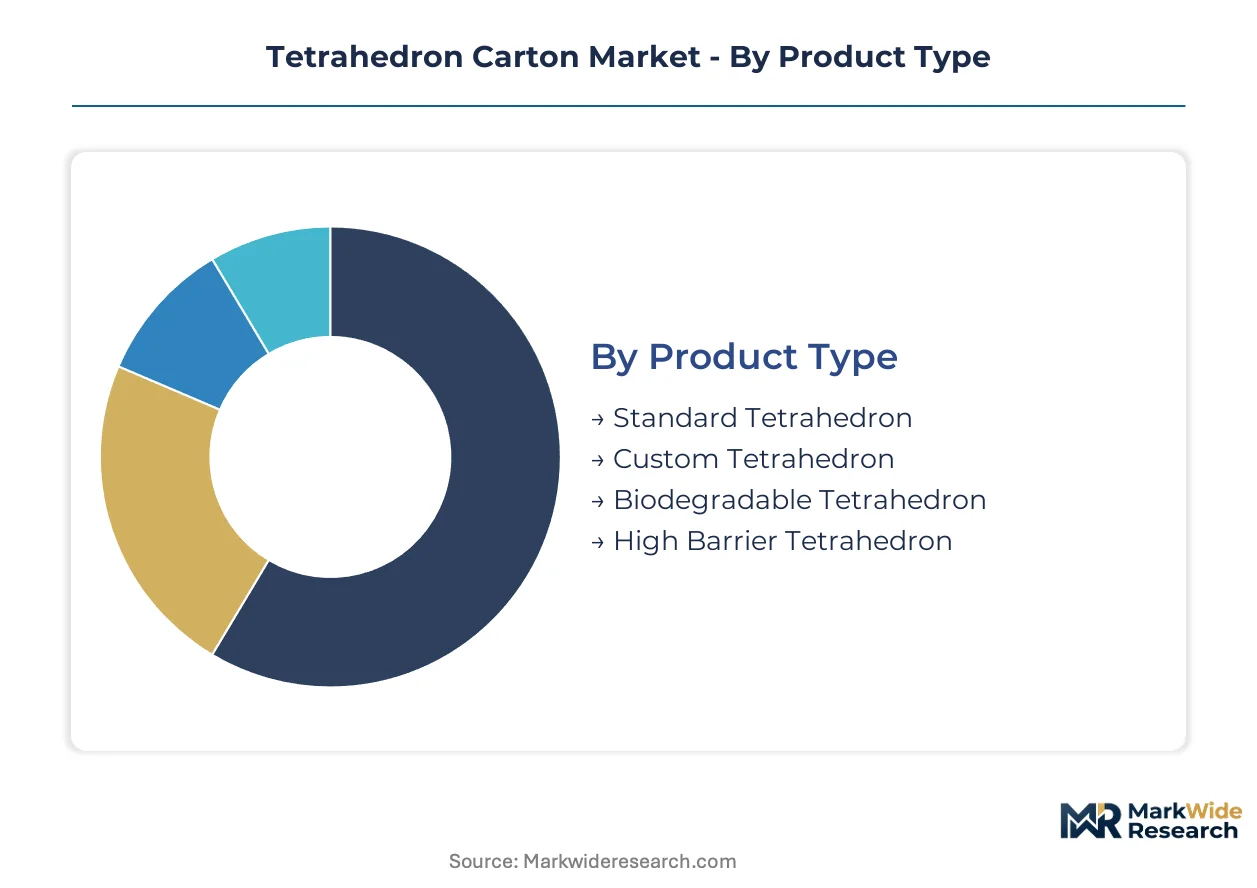
Channel fragmentation across retail, institutional, and digital routes demands format-specific barrier properties and minimum order flexibility. Procurement bifurcation between high-volume dairy contracts and small-batch foodservice runs shapes converter capacity allocation and margin structures.
Product Type:
Retail dairy and ambient beverage channels favor standardized formats for filling-line compatibility, while direct institutional procurement pulls toward customizable geometries with shorter lead times.
- High Barrier Tetrahedron:Aluminum oxide or ethylene vinyl alcohol coatings replace foil laminations to achieve oxygen transmission rates below 0.1 cc/m²/day for nutritional beverages distributed through ambient retail networks. German and Chinese dairy processors specify this format for extended shelf-life milk and plant-based drinks requiring six-month distribution windows without refrigeration.
- Biodegradable Tetrahedron:Bio-based sealant layers paired with ultrasonic bonding equipment enable compostable certification for institutional foodservice contracts in São Paulo hospital systems and Shanghai school districts facing Scope 3 emissions disclosure obligations.
- Standard Tetrahedron:Conventional polymer-foil-paperboard lamination serves mass-market dairy through retail-centric distribution at lowest unit cost.
- Custom Tetrahedron:Variable geometry and print configurations accommodate direct-contracting institutional buyers requiring smaller batch sizes and brand differentiation.
High Barrier Tetrahedron dominates installed base. Biodegradable Tetrahedron is where expansion concentrates.
Material:
Cost tiers stratify sharply between commodity fiberboard and precision-engineered composite barriers requiring coextrusion capability.
- Composite:Polymer-foil-paperboard multilayers deliver maximum shelf-life extension for ambient dairy but face mechanical recycling rejection at European sorting facilities due to incompatible melting points.
- Recyclable Material:Monomaterial or fiber-dominant constructions satisfy EU Packaging and Packaging Waste Regulation verification requirements and ECHA substance restriction protocols for German and French retail channels.
- Cardboard:Bleached hardwood pulp substrates anchor economy-tier beverage packaging with basic barrier requirements.
- Plastic:Polyethylene and polypropylene dominant layers serve short-shelf-life applications with simplified recycling pathways.
Composite materials command premium pricing. Recyclable Material configurations are climbing the fastest as regulatory pressure intensifies.
End User:
Volume concentration in beverage processing contrasts with margin opportunity in personal care and household segments requiring specialized barrier chemistries.
- Beverage Industry:Aseptic filling infrastructure scale in Brazil and China drives procurement of geometrically stable formats for ambient distribution networks serving retail and institutional channels.
- Food Industry:Ready-to-eat meal and sauce applications demand retort-stable laminates with thermal resistance beyond standard dairy specifications.
- Personal Care:Cosmetic and pharmaceutical liquid formulations require FDA food contact substance notification compliance and migration-tested barrier layers.
- Household Products:Cleaning and chemical applications utilize modified atmosphere packaging with corrosion-resistant interior coatings.
Beverage Industry commands volume concentration. Personal Care represents the steepest expansion trajectory for specialized barrier engineering.
Distribution Channel:
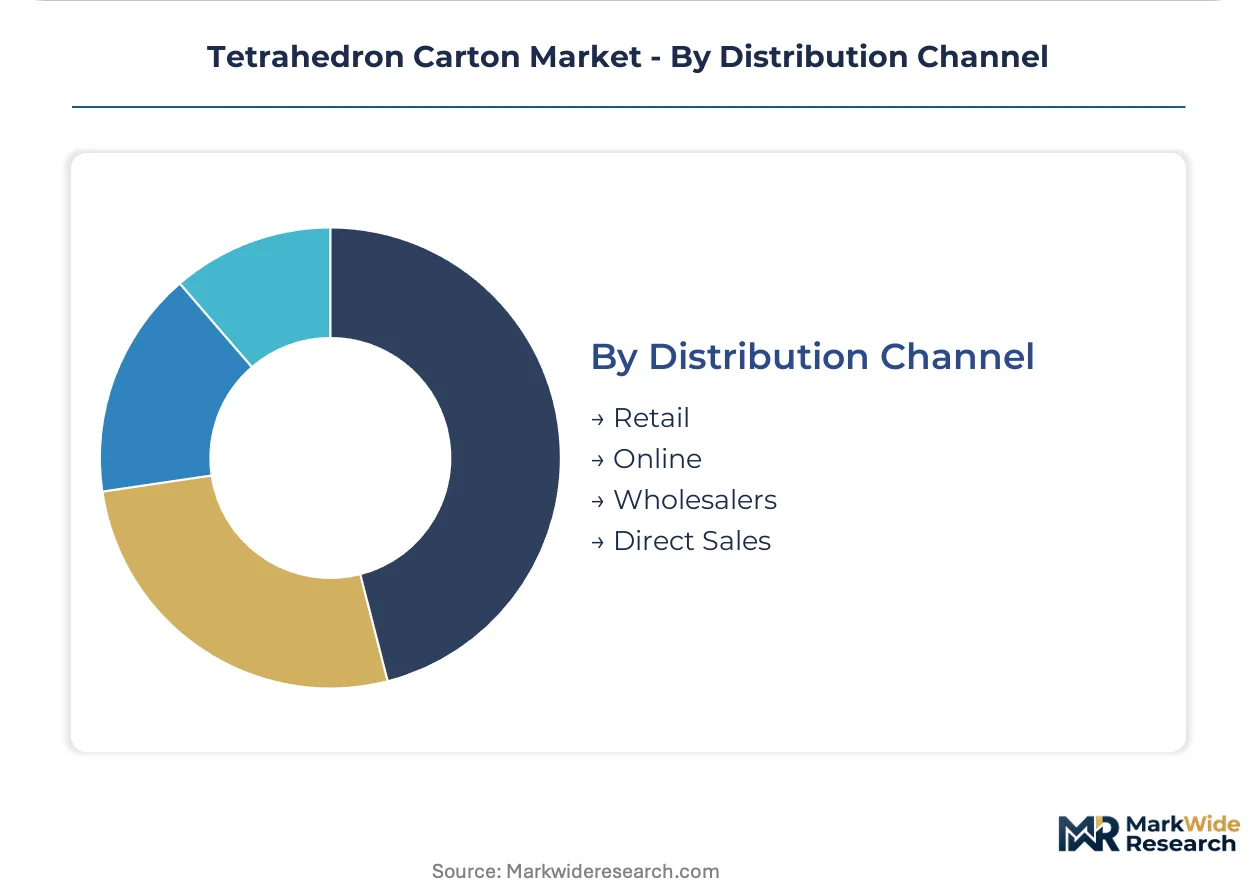
Channel selection determines minimum efficient scale, print customization requirements, and inventory holding patterns across converter operations.
- Direct Sales:Institutional foodservice operators in German healthcare and Brazilian education sectors negotiate volume commitments bypassing distributor markups for custom-printed, smaller-batch formats.
- Retail:Mass-market dairy and beverage distribution requires standardized geometries compatible with automated filling lines and palletization efficiency.
- Wholesalers:Intermediate inventory pooling serves regional beverage processors lacking capital for direct converter relationships.
- Online:Digital procurement platforms aggregate fragmented foodservice demand for trial quantities and rapid format testing.
Retail anchors volume throughput. Direct Sales is where margin expansion concentrates through disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered carton substrates to dairy processors across Southeast Asia, while China ships filling-line equipment to Brazil's expanding aseptic beverage infrastructure.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia negotiate direct contracts for biodegradable tetrahedron formats to meet Scope 3 disclosure obligations. The EU Packaging and Packaging Waste Regulation mandates fiber-dominant constructions for retail channels. Converter clusters around Hamburg and Frankfurt retrofit ultrasonic bonding lines to accommodate bio-based sealants.
China
Dairy processors in Shandong and Hebei provinces scale automated filling capacity for ambient plant-based beverages. GB standards for composite packaging migration testing compress certification timelines for export-focused manufacturers. Yangtze River Delta converters develop aluminum oxide barrier coatings to replace foil laminations in nutritional beverage packaging.
Brazil
São Paulo hospital systems and school districts contract directly with regional manufacturers for custom-printed, smaller-batch formats. ANVISA regulates food contact substance notifications for imported barrier materials. Converter capacity concentrates in São Paulo state where aseptic filling infrastructure permits flexible production runs without retail-channel minimum order penalties.
United States
FDA food contact substance notifications shape material migration limits for high-barrier nutritional beverage cartons distributed through ambient retail networks. Dairy processors in Wisconsin and California specify extended shelf-life formats for six-month distribution windows. Converter engineering talent clusters around Chicago and Minneapolis for precision coextrusion of polymer-foil-paperboard laminations.
Indonesia
Pediatric and elderly nutritional beverage demand outpaces domestic aseptic filling capacity, creating procurement white space for carton-plus-filler system bundles. The national standards body enforces composite packaging testing protocols for imported substrates. Java-based beverage processors expand ambient distribution networks to reach underpenetrated eastern archipelago markets.
Tetrahedron Carton Market Competitive Landscape
Player mix skews toward integrated packaging technology conglomerates with captive aseptic filling system offerings. Market structure concentrates around three to five vertically capable specialists commanding high-volume dairy contracts, while regional converters fragment across foodservice and institutional niches. Strategic archetypes include technology-integrated multinationals, regional manufacturing specialists, and flexible coating innovators. Dominant competitive moves encompass ultrasonic sealing equipment licensing and direct institutional channel bypass.
Within the technology-integrated tier, Tetra Pak International S.A. and SIG Group AG exemplify the multinational conglomerate archetype with bundled carton-filler system offerings. Huhtamaki Oyj occupies a position among flexible barrier specialists. Regional manufacturing scale concentrates with Elopak AS and Stora Enso Oyj. Mondi Group and ProAmpac Intermediate, Inc. represent diversified packaging portfolios with carton segment participation. Lamipak and Asepto sit within the emerging specialist tier focused on aseptic format expansion.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| Elopak AS |
| SIG Group AG |
| Stora Enso Oyj |
| ProAmpac Intermediate, Inc. |
| Mondi Group |
| Huhtamaki Oyj |
| Asepto |
| Lamipak |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Brazilian dairy processors and Nordic pulp suppliers lock in bleached hardwood fiber access while stabilizing input cost visibility against Nordic supply disruptions. These contracts compress margin volatility for converters serving fixed-price annual beverage contracts in Germany and China.
Pricing Analysis
Heat-seal versus ultrasonic bonding equipment generations command divergent pricing premiums, with legacy thermal lines trading at depreciation-heavy rates while next-gen ultrasonic systems capture certification-grade premiums for biodegradable formats. Three-tier pricing structure across premium, standard, and economy levels separates aluminum oxide barrier cartons from conventional foil laminations from basic polymer-paperboard constructions. Cost compression in economy-tier cardboard substrates is intensifying because Brazilian pulp price volatility transmits directly through fixed annual contracts. Foodservice institutional buyers exhibit highest price sensitivity due to direct-contracting disintermediation, while pharmaceutical nutritional beverage processors accept premium positioning for FDA-compliant migration-tested barriers.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for EVOH resin shipments from Japan and South Korea to German and Brazilian laminate producers. Manufacturing gravity centers on China, Germany, and Brazil, where aseptic filling infrastructure scale permits flexible production runs. Raw material dependencies draw from Nordic bleached hardwood pulp, Japanese EVOH resin, and aluminum oxide coating precursors. Single-source vulnerability concentrates in EVOH supply given production clustering in Northeast Asia. Distribution runs through direct institutional contracting channels in São Paulo hospital systems and Shanghai school districts alongside traditional retail-centric wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical pulp fiber cost volatility as Nordic supply disruptions ease and Brazilian hardwood inventories rebuild.
For Market Incumbents: Fortify barrier technology moats through captive aluminum oxide coating capacity in Germany and China, insulating against emerging ultrasonic bonding specialists. Invest in precision coextrusion talent retention as composite laminate engineers command premium compensation in Hamburg and Shanghai labor markets. Prioritize direct institutional channel control in Brazilian education and German healthcare sectors where disintermediation threatens distributor-mediated revenue pools. For New Entrants and Emerging Players: Anchor in Indonesia's underpenetrated pediatric and elderly nutritional beverage segment where domestic aseptic filling capacity lags demand growth. Target carton-plus-filler system bundles for Java-based processors expanding ambient distribution to eastern archipelago markets. Pursue ultrasonic equipment licensing partnerships with Yangtze River Delta converters seeking bio-based sealant compatibility without legacy heat-seal retrofit burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated carton-filler system bundlers with captive aseptic technology platforms. Long-term viability favors specialists with monomaterial substrate roadmaps aligned to EU Packaging and Packaging Waste Regulation fiber-dominant mandates. Monitor GB standards compliance timeline compression as an inflection signal for export-focused converter margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Bonding Equipment Licensing | Enables bio-based sealant compatibility for São Paulo hospital biodegradable contracts. |
| Backward Integration into Aluminum Oxide Coating | Secures barrier material supply for German dairy processors facing ECHA substance restrictions. |
| Direct Institutional Channel Expansion | Bypasses distributor markups in Brazilian education and German healthcare procurement. |
| Precision Coextrusion Talent Acquisition | Addresses scarcity of composite laminate engineers in European and Chinese labor markets. |
| Monomaterial Substrate Redesign | Satisfies EU Green Deal circular economy mandates for fiber-dominant recycling pathways. |
Research Methodology
Cross-validation between converter production data and dairy processor filling-line deployment records anchors the qualitative findings on aseptic infrastructure expansion. Primary interviews with plant managers at laminate manufacturing facilities, procurement leads at Brazilian and Chinese dairy processors, distribution channel partners in German foodservice, and technical R&D directors at barrier coating specialists combined with secondary validation from customs trade data, EU Packaging and Packaging Waste Regulation filings, SEC 10-K disclosures from packaging conglomerates, and GB standards certification databases. Bottom-up capacity utilization estimates and top-down beverage industry packaging demand projections were triangulated.
Sensitivity analysis around pulp fiber price volatility and EVOH resin supply disruption scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include barrier technology tier, material composition, end-use industry, distribution channel structure, and regional regulatory cluster. CAGRs were derived from installed base growth rates for aseptic filling lines and per-line carton consumption coefficients. Forecast inputs incorporated EU Green Deal circular economy action plan implementation timelines and FDA food contact substance notification approval patterns.
Material uncertainties — pulp fiber cost spikes, EVOH supply chain disruptions, GB standards certification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Round Corrugated Box Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Carton Form Fill Seal Machine Market
Cartons
Interlocking Boxes Market
Cartons
Folding Cartons Market
Cartons
MET-PET Cartons Market
Cartons
Carton Sealer Market
Cartons
Cartoning Machines Market
Cartons
Liquid Packaging Cartons Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Twist Opening Cartons Market
Cartons
Shaped Liquid Cartons Market
Cartons
End Load Cartoning Machine Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Japan Corrugated Boxes Market
Cartons
Metallized PET Cartons Market