
 Braille Cartons Packaging Market | 2026-2036
Braille Cartons Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Braille Cartons Packaging Market Outlook
Pharmaceutical packaging is expanding as the dominant end-use vertical for Braille Cartons Packaging, displacing traditional cosmetics applications in volume priority. Smurfit Westrock leverages its European manufacturing footprint to anchor supply for regulated pharma clients. Mondi Group specializes in FSC-certified paperboard substrates that meet dual sustainability and accessibility requirements. ProAmpac competes through R&D intensity in high-contrast embossing technologies for low-vision compliance.
Braille Cartons Packaging denotes carton structures incorporating raised-dot tactile systems, typically produced through rotary embossing or thermoforming processes on paperboard substrates between 250-400 gsm, enabling visually impaired consumers to identify product information without assistance. Folding cartons dominate unit volume due to their compatibility with automated pharmaceutical filling lines, while rigid boxes command margin pools in premium cosmetic and oncology drug segments. Paperboard materials lead the material split, though cardboard variants are gaining share in cold-chain pharmaceutical distribution where structural rigidity protects temperature-sensitive inserts.
The EU Accessibility Act and FDA labeling requirements shape product specifications across the two largest regulated corridors, with EMA pharmaceutical packaging guidelines explicitly mandating Braille inclusion for prescription medicines in Europe. ISO 9001 and GMP certification frameworks create tiered market access barriers that favor established converters over regional entrants. Stakeholders must monitor evolving national transpositions of the European Accessibility Act and anticipate whether the FDA will extend tactile labeling beyond current voluntary guidance into enforceable rulemaking.
Market Dynamics
The EU Accessibility Act's mandatory tactile labeling requirements for pharmaceutical packaging is compressing conversion timelines and forcing capital redeployment toward certified embossing capacity across European converters.
Growth Catalysts
- EMA Pharmaceutical Packaging Guidelines:Braille inclusion mandates for prescription medicines across EU member states create legally binding demand for compliant carton structures.
- Rotary Embossing Process Advancements:High-speed rotary embossing lines now achieve 400+ impressions per minute, enabling cost parity with standard pharmaceutical cartons at volume.
- Oncology Drug Segment Concentration:Germany, France, and Italy host the densest clusters of oncology biologics manufacturing, generating concentrated demand for premium rigid Braille cartons with cold-chain compatibility.
Market Restraints
- Specialized Tooling Capital Intensity:Custom rotary embossing dies for pharmaceutical-grade Braille require six-figure capital outlays with 12-18 month amortization cycles.
- FSC-Certified Paperboard Supply Concentration:Nordic pulp mills control approximately 70% of European pharmaceutical-grade FSC paperboard supply, creating input cost volatility exposure.
- Thermoforming Process Limitations:Thermoformed Braille dots exhibit 15-20% higher failure rates in automated vision inspection systems compared to embossed alternatives.
Strategic Opportunities
- Central and Eastern European Manufacturing:Poland and Czech Republic offer underexploited production bases with lower labor costs and proximity to expanding pharma corridors.
- Cosmetics Premium Segment Pivot:Luxury fragrance and skincare brands are voluntarily adopting Braille cartons for accessibility positioning and retail differentiation.
- EU Green Deal Packaging Requirements:The EU's sustainable packaging mandates are accelerating demand for recyclable paperboard substrates that simultaneously satisfy accessibility and circularity criteria.
Industry Challenges
- Braille Certification Specialist Shortage:Qualified tactile readability auditors capable of validating pharmaceutical-grade embossing depth and dot spacing remain scarce across converter networks.
- ISO 9001 and GMP Dual Certification Timelines:New entrants face 18-24 month approval windows to achieve the quality management certifications required by major pharmaceutical contract manufacturers.
- Legacy Carton Line Retrofit Complexity:Existing folding carton equipment requires substantial mechanical modification to accommodate precision embossing modules without compromising line speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Braille Cartons Packaging Market |
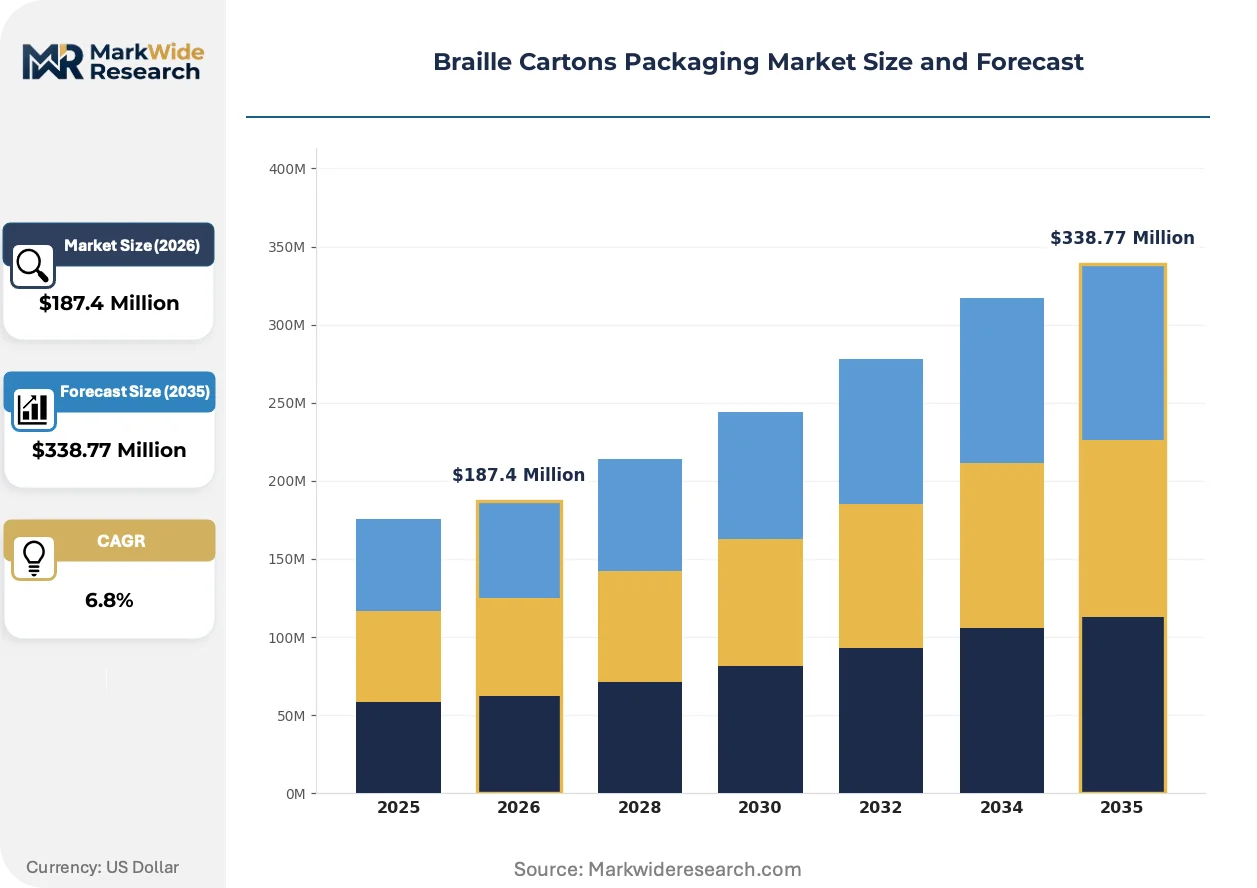
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Cartons, Rigid Boxes, Corrugated Boxes, Sleeves Material: Cardboard, Paperboard, Plastic, Wood End User: Pharmaceuticals, Food & Beverage, Cosmetics, Electronics Certification: ISO 9001, GMP, FSC Certified, FDA Approved |
| Companies Covered | Sealed Air, ProAmpac, CCL Healthcare, Smurfit Westrock, Mondi Group, Amcor, Tetra Pak, International Paper, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Braille Cartons Packaging Market Strategic Shifts
Digital embossing control systems and sustainable substrate engineering are converging to reshape production economics and regulatory compliance pathways for tactile packaging.
Laser-assisted embossing depth control is integrating real-time feedback loops that maintain dot height tolerances within 0.05mm across high-speed production runs. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting this technology to eliminate batch rejection risks from readability audit failures. The integration of closed-loop quality systems is compressing the cost gap between standard and Braille-capable carton lines.
The European Accessibility Act's national transposition deadlines are forcing alignment between packaging accessibility and existing pharmaceutical serialization requirements under the EU Falsified Medicines Directive. Converters must now engineer cartons that accommodate both Braille embossing and 2D data matrix codes without structural compromise. Oncology and biologics packaging in France and Italy faces the tightest compliance windows as national regulators accelerate enforcement.
Pharmaceutical procurement departments are consolidating supplier panels to favor converters offering integrated accessibility compliance, sustainability certification, and serialization capability. This triple-requirement screening is displacing single-service carton vendors from preferred supplier lists. The consolidation pressure is most visible in the Benelux region, where large pharma headquarters procurement functions are driving vendor rationalization programs.
Braille Cartons Packaging Market Segmentation
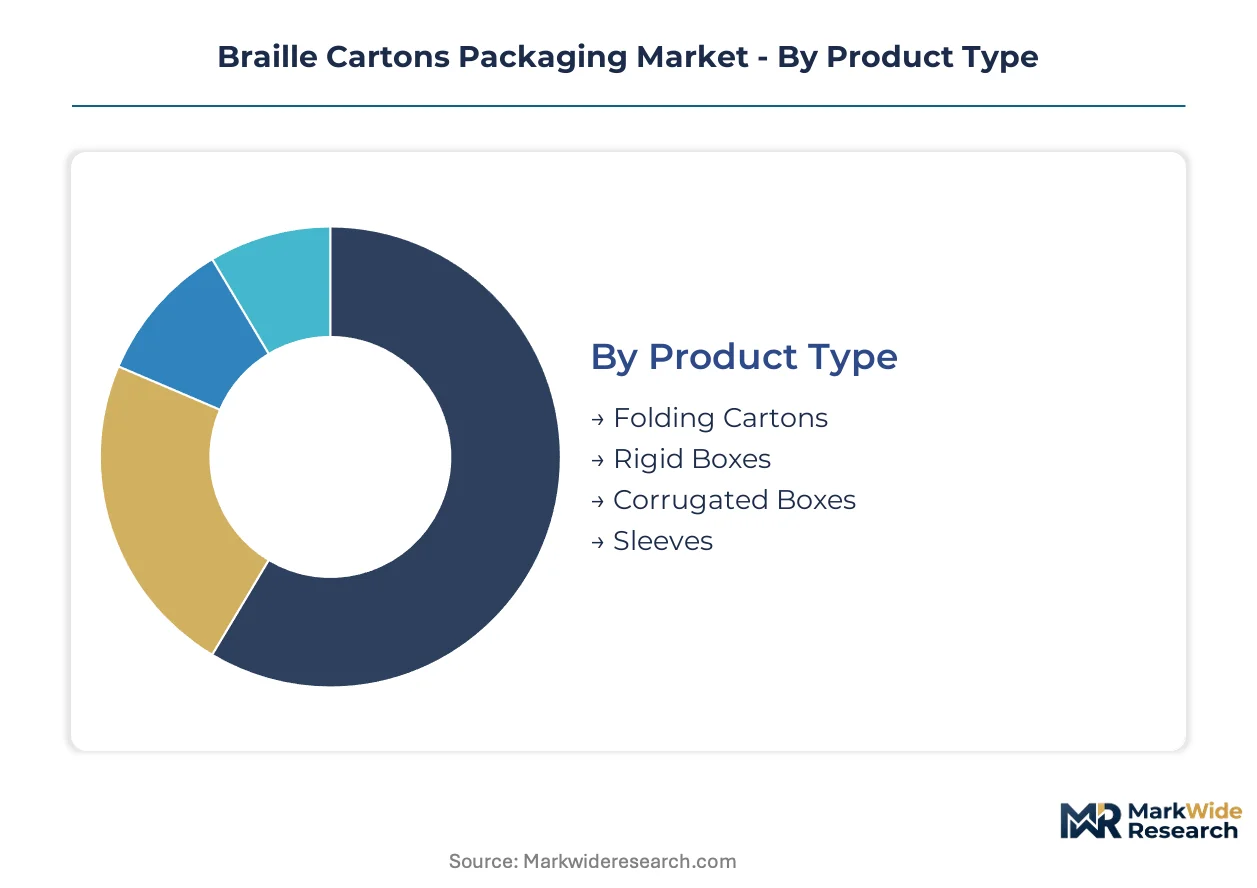
Segmentation in Braille Cartons Packaging reveals how regulatory mandates and production economics concentrate value across substrate grades and carton architectures. Understanding these splits enables converters to align capital deployment with the highest-margin compliance corridors.
Product Type:
Supply concentration for precision embossing equipment favors carton formats compatible with high-speed pharmaceutical lines, creating tiered access based on capital intensity.
- Folding Cartons:These 250-400 gsm paperboard structures integrate rotary embossing modules directly into automated filling lines. Pharmaceutical contract manufacturers in Germany and Switzerland prioritize folding cartons for oncology and biologics packaging where line speed and Braille compliance must coexist.
- Rigid Boxes:Thick-wall constructions (typically 800+ gsm or composite board) accommodate deeper embossing for premium cosmetic and cold-chain pharmaceutical applications. France and Italy host the densest demand clusters for rigid Braille boxes in high-value oncology drug segments.
- Corrugated Boxes:Secondary packaging applications in pharmaceutical distribution leverage flute structures with surface-printed Braille overlays rather than direct embossing.
- Sleeves:Wraparound carton formats serve over-the-counter pharmaceutical and cosmetic samples where partial coverage embossing meets minimum regulatory requirements.
Today's leader: Folding Cartons. Tomorrow's challenger: Rigid Boxes.
Material:
Cost tier differentiation separates certified pharmaceutical substrates from commodity alternatives, with sustainability premiums widening the spread.
- Paperboard:Bleached sulfate and SBS grades between 250-400 gsm dominate unit volume, offering optimal embossing depth retention and printability. Nordic FSC-certified supply chains anchor European pharmaceutical packaging demand.
- Cardboard:Uncoated recycled grades gain traction in cold-chain distribution where structural rigidity protects temperature-sensitive inserts. Central and Eastern European converters exploit lower-cost cardboard sourcing for regional pharma clients.
- Plastic:PET and PP substrates serve niche applications requiring moisture barriers or transparent windows alongside tactile labeling.
- Wood:Premium cosmetic and gift packaging segments utilize wood-based substrates for tactile differentiation beyond regulatory minimums.
Paperboard commands current volume. Cardboard climbs fastest on sustainability positioning.
End User:
Application concentration in regulated pharmaceutical corridors creates asymmetric growth profiles across verticals.
- Pharmaceuticals:EMA-mandated Braille inclusion for prescription medicines generates legally binding demand across EU member states. Germany, France, and Italy concentrate oncology and biologics manufacturing requiring premium rigid carton solutions.
- Cosmetics:Voluntary accessibility adoption by luxury fragrance and skincare brands drives premium positioning. French and Italian beauty houses lead voluntary Braille implementation for retail differentiation.
- Food & Beverage:Limited regulatory traction outside specialized nutritionals keeps penetration shallow relative to pharmaceutical mandates.
- Electronics:Minimal regulatory pressure restricts adoption to corporate social responsibility initiatives by select consumer device manufacturers.
Pharmaceuticals anchor revenue. Cosmetics represent the steepest expansion trajectory on voluntary premium positioning.
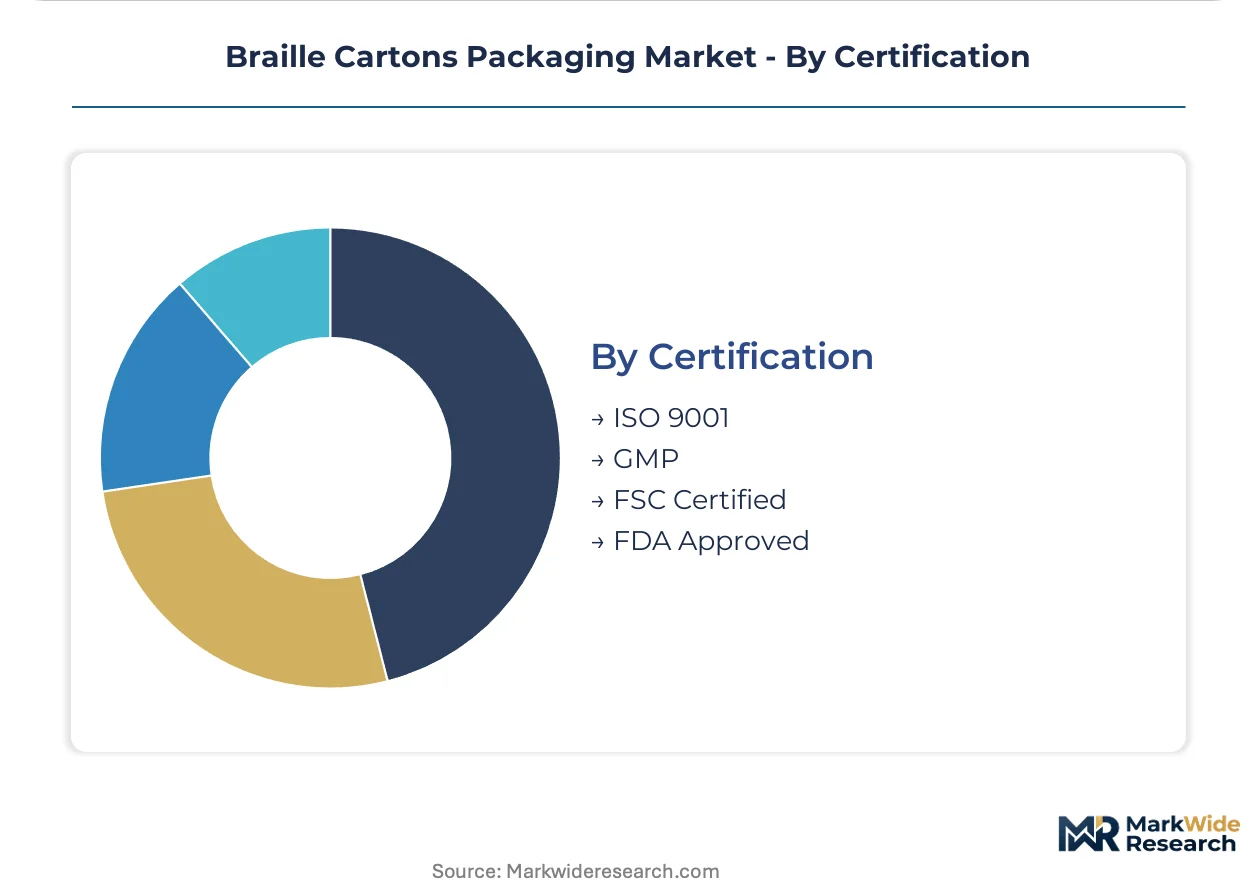
Certification:
Customer type stratification separates qualified suppliers from commodity converters through dual quality frameworks.
- ISO 9001:Foundational quality management certification required by all major pharmaceutical contract manufacturers. European converters face 18-24 month approval windows for initial certification.
- GMP:Good Manufacturing Practice compliance specific to pharmaceutical packaging creates the highest barrier to tier-one supplier status. German and Swiss pharma headquarters procurement functions mandate GMP for preferred vendor lists.
- FSC Certified:Chain-of-custody certification for sustainable sourcing increasingly gates access to EU Green Deal-aligned pharmaceutical procurement panels.
- FDA Approved:US market access requirement for exporters, though current FDA guidance on Braille remains voluntary rather than mandatory.
GMP dominates pharma access. FSC Certified gains fastest on sustainability integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are migrating production toward jurisdictions where EU Accessibility Act compliance costs intersect with favorable labor economics and pharma corridor proximity. This regulatory-arbitrage dynamic concentrates new capacity in Central European manufacturing zones while Western European sites defend premium positioning through certification density.
Germany
Oncology biologics manufacturing in Baden-Württemberg and Bavaria generates concentrated demand for rigid Braille cartons with cold-chain compatibility. EMA pharmaceutical packaging guidelines enforce Braille inclusion mandates through Germany's national medicines regulator, the Bundesinstitut für Arzneimittel und Medizinprodukte. The Stuttgart-Mannheim pharmaceutical corridor hosts the densest cluster of GMP-certified carton converters serving Merck KGaA and Boehringer Ingelheim contract packaging operations.
France
Luxury fragrance houses in Paris and Grasse drive voluntary Braille adoption for retail differentiation alongside mandatory pharma demand. ANSM enforces EMA tactile labeling standards through national pharmacovigilance inspections. The Lyon-Grenoble biotech triangle concentrates demand for premium rigid boxes in oncology drug segments, with Sanofi and Servier procurement functions mandating dual FSC-GMP certification.
Italy
Specialty pharma manufacturing in Lombardy and Emilia-Romagna creates demand for folding cartons compatible with high-speed automated lines. AIFA transposes EMA guidelines into national enforcement protocols with accelerated timelines for biologics packaging. The Milan-Novara pharmaceutical corridor anchors Smurfit Westrock's Southern European embossing capacity, serving Chiesi Farmaceutici and Recordati contract manufacturers.
Switzerland
Novartis and Roche headquarters procurement in Basel mandate the strictest Braille certification standards globally, exceeding baseline EMA requirements. Swissmedic operates a parallel but aligned regulatory framework with enhanced tactile readability audit protocols. The Basel-Zürich corridor concentrates precision embossing technology adoption, with converters deploying laser-assisted depth control systems to eliminate batch rejection risks.
Poland
Central European pharma manufacturing expansion in Warsaw and Kraków attracts converter investment seeking lower labor costs within EU regulatory reach. Polish pharmaceutical law transposes EMA accessibility mandates with enforcement timelines lagging Western Europe by 12-18 months. The Łódź-Warsaw corridor hosts emerging carton capacity serving regional subsidiaries of Teva and Mylan, with Polish converters exploiting certification cost differentials against German competitors.
Braille Cartons Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated packaging conglomerates defending pharmaceutical accounts through certification bundling while regional converters capture price-sensitive volume. The vendor base stratifies into three tiers: multinational paperboard conglomerates with GMP-certified European footprints, mid-cap specialists in rotary embossing equipment, and regional job shops serving cosmetic voluntary-adoption segments. Dominant competitive moves include backward integration into FSC-certified paperboard supply and geographic expansion into Central European manufacturing zones.
Within the multinational conglomerate tier, Smurfit Westrock and Mondi Group exemplify archetypes of regulatory-compliance bundling. Smurfit Westrock leverages its European manufacturing footprint to anchor supply for regulated pharma clients requiring integrated serialization and accessibility compliance. Mondi Group occupies a position emphasizing FSC-certified paperboard substrates that satisfy dual sustainability and accessibility procurement screens. ProAmpac sits within the specialist tier, representing R&D-intensive positioning in high-contrast embossing technologies for low-vision compliance beyond baseline regulatory minimums.
| Leading Market Players |
|---|
| Sealed Air |
| ProAmpac |
| CCL Healthcare |
| Smurfit Westrock |
| Mondi Group |
| Amcor |
| Tetra Pak |
| International Paper |
| Berry Global |
| Others |
Value Chain & Pricing Dynamics
Qualified tactile readability auditors concentrated in Germany and Switzerland command premium compensation that widens spreads between GMP-certified and uncertified converter pricing tiers.
Pricing Analysis
Distributor margins on pharmaceutical-grade Braille cartons absorb 12-18% of end-user pricing, with direct-to-OEM contracts commanding steeper volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates FSC-GMP dual-certified supply from ISO-only and uncertified alternatives. Pricing pressure stems from Polish and Czech converters undercutting Western European GMP-certified rates by 15-25% on comparable substrate grades. Generic pharmaceutical contract manufacturers exhibit highest price sensitivity, while Swiss oncology biologics producers prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Sanofi and Roche procurement functions require qualified backup suppliers for all Braille embossing capacity, preventing single-converter dependency. Nordic pulp mills in Sweden and Finland anchor 70% of pharmaceutical-grade FSC paperboard supply, with German and Austrian converters drawing from this concentrated base. Single-source vulnerability in certified substrate supply creates exposure to pulp price volatility and mill capacity allocation decisions. Distribution runs through pharmaceutical contract manufacturing organizations in Germany, Switzerland, and France before reaching final drug packaging operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polish converter investment offers 18-24 month certification cost arbitrage against German competitors, exploiting identical EU Accessibility Act compliance with lower labor and facility overhead.
For Market Incumbents: To counter emerging Polish and Czech price competition, Smurfit Westrock and Mondi Group should accelerate backward integration into Nordic FSC paperboard supply and deploy laser-assisted embossing systems in Basel-Zürich corridor facilities. GMP certification density at existing Western European sites creates defendable moats against regional entrants targeting price-sensitive generic pharma accounts. For New Entrants and Emerging Players: Pharmaceutical contract manufacturers in Warsaw and Kraków represent the most penetrable channel partner type for new converter capacity, with Teva and Mylan regional subsidiaries actively diversifying supplier panels. Target Italian and French luxury cosmetics houses for voluntary Braille adoption ahead of regulatory mandates, leveraging lower certification timelines than pharmaceutical GMP requirements. For Investors and Strategic Acquirers: Mid-cap paperboard conglomerates with existing European pharma footprints are the most active acquirer in this space, seeking rotary embossing equipment specialists to bolt onto existing carton operations. Acquisition targets should demonstrate installed laser-assisted depth control capability and active Swissmedic or EMA audit relationships. Watch for FDA rulemaking on mandatory tactile labeling as the critical inflection signal for US market expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into FSC Paperboard Supply | Nordic mill partnerships secure substrate access for EMA-mandated pharmaceutical packaging. |
| Laser-Assisted Embossing Deployment | Real-time depth control eliminates Swissmedic batch rejection risks in Basel corridor. |
| Central European Manufacturing Expansion | Polish and Czech facilities exploit labor cost differentials within EU regulatory reach. |
| Cosmetics Premium Segment Pivot | French and Italian luxury houses adopt voluntary Braille for retail differentiation. |
| GMP-ISO Dual Certification Investment | Dual quality frameworks gate access to Merck KGaA and Boehringer Ingelheim supplier lists. |
Study Parameters
Bottom-up pharmaceutical packaging modeling reconciled against top-down rotary embossing equipment tracking forms the analytical core of this study. Primary interviews with carton procurement managers at contract manufacturing organizations, quality assurance directors at pharmaceutical headquarters, and technical sales leads at embossing equipment manufacturers combined with secondary validation against EMA pharmaceutical packaging guideline documents, FDA labeling guidance, and EU Accessibility Act national transposition records. Nordic pulp mill capacity disclosures and GMP certification registry data provided supply-side triangulation.
Input-output matrices mapped folding carton and rigid box production volumes against oncology and biologics drug packaging demand across the analysis window. Segmentation dimensions included product type, material grade, end-use vertical, and certification tier, with CAGRs derived from regression analysis of historical pharmaceutical packaging expenditure patterns and regulatory mandate enforcement timelines. Forecast inputs incorporated EMA guideline adoption curves and Swissmedic enhanced audit protocol diffusion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA rulemaking evolution and EU Green Deal packaging requirement amendments. Forecasts reflect documented assumptions on regulatory enforcement intensity and substrate supply concentration stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Liners Market
Cartons
Global Open Top Cartons Market
Cartons
Fully Enclosed Cartons Market
Cartons
Japan Corrugated Boxes Market
Cartons
Luxury Folding Carton Market
Cartons
GCC Folding Carton Market
Cartons
Cartoning Machines Market
Cartons
Europe Corrugated Box Market
Cartons
Wax Boxes Market
Cartons
Carton Display Market
Cartons
Interlocking Boxes Market
Cartons
Africa Folding Carton Market
Cartons
Shaped Corrugated Packaging Market
Cartons
Shaped Liquid Cartons Market
Cartons
Digital Folding Cartons Market
Cartons
Pulp Roll Cradles Market