
 Europe Corrugated Box Market | 2026-2036
Europe Corrugated Box Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Corrugated Box Market Foresight
Green bond financing and sustainability-linked leasing arrangements is reconfiguring capital access for mid-tier European converters who previously lacked balance sheet scale. Smurfit Kappa Group leverages its integrated containerboard-to-box network across Iberia and the Nordics to control input costs. DS Smith Plc anchors its competitive position through lightweighting R&D that reduces material intensity per shipped unit. Mondi Plc specializes in kraftliner grades tailored for temperature-sensitive pharmaceutical payloads.
Corrugated boxes are paper-based containers constructed from fluted medium sandwiched between linerboard facings, typically specified by burst strength, edge crush test (ECT) ratings, and basis weight in grams per square meter. Their primary purpose is to protect goods through distribution networks while providing printable surfaces for branding and handling instructions. Single wall products dominate volume across European retail replenishment, though triple wall configurations capture premium margin pools in heavy machinery export. Recycled paperboard feeds the majority of tonnage, yet virgin kraftliner commands structural priority in moisture-resistant applications for fresh produce chains.
REACH compliance and the EU Green Deal's packaging recyclability mandates shape material sourcing decisions, while F-Gas Regulation indirectly steers cold-chain box designs toward insulated corrugated substitutes. ECHA's chemical restrictions limit certain coatings, pushing converters toward water-based barrier technologies. Stakeholders must monitor how PPWR implementation timelines alter minimum recycled content thresholds and whether national transpositions create fragmented compliance obligations across member states.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles across European converter networks, forcing rapid material substitution decisions before 2030 compliance deadlines lock in.
Growth Catalysts
- E-commerce fulfillment density:Last-mile delivery networks in Germany, France, and the Netherlands are consuming record box volumes as same-day delivery commitments expand pallet-to-parcel conversion rates.
- REACH-compliant barrier coatings:Water-based formulations replacing solvent-based chemistries are unlocking fresh produce chain contracts previously held by plastic crates.
- Green bond issuance:Sustainability-linked financing instruments are lowering capital costs for mid-tier converters upgrading recycled fiber processing lines.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import quota fluctuations, squeezing converter margins unpredictably.
- Containerboard supply concentration:Nordic and Iberian integrated producers control over half of European kraftliner capacity, creating bottleneck risk during maintenance cycles.
- Plastic substitution resilience:Reusable crate pooling systems in German automotive supply chains resist fiber conversion despite PPWR pressure.
Strategic Opportunities
- Polish manufacturing corridor:Underdeveloped converter capacity relative to German industrial demand creates arbitrage potential for cross-border fulfillment.
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distribution is generating premium demand for insulated corrugated with phase-change liners.
- Digital print integration:Hybrid flexo-inkjet lines are enabling batch-size-one customization for direct-to-consumer brands seeking unboxing differentiation.
Industry Challenges
- Recycled fiber quality variance:Sorting infrastructure gaps across Eastern Europe contaminate furnish streams, degrading finished box performance consistency.
- CSRD reporting readiness:Scope 3 emissions disclosure requirements are exposing data collection deficits in multi-tier supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Corrugated Box Market |
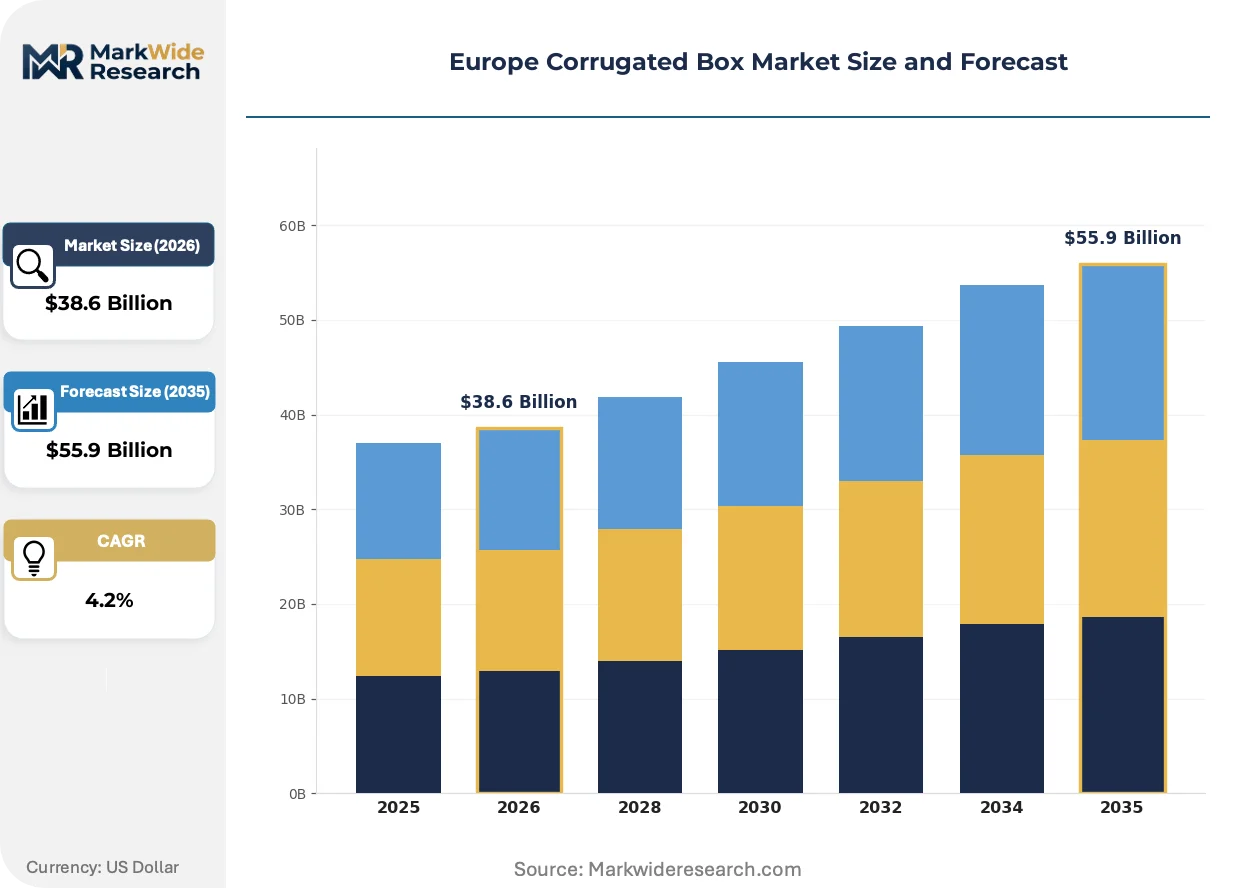
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $55.9 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Handle Boxes Material: Recycled Paperboard, Virgin Paperboard, Coated Paperboard, Specialty Paperboard End User: Food & Beverage, Electronics, Pharmaceuticals, E-Commerce Distribution Channel: Retail, Wholesale, Direct Sales, Online |
| Companies Covered | Smurfit Kappa Group, DS Smith Plc, Mondi Plc, International Paper Co., WestRock Co., Stora Enso Oyj, Georgia Pacific LLC, VPK Group, Sonoco Products Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Corrugated Box Market Shifts & Advancements
Active substitution of plastic transit packaging with fiber-based alternatives is accelerating specification changes across European supply chains, with material science advances collapsing the performance gap in moisture-critical applications.
Lightweighting through micro-flute engineering is hybridizing structural performance with material reduction. Food processors and consumer electronics assemblers are specifying F-flute and N-flute configurations for shelf-ready display compliance. The technology is hybridizing corrugated into premium retail presentation roles previously reserved for folding carton or rigid box formats.
F-Gas Regulation phase-down schedules are redirecting cold-chain investment toward passive thermal protection. Pharmaceutical distributors and fresh meal-kit operators are specifying insulated corrugated with bio-based phase-change materials to replace mechanical refrigeration units. Nordic logistics providers are piloting these solutions for last-mile vaccine distribution.
Consolidated buying desks at major retail chains are compressing supplier rosters and extending payment terms. German and French grocery multiples now mandate direct mill relationships for private-label packaging, bypassing traditional merchant converter networks. Eastern European discount retailers are replicating this procurement centralization to capture volume leverage.
Europe Corrugated Box Market Segmentation
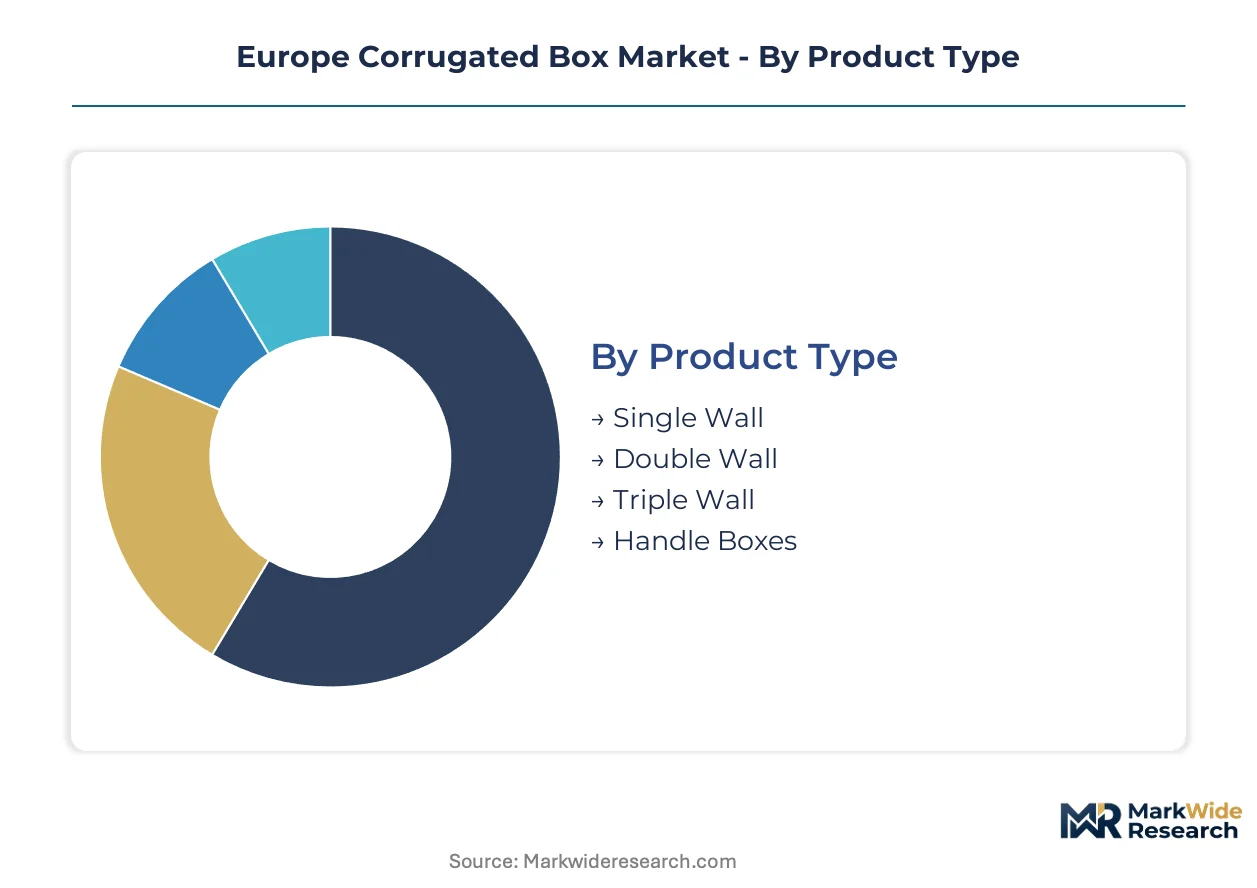
Corrugated box specifications vary sharply by protection requirements and handling cycles. Segment selection determines converter capital allocation, inventory turns, and margin capture across European fulfillment networks.
Product Type:
Cycle times compress from weeks for single-wall retail replenishment to months for triple-wall industrial export, creating divergent working capital intensity across converter portfolios.
- Single Wall:One fluted medium layer between linerboards, typically 3mm B-flute or C-flute. E-commerce parcel networks in the Netherlands and western Germany consume this specification for apparel and consumer goods fulfillment, driven by pallet-to-parcel conversion rates and same-day delivery density.
- Double Wall:Two fluted layers combining B and C flutes for stacking strength. Automotive parts suppliers in Baden-Württemberg specify this grade for returnable component loops, constrained by reusable plastic crate pooling systems that resist fiber substitution despite PPWR pressure.
- Triple Wall:Heavy machinery exporters in northern Italy and the German industrial corridor anchor demand for this specification.
- Handle Boxes:Die-cut apertures for manual carrying, common in retail-ready produce distribution.
Single wall anchors the volume base while triple wall gains share at the steepest rate on machinery export growth.
Material:
Cost tiers separate commodity recycled furnish from premium virgin kraftliner, with coating investments determining barrier performance and customer switching costs.
- Recycled Paperboard:Post-consumer OCC furnish processed to 80-150 gsm linerboard. Discount retailers across Poland and Romania specify this grade for cost-optimized dry goods packaging, constrained by sorting infrastructure gaps that contaminate furnish streams and degrade performance consistency.
- Virgin Paperboard:Unbleached kraftliner from Nordic softwood pulp. Fresh produce chains in France and Spain require this specification for moisture-resistant applications, driven by REACH-compliant water-based barrier coatings that unlock contracts previously held by plastic crates.
- Coated Paperboard:Clay or polymer surface treatments for print quality and grease resistance.
- Specialty Paperboard:Custom formulations including flame-retardant or anti-static grades for industrial safety compliance.
Recycled paperboard dominates tonnage throughput while virgin paperboard commands the widest premium spreads.
End User:
Application requirements dictate structural specifications, with temperature-sensitive payloads generating the steepest margin pools per shipped unit.
- Food & Beverage:Moisture-resistant specifications for chilled meat, dairy, and produce distribution. French and German grocery multiples mandate direct mill relationships for private-label packaging, bypassing traditional merchant converter networks to capture volume leverage.
- E-Commerce:Lightweight single-wall configurations optimized for dimensional weight pricing. German, French, and Dutch last-mile networks consume record volumes as same-day delivery commitments expand, constrained by OCC price volatility that squeezes converter margins unpredictably.
- Electronics:Anti-static and cushioning specifications for device assembly and distribution.
- Pharmaceuticals:Temperature-sensitive biologics distribution generates premium demand for insulated corrugated with phase-change liners, replacing mechanical refrigeration units under F-Gas Regulation phase-down schedules.
Food and beverage anchors the volume base while pharmaceuticals expands most quickly on cold-chain biologics growth.
Distribution Channel:
Customer type determines order fragmentation, with consolidated retail buying desks compressing supplier rosters and extending payment terms across converter networks.
- Retail:Direct procurement by grocery multiples and mass merchants for shelf-ready packaging. Eastern European discount retailers are replicating German and French centralization models to capture volume leverage.
- Wholesale:Merchant converter networks serving small and mid-sized manufacturers.
- Direct Sales:Mill-direct relationships for high-volume industrial accounts.
- Online:Digital platforms enabling batch-size-one customization for direct-to-consumer brands seeking unboxing differentiation through hybrid flexo-inkjet print integration.
Retail procurement anchors the volume base while online channels climb the fastest on digital print adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation compresses design cycles across converter networks, forcing rapid material substitution decisions before 2030 compliance deadlines lock in capital commitments.
Germany
Automotive parts suppliers in Baden-Württemberg and food processors in the industrial corridor anchor regional box consumption. The country's national packaging regulator enforces strict recyclability targets that favor fiber-based solutions over plastic alternatives. Last-mile delivery networks in western Germany consume record single-wall volumes as same-day delivery commitments expand pallet-to-parcel conversion rates.
France
Fresh produce chains and grocery multiples drive moisture-resistant specification demand across the Île-de-France and Auvergne-Rhône-Alpes regions. REACH-compliant water-based barrier coatings unlock contracts previously held by plastic crates under ECHA chemical restrictions. French grocery retailers mandate direct mill relationships for private-label packaging, bypassing traditional merchant converter networks.
Netherlands
E-commerce fulfillment density in the Randstad logistics hub consumes lightweight single-wall configurations optimized for dimensional weight pricing. The EU Green Deal's packaging recyclability mandates shape material sourcing decisions for Dutch distribution networks serving northern European markets. Rotterdam-area converters pilot hybrid flexo-inkjet lines enabling batch-size-one customization for direct-to-consumer brands.
Poland
Underdeveloped converter capacity relative to German industrial demand creates arbitrage potential for cross-border fulfillment from the Warsaw and Silesian manufacturing corridors. Sorting infrastructure gaps across Eastern Europe contaminate furnish streams, degrading finished box performance consistency. Discount retailers specify recycled paperboard grades for cost-optimized dry goods packaging.
Italy
Heavy machinery exporters in northern Italy anchor demand for triple-wall configurations capturing premium margin pools. The F-Gas Regulation phase-down schedules redirect cold-chain investment toward passive thermal protection for pharmaceutical distribution. Milan-area logistics providers pilot insulated corrugated with bio-based phase-change materials for temperature-sensitive payloads.
Europe Corrugated Box Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Nordic and Iberian integrated producers control over half of European kraftliner capacity, creating bottleneck risk during maintenance cycles. Three strategic archetypes dominate: integrated containerboard-to-box networks, lightweighting R&D specialists, and kraftliner grade innovators. Consolidated buying desks at major retail chains compress supplier rosters, while sustainability-linked financing instruments lower capital costs for mid-tier converters upgrading recycled fiber processing lines.
Within the integrated network tier, Smurfit Kappa Group and DS Smith Plc exemplify archetypes controlling input costs through backward integration into containerboard production. Mondi Plc occupies a specialist position among kraftliner innovators serving temperature-sensitive pharmaceutical applications. These three companies represent the dominant competitive positioning vectors—geographic network density, material science R&D, and application-specific formulation expertise—that separate market leaders from merchant converter competition.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith Plc |
| Mondi Plc |
| International Paper Co. |
| WestRock Co. |
| Stora Enso Oyj |
| Georgia Pacific LLC |
| VPK Group |
| Sonoco Products Co. |
| Others |
Supply & Pricing Matrix
OCC price volatility from Chinese import quota fluctuations determines both margin compression severity across converter tiers and the geographic shape of European supply networks. This feedstock instability widens pricing spreads between integrated producers with captive pulp supply and merchant converters exposed to spot markets, while simultaneously accelerating capacity relocation toward Nordic and Iberian kraftliner strongholds.
Pricing Analysis
Certification level under EU Green Deal packaging recyclability mandates creates the primary spread between premium virgin kraftliner and commodity recycled grades. Three-tier pricing structure across pharmaceutical-grade insulated specifications, food-contact barrier coatings, and standard dry goods packaging reflects material science R&D investment depth. Cost compression in mid-tier recycled paperboard intensifies because sorting infrastructure gaps degrade furnish quality consistency. Discount retailers across Poland and Romania exhibit highest price sensitivity, while pharmaceutical cold-chain distributors absorb premium spreads for temperature-validated performance.
Supply Chain Analysis
Nordic and Iberian integrated producers hold over half of European kraftliner capacity, with Smurfit Kappa and DS Smith controlling strategic mill networks. Containerboard production concentrates in Sweden, Finland, and Spain, drawing from softwood pulp feedstocks and recycled OCC streams. Single-source vulnerability emerges from maintenance cycle synchronization across these concentrated assets. Distribution runs through consolidated retail buying desks at German and French grocery multiples that mandate direct mill relationships, bypassing traditional merchant converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
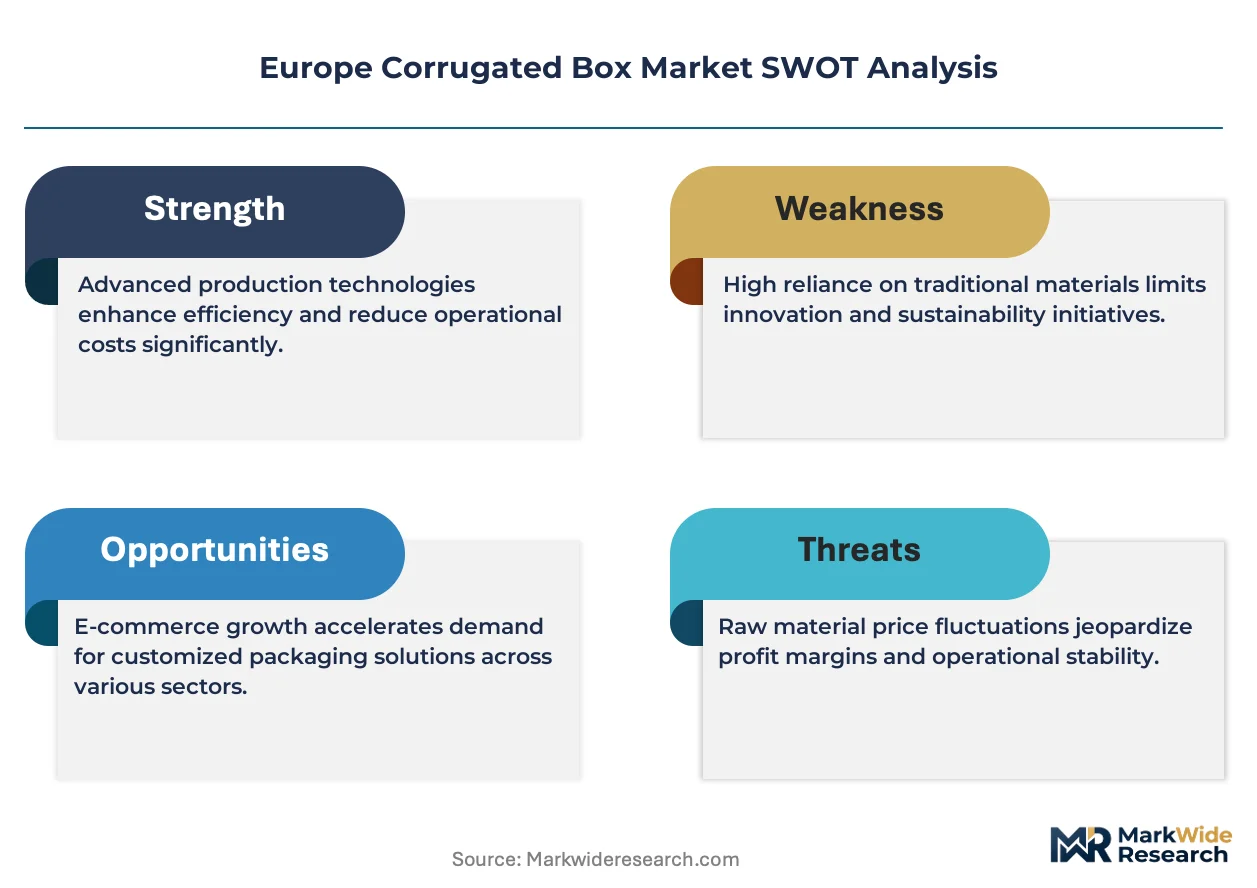
Specialized barrier coating formulation expertise represents the scarcest capability in this market, separating pharmaceutical-grade insulated box suppliers from commodity converters. The gap between REACH-compliant water-based technology holders and legacy solvent-dependent operations is widening faster than talent replication cycles.
For Market Incumbents: Pre-empt displacement from lightweighting R&D specialists by accelerating micro-flute engineering investment in F-flute and N-flute configurations for shelf-ready display compliance. Consolidate backward integration into containerboard production to insulate margins from OCC price volatility. Capture channel control through direct mill relationships with consolidated retail buying desks before merchant converter networks collapse. For New Entrants and Emerging Players: Polish manufacturing corridors with underdeveloped converter capacity relative to German industrial demand represent the most penetrable entry point for cross-border fulfillment arbitrage. Pharmaceutical cold-chain expansion for temperature-sensitive biologics offers premium margin capture insulated from commodity pricing cycles. Digital print integration through hybrid flexo-inkjet lines enables batch-size-one customization for direct-to-consumer brands seeking unboxing differentiation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated containerboard-to-box networks with sustainability-linked financing access. Long-term viability over the coming decade rests on regulatory compliance infrastructure and green bond issuance capability rather than scale alone. Watch PPWR implementation timeline acceleration as the signal for minimum recycled content threshold inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting R&D Investment | Micro-flute engineering reduces material intensity per shipped unit for F-flute configurations. |
| Backward Integration into Kraftliner | Captive pulp supply insulates margins from OCC price volatility and Chinese quota fluctuations. |
| REACH-Compliant Barrier Coating Scale-Up | Water-based formulations unlock fresh produce contracts previously held by plastic crates. |
| Direct Mill Relationship Expansion | Bypassing merchant networks captures volume leverage with consolidated German grocery multiples. |
| Pharmaceutical Cold-Chain Partnership | Insulated corrugated with phase-change liners replaces mechanical refrigeration under F-Gas Regulation. |
Research Methodology
A spread of perspectives from converter operations directors, procurement leads at German automotive parts suppliers, sustainability officers at French grocery multiples, and barrier coating R&D specialists converged on the working assumptions. Primary fieldwork combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation documents, ECHA chemical restriction databases, and containerboard trade association statistics. Bottom-up volume modeling across product type, material grade, end-use application, and distribution channel triangulated against top-down macroeconomic indicators.
Demand-supply balance dynamics across the analysis window shaped the analytical framework, with segmentation modeling across single-double-triple wall configurations, recycled versus virgin paperboard grades, food-ecommerce-pharmaceutical end uses, and retail-wholesale-direct-online channels. CAGRs derived from elasticity-adjusted consumption trends and capacity expansion announcements. Forecast inputs incorporated PPWR compliance timeline uncertainty and F-Gas Regulation phase-down schedules for cold-chain substitution patterns.
Practitioners should monitor Chinese OCC import quota announcements and Nordic mill maintenance cycle synchronization for early signals of feedstock cost disruption. Forecasts reflect assumptions about regulatory implementation pacing and substitution technology readiness. Quarterly review of green bond issuance flows and CSRD reporting readiness indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Tablet Cartons Market
Cartons
Carton Serialization Machine Market
Cartons
Brick Carton Packaging Market
Cartons
Fully Enclosed Cartons Market
Cartons
Cupcake Box Market
Cartons
Fluted Carton Trays Market
Cartons
Braille Cartons Packaging Market
Cartons
Africa Folding Carton Market
Cartons
Luxury Folding Carton Market
Cartons
Pulp Roll Cradles Market
Cartons
End Load Cartoning Machine Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Wax Boxes Market
Cartons
Reverse Tuck Cartons Market
Cartons
Metallized Folding Cartons Market
Cartons
Global Folding Carton Packaging Market