
 Digital Printed Cartons Market | 2026-2036
Digital Printed Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Printed Cartons Market Outlook
Buyer concentration in the food and beverage sector is decoupling as craft producers and direct-to-consumer brands fragment procurement volumes across shorter runs. WestRock Company leverages its North American mill network to control substrate supply for digital-ready paperboard. DS Smith Plc anchors European corrugated and carton capacity with integrated recycling operations. Mondi Group specializes in sustainable barrier papers that bridge flexo and inkjet compatibility.
Digital printed cartons are paperboard or plastic-based containers produced through non-contact, variable-data printing systems, typically employing water-based or UV-curable inks at resolutions exceeding 600 dpi for shelf-ready graphics and trackable codes. Their primary purpose is to enable brand owners to customize packaging at production speed without plate changes or minimum order thresholds. Folding cartons dominate volume due to their prevalence in retail-ready food and pharmaceutical configurations, while rigid cartons command premium positioning in cosmetics where structural integrity supports unboxing experience. Inkjet printing technology leads growth among printing methods as single-pass systems close the speed gap with flexography for medium-run folding carton jobs.
FDA food contact notifications and EPA VOC emission standards govern ink formulations and substrate coatings in the United States, while REACH and the EU Packaging and Packaging Waste Regulation enforce chemical disclosure and recyclability claims across European supply chains. These frameworks elevate compliance costs for imported cartons while rewarding domestic digital production with shorter audit trails. Stakeholders must weigh capital allocation between faster inkjet presses and retrofit hybrid lines as run-length economics continue to compress.
Market Dynamics
Run-length compression in folding carton procurement is fragmenting volume across shorter, more frequent orders. Brand owners now treat packaging as a content layer requiring weekly refreshes rather than static annual commitments. This shift strains conventional flexo economics while rewarding digital-native production assets.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets and extended producer responsibility schemes accelerate carton-to-carton fiber recovery. Digital production enables lot-level material traceability that satisfies audit requirements.
- Pharmaceutical serialization mandates:Track-and-trace regulations in the United States and European Union require unique identifiers on every saleable unit. Inkjet systems embed variable QR codes and alphanumeric strings at production speed without plate costs.
- Water-based ink chemistry advances:Barrier coatings compatible with high-speed inkjet now match oil and grease resistance of solvent-based alternatives. Food-contact applications in bakery and confectionery segments open to digital conversion.
Market Restraints
- Substrate cost volatility:Bleached kraft pulp prices fluctuate with energy-intensive European mill operations. Carton converters face margin compression when passing through raw material spikes to fragmented buyer bases.
- Speed ceiling on single-pass inkjet:Current generation presses plateau below flexographic throughput for long-run folding carton jobs. High-volume CPG brands retain analog workflows for promotional staples with predictable artwork.
- Capital intensity of press replacement cycles:Five-to-seven-year depreciation schedules lock converters into equipment decisions. Hybrid retrofit investments compete with full digital replacements for constrained capex allocations.
Strategic Opportunities
- India PLI scheme for packaging machinery:Production-linked incentives attract domestic assembly of digital press components. Localized equipment supply reduces import duty exposure and service response times.
- Cannabis and CBD product packaging:Regulatory labeling variability across United States state jurisdictions demands compliant, small-batch production. Child-resistant folding cartons with variable potency disclosures suit digital workflows.
- Near-field communication (NFC) tag integration:Conductive inkjet deposition embeds authentication and engagement layers directly onto carton surfaces. Luxury cosmetics and spirits brands pilot connected packaging for anti-counterfeiting and loyalty programs.
Industry Challenges
- Prepress color consistency across substrate lots:Digital presses require spectrophotometric calibration for every paperboard grade change. Skilled operators capable of G7 color space management command wage premiums in tight labor markets.
- FDA food contact notification timelines:Novel ink formulations and barrier coatings undergo twelve-to-eighteen-month safety reviews. Product development pipelines stall when regulatory submissions lag commercial launch targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Printed Cartons Market |
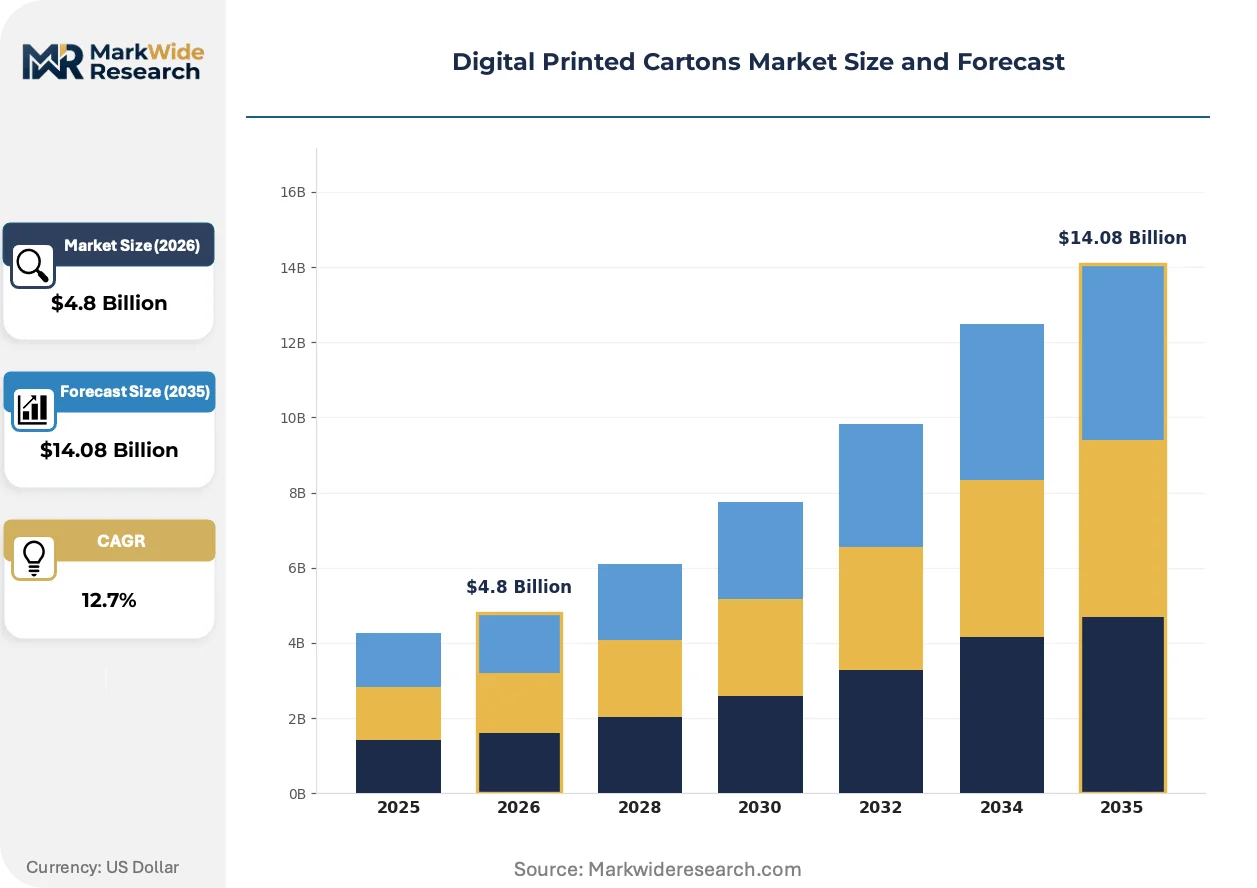
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $14.08 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Cartons, Rigid Cartons, Two-Piece Cartons, Sleeve Packs Printing Technology: Inkjet, Laser, Flexography, Offset End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Material: Paperboard, Plastic, Recycled Materials, Composite Materials |
| Companies Covered | HP Inc., WestRock Company, Graphic Packaging International, Amcor Plc, DS Smith Plc, CCL Industries Inc., Mondi Group, Smurfit Kappa Group, International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Printed Cartons Market Strategic Shifts
Artificial intelligence is penetrating prepress and makeready workflows. Machine learning models now predict color drift and auto-correct image files before rasterization. This compresses job setup from hours to minutes.
Single-pass inkjet arrays are automating variable-data insertion at flexographic speeds. Pharmaceutical contract packagers in Germany and the United States adopt these systems to consolidate serialization and decoration into one pass. The technology is automating compliance workflows that previously required offline thermal transfer overprinting.
REACH substance restrictions are tightening pigment and additive disclosure requirements for imported cartons. European converters must document SVHC content down to 0.1% concentration thresholds. Cosmetic and personal care brands with complex European supply chains are bringing digital production in-house to shorten chemical audit trails.
Brand procurement teams are consolidating carton specifications across regional supplier panels. Direct-to-consumer food startups in France and the United Kingdom negotiate monthly minimums rather than annual volume commitments. This pattern fragments order sizes and rewards converters with digital-first asset configurations.
Digital Printed Cartons Market Segmentation
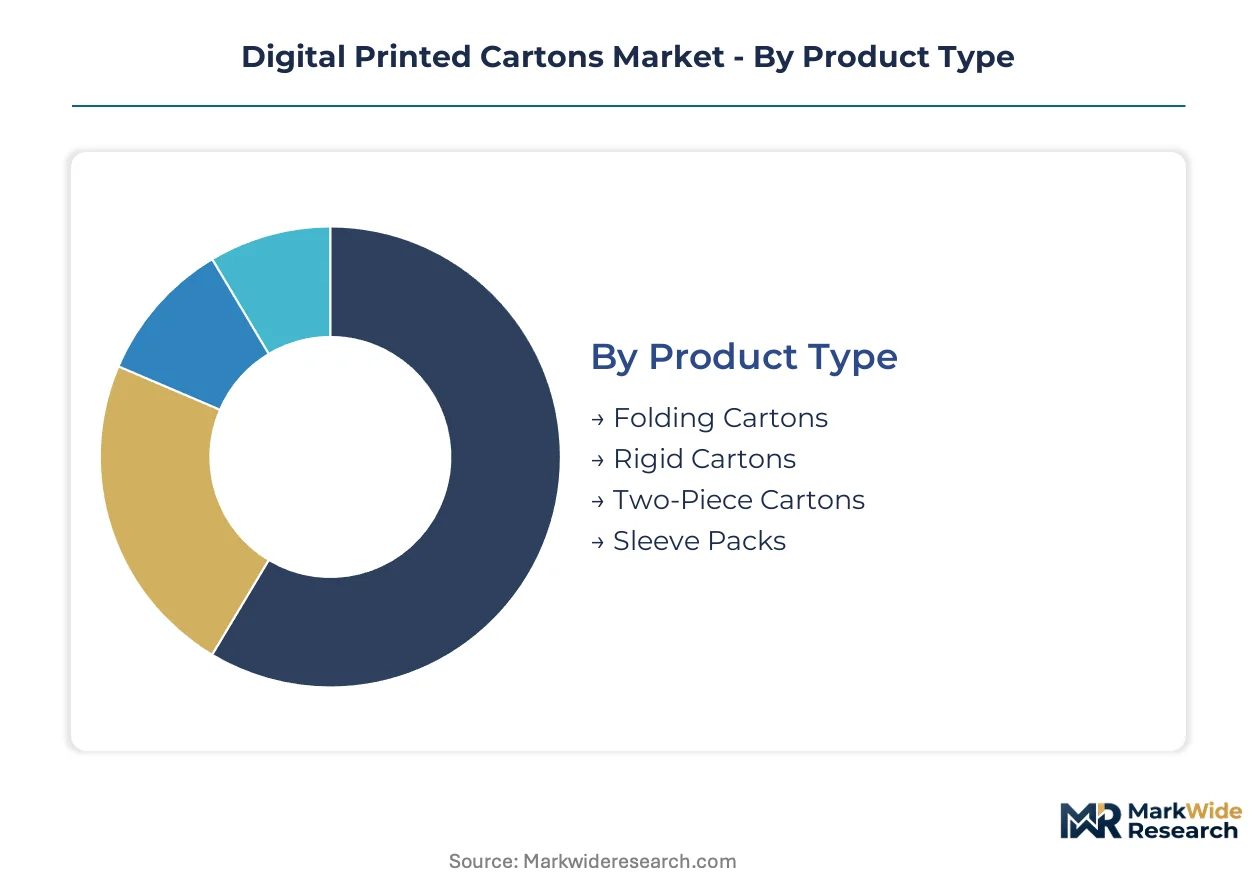
Digital printed carton procurement fragments across structural formats, deposition technologies, end-use compliance regimes, and substrate specifications. Each segmentation axis carries distinct margin profiles, capital requirements, and regulatory exposure that reshape converter investment priorities.
Product Type:
Structural formats diverge sharply between standalone retail-ready containers and embedded protective systems requiring secondary assembly. Integration depth determines press configuration, finishing equipment, and logistics partnerships.
- Folding Cartons:Converted from single-sheet paperboard with pre-scored creases and die-cut locking tabs, these containers ship flat and erect at filling lines. Pharmaceutical contract packagers in Germany and food startups in France prioritize folding cartons for their production flexibility and minimal warehousing footprint.
- Rigid Cartons:Built from heavyweight paperboard laminated to rigid chipboard or greyboard, these structures maintain dimensional integrity without contents. Cosmetic houses in Paris and Milan specify rigid cartons for premium unboxing experiences that justify per-unit decoration investments.
- Two-Piece Cartons:Separate base and lid components enable depth customization for irregular products.
- Sleeve Packs:Wrap-around paperboard sleeves decorate pre-formed trays or bottles, reducing material versus full cartons.
Folding cartons lead volumes today; rigid cartons are gaining share fastest in premium personal care applications.
Printing Technology:
Deposition systems stratify by run-length economics, with cost-per-thousand curves crossing at distinct volume thresholds that reshape converter equipment planning.
- Inkjet:Piezoelectric or thermal drop-on-demand heads deposit water-based or UV-curable inks without plate costs. Single-pass arrays from Fujifilm and Heidelberg now match flexographic speeds for medium-run folding carton work, capturing pharmaceutical serialization mandates in the United States and European Union.
- Laser:Electrophotographic drums fuse toner to substrate surfaces with precise registration. Toner-based systems dominate short-run proofing and variable-data jobs where color consistency outweighs unit cost.
- Flexography:Rotary relief plates transfer fast-drying solvent or water-based inks at high speeds. Long-run beverage and confectionery staples retain flexographic workflows where artwork remains static across millions of impressions.
- Offset:Lithographic plates and rubber blankets deliver fine halftone detail on coated stocks. High-volume cosmetic and electronics packaging leverages offset for metallic effects and spot-color precision that digital systems struggle to replicate.
Flexography still commands the highest absolute output; inkjet is climbing the fastest as run lengths compress toward digital breakeven.
End User:
Vertical applications impose divergent compliance burdens, with food contact and pharmaceutical traceability requirements filtering accessible supplier pools.
- Food & Beverage:Bakery, confectionery, and ready-meal brands specify barrier-coated paperboard with grease and moisture resistance. FDA food contact notifications and EFSA compliance documentation dominate supplier qualification timelines.
- Pharmaceuticals:Serialization mandates in the United States and European Union require unique identifiers on every saleable unit. Inkjet systems embed track-and-trace codes at production speed without offline overprinting.
- Cosmetics:Premium skincare and fragrance houses prioritize shelf impact and unboxing theater over unit economics.
- Electronics:Anti-static coatings and structural cushioning protect sensitive components during distribution.
Food and beverage generates the largest absolute demand; pharmaceuticals is expanding most quickly under regulatory serialization pressure.
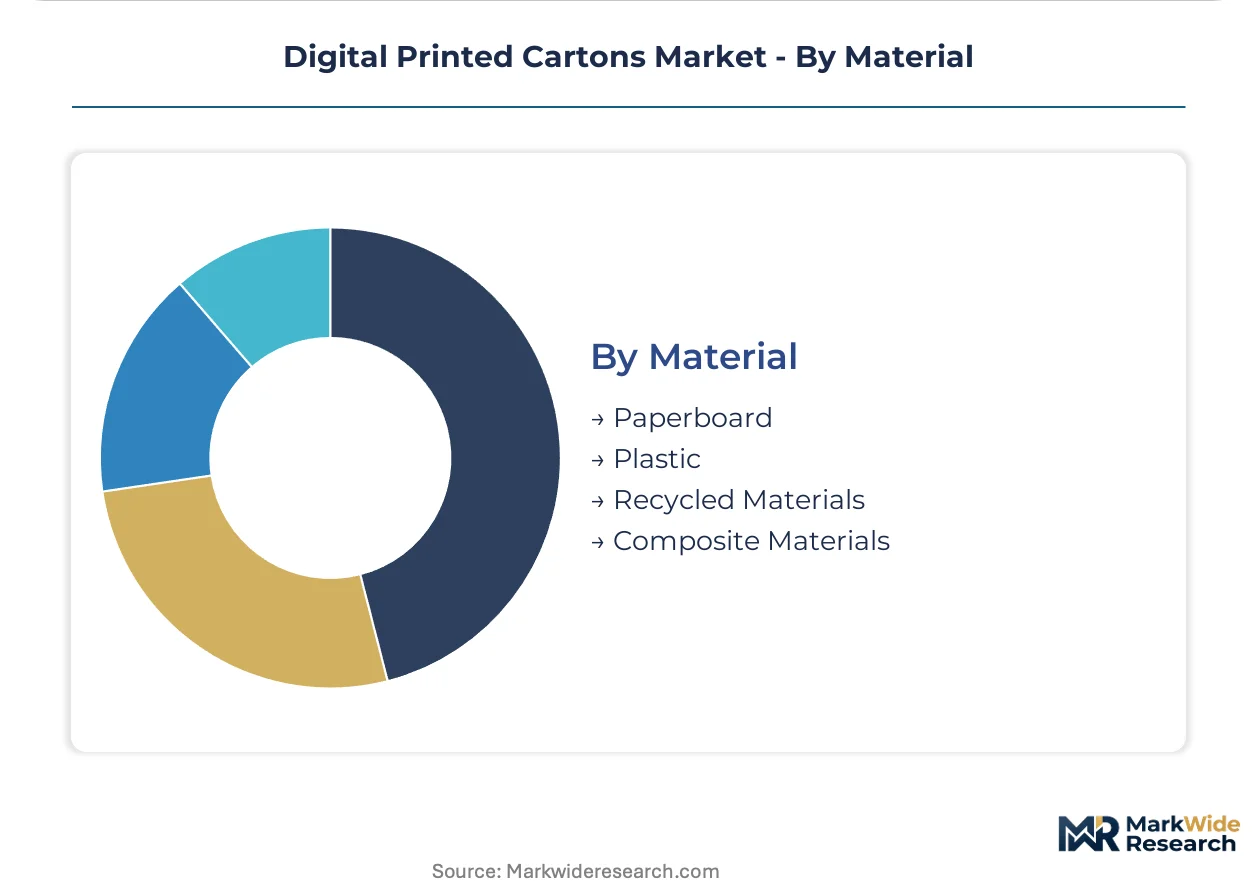
Material:
Substrate selection balances mechanical performance, print receptivity, and end-of-life recovery pathways that increasingly influence brand owner procurement scorecards.
- Paperboard:Bleached kraft or solid bleached sulfate stocks provide stiffness, printability, and established recycling streams. European mills in Sweden and Finland supply coated grades optimized for high-speed inkjet absorption.
- Plastic:PET, PP, and polystyrene substrates enable transparent windows and moisture barriers. REACH substance restrictions and extended producer responsibility schemes elevate compliance costs for fossil-based materials.
- Recycled Materials:Post-consumer fiber content satisfies corporate sustainability commitments and EU Packaging and Packaging Waste Regulation targets.
- Composite Materials:Multi-layer paper-plastic laminates combine barrier performance with print aesthetics.
Paperboard dominates procurement volumes today; recycled materials are gaining share fastest under tightening circular economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in digital carton adoption for pharmaceutical serialization, while the United States leads absolute volume through fragmented food and beverage procurement. National regulatory frameworks and industrial clustering patterns reshape converter investment priorities across major economies.
United States
FDA pharmaceutical serialization mandates and craft beverage proliferation fragment order sizes toward digital breakeven. EPA VOC emission standards govern ink formulations for food-contact applications. Chicago and Wisconsin paperboard corridors host converters retrofitting hybrid lines for short-run CPG contracts.
Germany
Pharmaceutical contract packagers in Baden-Württemberg consolidate serialization and decoration into single-pass inkjet workflows. REACH substance restrictions enforce SVHC documentation down to 0.1% concentration thresholds. The Rhine-Main packaging cluster anchors European digital capacity with integrated recycling operations.
France
Cosmetic houses in Paris and Lyon specify rigid cartons for premium unboxing experiences with weekly artwork refreshes. EU Packaging and Packaging Waste Regulation recyclability targets accelerate carton-to-carton fiber recovery. The Île-de-France region concentrates brand owner procurement teams negotiating monthly minimums rather than annual commitments.
India
Domestic food startups and export-oriented pharmaceutical packaging drive digital press adoption. The PLI scheme for packaging machinery attracts domestic assembly of digital press components, reducing import duty exposure. Gujarat and Maharashtra industrial corridors host converters localizing equipment supply and service response.
United Kingdom
Direct-to-consumer food brands in London and the Southeast negotiate fragmented procurement volumes across shorter runs. EFSA compliance documentation dominates supplier qualification timelines for barrier-coated paperboard. The Midlands packaging belt retrofits lines for bakery and confectionery digital conversion.
Digital Printed Cartons Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Paperboard integrators with captive mill networks control substrate supply for digital-ready grades, while independent converters specialize in variable-data pharmaceutical and cosmetic workflows. Two strategic archetypes dominate: integrated fiber-to-print operators and agile short-run service bureaus. Competitive moves concentrate on hybrid press retrofits and regional recycling partnerships.
Among North American integrated players, WestRock Company and International Paper exemplify scale-driven fiber control. European specialists DS Smith Plc and Mondi Group occupy positions bridging sustainable barrier development with inkjet compatibility. HP Inc. anchors technology supply through press manufacturing rather than carton production.
| Leading Market Players |
|---|
| HP Inc. |
| WestRock Company |
| Graphic Packaging International |
| Amcor Plc |
| DS Smith Plc |
| CCL Industries Inc. |
| Mondi Group |
| Smurfit Kappa Group |
| International Paper |
| Others |
Value Chain & Pricing Dynamics
Single-pass inkjet press adoption in Germany and the United States is simultaneously compressing per-unit decoration costs and redistributing margin capture toward converters with localized digital assets. This technology transition rewards regional production flexibility over long-haul substrate logistics.
Pricing Analysis
Capacity additions in India and Germany are reshaping price floors for medium-run folding carton work. Three-tier pricing structure across premium, standard, and economy levels stratifies by serialization compliance tier and substrate certification grade. Pricing pressure stems from pulp cost pass-through volatility in European mill networks. Direct-to-consumer food startups exhibit highest price sensitivity; pharmaceutical contract packagers accept premium positioning for lot-level traceability.
Supply Chain Analysis
Carton-to-carton fiber recovery flows through reverse logistics networks anchored in Germany, France, and Sweden. Bleached kraft pulp draws from Nordic mill clusters; water-based ink chemistry rests on German specialty chemical suppliers. Single-source vulnerability concentrates in single-pass inkjet printhead arrays from Japanese and European OEMs. Distribution runs through regional converter hubs serving brand owner co-location requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
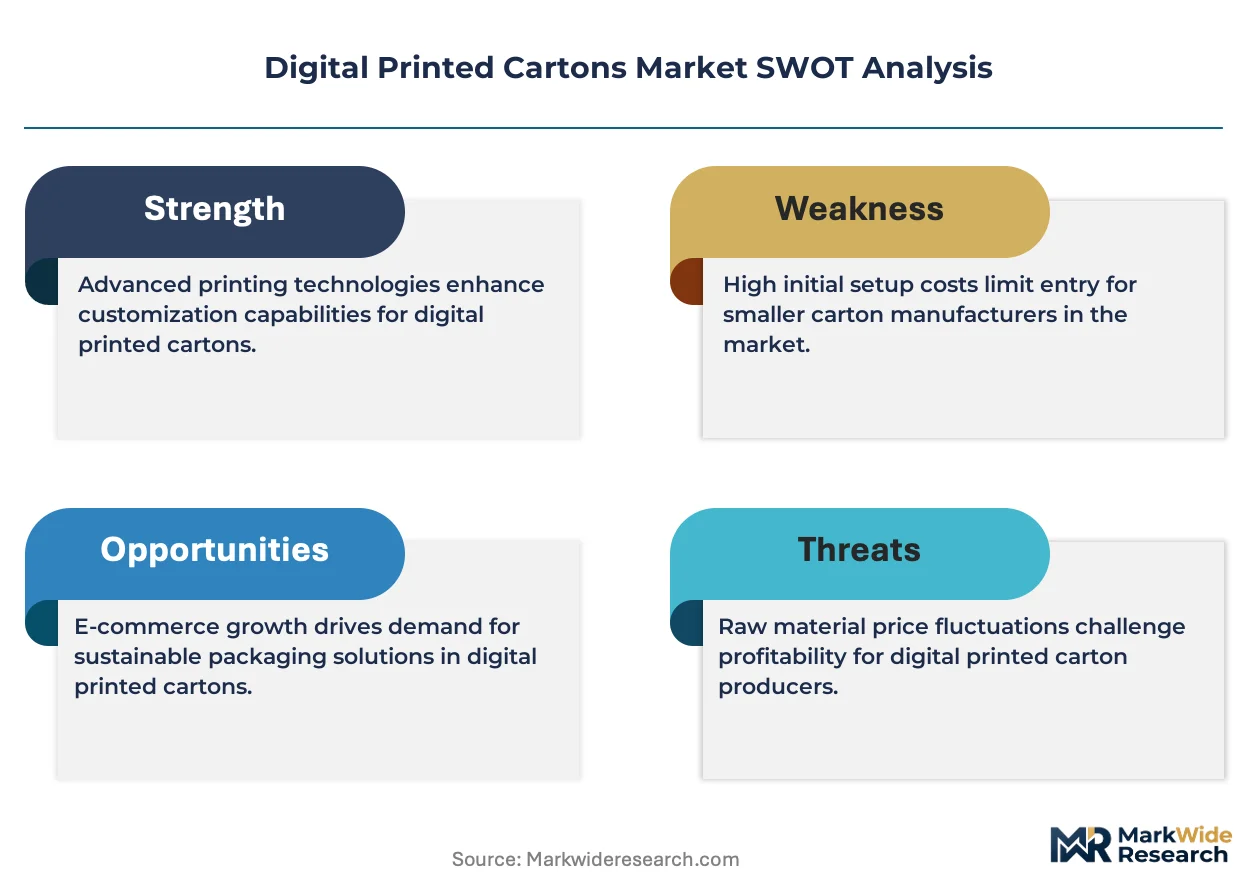
The digital printed cartons market compounds steadily as regulatory serialization mandates in pharmaceuticals and food contact traceability create durable demand for variable-data production infrastructure.
For Market Incumbents: Lock in substrate supply security through backward integration into coated paperboard grades optimized for high-speed inkjet absorption. Prioritize G7 color certification investments to capture wage-premium operator scarcity. Defend against agile short-run service bureaus by embedding serialization compliance into turnkey managed print programs. For New Entrants and Emerging Players: The EU Packaging and Packaging Waste Regulation in France and Germany opens a window for localized carton-to-carton fiber recovery specialists. Target cannabis and CBD packaging in United States state jurisdictions with variable labeling requirements. Lead with conductive inkjet deposition pilots for NFC-enabled luxury cosmetics authentication. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-press retrofit converters with stranded flexographic assets and underutilized finishing equipment. Five-to-ten-year viability favors integrated fiber-to-print operators with captive recycling streams. Monitor FDA food contact notification backlog clearance timelines as inflection signal for novel barrier coating commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Press Retrofit | Extends asset life for medium-run folding carton jobs in pharmaceutical serialization workflows. |
| Backward Integration into Coated Paperboard | Captures margin from bleached kraft pulp volatility through captive substrate supply. |
| G7 Color Certification Investment | Addresses skilled operator scarcity in spectrophotometric calibration for substrate grade changes. |
| NFC Tag Integration Pilot | Enables anti-counterfeiting and loyalty programs for luxury spirits and cosmetics brands. |
| Regional Recycling Partnership | Satisfies EU Packaging and Packaging Waste Regulation carton-to-carton fiber recovery targets. |
Study Parameters
Direct dialogue with carton converter operations directors, pharmaceutical contract packaging managers, cosmetic brand procurement leads, and water-based ink formulation chemists grounded qualitative findings. Secondary validation drew from FDA food contact notification databases, ECHA SVHC substance registrations, EU Packaging and Packaging Waste Regulation implementation guidance, and SEC filings of integrated paperboard producers. Bottom-up press installation counts and top-down end-use demand estimates underwent cross-triangulation.
Segmented outputs across structural format, deposition technology, end-use compliance regime, and substrate specification informed the analytical framework over the projection horizon. CAGRs derived from equipment replacement cycle modeling and run-length compression elasticity estimates. Forecast inputs incorporated pharmaceutical serialization mandate phase-in schedules and REACH substance restriction amendment pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt pulp price spikes or extended FDA notification delays. Practitioners should monitor single-pass inkjet speed breakthrough announcements and EU extended producer responsibility fee structures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Thailand Folding Carton Packaging Market
Cartons
Carton Display Market
Cartons
North America Corrugated Boxes Market
Cartons
Beverage Cartoners Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Global Cartonboard Market
Cartons
Braille Cartons Packaging Market
Cartons
Tablet Cartons Market
Cartons
Carton Bottle Market
Cartons
Beverage Cartons Market
Cartons
Wax Boxes Market
Cartons
Africa Folding Carton Market
Cartons
Reverse Tuck Cartons Market
Cartons
Luxury Folding Carton Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Tetrahedron Carton Market